
 Asia-Pacific Power Transistor Market | 2026-2036
Asia-Pacific Power Transistor Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Power Transistor Market Insights
Silicon carbide is shifting from niche aerospace applications into mainstream automotive inverters, compressing cost premiums against conventional silicon IGBTs. Infineon Technologies leverages its Dresden-to-Kulim manufacturing corridor to sustain wafer supply for Asian EV module makers. Mitsubishi Electric anchors its position through proprietary trench-gate SiC MOSFET designs optimized for rail and traction systems. Toshiba competes on legacy silicon expertise while navigating gradual portfolio migration toward wide-bandgap platforms.
A power transistor is a semiconductor device engineered to switch or amplify electrical power in circuits handling currents above one ampere, typically fabricated from silicon, silicon carbide, or gallium nitride with doping concentrations and epitaxial layer thicknesses tuned to breakdown voltage ratings spanning 40V to 10kV. Its primary purpose is efficient power conversion across variable loads in motor drives, inverters, and switched-mode supplies. MOSFET segments dominate consumer electronics and low-voltage automotive auxiliaries where switching speed outweighs conduction loss, while IGBT platforms retain structural importance in industrial motor drives above 600V. SiC technology captures the fastest expansion within electric vehicle traction inverters, where thermal efficiency gains translate directly into extended range and reduced cooling hardware.
China's MIIT enforces GB standards for automotive semiconductor reliability that effectively gate market access for imported power modules, while Japan's METI coordinates domestic SiC substrate capacity expansion through technology roadmaps binding equipment makers and material suppliers. South Korea's K-REACH chemical regulations and carbon neutrality commitments are forcing foundries to document lifecycle emissions across epitaxial growth and wafer processing stages. Stakeholders must monitor which jurisdiction's certification timeline becomes the binding constraint for multi-country platform rollouts.
Market Dynamics
Silicon carbide substrate supply concentration in China's coastal manufacturing clusters is forcing EV module makers to co-locate epitaxial growth and packaging operations within single industrial parks.
Growth Catalysts
- China's GB automotive semiconductor standards:Mandatory reliability testing for imported power modules is accelerating localization investments by foreign suppliers seeking market access.
- Electric vehicle traction inverters:Automakers in Japan and South Korea are specifying SiC MOSFETs for next-generation drivetrains to meet tightening fleet emissions frameworks.
- Coastal foundry clustering:Integrated circuit fabrication and module assembly co-location in Jiangsu and Guangdong provinces shortens supply loops and reduces logistics costs.
Market Restraints
- 6-inch SiC wafer supply:Substrate fabrication capacity remains concentrated among a limited set of equipment-constrained suppliers, creating input bottlenecks for power module makers.
- Japan's METI-coordinated substrate expansion:Domestic capacity buildout timelines lag module demand curves, forcing Japanese suppliers to compete for Taiwanese and Korean wafer allocations.
- Silicon IGBT cost base:Mature pricing for conventional silicon devices in industrial motor drives above 600V slows substitution economics outside premium automotive applications.
Strategic Opportunities
- South Korea's K-REACH chemical regulations:Carbon neutrality documentation requirements for foundry operations are creating first-mover advantage for suppliers with lifecycle emissions certification.
- Rail and traction systems:Proprietary trench-gate SiC MOSFET designs optimized for heavy-duty cycling are penetrating mass transit electrification projects across the region.
- Direct module-maker relationships:Tier-one automotive suppliers are bypassing traditional distribution channels to secure long-term supply agreements with foundries in Malaysia and Vietnam.
Industry Challenges
- Epitaxial growth technician scarcity:The specialized skill set for SiC crystal defect management is concentrated among a small cohort of engineers, constraining foundry expansion timelines.
- Multi-jurisdiction certification synchronization:China's MIIT GB standards, Japan's JIS frameworks, and South Korea's KC marking create overlapping compliance timelines that delay platform rollouts.
Report Scope
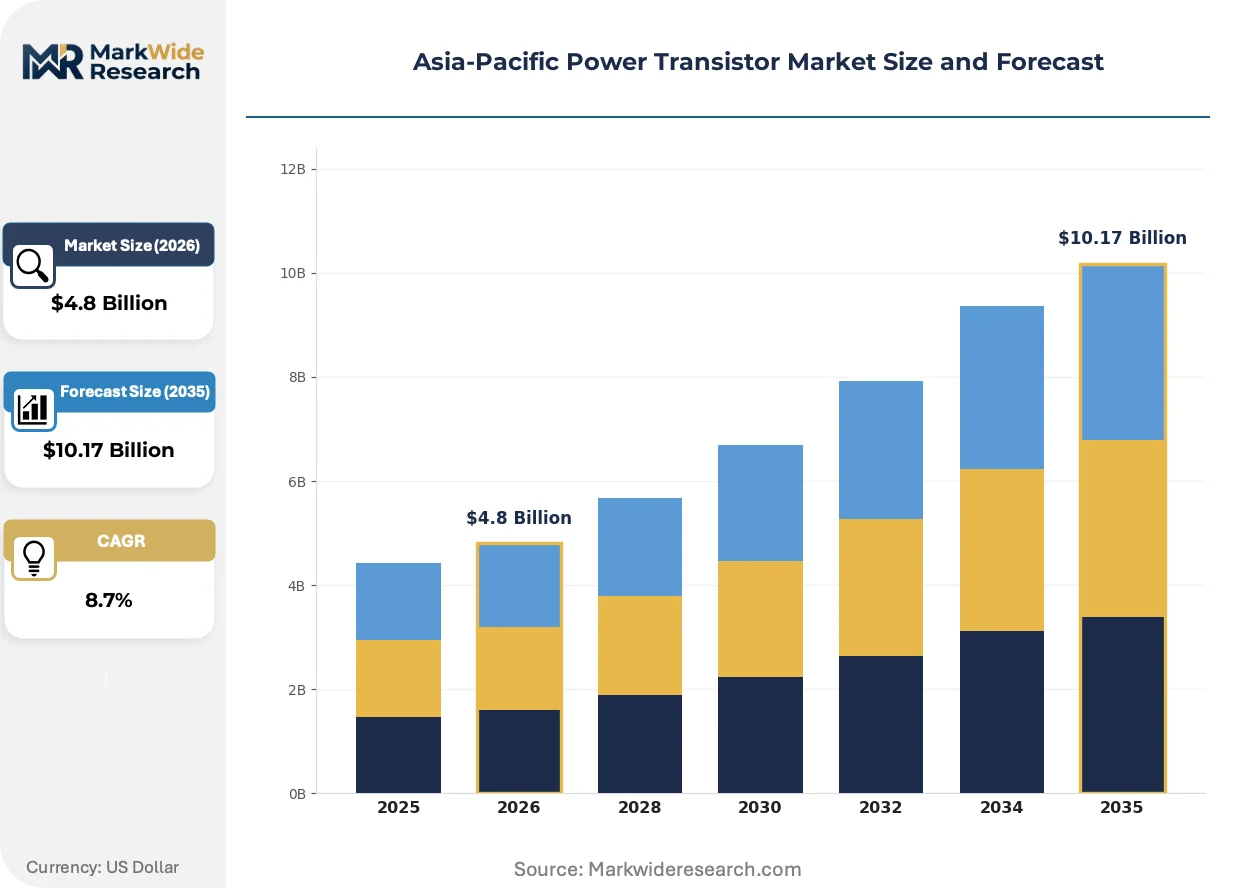
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Power Transistor Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bipolar Junction Transistor, Field Effect Transistor, IGBT, MOSFET Technology: SIC, GAN, BJT, LDMOS Application: Renewable Energy Systems, Consumer Electronics, Industrial Automation, Electric Vehicles End User: Telecommunications, Automotive, Aerospace, Healthcare |
| Companies Covered | Infineon Technologies, ROHM Semiconductor, Mitsubishi Electric, Texas Instruments, NXP Semiconductors, Toshiba, Fuji Electric, Champion Microelectronics, Renesas Electronics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Power Transistor Market Trends and Innovations
Power transistor architecture is fragmenting across application-specific optimized designs rather than converging on universal platforms, with thermal management and switching frequency requirements dictating material selection.
Silicon carbide power modules are modularizing from discrete component sales into integrated thermal-mechanical-electrical subsystems. Tier-one automotive suppliers in South Korea are specifying complete inverter building blocks rather than bare dies. This compression of the value chain is displacing traditional module assemblers and forcing foundries to develop in-house packaging capabilities.
China's MIIT enforcement of GB/T automotive semiconductor reliability standards is creating a bifurcated certification landscape. Foreign suppliers face extended validation timelines for imported power modules. Domestic foundries with pre-certified process flows are capturing design wins in local EV platforms ahead of multinational competitors.
Long-term supply agreements are replacing spot-market purchasing for SiC substrates and epitaxial wafers. Japanese and Korean automotive module makers are locking in multi-year allocations directly with substrate growers, bypassing merchant distributors. This channel compression is most visible in China's Yangtze River Delta, where foundries and automakers co-locate procurement teams within shared industrial parks.
Asia-Pacific Power Transistor Market Segmentation
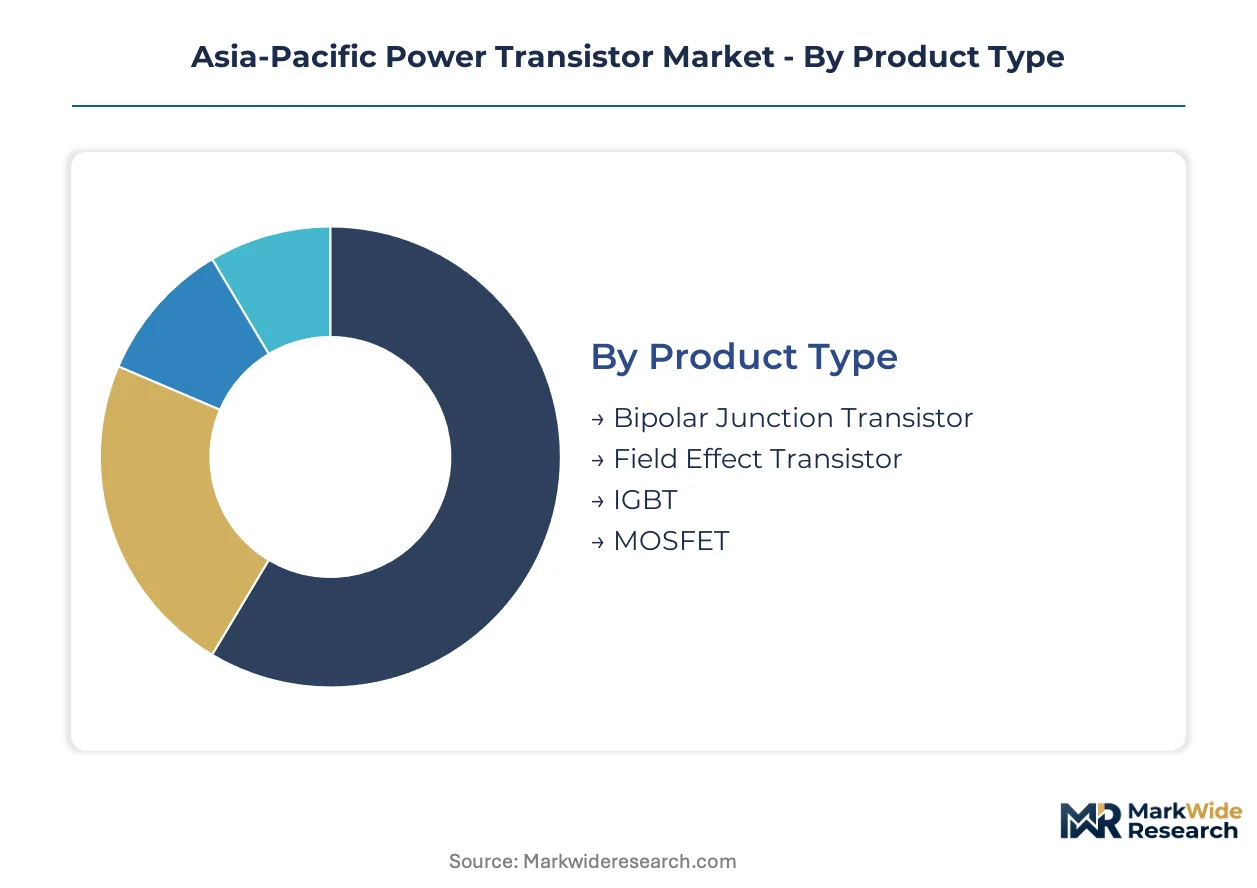
Power transistor procurement patterns across the Asia-Pacific diverge sharply by voltage class and thermal requirements. Upgrade cycles in automotive traction systems and renewable energy inverters are compressing technology refresh timelines from seven years toward four.
Product Type:
Replacement cycles in industrial motor drives and EV powertrains are shortening as wide-bandgap alternatives achieve cost parity with legacy silicon platforms.
- IGBT:Insulated-gate bipolar transistors combine MOS gate control with bipolar conduction, delivering 600V to 6.5kV blocking capability. Demand concentrates in China's wind turbine converters and Japan's rail traction systems where METI efficiency mandates drive retrofit programs.
- MOSFET:Metal-oxide-semiconductor field-effect transistors enable switching frequencies above 100kHz with minimal gate drive losses. South Korean EV auxiliary systems and Shenzhen consumer electronics clusters specify super-junction and planar designs for onboard chargers and DC-DC converters.
- Bipolar Junction Transistor:Legacy silicon BJTs persist in cost-sensitive linear regulators and low-frequency switching below 10kHz.
- Field Effect Transistor:General-purpose FET architectures serve discrete switching applications in Jiangsu province appliance manufacturing.
Volume placements concentrate in IGBT platforms for industrial drives; the faster expansion belongs to MOSFET designs penetrating EV auxiliary circuits.
Technology:
Cost tier stratification separates premium wide-bandgap substrates from mature silicon processes, with foundry pricing reflecting epitaxial growth complexity.
- SiC:Silicon carbide delivers 10x higher breakdown field strength than silicon, enabling thinner drift layers and reduced switching losses. Chinese EV manufacturers in Ningbo and Xi'an specify 650V to 1,700V SiC MOSFETs for traction inverters as GB standards tighten efficiency thresholds.
- GaN:Gallium nitride supports switching frequencies beyond 1MHz with minimal reverse recovery charge. South Korean telecommunications infrastructure and Tokyo data center power supplies adopt GaN HEMTs for 48V bus converters.
- BJT:Conventional bipolar technology retains position in linear audio amplifiers and legacy industrial controls.
- LDMOS:Laterally-diffused MOS structures dominate RF power amplification for base stations across Australia's telecommunications upgrade programs.
Cost tiers separate SiC for premium automotive traction from GaN for mid-range telecom power; steepest expansion trajectory sits with SiC as substrate supply scales.
Application:
Customer type differentiation splits between capital-intensive infrastructure operators and high-volume electronics assemblers with divergent procurement timelines.
- Electric Vehicles:Traction inverters, onboard chargers, and DC-DC converters require 650V to 1,200V switching devices with automotive-grade reliability. Japanese and South Korean automakers specify SiC modules for next-generation platforms as fleet emissions frameworks tighten.
- Renewable Energy Systems:Solar inverters and wind turbine converters demand 1,200V to 1,700V devices with 25-year operational lifespans. China's coastal manufacturing clusters co-locate module assembly with photovoltaic panel production.
- Industrial Automation:Motor drives and servo systems above 600V specify IGBT modules with integrated gate drivers.
- Consumer Electronics:Low-voltage MOSFETs populate smartphone chargers and laptop adapters from Shenzhen and Dongguan assembly lines.
Volume placements concentrate in industrial automation retrofits; the fastest share gains belong to electric vehicle traction systems.
End User:
Supply concentration varies by certification intensity, with automotive and aerospace segments demanding traceable manufacturing records.
- Automotive:Tier-one suppliers in South Korea and Japan procure qualified power modules through direct foundry relationships, bypassing distribution channels. China's MIIT enforces GB/T reliability testing that gates market access for imported devices.
- Telecommunications:Base station power amplifiers and data center rectifiers specify LDMOS and GaN devices from Malaysian and Vietnamese foundries.
- Aerospace:Satellite power conditioning and aircraft actuation systems require radiation-hardened and high-reliability screening.
- Healthcare:MRI gradient amplifiers and surgical equipment specify isolated gate drivers with fault protection.
Volume placements concentrate in telecommunications infrastructure; the fastest expansion belongs to automotive electrification platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates along China's eastern seaboard, where EV module makers cluster within industrial parks to compress supply loops. Japanese and South Korean automakers drive premium-tier procurement through direct foundry relationships. Regulatory divergence across MIIT, METI, and domestic frameworks creates overlapping compliance timelines that shape market access.
China
Domestic EV manufacturers in Ningbo and Xi'an specify 650V to 1,700V SiC MOSFETs for traction inverters as MIIT tightens efficiency thresholds through GB standards. The ministry's mandatory reliability testing gates market access for imported power modules, accelerating localization investments. Jiangsu and Guangdong provinces co-locate foundries and module assemblers to shorten logistics cycles.
Japan
Automakers specify SiC modules for next-generation platforms to meet METI-coordinated fleet emissions frameworks. The ministry binds equipment makers and material suppliers through technology roadmaps that expand domestic substrate capacity. Nagoya and Osaka industrial corridors anchor rail traction retrofits where proprietary trench-gate designs penetrate mass transit electrification.
South Korea
Tier-one automotive suppliers procure qualified modules through direct foundry relationships, bypassing traditional distribution channels. K-REACH chemical regulations and carbon neutrality commitments force foundries to document lifecycle emissions across epitaxial growth stages. Seoul Capital Area and Busan-Ulsan clusters host procurement teams co-located with automaker technical centers.
Malaysia
Long-term supply agreements replace spot-market purchasing as module makers lock multi-year substrate allocations directly with growers. The country's semiconductor fabrication zones attract packaging operations seeking proximity to Singapore logistics hubs. Penang and Kulim industrial parks sustain wafer supply corridors serving Asian EV module makers.
Vietnam
Telecommunications infrastructure and data center power supplies specify GaN and LDMOS devices from emerging fabrication zones. The country's electronics manufacturing clusters absorb packaging operations displaced by coastal Chinese cost pressures. Ho Chi Minh City and Hanoi industrial corridors host module assembly for regional distribution networks.
Asia-Pacific Power Transistor Market Competitive Landscape
Capacity expansion dominates the current landscape as substrate bottlenecks force foundries to secure captive supply. The vendor base stratifies across three tiers: integrated device manufacturers with in-house substrate growth, fabless designers dependent on merchant foundries, and module assemblers compressing value chains into thermal-mechanical-electrical subsystems. Two strategic archetypes occupy distinct positions: European-headquartered suppliers leveraging Dresden-to-Kulim manufacturing corridors, and Japanese industrial conglomerates anchoring rail and traction specializations. Competitive moves concentrate on backward integration into epitaxial wafer supply and direct automotive partnerships that displace distribution channels.
Among European-headquartered suppliers, Infineon Technologies and NXP Semiconductors occupy positions within the integrated device manufacturer tier, representing archetypes of manufacturing corridor strategies. Japanese industrial conglomerates Mitsubishi Electric and Toshiba exemplify diversified technology portfolios spanning legacy silicon expertise and gradual wide-bandgap migration. ROHM Semiconductor, bearing Japanese geographic origin in its market positioning, sits within the specialized substrate supplier archetype. Texas Instruments and Renesas Electronics represent contrasting scale vectors—American broad-line semiconductor exposure against Japanese automotive-focused consolidation.
| Leading Market Players |
|---|
| Infineon Technologies |
| ROHM Semiconductor |
| Mitsubishi Electric |
| Texas Instruments |
| NXP Semiconductors |
| Toshiba |
| Fuji Electric |
| Champion Microelectronics |
| Renesas Electronics |
| Others |
Pricing and Supply Chain Analysis
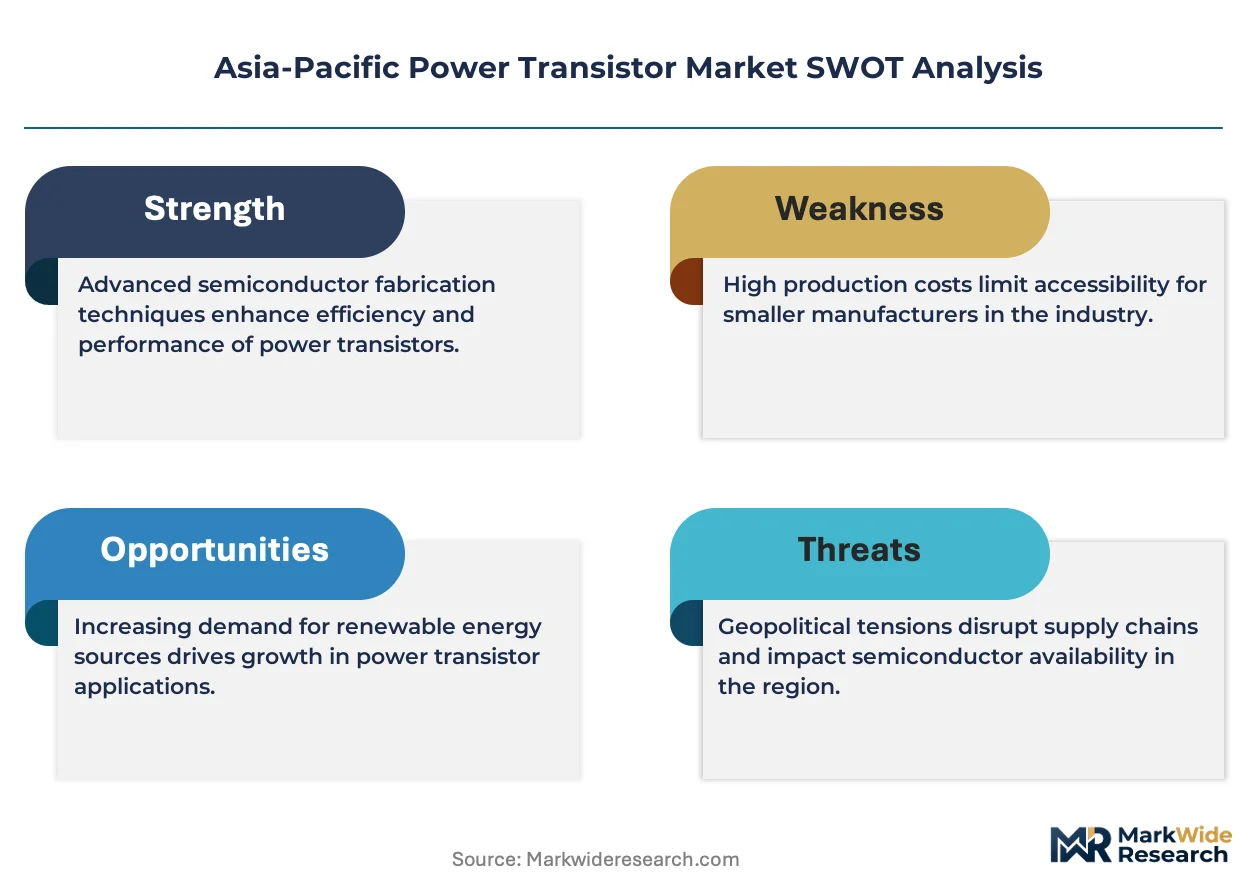
Certification-grade bifurcation between automotive-qualified and industrial-grade power transistors manifests in both pricing spreads and supply chain configurations across the Asia-Pacific. China's MIIT GB standards create a compliance ladder where pre-certified domestic foundries command premium positioning over import-dependent suppliers facing extended validation timelines.
Pricing Analysis
Volume placements in mature silicon IGBTs run on thin margins, while SiC MOSFETs for traction inverters sustain structural premiums through substrate scarcity. Price differentiation hinges on automotive-grade reliability certification and wafer diameter scale, with 6-inch SiC commanding substantial markups over legacy silicon. Cost compression in industrial-grade devices is intensifying because Chinese foundries are scaling 8-inch silicon lines. Fleet procurement teams at Japanese automakers show lowest price sensitivity; appliance assemblers in Jiangsu province exhibit highest.
Supply Chain Analysis
Qualification gating through China's MIIT GB standards, Japan's JIS frameworks, and South Korea's KC marking creates overlapping compliance timelines that fragment supplier eligibility. Substrate fabrication concentrates in China, Japan, and Taiwan, with epitaxial wafer growth drawing from silicon carbide boules and high-purity graphite crucibles. Single-source vulnerability sits with 6-inch SiC wafer supply among equipment-constrained growers. Distribution runs through direct foundry relationships that displace traditional module assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific power transistor market sits in a technology-transition phase as silicon carbide displaces legacy silicon IGBTs in automotive traction systems. This substitution dynamic rewards early movers with captive substrate supply and certified process flows.
For Market Incumbents: Lock in long-term substrate allocations directly with SiC boule growers before capacity constraints harden. Secure automotive qualification through China's MIIT GB standards ahead of multinational competitors facing extended import validation timelines. Backward integration into epitaxial growth capabilities protects margin structure against merchant wafer price volatility.
For New Entrants and Emerging Players: Direct-to-automaker digital procurement platforms offer route-to-market acceleration for qualified module suppliers. White-space targets sit in Vietnam's emerging packaging zones and Malaysia's Kulim corridor serving Korean Tier 1s. Telecommunications infrastructure GaN devices present lower certification barriers than automotive traction systems.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated substrate-to-module suppliers given China's localization mandates tightening market access for import-dependent competitors. Long-term viability centers on 5-10 year substrate supply security rather than spot-market merchant positioning. Watch for MIIT GB certification timeline acceleration as the inflection signal for competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Substrate Growth | Captive wafer supply secures allocation priority as 6-inch capacity bottlenecks persist. |
| Automotive Qualification Investment | MIIT GB pre-certification accelerates design wins in Ningbo and Xi'an EV platforms. |
| Direct Foundry-Automaker Partnerships | Channel compression bypasses module assemblers in Seoul Capital Area procurement clusters. |
| Packaging Capability Expansion | In-house thermal-mechanical integration responds to Korean Tier 1 subsystem specifications. |
| Lifecycle Emissions Certification | K-REACH documentation creates first-mover advantage for carbon-neutral foundry operations. |
Research Methodology
Trade databases, foundry capacity disclosures, and automotive platform specifications formed the secondary backbone of this analysis. Primary interviews with SiC substrate procurement managers, power module design engineers, and Tier 1 supplier sourcing directors combined with bottom-up and top-down triangulation. Secondary validation drew from MIIT regulatory filings, METI technology roadmaps, and customs data on epitaxial wafer imports.
Bottom-up modeling of wafer supply, module assembly capacity, and end-use demand converged with top-down macroeconomic drivers across the projection horizon. Segmentation dimensions included voltage class, technology material, application end-use, and regional regulatory cluster. CAGRs derived from supply-demand balance modeling through the forecast period, with SiC substrate expansion timelines and EV platform rollout schedules as key inputs.
The model holds under stable regulatory enforcement timelines; deviation in MIIT certification acceleration or METI subsidy shifts would alter competitive positioning. Forecasts reflect assumptions on substrate capacity scaling and automotive qualification success rates. A model refresh is warranted upon material change in China's GB standard enforcement stringency or Japanese domestic substrate expansion timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Europe MLCC Market
Semiconductor Devices
Semiconductor Memory IP Market
Semiconductor Devices
Metal-Semiconductor-Metal Photodetector Market
Semiconductor Devices
Global Small Signal Diode Market
Semiconductor Devices
Gan Transistor Market
Semiconductor Devices
AIN DBC Ceramic Substrate Market
Semiconductor Devices
Silicon Carbide Mosfets Market
Semiconductor Devices
Transistor Arrays Market
Semiconductor Devices
Gan-On-Silicon Market
Semiconductor Devices
Data Processing Unit Market
Semiconductor Devices
Chip Equalizers Market
Semiconductor Devices
Quartz Crystal Oscillators Market
Semiconductor Devices
Field Effect Transistor Market
Semiconductor Devices
Hairpin Stator Market
Semiconductor Devices
Thin Wafer Market
Semiconductor Devices
High Voltage Diodes Market