
 Temperature Detection Screen Market | 2026-2036
Temperature Detection Screen Market Size, Share, and Industry Trends Forecast 2026-2036
Temperature Detection Screen Market Analysis
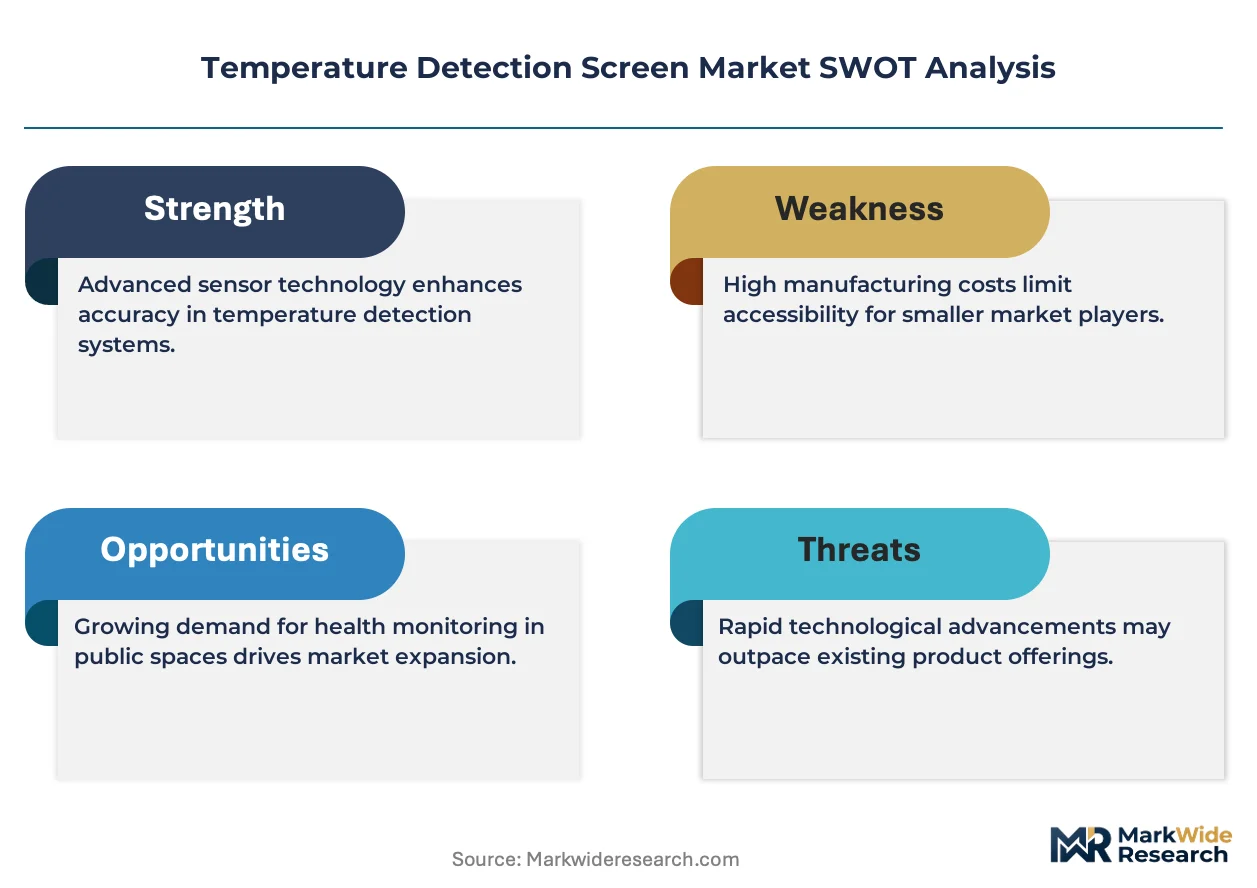
Healthcare facilities is collapsing into manufacturing plants as the dominant buyer archetype for temperature detection screens, driven by industrial OSHA compliance mandates and worker safety automation. FLIR Systems anchors the thermal imaging sub-area through deep R&D intensity in uncooled detector arrays. Honeywell International dominates building automation integration, leveraging its channel control across facility management networks. Siemens competes in Europe with process instrumentation expertise that extends into plant-wide thermal monitoring architectures.
Temperature detection screens are non-contact measurement instruments that convert infrared radiation emitted by surfaces into calibrated temperature readings, typically operating within spectral bands of 8–14 micrometers for human-targeted applications. Their primary commercial purpose is mass fever screening and industrial thermal anomaly detection without physical proximity. Infrared cameras capture the largest margin pool among product types due to permanent installation contracts in airports and event venues. Thermal imaging technology leads volume in industrial settings where passive sensors struggle with emissivity variation across metal and ceramic surfaces. Smart wearables represent the fastest-growing application among educational institutions seeking distributed student health monitoring.
FDA device classification rules and OSHA workplace exposure standards jointly determine product certification requirements and procurement eligibility in the United States. ISO 80601-2-59 technical specifications for screening thermographs shape design thresholds for clinical accuracy claims. The EU Medical Device Regulation imposes conformity assessment burdens on manufacturers seeking European healthcare access. Stakeholders must monitor evolving cybersecurity frameworks for networked thermal sensors as connectivity becomes standard in enterprise deployments.
Market Dynamics
FDA clearance pathways for clinical-grade infrared thermography are tightening performance benchmarks while healthcare facilities expand non-contact fever screening protocols across outpatient clinics and hospital entryways.
Growth Catalysts
- OSHA workplace safety mandates:Manufacturing plants face intensifying compliance pressure to automate thermal anomaly detection for worker protection.
- ISO 80601-2-59 technical specifications:Screening thermograph accuracy standards validate clinical-grade claims and unlock hospital procurement eligibility.
- Smart wearables:Educational institutions deploy distributed student health monitoring systems requiring networked temperature sensing infrastructure.
Market Restraints
- Uncooled detector array supply concentration:Manufacturing bottlenecks in microbolometer fabrication constrain volume scaling.
- Emissivity variation across metal and ceramic surfaces:Industrial applications suffer measurement drift requiring recalibration protocols.
- EU Medical Device Regulation conformity assessment:Extended certification timelines delay European healthcare market entry.
Strategic Opportunities
- Building automation integration:Facility management networks seek unified thermal monitoring architectures combining HVAC, access control, and health screening.
- Industrial process instrumentation:Plant-wide thermal monitoring extends beyond safety into predictive maintenance and quality control.
- Federal pandemic preparedness funding:United States government appropriations sustain institutional procurement momentum for multi-year deployment cycles.
Industry Challenges
- Cybersecurity framework gaps:Networked thermal sensors lack standardized hardening protocols for enterprise IT environments.
- Interoperability with legacy access control:Retrofitting temperature screens into existing building management systems demands custom middleware development.
- Field calibration expertise shortage:Clinical accuracy claims require trained technicians for traceable blackbody reference verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Temperature Detection Screen Market |
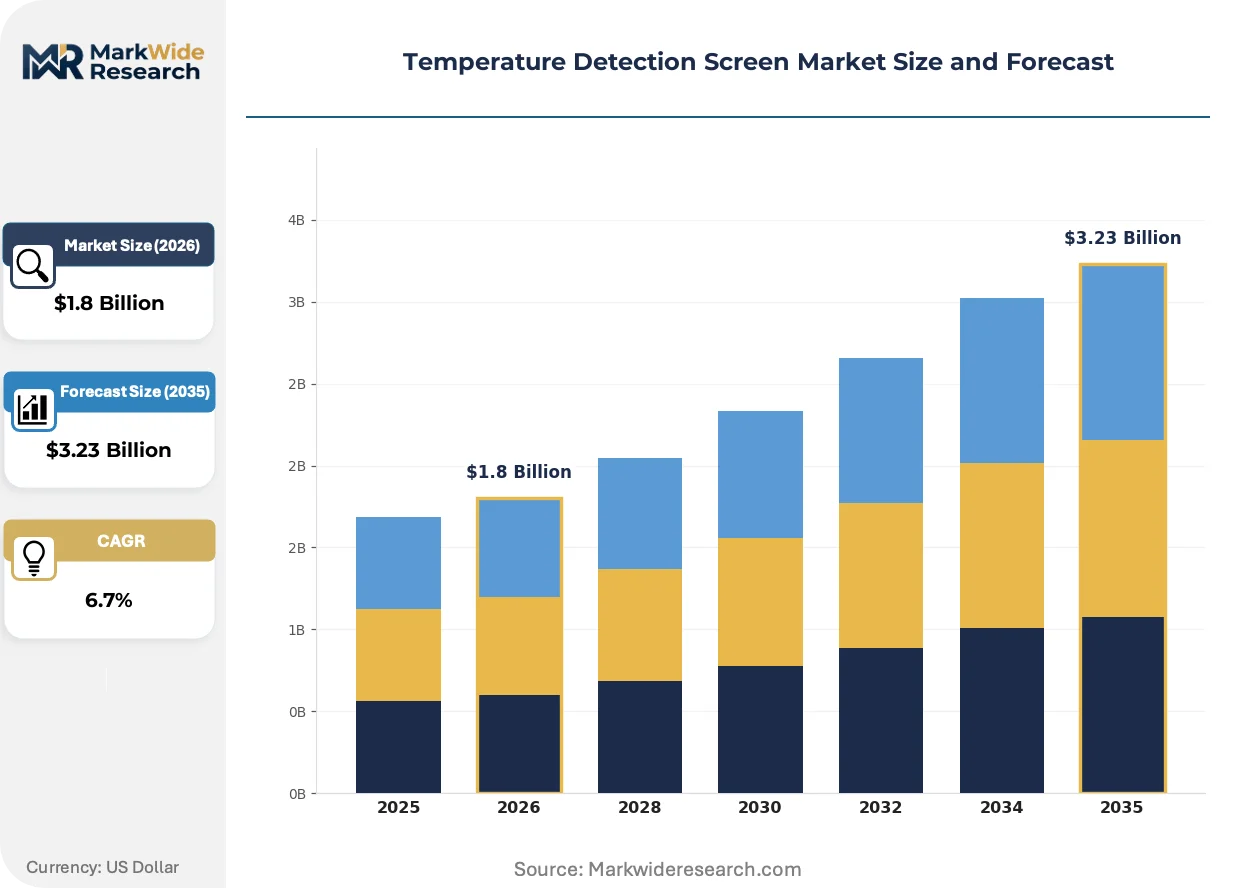
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared Cameras, Thermographic Sensors, Smart Wearables, Handheld Thermometers Application: Healthcare Facilities, Industrial Settings, Educational Institutions, Public Venues Technology: Active Sensors, Passive Sensors, Thermal Imaging, Optical Sensors End User: Clinics, Manufacturing Plants, Airports, Event Venues |
| Companies Covered | 3M Company, FLIR Systems, Honeywell International, TE Connectivity, Texas Instruments, Analog Devices, Siemens, Emerson Electric, Microchip Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Temperature Detection Screen Market Emerging Trajectories
Multi-spectral sensor fusion and edge computing architectures are compressing form factors while expanding deployment scenarios beyond traditional checkpoint screening.
Microbolometer arrays with reduced pixel pitch are supplanting thermopile detectors in handheld screening devices. Airport authorities and event venue operators are accelerating procurement of permanent installation contracts requiring higher spatial resolution. The shift is compressing margins for single-point infrared sensors while expanding service revenue from integrated analytics platforms.
EU AI Act risk classification rules are redefining algorithmic transparency requirements for automated fever detection systems. Manufacturers must document decision logic and maintain human oversight protocols for high-risk biometric applications. Healthcare procurement committees in Germany and France now prioritize vendors with established conformity assessment procedures.
Subscription-based thermal monitoring services are displacing capital purchase models in educational and corporate campuses. Channel partners bundle hardware, cloud analytics, and compliance reporting into per-location monthly fees. This restructuring is most visible in United States K-12 districts seeking to distribute capital expenditures across operating budgets.
Temperature Detection Screen Market Segmentation
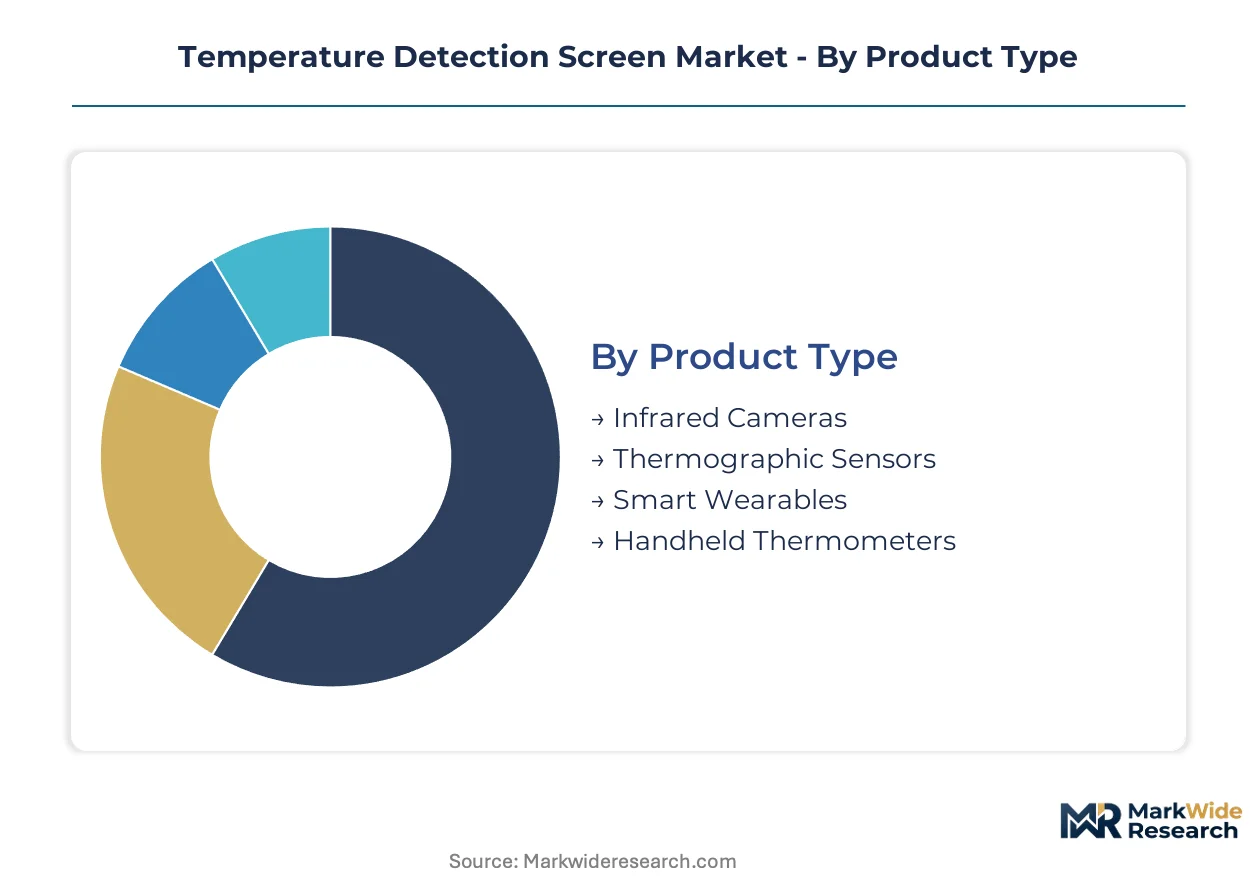
Product architecture choices determine margin capture and procurement eligibility across clinical, industrial, and public safety deployments. Technology selection shapes emissivity compensation requirements, while end-user concentration dictates whether vendors pursue FDA clearance or OSHA compliance pathways.
Product Type:
Thermopile detectors face substitution pressure from microbolometer arrays as uncooled infrared technology scales down in cost and form factor.
- Infrared Cameras:Permanent installation systems with focal plane arrays delivering spatial resolution above 320x240 pixels. Demand concentrates in United States airport authorities and event venue operators seeking mass screening throughput with minimal staffing.
- Thermographic Sensors:Fixed-mount single-point detectors calibrated for continuous monitoring applications. Manufacturing plants in Germany and Japan deploy these for conveyor belt thermal anomaly detection where emissivity-stable surfaces permit simpler compensation algorithms.
- Smart Wearables:Distributed temperature sensing patches and wristbands networked through Bluetooth or LoRa protocols.
- Handheld Thermometers:Portable single-point devices with laser targeting for spot measurements.
Infrared Cameras anchors the volume base while Smart Wearables gains share at the steepest rate.
Application:
Cost tier stratification separates capital-intensive permanent installations from subscription-based distributed monitoring services.
- Healthcare Facilities:Outpatient clinics and hospital entryways requiring FDA-cleared devices meeting ISO 80601-2-59 accuracy specifications. United States procurement committees prioritize vendors with established 510(k) pathways and blackbody calibration protocols.
- Industrial Settings:Manufacturing floors and process plants where OSHA workplace exposure standards mandate automated thermal monitoring for worker protection. Metal fabrication facilities in the United States Midwest and automotive assembly plants in Mexico drive volume.
- Educational Institutions:K-12 districts and university campuses seeking distributed student health monitoring.
- Public Venues:Stadiums, convention centers, and transportation terminals requiring high-throughput screening.
Healthcare Facilities anchors the volume base while Educational Institutions climbs the fastest as subscription models displace capital purchases.
Technology:
Supply concentration in microbolometer fabrication favors thermal imaging architectures over passive thermopile alternatives.
- Thermal Imaging:Microbolometer-based focal plane arrays capturing infrared radiation across 8-14 micrometer spectral bands. Industrial applications in ceramics processing and metal casting favor this technology where emissivity variation demands spatial resolution for compensation algorithms.
- Active Sensors:Systems incorporating reference sources or controlled illumination for enhanced measurement stability. United States pharmaceutical cleanrooms and semiconductor fabrication facilities deploy these where traceable accuracy documentation supports regulatory compliance.
- Passive Sensors:Uncooled detectors relying solely on emitted radiation without active compensation.
- Optical Sensors:Visible-spectrum cameras with algorithmic temperature estimation.
Thermal Imaging anchors the volume base while Active Sensors expands most quickly in regulated manufacturing environments.
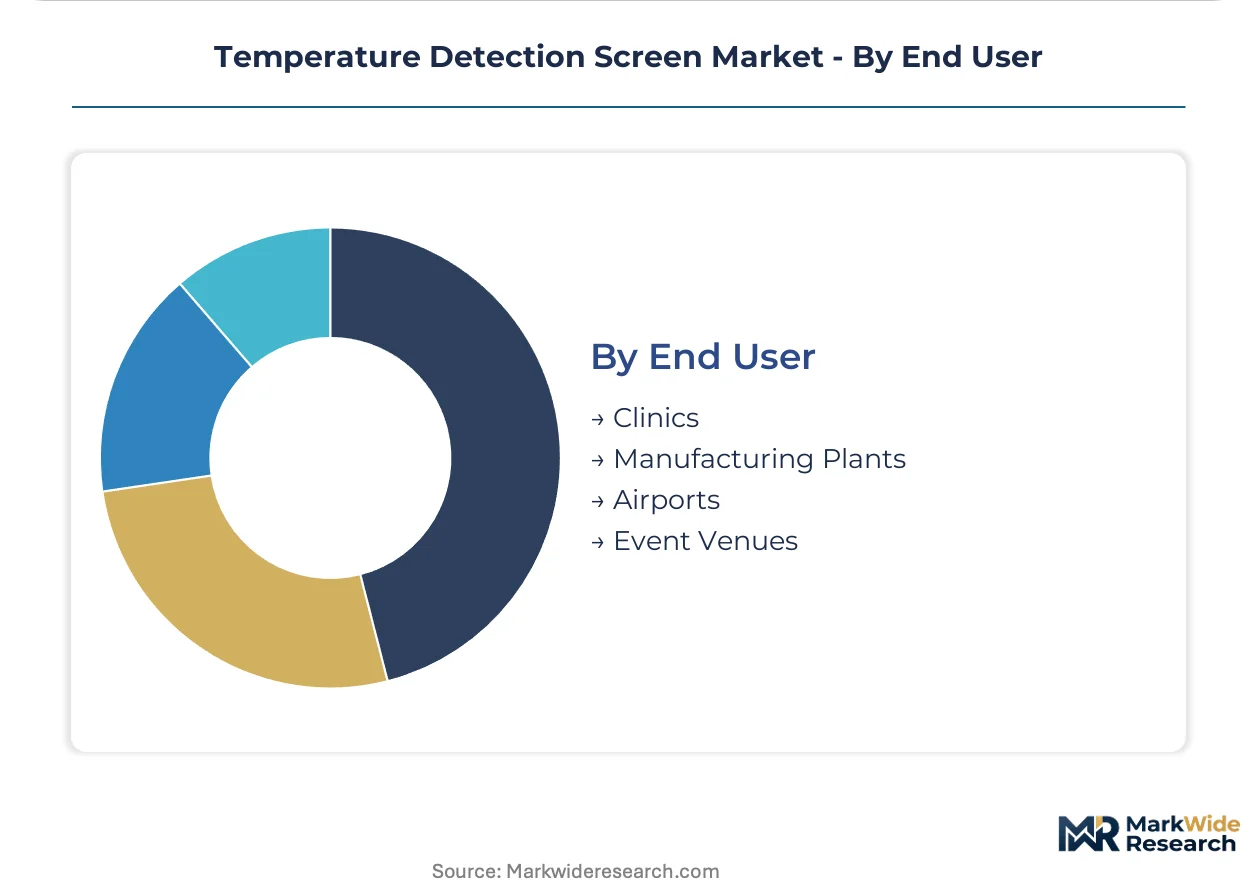
End User:
Customer type determines certification burden, with clinical endpoints requiring FDA clearance and industrial endpoints governed by OSHA performance mandates.
- Airports:Federal aviation authorities and port authorities in the United States, United Kingdom, and Singapore procurement permanent installation contracts with integrated analytics platforms. TSA coordination requirements and customs screening protocols demand interoperability with existing security infrastructure.
- Manufacturing Plants:Automotive assembly, steel production, and chemical processing facilities automating worker thermal protection. OSHA compliance mandates in the United States and Germany's employers' liability insurance associations drive standardization around predictive maintenance integration.
- Clinics:Outpatient facilities and urgent care centers requiring clinical-grade screening thermographs.
- Event Venues:Stadium operators and convention center managers seeking temporary or seasonal deployment flexibility.
Airports anchors the volume base while Manufacturing Plants gains share at the steepest rate as industrial safety automation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Microbolometer fabrication concentrates in the United States, Japan, and Germany, creating supply dependencies that shape procurement patterns across clinical and industrial deployments. Demand fragmentation follows regulatory divergence, with FDA clearance pathways, EU MDR conformity assessments, and China's NMPA standards creating distinct market access requirements.
United States
Federal pandemic preparedness funding sustains multi-year procurement cycles across hospital systems and airport authorities. FDA 510(k) clearance pathways for clinical-grade infrared thermography tighten accuracy benchmarks for outpatient clinic deployments. Dallas-Fort Worth International Airport and Hartsfield-Jackson Atlanta anchor permanent installation demand for integrated thermal screening infrastructure.
Germany
Employers' liability insurance associations mandate automated thermal monitoring across automotive assembly and metal fabrication floors. EU Medical Device Regulation conformity assessments extend certification timelines for clinical-grade screening thermographs. Stuttgart's automotive cluster and Ruhr Valley steel operations drive industrial thermal imaging procurement for predictive maintenance integration.
China
GB standards for infrared temperature measurement and NMPA device registration create dual compliance layers for domestic and export-bound manufacturers. Yangtze River Delta electronics fabrication and Pearl River Delta export processing zones concentrate microbolometer assembly capacity. Shanghai Pudong International Airport deploys high-throughput screening systems for customs coordination protocols.
Japan
METI industrial safety guidelines and PMDA medical device standards govern product classification for manufacturing plant and clinical applications. Kansai region semiconductor fabrication facilities and Chubu automotive supplier networks deploy active sensor systems for traceable accuracy documentation. Osaka-based process instrumentation specialists extend plant-wide thermal monitoring architectures.
Singapore
Changi Airport Group procurement specifications for integrated security infrastructure drive demand for networked thermal sensors with analytics platforms. The country's national health technology regulator aligns screening thermograph standards with WHO technical guidance. Biomedical manufacturing clusters in Tuas and one-north deploy continuous monitoring for cleanroom worker protection protocols.
Temperature Detection Screen Market Vendor Landscape
Concentration sits with diversified industrial conglomerates controlling detector array supply and building automation channels. The vendor base spans three tiers: integrated sensor manufacturers with captive microbolometer fabrication, facility management platform vendors leveraging channel control, and specialized thermography equipment providers. Strategic moves center on backward integration into uncooled detector production and geographic expansion through regional certification partnerships.
Within the integrated sensor tier, FLIR Systems and Texas Instruments exemplify archetypes of detector technology control and semiconductor-scale manufacturing respectively. Honeywell International occupies a position bridging building automation integration with enterprise facility management networks. Siemens anchors European process instrumentation expertise extending into plant-wide thermal monitoring architectures. These three represent distinct competitive vectors: component supply dominance, channel control through facility networks, and industrial system integration.
| Leading Market Players |
|---|
| 3M Company |
| FLIR Systems |
| Honeywell International |
| TE Connectivity |
| Texas Instruments |
| Analog Devices |
| Siemens |
| Emerson Electric |
| Microchip Technology |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts for microbolometer arrays lock in supply access and price visibility for infrared camera manufacturers serving United States airport authorities and German automotive clusters. These arrangements insulate volume buyers from spot-market volatility in uncooled detector fabrication while embedding FDA and ISO 80601-2-59 certification costs into multi-year unit economics.
Pricing Analysis
FDA 510(k) clearance pathways dictate the pricing tier structure across clinical-grade screening thermographs. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared hospital systems from OSHA-compliant industrial units and uncertified consumer devices. Cost compression in the economy tier is intensifying because educational institutions favor subscription-based smart wearables over capital purchases. Healthcare procurement committees show the least price sensitivity given liability exposure, while K-12 districts negotiate aggressively on per-location monthly fees.
Supply Chain Analysis
Strategic stockpiling of vanadium oxide and amorphous silicon substrates characterizes procurement behavior among tier-one infrared sensor manufacturers. Microbolometer fabrication concentrates in the United States, Japan, and Germany, with final assembly drawing from Malaysia and Mexico. Supply chain risk centers on single-source vulnerability for specialized readout integrated circuits. Distribution runs through building automation channel partners and medical device distributors serving distinct end-user certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from smartphone-integrated thermal sensors and algorithmic fever detection apps that erode demand for dedicated hardware. Defense requires anchoring in regulatory moats and supply chain control.
For Market Incumbents: Compound defensive positioning through backward integration into microbolometer fabrication and exclusive channel control across facility management networks. FLIR Systems and Honeywell International demonstrate how captive detector supply and building automation integration resist commoditization from smartphone-based alternatives. Prioritize ISO 80601-2-59 certification investment to maintain hospital procurement eligibility against consumer-grade substitutes. For New Entrants and Emerging Players: Lead with software-analytics differentiation targeting educational institutions seeking subscription-based distributed monitoring without capital expenditure approval cycles. White-space opportunity concentrates in United States K-12 districts and community college systems where procurement flexibility exceeds healthcare and airport segments. Partner with existing IoT infrastructure vendors to bypass hardware certification timelines. For Investors and Strategic Acquirers: Capital is best deployed toward integrated sensor manufacturers with captive uncooled detector production and established FDA 510(k) pathways. Long-term viability hinges on regulatory compliance automation rather than hardware innovation alone. Monitor EU AI Act algorithmic transparency enforcement as an inflection signal for automated fever detection system valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Detector Fabrication | Captive microbolometer supply insulates margins from foundry bottlenecks in United States and Japan. |
| FDA 510(k) Clearance Pathway Investment | Clinical-grade certification unlocks hospital procurement eligibility against consumer-grade substitutes. |
| Building Automation Platform Integration | Honeywell International and Siemens demonstrate channel control across facility management networks. |
| Subscription Service Model Transition | Educational institutions in United States K-12 systems favor operating budget distribution over capital purchases. |
| EU AI Act Conformity Assessment | Algorithmic transparency documentation becomes prerequisite for German and French healthcare procurement. |
Methodological Framework
A standing panel of hospital biomedical engineers, airport security infrastructure managers, manufacturing plant safety officers, and educational technology procurement directors provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with GPO contracts managers and aftermarket service heads with secondary validation against FDA 510(k) filings, ISO technical committee documentation, and OSHA enforcement data. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Cross-validation against external benchmarks confirmed analytical consistency across product type, application, technology, and end-user dimensions. Modeled segmentation included infrared cameras versus smart wearables, healthcare facilities versus industrial settings, thermal imaging versus active sensors, and airports versus manufacturing plants. CAGRs were derived from installed base growth rates and replacement cycle analysis rather than extrapolated shipment data alone. Forecast inputs incorporated microbolometer fabrication capacity announcements and federal pandemic preparedness appropriation trends.
The analysis sits within stated boundaries; outcomes outside sustained OSHA enforcement intensity or FDA clearance pathway stability would require recalibration. Forecasts reflect documented assumptions regarding detector array supply scaling and regulatory framework continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Portable Metal Detectors Market
Detection and Regulation Devices
ESD Suppressors Market
Detection and Regulation Devices
Voltage Detection System Market
Detection and Regulation Devices
Pin and Sleeve Devices Market
Detection and Regulation Devices
Radiometric Detectors Market
Detection and Regulation Devices
Global Gas Leak Detectors Market
Detection and Regulation Devices
Infrared Detection Chip Market
Detection and Regulation Devices
Global Tunnel Diode Detectors Market
Detection and Regulation Devices
Water Leak Detector Market
Detection and Regulation Devices
IR Detector Market
Detection and Regulation Devices
Ultraviolet Currency Detector Market
Detection and Regulation Devices
Transient Voltage Suppressor Market
Detection and Regulation Devices
EMEA Frequency Control and Timing Devices Market
Detection and Regulation Devices
Betavoltaic Device Market
Detection and Regulation Devices
US Pin and Sleeve Devices Market
Detection and Regulation Devices
Arc Fault Detection Devices Market