
 Photoionization Detectors Market | 2026-2036
Photoionization Detectors Market Size, Share, and Industry Trends Forecast 2026-2036
Photoionization Detectors Market Analytics
ATEX and IECEx certification is unwinding competitive access across the Photoionization Detectors landscape, forcing smaller participants toward costly redesign cycles. Honeywell Analytics leverages its captive sensor fabrication to sustain margin pressure at the premium tier. MSA Safety anchors North American channel density through industrial distribution partnerships. Ion Science dominates European portable specifications with proprietary lamp longevity technology.
A photoionization detector employs ultraviolet light to ionize volatile organic compounds, generating a measurable current proportional to contaminant concentration with detection thresholds reaching parts-per-billion sensitivity. The device serves critical industrial hygiene and hazmat response functions where real-time VOC quantification prevents acute exposure incidents. Portable detectors command the largest revenue pool due to field mobility requirements across petrochemical turnaround inspections, though multi-gas detector configurations are capturing the fastest growth as facilities consolidate monitoring instrumentation. Fixed detector deployments remain structurally mature with replacement cycles tied to plant refurbishment schedules rather than greenfield expansion.
OSHA workplace exposure limits and EPA Method 21 leak detection protocols shape product sensitivity specifications and calibration intervals in the United States market. IECEx and ATEX directives govern European hazardous area approvals, while China's GB standards and SAMR certification requirements create parallel compliance tracks for imported equipment. Stakeholders must monitor evolving hydrogen economy safety codes, as emerging electrolyzer and fueling station standards will extend detector addressable demand into previously unserved application terrain.
Market Dynamics
ATEX and IECEx certification requirements are compressing competitive access across the Photoionization Detectors landscape, forcing smaller participants toward costly redesign cycles while premium-tier suppliers leverage captive sensor fabrication to sustain margin pressure.
Growth Catalysts
- EPA Method 21 protocols:Leak detection mandates in United States refineries tighten calibration interval requirements and drive replacement demand for aging fixed installations.
- Hydrogen economy codes:Emerging electrolyzer and fueling station safety standards in Germany and Japan extend detector addressable demand into previously unserved application terrain.
- Petrochemical corridor expansion:Benzene monitoring deployment concentrates along Texas and Louisiana Gulf Coast facilities undergoing capacity additions.
Market Restraints
- Ultraviolet lamp supply concentration:Proprietary lamp longevity technologies remain concentrated among European specialists, creating input bottlenecks for second-tier assemblers.
- Multi-gas configuration cost:Consolidated monitoring instrumentation demands higher upfront capital than single-purpose detectors, elongating procurement cycles at mid-size facilities.
- Calibration gas dependency:Parts-per-billion sensitivity validation requires certified reference materials with limited qualified suppliers in hazardous area markets.
Strategic Opportunities
- Portable specification convergence:Bluetooth-enabled data logging and cloud connectivity integration creates premium positioning for field mobility applications in petrochemical turnaround inspections.
- Chinese GB standards alignment:SAMR certification requirements for imported equipment create parallel compliance tracks where early alignment captures domestic channel access.
- Industrial hygiene service bundling:Detector-as-a-service models incorporating calibration management and sensor replacement penetrate facilities lacking in-house technical staff.
Industry Challenges
- IECEx documentation timelines:Hazardous area approval processes extend 12-18 months for modified designs, compressing product refresh windows against competitive launches.
- Legacy 4-20mA integration:Fixed detector replacement cycles tied to plant DCS refurbishment schedules create demand lumpiness unpredictable by equipment age alone.
- VOC library standardization:Compound-specific response factors vary by manufacturer calibration protocols, complicating cross-facility data comparability for industrial hygiene teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photoionization Detectors Market |
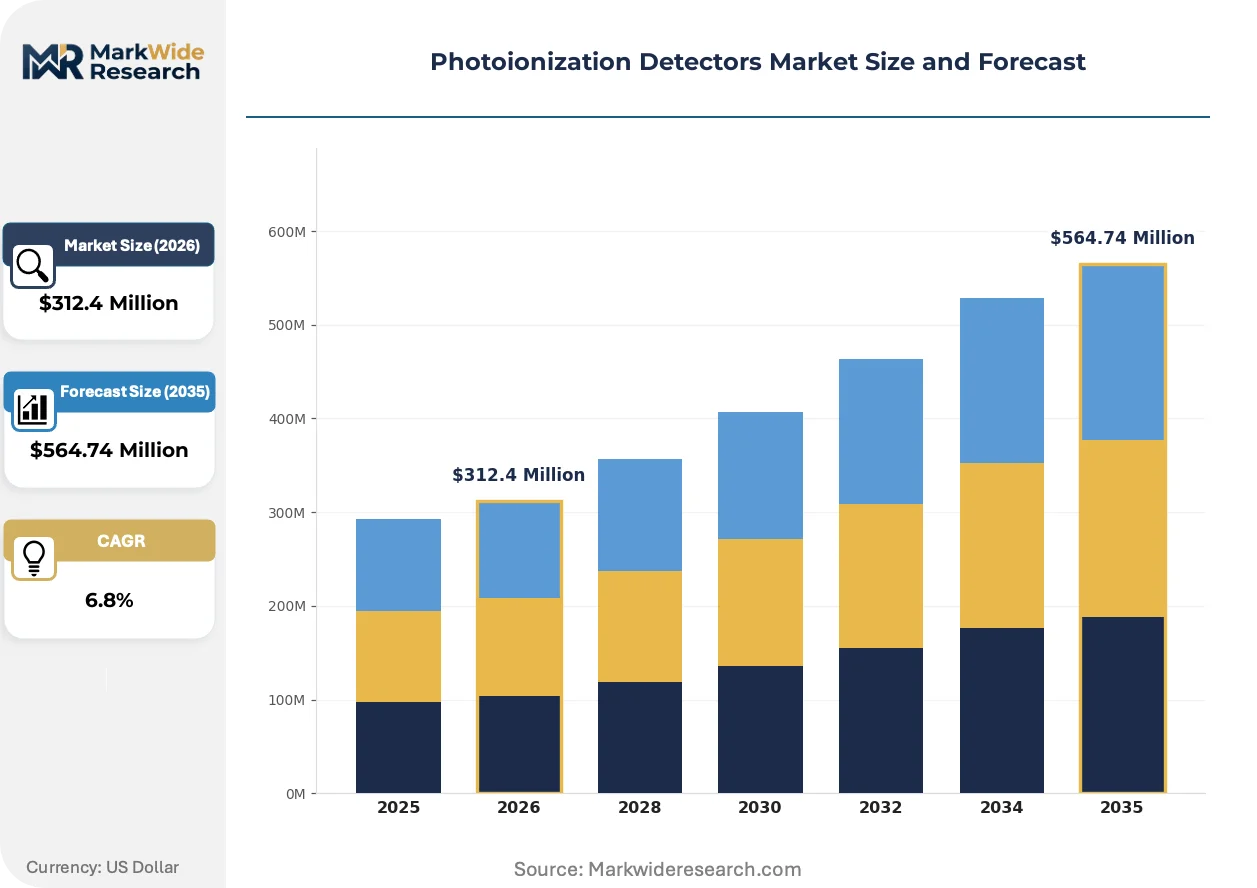
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Detectors, Fixed Detectors, Multi-Gas Detectors, Area Monitors Technology: UV Light, Photoelectric Sensors, Gas Chromatography, Optical Sensors End User: Industrial Safety, Environmental Monitoring, Military Applications, Research Laboratories Deployment: On-Site, Remote Monitoring, Integrated Systems, Standalone Units |
| Companies Covered | Honeywell Analytics, Ion Science, MSA Safety, Dräger, Industrial Scientific, Thermo Fisher Scientific, RC Systems, RKI Instruments, HORIBA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photoionization Detectors Market Evolving Landscape
Real-time connectivity architectures and miniaturized sensor packaging are reshaping how detection data flows from field instruments to enterprise safety systems, compressing the gap between measurement and response.
Extended-life ultraviolet lamp technology with 6,000+ hour operational lifespans is supplanting conventional 2,000-hour designs in portable detector specifications. North American petrochemical operators are adopting these configurations for turnaround inspection contracts where lamp replacement logistics prove costly. The shift is compressing aftermarket revenue pools for consumables while enabling longer deployment cycles between maintenance events.
REACH substance restriction proposals targeting per- and polyfluoroalkyl substances are pressuring manufacturers to reformulate lamp window coatings and housing seals. European industrial distributors are demanding material declarations upstream to preempt supply disruption. Portable detector specifications in Germany and the Netherlands now explicitly exclude fluorinated compounds, forcing design revisions ahead of formal restriction dates.
Procurement centralization at integrated oil majors is consolidating vendor panels and unbundling after-sales service from hardware transactions. Third-party calibration providers in Texas and Alberta are capturing recurring revenue streams previously retained by original equipment manufacturers. This shift is most visible among supermajor operators with standardized global safety equipment lists and centralized technical qualification processes.
Photoionization Detectors Market Segmentation
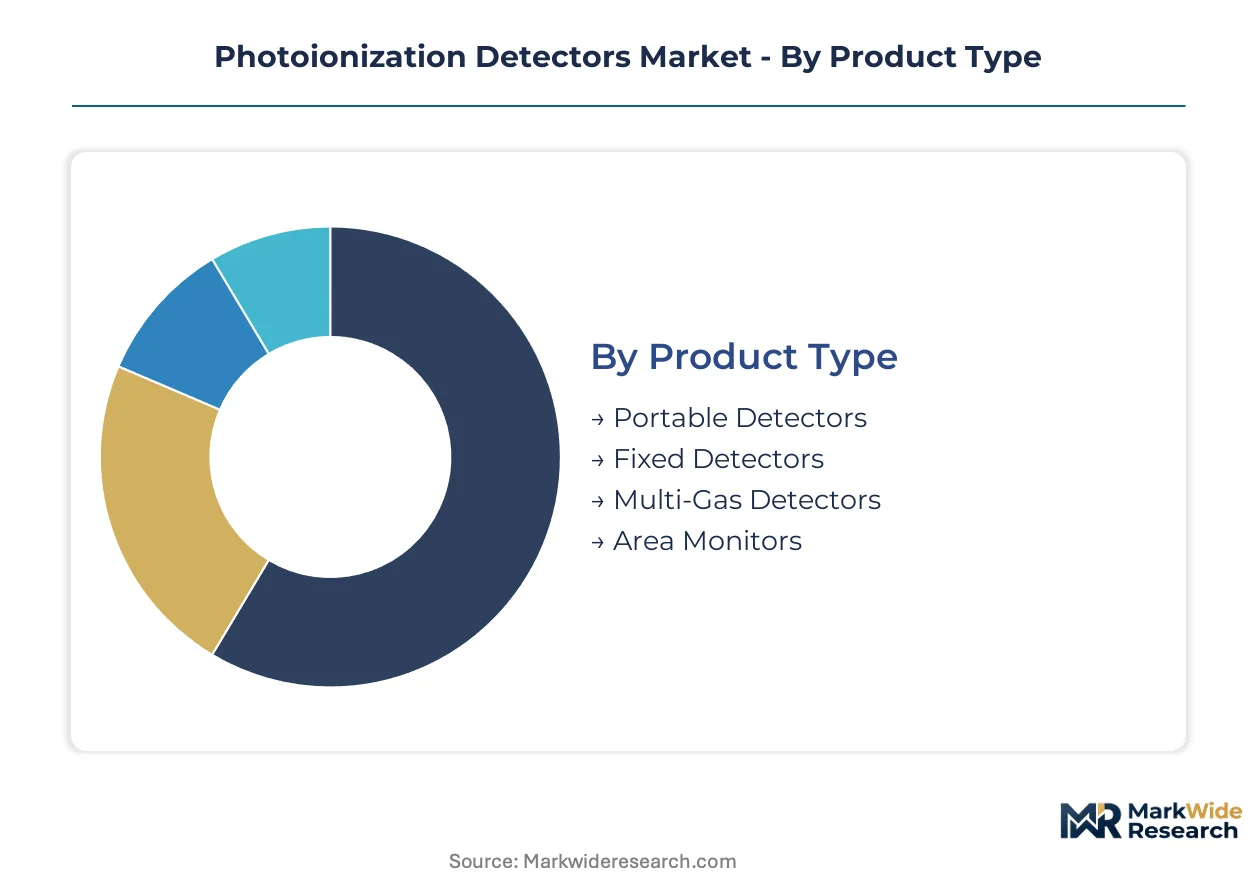
Photoionization detector procurement patterns diverge sharply between export-heavy portable configurations and domestically consumed fixed installations. Understanding these segment boundaries clarifies why calibration service bundling and certification alignment matter differently across customer types.
Product Type:
Portable detectors dominate cross-border trade flows, while fixed installations track domestic plant construction cycles. European and North American channels absorb the bulk of field-mobile units, whereas area monitors concentrate in Gulf Coast petrochemical clusters.
- Portable Detectors:Handheld units with 10.6 eV lamp configurations achieve parts-per-billion benzene sensitivity for turnaround inspections. Demand concentrates in Texas and Louisiana refineries where OSHA Process Safety Management mandates drive replacement cycles. Field mobility requirements sustain premium pricing against fixed alternatives.
- Multi-Gas Detectors:Consolidated instrumentation packages combine PID modules with electrochemical and infrared sensors in single housings. German electrolyzer projects and Japanese hydrogen fueling stations are adopting these configurations for unified safety system architectures. Procurement cycles elongate due to higher capital outlays and extended technical qualification processes.
- Fixed Detectors:Permanently mounted units tied to plant distributed control systems through 4-20mA signaling loops.
- Area Monitors:Wide-coverage perimeter installations for fence-line environmental compliance and community air monitoring programs.
Portable detectors hold the largest share; momentum sits with multi-gas configurations.
Technology:
Cost tiers separate ultraviolet lamp-based systems from photoelectric alternatives, with gas chromatography occupying a narrow premium niche for laboratory validation. Margin structures favor proprietary lamp longevity technologies that compress consumables revenue while extending replacement intervals.
- UV Light:Standard 10.6 eV photon emission ionizes volatile organic compounds with predictable response factors across aromatic and aliphatic species. Ion Science and Honeywell Analytics control captive lamp fabrication, creating input bottlenecks for second-tier assemblers seeking ATEX certification.
- Photoelectric Sensors:Solid-state alternatives eliminate lamp replacement logistics but sacrifice the universal VOC response that makes PID technology indispensable for unknown contaminant screening. Adoption concentrates in facilities with predictable, single-species exposure profiles where calibration stability outweighs detection breadth.
- Gas Chromatography:Laboratory-grade separation and quantification systems for forensic-level speciation beyond field PID capabilities.
- Optical Sensors:Tunable diode laser and infrared absorption methods for methane and light hydrocarbon detection in parallel with PID functionality.
UV light technology anchors installed value; photoelectric sensors are climbing the fastest as solid-state reliability improves.
End User:
Customer type determines specification intensity, with industrial safety buyers demanding hazardous area certifications that research laboratories often bypass. Military procurement channels impose electromagnetic interference and environmental ruggedization standards absent in commercial markets.
- Industrial Safety:Petrochemical operators, pharmaceutical manufacturers, and chemical processors deploy detectors for worker protection and leak detection compliance. EPA Method 21 protocols in United States refineries mandate calibrated response to benzene, toluene, and xylene with documented traceability to National Institute of Standards and Technology reference materials.
- Environmental Monitoring:Regulatory agencies and industrial fence-line programs measure ambient VOC concentrations for community exposure assessment. China's MEE and Germany's Länder environmental authorities are expanding continuous monitoring networks that integrate PID sensors with meteorological data for dispersion modeling.
- Military Applications:Chemical warfare agent detection and hazardous materials response for defense and civil emergency services.
- Research Laboratories:Academic and industrial R&D facilities employing PID technology for method development and validation studies.
Industrial safety commands the dominant revenue pool; environmental monitoring is expanding most quickly on regulatory network buildouts.
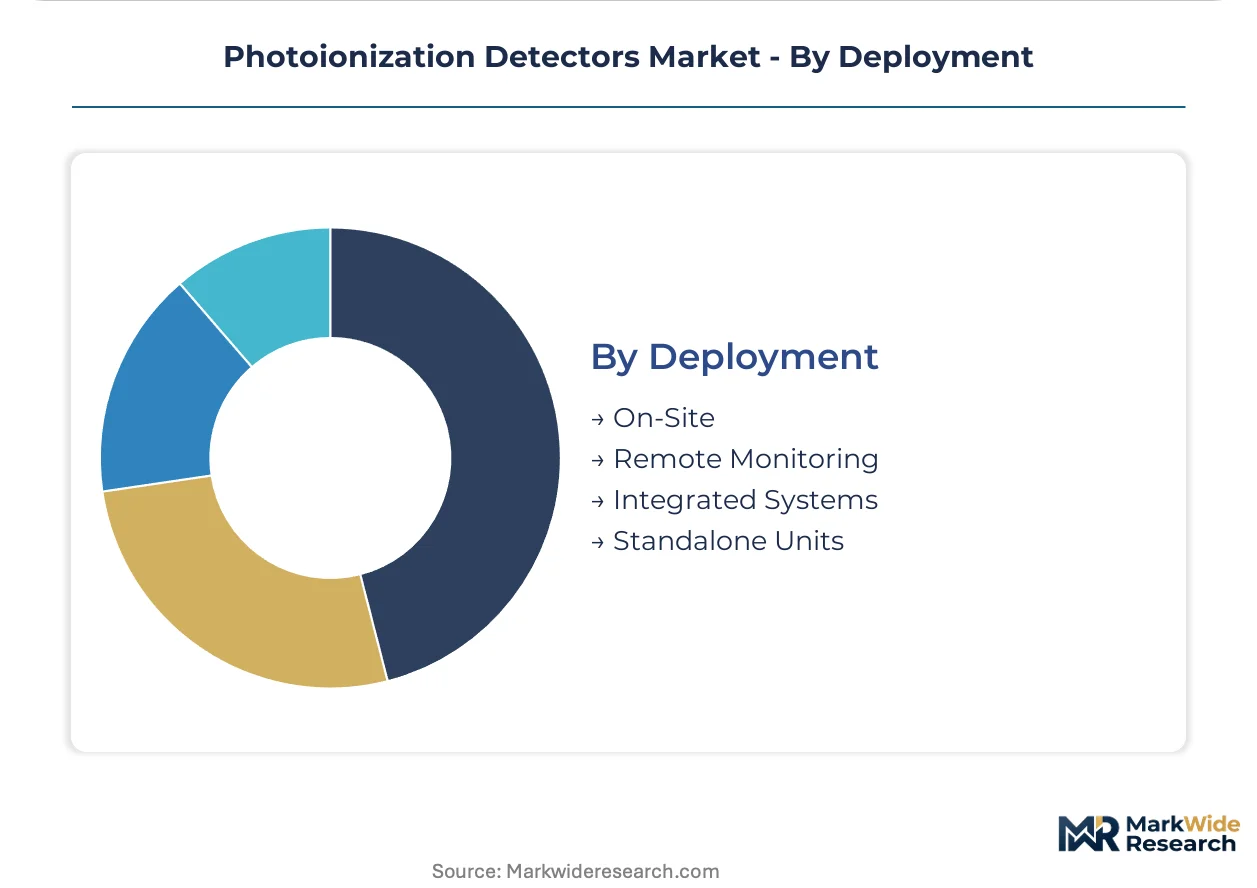
Deployment:
Supply concentration in integrated safety system architectures is displacing standalone unit sales at major facilities. Procurement centralization at oil majors favors vendors capable of enterprise-wide data integration over point-solution specialists.
- Integrated Systems:PID modules embedded within plant-wide safety instrumented systems and distributed control architectures. Supermajor operators in Texas and Alberta are standardizing on Honeywell and MSA platforms with centralized calibration management and predictive maintenance analytics.
- Remote Monitoring:Cellular and satellite-connected detectors transmitting real-time concentration data to cloud-based dashboards. Bluetooth-enabled data logging is penetrating petrochemical turnaround contractors where immediate exposure documentation supports billing and liability management.
- On-Site:Manually operated detectors with local display and alarm functions for immediate worker notification.
- Standalone Units:Battery-powered instruments without external connectivity for temporary deployment and backup coverage.
Integrated systems hold the largest share; remote monitoring configurations are gaining share fastest on connectivity architecture investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA process safety management standards and EPA leak detection mandates in the United States tighten compliance requirements for benzene monitoring equipment. Demand concentrates in Texas and Louisiana along the Gulf Coast petrochemical corridor. Similar regulatory frameworks in Germany and Japan are extending detector applications into hydrogen economy infrastructure.
United States
EPA Method 21 protocols mandate calibrated leak detection response to benzene, toluene, and xylene with documented traceability to National Institute of Standards and Technology reference materials. OSHA workplace exposure limits shape product sensitivity specifications and calibration intervals. Texas and Louisiana Gulf Coast refineries drive replacement demand for aging fixed installations as capacity additions accelerate.
Germany
Emerging electrolyzer and hydrogen fueling station safety standards extend detector addressable demand into previously unserved application terrain. ECHA REACH substance restriction proposals targeting per- and polyfluoroalkyl substances pressure manufacturers to reformulate lamp window coatings. Industrial distributors in the Netherlands and Germany now demand material declarations upstream to preempt supply disruption.
China
GB standards and SAMR certification requirements create parallel compliance tracks for imported equipment. The country's MEE environmental authorities are expanding continuous monitoring networks that integrate PID sensors with meteorological data for dispersion modeling. Yangtze River Delta petrochemical clusters absorb the bulk of fixed detector deployments tied to plant distributed control system refurbishment schedules.
Japan
METI-led hydrogen economy codes are establishing safety standards for electrolyzer and fueling station infrastructure. JIS certification requirements govern hazardous area approvals for industrial safety equipment. Kansai and Chubu industrial corridors show concentrated adoption of multi-gas detector configurations for unified safety system architectures.
Photoionization Detectors Market Competitive Landscape
Player mix skews toward integrated safety conglomerates with captive sensor fabrication capabilities and specialized European lamp technology providers. Market structure concentrates premium-tier supply among vertically integrated participants controlling proprietary ultraviolet lamp longevity technologies. Three archetypes dominate: conglomerates with in-house sensor production, European specialists with proprietary lamp intellectual property, and regional assemblers dependent on third-party component sourcing. Competitive moves center on certification pre-emption in emerging hydrogen economy markets and service bundling to capture recurring calibration revenue.
Among integrated safety conglomerates, Honeywell Analytics and MSA Safety occupy positions where captive manufacturing and North American channel density anchor market presence. Ion Science exemplifies the European specialist archetype with proprietary lamp longevity technology. These three participants represent the tier where hazardous area certification depth and sensor fabrication control create structural barriers for second-tier assemblers seeking ATEX and IECEx approval.
| Leading Market Players |
|---|
| Honeywell Analytics |
| Ion Science |
| MSA Safety |
| Dräger |
| Industrial Scientific |
| Thermo Fisher Scientific |
| RC Systems |
| RKI Instruments |
| HORIBA |
| Others |
Value Network & Pricing Analysis
Captive ultraviolet lamp fabrication at scale anchors margin structures across the Photoionization Detectors landscape, compressing price floors for assemblers lacking in-house production while enabling premium-tier suppliers to sustain service-bundled positioning. Texas and Louisiana Gulf Coast procurement centralization at integrated oil majors amplifies volume-discount leverage, forcing second-tier participants toward calibration-service attachments to defend profitability.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ATEX and IECEx hazardous area approvals commanding substantial markups over non-certified alternatives. Three-tier pricing structure across premium, standard, and economy levels segments by lamp longevity technology and connectivity integration. Cost compression in the economy tier intensifies as Chinese GB-standard alternatives penetrate Southeast Asian channels. Mid-size petrochemical facilities in Texas show highest price sensitivity due to capital constraint, while supermajor operators prioritize total-cost-of-ownership metrics over unit acquisition cost.
Supply Chain Analysis
United Kingdom and Germany anchor proprietary ultraviolet lamp production, with Ion Science and Honeywell Analytics controlling captive fabrication that feeds downstream assembly operations. Malaysia and Mexico host final instrument assembly for North American market access, drawing from Japanese photodiode suppliers and German optical component specialists. Single-source vulnerability concentrates in 10.6 eV lamp electrodes and proprietary window coatings, where REACH substance restrictions threaten input continuity. Distribution runs through industrial safety distributors in Houston and Rotterdam, with calibration gas logistics tethered to regional qualified supplier networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in calibration management and sensor replacement are expanding faster than hardware revenue as facilities lacking in-house technical staff outsource maintenance obligations. Detector-as-a-service models capture recurring revenue streams previously retained by original equipment manufacturers.
For Market Incumbents: Secure captive sensor fabrication capacity to defend margin pressure from Chinese GB-standard competitors entering Southeast Asian channels. Deepen backward integration into ultraviolet lamp electrode sourcing to preempt REACH restriction disruption. Anchor North American channel density through exclusive industrial distribution partnerships that bundle calibration logistics.
For New Entrants and Emerging Players: Differentiate on Bluetooth-enabled data logging and cloud connectivity integration for petrochemical turnaround contractors requiring immediate exposure documentation. Target hydrogen economy safety codes in Germany and Japan where emerging electrolyzer standards create specification white space. Pursue SAMR certification alignment early to capture domestic channel access in China's Yangtze River Delta clusters.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors European specialists with proprietary lamp longevity intellectual property and established IECEx documentation capabilities. Long-term viability hinges on hydrogen economy code participation and industrial hygiene service bundling penetration. Watch for procurement centralization signals at supermajor operators as inflection indicators for vendor consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Lamp Longevity Investment | Extended 6,000-hour operational lifespans compress aftermarket consumables revenue while enabling premium positioning. |
| Hydrogen Economy Certification Pre-emption | Early alignment with German electrolyzer and Japanese fueling station safety codes captures unserved application terrain. |
| Calibration Service Bundling | Detector-as-a-service models penetrate facilities lacking in-house technical staff across Texas and Louisiana Gulf Coast. |
| Chinese GB Standards Alignment | SAMR certification requirements for imported equipment create parallel compliance tracks for domestic channel access. |
| Bluetooth-Cloud Connectivity Integration | Real-time data logging architectures satisfy petrochemical turnaround contractor billing and liability documentation needs. |
Research Methodology
Desk research of regulatory filings from EPA, OSHA, and ECHA preceded structured interviews with plant safety managers at Gulf Coast refineries, industrial distribution channel partners, and calibration service technicians. Secondary validation drew from customs trade data, hazardous area certification registries, and petrochemical operator procurement disclosures. Bottom-up unit demand estimates triangulated against top-down market sizing from sensor component shipment analysis.
Variance decomposition across product type, end-user industry, deployment architecture, and regional regulatory cluster shaped the analytical framework. CAGRs derived from segment-level growth rate reconciliation against macro industrial safety equipment spending patterns. Forecast inputs incorporated hydrogen economy infrastructure buildout trajectories and REACH substance restriction implementation timelines.
Forecasts assume regulatory continuity in EPA Method 21 protocols and OSHA process safety management standards; material policy shifts would require re-modeling. Specific risks include ultraviolet lamp supply disruption from REACH coating restrictions and procurement centralization acceleration at integrated oil majors. Recalibration cycles align with material shifts in hydrogen economy code finalization and hazardous area certification directive updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Hydrogen Leak Detector Market
Detection and Regulation Devices
Global Inflation Device Market
Detection and Regulation Devices
Flooded Member Detection Equipment Market
Detection and Regulation Devices
Antistatic Device for Ultrapure Water Market
Detection and Regulation Devices
Active Buzzer Market
Detection and Regulation Devices
Asia-Pacific Trace Detection Screening Market
Detection and Regulation Devices
Signaling Devices Market
Detection and Regulation Devices
Transient Voltage Suppressor Market
Detection and Regulation Devices
Radiometric Detectors Market
Detection and Regulation Devices
Vapour Particle Barrier Market
Detection and Regulation Devices
Global Portable Gas Detector Market
Detection and Regulation Devices
Pyro Electric Infrared Detectors Market
Detection and Regulation Devices
Semiconductor Inspection System Market
Detection and Regulation Devices
US Pin and Sleeve Devices Market
Detection and Regulation Devices
Radar Detector Market
Detection and Regulation Devices
Pedestrian Detection System Market