
 Flooded Member Detection Equipment Market | 2026-2036
Flooded Member Detection Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Flooded Member Detection Equipment Market Analytics
Multi-source procurement of subsea inspection technology is repositioning how offshore operators manage asset integrity programs. TSC Subsea leverages proprietary acoustic detection systems to anchor its position in deepwater flooded member surveys. Impact Subsea competes through compact, diver-deployable sensor packages designed for platform leg inspection. Cygnus Instruments specializes in ultrasonic thickness measurement extensions that complement flooded member detection workflows.
Flooded member detection equipment comprises sensor-based systems engineered to identify seawater ingress into hollow structural members of offshore platforms, typically employing ultrasonic pulse-echo techniques with operating frequencies between 0.5 and 5 MHz to detect liquid levels behind steel walls up to 100 mm thick. These systems prevent catastrophic structural failure by enabling early intervention on corroded or breached members. Ultrasonic sensors dominate the product type landscape due to proven reliability in high-pressure subsea environments, while IoT-enabled systems represent the fastest-growing technology segment as operators integrate real-time platform monitoring with shore-based control centers. Wireless communication modules are gaining traction where tethered diver operations present safety constraints.
The US Bureau of Safety and Environmental Enforcement mandates structural integrity verification for outer continental shelf facilities, while the UK's Health and Safety Executive enforces offshore installation inspection standards under the Safety Case Regulations. Norway's Petroleum Safety Authority requires periodic underwater inspection of platform support structures, including explicit flooded member assessment protocols. Stakeholders must monitor evolving sensor fusion requirements that combine acoustic, pressure, and optical modalities into unified detection platforms.
Market Dynamics
Regulatory mandates from the US Bureau of Safety and Environmental Enforcement and the UK's Health and Safety Executive are compressing inspection cycles for aging North Sea and Gulf of Mexico platforms, forcing operators to automate flooded member monitoring rather than rely on periodic diver surveys.
Growth Catalysts
- Offshore Safety Case Regulations:The UK's Health and Safety Executive mandates structural integrity verification for all offshore installations, requiring continuous flooded member assessment protocols that drive equipment procurement.
- Sensor fusion architectures:Integration of acoustic, pressure, and optical modalities into unified detection platforms is expanding addressable inspection scenarios beyond legacy ultrasonic-only systems.
- North Sea infrastructure aging:Platform operators in UK and Norwegian waters face escalating maintenance burdens on structures installed during the 1970s-1980s offshore boom, concentrating demand for predictive monitoring equipment.
Market Restraints
- Titanium alloy sensor housings:Input cost volatility for corrosion-resistant metals used in deepwater pressure vessels creates margin pressure for equipment manufacturers serving ultra-deepwater segments.
- Subsea cable and connector supply:Concentrated production of wet-mateable electrical connectors in a limited supplier base exposes procurement timelines to single-source bottlenecks.
- Acoustic signal attenuation:Technical limitations in through-wall detection reliability for steel thicknesses exceeding 100mm constrain addressable platform leg geometries without multi-sensor redundancy.
Strategic Opportunities
- Floating offshore wind foundations:Emerging demand from monopile and jacket structures in UK, Norwegian, and US Atlantic coast wind farms creates new inspection workflows requiring flooded member detection adaptation.
- Real-time shore connectivity:IoT-enabled systems with satellite or fiber backhaul allow platform operators to centralize structural monitoring from onshore control centers, displacing vessel-based inspection teams.
- Norwegian Petroleum Safety Authority mandates:Explicit requirements for periodic underwater inspection of platform support structures create regulatory tailwinds for certified equipment vendors.
Industry Challenges
- Subsea robotics integration:Autonomous underwater vehicle deployment of flooded member sensors requires specialized mechanical and software engineering talent scarce in traditional offshore inspection firms.
- ISO 13628-8 certification timelines:Extended validation periods for subsea production control equipment standards delay product commercialization and lock out unproven entrants.
- Legacy platform data architectures:Integration of new detection systems with decades-old SCADA infrastructure on aging Gulf of Mexico and North Sea platforms demands costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flooded Member Detection Equipment Market |
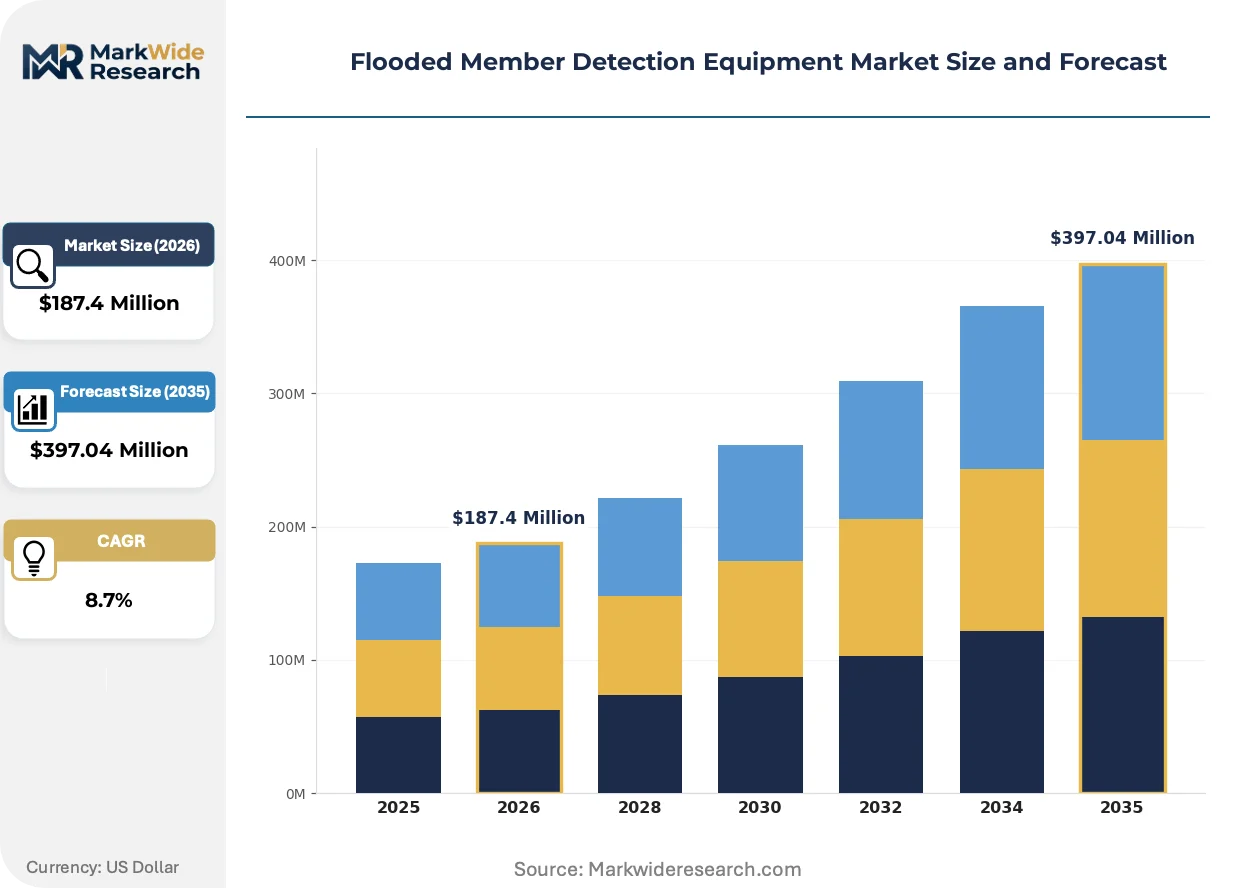
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Sensors, Pressure Sensors, Capacitive Sensors, Optical Sensors Application: Agricultural Monitoring, Infrastructure Safety, Environmental Research, Flood Management End User: Government Agencies, Research Institutions, Agriculture Sector, Private Developers Technology: IoT-Enabled Systems, Wireless Communication, Remote Monitoring, Data Analytics |
| Companies Covered | TSC Subsea, Impact Subsea, Scanning Technologies Inc., DeepOcean, Cygnus Instruments, Dacon Inspection Services, ECHO81, Repsol Norge, Astead Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flooded Member Detection Equipment Market Evolving Landscape
Digitalization of subsea asset integrity is compressing inspection intervals and shifting operator preferences toward continuous monitoring architectures. Three developments are restructuring competitive positioning in flooded member detection equipment.
Ultrasonic pulse-echo systems with integrated wireless communication modules are electrifying platform leg inspection workflows by eliminating tethered diver dependencies. Major North Sea operators are deploying these systems on unmanned platforms and marginal fields where manned intervention costs prove prohibitive. The technology is electrifying market expansion into previously uneconomical shallow-water assets.
The EU's CSRD sustainability disclosure requirements and the US Bureau of Safety and Environmental Enforcement's structural integrity verification mandates are tightening documentation standards for offshore asset conditions. Operators must now maintain auditable inspection records spanning equipment lifecycles. Subsea inspection service providers are responding by embedding blockchain-verified data logging into detection equipment to satisfy regulatory traceability demands.
Asset integrity procurement is consolidating around integrated service contracts bundling detection hardware, data analytics, and predictive maintenance software. Traditional equipment-only vendors face displacement by subsea engineering firms offering outcome-based structural monitoring subscriptions. This model is most visible in Norwegian and UK North Sea operations where integrated offshore service providers have captured platform operator procurement decisions.
Flooded Member Detection Equipment Market Segmentation
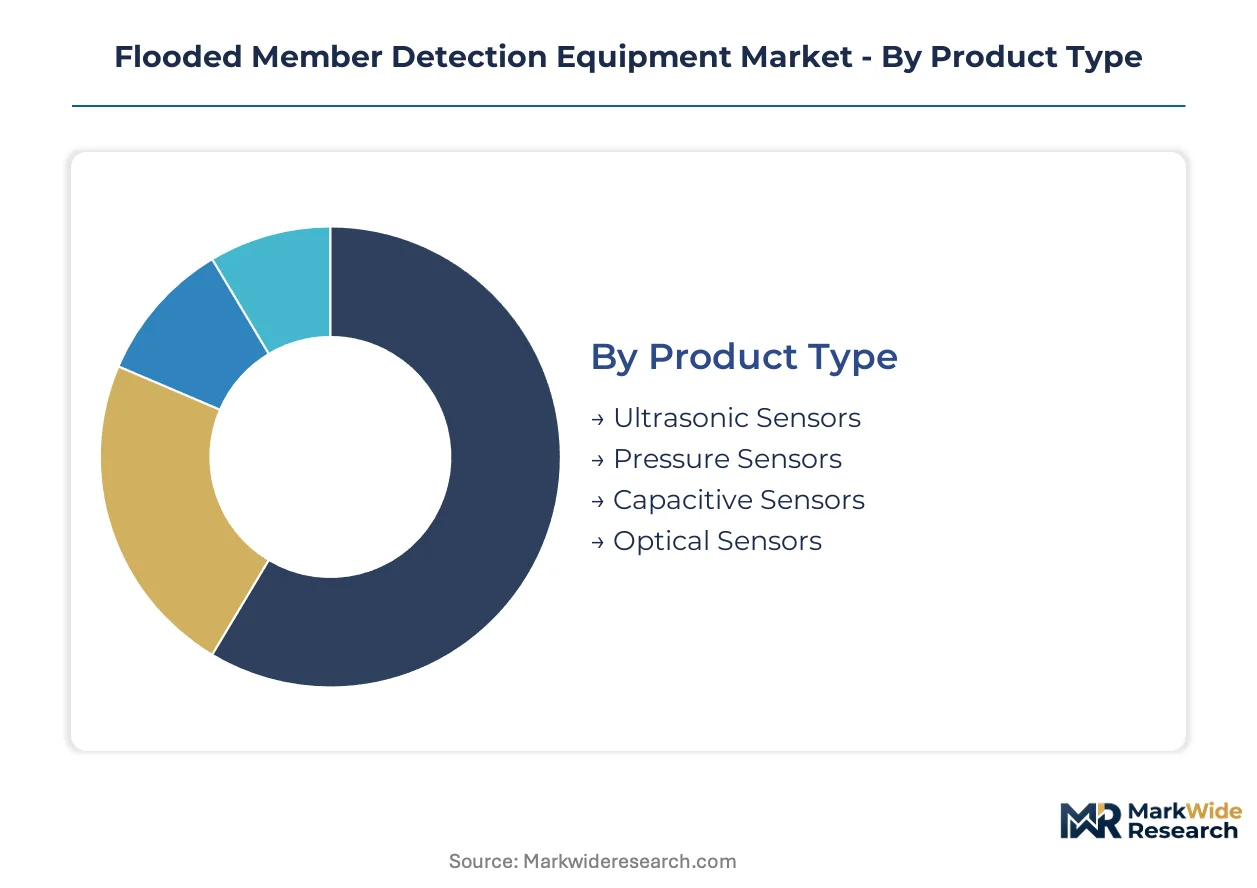
Segmentation in flooded member detection equipment reveals how sensor technologies, deployment contexts, and connectivity architectures split procurement decisions across offshore operators. Each axis carries distinct margin profiles and regulatory compliance requirements that reshape vendor positioning.
Product Type:
Ultrasonic pulse-echo specifications anchor equipment selection decisions for through-steel detection reliability.
- Ultrasonic Sensors:Pulse-echo systems operating between 0.5 and 5 MHz penetrate steel walls up to 100 mm thick with proven subsea reliability. North Sea platform operators specify these for mandatory flooded member assessment protocols under UK and Norwegian regulations.
- Pressure Sensors:Differential pressure transducers detect hydrostatic anomalies indicating seawater ingress into structural voids. Gulf of Mexico operators deploy these for continuous monitoring of aging platform legs where diver access is restricted by weather windows.
- Capacitive Sensors:Dielectric measurement devices suited for thin-walled members and splash zone applications.
- Optical Sensors:Fiber-optic systems for specialized deployments requiring electromagnetic immunity.
Ultrasonic sensors lead on scale; optical sensors lead on momentum in hybrid detection platforms.
Application:
Deployment context determines sensor packaging requirements and certification standards.
- Infrastructure Safety:Offshore platform structural integrity monitoring dominates equipment procurement volumes. UK North Sea operators face compressed inspection cycles under Health and Safety Executive mandates for aging 1970s-1980s installations.
- Flood Management:Coastal defense and levee monitoring applications are expanding fastest as climate adaptation infrastructure attracts public investment.
- Agricultural Monitoring:Irrigation system and reservoir applications with lower specification requirements.
- Environmental Research:Academic and governmental water quality monitoring deployments.
Infrastructure safety leads on scale; flood management leads on momentum.
End User:
Procurement authority concentration varies sharply between regulated offshore operators and public infrastructure agencies.
- Government Agencies:Coastal protection authorities and maritime safety regulators specify detection equipment for public infrastructure. US Bureau of Safety and Environmental Enforcement mandates drive federal procurement for outer continental shelf facility monitoring.
- Private Developers:Offshore wind farm constructors represent the steepest expansion trajectory as UK, Norwegian, and US Atlantic coast projects multiply.
- Research Institutions:Universities and governmental laboratories with grant-funded acquisition cycles.
- Agriculture Sector:Irrigation cooperatives and large-scale farming operations with price-sensitive procurement.
Government agencies lead on scale; private developers lead on momentum.
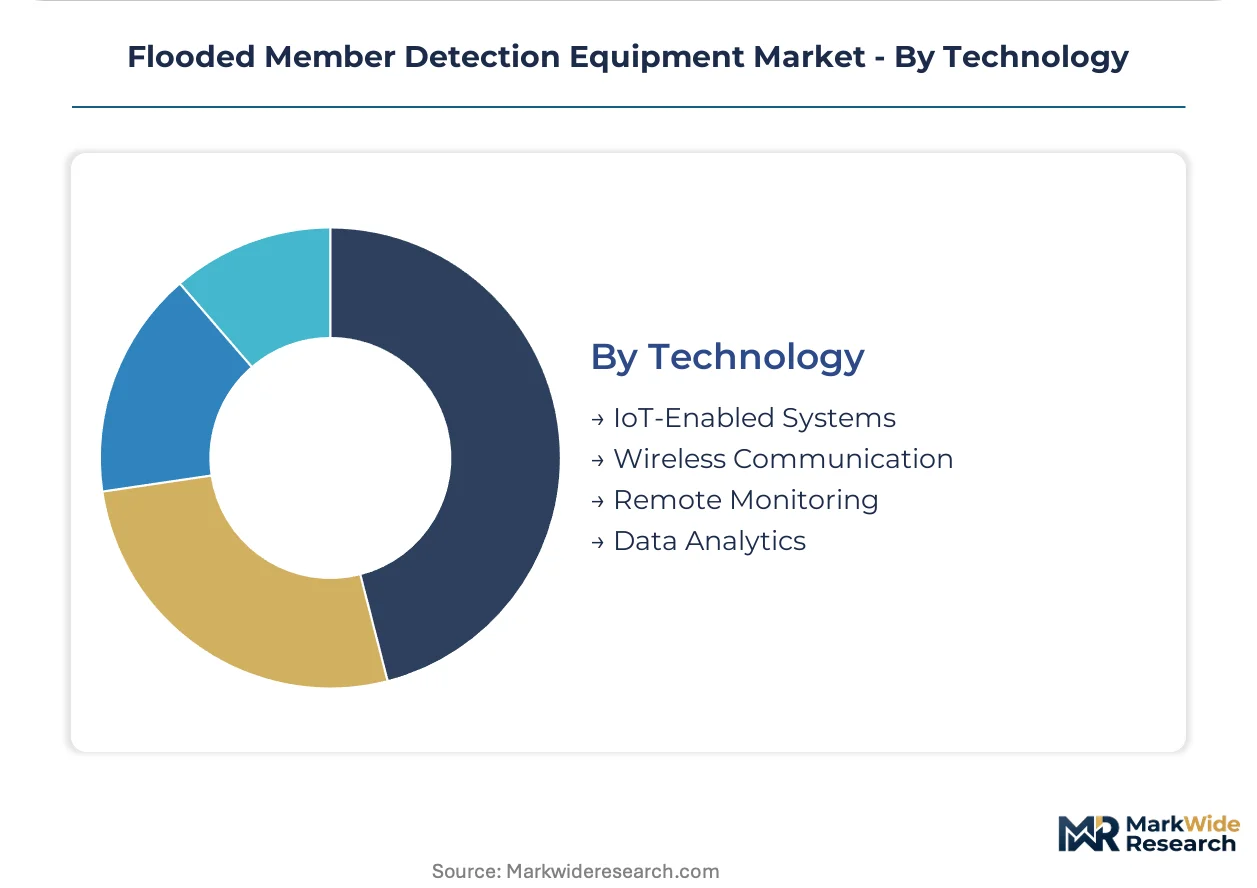
Technology:
Connectivity architecture separates legacy diver-dependent inspection from autonomous monitoring platforms.
- IoT-Enabled Systems:Sensor networks with shore-based data integration allow platform operators to centralize structural monitoring from onshore control centers. Norwegian operators are displacing vessel-based inspection teams with these architectures.
- Remote Monitoring:Satellite and fiber backhaul systems for unmanned platform applications are gaining share fastest where manned intervention costs prove prohibitive.
- Wireless Communication:Acoustic and radio-frequency modules eliminating tethered diver dependencies.
- Data Analytics:Predictive algorithms for anomaly detection and maintenance scheduling.
IoT-enabled systems lead on scale; remote monitoring leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea basin anchors global procurement of flooded member detection equipment, with aging platform infrastructure and stringent safety mandates driving concentrated demand across multiple offshore jurisdictions.
United Kingdom
The UK Continental Shelf hosts over 280 offshore installations requiring continuous structural monitoring under Health and Safety Executive Safety Case Regulations. Aberdeen serves as the primary procurement hub where integrated service providers bundle detection hardware with predictive maintenance contracts for North Sea operators.
Norway
Equinor and Aker BP operate substantial aging platform portfolios in the Norwegian North Sea and Barents Sea. The Petroleum Safety Authority mandates explicit flooded member assessment protocols, concentrating equipment procurement through Stavanger-based engineering firms that specialize in subsea integrity management.
United States
Gulf of Mexico platform operators face compressed inspection cycles under Bureau of Safety and Environmental Enforcement structural integrity verification rules. Houston anchors domestic procurement activity, with supermajor headquarters driving specification standards for outer continental shelf facilities.
Brazil
Petrobras operates pre-salt development fields requiring deepwater flooded member detection capabilities. The national oil company's local content requirements channel equipment procurement through Rio de Janeiro-based subsea engineering clusters serving Campos and Santos basin installations.
Australia
Northwest Shelf and Bass Strait platform operators confront cyclone exposure and aging infrastructure challenges. NOPSEMA safety case requirements mirror UK and Norwegian standards, driving Perth-based procurement of inspection technologies for offshore LNG production facilities.
Flooded Member Detection Equipment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue IoT-enabled remote monitoring architectures. The vendor base stratifies across three capability tiers: integrated subsea service providers, specialized sensor manufacturers, and inspection technology distributors. Strategic differentiation centers on sensor fusion integration and outcome-based service contracting rather than equipment-only sales. Consolidation pressure intensifies as operators consolidate procurement around bundled integrity management subscriptions.
Within the specialized sensor tier, TSC Subsea and Impact Subsea exemplify diver-deployable system architects, while Cygnus Instruments occupies a position among ultrasonic instrumentation specialists. These entities represent contrasting approaches to subsea detection technology—acoustic system integration versus compact sensor packaging—reflecting broader segmentation between integrated platforms and modular toolkits. Geographic concentration among UK and Norwegian vendors mirrors North Sea regulatory stringency and operator procurement authority.
| Leading Market Players |
|---|
| TSC Subsea |
| Impact Subsea |
| Scanning Technologies Inc. |
| DeepOcean |
| Cygnus Instruments |
| Dacon Inspection Services |
| ECHO81 |
| Repsol Norge |
| Astead Technology |
| Others |
Value Network & Pricing Analysis
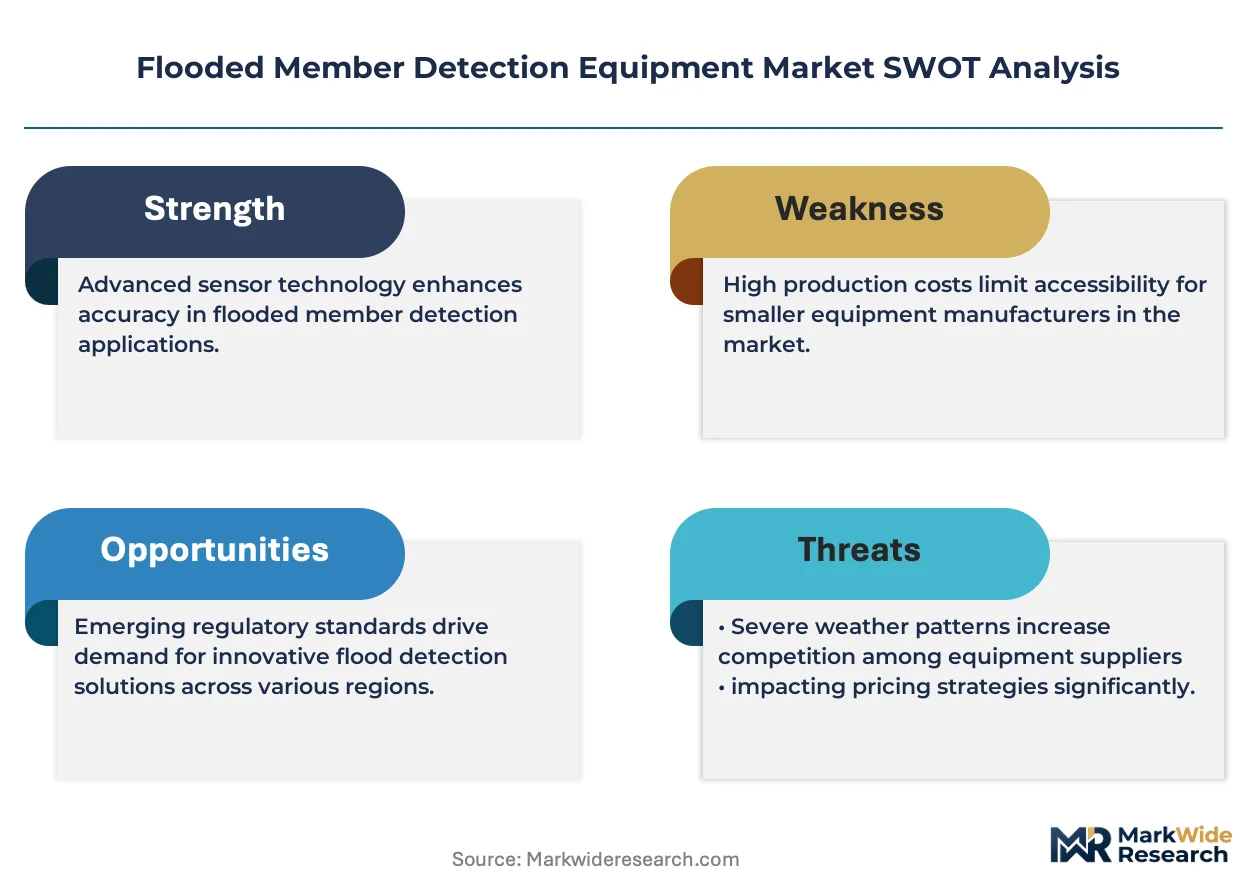
Wireless sensor module miniaturization is compressing production costs while simultaneously concentrating manufacturing expertise among Norwegian and UK subsea engineering clusters serving North Sea platform operators. This dual shift intensifies margin pressure on legacy ultrasonic equipment vendors while rewarding suppliers with captive titanium alloy machining and wet-mateable connector integration capabilities.
Pricing Analysis
Input-cost pass-through from titanium alloy housings and subsea-grade electronics governs equipment pricing, with three-tier pricing structure across premium, standard, and economy levels separating diver-deployable systems from permanently installed IoT architectures. Price differentiation hinges on ISO 13628-8 certification tier and bundled predictive maintenance software. Margins are tightening due to procurement consolidation around integrated service contracts. Government agencies exhibit highest price sensitivity; supermajor operators prioritize reliability over unit cost.
Supply Chain Analysis
Titanium alloy feedstock rests on specialty metal suppliers in the United States, United Kingdom, and Norway, while wet-mateable electrical connectors draw from a concentrated German and French supplier base. Critical dependencies include corrosion-resistant sensor housings, high-pressure transducer elements, and fiber-optic cable assemblies. Single-source vulnerability in subsea connector manufacturing exposes procurement timelines to disruption. Distribution runs through Stavanger and Aberdeen-based engineering firms that bundle hardware with inspection services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flooded member detection equipment market functions as a geographic-arbitrage play where Norwegian regulatory stringency and UK platform decommissioning timelines create premium pricing power unavailable in Gulf of Mexico cost-optimization environments.
For Market Incumbents: Anchor market position through backward integration into titanium alloy machining and captive wet-mateable connector production, eliminating single-source supply risk while defending against IoT-enabled remote monitoring entrants. Pursue ISO 13628-8 certification pre-emption to lock out unproven competitors from Norwegian Petroleum Safety Authority-mandated procurement cycles. For New Entrants and Emerging Players: Satellite-linked real-time monitoring architectures offer the most penetrable wedge for displacing legacy diver-dependent inspection workflows in UK marginal field and unmanned platform applications. Target floating offshore wind foundation contracts where established offshore oil and gas incumbents lack proven track records. Lead with outcome-based structural monitoring subscriptions rather than equipment-only sales. For Investors and Strategic Acquirers: Roll-up economics work for subsea engineering specialists with integrated integrity management platforms because operator procurement consolidation favors bundled service providers over pure-play sensor manufacturers. Acquisition targets should demonstrate Norwegian or UK regulatory certification and existing supermajor relationships. Watch floating offshore wind project FID announcements as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Development | Combines acoustic, pressure, and optical modalities into unified detection architectures for complex platform geometries. |
| IoT-Enabled Remote Monitoring Deployment | Eliminates vessel-based inspection teams through satellite backhaul to onshore control centers. |
| Backward Integration into Titanium Machining | Captures margin compression from corrosion-resistant metal input cost volatility. |
| Floating Offshore Wind Adaptation | Extends flooded member detection workflows to monopile and jacket foundation inspection. |
| Blockchain-Verified Data Logging Integration | Satisfies EU CSRD and BSEE documentation mandates for auditable inspection records. |
Research Methodology
Multiple input streams — structured interviews with subsea integrity managers, primary fieldwork with offshore inspection contractors, and regulatory filing analysis — were reconciled against equipment procurement databases and customs trade records. Stakeholder consultations encompassed platform operators in the UK North Sea and Norwegian Continental Shelf, subsea engineering firms in Aberdeen and Stavanger, and sensor technology specialists. Secondary validation drew from Petroleum Safety Authority inspection protocols, BSEE structural integrity guidelines, and SEC filings from listed offshore service providers. Bottom-up equipment unit estimates and top-down market sizing were cross-referenced for convergence.
Data-stream reconciliation across product type, application, and connectivity architecture dimensions produced volume and value estimates throughout the forecast period. Segmentation modeling captured ultrasonic versus alternative sensor technologies, infrastructure safety versus emerging flood management applications, and diver-deployable versus autonomous monitoring deployment modes. CAGRs were derived from regression analysis against North Sea platform decommissioning schedules and regulatory mandate implementation timelines. Forecast inputs included projected floating offshore wind capacity additions and IoT sensor adoption curves in unmanned platform environments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to floating offshore wind project delays, titanium alloy price volatility, and subsea robotics integration bottlenecks. Assumptions reflect current regulatory enforcement intensity and operator capital allocation patterns. A small set of triggers — Norwegian Petroleum Safety Authority mandate expansion, UK North Sea decommissioning acceleration, and Gulf of Mexico hurricane damage events — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Europe Gas Detectors Market
Detection and Regulation Devices
Global a-Si X-Ray Flat Panel Detectors Market
Detection and Regulation Devices
Handheld Optical Gas Imaging Camera Market
Detection and Regulation Devices
Temperature Detection Screen Market
Detection and Regulation Devices
Arc Fault Detection Devices Market
Detection and Regulation Devices
Temperature Modulation Devices Market
Detection and Regulation Devices
Global Wireless Gas Detection Market
Detection and Regulation Devices
Null Detector Market
Detection and Regulation Devices
Digital Underground Metal Detector Market
Detection and Regulation Devices
Global Gas Detection System Market
Detection and Regulation Devices
Global Gas Leak Detectors Market
Detection and Regulation Devices
Semiconductor Inspection System Market
Detection and Regulation Devices
Walk Through Metal Detector Market
Detection and Regulation Devices
Noise Monitoring Device Market
Detection and Regulation Devices
Leak Detection Equipment Market
Detection and Regulation Devices
Surge Suppression IC Market