
 Single Electron Transistor Market | 2026-2036
Single Electron Transistor Market Size, Share, and Industry Trends Forecast 2026-2036
Single Electron Transistor Market Analytics
The capability gap between cryogenic fabrication specialists and conventional CMOS foundries is collapsing as single-electron transistor production demands sub-kelvin operating environments and atomic-precision lithography. Supracon AG leverages its superconducting device heritage to anchor European quantum research supply chains. Toshiba Schneider Inverter Corporation sustains Japanese leadership through dedicated cryogenic test facilities. Texas Instruments competes by extending its analog semiconductor expertise into ultra-low-noise measurement circuits.
A single electron transistor controls individual electron tunneling through nanoscale quantum dots, achieving charge sensitivity below 10^-6 electrons per root hertz at millikelvin temperatures. Its primary purpose lies in quantum computing readout circuitry, precision electrometry, and radiation-hard logic for space applications. Quantum dot product types dominate current revenue as foundries master deterministic dot placement, while spintronics technology represents the fastest-growing segment due to its compatibility with existing CMOS infrastructure. Sensors applications command premium margins where aerospace end users require fault-tolerant operation under extreme conditions.
ISO nanoelectronics standards and national quantum computing initiatives shape device qualification pathways across Japan's METI, the United States' NIST framework, and Finland's VTT quantum ecosystem. These regulators enforce cryogenic reliability benchmarks that filter out conventional semiconductor suppliers lacking specialized test infrastructure. Stakeholders must monitor which fabrication consortia secure priority access to helium-3 dilution refrigeration capacity as quantum processor roadmaps accelerate.
Market Dynamics
Helium-3 dilution refrigeration capacity scarcity is concentrating single-electron transistor fabrication among cryogenic infrastructure holders, forcing quantum processor roadmaps to synchronize with refrigeration supply timelines rather than lithography scaling alone.
Growth Catalysts
- Japan's METI quantum initiative:National funding streams prioritize cryogenic device qualification pathways that accelerate domestic foundry certification for sub-kelvin operation.
- Quantum computing readout demand:Superconducting qubit arrays require single-electron transistors for charge sensing at millikelvin temperatures, pulling specialized CMOS foundries into cryogenic process development.
- Atomic-precision lithography maturation:Deterministic quantum dot placement techniques now achieve yield rates sufficient for pilot production runs in Finnish and Dutch research consortia.
Market Restraints
- Helium-3 supply concentration:Dilution refrigeration systems depend on Russian and US government stockpiles, creating geopolitical chokepoints for cryogenic test capacity expansion.
- Sub-kelvin operating requirement:Millikelvin environments demand infrastructure investments an order of magnitude beyond conventional semiconductor cleanrooms, filtering out mid-scale foundries.
- CMOS compatibility limitations:Silicon spin qubit alternatives leverage existing fabrication infrastructure, threatening single-electron transistor adoption in quantum computing timelines.
Strategic Opportunities
- Finland's VTT quantum ecosystem:Helsinki-region cryogenic infrastructure clusters offer co-location advantages for foundries seeking dilution refrigeration access without capital ownership.
- Aerospace radiation-hard logic:Satellite operators require fault-tolerant single-electron transistors for extreme environment computing, commanding premium pricing outside quantum computing volumes.
- ISO nanoelectronics standardization:Emerging cryogenic reliability benchmarks create first-mover certification advantages for early-compliant foundries in Japanese and European supply chains.
Industry Challenges
- Cryogenic process engineering talent scarcity:Sub-kelvin device physics expertise concentrates in national laboratory systems, constraining private-sector fabrication scale-up.
- Multi-year certification timelines:NIST framework validation for quantum computing readout applications extends product qualification cycles beyond conventional semiconductor release schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Electron Transistor Market |
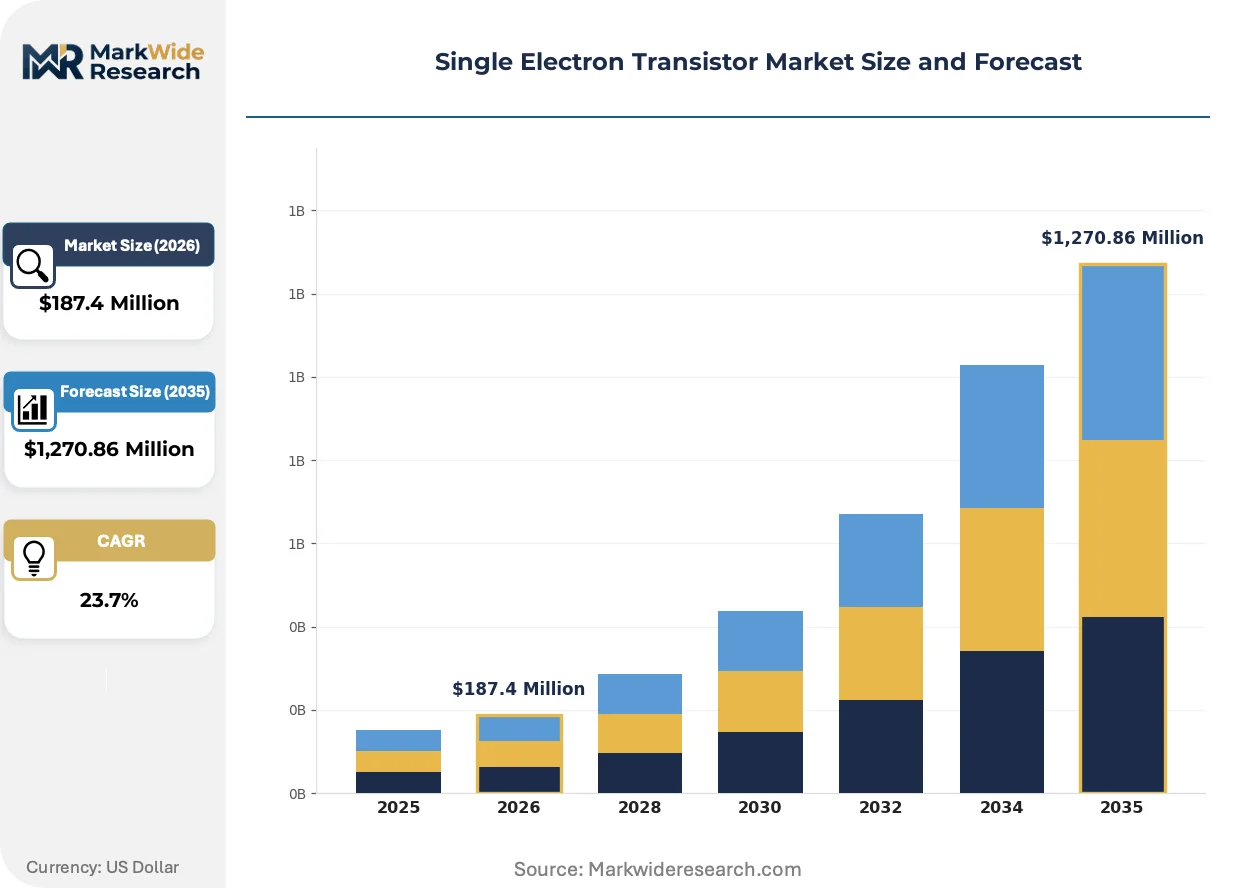
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,270.86 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quantum Dot, Nanowire, Molecular, Hybrid Technology: Single Electron Tunneling, RF-MEMS, CMOS Compatibility, Spintronics Application: Logic Circuits, Quantum Computing, Analog Devices, Sensors End User: Telecommunications, Consumer Electronics, Automotive, Aerospace |
| Companies Covered | Supracon AG, Continental Device India Limited, onsemi, 4-star Electronics Pvt Ltd, Toshiba Schneider Inverter Corporation, Texas Instruments, Cerebras Systems, Torex Semiconductor, Panasonic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Electron Transistor Market Evolving Landscape
Deterministic quantum dot placement techniques are collapsing the yield gap that historically separated single-electron transistors from CMOS manufacturability, enabling volume production conversations previously restricted to research quantities.
Silicon spin qubit architectures is supplanting III-V compound semiconductor approaches in quantum processor designs. IBM and Intel fabrication divisions prioritize silicon MOS quantum dots for their lithographic compatibility with existing 300mm wafer infrastructure. This technology trajectory is compressing the addressable market for compound-semiconductor single-electron transistors while expanding silicon-based device opportunities.
REACH nanomaterial registration requirements in Europe are forcing quantum dot suppliers to document cryogenic stability profiles previously outside regulatory scope. ECHA substance evaluation protocols now capture sub-kelvin degradation mechanisms. German and Dutch foundries are responding by integrating environmental fate testing into early-stage process development rather than retrofitting compliance post-qualification.
Consolidated procurement through national quantum computing centers is displacing distributed laboratory purchasing for single-electron transistor volumes. France's GENCI and Germany's Gauss Centre aggregate demand across academic consortia, concentrating negotiation leverage with foundries. This channel shift is most visible in European quantum processor roadmaps where center-directed supply agreements now govern device qualification priorities.
Single Electron Transistor Market Segmentation
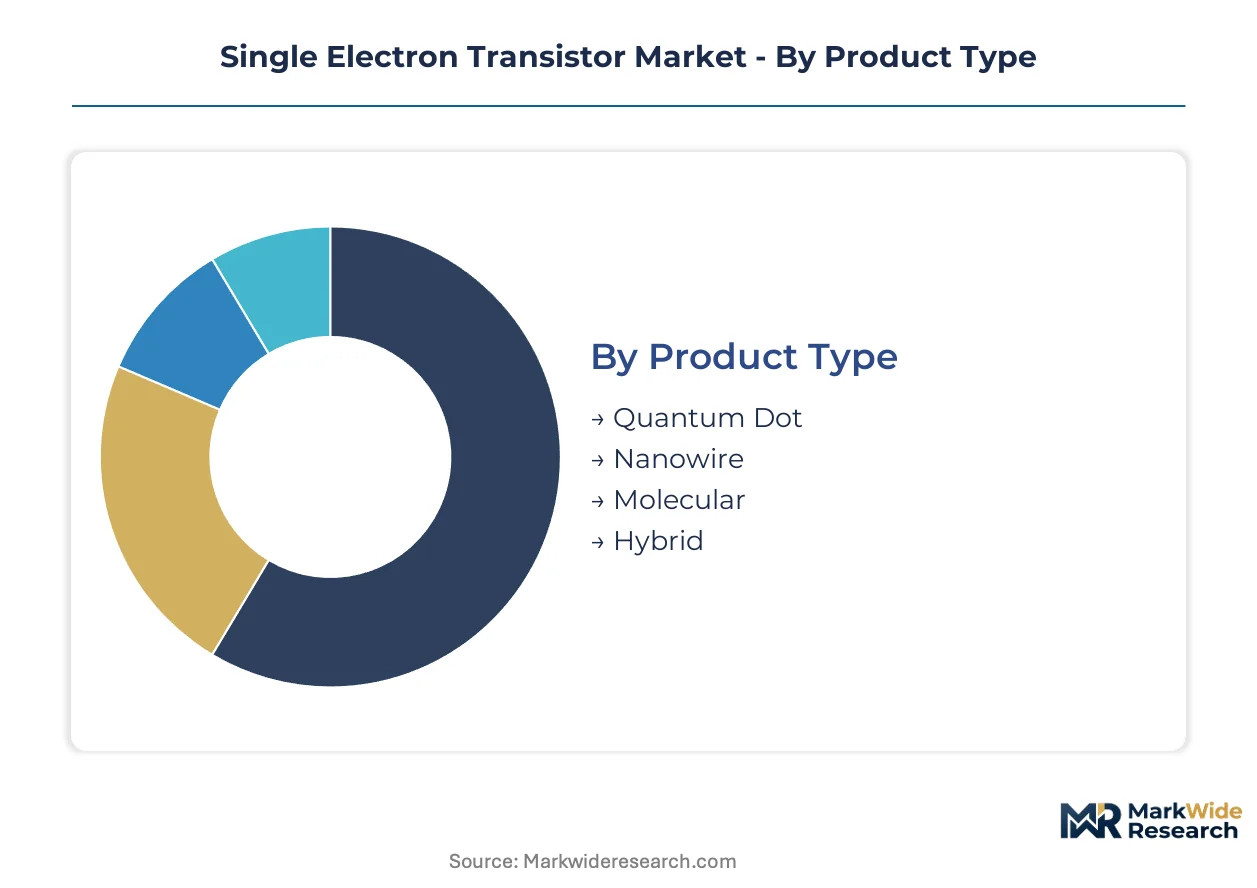
Single electron transistor procurement flows through distinct channels shaped by operating temperature requirements and application criticality. Cryogenic infrastructure access determines which segments reach volume production versus research-scale supply.
Product Type:
Channel mix varies sharply across product architectures, with quantum dot devices flowing through national quantum center procurement while hybrid architectures serve distributed aerospace contractors.
- Quantum Dot:Deterministic placement techniques now achieve yield rates sufficient for pilot production runs. Demand concentrates in Finnish and Dutch research consortia where dilution refrigeration infrastructure anchors supply chains.
- Hybrid:Combines quantum dot precision with CMOS-compatible fabrication layers. Aerospace end users in satellite communications drive premium pricing for radiation-hard variants that tolerate extreme thermal cycling.
- Nanowire:One-dimensional electron confinement enables ultra-low power switching. Japanese METI-funded foundries dominate qualification pathways for sub-kelvin operation.
- Molecular:Organic-inorganic heterostructures offer solution-processable alternatives. Research quantities flow through academic consortia lacking cryogenic test infrastructure.
Quantum Dot dominates installed base. Hybrid architectures are where expansion concentrates for non-quantum applications.
Technology:
Cost tier stratification separates cryogenic-native approaches from CMOS-derivable methods, with spintronics commanding mid-range pricing between premium single-electron tunneling and economy RF-MEMS alternatives.
- Spintronics:Leverages electron spin states for classical and quantum information processing. Silicon MOS quantum dots from IBM and Intel fabrication divisions gain share fastest due to 300mm wafer infrastructure compatibility.
- Single Electron Tunneling:Direct Coulomb blockade control achieves charge sensitivity below 10^-6 electrons per root hertz. Millikelvin operating requirements restrict supply to helium-3 refrigeration holders.
- CMOS Compatibility:Modified foundry processes enable room-temperature single-electron effects. Consumer electronics applications in low-power logic drive volume conversations previously restricted to cryogenic niches.
- RF-MEMS:Integrates resonant tunneling with microelectromechanical structures. Telecommunications infrastructure demands for cryogenic low-noise amplifiers sustain niche production.
Single Electron Tunneling anchors quantum computing roadmaps. Spintronics is climbing the fastest as silicon quantum processor designs mature.
Application:
Volume distribution skews heavily toward sensor applications where aerospace procurement aggregates demand, while quantum computing volumes remain concentrated in national laboratory systems.
- Sensors:Charge electrometry and radiation detection command fault-tolerant specifications. Satellite operators require extreme environment operation with premium pricing outside quantum computing volumes.
- Quantum Computing:Superconducting qubit readout circuitry demands millikelvin charge sensing. France's GENCI and Germany's Gauss Centre consolidate procurement through center-directed supply agreements.
- Logic Circuits:Ultra-low-power digital switching for space applications. Automotive qualification timelines extend product development cycles beyond conventional semiconductor releases.
- Analog Devices:Precision current sources and electrometers for metrology. NIST framework validation governs qualification pathways for instrumentation-grade devices.
Sensors dominate revenue contribution. Quantum Computing is where technology roadmaps concentrate investment.
End User:
Customer type determines margin structure, with aerospace and telecommunications tolerating extended lead times for certified devices while consumer electronics demands CMOS-compatible price points.
- Telecommunications:Cryogenic low-noise amplifiers for satellite ground stations. ISO nanoelectronics standards enforce reliability benchmarks that filter conventional suppliers.
- Aerospace:Radiation-hard logic for orbital computing platforms. Fault-tolerant operation requirements sustain premium pricing tiers independent of quantum computing demand cycles.
- Automotive:Emerging interest in quantum-enhanced sensing for autonomous navigation. Sub-kelvin infrastructure requirements constrain near-term adoption timelines.
- Consumer Electronics:Ultra-low-power wearable applications. Room-temperature CMOS-compatible variants required for cost structure viability.
Telecommunications anchors current procurement volumes. Aerospace represents the steepest expansion trajectory for radiation-hard variants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in consumer electronics segments demonstrate acute price sensitivity, while aerospace and quantum computing procurement tolerates substantial premiums for cryogenic-certified devices. National laboratory systems and satellite operators anchor demand in high-margin tiers.
United States
NIST framework validation governs quantum computing readout applications, extending product qualification cycles beyond conventional semiconductor release schedules. The national quantum initiative channels federal funding toward domestic foundry certification for sub-kelvin operation. Greater Boston and the Pacific Northwest host concentrated cryogenic infrastructure clusters where dilution refrigeration capacity anchors fabrication scale-up.
Japan
METI quantum initiative funding prioritizes cryogenic device qualification pathways that accelerate domestic foundry certification. JIS standards enforcement filters conventional semiconductor suppliers lacking specialized test infrastructure. Tokyo and Osaka metropolitan areas concentrate Japanese superconducting device heritage and dedicated cryogenic test facilities.
Germany
Gauss Centre procurement consolidation aggregates academic consortium demand, concentrating negotiation leverage with foundries. REACH nanomaterial registration requirements force quantum dot suppliers to document cryogenic stability profiles previously outside regulatory scope. Munich and Stuttgart industrial clusters integrate environmental fate testing into early-stage process development.
Finland
VTT quantum ecosystem offers co-location advantages for foundries seeking dilution refrigeration access without capital ownership. ISO nanoelectronics standards emerging from European frameworks create first-mover certification advantages for early-compliant foundries. Helsinki-region cryogenic infrastructure clusters anchor deterministic quantum dot placement pilot production.
Netherlands
Eindhoven Region fabrication consortia secure priority access to helium-3 dilution refrigeration capacity as quantum processor roadmaps accelerate. ECHA substance evaluation protocols now capture sub-kelvin degradation mechanisms in quantum dot supply chains. Dutch research consortia master atomic-precision lithography yield rates sufficient for volume production conversations.
Single Electron Transistor Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with cryogenic-native specialists commanding premium positioning against CMOS-extendable analog semiconductor houses. The vendor base stratifies across three tiers: superconducting device heritage holders, diversified analog semiconductor divisions, and emerging quantum-focused hardware ventures. Dominant competitive moves include strategic partnerships with national quantum centers and backward integration into dilution refrigeration capacity.
Among cryogenic infrastructure holders, Supracon AG exemplifies the superconducting device heritage archetype, while Texas Instruments occupies a position representing analog semiconductor extension into ultra-low-noise measurement circuits. Toshiba Schneider Inverter Corporation anchors the Japanese tier through dedicated cryogenic test facility access.
| Leading Market Players |
|---|
| Supracon AG |
| Continental Device India Limited |
| onsemi |
| 4-star Electronics Pvt Ltd |
| Toshiba Schneider Inverter Corporation |
| Texas Instruments |
| Cerebras Systems |
| Torex Semiconductor |
| Panasonic |
| Others |
Value Network & Pricing Analysis
Twenty-four-month qualification timelines for NIST-validated quantum computing readout devices concentrate pricing power with cryogenic infrastructure holders while filtering out mid-scale foundries lacking helium-3 dilution refrigeration access. This lead-time band creates a structural premium for certified suppliers across Japanese METI-funded foundries and Finnish VTT ecosystem participants, with aerospace procurement absorbing extended delivery schedules that consumer electronics segments reject outright.
Pricing Analysis
After-sales service contracts for cryogenic test facility access and ongoing calibration support drive lifetime value beyond hardware margins. Three-tier pricing structure across radiation-hard aerospace variants, quantum computing laboratory grade, and research-scale academic quantities separates premium tiers by ISO nanoelectronics certification status and helium-3 refrigeration bundling. Cost compression in CMOS-compatible spintronics alternatives is intensifying because IBM and Intel fabrication divisions leverage existing 300mm wafer infrastructure. Consumer electronics buyers demonstrate acute price sensitivity, while satellite operators and national quantum centers tolerate substantial premiums for fault-tolerant operation guarantees.
Supply Chain Analysis
Strategic stockpiling of helium-3 isotope reserves dominates inventory strategy, with Japanese and Finnish consortia prioritizing captive refrigeration capacity over just-in-time component flows. Manufacturing concentrates in Japan, Finland, and the Netherlands where dilution refrigeration infrastructure anchors fabrication scale-up. Raw material dependencies center on gallium arsenide substrates, aluminum oxide gate dielectrics, and helium-3 isotope feedstocks drawn from Russian and US government stockpiles. Single-source vulnerability around helium-3 supply creates geopolitical chokepoints for cryogenic test capacity expansion. Distribution runs through national quantum computing centers that consolidate academic consortium demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from cryogenic test facility access and ongoing calibration contracts is expanding faster than hardware unit sales as qualification timelines extend. This recurring-revenue layer justifies positioning the market as a service opportunity rather than transactional component supply.
For Market Incumbents: Compound defensive positioning by securing backward integration into helium-3 dilution refrigeration capacity and deepening certification investment under Japan's METI quantum initiative pathways. Silicon spin qubit alternatives from IBM and Intel fabrication divisions threaten compound-semiconductor single-electron transistor adoption timelines. Priority levers include channel control through national quantum center procurement consolidation and captive supply of cryogenic test infrastructure. For New Entrants and Emerging Players: Cryogenic process engineering talent scarcity in private-sector fabrication represents the most exploitable service-layer gap where incumbents under-serve. White-space targets include aerospace radiation-hard logic for satellite operators and Finnish VTT ecosystem co-location arrangements for foundries seeking dilution refrigeration access without capital ownership. The most penetrable segment is hybrid architectures combining quantum dot precision with CMOS-compatible fabrication layers. Go-to-market execution should anchor in ISO nanoelectronics standardization consulting bundled with device supply. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified analog semiconductor divisions seeking to monetize ultra-low-noise measurement circuit expertise without full cryogenic infrastructure commitment. Long-term viability over a five-to-ten-year window hinges on quantum processor roadmap synchronization with refrigeration supply timelines rather than lithography scaling alone. Acquisition target archetypes include superconducting device heritage holders with existing helium-3 capacity. The signal to monitor is which fabrication consortia secure priority access to dilution refrigeration capacity as national quantum initiatives accelerate procurement consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dilution Refrigeration | Helium-3 capacity ownership secures supply chain autonomy against Russian and US stockpile concentration. |
| ISO Nanoelectronics Certification Investment | Early compliance with emerging cryogenic reliability benchmarks creates first-mover advantages in Japanese and European supply chains. |
| National Quantum Center Partnership | France's GENCI and Germany's Gauss Centre procurement consolidation concentrates negotiation leverage for volume device qualification. |
| Silicon Spin Qubit Process Development | 300mm wafer infrastructure compatibility with IBM and Intel roadmaps expands addressable market beyond compound-semiconductor niches. |
| Aerospace Radiation-Hard Variant Qualification | Satellite operator fault-tolerant specifications command premium pricing outside quantum computing demand cycles. |
Research Methodology
Operator-level perspectives from cryogenic fabrication engineers, quantum processor roadmap planners, dilution refrigeration facility managers, and national laboratory procurement officers anchored the qualitative base. Primary interviews with these stakeholders combined with secondary validation from NIST framework documentation, METI quantum initiative funding disclosures, VTT ecosystem partnership announcements, and ECHA substance evaluation protocols. SEC filings from diversified analog semiconductor divisions and customs data tracking helium-3 isotope trade flows provided quantitative anchors. Bottom-up unit economics triangulated against top-down national quantum computing center budget allocations.
Sensitivity analysis tested forecast robustness across helium-3 supply disruption scenarios, silicon spin qubit substitution rates, and aerospace procurement cycle timing. The analytical framework modeled product type segmentation by quantum dot, hybrid, nanowire, and molecular architectures; technology segmentation by spintronics, single electron tunneling, CMOS compatibility, and RF-MEMS; application segmentation by sensors, quantum computing, logic circuits, and analog devices; and end user segmentation by telecommunications, aerospace, automotive, and consumer electronics. CAGRs derived from fitted growth curves against historical cryogenic device adoption patterns. Industry-specific forecast inputs included quantum processor qubit count roadmaps and dilution refrigeration capacity expansion announcements.
Forecasts assume regulatory continuity in NIST framework validation, METI quantum initiative funding, and REACH nanomaterial registration requirements; material policy shifts would require re-modeling. Specific risks that could revise projections include helium-3 export restrictions from Russian stockpiles, accelerated silicon MOS quantum dot yield improvements, and ECHA substance evaluation protocol expansion capturing additional cryogenic degradation mechanisms. Revision becomes warranted when silicon spin qubit fabrication yield crosses thresholds enabling direct substitution for single-electron transistor readout functions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Global Layer Pads Market
Semiconductor Devices
COF (Chip-On-Film) Market
Semiconductor Devices
Non-Volatile Dual in-Line Memory Module Market
Semiconductor Devices
Quartz Crystal Oscillators Market
Semiconductor Devices
Automotive Grade Emmc Market
Semiconductor Devices
South Korea MLCC Market
Semiconductor Devices
Mosfet Power Transistors Market
Semiconductor Devices
Field Effect General Purpose Transistors Market
Semiconductor Devices
Semiconductor in Phones Market
Semiconductor Devices
Solar Cell Paste Market
Semiconductor Devices
Thin Wafer Market
Semiconductor Devices
Global Semiconductor Lead Frame Market
Semiconductor Devices
Mobile Phone Semiconductor Market
Semiconductor Devices
CZ Silicon Wafer Market
Semiconductor Devices
Spin Filters Market
Semiconductor Devices
APAC Semiconductor Device in Aerospace and Defense Market