
 Global Label-Free Detection Market | 2026-2036
Global Label-Free Detection Market Size, Share, and Industry Trends Forecast 2026-2036
Global Label-Free Detection Market Foresight
Specialized bioinstrumentation engineering talent is redrawing competitive boundaries in label-free detection. Danaher Corporation leverages its Life Sciences platform to sustain integrated workflow solutions across SPR and BLI modalities. Sartorius AG anchors European bioprocessing demand with biosensor systems optimized for biopharmaceutical quality control. Agilent Technologies competes through optical waveguide platforms that dominate pharmaceutical research laboratories in North America.
Label-free detection encompasses analytical methods that measure biomolecular interactions without fluorescent, enzymatic, or radioactive tags, typically resolving binding kinetics through refractive index changes at sensor surfaces with picomolar sensitivity. Surface plasmon resonance instruments command the largest product type revenue pool due to entrenched validation in regulatory submission pathways, while interferometry systems represent the fastest-expanding technology segment as pharmaceutical researchers pursue higher-throughput kinetic screening. Software and analysis tools increasingly concentrate margin pools as instrument commoditization pressures hardware pricing across mature geographies.
FDA bioanalytical guidance and EMA immunogenicity testing standards shape instrument validation requirements and data integrity protocols for market access in the United States and Europe. China's NMPA alignment with ICH Q2(R1) guidelines accelerates domestic adoption of label-free platforms for biologics development. Stakeholders must monitor evolving pharmacopeial standards for biosensor calibration as regulatory convergence between FDA, EMA, and NMPA frameworks intensifies competitive pressure on instrument manufacturers.
Market Dynamics
Biopharmaceutical quality control requirements are compressing instrument replacement cycles as FDA and EMA validation standards force laboratories toward higher-sensitivity platforms with enhanced data integrity architectures.
Growth Catalysts
- Biosimilar Pipeline Expansion:Contract research organizations in the United States and Germany are scaling label-free screening capacity to support immunogenicity testing for biosimilar submissions under tightened EMA reflection papers.
- SPR System Procurement:Antibody characterization workflows at North American biopharmaceutical laboratories are accelerating surface plasmon resonance instrument purchases to meet FDA bioanalytical method validation guidelines.
- Regulatory Convergence:China's NMPA alignment with ICH Q2(R1) standards is driving domestic adoption of label-free platforms for biologics development and quality control protocols.
Market Restraints
- Instrument Capital Intensity:Surface plasmon resonance systems require substantial upfront investment, constraining adoption at mid-sized pharmaceutical research facilities and academic laboratories.
- Optical Component Supply Concentration:Specialized laser sources and precision optics manufacturing concentrates in Germany and Japan, creating vulnerability to export control disruptions.
- Fluorescence Tag Persistence:Established fluorescence-based assays retain regulatory validation history that slows displacement in legacy drug discovery workflows despite inferior kinetic resolution.
Strategic Opportunities
- Interferometry Technology Convergence:Integration of optical waveguide platforms with microfluidic sample handling is enabling higher-throughput kinetic screening for pharmaceutical lead optimization.
- Software Margin Expansion:Analysis tools and data management platforms represent underexploited revenue pools as hardware commoditization pressures instrument pricing across mature markets.
- Chinese Domestic Manufacturing:Local production partnerships for biosensor systems can capture NMPA-preferred supplier status as China's biologics sector scales.
Industry Challenges
- Specialized Engineering Talent Scarcity:Bioinstrumentation firmware development and surface chemistry functionalization expertise concentrates at a handful of academic centers and incumbent manufacturers.
- Multi-Modal Integration Complexity:Laboratories struggle to harmonize surface plasmon resonance, bio-layer interferometry, and optical waveguide data formats within unified laboratory information management systems.
- Calibration Standard Fragmentation:Divergent pharmacopeial requirements across FDA, EMA, and NMPA jurisdictions force redundant validation protocols and extended certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Label-Free Detection Market |
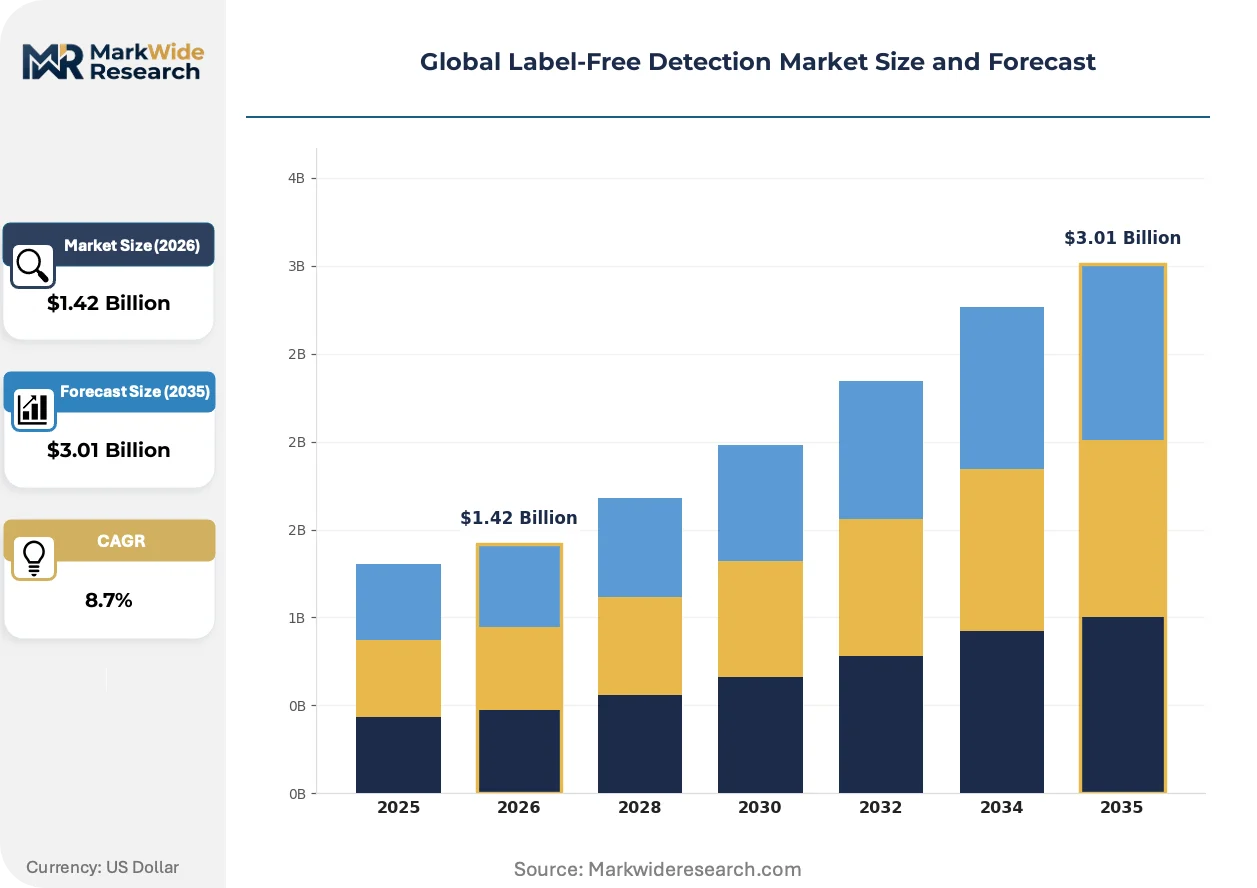
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Surface Plasmon Resonance, Optical Waveguide Lightmode Spectroscopy, Quartz Crystal Microbalance, Resonant Mirror, Interferometry Product Type: Instruments, Systems, Sensors, Software, Accessories Application: Pharmaceutical Research, Food Safety Testing, Environmental Monitoring, Chemical Analysis, Biotechnology End User: Research Laboratories, Contract Research Organizations, Academic Institutions, Biotechnology Firms, Regulatory Agencies |
| Companies Covered | Danaher Corporation, Sartorius AG, Agilent Technologies, Inc., Waters Corporation, Corning Incorporated, Thermo Fisher Scientific Inc., PerkinElmer, Inc., Bruker Corporation, AMETEK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Label-Free Detection Market Shifts & Advancements
Workflow automation and artificial intelligence-assisted kinetic modeling are compressing analysis timelines while regulatory data integrity requirements reshape instrument architecture priorities.
Interferometry-based detection is fragmenting the high-throughput screening segment as pharmaceutical researchers pursue parallel kinetic measurements. Contract research organizations in Germany and the United States are deploying these platforms for lead compound triage. The technology is fragmenting incumbent surface plasmon resonance dominance in early-stage drug discovery while creating new service revenue streams for kinetic characterization.
EMA reflection papers on biosimilar immunogenicity testing are tightening assay validation requirements for European biopharmaceutical submissions. Laboratory directors must now demonstrate comprehensive kinetic parameter documentation and statistical robustness. Surface plasmon resonance instrument manufacturers are responding with enhanced software audit trails and automated calibration protocols specifically engineered for EMA compliance.
Research procurement is consolidating through multi-year service contracts that bundle instrument access, consumables, and technical support. Large pharmaceutical companies in the United States are displacing capital purchase models with operational expenditure structures. This shift pressures smaller instrument vendors to develop financing partnerships or risk exclusion from preferred supplier programs at major biopharmaceutical headquarters.
Global Label-Free Detection Market Segmentation
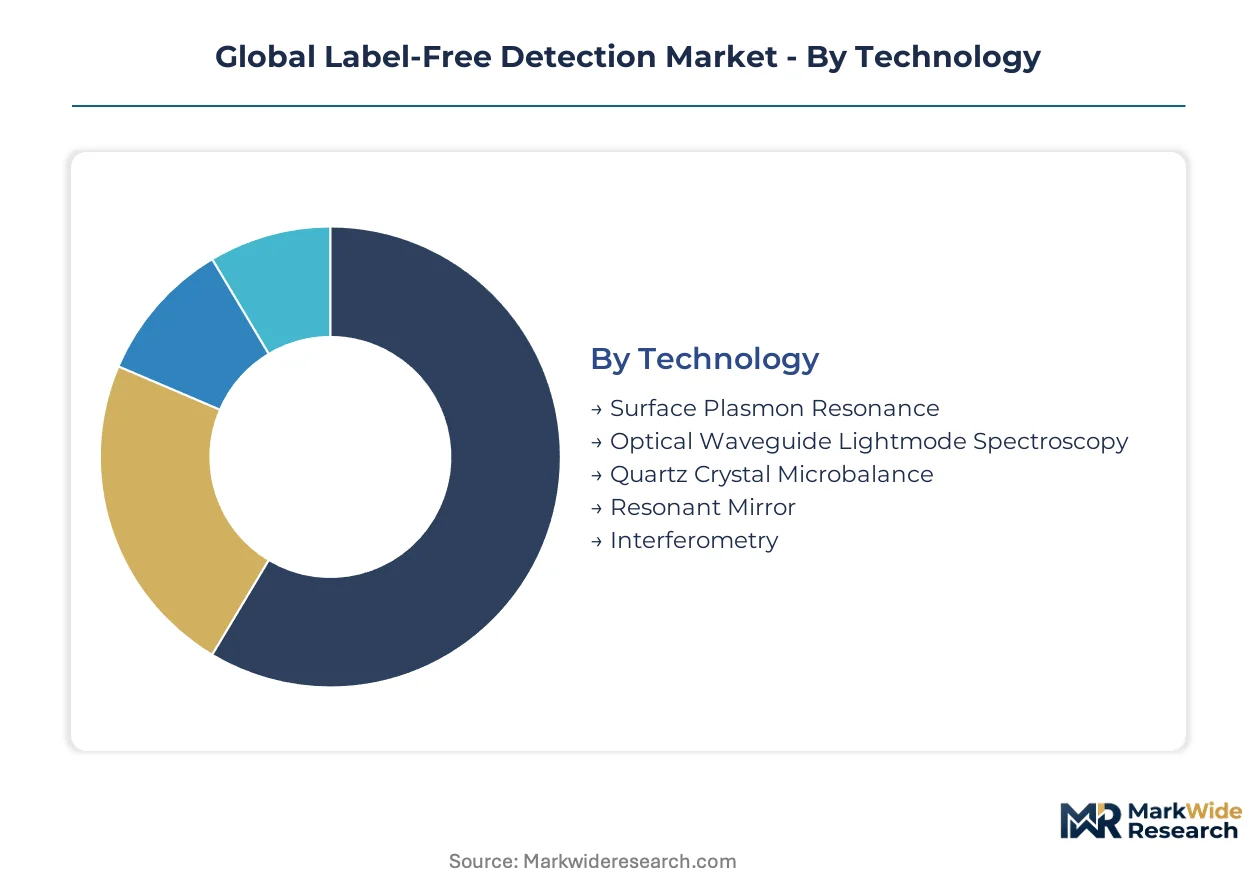
Label-free detection technologies fragment across distinct hardware architectures, software layers, and end-use workflows. Each segment carries different margin profiles, replacement cycles, and regulatory validation requirements that reshape competitive positioning.
Technology:
Instrument procurement channels bifurcate between direct manufacturer sales for high-capital SPR platforms and distributor networks for modular interferometry components.
- Surface Plasmon Resonance:Refractive index sensing at gold-dielectric interfaces measures binding kinetics with picomolar sensitivity. Biopharmaceutical quality control laboratories in the United States and Germany prioritize SPR systems for FDA and EMA antibody characterization submissions.
- Interferometry:Optical path difference measurements enable parallel kinetic screening across 16-96 simultaneous interactions. Contract research organizations in China and the United States deploy these platforms for accelerated lead compound triage.
- Optical Waveguide Lightmode Spectroscopy:Evanescent field sensing through planar waveguides dominates pharmaceutical research installations requiring label-free immunoassay formats.
- Quartz Crystal Microbalance:Mass-sensitive piezoelectric resonators track viscoelastic changes at sensor surfaces for environmental monitoring applications.
- Resonant Mirror:Polarization-based detection architectures serve academic laboratories with lower throughput requirements and constrained capital budgets.
Surface Plasmon Resonance dominates installed base. Interferometry is where expansion concentrates.
Product Type:
Revenue concentration shifts from hardware toward recurring consumables and software subscriptions as instrument commoditization intensifies.
- Instruments:Capital equipment encompassing SPR biosensors, interferometers, and optical waveguide platforms. Research laboratories in Germany and China drive replacement demand as FDA and NMPA validation standards tighten.
- Software:Kinetic modeling algorithms, data integrity audit trails, and LIMS integration modules capture expanding margin pools. Biopharmaceutical firms in the United States prioritize automated analysis tools for regulatory submission documentation.
- Systems:Integrated hardware-software bundles with validated workflows for GMP-compliant quality control environments.
- Sensors:Surface chemistry variants including carboxymethyl dextran, protein A/G, and custom capture molecule immobilization matrices.
- Accessories:Microfluidic cartridges, temperature control modules, and automated sample handling peripherals.
Instruments anchor revenue volume. Software is climbing the fastest as hardware pricing erodes.
Application:
End-use demand stratifies by regulatory validation burden and kinetic data complexity requirements.
- Pharmaceutical Research:Lead optimization and antibody characterization workflows at biotechnology firms and contract research organizations. EMA immunogenicity testing guidelines and FDA bioanalytical method validation standards mandate comprehensive kinetic parameter documentation.
- Biotechnology:Cell line development and bioprocess monitoring applications where real-time binding measurements accelerate clone selection timelines.
- Food Safety Testing:Pathogen detection and allergen screening protocols at regulatory agency laboratories and commercial testing facilities.
- Environmental Monitoring:Pollutant detection and water quality assessment deployments requiring field-portable sensor configurations.
- Chemical Analysis:Small molecule interaction studies at academic institutions and industrial research centers.
Pharmaceutical Research commands premium pricing. Biotechnology is gaining share fastest through bioprocess integration demand.
End User:
Purchasing authority concentrates at large pharmaceutical headquarters while procurement fragmentation persists across academic and mid-sized research settings.
- Contract Research Organizations:Multi-year service contracts bundle instrument access, technical support, and kinetic characterization expertise. CROs in the United States and Germany scale label-free screening capacity for biosimilar immunogenicity testing under tightened EMA reflection papers.
- Biotechnology Firms:Cell therapy and monoclonal antibody developers prioritize integrated SPR-BLI workflows for accelerated IND-enabling studies.
- Research Laboratories:Biopharmaceutical quality control and analytical development groups at headquarters facilities in the United States, Germany, and China.
- Academic Institutions:Basic science research groups with constrained capital budgets and longer replacement cycles.
- Regulatory Agencies:Reference method development and biosensor calibration standardization activities at FDA, EMA, and NMPA facilities.
Contract Research Organizations drive volume concentration. Biotechnology Firms represent the steepest expansion trajectory through pipeline scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA bioanalytical method validation guidelines anchor United States demand for surface plasmon resonance systems in antibody characterization workflows. Contract research organizations across Germany, China, and Japan are scaling label-free screening capacity to meet tightening regulatory standards for biologics development.
United States
Biopharmaceutical headquarters in Massachusetts and California drive SPR instrument procurement for IND-enabling studies. FDA updated bioanalytical guidance in 2022 mandates comprehensive kinetic parameter documentation for antibody submissions. Greater Boston hosts the densest concentration of contract research organizations expanding label-free screening capacity for biosimilar immunogenicity testing.
Germany
Specialized laser source manufacturing in Baden-Württemberg and Bavaria anchors optical component supply chains for interferometry systems. EMA reflection papers on biosimilar immunogenicity testing tighten assay validation requirements for European submissions. Munich and Heidelberg biotech clusters are accelerating procurement of bio-layer interferometry platforms for accelerated lead optimization.
China
Domestic biologics developers in Shanghai and Suzhou are adopting label-free platforms as NMPA aligns with ICH Q2(R1) guidelines. The national pharmaceutical regulator's quality control standards now require kinetic characterization data for monoclonal antibody approvals. Yangtze River Delta contract manufacturers are building in-house biosensor capabilities to capture preferred supplier status.
Japan
Pharmaceutical research laboratories in Kanto and Kansai regions prioritize optical waveguide systems for high-sensitivity immunoassay development. METI funding for advanced bioinstrumentation supports domestic manufacturers competing in interferometry segments. Osaka-based bioprocessing facilities are integrating label-free detection into continuous manufacturing workflows for cell therapy products.
Switzerland
Swissmedic's stringent biosimilar approval pathways drive demand for validated SPR systems at Basel and Zurich headquarters operations. Precision optics engineering expertise concentrates around Lake Geneva and Zurich clusters. Roche and Novartis supplier networks are mandating enhanced data integrity architectures for contract manufacturing partners.
Global Label-Free Detection Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across surface plasmon resonance, interferometry, and optical waveguide modalities. The vendor base stratifies into three tiers: diversified life sciences conglomerates with integrated workflow platforms, specialized bioinstrumentation engineers with optical core competencies, and emerging regional fabricators serving price-sensitive academic markets. Strategic moves concentrate on software margin expansion through kinetic modeling subscriptions and multi-year service contracts displacing capital purchase models.
Among diversified life sciences conglomerates, Danaher Corporation and Thermo Fisher Scientific exemplify the integrated platform archetype spanning SPR, BLI, and consumables ecosystems. Sartorius AG represents the European bioprocessing specialist position with biosensor systems optimized for GMP quality control environments. These three companies anchor the premium tier where procurement consolidation through headquarters-level contracts is displacing fragmented laboratory purchasing.
| Leading Market Players |
|---|
| Danaher Corporation |
| Sartorius AG |
| Agilent Technologies, Inc. |
| Waters Corporation |
| Corning Incorporated |
| Thermo Fisher Scientific Inc. |
| PerkinElmer, Inc. |
| Bruker Corporation |
| AMETEK |
| Others |
Supply & Pricing Matrix
Capacity utilization at specialized laser source manufacturers in Germany and Japan directly shapes both supply availability and price floors for surface plasmon resonance systems. Scale advantages at these optical component hubs concentrate bargaining power upstream while forcing mid-tier instrument vendors toward aggressive pricing to capture biopharmaceutical procurement contracts.
Pricing Analysis
Geographic price spreads of 25-40% separate United States pharmaceutical headquarters from academic laboratories in India and Southeast Asia. Three-tier pricing structure across premium, standard, and economy levels aligns with FDA validation tier, software audit trail depth, and after-sales service bundling. Pricing pressure stems from hardware commoditization as interferometry platforms displace SPR dominance in early-stage screening. Contract research organizations exhibit highest price sensitivity due to operational expenditure constraints, while GMP-compliant quality control laboratories accept premium tiers for regulatory risk mitigation.
Supply Chain Analysis
Inventory lead times for precision optics and specialized laser sources now extend 16-24 weeks due to concentrated fabrication capacity. Manufacturing draws from Germany, Japan, and the United States for optical components, with surface chemistry functionalization reagents sourced from Switzerland and the Netherlands. Single-source vulnerability concentrates at precision interferometer mirror suppliers in Baden-Württemberg. Distribution runs through direct manufacturer sales for high-capital SPR platforms and authorized distributor networks for modular interferometry components serving academic markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software subscriptions and kinetic characterization service contracts now expand faster than instrument hardware revenue, creating a service-attach opportunity where recurring revenue multiples exceed capital equipment valuations. This shift rewards vendors who bundle analysis tools, technical support, and regulatory validation assistance into multi-year agreements.
For Market Incumbents: Fortify data integrity architectures and automated calibration protocols to preempt regulatory compliance divergence across FDA, EMA, and NMPA jurisdictions. Incumbent SPR manufacturers face displacement risk from interferometry platforms in high-throughput screening segments; vertical integration into surface chemistry functionalization reagents secures margin pools and creates switching costs for biopharmaceutical quality control laboratories. For New Entrants and Emerging Players: Cloud-native kinetic modeling platforms represent a service-layer gap where incumbents under-serve mid-sized biotechnology firms with constrained bioinformatics capabilities. White-space concentrates in Chinese domestic manufacturing partnerships for NMPA-preferred supplier status and in interferometry-based screening services for European contract research organizations. A software-first go-to-market angle with usage-based pricing penetrates academic laboratories excluded from capital-intensive SPR procurement. For Investors and Strategic Acquirers: Specialized bioinstrumentation firmware engineering firms with optical core competencies offer acquisition targets where talent scarcity constrains organic development timelines. Long-term viability hinges on regulatory data integrity requirements intensifying across the analysis window, with software audit trail capabilities as the critical inflection signal separating premium from commodity positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Software Subscription Migration | Kinetic modeling platforms capture recurring revenue as hardware pricing erodes in mature markets. |
| Regulatory Validation Partnership | FDA and EMA compliance bundling differentiates service contracts for antibody characterization workflows. |
| Interferometry Platform Launch | Parallel kinetic screening addresses throughput gaps in pharmaceutical lead optimization pipelines. |
| Chinese Domestic Manufacturing | NMPA-preferred supplier status captures biologics sector scaling in Shanghai and Suzhou clusters. |
| Surface Chemistry Backward Integration | Captive supply of functionalization reagents secures margins and creates laboratory switching costs. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with biopharmaceutical analytical development directors, regulatory affairs leads, contract research organization procurement managers, and bioinstrumentation firmware engineers; and secondary validation against FDA bioanalytical guidance documents, EMA reflection papers, NMPA ICH alignment notices, and SEC 10-K filings from diversified life sciences conglomerates. Bottom-up instrument shipment modeling and top-down biopharmaceutical R&D expenditure allocation were triangulated to converge on segment-level estimates.
Across the analysis window, the forecasting framework modeled technology modality, product type tier, application regulatory burden, and end-user purchasing authority concentration. CAGRs were derived from instrument replacement cycle compression rates and software attach ratio expansion trajectories. Kinetic data complexity requirements and pharmacopeial standard convergence intensity served as industry-specific forecast inputs.
Underlying assumptions cover regulatory validation standard stability and optical component supply chain continuity, with deviation risk concentrated in export control disruptions affecting German and Japanese precision optics. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Europe Portable Gas Detector Market
Detection and Regulation Devices
Radiation Detection Device Market
Detection and Regulation Devices
Global a-Si X-Ray Flat Panel Detectors Market
Detection and Regulation Devices
Semiconductor Inspection System Market
Detection and Regulation Devices
Global Gas Sensors Market
Detection and Regulation Devices
South East Asia Gas Detection Device Market
Detection and Regulation Devices
Negative Temperature Coefficient (NTC) Thermistor Market
Detection and Regulation Devices
Spark Detector Market
Detection and Regulation Devices
Filter Panels Market
Detection and Regulation Devices
Digital Metal Detector Market
Detection and Regulation Devices
Global Portable Gas Detector Market
Detection and Regulation Devices
Arc Fault Detection Market
Detection and Regulation Devices
Wireless Gas Detection System Market
Detection and Regulation Devices
Flooded Member Detection Equipment Market
Detection and Regulation Devices
Ultra Low Dropout Regulator (LDO) Market
Detection and Regulation Devices
Pin and Sleeve Devices Market