
 Temperature Modulation Devices Market | 2026-2036
Temperature Modulation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Temperature Modulation Devices Market Analytics
Hospital procurement channels for temperature modulation equipment is narrowing as group purchasing organizations consolidate vendor lists. Gentherm Incorporated leverages its automotive thermal expertise to cross-sell medical warming platforms. Stryker Corporation dominates surgical patient warming through dedicated operating-room product lines. ICU Medical, Inc. competes on disposable temperature management consumables tied to infusion therapy protocols.
Temperature modulation devices regulate thermal energy transfer through conductive, convective, or radiative mechanisms, typically achieving set-point precision within 0.5 degrees Celsius for clinical applications; Peltier-effect modules convert electrical current directly across semiconductor junctions to pump heat without refrigerant circulation. These systems serve critical functions from perioperative hypothermia prevention to cold-chain pharmaceutical logistics. Liquid circulation technology anchors medical treatment applications where continuous normothermia maintenance drives procedure outcomes. Phase change materials sustain sports recovery segments through portable, passive cooling without power dependence. Infrared warming equipment leads industrial process integration for polymer curing and semiconductor fabrication thermal control.
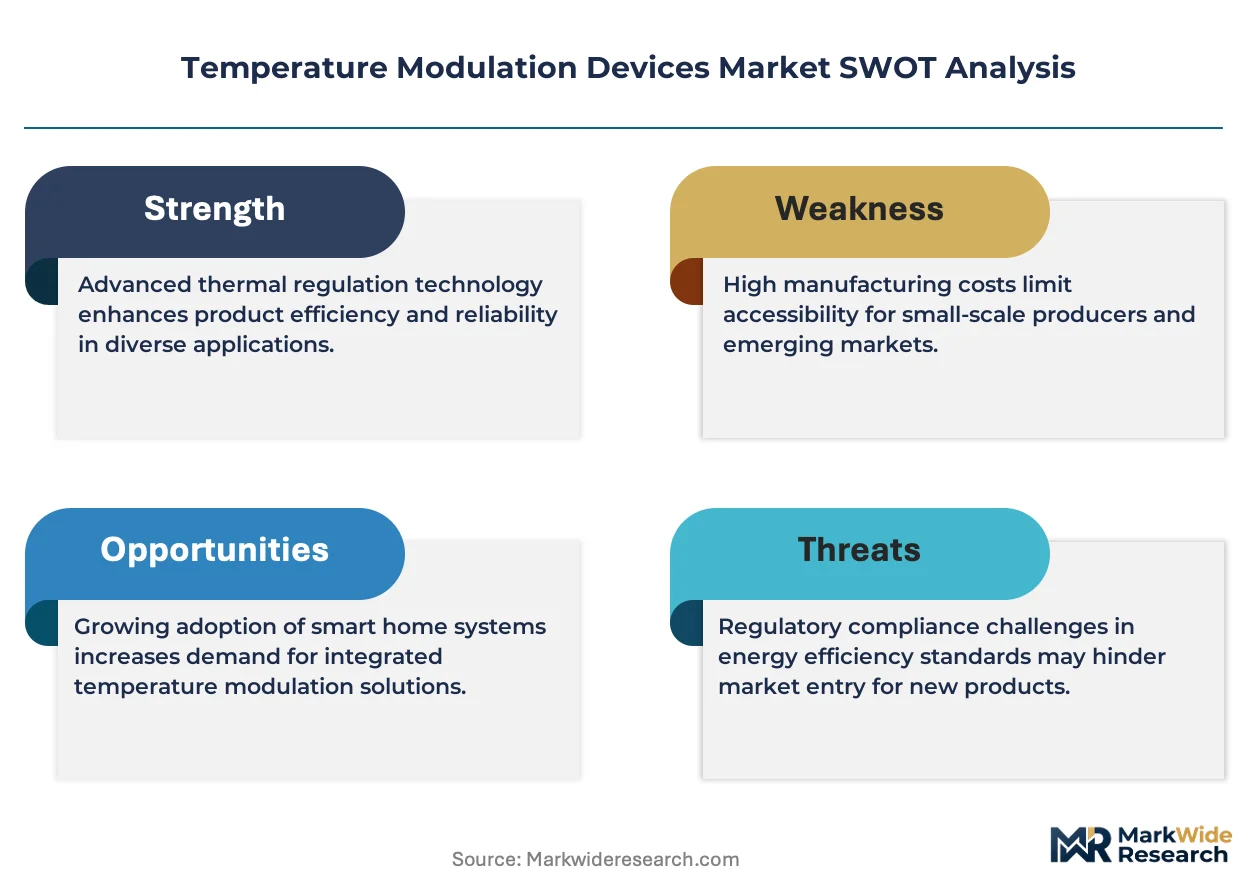
FDA 510(k) clearance requirements and EU MDR technical documentation obligations shape product development timelines and market access barriers for temperature modulation manufacturers. ISO 80601-2-35 standards for patient warming devices enforce electrical safety and thermal uniformity testing protocols that differentiate compliant from non-compliant suppliers. Stakeholders must monitor evolving energy efficiency regulations from EPA and MEE as thermal management systems face decarbonization mandates across healthcare and industrial installations.
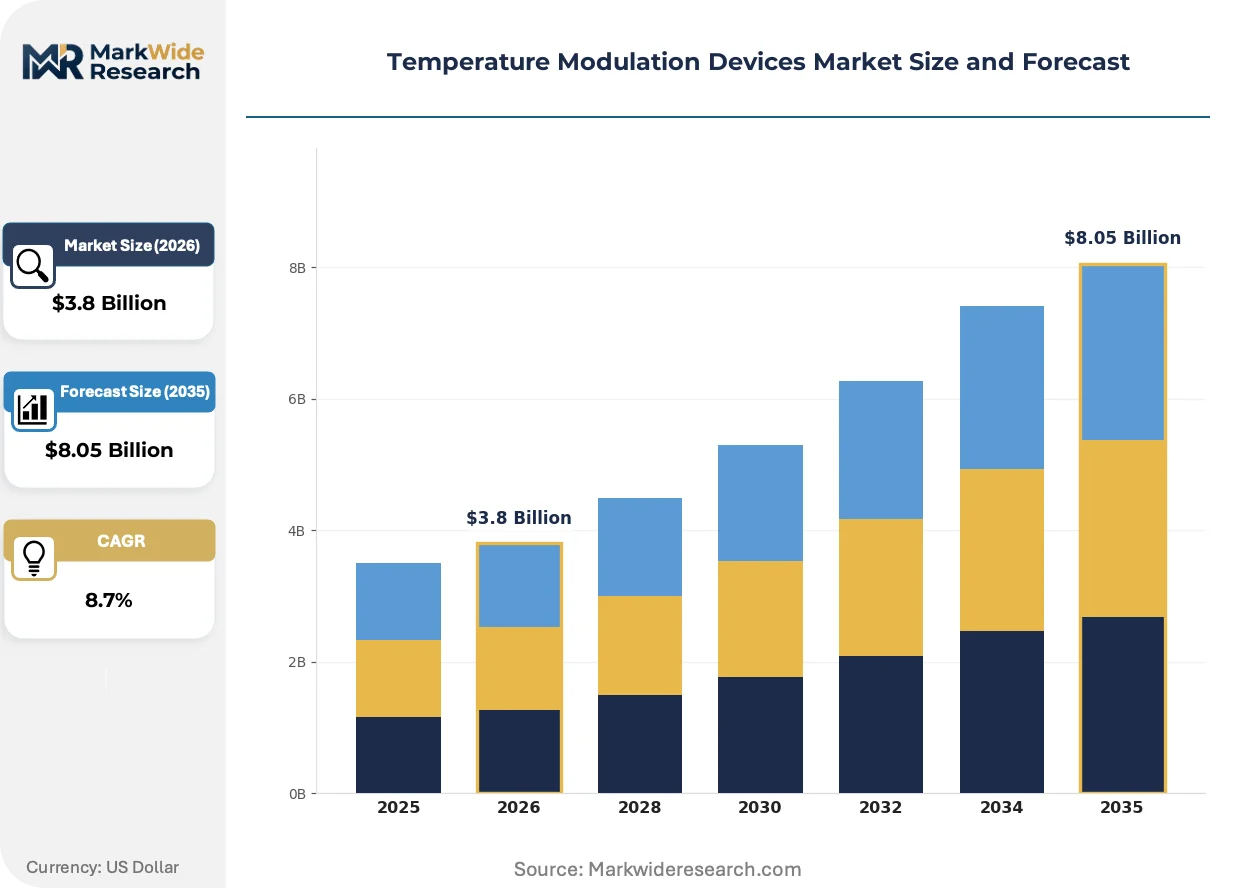
Market Dynamics
Hospital group purchasing organizations are consolidating vendor lists for temperature modulation equipment, squeezing mid-tier suppliers while rewarding manufacturers with full-suite surgical warming platforms and disposable consumable ecosystems.
Growth Catalysts
- EU MDR compliance deadlines:Device manufacturers are accelerating facility upgrades to meet technical documentation and post-market surveillance requirements, expanding the addressable market for validated thermal management systems.
- Peltier-effect semiconductor junctions:Solid-state heat pumping without refrigerant circulation is displacing compressor-based systems in portable medical devices and cold-chain logistics applications.
- German hospital infrastructure renewal:Federal procurement programs prioritize temperature-controlled therapeutic devices in operating theater modernization budgets.
Market Restraints
- Copper and semiconductor input volatility:Peltier module fabrication depends on bismuth telluride and copper interconnects, exposing manufacturers to commodity price swings.
- Supply concentration in East Asian foundries:Thermal semiconductor wafer production clusters in Taiwan and South Korea, creating geographic vulnerability for medical device OEMs.
- FDA 510(k) timeline friction:Substantial equivalence determinations for patient warming devices extend product launch windows by months.
Strategic Opportunities
- Home-based recovery segments:Post-acute care providers are sourcing portable passive cooling systems using phase change materials for ambulatory patient temperature management.
- EPA decarbonization mandates:Healthcare facility energy efficiency regulations are creating replacement demand for refrigerant-free thermal management installations.
- Convergence of infrared warming and polymer curing:Industrial process integrators are deploying radiative thermal control for semiconductor fabrication and advanced materials processing.
Industry Challenges
- ISO 80601-2-35 electrical safety certification:Thermal uniformity testing protocols require specialized metrology infrastructure that smaller manufacturers struggle to access.
- Legacy hospital HVAC integration:New patient warming systems must interface with existing building management networks, complicating installation and commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Temperature Modulation Devices Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heating Pads, Cooling Vests, Thermoelectric Coolers, Temperature Sensors Technology: Infrared, Liquid Circulation, Peltier Effect, Phase Change Materials Application: Sports Recovery, Medical Treatment, Food Preservation, Industrial Processes End User: Healthcare Providers, Athletes, Restaurants, Manufacturers |
| Companies Covered | Gentherm Incorporated, Smiths Group plc, 3M Company, The Surgical Company, Becton, Dickinson and Company, Stryker Corporation, ICU Medical, Inc., ZOLL Medical Corporation, Belmont Medical Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Temperature Modulation Devices Market Evolving Landscape
Digital thermal sensing and closed-loop control architectures are replacing analog thermostat systems across medical and industrial temperature modulation applications, compressing calibration cycles and enabling predictive maintenance.
Embedded fiber-optic temperature sensors with distributed sensing capability are digitizing real-time thermal mapping in surgical warming blankets and hypothermia prevention systems. Academic medical centers in the United States are piloting these platforms for procedure outcome documentation. The technology is digitizing compliance workflows by automating the continuous temperature logging previously performed manually.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of phase change materials used in passive cooling devices. European medical device manufacturers are qualifying bio-based paraffin alternatives and salt hydrate eutectics. The F-Gas Regulation is simultaneously accelerating heat pump technology transitions in industrial process heating applications.
Group purchasing organizations are unbundling after-sales service contracts from capital equipment procurement, forcing temperature modulation vendors to price maintenance separately. Surgical suite managers now compare lifecycle service costs across warming platform vendors. This shift is most pronounced in United States health systems with centralized supply chain functions.
Temperature Modulation Devices Market Segmentation
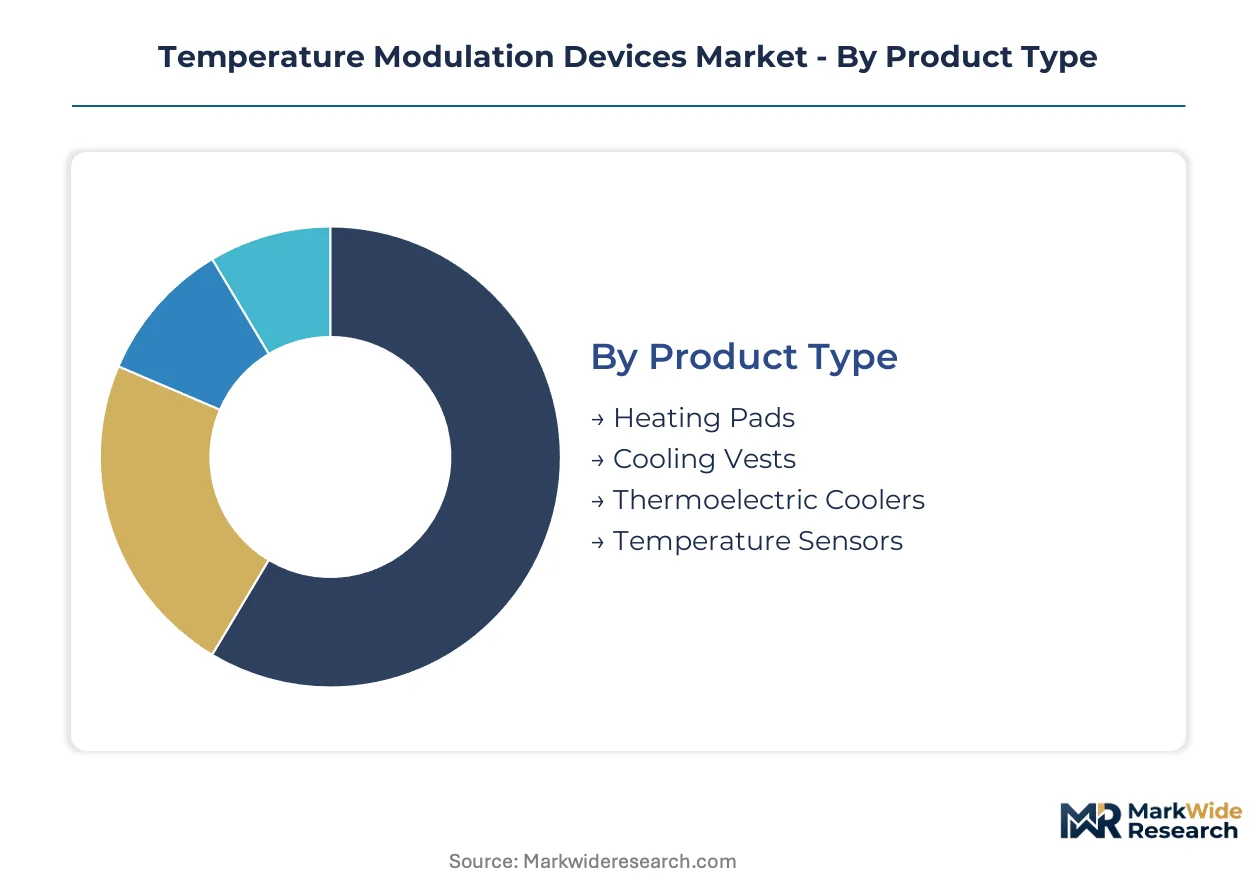
Segmentation in temperature modulation devices reveals divergent engineering requirements across medical precision, athletic portability, and industrial throughput applications. Each dimension—product architecture, thermal physics, use environment, and purchaser type—carries distinct margin structures and certification burdens that reshape vendor prioritization.
Product Type:
Use-case spectrum spans passive consumer comfort through active therapeutic intervention, with semiconductor-based systems commanding premium positioning.
- Heating Pads:Resistive wire or carbon fiber elements embedded in flexible substrates deliver localized thermal therapy. Post-acute care facilities in Germany prioritize disposable warming blankets for surgical recovery protocols, driving procurement consolidation through group purchasing organizations.
- Thermoelectric Coolers:Solid-state Peltier modules pump heat across semiconductor junctions without compressor mechanics. Cold-chain pharmaceutical logistics operators favor these units for last-mile vaccine distribution where refrigerant-free operation satisfies EPA decarbonization mandates.
- Cooling Vests:Garment-integrated circulation or evaporation systems manage core body temperature during exertion. Professional athletics programs represent concentrated demand.
- Temperature Sensors:Fiber-optic and thermistor-based probes enable closed-loop thermal control. Embedded sensing architectures are displacing analog thermostats in surgical warming platforms.
The dominant share belongs to Heating Pads, while Thermoelectric Coolers are closing the gap fastest.
Technology:
Cost tier stratification separates capital-intensive active systems from commodity passive materials, with regulatory compliance acting as the sorting mechanism.
- Liquid Circulation:Pump-driven fluid networks achieve precise thermal transfer through conductive exchange. Academic medical centers in the United States deploy these systems for perioperative normothermia maintenance, where ISO 80601-2-35 electrical safety certification filters out non-compliant suppliers.
- Peltier Effect:Direct current across bismuth telluride junctions creates heat pumping without mechanical refrigeration. Portable medical device manufacturers favor this technology for battery-operated field applications, though copper and semiconductor input volatility compresses margins.
- Infrared:Radiative thermal energy transfer enables non-contact heating for industrial polymer curing and semiconductor fabrication processes.
- Phase Change Materials:Latent heat absorption through solid-liquid transitions provides passive cooling without power dependence. Salt hydrate eutectics are replacing PFAS-laden formulations under REACH restrictions.
Liquid Circulation holds the installed base advantage, though Peltier Effect systems are expanding most quickly into refrigerant-restricted environments.
Application:
Customer type diversity creates divergent performance specifications, from clinical precision to food safety compliance to manufacturing throughput.
- Medical Treatment:Perioperative hypothermia prevention and therapeutic temperature management demand set-point precision within 0.5 degrees Celsius. German hospital infrastructure renewal programs explicitly budget for temperature-controlled therapeutic devices in operating theater modernization.
- Industrial Processes:Thermal control for polymer curing, semiconductor fabrication, and materials processing requires sustained high-temperature operation. Infrared warming equipment leads integration here.
- Sports Recovery:Portable cooling systems support athlete performance and post-exertion recovery. Phase change material vests serve ambulatory applications.
- Food Preservation:Cold-chain integrity for perishables depends on continuous temperature logging and compliance documentation.
Medical Treatment commands the revenue concentration, while Industrial Processes are gaining share fastest through manufacturing reshoring initiatives.
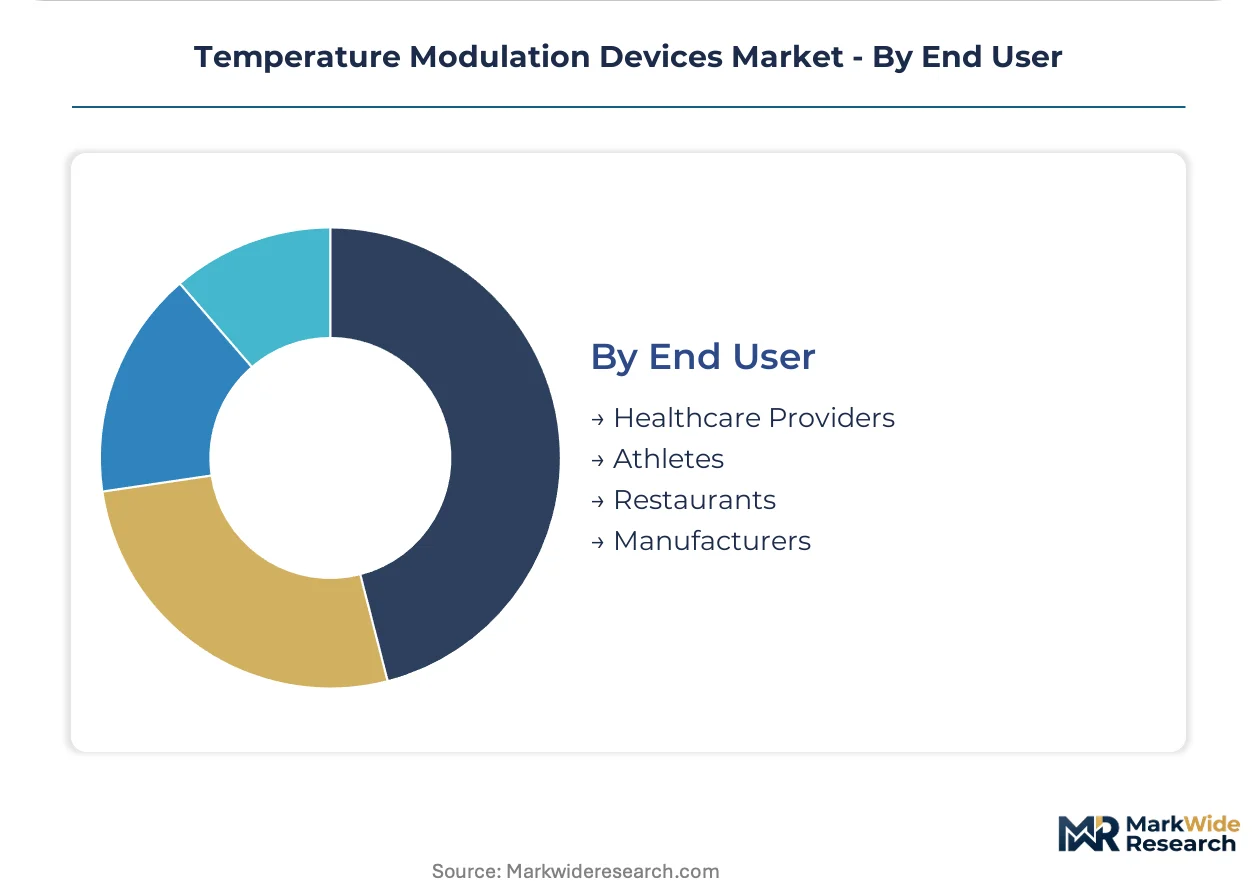
End User:
Procurement authority and volume scale separate institutional purchasers from individual consumers, with contract structures reshaping vendor economics.
- Healthcare Providers:Hospitals and surgical centers source patient warming systems through consolidated vendor lists. FDA 510(k) clearance timelines and EU MDR technical documentation obligations extend procurement cycles but lock in compliant suppliers.
- Manufacturers:Industrial process integrators deploy thermal management for production line control. Energy efficiency regulations from EPA and MEE drive replacement demand for legacy systems.
- Athletes:Individual and team purchasers prioritize portability and rapid deployment. Direct-to-consumer channels dominate.
- Restaurants:Food service operators require temperature compliance for safety protocols. Price sensitivity limits premium system adoption.
Healthcare Providers dominate procurement volume, while Manufacturers are climbing the fastest on industrial automation investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German hospital procurement channels while US group purchasing organizations compress vendor margins through consolidated vendor lists. Federal infrastructure programs in Berlin and state-level energy efficiency mandates in California reshape demand trajectories across both markets.
Germany
Hospital infrastructure renewal programs prioritize temperature-controlled therapeutic devices in operating theater modernization budgets. EU MDR technical documentation obligations filter non-compliant suppliers from federal procurement lists. Bavaria's medical device cluster around Munich anchors production of ISO 80601-2-35 certified patient warming systems.
United States
Academic medical centers pilot fiber-optic thermal sensing platforms for perioperative outcome documentation. FDA 510(k) clearance timelines extend product launch windows by months, locking in established vendors. The Greater Boston corridor concentrates digital thermal control R&D for surgical applications.
China
MEE decarbonization mandates accelerate refrigerant-free thermal management adoption in healthcare facilities. NMPA medical device registration requirements reshape import substitution patterns for patient warming equipment. The Yangtze River Delta cluster around Shanghai dominates Peltier module assembly for portable medical devices.
Japan
METI energy efficiency standards drive replacement demand for legacy compressor-based systems in industrial process heating. PMDA quality management system audits enforce thermal uniformity testing protocols that differentiate compliant suppliers. The Kansai region around Osaka anchors precision thermoelectric component fabrication.
United Kingdom
NHS procurement frameworks consolidate vendor lists for surgical patient warming platforms, squeezing mid-tier suppliers. MHRA post-Brexit regulatory divergence creates parallel compliance tracks for EU MDR and UKCA marking. The Cambridge-London corridor concentrates closed-loop thermal control algorithm development.
Temperature Modulation Devices Market Competitive Landscape
Diversified industrial conglomerates and specialized medical device manufacturers split the market along technology-architecture lines. Consolidation pressure intensifies as group purchasing organizations demand full-suite warming platforms bundled with disposable consumable ecosystems. Three archetypes dominate: automotive-thermal crossovers, dedicated surgical warming specialists, and infusion-therapy consumable suppliers. Capacity expansion and strategic portfolio diversification represent the dominant competitive moves as vendors defend position against refrigerant-free technology transitions.
Within the diversified industrial tier, Gentherm Incorporated and 3M Company exemplify cross-sector thermal expertise applied to medical platforms. Stryker Corporation anchors the surgical-specialist archetype through dedicated operating-room product lines. These three occupy positions across distinct procurement channels, with Gentherm leveraging automotive scale, 3M representing materials-science integration, and Stryker concentrating on acute-care workflow capture.
| Leading Market Players |
|---|
| Gentherm Incorporated |
| Smiths Group plc |
| 3M Company |
| The Surgical Company |
| Becton, Dickinson and Company |
| Stryker Corporation |
| ICU Medical, Inc. |
| ZOLL Medical Corporation |
| Belmont Medical Technologies |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta manufacturing cluster around Shanghai dictates Peltier module availability and pricing leverage for medical device OEMs sourcing solid-state thermal components. Downward cost pressure from consolidated hospital group purchasing organizations in the United States and Germany compresses margins for non-integrated suppliers lacking captive semiconductor fabrication.
Pricing Analysis
Configured-to-order surgical warming platforms command 40-60% premiums over standard patient warming blankets due to embedded fiber-optic sensing and closed-loop control architectures. Pricing stratifies across FDA 510(k)-cleared premium tiers, ISO 80601-2-35 certified standard tiers, and uncertified economy imports. Cost compression in the standard tier intensifies because GPOs unbundle service contracts and force transparent lifecycle cost comparisons. Healthcare providers in Germany exhibit lowest price sensitivity due to federal infrastructure renewal budgets, while ambulatory surgery centers in the United States face acute capital constraint.
Supply Chain Analysis
Taiwan Semiconductor Manufacturing Company and South Korean foundries dominate bismuth telluride wafer fabrication for Peltier junctions, with Chinese EMS providers handling final module assembly. Raw material dependencies center on copper interconnects, ceramic substrates, and rare-earth-doped semiconductor materials. Single-source vulnerability concentrates in East Asian thermal semiconductor wafer production, exposing medical device OEMs to geographic disruption. Distribution runs through authorized medical device distributors in regulated markets and direct OEM relationships for industrial process integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of ISO 80601-2-35 certified manufacturing infrastructure and specialized thermal metrology capability concentrates competitive advantage among incumbent suppliers with validated quality systems. This capability gap limits rapid market entry and sustains pricing power for compliant vendors.
For Market Incumbents: Build regulatory certification moats by accelerating EU MDR technical documentation and post-market surveillance infrastructure before compliance deadlines. Deepen backward integration into Peltier semiconductor sourcing through long-term offtake agreements with Taiwanese foundries to offset copper and bismuth telluride price volatility. Capture channel control by bundling disposable temperature sensor consumables with capital equipment to lock in hospital procurement committees against emerging entrants. For New Entrants and Emerging Players: Build out home-based recovery segments with portable phase change material cooling systems targeting post-acute care providers outside consolidated GPO networks. Penetration concentrates in ambulatory surgical centers and sports medicine clinics seeking refrigerant-free alternatives for EPA compliance. A direct-to-clinic go-to-market angle bypasses centralized hospital procurement and accelerates initial reference site accumulation. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because tightening FDA and EU MDR requirements extend product development timelines and inflate compliance costs that favor scaled incumbents. Acquisition targets with validated ISO 80601-2-35 infrastructure and established hospital system relationships offer defensive positioning. The signal to watch is NMPA registration acceleration in China indicating import substitution momentum that could reshape competitive dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Post-market surveillance infrastructure locks in federal procurement eligibility in Germany. |
| Peltier Module Backward Integration | Captive semiconductor sourcing insulates margins from East Asian supply concentration. |
| Disposable Sensor Consumable Ecosystem | Recurring revenue streams defend against GPO unbundling of service contracts. |
| Home-Based Recovery Platform Launch | Portable phase change systems penetrate ambulatory segments outside hospital procurement. |
| FDA 510(k) Parallel Submission Strategy | Accelerated clearance timelines compress emerging entrant market entry windows. |
Research Methodology
A standing panel of hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and thermal device regulatory affairs leads provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) clearance databases, EU MDR technical documentation filings, hospital procurement contract registries, and ISO 80601-2-35 certification records. Bottom-up unit demand modeling triangulated against top-down healthcare capital expenditure forecasts across the analysis window.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation modeling across product architecture, thermal physics mechanism, clinical versus industrial application, and purchaser type dimensions. CAGRs derived from weighted regression of historical procurement data and forward-looking infrastructure budget trajectories. Forecast inputs incorporated German hospital modernization program allocations and EPA decarbonization mandate implementation timelines for refrigerant-free system replacement.
Sensitivities concentrate around EU MDR compliance deadline extensions, copper and semiconductor commodity price spikes, and NMPA registration acceleration in China altering import substitution patterns. Quarterly review of hospital GPO vendor list consolidations and thermal semiconductor foundry capacity announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Semiconductor Leak Detectors Market
Detection and Regulation Devices
Digital Underground Metal Detector Market
Detection and Regulation Devices
Temperature Detection Screen Market
Detection and Regulation Devices
Walk Through Metal Detector Market
Detection and Regulation Devices
Surge Suppression IC Market
Detection and Regulation Devices
Global Noise Detection and Monitoring Market
Detection and Regulation Devices
Limiter Diodes Market
Detection and Regulation Devices
Wireless Gas Detection System Market
Detection and Regulation Devices
Electronic Article Surveillance Market
Detection and Regulation Devices
Radar Detector Market
Detection and Regulation Devices
Digital Metal Detector Market
Detection and Regulation Devices
Hydrogen Detection Transmitters Market
Detection and Regulation Devices
Pyro Electric Infrared Detectors Market
Detection and Regulation Devices
Spark Detector Market
Detection and Regulation Devices
Handheld Optical Gas Imaging Camera Market
Detection and Regulation Devices
Global Ultrasonic Air Bubble Detectors Market