
 Digital Metal Detector Market | 2026-2036
Digital Metal Detector Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Metal Detector Market Outlook
The capital-intensity gap between high-throughput industrial specialists and handheld consumer brands is collapsing. METTLER TOLEDO leverages its precision weighing heritage to dominate pharmaceutical and food-grade inspection lines. Garrett Electronics Inc. anchors the recreational and security handheld segments through deep channel control in North American retail.
A digital metal detector is an electronic instrument that senses metallic objects through electromagnetic field disturbance, typically operating at frequencies between 3 kHz and 100 kHz depending on target conductivity and soil mineralization. Industrial models integrate conveyor-mounted coil arrays with automatic reject mechanisms to safeguard packaged goods and raw material flows. Pulse induction systems lead underwater and gold prospecting applications due to superior depth penetration and saltwater stability, while very low frequency units retain cost advantages for hobbyist treasure hunting. Pipeline detectors command premium pricing in oil and gas infrastructure, where magnetometry variants address non-ferrous detection challenges in corrosive environments.
FDA food safety modernization rules and EU machinery directives shape product certification requirements across export-bound manufacturing. CE marking under EU electromagnetic compatibility standards gates market access for European-bound industrial systems. Stakeholders must weigh technology migration timelines against evolving hazardous substance thresholds in both North American and European compliance frameworks.
Market Dynamics
Inline inspection mandates from FDA hazard analysis protocols are forcing food processing plants to upgrade from manual sampling to continuous digital detection architectures, collapsing the capital threshold between industrial and mid-tier equipment tiers.
Growth Catalysts
- EU Machinery Directives:CE marking requirements under electromagnetic compatibility standards compel export-bound manufacturers to certify inline detection systems, creating baseline demand for upgraded coil array technologies.
- Food-grade inspection lines:Packaged goods producers in Germany's precision manufacturing corridor are deploying conveyor-mounted systems with automatic reject mechanisms to satisfy retailer contamination liability protocols.
- Pulse induction advancement:Saltwater stability and depth penetration improvements are expanding underwater pipeline inspection contracts in corrosive oil and gas infrastructure.
Market Restraints
- Copper coil volatility:Electromagnetic sensor arrays depend on copper winding stability, and price swings in refined copper concentrates compress margin predictability for mid-tier manufacturers.
- Magnetometry substitution:Non-ferrous detection challenges in certain mineralized soils favor fluxgate magnetometer alternatives, capping pulse induction penetration in specific geological applications.
- REACH substance thresholds:Evolving hazardous substance restrictions in European compliance frameworks extend certification timelines for coil encapsulation materials and electronic component sourcing.
Strategic Opportunities
- Pharmaceutical serialization:Track-and-trace mandates for drug packaging create adjacent demand for metal contamination verification before serialization line integration.
- India food safety expansion:FSSAI enforcement modernization in processed food corridors opens retrofit opportunities for inline detection systems in existing packaging infrastructure.
- AI-driven false-positive reduction:Machine learning classification of electromagnetic signatures converges with hardware miniaturization to enable portable units with industrial-grade discrimination capability.
Industry Challenges
- Electromagnetic interference calibration:Variable mineralization across extraction sites demands field technicians with rare expertise in frequency-tuning protocols, constraining deployment velocity.
- Legacy conveyor integration:Retrofitting automatic reject mechanisms onto existing material handling lines requires mechanical engineering coordination that extends installation timelines.
- Dual certification burden:Simultaneous FDA food contact and ATEX hazardous area approvals for oil and gas applications multiply documentation requirements for multi-sector vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Metal Detector Market |
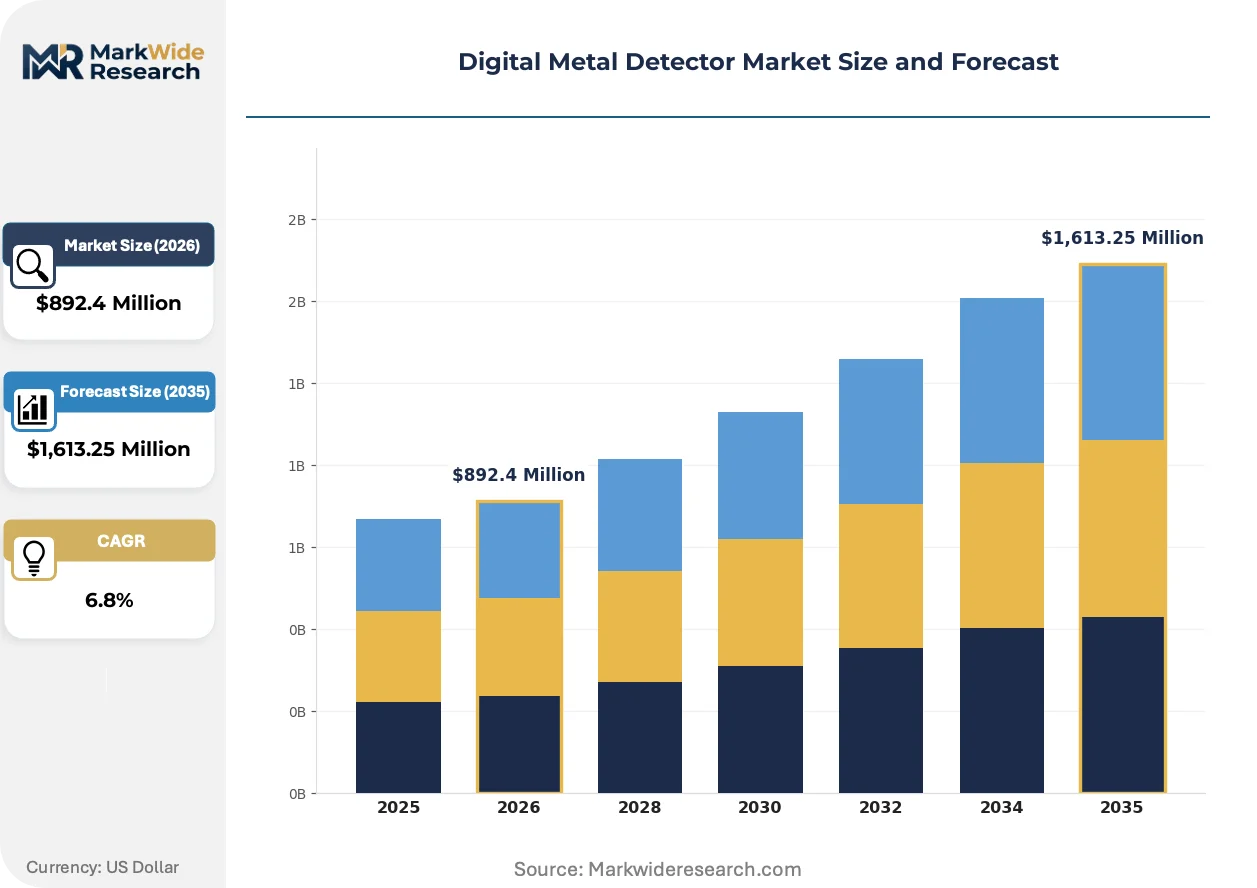
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,613.25 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Detectors, Ground Search Detectors, Industrial Detectors, Pipeline Detectors End User: Mining, Archaeology, Security, Construction Technology: Pulse Induction, Very Low Frequency, Beat-frequency Oscillation, Magnetometry Application: Treasure Hunting, Utility Location, Gold Prospecting, Environmental Monitoring |
| Companies Covered | Fortress Technology Inc., Eriez, METTLER TOLEDO, OSI Systems Inc., WIPOTEC GmbH, Thermo Fisher Scientific Inc., Garrett Electronics Inc., Sesotec, CEIA S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Metal Detector Market Strategic Shifts
Detection hardware is compressing toward semiconductor-scale integration while regulatory complexity fragments certification pathways, forcing vendors to choose between depth specialization or horizontal compliance breadth.
Multi-frequency digital signal processing is miniaturizing. Advanced coil controllers now embed FPGA arrays that simultaneously sweep 3 kHz to 100 kHz bands, replacing discrete analog filter banks. Pharmaceutical tablet inspection lines in Switzerland and Singapore are piloting these units to eliminate aluminum blister packaging contamination without line speed reduction. The technology is miniaturizing benchtop units toward handheld form factors while preserving industrial discrimination thresholds.
REACH substance restrictions are tightening encapsulation material specifications. Coil potting compounds containing legacy flame retardants face sunset dates under evolving ECHA candidate list reviews. European-bound industrial systems must now document full material disclosure across electromagnetic shielding components. German precision manufacturers are responding by qualifying bio-based epoxy alternatives that maintain saltwater stability in pipeline inspection deployments.
Service unbundling is disrupting traditional capital equipment sales. Food processors in the United States now lease detection capacity with per-package pricing rather than purchasing conveyor-mounted systems outright. Third-party inspection providers maintain coil calibration and software update responsibilities. This model concentrates fastest in co-packing facilities serving multiple brand owners with variable SKU volumes.
Digital Metal Detector Market Segmentation
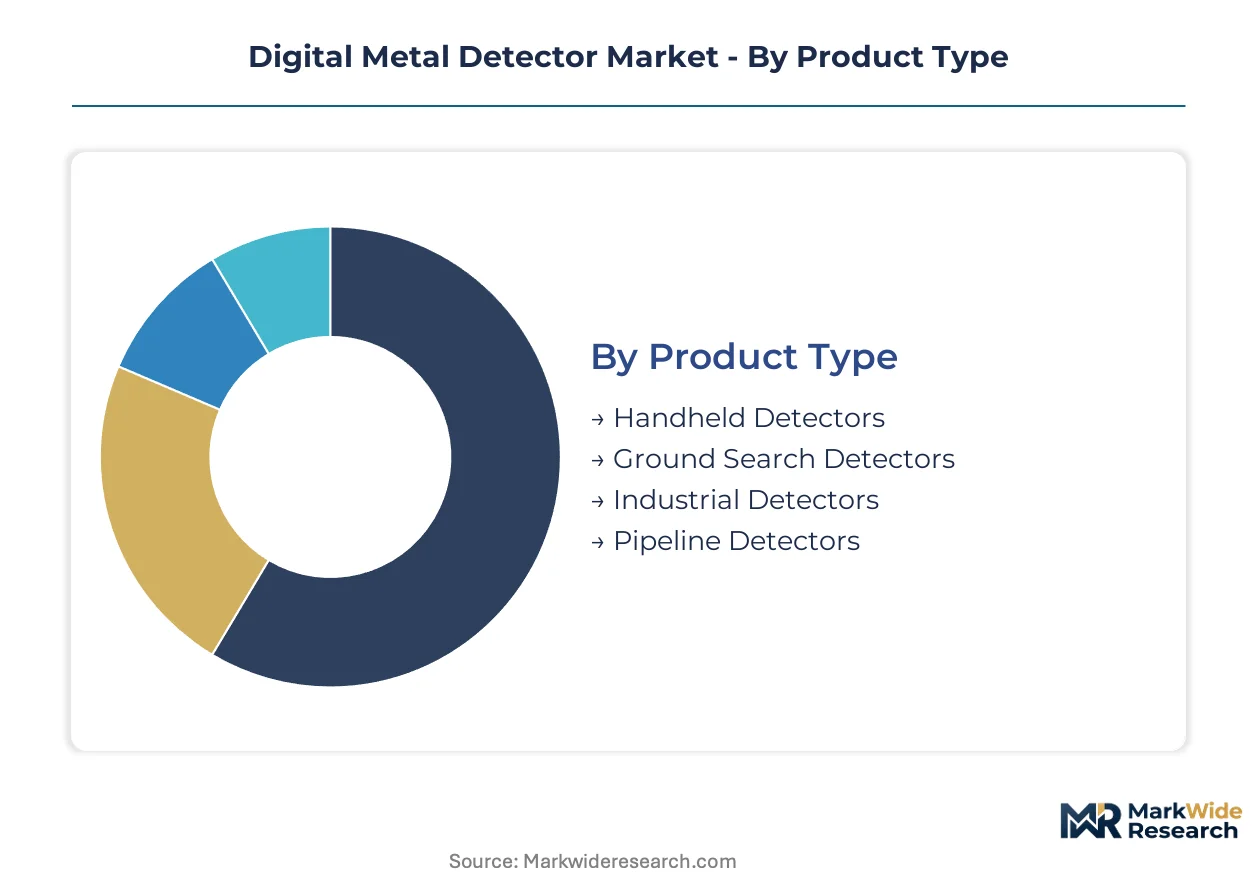
Digital metal detector segmentation reveals divergent channel economics. Industrial systems move through direct technical sales with integration engineering, while handheld units distribute through retail and e-commerce with minimal service attachment. Understanding these flow patterns exposes margin concentration and vendor positioning leverage.
Product Type:
Industrial detectors flow through manufacturer-direct channels with field engineering support, whereas handheld and recreational units concentrate in retail distributors and specialty e-commerce platforms with lower touch requirements.
- Handheld Detectors:Portable units operating between 3 kHz and 100 kHz with simplified discrimination circuits. Security screening contracts at German transportation hubs and recreational sales through North American outdoor retailers concentrate demand here. Coil miniaturization and battery efficiency improvements are compressing price points toward consumer accessibility.
- Ground Search Detectors:Mid-weight systems with adjustable frequency sweep for mineralized soil compensation. Archaeological survey contracts in the United Kingdom and hobbyist treasure hunting communities in Australia drive procurement. Depth penetration specifications separate premium from economy tier offerings.
- Industrial Detectors:Conveyor-mounted coil arrays with automatic reject mechanisms safeguarding packaged goods flows. FDA-mandated hazard analysis protocols in United States food processing plants and retailer contamination liability requirements in Germany's precision manufacturing corridor anchor demand.
- Pipeline Detectors:Magnetometry and pulse induction variants engineered for corrosive oil and gas infrastructure inspection. Saltwater stability requirements and depth penetration specifications command premium pricing in underwater deployment contracts.
Industrial detectors dominate installed base. Handheld units are where expansion concentrates.
End User:
Mining and construction applications prioritize depth penetration and mineralization tolerance, while security and archaeology segments emphasize discrimination precision and portability.
- Mining:Extraction operators require pulse induction systems for deep target detection in highly mineralized formations. Gold prospecting operations in Western Australia and alluvial mining contracts in Brazil concentrate procurement toward units with superior ground balance automation.
- Archaeology:Research institutions and heritage management agencies demand multi-frequency discrimination to distinguish ferrous debris from non-ferrous artifacts. Survey contracts in Italy and preservation mandates in Egypt drive specification requirements for non-invasive subsurface mapping.
- Security:Event venues, transportation terminals, and correctional facilities deploy handheld wands and walk-through portals. TSA-equivalent screening protocols in Saudi Arabia and stadium security contracts in Qatar shape procurement toward rapid throughput with minimal false-positive rates.
- Construction:Utility location and rebar detection before excavation drives demand for electromagnetic and ground-penetrating radar hybrid systems. Infrastructure renewal projects in Japan and subway expansion contracts in India concentrate volume.
Security maintains the broadest installed footprint. Mining represents the steepest expansion trajectory.
Technology:
Pulse induction and very low frequency systems split between premium depth applications and cost-sensitive recreational markets, while magnetometry captures specialized non-ferrous detection in corrosive environments.
- Pulse Induction:Transmits high-voltage pulses into the ground, measuring decay time to detect metallic objects without sensitivity to mineralization. Underwater pipeline inspection contracts and gold prospecting in saltwater environments anchor premium demand. FPGA-based multi-frequency controllers are miniaturizing these systems toward handheld form factors.
- Very Low Frequency:Continuous wave transmission at discrete frequencies with phase discrimination between target and ground response. Hobbyist treasure hunting and entry-level security screening concentrate volume due to manufacturing simplicity and lower component costs.
- Beat-frequency Oscillation:Two oscillators create audible frequency difference upon target detection, simplest architecture for basic metallic object location. Educational markets and ultra-low-cost recreational units in emerging economies sustain residual demand.
- Magnetometry:Measures distortion in Earth's magnetic field caused by ferromagnetic objects, essential for detecting non-ferrous pipelines and UXO clearance. Oil and gas infrastructure inspection and military ordnance disposal contracts command specialized procurement.
Very low frequency systems dominate unit volume. Pulse induction is gaining share fastest in value terms.
Application:
Treasure hunting and gold prospecting flow through retail and enthusiast channels with seasonal demand patterns, while utility location and environmental monitoring concentrate in professional service contracts with recurring calibration requirements.
- Treasure Hunting:Recreational metal detecting for historical artifacts and coin recovery. Club-organized events in the United Kingdom and beach detecting permissions in Florida concentrate hobbyist equipment turnover. Social media discovery documentation drives replacement cycle acceleration.
- Utility Location:Pre-excavation electromagnetic scanning to avoid gas, water, and electrical infrastructure strikes. Municipal contract specifications in France and fiber optic deployment mandates in South Korea require certified operator training and equipment calibration documentation.
- Gold Prospecting:Alluvial and hard rock exploration targeting native metal deposits. Pulse induction depth advantages in Western Australian Pilbara operations and small-scale mining cooperatives in Ghana shape regional specification preferences.
- Environmental Monitoring:Contaminated site assessment and landfill boundary verification. EPA-equivalent remediation mandates in Canada and brownfield redevelopment protocols in the Netherlands drive procurement toward data-logging capable systems with GPS integration.
Utility location anchors professional service revenue. Gold prospecting is where hardware margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Food processors in Germany accept premium pricing for precision inspection systems, while hobbyist markets in Brazil and Southeast Asia gravitate toward entry-level handheld units with basic discrimination circuits.
United States
FDA hazard analysis mandates force food processing plants toward continuous inline detection architectures. The Food Safety Modernization Act tightens contamination liability thresholds for packaged goods producers. Chicago-area meatpacking corridors and California central valley nut processing facilities anchor industrial detector procurement volume.
Germany
CE marking under EU electromagnetic compatibility standards gates market access for export-bound industrial systems. REACH substance thresholds extend certification timelines for coil encapsulation materials. Bavaria's precision manufacturing corridor concentrates conveyor-mounted system deployment for pharmaceutical and food-grade inspection lines.
China
Domestic food safety enforcement modernization accelerates retrofit demand in existing packaging infrastructure. GB standards for electromagnetic compatibility shape local certification requirements. Yangtze River Delta electronics assembly clusters and Pearl River Delta consumer goods manufacturing zones drive mid-tier industrial detector volume.
India
FSSAI enforcement expansion in processed food corridors creates retrofit opportunities for inline detection systems. The country's food safety regulator tightens contamination protocols across packaged goods supply chains. Maharashtra and Gujarat pharmaceutical tablet manufacturing belts pilot multi-frequency digital signal processing units for aluminum blister packaging verification.
Australia
Gold prospecting operations in Western Australia's Pilbara region concentrate pulse induction system procurement toward deep target detection specifications. The country's mining safety regulator mandates electromagnetic survey protocols for pre-excavation utility location. Queensland beach detecting permissions and club-organized events sustain recreational handheld turnover through seasonal replacement cycles.
Digital Metal Detector Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the digital metal detector market. Industrial system vendors with precision weighing heritage dominate pharmaceutical and food-grade inspection lines, while handheld specialists anchor recreational and security segments through retail channel control. Three archetypes define competitive positioning: integrated precision equipment conglomerates, security-focused electronics manufacturers, and regional fabrication specialists serving cost-sensitive emerging markets. Consolidation pressure concentrates through backward integration into coil winding and FPGA controller production, alongside geographic expansion into India's food safety modernization wave.
Among precision equipment conglomerates, METTLER TOLEDO occupies a position exemplifying industrial-grade inspection heritage, while Thermo Fisher Scientific Inc. represents the analytical instrumentation archetype extending into contamination detection. Garrett Electronics Inc. anchors the recreational and security handheld tier with deep North American retail penetration. These three entities illustrate the vertical stratification between premium industrial systems and accessible consumer units.
| Leading Market Players |
|---|
| Fortress Technology Inc. |
| Eriez |
| METTLER TOLEDO |
| OSI Systems Inc. |
| WIPOTEC GmbH |
| Thermo Fisher Scientific Inc. |
| Garrett Electronics Inc. |
| Sesotec |
| CEIA S.p.A. |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day coil winding lead times concentrate pricing power among German and Japanese electromagnetic component specialists, compressing margin flexibility for mid-tier detector assemblers who lack captive ferrite core production. Inventory buffers at FPGA controller distributors in Taiwan further amplify cost pass-through volatility when copper concentrate prices swing.
Pricing Analysis
Service contract revenue—spanning coil recalibration, software updates, and per-package inspection leasing—drives lifetime value concentration in the industrial tier. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical lines from CE-marked food-grade systems and basic recreational handhelds. Price differentiation hinges on certification grade and after-sales bundling intensity. Cost compression in the handheld tier intensifies because battery and coil miniaturization commoditize entry-level discrimination circuits. Security screening procurement at German transportation hubs shows least price sensitivity; Brazilian hobbyist channels exhibit maximum elasticity.
Supply Chain Analysis
China and Japan anchor ferrite core and precision coil winding capacity, while Taiwan and South Korea concentrate FPGA controller and electromagnetic shielding component fabrication. Electromagnetic sensor arrays draw from refined copper concentrates, rare-earth ferrite powders, and epoxy encapsulation compounds. Single-source vulnerability in high-frequency FPGA arrays from Xilinx and Altera distribution channels threatens production continuity for multi-frequency industrial systems. Distribution runs through manufacturer-direct technical sales for conveyor-mounted units, retail distributors for handheld security and recreational segments, and third-party inspection service providers for leased capacity models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluxgate magnetometry and ground-penetrating radar hybrids threaten pulse induction dominance in pipeline inspection contracts, forcing electromagnetic specialists to defend sensor architecture relevance through certification lock-in and service bundling.
For Market Incumbents: Compound certification breadth across FDA food contact and ATEX hazardous area approvals to raise switching costs for oil and gas procurement officers evaluating magnetometry alternatives. Deepen backward integration into FPGA controller firmware development to capture margin from multi-frequency signal processing miniaturization. Coil winding captive supply in Germany's precision manufacturing corridor reinforces delivery reliability against Asian component volatility. For New Entrants and Emerging Players: Calibration-as-a-service gaps in India's FSSAI modernization wave expose white-space for third-party inspection providers who lease detection capacity with per-package pricing. Target co-packing facilities serving multiple brand owners with variable SKU volumes as the most penetrable end-use archetype. Pursue direct technical sales partnerships with existing conveyor OEMs to bypass entrenched distributor relationships in United States meatpacking corridors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified analytical instrumentation conglomerates where metal detection represents non-core revenue concentration. Five-to-ten-year viability frames this market around regulatory enforcement durability rather than technology substitution risk. Acquisition screening prioritizes coil array calibration IP and pharmaceutical serialization integration capabilities. The signal to watch is REACH substance threshold acceleration for coil encapsulation materials, which would compress margin for non-compliant inventory holders.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-frequency FPGA Controller Development | Enables miniaturization of industrial-grade discrimination into handheld form factors for security screening contracts. |
| REACH-compliant Bio-based Epoxy Qualification | Preserves European market access for pipeline inspection systems as ECHA candidate list reviews tighten. |
| Per-package Inspection Leasing Model | Captures recurring revenue from United States co-packing facilities with variable contamination liability exposure. |
| Pharmaceutical Serialization Line Integration | Positions contamination verification upstream of track-and-trace mandates in Swiss and Singapore tablet manufacturing. |
| India FSSAI Retrofit Channel Partnership | Opens installed base penetration in Maharashtra and Gujarat packaging infrastructure with minimal greenfield competition. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with plant engineers, aftermarket service heads, OEM procurement teams, and food safety compliance officers; and secondary validation against FDA warning letter databases, EU machinery directive certification registries, customs trade records for electromagnetic component flows, and SEC filings from precision equipment conglomerates. Bottom-up unit economics triangulated against top-down regulatory enforcement timelines.
Across the projection horizon, the analytical framework modeled product type, end-use industry, technology architecture, and application vertical segmentation dimensions. CAGRs derived from installed base replacement cycles, regulatory mandate effective dates, and coil miniaturization cost curves. Forecast inputs incorporated FSSAI enforcement cadence in India and FDA hazard analysis protocol adoption velocity in United States food processing corridors.
Forecasts assume regulatory continuity in FDA food safety modernization and REACH substance threshold regimes; material policy shifts would require re-modeling. Specific risks include copper concentrate price volatility compressing mid-tier manufacturer margins, and magnetometry substitution accelerating in corrosive pipeline environments. Recalibration cycles align with material shifts in hazardous substance compliance thresholds and electromagnetic interference standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Transient Voltage Suppressor Market
Detection and Regulation Devices
Vapour Particle Barrier Market
Detection and Regulation Devices
Digital Vacuum Regulators Market
Detection and Regulation Devices
Vacuum Leak Detectors Market
Detection and Regulation Devices
Portable Radar Detectors Market
Detection and Regulation Devices
Infrared Detection Chip Market
Detection and Regulation Devices
Infrared Detector Market
Detection and Regulation Devices
Chemical Detection Armband Market
Detection and Regulation Devices
Active Buzzer Market
Detection and Regulation Devices
Global a-Si X-Ray Flat Panel Detectors Market
Detection and Regulation Devices
Volatile Organic Compound (VOC) Detector Market
Detection and Regulation Devices
Microwave Leakage Detector Market
Detection and Regulation Devices
Voltage Detection System Market
Detection and Regulation Devices
Duct Smoke Detectors Market
Detection and Regulation Devices
Noise Monitoring Device Market
Detection and Regulation Devices
Asia-Pacific Trace Detection Screening Market