
 Global Gas Sensors Market | 2026-2036
Global Gas Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gas Sensors Market Analysis
Germany's sensor component fabrication base is narrowing as Bosch and Siemens AG extend their captive MEMS foundry operations. Honeywell International Inc. leverages its distributed safety systems channel to dominate North American process industry retrofit programs. Figaro Engineering Inc. anchors the Asia-Pacific supply chain through specialized metal oxide semiconductor wafer production in Japan.
Gas sensors are electrochemical, semiconductor, or spectroscopic transducers that detect target molecules at concentrations ranging from parts-per-billion to percentage levels, converting chemical information into quantifiable electrical signals for industrial safety and environmental compliance systems. Electrochemical sensors sustain the largest installed base across emission monitoring applications due to proven selectivity for toxic gases like carbon monoxide and hydrogen sulfide. Infrared technology is displacing legacy platforms in leak detection as optical path stability improves and unit costs decline across natural gas distribution networks.
The EU Green Deal and F-Gas Regulation compel European operators to upgrade refrigerant detection infrastructure, while China's MEE enforces GB emission standards that mandate continuous stack monitoring. OSHA permissible exposure limits and EPA stationary source rules shape product certification requirements in the United States. Stakeholders must calibrate R&D portfolios against diverging regional certification timelines rather than pursuing single-standard designs.
Market Dynamics
Metal oxide semiconductor technology is compressing replacement cycles across high-humidity industrial environments, forcing incumbent electrochemical suppliers to defend installed bases through firmware upgrades rather than hardware swaps.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant leak detection mandates across commercial HVAC installations are pulling infrared sensor volumes upward in Germany, France, and Italy.
- China's MEE enforcement:Continuous emission monitoring system retrofits in the Yangtze and Pearl River Delta manufacturing corridors are accelerating metal oxide semiconductor procurement.
- Industrial safety digitization:Wireless-enabled gas detection nodes are penetrating oil and gas facilities seeking predictive maintenance integration with distributed control systems.
Market Restraints
- Palladium and platinum input volatility:Electrochemical sensor electrodes depend on noble metal catalysts whose price swings compress margin visibility for mid-tier fabricators.
- Japanese wafer supply concentration:Specialized metal oxide semiconductor substrate production clusters in Kyushu and Tohoku create single-source vulnerability for Asia-Pacific module assemblers.
- Cross-sensitivity limitations:Humidity interference in semiconductor platforms persists below 15% relative humidity, restricting deployment in arid climate zones without conditioning hardware.
Strategic Opportunities
- India's industrial corridor buildout:The Delhi-Mumbai Industrial Corridor and Chennai-Bengaluru manufacturing belt remain underpenetrated for continuous emission monitoring relative to installed industrial capacity.
- Electrochemical-infrared convergence:Hybrid sensor architectures combining semiconductor selectivity with optical stability are opening medical anesthesia monitoring applications.
- OSHA process safety management updates:Anticipated revisions to permissible exposure limit enforcement protocols will force downstream chemical processors into detection infrastructure refreshes.
Industry Challenges
- Calibration technician scarcity:Field service networks lack personnel trained on both electrochemical cell replacement and infrared optical path alignment, extending downtime windows.
- Legacy system integration friction:Analog 4-20mA output sensors predominate in 1990s-era safety instrumented systems, complicating digital retrofit without control system replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gas Sensors Market |
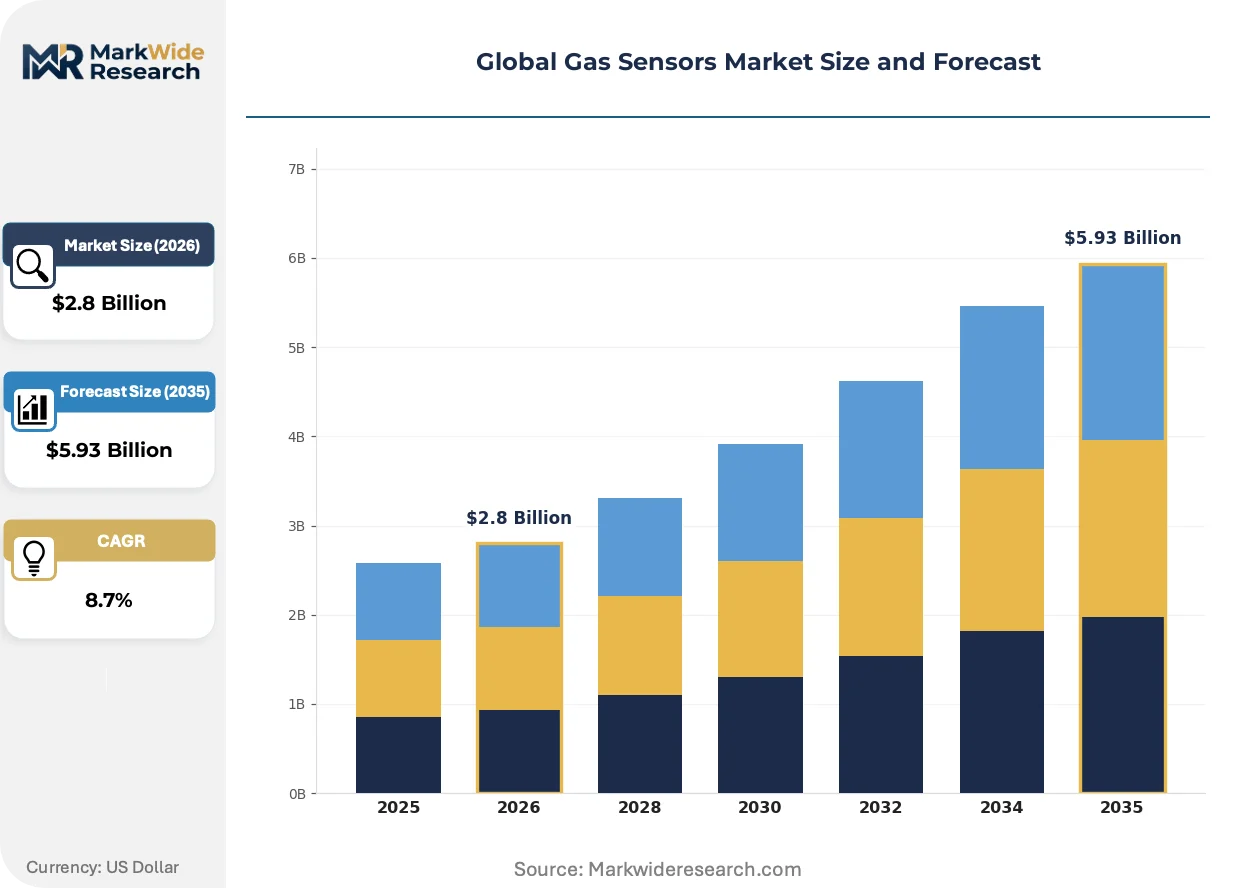
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Oxide Semiconductors, Electrochemical, Infrared, Photoionization Technology: Wireless, Wired, Optical, Acoustic End User: Manufacturing, Healthcare, Environmental Monitoring, Automotive Application: Indoor Air Quality, Emission Monitoring, Leak Detection, Safety Systems |
| Companies Covered | Honeywell International Inc., Figaro Engineering Inc., Drägerwerk AG & Co. KGaA, Robert Bosch GmbH, Siemens AG, ABB Ltd., Amphenol Corporation, Sensirion AG, Alphasense, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gas Sensors Market Emerging Trajectories
Sensor architectures are bifurcating between low-cost commodity modules for residential smoke and carbon monoxide detection and precision instruments for industrial process control, with the middle tier eroding.
Photonic integrated circuits for tunable diode laser absorption spectroscopy are migrating from laboratory analytical instruments into field-deployable natural gas leak detection packages. Pipeline operators in Texas and Alberta are piloting these platforms for sub-ppm methane sensitivity. The technology is migrating from stationary source monitoring into mobile inspection workflows, compressing the addressable market for handheld thermal imaging alternatives.
The EU Green Deal's carbon border adjustment mechanism will require embedded emission verification for imported steel, cement, and aluminum starting in 2026. Continuous monitoring system certification under EN 15267 is becoming a de facto trade compliance instrument. German sensor integrators are pre-certifying modular analyzer racks to capture retrofit demand from Eastern European heavy industry.
Buyers are unbundling sensor hardware from recurring calibration service contracts, treating the latter as competitively tendered commodities. North American petrochemical operators now source detection devices through MRO distributors while contracting third-party metrology labs for span gas verification. This pattern is most visible in the US Gulf Coast, where integrated service providers face margin compression from specialized calibration boutiques.
Global Gas Sensors Market Segmentation
Gas sensor procurement patterns diverge sharply by replacement cadence and certification burden. Industrial buyers cycle through detection hardware on three-to-seven-year horizons depending on technology maturity and regulatory pressure, while residential and commercial installations stretch intervals toward decade-long depreciation schedules.
Product Type:
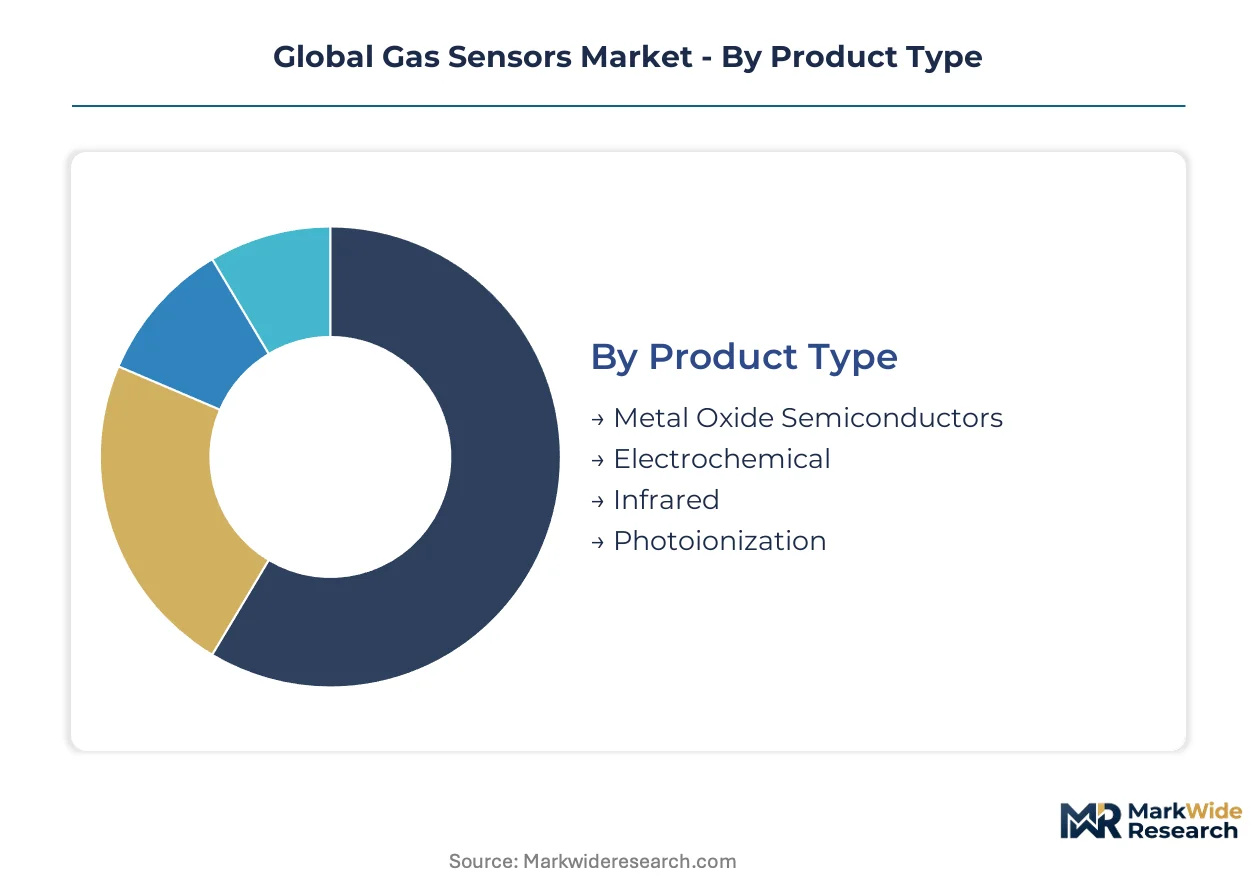
Replacement velocity varies from eighteen-month refresh cycles for humidity-stressed semiconductor platforms to decade-long electrochemical deployments in stable process environments.
- Metal Oxide Semiconductors:Ceramic substrates doped with tin oxide or tungsten oxide detect reducing gases through surface resistance changes. China's Yangtze River Delta manufacturing corridors are absorbing the bulk of procurement as MEE enforcement of GB standards accelerates stack monitor retrofits.
- Electrochemical:Three-electrode cells with porous membrane diffusion barriers deliver parts-per-billion selectivity for toxic gases. The installed base across German chemical parks sustains demand through recurring calibration service contracts rather than hardware replacement.
- Infrared:Non-dispersive absorption spectroscopy using dual-beam compensation eliminates cross-sensitivity to humidity. Natural gas distribution operators in Texas and Alberta are adopting these platforms for sub-ppm methane detection.
- Photoionization:Ultraviolet lamp ionization detects volatile organic compounds at sub-ppm thresholds. Refinery turnaround safety protocols in the US Gulf Coast drive portable detector procurement.
Electrochemical sensors anchor the volume base while metal oxide semiconductors gain share at the steepest rate.
Technology:
Connectivity infrastructure investments are separating premium-tier digital deployments from legacy analog installations on cost-to-integrate metrics.
- Wireless:Battery-powered nodes using LoRaWAN or proprietary mesh protocols transmit concentration data to distributed control systems. Oil and gas facilities in Norway's North Sea operations are prioritizing these for unmanned platform monitoring.
- Wired:4-20mA current loop outputs dominate safety instrumented systems installed during the 1990s. Process plants in Louisiana and Texas face stranded asset risk as control system vendors deprecate analog input modules.
- Optical:Tunable diode laser absorption spectroscopy delivers path-integrated methane measurements across kilometer-scale fence lines. Pipeline operators in Alberta are piloting these for continuous perimeter surveillance.
- Acoustic:Ultrasonic leak detection correlates pressure wave signatures with gas release events. Compressed natural gas refueling stations in Germany deploy these for rapid-response isolation triggering.
Wired technology retains the largest installed base while wireless platforms are expanding most quickly through greenfield industrial digitization projects.
End User:
Compliance-driven procurement intensity separates heavy industrial buyers from price-sensitive commercial segments on specification stringency.
- Manufacturing:Continuous emission monitoring systems in steel, cement, and aluminum production require EN 15267 certification for EU carbon border adjustment compliance. German integrators are pre-certifying modular analyzer racks for Eastern European retrofit demand.
- Healthcare:Anesthesia gas monitoring in surgical suites demands hybrid electrochemical-infrared architectures for simultaneous oxygen, carbon dioxide, and anesthetic agent quantification. Japanese hospital procurement is accelerating following revised clinical engineering standards.
- Environmental Monitoring:Urban air quality networks deploy electrochemical sensor arrays for ozone and nitrogen dioxide mapping. The Delhi-Mumbai Industrial Corridor is expanding stationary monitor density under National Clean Air Programme mandates.
- Automotive:Cabin air quality modules integrate metal oxide semiconductors for external pollution intrusion detection. South Korean OEMs are qualifying domestic sensor suppliers for platform-wide deployment.
Manufacturing commands the highest per-site sensor density while healthcare applications are climbing fastest on safety-critical specification upgrades.
Application:
Regulatory enforcement calendars are compressing procurement timelines for emission-linked applications relative to discretionary indoor air quality deployments.
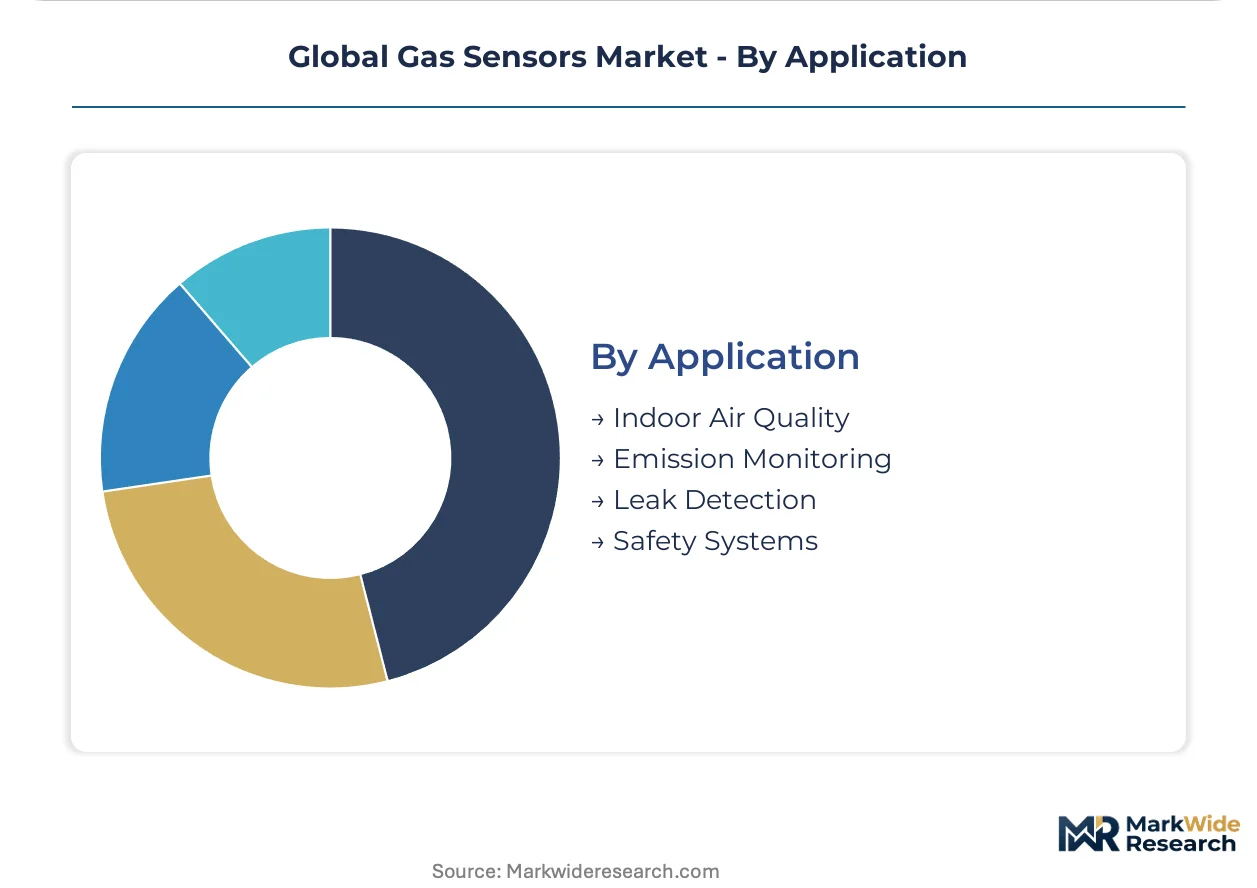
- Indoor Air Quality:Carbon dioxide and volatile organic compound sensors modulate HVAC fresh air intake in commercial buildings. Post-pandemic ventilation code revisions in California and New York are accelerating replacement of legacy single-gas detectors.
- Emission Monitoring:Continuous stack analyzers measure sulfur dioxide, nitrogen oxides, and particulate for regulatory reporting. China's Pearl River Delta power generators are retrofitting under MEE intensified inspection protocols.
- Leak Detection:Refrigerant sensors using infrared absorption detect hydrofluorocarbon releases in commercial HVAC systems. The EU F-Gas Regulation is pulling upgrade demand across Germany, France, and Italy.
- Safety Systems:Fixed-point detectors for hydrogen sulfide and carbon monoxide protect confined space entry in petrochemical facilities. OSHA process safety management updates are forcing downstream chemical processors into infrastructure refreshes.
Emission monitoring anchors current procurement volume while leak detection applications are expanding most quickly on refrigerant phase-down regulatory deadlines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wafer fabrication for metal oxide semiconductors clusters in Kyushu and Tohoku, creating single-source vulnerability for Asia-Pacific module assemblers while European integrators pre-certify modular analyzer racks for carbon border adjustment compliance.
United States
OSHA process safety management updates and EPA stationary source rules are forcing downstream chemical processors into detection infrastructure refreshes. The US Gulf Coast petrochemical corridor drives procurement of fixed-point hydrogen sulfide detectors for confined space entry protocols. Texas and Louisiana process plants face stranded asset risk as control system vendors deprecate analog input modules.
Germany
EU F-Gas Regulation refrigerant leak detection mandates and EU Green Deal carbon border adjustment timelines are pulling infrared sensor volumes upward. Bosch and Siemens AG extend captive MEMS foundry operations, narrowing the sensor component fabrication base. Industrial manufacturing facilities across the Ruhr and Bavarian chemical parks expand emission monitoring deployments under tightening compliance deadlines.
China
MEE enforcement of GB emission standards accelerates replacement cycles for continuous stack monitoring systems. The Yangtze River Delta and Pearl River Delta manufacturing corridors absorb the bulk of metal oxide semiconductor procurement for retrofit programs. Power generators in the Pearl River Delta retrofit under intensified inspection protocols.
Japan
Revised clinical engineering standards accelerate hospital procurement of hybrid electrochemical-infrared architectures for anesthesia gas monitoring. Figaro Engineering Inc. anchors Asia-Pacific supply chain through specialized metal oxide semiconductor wafer production in Kyushu and Tohoku. Tokyo and Osaka medical device clusters drive specification upgrades for surgical suite safety systems.
India
National Clean Air Programme mandates expand stationary monitor density across urban air quality networks. The Delhi-Mumbai Industrial Corridor and Chennai-Bengaluru manufacturing belt remain underpenetrated for continuous emission monitoring relative to installed industrial capacity. Maharashtra and Tamil Nadu industrial zones show the steepest procurement acceleration for electrochemical sensor arrays.
Global Gas Sensors Market Vendor Landscape
Vertically integrated conglomerates and specialized component fabricators split the market into distinct capability tiers. Consolidation pressure concentrates around MEMS foundry access and calibration service network density. Three archetypes dominate: captive semiconductor producers with in-house wafer operations, safety systems integrators leveraging distributed channel infrastructure, and precision sensor specialists focused on medical and environmental applications. Capacity expansion in ceramic substrate production and strategic partnerships for wireless connectivity modules represent the dominant competitive moves.
Among German industrial conglomerates, Robert Bosch GmbH and Siemens AG exemplify the captive foundry archetype through extended MEMS operations. Honeywell International Inc. represents the safety systems integrator model with distributed channel reach into process industry retrofit programs. Figaro Engineering Inc. occupies the precision specialist position, anchoring Asia-Pacific supply chain relationships through Japanese wafer production expertise.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Figaro Engineering Inc. |
| Drägerwerk AG & Co. KGaA |
| Robert Bosch GmbH |
| Siemens AG |
| ABB Ltd. |
| Amphenol Corporation |
| Sensirion AG |
| Alphasense |
| Others |
Supply Flow & Price Mechanics
Kyushu and Tohoku wafer fabrication clusters in Japan anchor metal oxide semiconductor substrate supply, concentrating pricing leverage among captive foundry operators while compressing margin visibility for mid-tier module assemblers dependent on spot procurement. Electrochemical sensor electrode costs swing with palladium and platinum commodity markets, forcing tier-two fabricators into fixed-price contracts to hedge input volatility.
Pricing Analysis
EU F-Gas Regulation and EU Green Deal carbon border adjustment timelines dictate the pricing tier structure across refrigerant detection and emission monitoring segments. Certification grade under EN 15267 separates premium modular analyzer racks from standard sensor modules, while volume scale drives economy-tier procurement for residential carbon monoxide detectors. Cost compression in mid-tier electrochemical platforms is intensifying because buyers unbundle hardware from calibration service contracts, treating span gas verification as competitively tendered commodities. Commercial HVAC installers show highest price sensitivity, whereas German chemical parks demonstrate lowest sensitivity due to compliance-driven specification rigidity.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are becoming standard for ceramic substrate procurement, with Japanese wafer producers leveraging balance-sheet strength to secure preferred supplier status. Production concentrates in Japan, Germany, and China, with Bosch and Siemens AG operating captive MEMS foundries and Figaro Engineering Inc. anchoring Asia-Pacific substrate supply. Raw material dependencies include tin oxide and tungsten oxide dopants, noble metal catalysts for electrochemical cells, and specialized ceramic substrates. Single-source vulnerability in Kyushu and Tohoku production clusters threatens module assemblers. Distribution runs through MRO distributors for hardware and third-party metrology labs for calibration services, particularly visible across the US Gulf Coast petrochemical corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of field technicians trained on both electrochemical cell replacement and infrared optical path alignment constrains service network expansion, creating acquisition premiums for calibration-capable firms. MEMS foundry access and certification infrastructure represent the binding capability gaps.
For Market Incumbents: Insulate installed base positions through firmware upgrade pathways for legacy electrochemical deployments rather than hardware displacement, while deepening backward integration into ceramic substrate production to offset Japanese wafer supply concentration. Metal oxide semiconductor technology substitution threatens electrochemical market share in high-humidity environments. Certification investment under EN 15267 for modular analyzer racks captures EU carbon border adjustment compliance demand. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point for wireless-enabled gas detection nodes, given limited penetration of continuous emission monitoring relative to installed industrial capacity. India's Delhi-Mumbai Industrial Corridor and Chennai-Bengaluru manufacturing belt offer secondary white-space for electrochemical sensor arrays under National Clean Air Programme mandates. Go-to-market positioning through MRO distributors rather than integrated service providers aligns with buyer unbundling trends. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision sensor specialists with medical and environmental application focus over commodity residential detector producers. Long-term viability across the analysis window rests on hybrid electrochemical-infrared architecture development and wireless connectivity module partnerships. Acquisition targets should demonstrate calibration service network density or captive MEMS foundry access. The signal to watch is OSHA process safety management update timing, which would force downstream chemical processors into detection infrastructure refreshes.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Capacity Expansion | Bosch and Siemens AG extend captive operations to narrow component fabrication base for EU Green Deal compliance hardware. |
| Calibration Service Network Buildout | Third-party metrology labs capture span gas verification demand from unbundled buyer contracts across North American petrochemical facilities. |
| Hybrid Sensor Architecture Development | Electrochemical-infrared convergence opens medical anesthesia monitoring applications under revised Japanese clinical engineering standards. |
| Wireless Connectivity Module Partnership | LoRaWAN and proprietary mesh protocol integration enables predictive maintenance integration with distributed control systems in Norway's North Sea operations. |
| EN 15267 Pre-Certification Investment | German integrators capture Eastern European heavy industry retrofit demand for EU carbon border adjustment mechanism compliance. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs and trade data, and industry association reports. Plant managers at German chemical parks, procurement leads at US Gulf Coast petrochemical facilities, and technical R&D directors at Japanese wafer producers provided operational perspective. Calibration service network heads and MRO distribution channel partners supplied downstream market intelligence. Secondary validation drew from EPA stationary source rulemakings, MEE GB standard enforcement protocols, EU F-Gas Regulation implementation guidance, and SEC 10-K disclosures from listed sensor manufacturers. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Forecast inputs include technology replacement cadence by humidity exposure level, regulatory enforcement calendar phasing across MEE, EPA, and EU Green Deal timelines, and wireless connectivity penetration rates in oil and gas facility digitization programs. Segmentation dimensions span product type, technology connectivity infrastructure, end-user compliance intensity, and application regulatory linkage. CAGRs derive from fitted growth curves against historical replacement cycle data and projected compliance-driven procurement accelerations. Industry-specific inputs incorporate noble metal commodity price trajectory assumptions and MEMS foundry capacity expansion announcements.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles, noble metal commodity prices, or trade policy affecting Japanese wafer exports would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Flooded Member Detection Equipment Market
Detection and Regulation Devices
Digital Attenuators Market
Detection and Regulation Devices
Hydrogen Detection Transmitters Market
Detection and Regulation Devices
Photoionization Detectors Market
Detection and Regulation Devices
Digital Vacuum Regulators Market
Detection and Regulation Devices
Constant Current Regulator Market
Detection and Regulation Devices
Magnetic Crack Detectors Market
Detection and Regulation Devices
Hydrogen Leak Detector Market
Detection and Regulation Devices
Spark Detector Market
Detection and Regulation Devices
Ultra Low Dropout Regulator (LDO) Market
Detection and Regulation Devices
Smart Water Leak Detector Market
Detection and Regulation Devices
Semiconductor Inspection System Market
Detection and Regulation Devices
Gas Detectors Market
Detection and Regulation Devices
Antistatic Device for Ultrapure Water Market
Detection and Regulation Devices
Global Counterfeit Money Detection Market
Detection and Regulation Devices
Compliance Monitoring Devices Market