
 Wire Bonder Equipment Market | 2026-2036
Wire Bonder Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Wire Bonder Equipment Market Intelligence
The shift towards heterogeneous integration and chiplet architectures is rewriting the rules for semiconductor interconnects, demanding bonders with unprecedented precision. This evolution supports complex 3D stacking in advanced packaging. Kulicke & Soffa Industries leverages its R&D in fine-pitch bonding to serve this segment. Meanwhile, ASM Pacific Technology sustains its market position through a comprehensive portfolio targeting high-volume semiconductor fabricators.
Wire bonder equipment establishes electrical interconnections between a semiconductor die and its package substrate using fine wires, often made of gold or copper. These systems are critical in semiconductor packaging, forming the conductive pathways for power and data signals within an integrated circuit. While Ball Bonders command the largest share due to their speed in volume manufacturing, Wedge Bonders are indispensable for specialized power and RF devices. The semiconductor packaging application segment represents the core demand center.
Equipment manufacturers must comply with a matrix of international standards, including the EU's RoHS directive restricting hazardous substances and China's GB standards for machinery safety. Adherence to ISO 9001 quality management systems is a baseline requirement for suppliers targeting top-tier semiconductor fabricators. The critical decision for equipment buyers now revolves around balancing investment in current-generation thermosonic bonders against the adoption timeline for next-generation hybrid bonding technologies.
Market Dynamics
The central tension in the wire bonder market is the bifurcation of demand between high-volume, cost-sensitive applications served by legacy thermosonic bonders and the precision-driven requirements of advanced packaging, which pulls investment toward next-generation thermocompression and hybrid bonding technologies.
Growth Catalysts
- Advanced Packaging Architectures:The semiconductor industry's shift to heterogeneous integration and chiplet-based designs requires bonders with finer pitch and higher placement accuracy, directly stimulating demand for new equipment to build complex 3D and 2.5D packages.
- Geographic Concentration of Fabrication:Heavy capital investment in new semiconductor fabs and packaging facilities, particularly in Taiwan and South Korea, creates geographically concentrated demand pulses for entire fleets of new wire bonding equipment.
- Power and RF Device Proliferation:Expanding markets for electric vehicles and 5G infrastructure drive requirements for wedge bonders capable of handling larger diameter aluminum wires and ribbon for high-power and radio-frequency applications.
Market Restraints
- Alternative Interconnect Technologies:The increasing adoption of flip-chip and fan-out wafer-level packaging (FOWLP) for high-performance logic and mobile processors presents a direct substitution threat to wire bonding in certain high-value segments.
- Input Material Cost Volatility:Equipment performance is tied to wire material, and the high and volatile price of gold wire creates significant cost pressure on end-users, pushing them to qualify less expensive copper wire alternatives which require different machine parameters.
- Physical Scaling Limits:Traditional ball bonding faces fundamental physical limitations in pitch scaling, making it less suitable for next-generation devices requiring interconnect pitches below a certain micron threshold, thereby capping its addressable market in the most advanced nodes.
Strategic Opportunities
- System-in-Package for IoT:The proliferation of compact IoT and wearable devices creates a significant opportunity for bonders optimized for System-in-Package (SiP) modules, which integrate diverse components and often rely on fine-wire bonding for assembly.
- Hybrid Assembly Processes:There is a growing opportunity to position wire bonders as a complementary technology within hybrid assembly workflows, combining wire bonds with other interconnect methods like copper pillars to optimize cost and performance.
- Emerging Assembly Hubs:As semiconductor supply chains diversify, emerging assembly and test locations in Southeast Asia and India present new geographic markets for wire bonder equipment sales and support services.
Industry Challenges
- Advanced Process Control Skills:Operating and maintaining bonders for fine-pitch copper or thermocompression applications requires a higher level of technician skill and process engineering expertise, creating a talent bottleneck for many manufacturers.
- Capital Investment Cycles:The high capital expenditure required for state-of-the-art wire bonders, especially those with thermocompression capabilities, creates a significant investment hurdle and lengthens procurement decision cycles for semiconductor assemblers.
- Compliance with Regional Standards:Equipment makers face the challenge of ensuring their machines comply with a diverse array of regional regulations, including China's GB standards for machinery safety and the EU's CE marking requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wire Bonder Equipment Market |
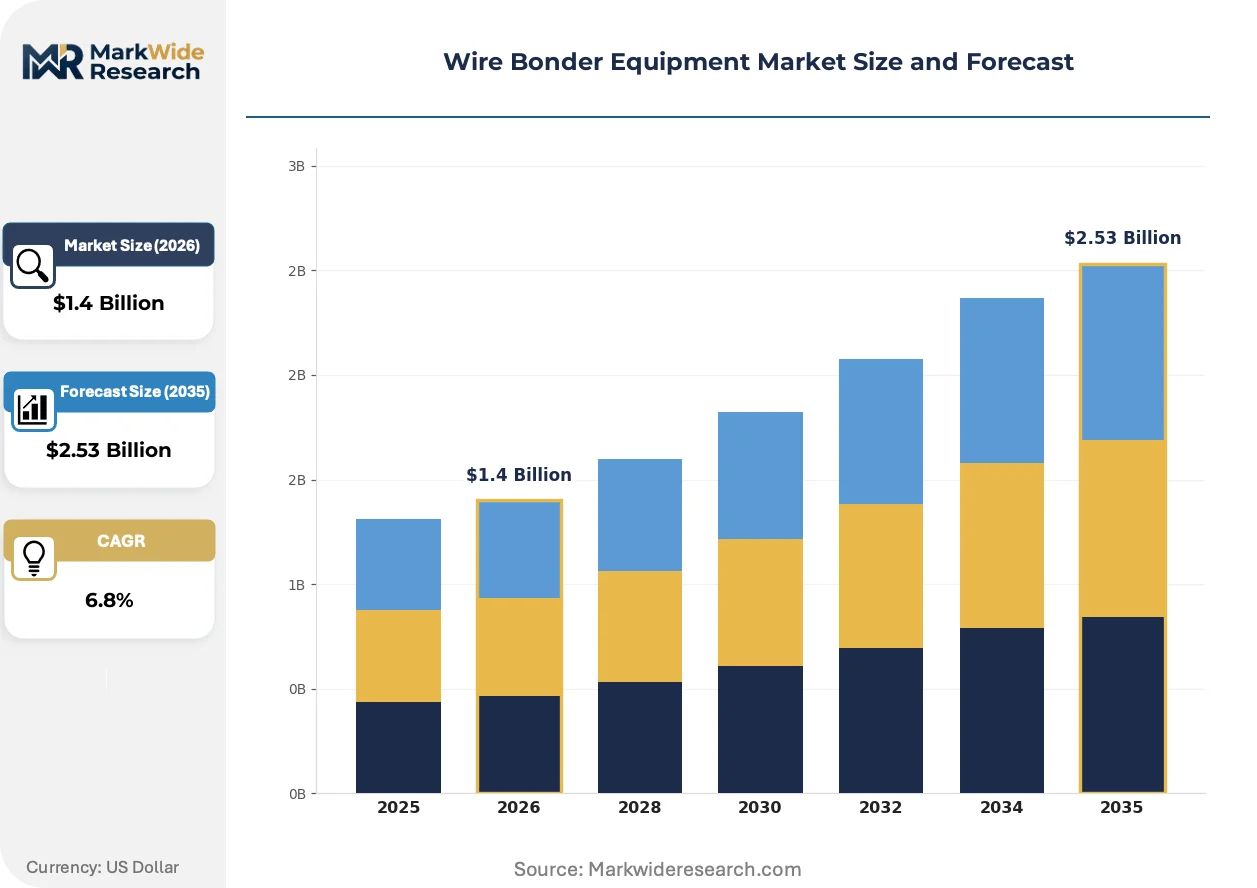
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermosonic Wire Bonder, Ultrasonic Wire Bonder, Ball Bonder, Wedge Bonder, Ribbon Bonder Technology: Capillary Bonding, Thermocompression Bonding, Wire Bonding, Laser Bonding, Punch Bonding Application: Consumer Electronics Assembly, Semiconductor Packaging, LED Manufacturing, MEMS Fabrication, Photonics Integration End User Industry: Semiconductor Fabricators, Electronics Manufacturing Services, MEMS Device Producers, LED Module Makers, Photonics Companies |
| Companies Covered | Kulicke & Soffa Industries, ASM Pacific Technology, BE Semiconductor Industries, Shinkawa Ltd, Palomar Technologies, Hesse Mechatronics, DIAS Automation, F&K Delvotec Bondtechnik, West Bond, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wire Bonder Equipment Market Strategic Shifts & Innovations
The market's trajectory is defined by a pivot from throughput-centric metrics to precision-focused capabilities. This evolution is a direct response to the increasing complexity of semiconductor packages, where interconnect reliability and density are paramount for device performance and yield.
Thermocompression bonding uses a combination of heat, force, and time to create fine-pitch interconnects without the kinetic energy of ultrasonic methods. Advanced packaging facilities serving the high-performance computing (HPC) and artificial intelligence sectors are rapidly adopting this process for 3D stacking. This technology is collapsing the gap between traditional wire bonding and direct die-to-wafer hybrid bonding, enabling new levels of interconnect density.
Material compliance regulations, led by the EU's RoHS directive, continue to influence equipment design and process qualification. These rules restrict hazardous substances, compelling a transition to lead-free materials and new wire alloys that require different bonding parameters. The power semiconductor segment is particularly impacted, as manufacturers must re-validate package reliability to meet stringent automotive and industrial quality standards with these new materials.
A notable shift in purchasing behavior is altering how equipment is evaluated by semiconductor manufacturers. Buyers increasingly prioritize total cost of ownership, focusing on metrics like yield, uptime, and process flexibility over raw units-per-hour speed. This change disrupts the traditional procurement model and favors suppliers whose machines offer superior process control and in-situ monitoring. This trend is most prominent among the leading outsourced semiconductor assembly and test (OSAT) firms based in Taiwan.
Wire Bonder Equipment Market Segmentation
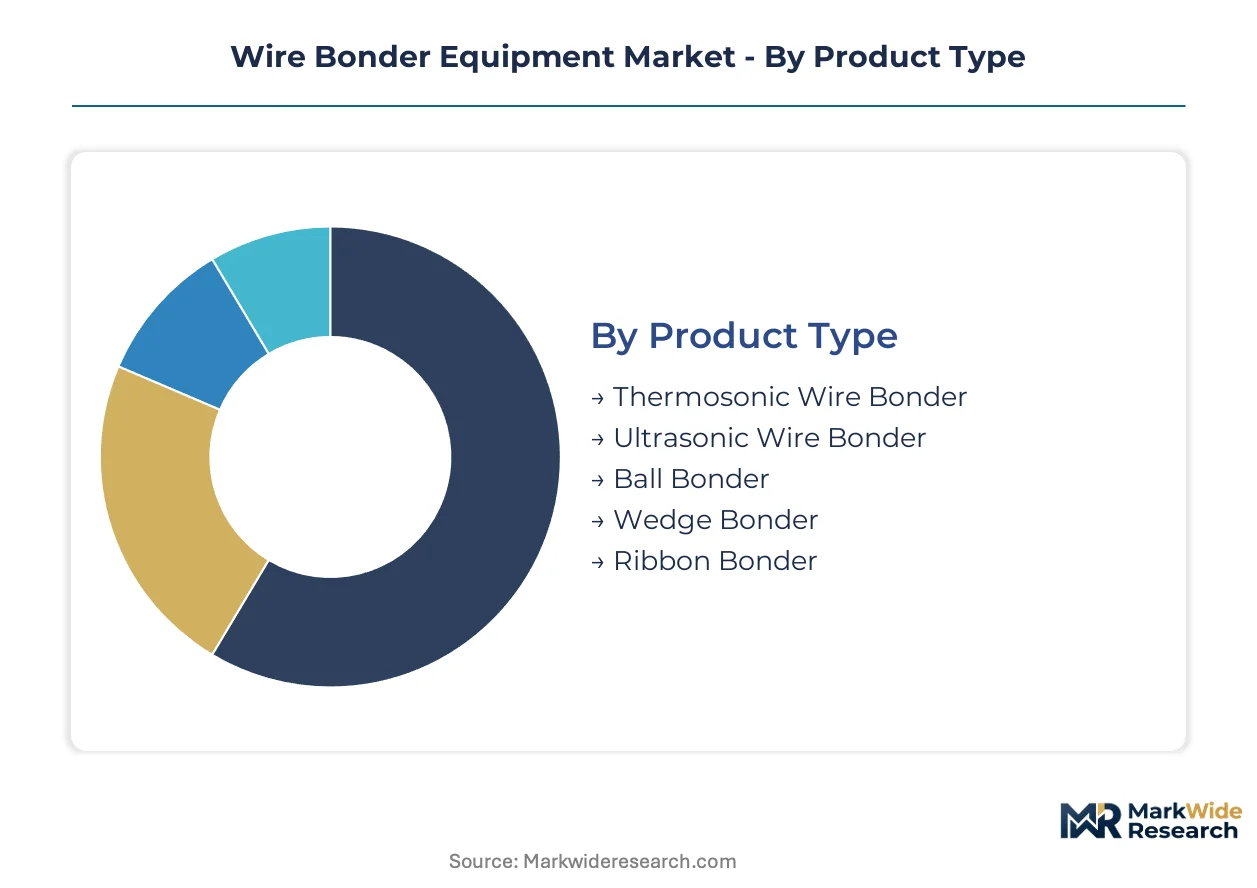
The wire bonder equipment market exhibits diverse requirements across its operational landscape. Understanding these distinct segments allows manufacturers to tailor solutions for specific performance needs. This segmentation highlights the varied technological approaches and application demands shaping the industry.
Product Type:
The product type segment spans both mature and rapidly evolving solutions for interconnect formation.
- Ball Bonder:Ball bonders form electrical connections using a ball of wire, typically gold or copper, melted at the wire tip. Demand concentrates in Taiwan for high-volume packaging lines, where their speed is critical for efficient production.
- Wedge Bonder:Wedge bonders utilize a wedge-shaped tool to create interconnections, often with aluminum or large diameter wires. South Korean automotive power module manufacturers rely on these for robust connections in high-power devices.
- Thermosonic Wire Bonder:These bonders combine heat, ultrasonic energy, and pressure for fine-pitch interconnections in advanced packages.
- Ultrasonic Wire Bonder:Ultrasonic bonders use high-frequency vibrations to create bonds without heat, suitable for sensitive components.
- Ribbon Bonder:Ribbon bonders utilize flat metallic ribbons instead of round wires for enhanced current carrying capacity in power electronics.
Ball Bonder handles the majority of throughput; Wedge Bonder is the fastest mover on share.
Technology:
Technology differentiation reflects the varied precision and material requirements across semiconductor manufacturing processes.
- Thermocompression Bonding:Thermocompression bonding applies heat and force to create fine-pitch interconnects without ultrasonic energy, ideal for advanced 3D stacking. High-performance computing applications in Japan increasingly adopt this technology for dense packaging.
- Wire Bonding:Wire bonding, a foundational interconnect technique, uses fine wires to connect a die to its package, ensuring electrical conductivity. Global outsourced semiconductor assembly and test (OSAT) firms utilize this for a broad range of integrated circuits.
- Capillary Bonding:This technique employs a heated capillary tool to form bonds, common in traditional wire bonding processes.
- Laser Bonding:Laser bonding uses focused laser energy for precise and localized interconnect formation, suitable for delicate substrates.
- Punch Bonding:Punch bonding creates electrical connections by mechanically deforming a wire onto a pad, used in specific niche applications.
Thermocompression Bonding offers superior density for next-generation devices, while Wire Bonding maintains its broad utility across the industry.
Application:
Application segments delineate the specific end-use environments driving equipment design and feature sets.
- Semiconductor Packaging:Semiconductor packaging involves enclosing integrated circuits in protective cases and establishing external connections. Demand from leading chipmakers in Taiwan drives innovation for higher density and reliability in advanced packages.
- Consumer Electronics Assembly:This segment encompasses the integration of wire-bonded components into devices like smartphones, wearables, and smart home products. Manufacturers in China prioritize cost-effective, high-throughput solutions for mass production.
- LED Manufacturing:LED manufacturing requires precise wire bonding for light-emitting diode chips, ensuring optical performance and longevity.
- MEMS Fabrication:MEMS fabrication uses wire bonding for connecting micro-electromechanical systems, critical for sensors and actuators.
- Photonics Integration:Photonics integration involves bonding optical and electrical components, crucial for high-speed data communication and sensing.
Semiconductor Packaging commands the largest share of equipment purchases, with Consumer Electronics Assembly expanding most quickly.
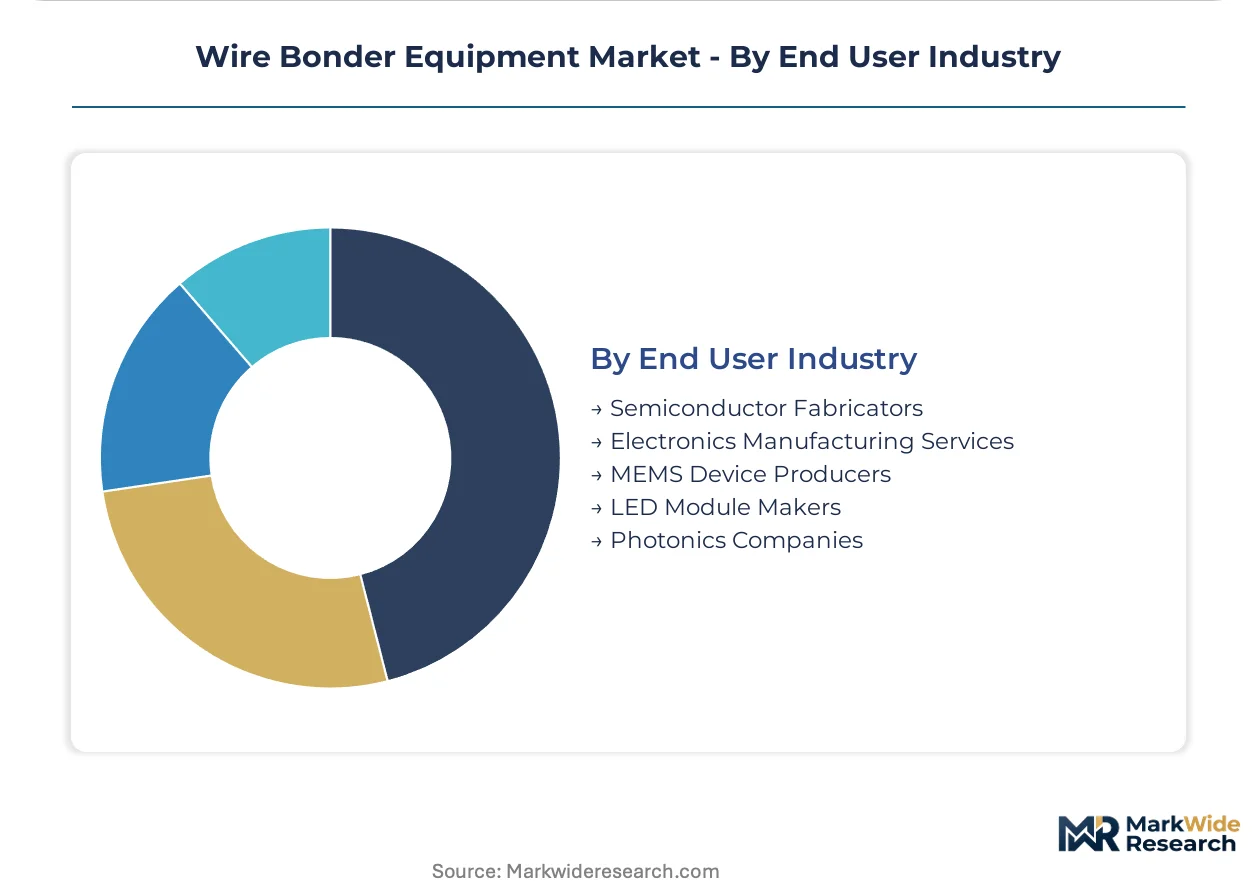
End User Industry:
End-user industries represent the primary purchasers and operators of wire bonder equipment, each with distinct operational scales.
- Semiconductor Fabricators:Semiconductor fabricators, including integrated device manufacturers (IDMs) and foundries, perform chip manufacturing and packaging in-house. Major investments by companies in the United States and Europe target advanced packaging capabilities.
- Electronics Manufacturing Services:Electronics Manufacturing Services (EMS) providers offer contract manufacturing for electronic components and assemblies to various industries. Vietnamese and Malaysian EMS firms seek versatile bonders for diverse product portfolios.
- MEMS Device Producers:These companies specialize in fabricating micro-electromechanical systems, requiring specialized bonding for tiny, intricate structures.
- LED Module Makers:LED module makers integrate individual LED chips into larger modules, relying on bonders for reliable electrical connections.
- Photonics Companies:Photonics companies develop and produce optical components and systems, utilizing wire bonders for optoelectronic integration.
Semiconductor Fabricators drive high-end equipment demand, while Electronics Manufacturing Services firms prioritize adaptable and cost-efficient solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration heavily influences the global wire bonder equipment market, with major semiconductor fabricators and outsourced assembly and test (OSAT) firms driving demand. These entities, primarily located in East Asia, require advanced machinery for high-volume production and complex packaging. The regional landscape reflects significant capital investment in new fabrication and assembly facilities.
Taiwan
Taiwanese semiconductor fabricators drive substantial demand for advanced wire bonder equipment, focusing on high-density interconnects for logic and memory devices. The country's Industrial Technology Research Institute (ITRI) supports R&D in advanced packaging technologies. Hsinchu Science Park remains a critical hub for semiconductor manufacturing and equipment procurement, influencing global technology trends.
South Korea
South Korean automotive power module manufacturers and memory producers require robust wire bonders for high-power and high-bandwidth applications. The Ministry of Trade, Industry and Energy (MOTIE) actively promotes domestic semiconductor equipment development. Key industrial clusters in Gyeonggi and Chungcheong provinces lead in advanced packaging and module assembly.
China
Chinese consumer electronics assembly firms prioritize cost-effective, high-throughput wire bonding solutions for mass production of devices like smartphones and IoT modules. China's GB standards for machinery safety dictate equipment design and compliance for market entry. Major manufacturing centers in the Yangtze River Delta and Pearl River Delta regions continually expand their assembly capabilities.
Japan
Japanese high-performance computing (HPC) and advanced packaging facilities increasingly adopt thermocompression bonding for 3D stacking and fine-pitch interconnections. The Ministry of Economy, Trade and Industry (METI) supports initiatives for next-generation semiconductor manufacturing. Industrial hubs in Kyushu and Tohoku regions are home to specialized equipment developers and advanced material suppliers.
United States
United States-based semiconductor fabricators and defense contractors demand high-precision wire bonders for specialized applications and advanced R&D. The CHIPS and Science Act provides significant incentives for domestic semiconductor manufacturing and packaging investments. Silicon Valley and the Arizona corridor are expanding their advanced packaging capabilities, requiring state-of-the-art bonding solutions.
Wire Bonder Equipment Market Key Industry Players
Channel-controlling players compete with product-specialist players across the wire bonder equipment market, defining a structure where scale and niche expertise both command value. The market exhibits a tiered consolidation, with a few large integrated providers dominating the high-volume segments and numerous specialized firms serving specific application needs. Strategic archetypes include global technology leaders, regional specialists, and emerging innovators. Dominant competitive moves involve continuous R&D investment in next-generation bonding technologies and strategic partnerships to expand market reach.
Global leaders in wire bonder equipment, such as Kulicke & Soffa Industries and ASM Pacific Technology, exemplify the comprehensive portfolio approach, serving a broad spectrum of semiconductor fabricators. These entities anchor the market through extensive R&D in fine-pitch bonding and advanced process control. BE Semiconductor Industries also occupies a significant position, particularly in areas requiring high precision and automation for advanced packaging solutions.
| Leading Market Players |
|---|
| Kulicke & Soffa Industries |
| ASM Pacific Technology |
| BE Semiconductor Industries |
| Shinkawa Ltd |
| Palomar Technologies |
| Hesse Mechatronics |
| DIAS Automation |
| F&K Delvotec Bondtechnik |
| West Bond |
| Others |
Cost & Logistics Intelligence
Hsinchu Science Park's advanced packaging capacity directly influences pricing power for high-density interconnect solutions. This concentration of fabrication and assembly facilities creates a competitive landscape that shapes equipment investment decisions and vendor negotiations.
Pricing Analysis
Cost-plus contract patterns, often indexed to key material costs like gold or copper wire, dominate the wire bonder equipment market. Pricing differentiates based on process capability, particularly for fine-pitch thermocompression bonders, and the scope of after-sales service bundles. Cost compression intensifies for standard thermosonic bonders due to high-volume manufacturing demands from outsourced semiconductor assembly and test (OSAT) firms. Semiconductor fabricators in the high-performance computing segment exhibit lower price sensitivity for advanced, precision-focused equipment.
Supply Chain Analysis
Extended payment terms and dedicated supply-chain finance facilities are common practices to manage the high capital expenditure of wire bonder equipment. Supply concentration for critical components primarily resides in Japan for specialized optics, Germany for precision mechanics, and the United States for advanced control systems. The supply chain relies heavily on ceramic capillaries, piezoelectric transducers, and fine gold/copper wire. Single-source vulnerability for highly specialized components represents a structural risk. Distribution typically operates through a direct sales model, augmented by regional technical support centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a fragmentation opportunity, driven by the shift towards heterogeneous integration and chiplet architectures creating specialized bonding niches.
For Market Incumbents:
Insulate core market share by deepening R&D investments in next-generation hybrid bonding technologies and securing key intellectual property. This move helps counter the substitution threat from alternative interconnect technologies like flip-chip. Leverage existing channel control in high-volume regions like Taiwan and South Korea to maintain strong customer relationships and service contracts.
For New Entrants and Emerging Players:
Establish a beachhead in specialized segments such as System-in-Package (SiP) modules for IoT devices or advanced hybrid assembly workflows. The most penetrable segment lies within emerging assembly hubs in Southeast Asia and India. A compelling go-to-market angle involves offering cost-effective, application-specific solutions tailored for these growing regional markets.
For Investors and Strategic Acquirers:
Mid-cycle technology positioning favors specialized firms with proven expertise in thermocompression bonding or advanced process control software. The long-term viability of advanced packaging ensures sustained demand for precision bonding solutions. A key signal to watch is the adoption rate of thermocompression bonders in new semiconductor fabrication and advanced packaging facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D in Hybrid Bonding | Develop next-generation hybrid bonding capabilities to meet demand for ultra-fine pitch interconnects. |
| Geographic Expansion | Establish sales and support networks in emerging assembly hubs like Southeast Asia and India. |
| Process Control Software Integration | Enhance machine learning-driven process control for higher yield and reduced technician skill requirements. |
| Material Qualification Partnerships | Collaborate with wire material suppliers to qualify new alloys for cost efficiency and compliance. |
| Customer Training Programs | Offer advanced training for fine-pitch copper and thermocompression bonding to address talent bottlenecks. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews, validated against extensive secondary research. Stakeholder roles included semiconductor packaging engineers, OSAT procurement managers, equipment R&D leads, and fab operations directors. Secondary data was sourced from semiconductor industry association reports, financial filings, trade publications, and academic research on advanced packaging, triangulating bottom-up and top-down perspectives.
The forecast framework calibrated market sizing and growth projections across the analysis window using tiered capacity modeling and technology adoption curves. Segmentation dimensions modeled included product type, technology, application (semiconductor packaging, consumer electronics), end-user industry, and interconnect density. Compound annual growth rates were derived through regression analysis, informed by expert consensus and key forecast inputs like semiconductor capital expenditure trends and advanced packaging roadmaps.
Stress conditions across geopolitical trade policies, raw material supply disruptions, and rapid shifts in alternative interconnect adoption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these assumptions. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
SMT Machine Market
Semiconductor Equipment
Global Semiconductor Stepper Systems Market
Semiconductor Equipment
Global Laser Dicing Systems Market
Semiconductor Equipment
Global Cleanroom Technologies Market
Semiconductor Equipment
Global Microelectronics Cleaning Equipment Market
Semiconductor Equipment
Global Atomic Layer Deposition (ALD) Equipment Market
Semiconductor Equipment
Lithography Systems Market
Semiconductor Equipment
Slide Processing System Market
Semiconductor Equipment
Vacuum Ovens Market
Semiconductor Equipment
Die Bonder Machinery Market
Semiconductor Equipment
Analog and Digital IC Development Tools Market
Semiconductor Equipment
Semiconductor Laser Equipment Market
Semiconductor Equipment
OLED Vacuum Evaporation Machine Market
Semiconductor Equipment
Underfill Dispenser Market
Semiconductor Equipment
Dicing Equipment Market
Semiconductor Equipment
Semiconductor Lithography Equipment Market