
 Photoresist for Semiconductor Market | 2026-2036
Photoresist for Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
Photoresist for Semiconductor Market Insights
Photoresist maintenance and technical service contracts is consolidating procurement power among foundries that now bundle chemistry with lithography uptime guarantees. JSR Corporation leverages its ArF and EUV formulation depth to anchor Japanese supply security for domestic fabs. Fujifilm sustains R&D intensity across polymer platforms that feed both legacy DUV and emerging high-NA EUV nodes. DuPont competes through geographic diversification of its photoresist manufacturing footprint across North American and Asian sites.
Photoresist for semiconductor denotes a light-sensitive polymer formulation—typically comprising a photoactive compound, resin binder, and solvent carrier—engineered to undergo solubility changes upon exposure to specific wavelengths from g-line through EUV, enabling sub-7nm pattern transfer onto silicon wafers. Its primary commercial purpose is to serve as the imaging layer that defines transistor and interconnect geometries during chip fabrication. EUV lithography represents the fastest-expanding technology segment as foundries transition from multi-patterning ArF to single-exposure EUV at 3nm and below, while positive photoresist maintains volume dominance across all nodes due to its superior resolution and process latitude. Anti-reflective coating commands disproportionate margin attention because stack complexity rises with each lithography generation.
Japan's METI coordinates domestic chemical supply chain resilience policies that directly affect photoresist export licensing and stockpile requirements. The EPA in the United States enforces PFAS reporting rules that capture fluorinated polymers used in some advanced photoresist formulations, pressuring reformulation timelines. REACH in Europe restricts candidate substance use in semiconductor chemicals, forcing qualification of alternative photoacid generators. Stakeholders must monitor which regulatory jurisdiction moves first on next-generation chemical hazard classification, as that will dictate reformulation investment sequencing across the supply base.
Market Dynamics
EUV lithography transition is compressing qualification timelines for photoresist suppliers as foundries demand single-exposure patterning at 3nm nodes. This wavelength shift from ArF immersion to 13.5nm EUV is forcing reformulation of photoacid generators and resin platforms across the supply base.
Growth Catalysts
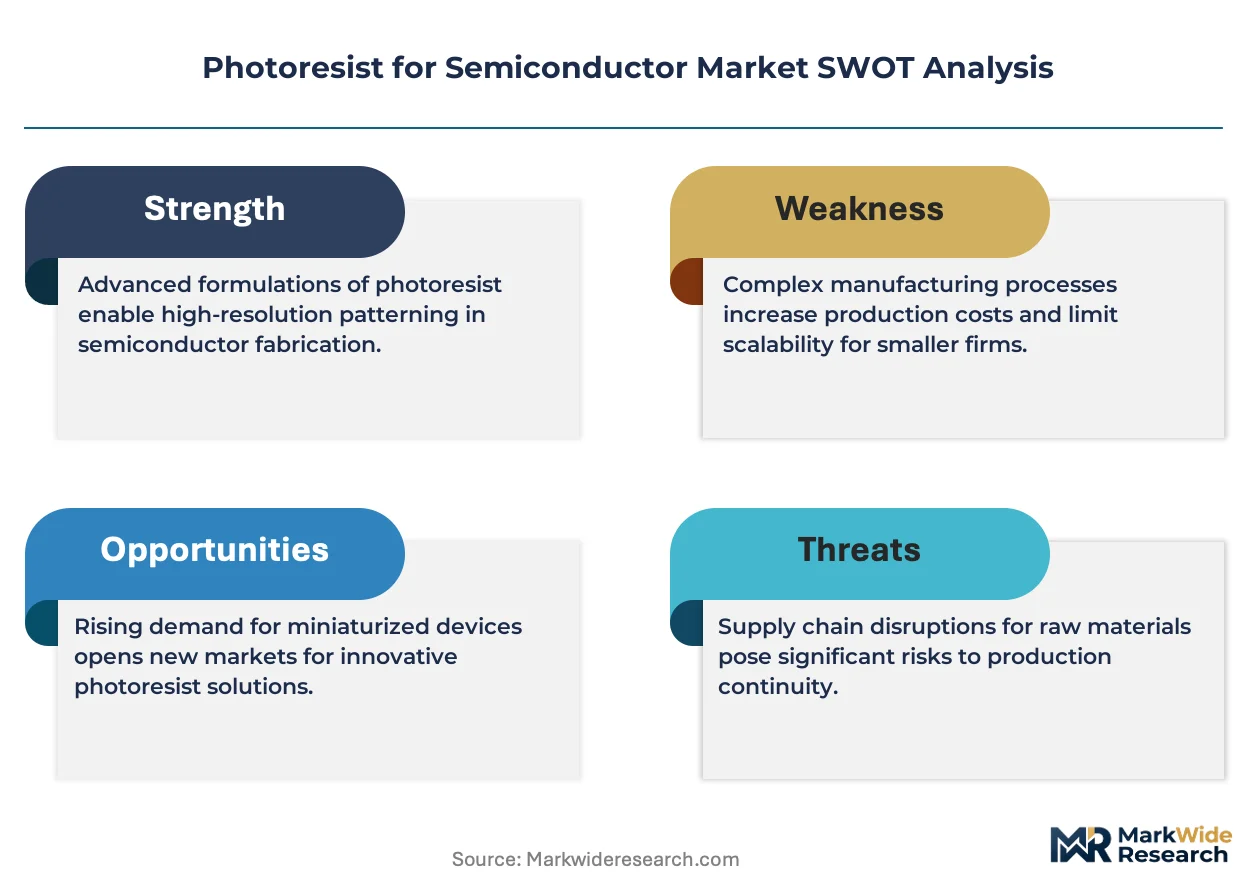
- High-NA EUV deployment:ASML's 0.55 numerical aperture systems require chemically amplified resists with tighter molecular weight distribution. Foundries in Taiwan and South Korea are qualifying these formulations for 2nm production ramps.
- CHIPS Act incentives:The United States is subsidizing domestic photoresist manufacturing capacity through direct grants and loan guarantees. New synthesis facilities in Arizona and Texas are breaking ground to serve regional fabs.
- Materials purity mandates:Semiconductor equipment manufacturers are imposing sub-ppb metal contamination specifications. This is pulling advanced filtration and purification equipment into photoresist production lines.
Market Restraints
- PFAS regulatory pressure:EPA reporting requirements for fluorinated polymers are capturing perfluorinated sulfonic acid photoacid generators used in EUV resists. Reformulation timelines extend 18-36 months for alternative acid generator qualification.
- Monomer supply concentration:Specialty cyclic olefin monomers for ArF and EUV resins originate from a narrow base of Japanese and Korean petrochemical producers. Geopolitical friction or plant outages transmit directly to photoresist output.
- EUV throughput limitations:Source power constraints and stochastic defect rates limit wafer-per-hour economics. This suppresses photoresist consumption velocity relative to DUV-era patterning intensity.
Strategic Opportunities
- India semiconductor manufacturing:The country's PLI scheme and semiconductor mission are attracting foundry investments in Gujarat and Karnataka. Photoresist suppliers can establish local blending and distribution operations ahead of volume ramp.
- Photoresist recycling:Spent solvent recovery and resin reclamation technologies are emerging as cost-reduction vectors. Environmental regulations in Europe are accelerating adoption of closed-loop manufacturing processes.
- Anti-reflective coating integration:Bottom and top anti-reflective layers are merging into single-stack formulations. This convergence reduces process steps and defects while capturing margin from combined material sales.
Industry Challenges
- EUV resist chemist scarcity:The intersection of polymer science, photochemistry, and lithography engineering commands premium compensation. Universities in Japan and the United States are struggling to graduate sufficient PhD talent.
- Customer-specific qualification:Each foundry node requires 12-24 month resist validation cycles. Duplicative testing across TSMC, Samsung, and Intel fabs consumes R&D resources without cross-leverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photoresist for Semiconductor Market |
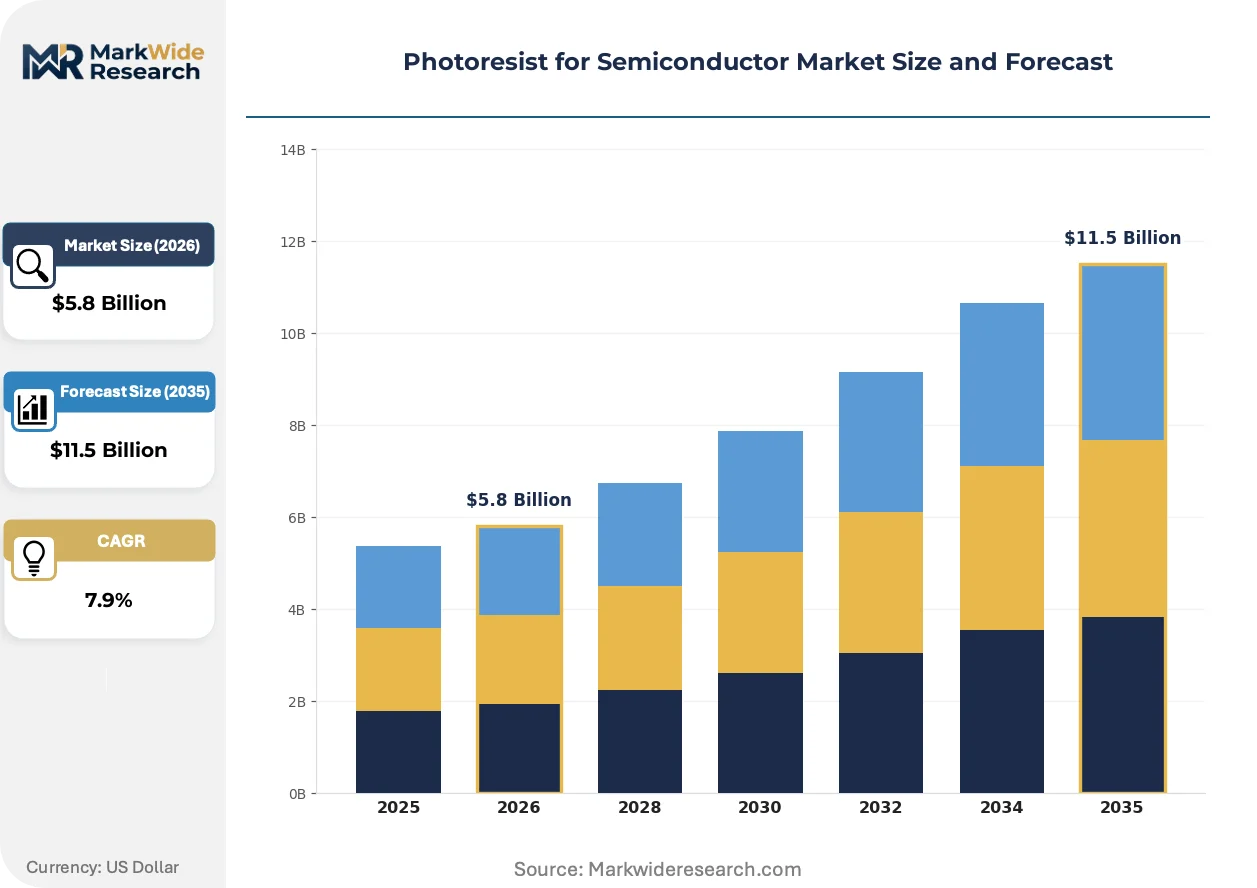
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.5 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Positive Photoresist, Negative Photoresist, Anti-reflective Coating, Speciality Photoresist Technology: UV Lithography, EUV Lithography, Nanoimprint Lithography, Immersion Lithography Form: Liquid Photoresist, Dry Film Photoresist, Spray Photoresist, Spin Coatable Photoresist Application: Integrated Circuits, MEMS Fabrication, Photovoltaics, Wafer Level Packaging |
| Companies Covered | TOKYO OHKA KOGYO CO., LTD., JSR Corporation, Fujifilm Corporation, Shin-Etsu Chemical Co., Ltd., DuPont, Sumitomo Chemical Co., Ltd., Merck KGaA, Dongjin Semichem, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photoresist for Semiconductor Market Trends and Innovations
Photoresist technology is fragmenting across wavelength-specific platforms while process integration demands unify previously separate material layers. Suppliers must simultaneously advance molecular precision and simplify customer process flows.
Metal oxide resists are unifying the functions of imaging and etch hardmask into a single layer. These formulations incorporate tin-oxide nanoparticles that absorb EUV photons efficiently while providing plasma etch resistance. Intel and Samsung are accelerating qualification timelines for 2nm node insertion. This unification eliminates separate spin-on carbon hardmask deposition, compressing cost-per-layer for critical levels.
REACH candidate substance restrictions are forcing substitution of triphenylsulfonium photoacid generators across European-qualified supply chains. ECHA's 2023-2024 SVHC additions captured several fluorinated sulfonate salts used in advanced formulations. German and Dutch chemical suppliers are reformulating with non-fluorinated acid generators and alternative counterions. This regulatory pressure is propagating to Asian formulation plants serving European-owned fabs.
Foundry technical service contracts now bundle photoresist supply with lithography cluster uptime guarantees. TSMC and Samsung are requiring suppliers to station on-site process engineers at leading-edge facilities. This service integration displaces traditional arm's-length chemical procurement with performance-based partnerships. The model is most advanced in Taiwan's Tainan Science Park and South Korea's Pyeongtaek semiconductor cluster.
Photoresist for Semiconductor Market Segmentation
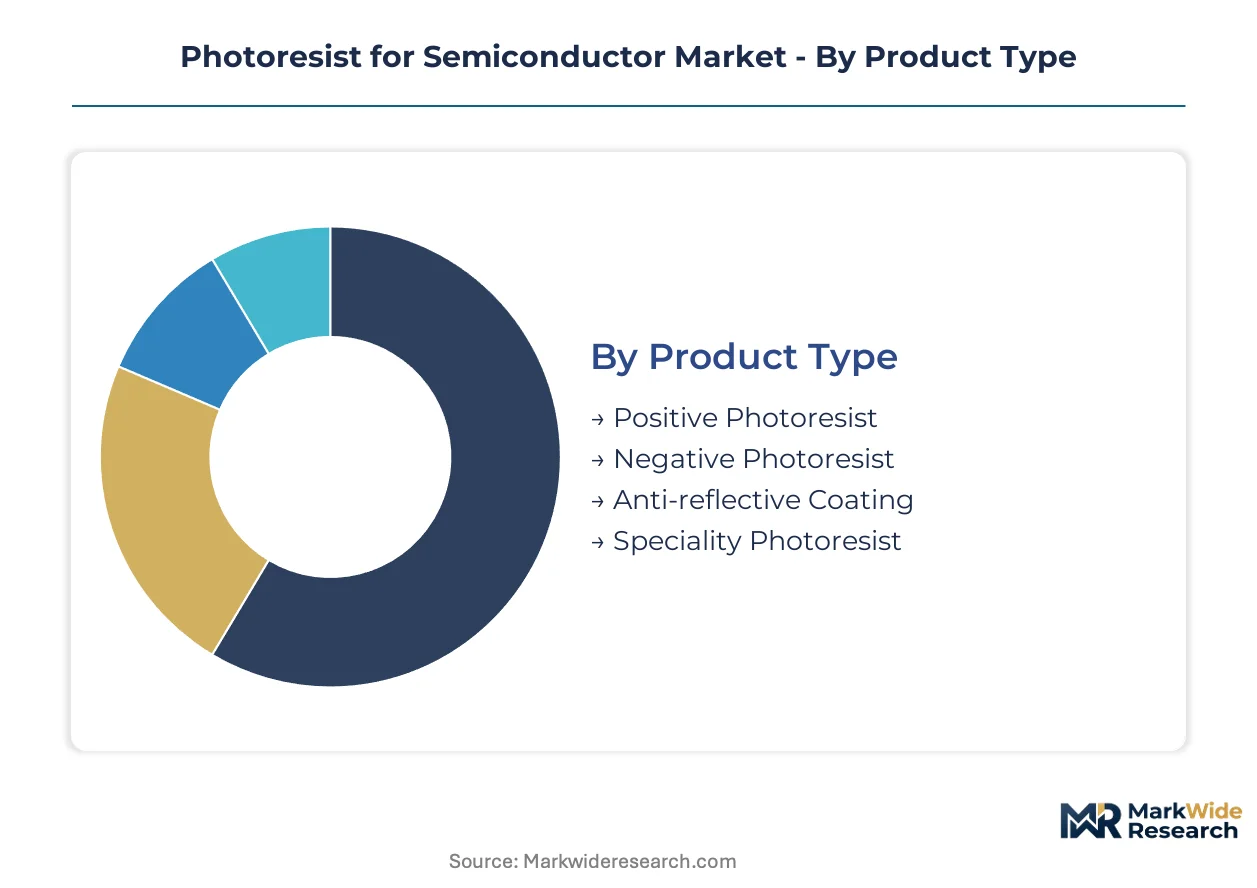
Photoresist segmentation reflects the tension between wavelength-specific chemistry requirements and the unifying pressure of process simplification. Each category captures a different axis of technical differentiation that suppliers must navigate simultaneously.
Product Type:
Positive photoresist dominates standalone patterning applications where dissolution contrast drives resolution, while negative formulations embed more naturally into permanent structural layers.
- Positive Photoresist:Chemically amplified formulations undergo deprotection reactions upon acid catalysis, creating sharp solubility contrast for sub-10nm features. Taiwan's Hsinchu Science Park fabs consume the highest volumes as TSMC ramps 3nm EUV production. The segment benefits from decades of process optimization but faces reformulation pressure from PFAS-related photoacid generator restrictions.
- Anti-reflective Coating:Bottom and top layers control thin-film interference and standing wave effects through tuned refractive indices and extinction coefficients. Samsung's Pyeongtaek complex qualifies these materials for high-NA EUV stacks where reflectivity control determines pattern fidelity. Margin capture here exceeds commodity photoresist due to stack complexity multiplication at each node shrink.
- Negative Photoresist:Crosslinking chemistry suits permanent structures in MEMS and advanced packaging where the patterned polymer remains functional.
- Speciality Photoresist:Formulations address niche applications including lift-off processing and thick-film MEMS patterning.
Volume placements concentrate in Positive Photoresist; the faster expansion belongs to Anti-reflective Coating.
Technology:
Cost tiers separate established DUV infrastructure from the capital-intensive EUV transition, with nanoimprint occupying a distinct economic position for non-semiconductor patterning.
- EUV Lithography:13.5nm wavelength systems demand entirely new resist platforms with metal oxide or chemically amplified chemistry optimized for photon absorption efficiency. South Korea's semiconductor clusters are qualifying these materials for 2nm production ahead of high-NA tool installation. Stochastic defect control remains the binding constraint on throughput economics.
- UV Lithography:G-line, I-line, and DUV systems continue serving mature nodes and power semiconductor fabrication where feature sizes exceed 90nm. Japanese foundries maintain significant installed base here, consuming legacy resist formulations with established supply chains and pricing structures.
- Immersion Lithography:ArF water-immersion systems bridge the gap between DUV and EUV for 7-14nm nodes using multiple patterning.
- Nanoimprint Lithography:Mechanical patterning offers cost advantages for photonics and storage applications where throughput requirements differ from leading-edge logic.
Capital deployment favors EUV Lithography; the steepest expansion trajectory runs through Immersion Lithography as multi-patterning extends tool lifecycles.
Form:
Application requirements dictate form selection, with liquid systems dominating precision patterning and dry film addressing throughput-sensitive packaging operations.
- Spin Coatable Photoresist:Centrifugal deposition achieves sub-nanometer thickness uniformity across 300mm wafers, essential for critical level patterning at advanced nodes. Arizona's emerging fab cluster is qualifying these materials for domestic supply chain resilience under CHIPS Act incentives. The form factor commands premium pricing tied to filtration and metal contamination specifications.
- Liquid Photoresist:Bulk dispense systems serve high-volume manufacturing where continuous coating operations minimize waste.
- Dry Film Photoresist:Lamination-based application suits wafer-level packaging and PCB-like processing where speed outweighs resolution requirements.
- Spray Photoresist:Aerosol deposition enables conformal coating on non-planar topographies for MEMS and 3D integration schemes.
Revenue concentration sits with Spin Coatable Photoresist; the fastest share gain is occurring in Dry Film Photoresist as advanced packaging volumes multiply.
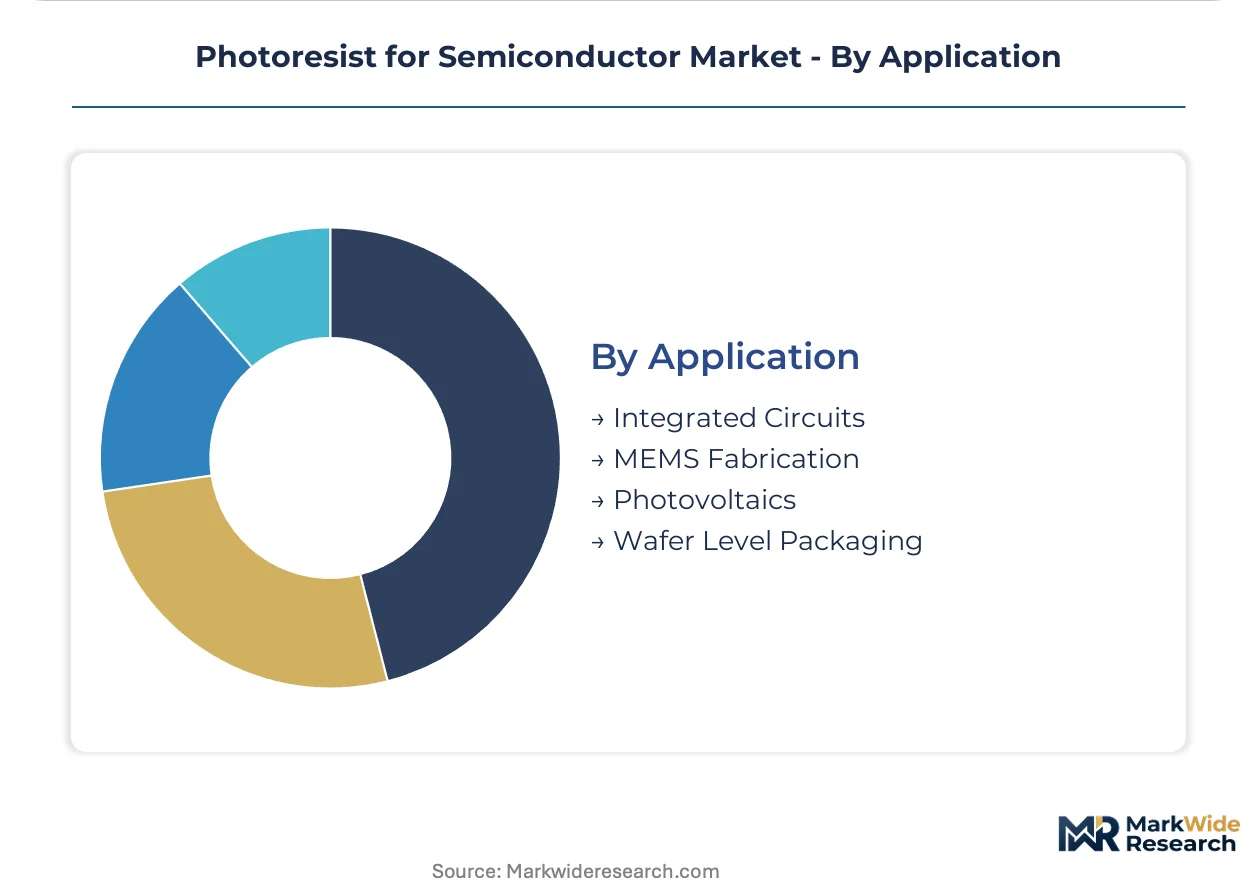
Application:
Customer maturity varies sharply, with integrated circuit fabs driving qualification intensity and photovoltaics presenting volume opportunities with relaxed specification requirements.
- Integrated Circuits:Logic and memory fabrication imposes the most stringent purity, uniformity, and defectivity standards across all photoresist categories. Taiwan and South Korea foundries specify sub-ppb metal contamination and lot-to-lot consistency for EUV layers. The application absorbs the majority of R&D investment and technical service resources.
- MEMS Fabrication:Microelectromechanical systems require thick-film patterning capabilities and etch resistance for structural silicon processing.
- Wafer Level Packaging:Redistribution layers and through-silicon vias consume resists optimized for copper plating compatibility and dielectric properties.
- Photovoltaics:Solar cell metallization patterning uses lower-cost formulations where linewidth requirements permit relaxed process windows.
Technical service intensity peaks in Integrated Circuits; the broadest volume base resides in Photovoltaics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian chemical clusters while consumption spreads across foundry hubs in Taiwan, South Korea, and the United States. This geographic split creates supply chain exposure that regional diversification policies seek to address.
United States
CHIPS Act subsidies are accelerating photoresist manufacturing investments in Arizona and Texas to serve domestic fabs. EPA PFAS reporting requirements are pressuring reformulation timelines for fluorinated photoacid generators. Intel's Oregon and Arizona facilities are qualifying new resist formulations under compressed validation cycles.
Japan
METI coordinates domestic supply chain resilience policies affecting export licensing and strategic stockpile requirements. The country's chemical producers maintain deep formulation expertise across ArF and EUV platforms. Kyushu and Kanto regions host concentrated synthesis capacity serving global foundry demand.
Taiwan
TSMC's 3nm EUV ramp is driving the fastest procurement velocity for chemically amplified resists and anti-reflective coatings. The island's national semiconductor strategy prioritizes material supply security alongside equipment access. Hsinchu Science Park fabs specify sub-ppb metal contamination standards that filter supplier eligibility.
South Korea
Samsung and SK Hynix are qualifying high-NA EUV resist formulations ahead of 2nm production timelines. The government's K-Semiconductor Belt initiative subsidizes domestic material ecosystem development. Pyeongtaek and Yongin clusters are absorbing technical service engineers from major suppliers under bundled uptime contracts.
Germany
REACH candidate substance restrictions are forcing substitution of triphenylsulfonium photoacid generators across European-qualified supply chains. ECHA's SVHC additions propagate reformulation requirements to Asian plants serving European-owned fabs. Dresden's Silicon Saxony cluster hosts advanced lithography research bridging chemistry and equipment integration.
Photoresist for Semiconductor Market Competitive Landscape
Top-tier vendors anchor the premium formulation segment, while mid-scale specialists occupy niche wavelength categories. The market structure reflects decades of accumulated polymer science expertise concentrated in Japanese and Korean chemical conglomerates. Two strategic archetypes dominate: integrated material-science conglomerates with captive resin synthesis, and lithography-focused specialists with deep foundry relationships. Competitive moves center on geographic manufacturing diversification and technical service integration with lithography cluster uptime guarantees.
Among Japan-based chemical groups, TOKYO OHKA KOGYO CO., LTD. and JSR Corporation exemplify the integrated conglomerate archetype with spanning formulation depth. Fujifilm Corporation occupies a distinct position sustaining R&D intensity across multiple polymer platforms. These three represent the supply security anchors that Taiwan and South Korean foundries rely upon for leading-edge node qualification.
| Leading Market Players |
|---|
| TOKYO OHKA KOGYO CO., LTD. |
| JSR Corporation |
| Fujifilm Corporation |
| Shin-Etsu Chemical Co., Ltd. |
| DuPont |
| Sumitomo Chemical Co., Ltd. |
| Merck KGaA |
| Dongjin Semichem |
| BASF SE |
| Others |
Pricing and Supply Chain Analysis
Cyclic olefin monomer costs transmit directly through EUV photoresist pricing tiers, with Japanese and Korean petrochemical feedstock premiums filtering into foundry contract negotiations. Specialty resin purification requirements compound this input pressure, separating premium-grade formulations from commodity DUV alternatives.
Pricing Analysis
Price erosion across legacy DUV formulations traces to foundry consolidation of procurement into bundled lithography uptime contracts. Three-tier pricing structure across premium, standard, and economy levels reflects metal contamination grade and qualification status with named foundries. TSMC and Samsung command the steepest cost-down pressure through volume commitments, while Indian and Southeast Asian packaging houses show highest price sensitivity due to thinner margin structures. Customization for customer-specific node qualification sustains premium capture at the top tier.
Supply Chain Analysis
Specialized EUV resist chemist scarcity in Japan and South Korea constrains synthesis capacity expansion despite foundry demand acceleration. Manufacturing concentrates in Japan's Kyushu and Kanto chemical corridors, with secondary blending operations in Taiwan's Hsinchu Science Park and South Korea's Pyeongtaek cluster. The supply chain draws from fluorinated photoacid generator precursors subject to EPA reporting requirements and high-purity solvent feeds. Single-source vulnerability permeates specialty monomer streams. Distribution runs through direct technical service partnerships rather than arm's-length chemical distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EUV resist synthesis capacity bottlenecks prop pricing power for qualified suppliers, with foundry bundling contracts locking in multi-year offtake commitments ahead of high-NA tool deployment.
For Market Incumbents: Hedge against PFAS regulatory exposure by accelerating non-fluorinated photoacid generator qualification timelines and securing alternative monomer supply agreements with Korean petrochemical producers. Backward integration into captive resin synthesis insulates margin pressure from feedstock volatility. METI export licensing requirements favor domestic Japanese capacity expansion. For New Entrants and Emerging Players: Regional blending facilities in Gujarat and Karnataka offer the most penetrable entry vector ahead of India's semiconductor manufacturing ramp. Photoresist recycling technology partnerships with European equipment vendors provide differentiated positioning against incumbent chemistries. Technical service contracts bundling uptime guarantees represent the essential go-to-market mechanism. For Investors and Strategic Acquirers: Intel's accelerated Arizona qualification timelines for metal oxide resists is the leading indicator that high-NA EUV chemistry platforms will command scarcity premia through the mid-2030s. Acquisition targets center on mid-scale Japanese formulation houses with dormant EUV R&D pipelines and existing foundry relationships. The signal to monitor is ECHA SVHC list expansion capturing additional fluorinated sulfonate salts.| Strategic Initiative | Industry Significance |
|---|---|
| High-NA EUV Resist Qualification | ASML's 0.55 NA systems require reformulated molecular weight distributions for 2nm production. |
| Domestic Synthesis Capacity Buildout | CHIPS Act grants in Arizona and Texas reduce reliance on Japanese chemical imports. |
| Non-Fluorinated PAG Development | REACH SVHC restrictions force substitution of triphenylsulfonium generators across European supply chains. |
| Technical Service Integration | TSMC and Samsung bundle on-site process engineers with material procurement contracts. |
| Photoresist Recycling Partnerships | Closed-loop solvent recovery addresses European environmental compliance cost pressures. |
Research Methodology
SEC 10-K filings, ECHA regulatory submissions, and foundry capex disclosures formed the secondary backbone, cross-referenced against primary interviews with photoresist R&D directors, foundry procurement leads, lithography equipment specialists, and specialty chemical distribution managers. Bottom-up triangulation across formulation volumes and top-down validation against wafer start projections ensured consistency. Primary fieldwork captured customer-specific qualification timelines and bundled service contract structures.
Historical trendline analysis of ArF-to-EUV transition patterns informed projection modeling across the analysis window. Segmentation dimensions included lithography technology node, resist chemistry platform, application layer criticality, and regional foundry cluster. CAGRs derived from wafer demand elasticity and resist consumption intensity per critical layer. Industry-specific inputs incorporated ASML tool shipment schedules and METI strategic stockpile policy adjustments.
Several conditions sit outside the modeled scope, including unanticipated EPA PFAS rulemakings, geopolitical disruption to Japanese monomer supply, and foundry node transition delays. Forecasts reflect assumptions about high-NA EUV adoption velocity and alternative patterning technology displacement. Material deviation in stochastic defect rate improvements or photoacid generator regulatory reclassification warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Global Sputtering Equipment Market
Semiconductor Equipment
Electrolytic Etching Machine Market
Semiconductor Equipment
Global Tamping Machine Market
Semiconductor Equipment
Laser Micro Perforation Equipment Market
Semiconductor Equipment
Semiconductor LPCVD Furnaces Market
Semiconductor Equipment
Global Semiconductor Etch Equipment Market
Semiconductor Equipment
Wire Bonder Equipment Market
Semiconductor Equipment
Partition Inserter Machines Market
Semiconductor Equipment
Global Semiconductor Stepper Systems Market
Semiconductor Equipment
Selective Soldering Equipment Market
Semiconductor Equipment
Global Equipment Front End Module (EFEM) Market
Semiconductor Equipment
Wafer Processing Equipment Market
Semiconductor Equipment
FOUP Load Port Market
Semiconductor Equipment
Photolithography Equipment Market
Semiconductor Equipment
I-Line Lithography Market
Semiconductor Equipment
X-Ray Lithography Equipment Market