
 Pulse Tube and Gifford-Mcmahon Cryocoolers Market | 2026-2036
Pulse Tube and Gifford-Mcmahon Cryocoolers Market Size, Share, and Industry Trends Forecast 2026-2036
Pulse Tube and Gifford-Mcmahon Cryocoolers Market Insights
Stirling-to-pulse tube technology migration is tilting procurement criteria toward oil-free, low-vibration cooling platforms for quantum computing testbeds. Sumitomo Heavy Industries leverages its regenerator material science portfolio to dominate superconducting magnet installations. Thales Group anchors European defense infrared programs through captive linear motor cryocooler production. Cryomech sustains North American research laboratory relationships via specialized dilution refrigerator integration.
Pulse tube and Gifford-McMahon cryocoolers are closed-cycle mechanical refrigerators that achieve temperatures below 10 Kelvin through oscillating helium gas expansion in regenerative heat exchangers, with pulse tube variants eliminating displacer mechanisms to reduce vibration below 0.1 micron. These systems primarily enable superconducting device operation, infrared sensor cooling, and cryogenic gas liquefaction in precision manufacturing environments. Gifford-McMahon cryocoolers occupy mature, high-reliability niches in medical MRI infrastructure where maintenance access favors field-serviceable designs. Pulse tube architectures represent the fastest-growing product category as semiconductor fabrication adopts vibration-sensitive extreme ultraviolet lithography stages. Aerospace and defense end-user industries concentrate margin pools in long-term service contracts for satellite-borne infrared sensor cooling.
ISO 14644 cleanroom standards and China's GB/T 16292 particulate limits constrain cryocooler lubricant outgassing specifications in electronics manufacturing facilities. The US EPA's phasedown of virgin helium production under the Helium Stewardship Act is accelerating closed-cycle recovery system adoption across research laboratories. Japan's METI energy efficiency benchmarks for cryogenic equipment are tightening compressor power density requirements. Stakeholders must monitor regenerator matrix material sourcing as rare-earth powder supply chains face export licensing pressures from multiple producing jurisdictions.
Market Dynamics
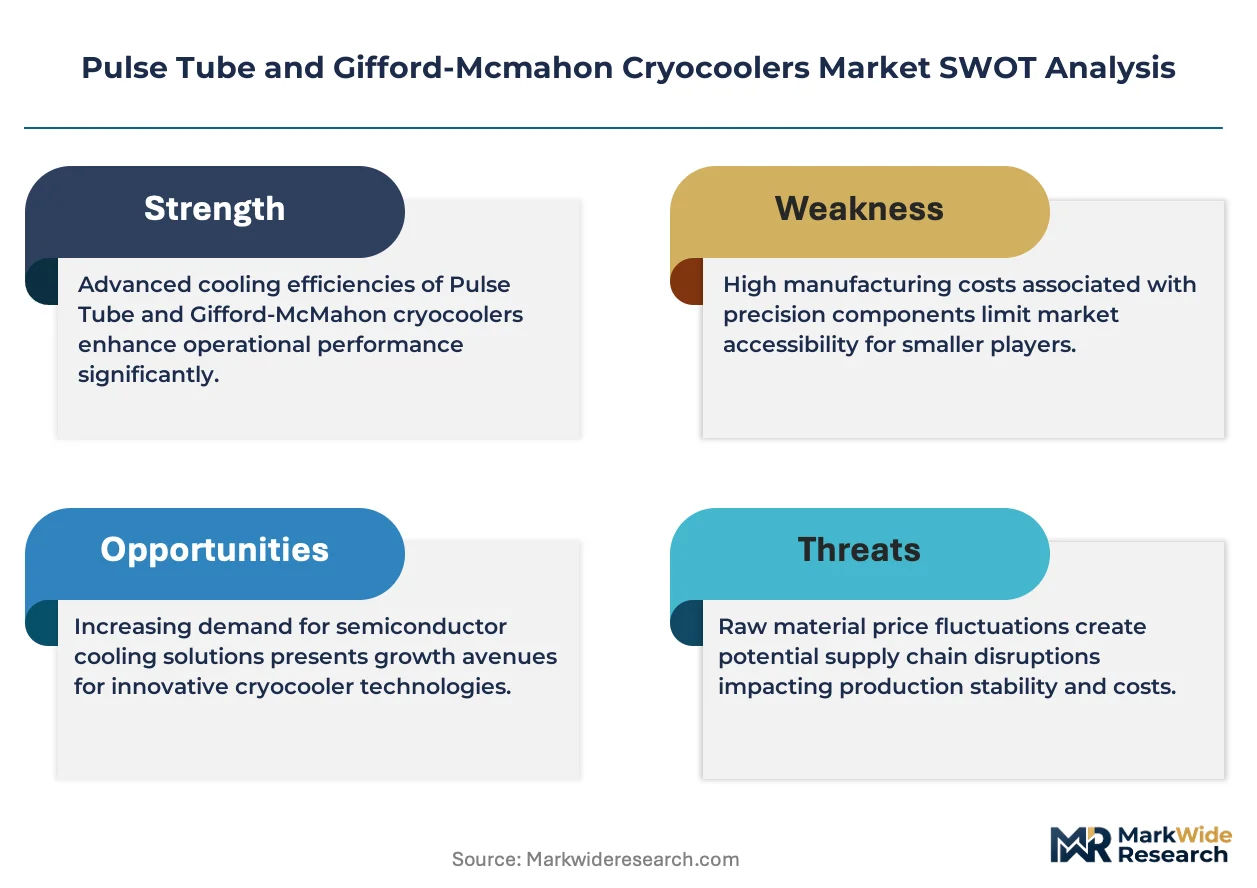
Magnetic bearing technology is rendering conventional gas-bearing systems obsolete in next-generation pulse tube designs, compressing maintenance intervals and enabling semiconductor lithography stages to achieve sub-nanometer positioning stability.
Growth Catalysts
- ISO 14644 Cleanroom Mandates:Semiconductor fabrication facilities in East Asia are scaling helium-free cooling architectures to eliminate lubricant outgassing contamination. This regulatory pressure accelerates pulse tube adoption over oil-lubricated Gifford-McMahon alternatives.
- Quantum Computing Testbed Expansion:Stirling-to-pulse tube technology migration is tilting procurement criteria toward oil-free, low-vibration cooling platforms. Research laboratories prioritize systems delivering vibration below 0.1 micron for superconducting qubit stability.
- Rare-Earth Regenerator Materials:Advanced regenerator matrix formulations using gadolinium-silicon-germanium alloys are improving coefficient of performance. China's Yangtze River Delta is expanding domestic cryocooler assembly capacity to capture this materials-science advantage.
Market Restraints
- Helium Supply Concentration:The US EPA's phasedown of virgin helium production under the Helium Stewardship Act is constraining closed-cycle system feedstock availability. Research laboratories face extended lead times for high-purity helium procurement.
- Magnetic Bearing Cost Structure:Active magnetic bearing assemblies require precision-machined rare-earth permanent magnets and position sensors. Input cost volatility in neodymium-dysprosium supply chains compresses margin pools for mid-tier manufacturers.
- Gifford-McMahon Technical Ceiling:Displacer mechanism wear limits mean-time-between-failures to approximately 10,000 hours in medical MRI infrastructure. This technical limitation prevents penetration into satellite-borne infrared sensor applications demanding 50,000+ hour lifetimes.
Strategic Opportunities
- European Defense Infrared Programs:Captive linear motor cryocooler production is securing long-term service contracts for satellite thermal management. Thales Group's manufacturing footprint creates template for sovereign supply chain replication.
- Japan METI Efficiency Benchmarks:Tightening compressor power density requirements are accelerating variable-speed drive adoption. Domestic manufacturers can capture regulatory tailwind by integrating permanent magnet synchronous motors with pulse tube cold heads.
- Dilution Refrigerator Integration:Specialized sub-Kelvin cooling platforms for quantum computing are converging with pulse tube pre-cooling stages. Cryomech's research laboratory relationships demonstrate channel architecture for this technology convergence.
Industry Challenges
- Cryogenic Welding Certification:ASME Section VIII and ISO 20485 qualification timelines extend 18-24 months for custom heat exchanger fabrications. Manufacturers face execution risk in scaling production for extreme ultraviolet lithography deployment schedules.
- Regenerator Matrix Sourcing:Rare-earth powder supply chains face export licensing pressures from multiple producing jurisdictions. Procurement teams must qualify secondary suppliers for spherical stainless steel mesh and lead-based alloys.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pulse Tube and Gifford-Mcmahon Cryocoolers Market |
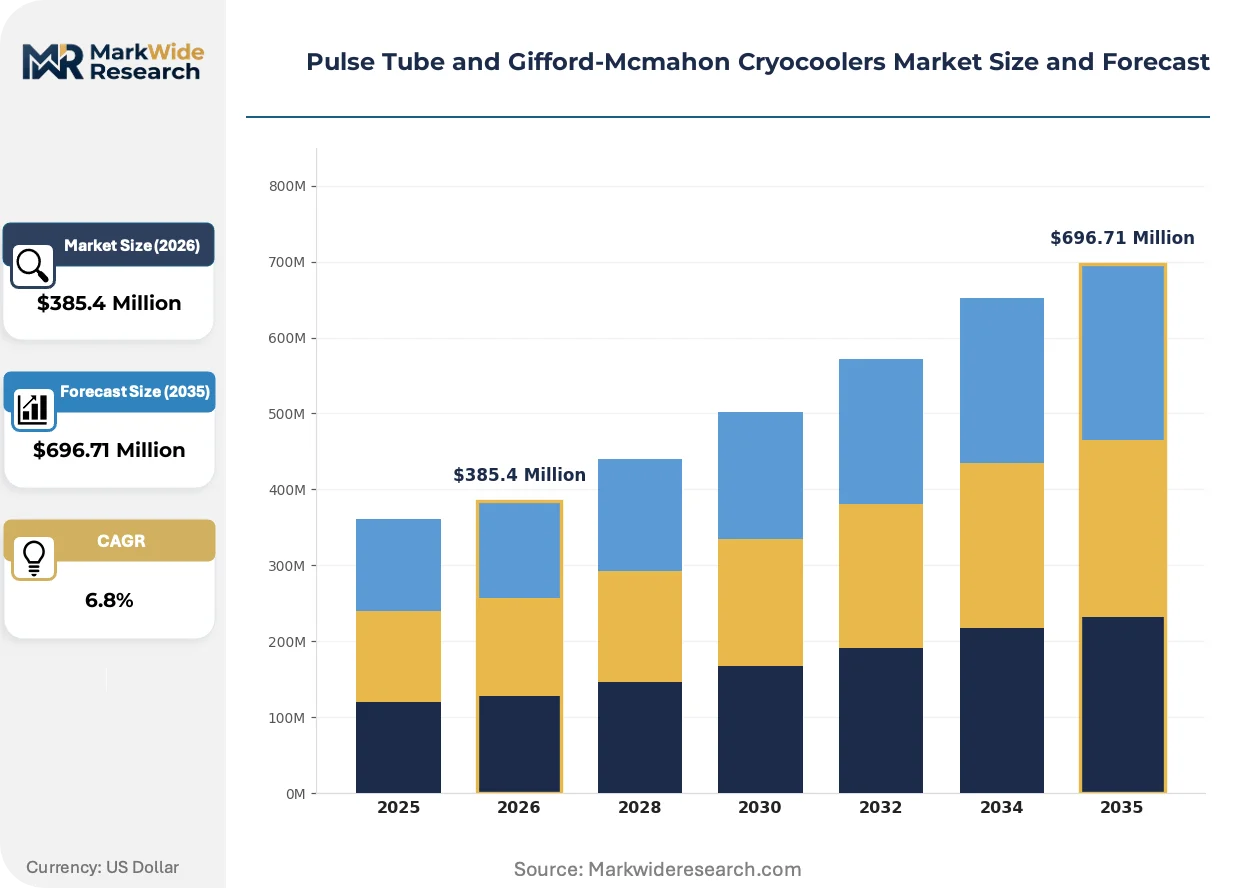
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pulse Tube Cryocoolers, Gifford-McMahon Cryocoolers, Stirling Cryocoolers, Joule-Thomson Cryocoolers, Hybrid Cryocoolers Application: Space Simulation, Infrared Sensors, Superconducting Devices, Liquefaction of Gases, Particle Accelerators End User Industry: Aerospace & Defense, Research Laboratories, Electronics Manufacturing, Medical Imaging, Semiconductor Fabrication Technology: Pulsating Flow, Reciprocating Compressor, Linear Motor, Regenerative Heat Exchange, Magnetic Bearing |
| Companies Covered | Sumitomo Heavy Industries, Thales Group, ULVAC Cryogenics, Cryomech (Bluefors), Edwards Vacuum, CSSC Pride Cryogenics, Advanced Research Systems, Lihan Cryogenics, Zhejiang Bwokai Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pulse Tube and Gifford-Mcmahon Cryocoolers Market Trends and Innovations
Active magnetic bearing systems are compressing vibration signatures below thresholds required for sub-10 nanometer semiconductor patterning, while regulatory pressure on helium stewardship reshapes closed-cycle architecture economics.
Magnetic bearing technology replaces mechanical contact points with electromagnetic levitation in pulse tube cryocooler compressors. Semiconductor equipment manufacturers in Taiwan and South Korea are specifying these systems for extreme ultraviolet lithography vacuum chambers. This adoption is rendering obsolete gas-bearing compressors that require 500-hour maintenance intervals and introduce particulate contamination risks.
The US EPA's Helium Stewardship Act mandates phased reduction in federal helium reserve sales, compressing virgin helium availability for open-cycle cooling systems. Research institutions and aerospace contractors are responding by retrofitting recovery and reliquefaction infrastructure. Closed-cycle pulse tube architectures are capturing preference in US Department of Energy national laboratories where helium operating costs now dominate total cost of ownership calculations.
Service contract unbundling is separating hardware procurement from long-term maintenance obligations in satellite infrared sensor programs. European defense agencies now specify performance-based availability agreements rather than capital purchase with warranty coverage. France and Germany are leading this behavioral shift, with Thales Group and Airbus Defence and Space restructuring revenue recognition toward operational expenditure models spanning 15-year satellite mission lifetimes.
Pulse Tube and Gifford-Mcmahon Cryocoolers Market Segmentation
Cryocooler procurement decisions pivot on vibration tolerance, maintenance access, and helium recovery economics. Technology choices cascade through product architecture, end-use certification requirements, and long-term operating cost structures.
Product Type:
Cost tier and performance envelope separate the five product architectures, with magnetic bearing variants commanding premiums for sub-micron stability applications.
- Pulse Tube Cryocoolers:Elimination of moving displacer mechanisms achieves vibration signatures below 0.1 micron. Semiconductor fabrication facilities in Taiwan and South Korea specify these systems for extreme ultraviolet lithography stages where nanometer positioning precision is mandatory.
- Gifford-McMahon Cryocoolers:Field-serviceable displacer designs dominate medical MRI infrastructure where 10,000-hour maintenance intervals align with hospital capital planning cycles. China's Yangtze River Delta assembly plants are scaling production of these mature architectures for domestic hospital procurement programs.
- Stirling Cryocoolers:Compact kinematic designs serve portable infrared sensor platforms in defense applications.
- Joule-Thomson Cryocoolers:Open-cycle architectures persist in missile seeker cooling where mission duration is measured in minutes.
- Hybrid Cryocoolers:Staged pulse tube and Joule-Thomson combinations enable sub-Kelvin dilution refrigerator pre-cooling.
Gifford-McMahon systems command the established base. The steepest expansion runs through pulse tube architectures.
Application:
Application segmentation reflects divergent thermal load profiles, with continuous-duty industrial processes demanding different reliability engineering than intermittent research operations.
- Semiconductor Fabrication:Extreme ultraviolet lithography vacuum chambers require oil-free cooling to prevent molecular contamination of precision optics. ISO 14644 cleanroom mandates in East Asian fabrication facilities are eliminating lubricated compressor alternatives from qualified vendor lists.
- Superconducting Devices:Quantum computing testbeds prioritize vibration isolation above coefficient of performance metrics. Research laboratories specify active magnetic bearing compressors to maintain qubit coherence windows.
- Infrared Sensors:Satellite-borne thermal management demands 50,000-hour lifetimes without maintenance access.
- Space Simulation:Ground-based thermal vacuum chambers replicate orbital conditions for payload qualification.
- Liquefaction of Gases:Helium recovery systems at US Department of Energy national laboratories close the loop on open-cycle boil-off.
Semiconductor fabrication commands the established base. The steepest expansion runs through superconducting device cooling.
End User Industry:
Customer type determines procurement modality, with defense agencies favoring availability contracts and research institutions prioritizing capital expenditure flexibility.
- Electronics Manufacturing:Extreme ultraviolet lithography tool builders in Japan and South Korea integrate pulse tube cold heads as standard subsystems. METI efficiency benchmarks are accelerating variable-speed drive adoption in compressor modules.
- Research Laboratories:US national laboratories under EPA Helium Stewardship Act constraints are retrofitting recovery infrastructure. Closed-cycle architectures now dominate total cost of ownership calculations where virgin helium procurement faces extended lead times.
- Aerospace & Defense:European agencies specify performance-based availability agreements spanning 15-year satellite missions.
- Medical Imaging:Hospital procurement favors field-serviceable Gifford-McMahon designs with predictable maintenance schedules.
- Semiconductor Fabrication:Foundry operators specify helium-free architectures to meet particulate contamination limits.
Medical imaging commands the established base. The steepest expansion runs through electronics manufacturing.
Technology:
Technology segmentation tracks the displacement of mechanical contact points by electromagnetic and thermodynamic innovations.
- Magnetic Bearing:Active electromagnetic levitation eliminates mechanical wear surfaces in compressor assemblies. Position sensor arrays and rare-earth permanent magnets enable sub-nanometer stability for semiconductor patterning equipment.
- Linear Motor:Direct-drive compressors eliminate crankshaft linkages to reduce vibration transmission. Thales Group's captive production lines in France serve European defense infrared programs.
- Regenerative Heat Exchange:Gadolinium-silicon-germanium matrix formulations improve coefficient of performance.
- Pulsating Flow:Oscillating pressure wave dynamics define pulse tube thermodynamic cycles.
- Reciprocating Compressor:Conventional crankshaft-driven pistons persist in cost-sensitive medical MRI installations.
Reciprocating compressor architectures command the established base. The steepest expansion runs through magnetic bearing systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German cryocooler exports supply precision cooling subsystems to Dutch semiconductor equipment builders. This trans-European trade corridor channels technology toward East Asian fabrication facilities. The following five countries concentrate distinct demand profiles and regulatory environments.
United States
DOE national laboratories under EPA Helium Stewardship Act constraints are retrofitting closed-cycle recovery infrastructure. The phased reduction in federal helium reserve sales compresses virgin feedstock availability for open-cycle systems. Greater Boston research clusters prioritize pulse tube architectures where helium operating costs dominate total cost of ownership calculations.
China
Domestic cryocooler assembly capacity is expanding rapidly in the Yangtze River Delta to serve semiconductor fabrication demand. GB/T 16292 particulate limits constrain lubricant outgassing specifications in electronics manufacturing facilities. Shanghai and Suzhou industrial parks are scaling production of helium-free cooling architectures for EUV lithography tool integration.
Japan
METI energy efficiency benchmarks for cryogenic equipment are tightening compressor power density requirements. Variable-speed drive adoption is accelerating in domestic manufacturing lines. Tokyo and Osaka metropolitan areas concentrate electronics manufacturing procurement for extreme ultraviolet lithography cooling subsystems.
South Korea
Semiconductor fabrication facilities specify oil-free pulse tube systems for extreme ultraviolet lithography vacuum chambers. ISO 14644 cleanroom mandates eliminate lubricated compressor alternatives from qualified vendor lists. Samsung and SK Hynix supply chain clusters in Gyeonggi Province drive specification standards across East Asian equipment procurement.
Germany
Precision engineering exports supply regenerator matrix components and magnetic bearing assemblies to global cryocooler integrators. REACH chemical regulations constrain rare-earth powder processing and permanent magnet fabrication. Bavarian industrial corridors concentrate specialized heat exchanger fabrication for ASME Section VIII qualification.
Pulse Tube and Gifford-Mcmahon Cryocoolers Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers. Japanese and European conglomerates anchor premium segments through captive material science portfolios. Chinese state-affiliated entities and private manufacturers occupy mid-tier volume production. North American specialists dominate research laboratory relationships through sub-Kelvin integration expertise. Dominant competitive moves include backward integration into rare-earth regenerator matrix supply and geographic expansion via regional assembly licensing.
Among Japanese industrial conglomerates, Sumitomo Heavy Industries and ULVAC Cryogenics occupy positions emphasizing regenerator material science and vacuum technology heritage respectively. Thales Group represents European defense-aerospace captive production archetypes. Cryomech, now under Bluefors ownership, exemplifies North American research-specialist positioning. Chinese entrants including CSSC Pride Cryogenics, Lihan Cryogenics, and Zhejiang Bwokai Technologies sit within state-supported capacity expansion trajectories targeting domestic substitution.
| Leading Market Players |
|---|
| Sumitomo Heavy Industries |
| Thales Group |
| ULVAC Cryogenics |
| Cryomech (Bluefors) |
| Edwards Vacuum |
| CSSC Pride Cryogenics |
| Advanced Research Systems |
| Lihan Cryogenics |
| Zhejiang Bwokai Technologies |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta cryocooler assembly clusters are scaling domestic capacity faster than demand absorption, compressing margin pools for imported systems and tilting procurement power toward foundry operators in East Asian semiconductor fabrication facilities.
Pricing Analysis
Next-generation magnetic bearing pulse tube systems command substantial premiums over conventional gas-bearing architectures and legacy Gifford-McMahon designs. Three-tier pricing structure across premium magnetic bearing, standard linear motor, and economy reciprocating compressor levels reflects certification grade differentiation and after-sales service bundling. Cost compression in mid-tier segments is intensifying because Chinese domestic manufacturers are scaling helium-free architectures for EUV lithography tool integration. Hospital procurement teams exhibit highest price sensitivity due to capital budget constraints, while semiconductor equipment manufacturers prioritize vibration performance over unit economics.
Supply Chain Analysis
Specialized heat exchanger fabricators in Bavaria and regenerator matrix processors in Japan hold concentrated contract-manufacturing capacity for precision cryocooler subassemblies. Manufacturing draws from China, Germany, and Japan for final assembly, with rare-earth powder inputs resting on neodymium-dysprosium supply chains subject to export licensing pressures. Single-source vulnerability in gadolinium-silicon-germanium alloy sourcing creates qualification risk for secondary suppliers. Distribution runs through OEM direct sales for semiconductor equipment integration and authorized service networks for medical MRI infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnetic bearing technology is disrupting conventional gas-bearing architectures, with ISO 14644 cleanroom mandates and EPA helium stewardship regulations accelerating closed-cycle adoption across precision manufacturing and research laboratory end uses.
For Market Incumbents: Entrench regenerator material science advantages through captive rare-earth powder processing and ASME Section VIII qualification investments. Backward integration into spherical stainless steel mesh sourcing defends against supply disruption from export licensing pressures. Sumitomo Heavy Industries demonstrates template through superconducting magnet installation dominance.
For New Entrants and Emerging Players: European defense infrared programs offer accessible white space where Thales Group's captive production creates sovereign supply chain replication opportunities. Performance-based availability contracts spanning satellite mission lifetimes represent most penetrable procurement modality. Target research laboratory relationships through dilution refrigerator integration expertise following Cryomech's channel architecture.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with underutilized cryogenic equipment divisions and stranded vacuum technology assets. Long-term viability hinges on quantum computing testbed expansion sustaining sub-Kelvin cooling platform demand. Monitor METI efficiency benchmark compliance as signal for variable-speed drive adoption inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Magnetic Bearing Technology Adoption | Active electromagnetic levitation enables sub-nanometer stability for EUV lithography vacuum chambers in Taiwan and South Korea. |
| Helium Recovery Infrastructure Retrofit | Closed-cycle architectures at US DOE national laboratories reduce operating costs under EPA Helium Stewardship Act constraints. |
| Regenerator Matrix Backward Integration | In-house gadolinium-silicon-germanium alloy production secures supply against rare-earth export licensing pressures. |
| Performance-Based Availability Contracts | Fifteen-year satellite mission service agreements shift revenue recognition toward operational expenditure models in European defense procurement. |
| Variable-Speed Drive Integration | Permanent magnet synchronous motor adoption aligns with Japan METI compressor power density benchmarks. |
Research Methodology
Cross-validation between primary interviews with cryocooler engineering directors, semiconductor equipment procurement managers, and hospital biomedical engineering heads anchors the qualitative findings against secondary validation from SEC filings, customs trade data, and ASME qualification registries. Bottom-up and top-down triangulation combines OEM shipment disclosures with end-user installation records across research laboratory, medical imaging, and electronics manufacturing verticals.
Calibration against historical capacity expansion announcements and regulatory filing timelines shapes the analytical framework across the analysis window. Segmentation dimensions encompass product architecture, application thermal load profile, end-user procurement modality, and regional regulatory cluster. CAGRs derive from installed base growth rates and replacement cycle dynamics, with extreme ultraviolet lithography deployment schedules and quantum computing testbed expansion serving as industry-specific demand inputs.
Practitioners should monitor rare-earth export licensing developments, EPA helium reserve sale schedules, and METI efficiency benchmark revisions for early signals of forecast trajectory shifts. Quarterly review of semiconductor capital expenditure announcements and national laboratory procurement awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Asia-Pacific Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Europe Chip Mounter Market
Semiconductor Equipment
Laser Annealing System Market
Semiconductor Equipment
Vacuum Coating Equipment Market
Semiconductor Equipment
Semiconductor Wafer Process Control Equipment Market
Semiconductor Equipment
Consumable Parts for Semiconductor Equipment Market
Semiconductor Equipment
Chip Mounter Market
Semiconductor Equipment
Vacuum Soldering System Market
Semiconductor Equipment
Global Equipment Front End Module (EFEM) Market
Semiconductor Equipment
North America Battery Manufacturing Equipment Market
Semiconductor Equipment
Wafer Chucks Market
Semiconductor Equipment
Wet Station Market
Semiconductor Equipment
Global Semiconductor Thermal Evaporators Market
Semiconductor Equipment
Plasma Etching Equipment Market
Semiconductor Equipment
Global Soldering Equipment Market
Semiconductor Equipment
Lithography Equipment Market