
 Semiconductor Laser Equipment Market | 2026-2036
Semiconductor Laser Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Laser Equipment Market Analytics
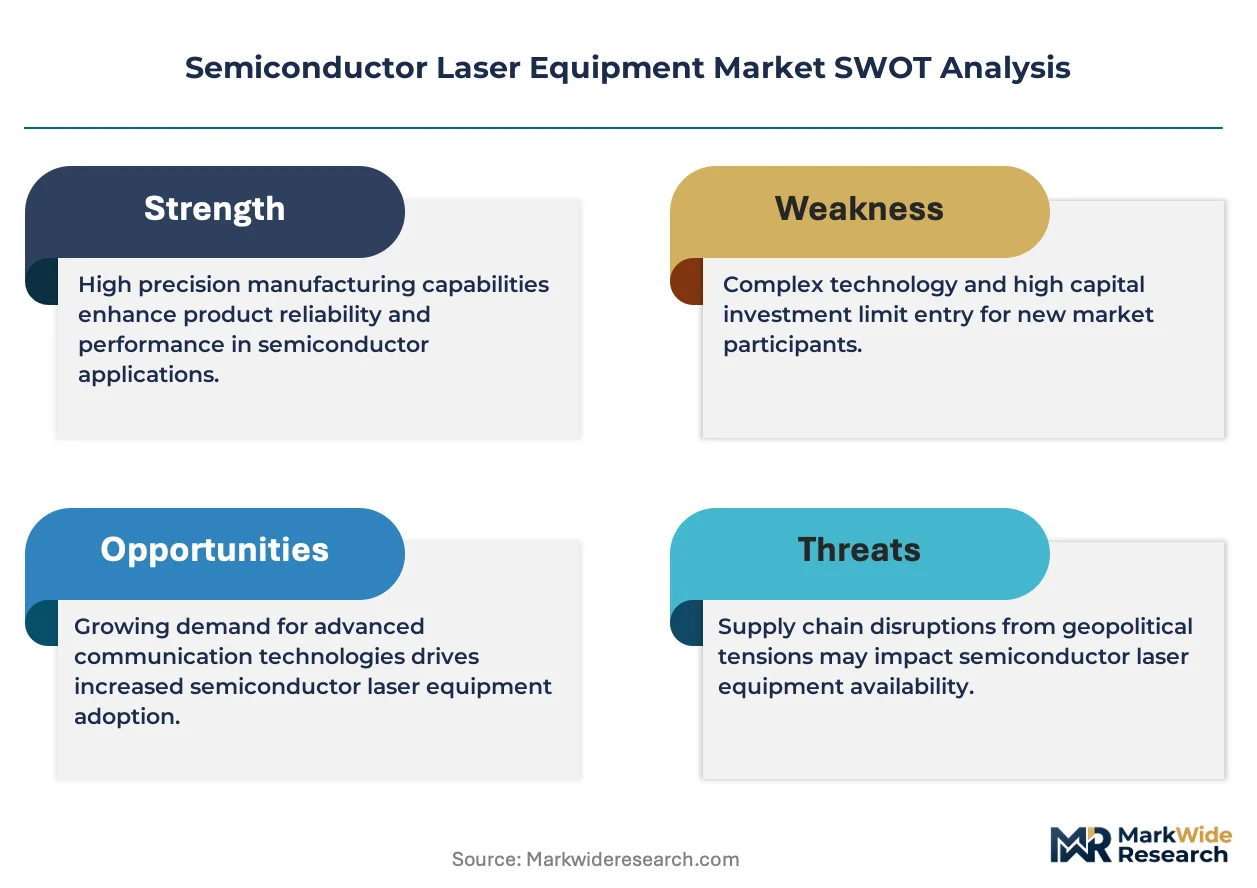
Multi-source procurement for critical optical components is shifting toward vertically integrated captive supply as lead times for specialty pump diodes stretch. Coherent Corporation leverages in-house gallium arsenide wafer production to anchor its fiber laser amplifier supply chain. IPG Photonics sustains dominance in high-power industrial systems through proprietary single-emitter diode packaging. Han's Laser Technology Industry Group Co Ltd competes on manufacturing scale across China's domestic machine tool sector.
Semiconductor laser equipment encompasses systems that generate coherent light through electrically pumped semiconductor junctions, typically operating at wavelengths from 375 nanometers in the violet to beyond 10 micrometers in the infrared, with output powers spanning milliwatts for telecom transceivers to tens of kilowatts for materials processing. These systems serve as precision energy delivery platforms for cutting, welding, medical surgery, and optical data transmission where beam quality and thermal stability determine process yield. Fiber lasers now occupy the dominant margin pool in materials processing due to superior wall-plug efficiency and maintenance intervals. Quantum dot lasers represent the fastest-expanding technology segment as atomic-layer epitaxy advances enable temperature-stable emission for next-generation datacenter interconnects. Diode lasers remain the volume foundation across sensing and medical treatment applications where cost-per-watt economics govern procurement.
The FDA regulates medical laser systems through 21 CFR 1040.10 performance standards that classify devices by hazard level and mandate emission labeling, directly shaping product development cycles for surgical and dermatological equipment. China's MIIT enforces GB standards for industrial laser safety and electromagnetic compatibility, while the EU Machinery Directive and CE marking requirements govern market access for European manufacturing customers. REACH compliance for rare-earth dopants and RoHS restrictions on hazardous substances in pump diode substrates add material qualification burdens that favor suppliers with established chemical stewardship programs. Stakeholders must monitor how forthcoming EU F-Gas Regulation amendments affect cooling system architectures for high-power installations.
Market Dynamics
Telecom infrastructure builders are intensifying wavelength-division multiplexing deployments, pulling demand for precision pump diodes and fiber amplifiers into concentrated procurement cycles that favor vertically integrated suppliers with captive gallium arsenide wafer production.
Growth Catalysts
- China's MIIT dual carbon goals:Mandatory GB standards for industrial energy efficiency are accelerating fiber laser substitution in metal cutting applications, forcing domestic machine tool retrofits.
- Wavelength-division multiplexing multiplication:Telecom carriers are expanding 400G and 800G coherent transceiver deployments, driving demand for narrow-linewidth external cavity lasers.
- Atomic-layer epitaxy advances:Quantum dot laser manufacturing maturity is enabling temperature-stable emission for datacenter interconnects, opening new insertion points in cloud infrastructure.
Market Restraints
- Rare-earth dopant supply concentration:Ytterbium and erbium refining capacity clusters in limited jurisdictions, creating input cost volatility for fiber laser gain media.
- Specialty pump diode lead times:Extended delivery schedules for high-brightness single-emitter devices constrain amplifier production ramp rates.
- EU F-Gas Regulation cooling constraints:Pending amendments threaten refrigerant architectures for high-power installations, forcing thermal management redesign cycles.
Strategic Opportunities
- Medical aesthetics underpenetration:Diode laser hair removal and skin resurfacing equipment remains below saturation in India's tier-two cities, creating distribution whitespace.
- Silicon photonics convergence:Hybrid integration of III-V lasers with CMOS electronics is enabling co-packaged optics for AI training clusters.
- Japan's METI semiconductor revival subsidies:Domestic production incentives for advanced compound semiconductors are reshoring epitaxial wafer capacity.
Industry Challenges
- Atomic-layer deposition technician scarcity:Quantum dot epitaxy requires specialized MOCVD operators, creating recruitment bottlenecks for expansion plans.
- 21 CFR 1040.10 certification timelines:FDA medical laser classification reviews extend product launch windows for surgical equipment developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Laser Equipment Market |
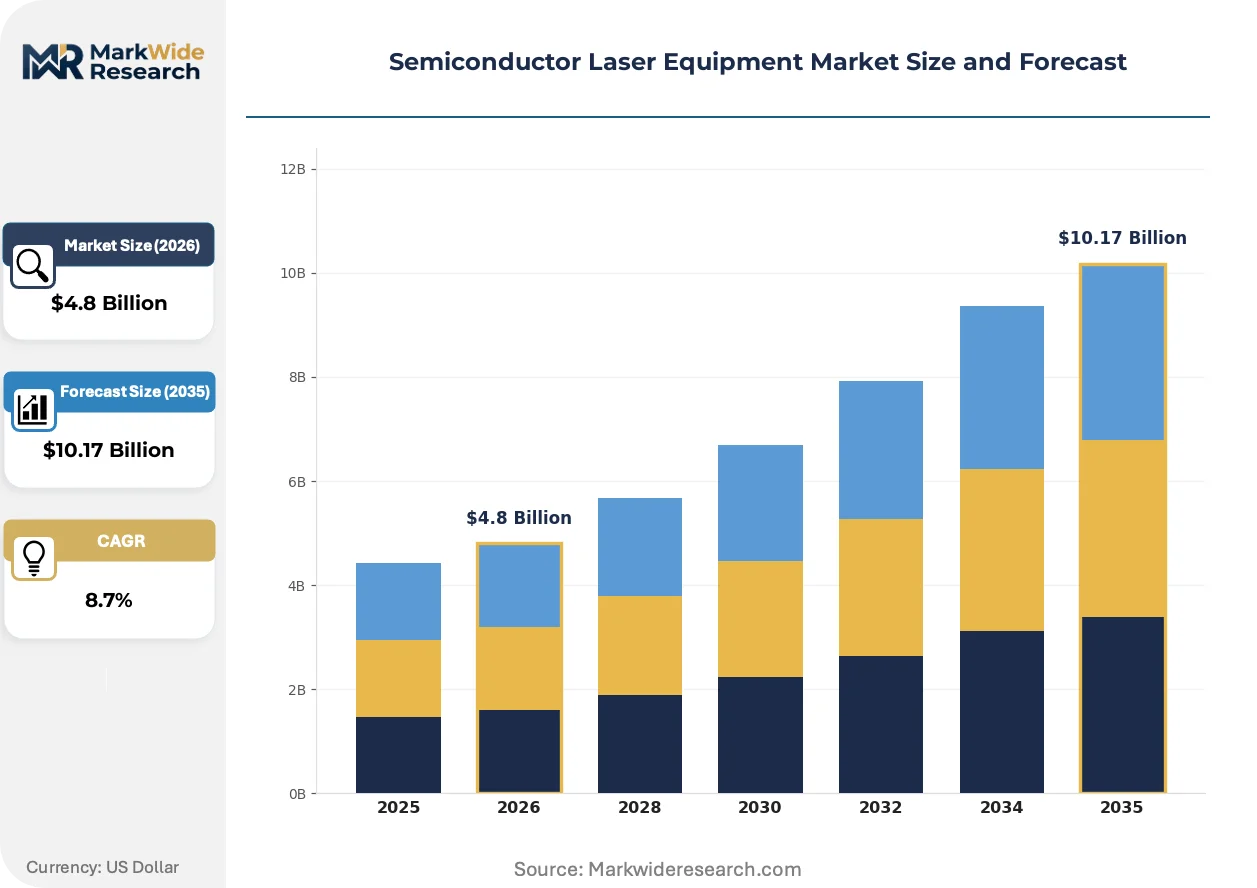
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diode Lasers, Fiber Lasers, Solid-State Lasers, Semiconductor Lasers Application: Communications, Material Processing, Medical Treatments, Sensing End User: Telecom, Manufacturing, Healthcare, Automotive Technology: Direct Modulation, External Modulation, Quantum Dot Lasers, Vertical-Cavity Surface-Emitting Lasers |
| Companies Covered | TRUMPF Group, Lumentum, Coherent Corporation, Nichia Corporation, Sumitomo Heavy Industries Ltd, IPG Photonics, Han’s Laser Technology Industry Group Co Ltd, Omtech Laser, ams-OSRAM AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Laser Equipment Market Evolving Landscape
Beam delivery architectures are fragmenting as solid-state and fiber platforms compete for dominance in precision manufacturing, while regulatory pressure on cooling chemistries and rare-earth stewardship reshapes equipment design priorities.
Quantum dot laser technology is decentralizing wavelength control across datacenter interconnects. Cloud operators are adopting these devices for 800G coherent links at accelerated procurement rates. Temperature-insensitive emission is decentralizing thermal management requirements, compressing system complexity and enabling passive packaging.
REACH compliance for rare-earth dopants is tightening material qualification burdens across European manufacturing supply chains. Chemical stewardship programs now govern ytterbium and erbium sourcing for fiber laser gain fibers. High-power industrial system vendors are responding by locking long-term offtake agreements with established rare-earth processors.
Equipment buyers are consolidating vendor relationships around integrated service capabilities. Machine tool operators in Germany are unbundling maintenance contracts from initial capital purchases, favoring suppliers with regional spare parts depots. This preference shift concentrates procurement among vendors with localized technical support infrastructure rather than pure equipment manufacturers.
Semiconductor Laser Equipment Market Segmentation
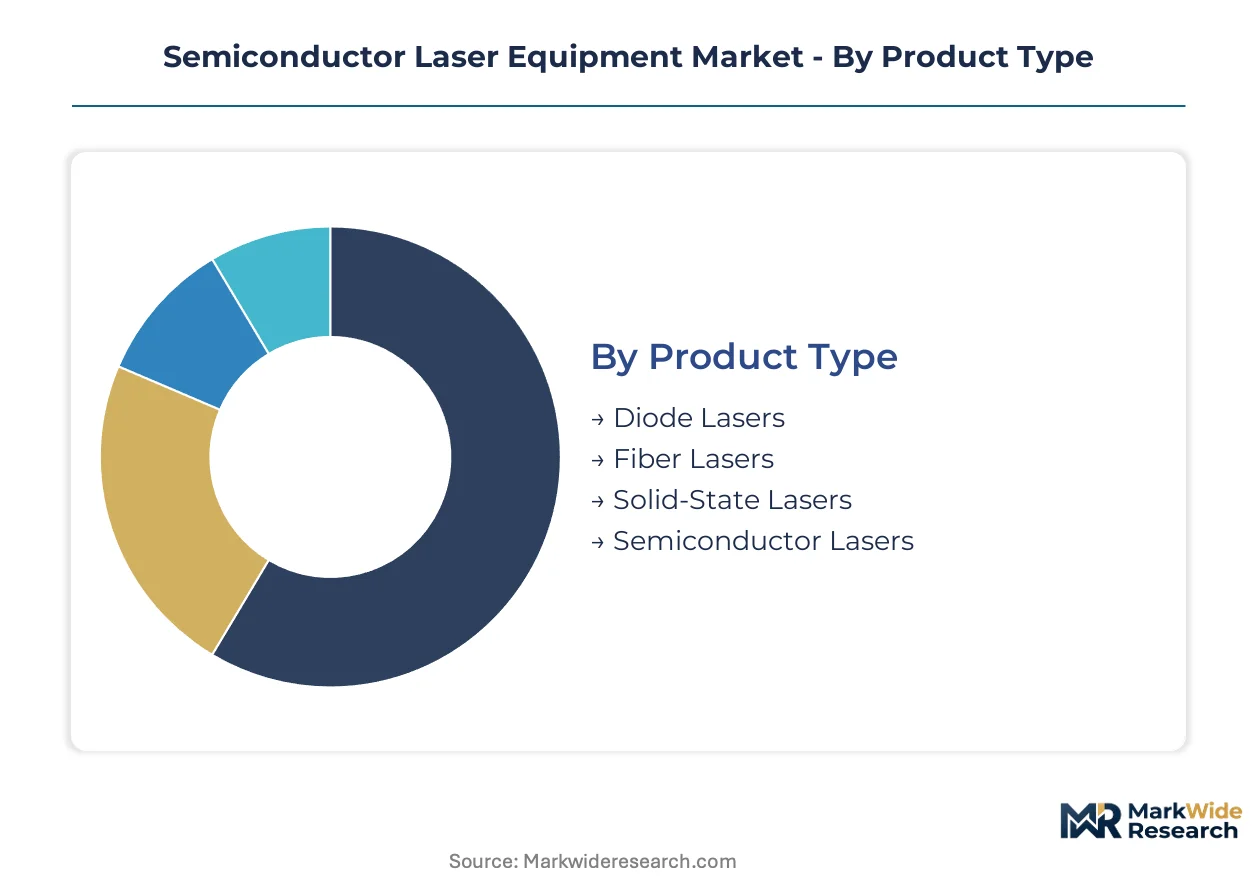
Equipment classification shapes procurement patterns across semiconductor laser markets. Certification requirements, thermal management architectures, and beam quality specifications create distinct commercial boundaries between product categories. Buyers segment investments by operational wavelength, power density, and regulatory compliance burden.
Product Type:
FDA 21 CFR 1040.10 governs medical-grade solid-state and diode systems, while industrial fiber lasers face OSHA workplace safety inspections and EU Machinery Directive CE marking. China's GB standards enforce dual carbon efficiency thresholds on high-power metal cutting equipment.
- Diode Lasers:Electrically pumped semiconductor junctions deliver direct emission from 375 nanometers to beyond 10 micrometers. Medical aesthetics clinics in India's tier-two cities drive procurement for hair removal systems. FDA Class II device classification extends certification timelines for dermatological equipment developers.
- Fiber Lasers:Rare-earth-doped silica gain fibers pumped by single-emitter diodes achieve wall-plug efficiencies exceeding 30 percent. Germany's precision manufacturing clusters command premium multi-kilowatt systems for automotive sheet metal cutting. REACH compliance for ytterbium and erbium sourcing concentrates procurement among established chemical stewardship programs.
- Solid-State Lasers:Crystalline gain media pumped by flashlamps or diodes enable Q-switched nanosecond pulses for micromachining.
- Semiconductor Lasers:Direct bandgap III-V epitaxial structures serve as pump sources and standalone emitters across sensing applications.
Leading the category by volume: Fiber Lasers. Growing fastest: Diode Lasers.
Application:
Cost tier stratification separates capital-intensive materials processing from volume-driven communications components. Medical treatments command price premiums tied to FDA PMA pathway investments.
- Communications:Narrow-linewidth external cavity lasers and directly modulated DFB devices enable 400G and 800G coherent transceiver architectures. Telecom infrastructure builders in the United States and Japan concentrate procurement for wavelength-division multiplexing deployments. Atomic-layer epitaxy advances for quantum dot emitters are compressing thermal management complexity in datacenter interconnects.
- Material Processing:Multi-kilowatt fiber and solid-state systems cut, weld, and mark metals across automotive and machine tool sectors. China's MIIT mandatory GB standards are accelerating fiber laser substitution in domestic metal fabrication retrofits. EU F-Gas Regulation amendments threaten refrigerant architectures for high-power installations.
- Medical Treatments:Selective photothermolysis drives surgical, dermatological, and ophthalmological equipment specifications.
- Sensing:Pulsed and CW diode sources serve LiDAR, spectroscopy, and industrial metrology applications.
Material Processing claims the largest revenue pool. Communications demonstrates the steepest expansion trajectory.
End User:
Customer type determines service contract structures and spare parts depot requirements. Manufacturing buyers unbundle maintenance from capital purchases.
- Telecom:Carrier procurement cycles concentrate demand for pump diodes and fiber amplifiers. Wavelength-division multiplexing multiplication pulls orders toward vertically integrated suppliers with captive gallium arsenide wafer production.
- Manufacturing:Machine tool operators in Germany favor vendors with regional technical support infrastructure over pure equipment manufacturers.
- Healthcare:Hospital systems and private clinics demand FDA-cleared surgical platforms with extended service agreements.
- Automotive:EV battery welding and body-in-white cutting specifications drive high-power fiber laser adoption.
Manufacturing dominates absolute unit demand. Telecom exhibits the sharpest procurement acceleration.
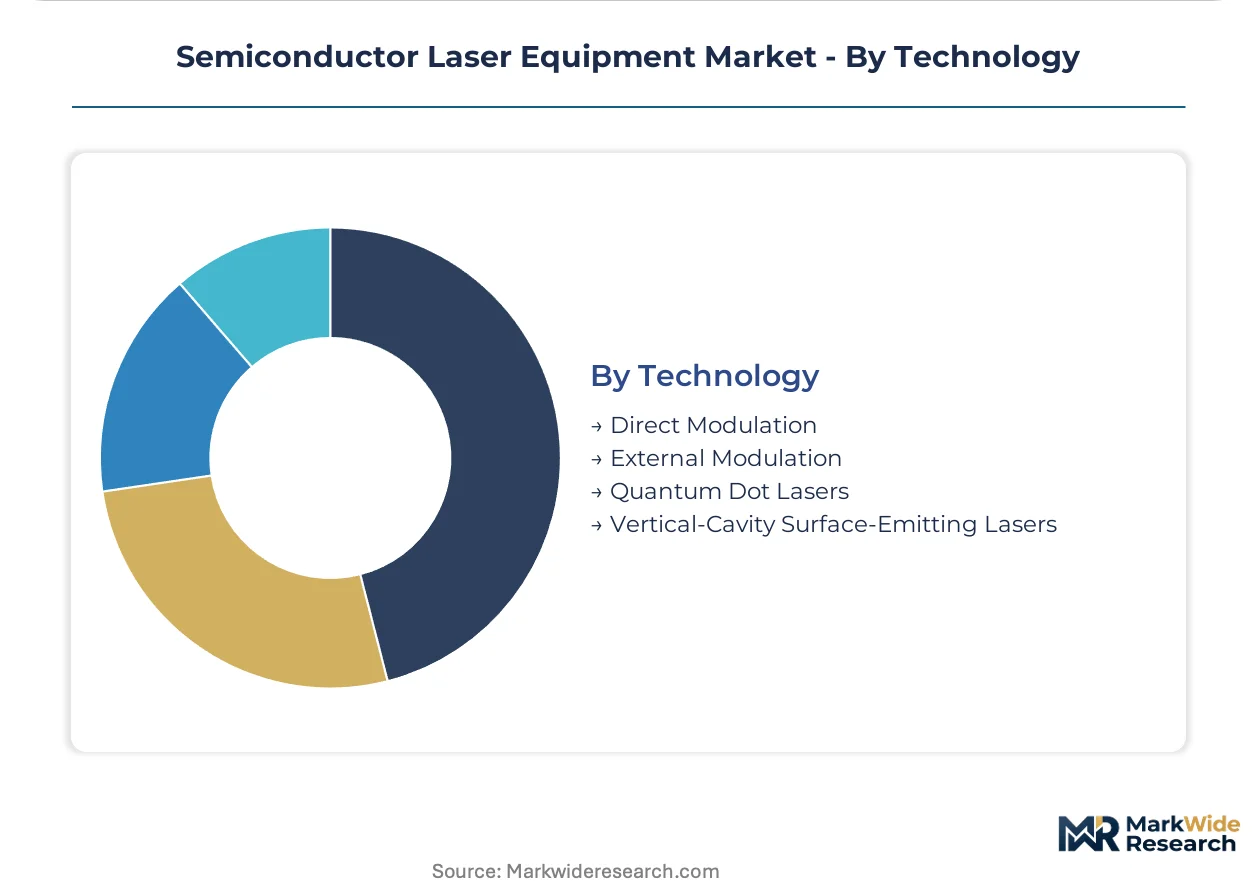
Technology:
Supply concentration in specialty epitaxial wafer production shapes competitive access to quantum dot and VCSEL architectures. MOCVD reactor capacity constraints limit expansion timelines.
- Direct Modulation:Current-injected DFB and Fabry-Perot lasers modulate output through drive signal variation. Short-reach datacenter interconnects favor these devices for cost-sensitive 100G links.
- External Modulation:Electro-absorption and Mach-Zehnder modulators paired with CW lasers achieve chirp-free transmission. Coherent 400G and 800G metro networks require these architectures for dispersion tolerance.
- Quantum Dot Lasers:Atomic-layer epitaxy enables temperature-stable emission with reduced threshold current. Cloud operators are adopting these devices for 800G coherent links at accelerated procurement rates.
- Vertical-Cavity Surface-Emitting Lasers:Short optical cavities perpendicular to the wafer surface enable 2D array fabrication. 3D sensing modules in consumer electronics drive volume demand.
Direct Modulation retains the broadest installed base. Quantum Dot Lasers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement concentrates in Germany, Japan, and the United States where precision manufacturing clusters command premium systems for automotive sheet metal cutting and telecom infrastructure deployment.
United States
Telecom carriers accelerate wavelength-division multiplexing multiplication for 400G and 800G coherent transceiver networks. The FCC spectrum allocation frameworks shape datacenter interconnect deployment timelines. Precision manufacturing clusters in Michigan and Ohio drive multi-kilowatt fiber laser adoption for EV battery welding and body-in-white cutting specifications.
Germany
Automotive OEMs and machine tool operators command premium high-power systems for sheet metal fabrication. The EU Machinery Directive and CE marking requirements govern market access for industrial laser installations. Manufacturing clusters in Stuttgart and Munich unbundle maintenance contracts from capital purchases, favoring vendors with regional spare parts depots.
China
Domestic machine tool retrofits accelerate as MIIT dual carbon goals enforce mandatory GB standards for industrial energy efficiency. GB standards for laser safety and electromagnetic compatibility reshape equipment specifications. Manufacturing scale concentrates in Shenzhen and Wuhan where Han's Laser Technology Industry Group Co Ltd competes across the domestic sector.
Japan
Telecom infrastructure builders concentrate procurement for narrow-linewidth external cavity lasers and pump diodes. METI semiconductor revival subsidies reshore advanced compound semiconductor epitaxial wafer capacity. Precision manufacturing clusters in Nagoya and Osaka anchor automotive and electronics production demanding beam quality stability.
India
Medical aesthetics clinics in tier-two cities drive procurement for diode laser hair removal and skin resurfacing equipment below market saturation. CDSCO device classification pathways extend certification timelines for dermatological equipment developers. Distribution whitespace concentrates in Hyderabad and Pune where private clinic networks expand service coverage.
Semiconductor Laser Equipment Market Competitive Landscape
Backward integration into gallium arsenide wafer production dominates the current competitive landscape as lead times for specialty pump diodes stretch. The vendor base concentrates around vertically integrated suppliers with captive epitaxial capacity and pure-play equipment manufacturers dependent on external component sourcing. Three archetypes define positioning: integrated compound semiconductor fabricators controlling upstream material supply, high-power industrial system specialists with proprietary packaging architectures, and scale-driven Chinese manufacturers serving domestic machine tool retrofits. M&A activity targets MOCVD reactor capacity and rare-earth processing assets, while strategic partnerships lock long-term offtake agreements for ytterbium and erbium gain media.
Among integrated compound semiconductor fabricators, Coherent Corporation and ams-OSRAM AG exemplify the archetype of suppliers with in-house III-V wafer production anchoring fiber laser amplifier supply chains. IPG Photonics occupies a position within the high-power industrial system specialist tier, representing proprietary single-emitter diode packaging approaches that sustain dominance in materials processing applications. At the scale-driven end, Han's Laser Technology Industry Group Co Ltd anchors Chinese domestic manufacturing, exemplifying volume-based competition across machine tool sector retrofits driven by MIIT regulatory mandates.
| Leading Market Players |
|---|
| TRUMPF Group |
| Lumentum |
| Coherent Corporation |
| Nichia Corporation |
| Sumitomo Heavy Industries Ltd |
| IPG Photonics |
| Han's Laser Technology Industry Group Co Ltd |
| Omtech Laser |
| ams-OSRAM AG |
| Others |
Value Network & Pricing Analysis
Captive gallium arsenide wafer production anchors supply positions and pricing power across the semiconductor laser equipment market, with Coherent Corporation and ams-OSRAM AG leveraging in-house III-V fabrication to control amplifier input costs while commanding premium positioning against externally sourcing competitors.
Pricing Analysis
Warranty and service contract unbundling distinguishes German machine tool procurement patterns from bundled Asian transactions. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared medical systems from industrial fiber lasers and commodity diode emitters. Cost compression in high-power fiber amplifiers intensifies as China's domestic manufacturers scale output. Medical aesthetics clinics in India's tier-two cities exhibit highest price sensitivity, while telecom carriers in Japan and the United States prioritize beam stability over unit economics.
Supply Chain Analysis
Dual-sourcing mandates for specialty pump diodes force amplifier manufacturers to qualify multiple gallium arsenide wafer suppliers, stretching procurement timelines. Production concentrates in Germany, Japan, and the United States for precision systems, while China dominates volume manufacturing. Ytterbium and erbium gain fibers, gallium arsenide substrates, and single-emitter diode packages constitute critical input dependencies. Single-source vulnerability in rare-earth refining threatens fiber laser gain media availability. Distribution runs through regional technical service depots that machine tool operators favor over direct equipment sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into epitaxial wafer production and rare-earth processing defines competitive positioning, with players racing to lock MOCVD reactor capacity and ytterbium offtake agreements before supply constraints harden.
For Market Incumbents: Anticipate quantum dot laser technology displacing conventional DFB architectures in datacenter interconnects by accelerating atomic-layer epitaxy capacity additions. Lock long-term rare-earth supply contracts with established processors to defend against ytterbium cost volatility. Deepen regional service infrastructure in Germany and Japan where manufacturing buyers unbundle maintenance from capital purchases.
For New Entrants and Emerging Players: Silicon photonics hybrid integration offers entry into co-packaged optics for AI training clusters where incumbent laser suppliers lack CMOS integration expertise. Target medical aesthetics distribution whitespace in India's tier-two cities where diode laser hair removal equipment remains below saturation. Pursue CDSCO certification pathways ahead of clinic network expansion.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated compound semiconductor fabricators seeking MOCVD reactor capacity. Five-to-ten year viability hinges on captive epitaxial wafer supply rather than pure equipment assembly. Monitor EU F-Gas Regulation amendment timing as inflection indicator for thermal management redesign cycles and vendor consolidation pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| MOCVD Reactor Capacity Acquisition | Atomic-layer epitaxy for quantum dot lasers requires specialized reactor operators scarce in labor markets. |
| Rare-Earth Long-Term Supply Agreement | Ytterbium and erbium offtake contracts with established processors mitigate REACH compliance burdens. |
| Regional Service Depot Expansion | German machine tool operators favor vendors with localized spare parts infrastructure over pure manufacturers. |
| Silicon Photonics Hybrid Integration | Co-packaged optics for AI clusters demand CMOS-compatible III-V laser attachment expertise. |
| CDSCO/FDA Dual Certification Pathway | Medical aesthetics equipment in India requires parallel regulatory investment to capture distribution whitespace. |
Research Methodology
Independent corroboration across primary interviews with MOCVD reactor operators, fiber laser system engineers, and telecom procurement managers, combined with secondary validation through SEC 10-K filings, MIIT GB standard publications, and EU F-Gas Regulation amendments, underwrites the qualitative findings. Bottom-up equipment shipment data from precision manufacturing clusters in Stuttgart, Nagoya, and Detroit triangulates against top-down rare-earth consumption estimates and gallium arsenide wafer production figures.
Comparable-period anchoring to historical fiber laser adoption curves in automotive sheet metal cutting and wavelength-division multiplexing deployment cycles shapes the projection horizon. The analytical framework segments by product type, application, end user, and technology across the modeling period. CAGRs derive from equipment replacement cycles, regulatory compliance deadlines, and datacenter interconnect upgrade trajectories. Forecast inputs incorporate MIIT dual carbon enforcement timelines and METI semiconductor revival subsidy disbursement patterns.
Several conditions sit outside the modeled scope, including unforeseen rare-earth export restrictions, abrupt EU F-Gas Regulation cooling system bans, and quantum dot laser yield breakthroughs that compress manufacturing costs faster than anticipated. Deviation in atomic-layer epitaxy technician availability or ytterbium refining capacity expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Semiconductor Assembly Equipment Market
Semiconductor Equipment
Vacuum Coating Equipment Market
Semiconductor Equipment
Automatic Laser PCB Depaneling Machines Market
Semiconductor Equipment
Consumable Parts for Semiconductor Equipment Market
Semiconductor Equipment
Partition Inserter Machines Market
Semiconductor Equipment
Die Bonder Equipment Market
Semiconductor Equipment
Global Semiconductor Back-End Equipment Market
Semiconductor Equipment
Europe Semiconductor Etch Equipment Market
Semiconductor Equipment
Automatic Dicing Saw Market
Semiconductor Equipment
Cathode Stripping Machines Market
Semiconductor Equipment
Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Global Wafer Processing and Assembly Equipment Market
Semiconductor Equipment
Semiconductor Photolithography Equipment Market
Semiconductor Equipment
Semiconductor Wafer Fab Equipment (WFE) Market
Semiconductor Equipment
Vacuum Ovens Market
Semiconductor Equipment
Reticle Pod Cleaning System Market