
 Global Cleanroom Technologies Market | 2026-2036
Global Cleanroom Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cleanroom Technologies Market Analysis
Qualified cleanroom technician availability is collapsing across major manufacturing corridors, forcing equipment suppliers to embed remote diagnostics and predictive maintenance into system architectures. Exyte AG leverages its turnkey facility engineering heritage to anchor large-scale pharmaceutical campus projects across Germany and Singapore. Taikisha Ltd. competes through HVAC-integrated cleanroom delivery models that compress commissioning timelines for semiconductor fabs. Kimberly-Clark Corporation sustains consumables pull-through via long-term apparel supply contracts tied to operator headcount at major biologics sites.
Cleanroom technologies encompass engineered enclosures, filtration systems, garments, and environmental monitoring equipment designed to maintain particulate concentrations below ISO 14644-1 thresholds through laminar airflow and positive-pressure containment. These systems prevent microbial and particle contamination during sterile drug filling, wafer lithography, and satellite assembly operations. Modular cleanrooms are capturing disproportionate capital flow as pharmaceutical tenants demand reconfigurable suites that adapt to multi-product cell therapy campaigns. Barrier isolator technology leads in margin contribution due to specialized glove-port fabrication and containment validation services. Semiconductor production applications are outpacing pharmaceutical growth in absolute capacity terms, though biologics maintains higher per-square-foot equipment intensity.
FDA current Good Manufacturing Practice enforcement and EU MDR Annex I sterility requirements mandate continuous particulate monitoring and documented environmental qualification across commercial manufacturing suites. EMA inspections of sterile product facilities in Ireland and Italy have intensified demand for redundant HEPA filtration architectures and real-time viable particle detection. ISO 14644-3 test methods govern periodic requalification schedules that sustain aftermarket service revenue for installed base owners. Stakeholders must weigh modular upgrade paths against greenfield construction as biologics pipelines shift toward personalized medicine batch sizes.
Market Dynamics
Advanced node semiconductor manufacturing is compressing cleanroom specifications below ISO Class 3 thresholds while pharmaceutical cell therapy pipelines demand rapid suite reconfiguration, forcing equipment architectures toward modular, software-defined environmental control systems.
Growth Catalysts
- EU MDR Annex I sterility mandates:Tightened environmental qualification requirements for sterile drug facilities in Ireland and Italy sustain replacement demand for redundant HEPA filtration and real-time viable particle detection systems.
- Semiconductor foundry concentration in South Korea and Taiwan:Memory and logic wafer capacity expansion drives absolute cleanroom square footage growth with specialized lithography-grade vibration and thermal stability specifications.
- Modular cleanroom architectures:Reconfigurable softwall and hardwall systems enable pharmaceutical tenants to repurpose suites between monoclonal antibody and personalized cell therapy campaigns without greenfield construction.
Market Restraints
- Specialized technician scarcity:Qualified cleanroom commissioning and validation engineers are collapsing across German and Singaporean pharmaceutical corridors, extending project timelines and inflating labor premiums.
- Supply concentration in East Asian HVAC componentry:Critical fan filter unit motors and HEPA media production clusters in China and South Korea expose lead time volatility to geopolitical friction and export control uncertainty.
- Barrier isolator glove-port fabrication bottlenecks:Specialized polymer molding and containment validation capacity constraints limit throughput for high-margin pharmaceutical isolator systems.
Strategic Opportunities
- India biologics manufacturing buildout:CDSCO regulatory alignment with ICH Q5A and PLI scheme incentives for active pharmaceutical ingredients create greenfield demand for turnkey cleanroom infrastructure.
- Remote diagnostics convergence with predictive maintenance:Equipment suppliers embedding IoT sensors and machine learning algorithms into fan filter units transform aftermarket service from scheduled to condition-based revenue models.
- Satellite and space hardware assembly:Commercial launch vehicle and constellation manufacturers in the United States require ISO Class 5 environments for optical payload integration outside traditional semiconductor and pharmaceutical demand centers.
Industry Challenges
- ISO 14644-3 requalification timeline compression:Pharmaceutical operators face escalating documentation burdens and inspectorate scrutiny during periodic facility revalidation, straining quality assurance headcount.
- Legacy facility HVAC integration:Brownfield pharmaceutical sites in Germany and Switzerland confront mechanical system interoperability gaps when retrofitting real-time environmental monitoring onto 1990s-era air handling architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cleanroom Technologies Market |
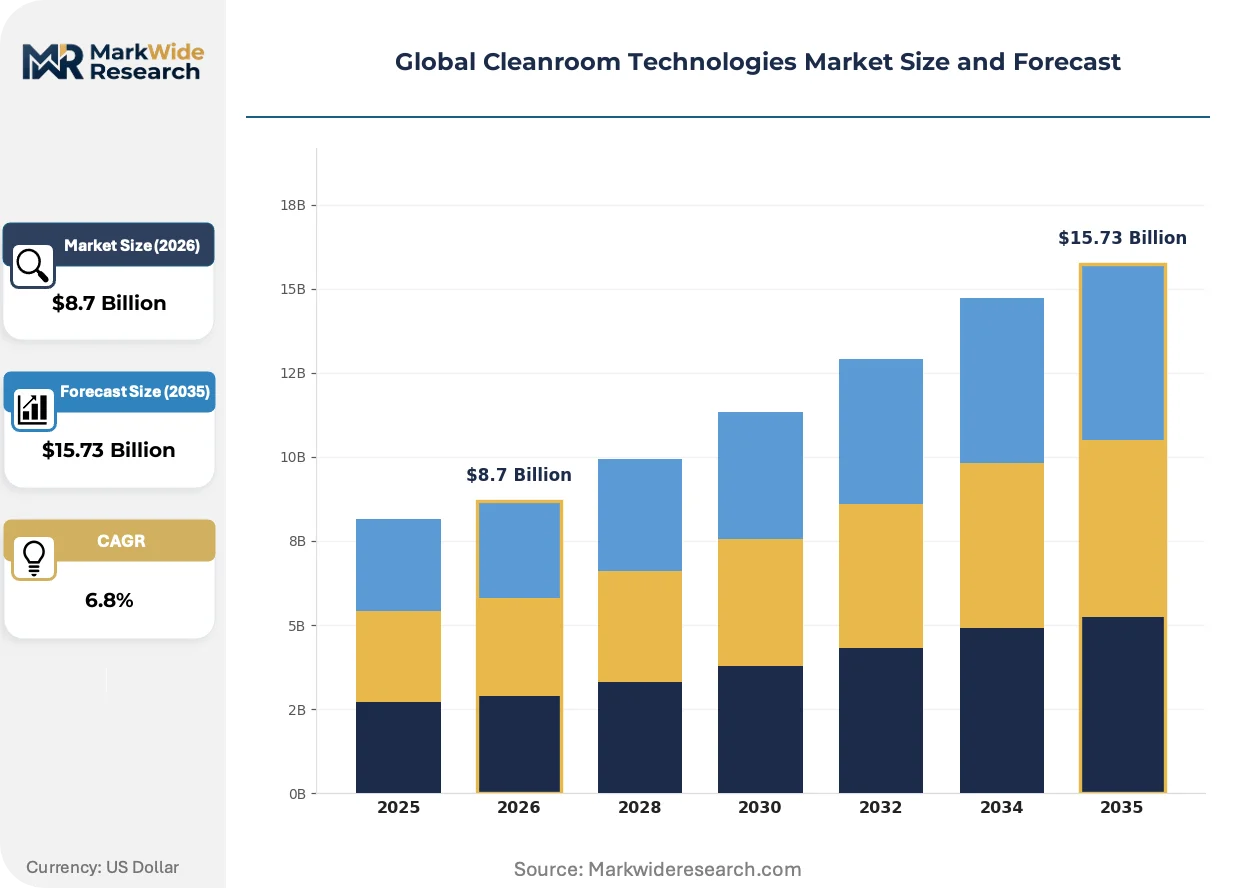
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Filters, Cleanroom Apparel, Cleaning Disinfectants, HVAC Systems Application: Pharmaceutical Manufacturing, Biotech Research, Semiconductor Production, Aerospace Engineering End User: Pharmaceutical Companies, Electronic Manufacturers, Healthcare Facilities, Research Laboratories Technology: Modular Cleanrooms, Barrier Isolators, Dynamic Cleanrooms, Controlled Environment Systems |
| Companies Covered | Exyte AG, Kimberly-Clark Corporation, DuPont de Nemours Inc., Azbil Corporation, Camfil AB, Taikisha Ltd., Clean Air Products, Terra Universal Inc., Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cleanroom Technologies Market Emerging Trajectories
Cleanroom technology architectures are bifurcating between monolithic central air handling systems and distributed edge-computing environmental controls, with software-defined monitoring displacing hardwired analog instrumentation across both greenfield and retrofit deployments.
Isolator technology is bifurcating between open restricted access barrier systems for aseptic processing and fully closed gloveless robotic isolators for high-potency compound containment. Biologics manufacturers in Switzerland and the United States are adopting hybrid configurations that combine human-accessible intervention points with automated material transfer. This technology is bifurcating the vendor landscape between specialized containment engineering firms and diversified automation suppliers.
The EU F-Gas Regulation phase-down of hydrofluorocarbon refrigerants is forcing cleanroom HVAC suppliers to deploy natural refrigerant and cascade cooling architectures for ultra-low temperature storage integration. Pharmaceutical facilities in the Netherlands and Denmark face accelerated retrofit deadlines for existing chilled water infrastructure. Semiconductor fabs in Ireland are responding with ammonia-based cooling systems that require specialized containment and detection protocols.
Biopharma procurement departments are unbundling cleanroom construction from long-term consumables supply, separating capital equipment vendors from apparel and cleaning agent contracts previously bundled as turnkey packages. This disintermediation is compressing supplier margins while creating independent sourcing opportunities for specialized garment laundries and sterile wipe manufacturers. The trend is most visible in Massachusetts and North Carolina biotech clusters where operator headcount scaling drives consumables volume volatility.
Global Cleanroom Technologies Market Segmentation
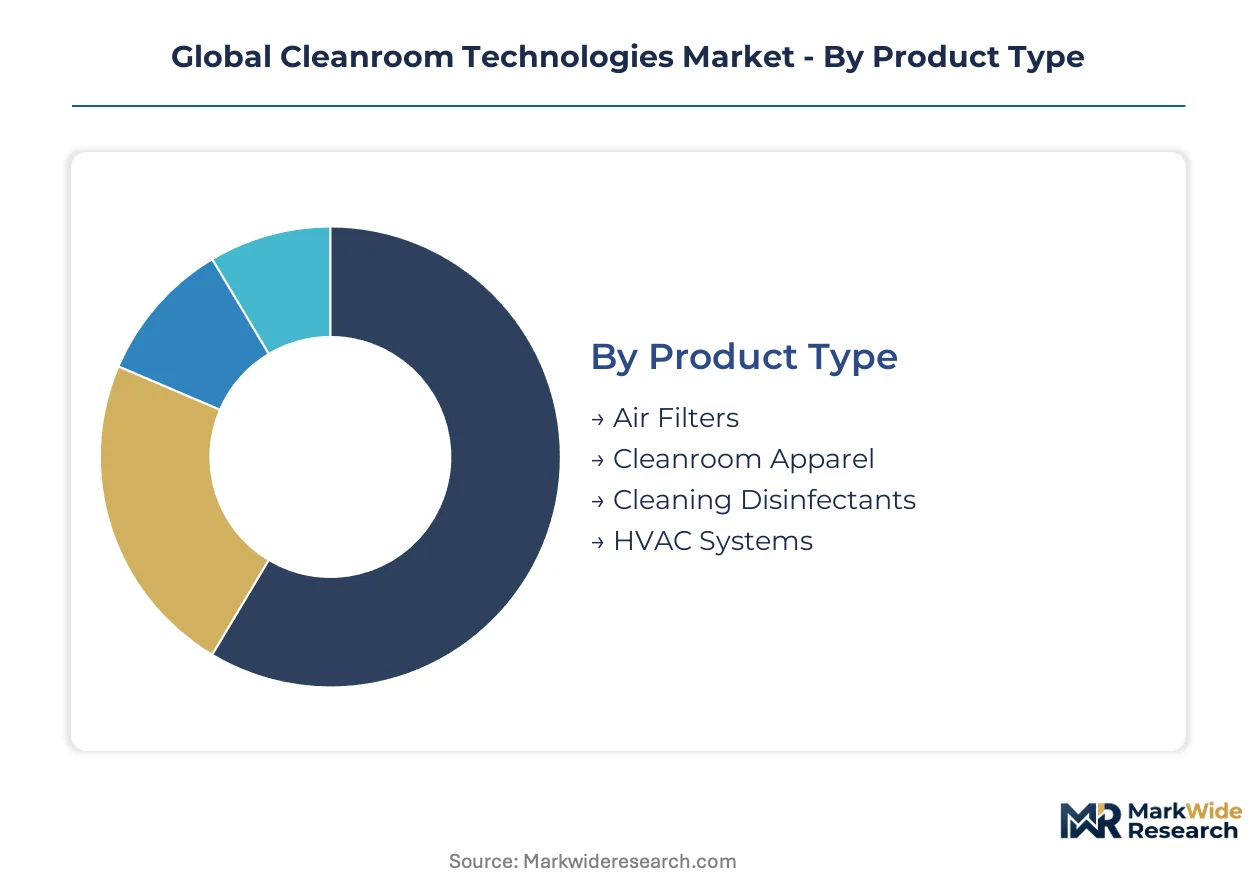
Cleanroom technology purchasing decisions split across capital equipment, consumables, and services with divergent margin profiles and replacement cycles. Segmentation clarity enables vendors to align R&D investment with the highest-value application clusters and regulatory exposure zones.
Product Type:
HVAC Systems face the most acute substitution pressure from modular point-source filtration architectures that bypass central air handling infrastructure in retrofit scenarios.
- HVAC Systems:Central air handling units with laminar flow distribution and temperature-humidity control constitute the largest capital allocation in greenfield pharmaceutical facilities. Demand concentrates in Singapore and Germany where EMA inspections drive redundant filtration upgrades.
- Air Filters:HEPA and ULPA media assemblies with rated efficiencies from 99.97% to 99.9995% capture sub-micron particles through glass fiber or PTFE membranes. Semiconductor fabs in Taiwan and South Korea specify lithography-grade filters with molecular contamination control.
- Cleanroom Apparel:Non-woven polypropylene and Tyvek garments with static-dissipative coatings prevent operator-borne particle shedding in aseptic processing zones.
- Cleaning Disinfectants:Sporicidal agents and sterile alcohol wipes maintain surface bioburden below pharmacopeial limits between production campaigns.
HVAC Systems anchor the volume base while Air Filters gain share at the steepest rate due to shorter replacement intervals and tightening ISO 14644-1 compliance thresholds.
Application:
Cost tier differentiation separates high-capex semiconductor fabs from mid-tier pharmaceutical suites and lower-intensity research environments.
- Semiconductor Production:Wafer lithography and etch processes require ISO Class 1-3 environments with vibration isolation and thermal stability to sub-0.1°C precision. Memory and logic capacity expansion in South Korea and Taiwan drives absolute square footage growth with specialized AMC filtration.
- Pharmaceutical Manufacturing:Sterile drug filling and lyophilization operations mandate EU MDR Annex I compliance with continuous viable particle monitoring. Facilities in Ireland and Italy face intensified EMA inspection protocols driving redundant HEPA architectures.
- Biotech Research:Cell therapy process development and analytical testing require flexible suite configurations for multi-product campaigns.
- Aerospace Engineering:Satellite optical payload integration and propulsion system assembly demand ISO Class 5-7 environments outside traditional manufacturing corridors.
Pharmaceutical Manufacturing anchors the volume base while Semiconductor Production climbs the fastest on absolute capacity expansion and specification compression below ISO Class 3.
End User:
Customer type determines procurement complexity, with electronic manufacturers driving standardization and pharmaceutical companies demanding custom validation documentation.
- Electronic Manufacturers:Foundry operators and memory producers in East Asia specify turnkey cleanroom infrastructure with compressed commissioning timelines. Samsung and TSMC supplier ecosystems concentrate demand in Gyeonggi Province and Hsinchu Science Park.
- Pharmaceutical Companies:Multinational biologics manufacturers and emerging CDMOs in India require modular suites adaptable to personalized medicine batch sizes. CDSCO alignment with ICH Q5A accelerates greenfield investment in Hyderabad and Ahmedabad clusters.
- Healthcare Facilities:Hospital pharmacies and compounding centers face USP 797 and USP 800 compliance deadlines for sterile and hazardous drug preparation.
- Research Laboratories:Academic and government facilities prioritize reconfigurable softwall systems for multi-disciplinary instrumentation sharing.
Electronic Manufacturers anchor the volume base while Pharmaceutical Companies expand most quickly on biologics pipeline growth and regulatory enforcement intensification.
Technology:
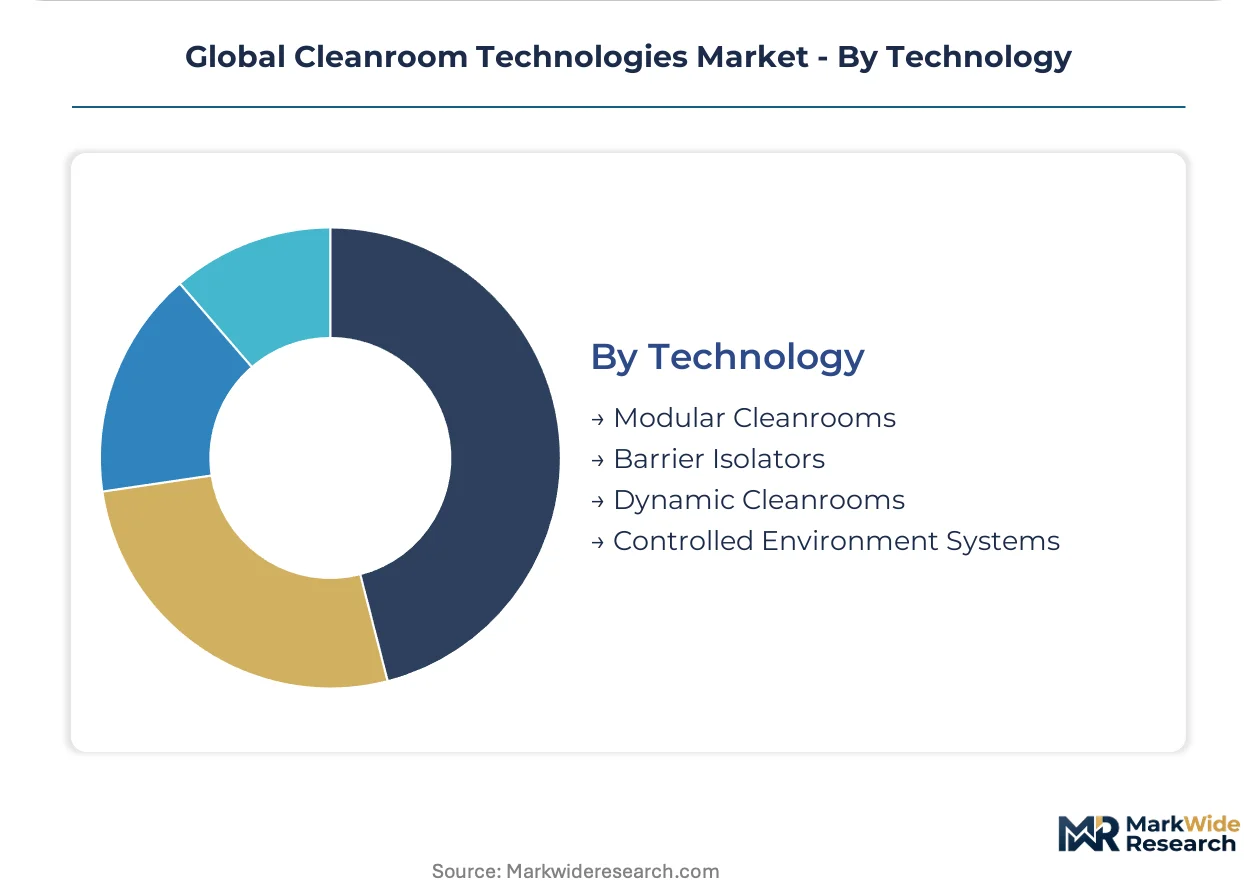
Maturity gradients separate established modular architectures from emerging robotic isolator platforms with higher containment assurance and steeper learning curves.
- Barrier Isolators:Glove-ported or gloveless containment systems separate operators from high-potency compounds through unidirectional airflow and rapid transfer ports. Swiss and US biologics manufacturers adopt hybrid configurations combining human access points with automated material handling.
- Modular Cleanrooms:Prefabricated softwall and hardwall systems enable pharmaceutical tenants to repurpose suites between monoclonal antibody and cell therapy campaigns without greenfield construction.
- Dynamic Cleanrooms:Pressure-cascaded environments with real-time airflow adjustment respond to occupancy and process changes through sensor-fed control algorithms.
- Controlled Environment Systems:Integrated monitoring platforms combining particulate, viable, and environmental parameter tracking into unified data architectures.
Modular Cleanrooms anchor the volume base while Barrier Isolators gain share at the steepest rate on high-potency pharmaceutical containment requirements and specialized validation service attach rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cleanroom deployment patterns diverge sharply by geography. Semiconductor fabs in East Asia demand lithography-grade vibration control and molecular contamination filtration, while pharmaceutical corridors in Europe and North America prioritize modular reconfiguration and barrier isolator containment for multi-product biologics campaigns.
United States
Commercial launch vehicle manufacturers and satellite constellation builders in California and Colorado require ISO Class 5 environments for optical payload integration. FDA current Good Manufacturing Practice enforcement intensifies environmental qualification documentation for sterile drug facilities in Massachusetts and North Carolina. The Greater Boston biotech cluster drives demand for reconfigurable softwall systems that adapt to personalized medicine batch sizes.
Germany
EMA inspections of sterile product facilities sustain replacement demand for redundant HEPA filtration architectures in pharmaceutical manufacturing corridors. The EU F-Gas Regulation phase-down forces ammonia-based cooling retrofits for ultra-low temperature storage integration. Bavaria and North Rhine-Westphalia anchor large-scale pharmaceutical campus projects requiring turnkey facility engineering and documented environmental qualification.
South Korea
Memory and logic wafer capacity expansion in Gyeonggi Province drives absolute cleanroom square footage growth with compressed commissioning timelines. MFDS alignment with ICH Q5A standards accelerates sterile drug facility investment alongside semiconductor foundry concentration. Samsung supplier ecosystems concentrate demand for specialized lithography-grade vibration and thermal stability specifications.
Taiwan
Foundry operators in Hsinchu Science Park specify cleanroom specifications below ISO Class 3 thresholds for advanced node chip production. Export control uncertainty surrounding HVAC componentry exposes lead time volatility for critical fan filter unit motors. The concentrated memory and logic investments create specialized demand for AMC filtration and real-time environmental monitoring integration.
India
CDSCO regulatory alignment with ICH Q5A and PLI scheme incentives for active pharmaceutical ingredients create greenfield demand for turnkey cleanroom infrastructure. Hyderabad and Ahmedabad clusters attract emerging CDMOs requiring modular suites adaptable to cell therapy campaigns. Biologics manufacturing buildout concentrates procurement of barrier isolator systems and continuous particulate monitoring platforms.
Global Cleanroom Technologies Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in cleanroom technology supply. Turnkey facility engineering firms anchor large-scale pharmaceutical campus projects through design-build-operate contracts, while HVAC-integrated delivery specialists compress commissioning timelines for semiconductor fabs. Consumables suppliers sustain pull-through via long-term apparel contracts tied to operator headcount. Competitive moves concentrate on embedding remote diagnostics into equipment architectures and unbundling construction from consumables supply to capture aftermarket service revenue.
Among the integrated facility engineering tier, Exyte AG and Taikisha Ltd. exemplify divergent competitive positioning. Exyte leverages German turnkey heritage to anchor pharmaceutical campus projects requiring documented environmental qualification and redundant filtration architectures. Taikisha represents Japanese HVAC-integrated delivery models that compress commissioning timelines for semiconductor fabrication facilities in East Asia. Kimberly-Clark Corporation occupies a position within consumables supply, sustaining volume relationships through long-term apparel contracts tied to biologics operator headcount scaling.
| Leading Market Players |
|---|
| Exyte AG |
| Kimberly-Clark Corporation |
| DuPont de Nemours Inc. |
| Azbil Corporation |
| Camfil AB |
| Taikisha Ltd. |
| Clean Air Products |
| Terra Universal Inc. |
| Thermo Fisher Scientific Inc. |
| Others |
Supply Flow & Price Mechanics
Twenty-six-week lead times for HEPA media assemblies from Chinese and South Korean suppliers concentrate pricing power with upstream filtration component manufacturers while forcing end-users into long-term offtake commitments that lock in cost structures across multi-year facility campaigns.
Pricing Analysis
Long-term offtake agreements dominate capital equipment procurement for pharmaceutical campus projects, while spot purchasing governs consumables replenishment for cleanroom apparel and disinfectants. Price differentiation rests on ISO 14644-1 certification grade and volume scale, with semiconductor fabs absorbing premium tiers for sub-ISO Class 3 specifications. Cost compression in standard-grade HVAC systems is intensifying because modular point-source filtration architectures displace central air handling in retrofit scenarios. Electronic manufacturers in East Asia exhibit lowest price sensitivity due to compressed commissioning timelines, while emerging CDMOs in India negotiate aggressively on turnkey packages.
Supply Chain Analysis
China and South Korea anchor production of critical fan filter unit motors and HEPA media substrates, with Taiwan concentrating lithography-grade vibration isolation componentry. The supply chain draws from glass fiber and PTFE membrane feedstocks, specialized polymer molding for glove-port fabrication, and precision motor windings. Single-source vulnerability around East Asian HVAC componentry exposes lead time volatility to export control friction and geopolitical uncertainty. Distribution runs through turnkey facility engineering contractors for pharmaceutical greenfield projects and direct OEM procurement for semiconductor fab expansions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cleanroom technologies market sits as a high-growth disruption as EU MDR Annex I sterility mandates and advanced node semiconductor specification compression below ISO Class 3 thresholds simultaneously reshape equipment architectures and service models.
For Market Incumbents: Compound aftermarket service revenue by embedding IoT-enabled predictive maintenance into fan filter unit architectures, offsetting margin erosion from unbundled consumables contracts. Prioritize certification investment in barrier isolator glove-port fabrication capacity to capture high-margin pharmaceutical containment demand. Defend against modular point-source filtration substitutes by anchoring long-term facility engineering contracts with documented environmental qualification protocols. For New Entrants and Emerging Players: Lead with remote diagnostics platforms targeting brownfield pharmaceutical sites in Germany and Switzerland confronting legacy HVAC integration gaps. White-space opportunities concentrate in India's biologics manufacturing buildout, where CDSCO regulatory alignment with ICH Q5A accelerates demand for turnkey modular suites. Position through design-build-operate contracts that bundle commissioning acceleration with continuous compliance monitoring. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because FDA and EMA enforcement intensification sustains replacement demand for redundant filtration architectures and real-time viable particle detection systems. Target acquisition profiles favor specialized containment engineering firms with validated glove-port fabrication capabilities and pharmaceutical customer concentration. Watch for inflection signals in India PLI scheme disbursement rates and East Asian export control escalation severity.| Strategic Initiative | Industry Significance |
|---|---|
| Remote Diagnostics Platform Integration | Transforms aftermarket service from scheduled maintenance to condition-based revenue models for fan filter units. |
| Barrier Isolator Capacity Expansion | Captures high-margin pharmaceutical containment demand driven by high-potency compound pipeline growth. |
| Modular Cleanroom Manufacturing Scale-Up | Enables rapid suite reconfiguration for cell therapy campaigns without greenfield construction delays. |
| India Turnkey Facility Engineering Entry | Positions for CDSCO-aligned biologics infrastructure buildout in Hyderabad and Ahmedabad clusters. |
| Natural Refrigerant Cooling Retrofit | Addresses EU F-Gas Regulation phase-down deadlines for pharmaceutical ultra-low temperature storage integration. |
Methodological Framework
Cross-validation between primary interviews with cleanroom facility engineers, pharmaceutical quality assurance directors, semiconductor fab operations managers, and HVAC procurement leads and secondary validation through EMA inspection databases, FDA 483 observation filings, ISO 14644-3 test method documentation, and SEC equipment supplier disclosures anchors the qualitative findings. Bottom-up triangulation aggregates facility-level capacity expansion announcements and greenfield project pipelines, while top-down validation cross-checks against regulatory enforcement trend analysis and industry association capital expenditure surveys.
Sensitivity analysis around semiconductor foundry concentration risk and pharmaceutical technician scarcity scenarios shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, end user, and technology maturity tier alongside regional regulatory cluster intensity. CAGRs derive from facility square footage expansion rates, replacement cycle compression, and aftermarket service attach rate evolution. Forecast inputs incorporate EU MDR implementation timeline phasing and East Asian HVAC componentry lead time volatility.
The analysis sits within stated boundaries; outcomes outside sustained EMA inspection intensification and advanced node semiconductor capacity expansion would require recalibration. Forecasts reflect assumptions around regulatory enforcement continuity, supply chain geographic concentration persistence, and modular architecture adoption velocity. Recalibration cycles align with material shifts in FDA warning letter issuance patterns, export control regime changes, and biologics pipeline personalization trends.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Wafer Processing Equipment Market
Semiconductor Equipment
I-Line Lithography Market
Semiconductor Equipment
Underfill Dispenser Market
Semiconductor Equipment
Solder Ball Mounter Market
Semiconductor Equipment
Vacuum Coating Equipment Market
Semiconductor Equipment
India Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Lithographic Photomasks Market
Semiconductor Equipment
Laser Annealing System Market
Semiconductor Equipment
300 Mm Front Opening Unified Pods (Foups) Market
Semiconductor Equipment
Global Semiconductor Etch Equipment Market
Semiconductor Equipment
Dicing Equipment Market
Semiconductor Equipment
Automatic Mounter Wafer Equipment Market
Semiconductor Equipment
Semiconductor Process and Control Equipment Market
Semiconductor Equipment
Asia-Pacific Aligner Sheet Market
Semiconductor Equipment
Quantum Annealing Equipment Market
Semiconductor Equipment
Acid Filling and Leveling Machine Market