
 Semiconductor CVD Equipment Market | 2026-2036
Semiconductor CVD Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor CVD Equipment Market Analytics
Buyer concentration across foundries and memory houses is rebalancing toward a handful of capital-intensive producers with multi-billion dollar fab commitments. Applied Materials, Inc. leverages its breadth across deposition, etch, and metrology to sustain integrated tool pull-through. Lam Research Corporation anchors its position through etch-CVD co-optimization for advanced logic nodes. Tokyo Electron Limited competes with differentiated chamber architectures serving both DRAM and 3D NAND transitions.
Semiconductor CVD equipment encompasses vacuum chambers, gas delivery subsystems, and thermal or plasma-based reaction modules that deposit thin films with angstrom-level precision onto silicon wafers. These systems operate at pressures ranging from atmospheric to ultra-high vacuum, with substrate temperatures typically spanning 300°C to 1100°C depending on film chemistry and conformality requirements. Single-wafer systems command premium positioning for leading-edge logic where uniformity tolerances tighten below one percent, while batch systems retain cost advantages in trailing-node and power device production. Plasma enhanced CVD technology leads in low-temperature dielectric applications, whereas atomic layer deposition variants capture margin pools in high-aspect-ratio memory cell stacks.
EPA regulates hazardous air emissions from semiconductor fabs under the National Emission Standards for Hazardous Air Pollutants, while REACH restricts perfluorinated compounds used in CVD chamber cleaning. Japan's METI enforces energy efficiency standards on production equipment imports. Stakeholders must monitor evolving chemical restriction lists and dual-use export controls as these determine eligible process chemistries and installed base upgrade cycles.
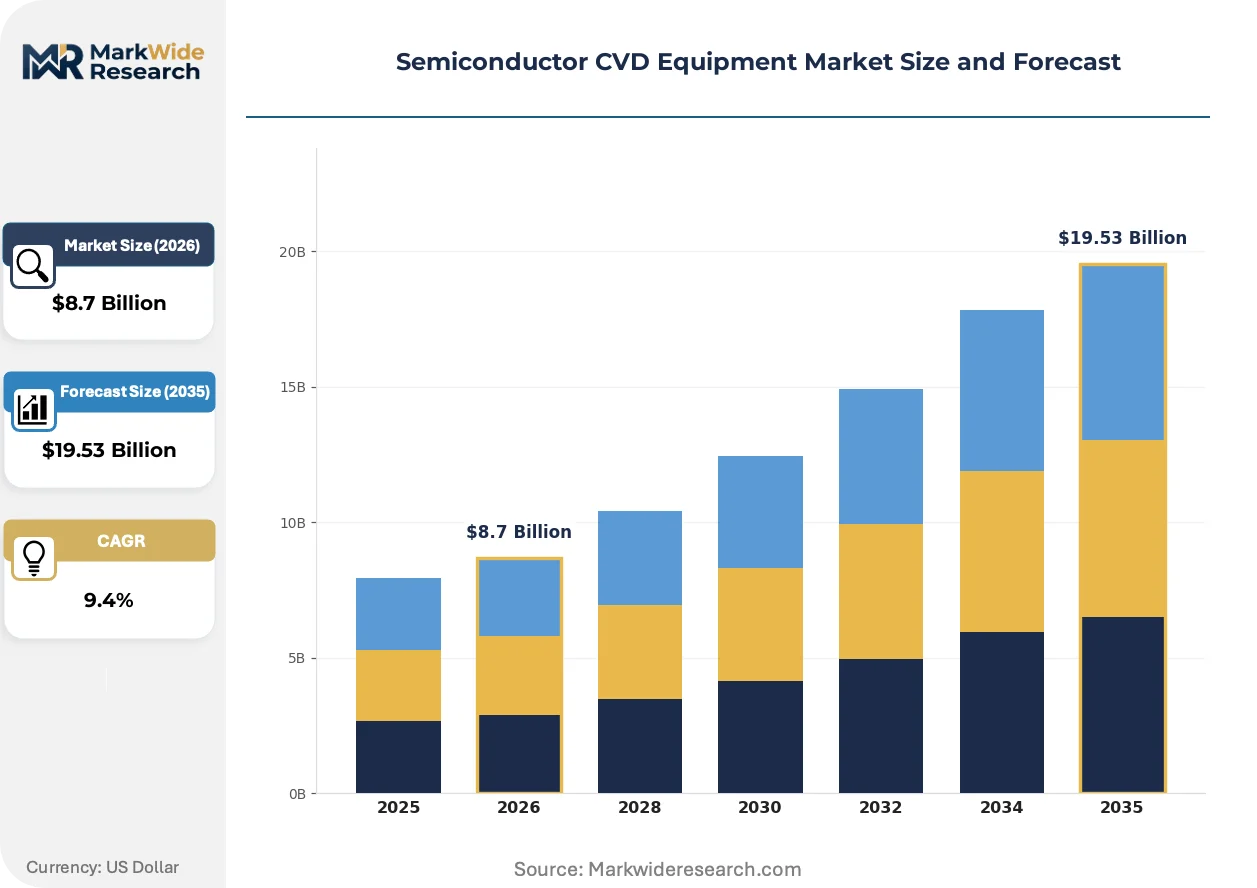
Market Dynamics
High-bandwidth memory stack architectures are compressing deposition cycle times while EPA and REACH chemical restrictions force simultaneous process chemistry overhauls, creating a dual-vector squeeze on equipment refresh cycles.
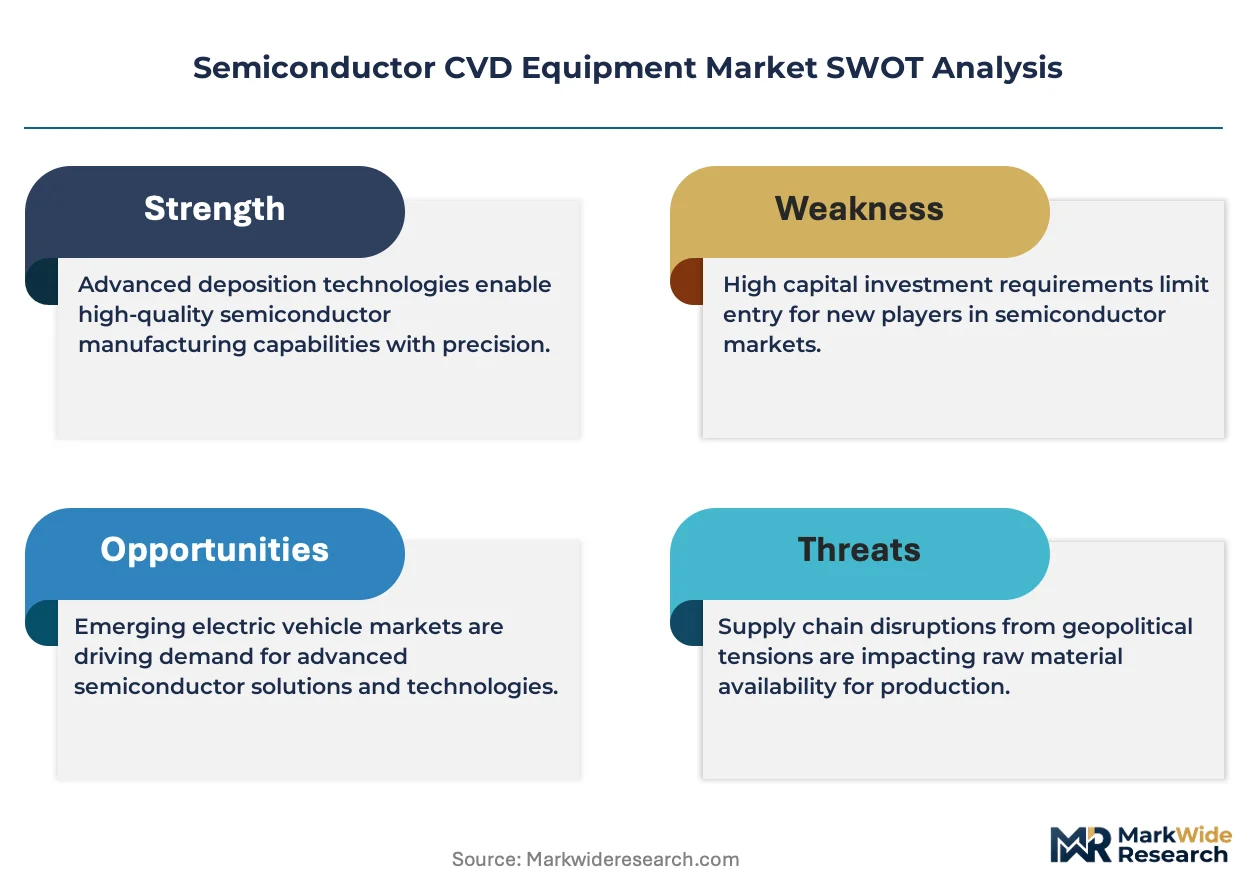
Growth Catalysts
- 3D NAND vertical scaling:Memory manufacturers in South Korea and Taiwan are expanding fab capacity for 200-plus layer cell stacks, pulling atomic layer deposition variants into high-volume production.
- EPA NESHAP compliance deadlines:Hazardous air pollutant rules are accelerating chamber replacement schedules among US-based logic foundries.
- Plasma-enhanced CVD dielectric demand:Low-temperature dielectric applications for advanced packaging interconnects are expanding equipment utilization rates.
Market Restraints
- Fluorinated gas supply concentration:Perfluorinated compound feedstock for chamber cleaning chemistry concentrates among Japanese and Belgian specialty gas suppliers, exposing fabs to input cost volatility.
- Sub-1% uniformity tolerance:Leading-edge logic nodes demand film thickness control beyond current batch system capabilities, forcing premature single-wafer system obsolescence.
- REACH authorization delays:ECHA chemical restriction list expansions are freezing process chemistry qualifications for European memory fabs.
Strategic Opportunities
- Power device trailing-node batch retrofit:Silicon carbide and gallium nitride foundries in Germany and Austria present untapped demand for refurbished atmospheric pressure CVD systems.
- Japan METI energy efficiency standards:Import equipment mandates are creating preferential market access for thermal management-optimized chamber architectures.
- ALD-CVD hybrid process convergence:Conformal film deposition for high-aspect-ratio DRAM capacitors is opening integrated tool configurations previously separated by technology silos.
Industry Challenges
- Process engineer scarcity:Plasma physics and thin-film chemistry expertise pools concentrate among veteran technicians at South Korean and Taiwanese equipment vendors, constraining fab ramp timelines elsewhere.
- Legacy system integration friction:New single-wafer platforms must interface with 200mm-era factory automation standards still prevalent at analog and power semiconductor facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor CVD Equipment Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Systems, Single-wafer Systems, Plasma Enhanced Systems, Low Pressure Systems Technology: Chemical Vapor Deposition, Atomic Layer Deposition, Hybrid CVD, Metal-Organic CVD End User: Foundries, Memory Manufacturers, Integrated Device Manufacturers, Research Institutions Application: Thin Film Deposition, Surface Modification, Coating, Material Synthesis |
| Companies Covered | Applied Materials, Inc., Lam Research Corporation, Tokyo Electron Limited, Aixtron SE, ASM International, Veeco Instruments Inc., KLA Corporation, Oxford Instruments PLC, ULVAC Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor CVD Equipment Market Evolving Landscape
Equipment architectures are bifurcating between atomic-scale precision systems for memory cell stacks and throughput-optimized platforms for power device epitaxy, with regulatory chemistry constraints forcing concurrent process innovation.
Remote plasma source technology is electrifying low-temperature dielectric deposition by decoupling ion generation from wafer exposure, enabling sub-400°C processing for thermally sensitive advanced packaging substrates. OSATs and interposer manufacturers are adopting these sources faster than historical equipment replacement cycles. The structural consequence is compressing thermal budget constraints that previously dictated material selection.
EPA's National Emission Standards for Hazardous Air Pollutants are tightening perfluorinated compound venting limits, forcing fabs to install point-of-use abatement on existing CVD clusters rather than await full tool replacement. The industrial consequence is diverting capital toward emissions control retrofits. Logic foundries in Arizona and Texas are responding fastest due to state-level air quality implementation timelines.
After-sales service unbundling is fragmenting long-term equipment contracts, with foundries negotiating chamber refurbishment and spare parts procurement separately from original system purchases. Equipment vendors are responding with modular service tiering. This pattern is most visible among Taiwanese memory houses managing multi-vendor installed bases.
Semiconductor CVD Equipment Market Segmentation
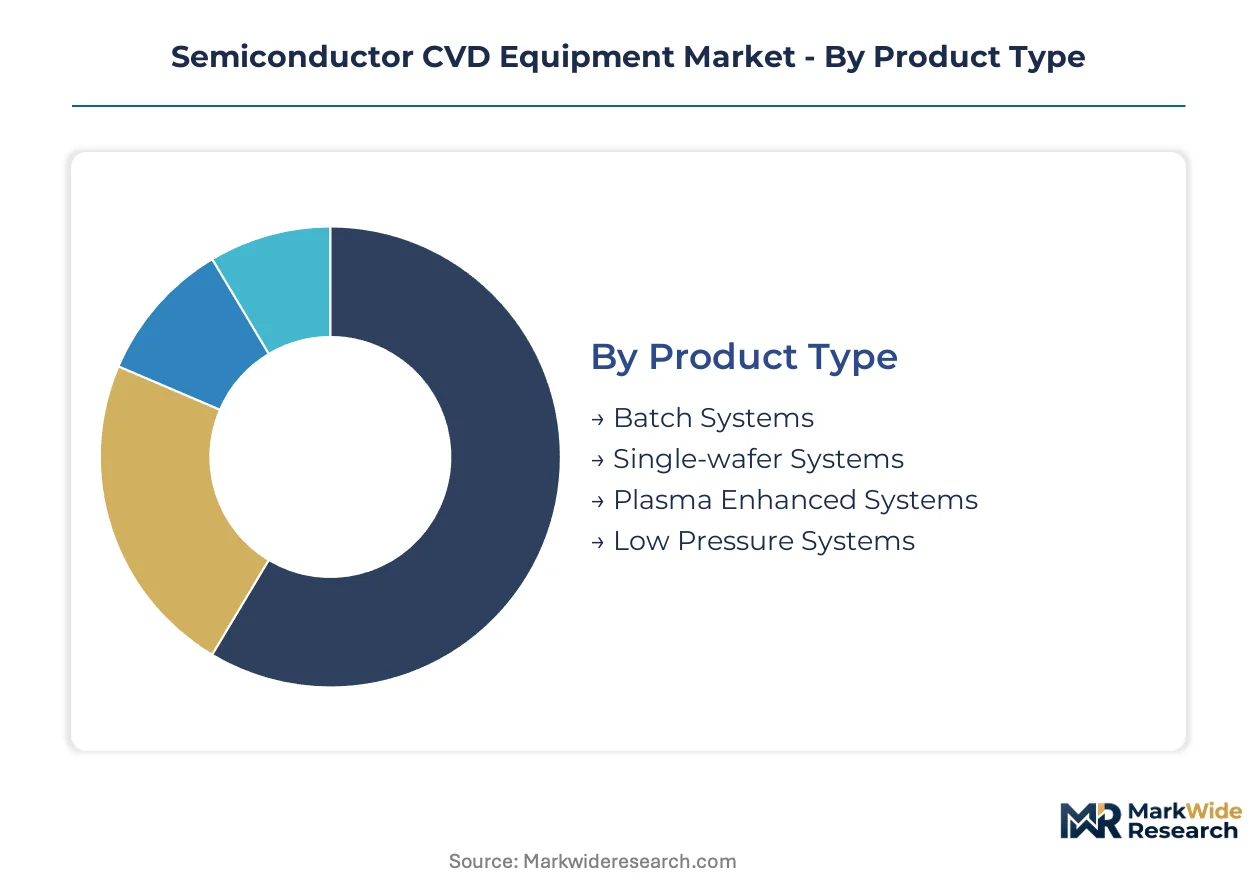
Equipment segmentation in the Semiconductor CVD Equipment Market determines capital allocation priorities across fabs with divergent process node requirements. Memory manufacturers prioritize conformality precision, while foundries balance uniformity against throughput economics.
Product Type:
Capital intensity varies sharply across chamber architectures, with single-wafer platforms commanding the highest upfront investment per unit of wafer throughput.
- Batch Systems:Multi-wafer processing chambers deposit films across 25-50 substrates simultaneously, sacrificing uniformity for cost efficiency. Demand concentrates at German and Austrian silicon carbide foundries serving automotive power modules, constrained by trailing-node automation compatibility.
- Single-wafer Systems:Individual substrate processing enables sub-1% thickness uniformity required for leading-edge logic nodes below 7nm. South Korean and Taiwanese foundries absorb the majority of new installations, driven by advanced node ramp schedules and EPA NESHAP compliance deadlines.
- Plasma Enhanced Systems:Low-temperature dielectric deposition for advanced packaging interconnects at OSATs in Taiwan and Malaysia.
- Low Pressure Systems:Epitaxial silicon deposition for power device manufacturing at trailing-node facilities.
Most installed capacity flows through batch systems. Expansion is steepest in single-wafer systems.
Technology:
Process chemistry compatibility with tightening EPA and REACH restrictions is reshaping technology selection across memory and logic fabs.
- Chemical Vapor Deposition:Conventional thermal CVD deposits silicon dioxide, silicon nitride, and polysilicon films through gas-phase reactions at 600-1100°C. Taiwanese memory houses dominate equipment utilization, though fluorinated gas abatement costs are compressing margins.
- Atomic Layer Deposition:Self-limiting surface reactions achieve atomic-scale thickness control for high-aspect-ratio 3D NAND cell stacks. South Korean manufacturers in Hsinchu and Pyeongtaek clusters drive demand, pulled by 200-plus layer vertical scaling roadmaps.
- Hybrid CVD:Integrated ALD-CVD sequences for DRAM capacitor conformality at sub-10nm nodes.
- Metal-Organic CVD:Compound semiconductor epitaxy for gallium nitride RF devices at defense contractors.
Conventional CVD retains the largest installed base. ALD is gaining share fastest among memory transitions.
End User:
Customer concentration is tilting toward capital-intensive producers with multi-billion dollar fab commitments.
- Foundries:Merchant logic manufacturers operate CVD clusters across deposition, etch, and metrology modules for advanced node production. Arizona and Texas facilities are accelerating chamber replacements ahead of state-level EPA implementation timelines.
- Memory Manufacturers:DRAM and 3D NAND producers in South Korea and Taiwan deploy atomic layer deposition variants for cell stack conformality. High-bandwidth memory architectures are compressing deposition cycle times while forcing simultaneous chemistry overhauls.
- Integrated Device Manufacturers:Captive analog and power semiconductor facilities with mixed-node requirements.
- Research Institutions:University and national laboratory pilot lines for process development.
Foundries command the largest equipment procurement volumes. Memory manufacturers are expanding most quickly.
Application:
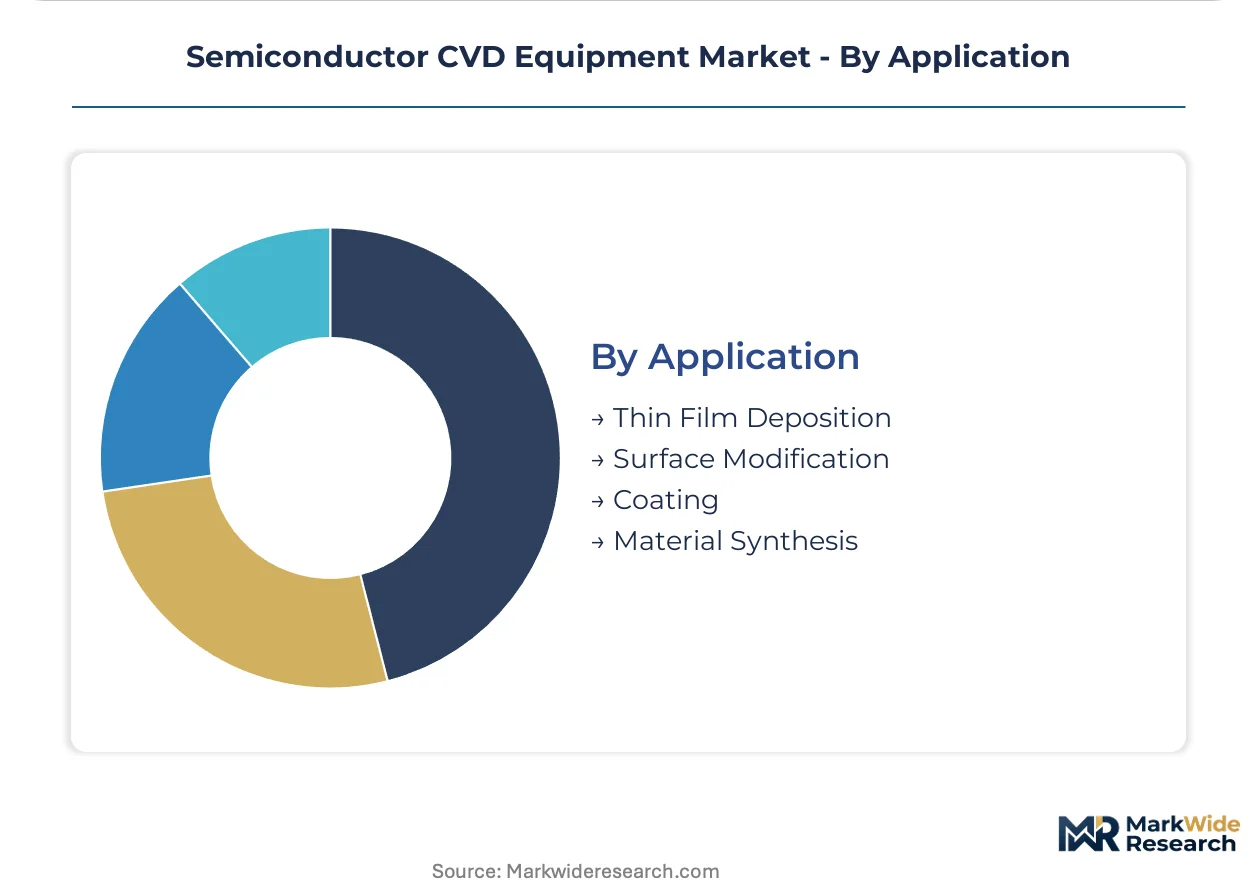
Functional requirements diverge between precision-critical memory cell formation and throughput-driven power device epitaxy.
- Thin Film Deposition:Dielectric, metal, and semiconductor layer formation constitutes the core revenue application for CVD equipment. Leading-edge logic nodes below 5nm in Taiwan and South Korea drive single-wafer system premiums, constrained by sub-1% uniformity tolerances.
- Surface Modification:Plasma-based treatments alter substrate surface energy and chemical reactivity prior to subsequent processing. Advanced packaging substrates from OSATs in Malaysia and Singapore are adopting remote plasma sources faster than historical replacement cycles.
- Coating:Protective and functional film deposition for MEMS and sensor devices.
- Material Synthesis:Novel compound semiconductor formation at research and pilot-scale facilities.
Thin film deposition absorbs the majority of equipment shipments. Surface modification is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plasma physics and thin-film chemistry expertise pools concentrate among veteran technicians at South Korean and Taiwanese equipment vendors, constraining fab ramp timelines elsewhere while anchoring regional competitive positioning.
South Korea
Memory manufacturers in Pyeongtaek and Hsinchu clusters are expanding fab capacity for 200-plus layer 3D NAND cell stacks, pulling atomic layer deposition variants into high-volume production. The Ministry of Trade, Industry and Energy enforces energy efficiency standards on production equipment imports. Samsung and SK Hynix facilities in the Seoul Capital Area are compressing deposition cycle times for high-bandwidth memory architectures.
Taiwan
Foundries in Hsinchu Science Park absorb the majority of new single-wafer system installations, driven by advanced node ramp schedules below 7nm. The Environmental Protection Administration implements hazardous air pollutant rules that accelerate chamber replacement schedules. TSMC and UMC facilities across Tainan and Taichung are negotiating chamber refurbishment contracts separately from original system purchases.
United States
Logic foundries in Arizona and Texas are accelerating chamber replacements ahead of state-level EPA NESHAP implementation timelines. The Environmental Protection Agency regulates hazardous air emissions from semiconductor fabs under National Emission Standards for Hazardous Air Pollutants. Intel and GlobalFoundries facilities in the Southwest and Northeast Corridor are installing point-of-use abatement on existing CVD clusters.
Japan
Specialty gas suppliers in Osaka and Tokyo prefectures dominate perfluorinated compound feedstock for chamber cleaning chemistry. The Ministry of Economy, Trade and Industry enforces energy efficiency standards on production equipment imports. Tokyo Electron and ULVAC facilities in the Kanto region are optimizing thermal management-optimized chamber architectures for preferential market access.
Germany
Silicon carbide and gallium nitride foundries in Bavaria and Baden-Württemberg present demand for refurbished atmospheric pressure CVD systems. The European Chemicals Agency REACH regulation restricts perfluorinated compounds used in CVD chamber cleaning. Bosch and Infineon facilities in Dresden and Regensburg are retrofitting trailing-node batch systems for automotive power modules.
Semiconductor CVD Equipment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across deposition, etch, and metrology modules. The vendor base separates into three tiers: integrated platform providers spanning multiple process steps, chamber architecture specialists serving memory transitions, and regional equipment fabricators capturing trailing-node retrofits. Competitive moves concentrate on strategic partnerships for process co-optimization and geographic expansion into European power device foundries.
Within the integrated platform tier, Applied Materials, Inc. and Lam Research Corporation occupy positions exemplifying breadth across deposition and etch modules. Tokyo Electron Limited anchors the chamber architecture specialist archetype serving both DRAM and 3D NAND transitions. These three entities represent the dominant competitive anchors against which regional specialists and retrofit providers position their offerings.
| Leading Market Players |
|---|
| Applied Materials, Inc. |
| Lam Research Corporation |
| Tokyo Electron Limited |
| Aixtron SE |
| ASM International |
| Veeco Instruments Inc. |
| KLA Corporation |
| Oxford Instruments PLC |
| ULVAC Inc. |
| Others |
Value Network & Pricing Analysis
Captive gas delivery subsystem production in Japan and Belgium anchors both supply security and pricing power for chamber cleaning chemistry, creating tiered cost structures that propagate through fab operating expenditures. Equipment vendors with in-house thermal management architectures command premium positioning against outsourced competitors facing METI compliance cost adders.
Pricing Analysis
Capacity additions in South Korea and Taiwan are reshaping price floors for single-wafer systems as foundries negotiate unbundled service contracts separately from original equipment purchases. Three-tier pricing structure across premium, standard, and economy levels stratifies by uniformity tolerance and after-sales bundling intensity. Cost compression in batch system retrofits is intensifying because silicon carbide foundries in Germany and Austria prioritize refurbished atmospheric pressure platforms over new capital deployment. Memory manufacturers in Pyeongtaek and Hsinchu clusters demonstrate lowest price sensitivity due to high-bandwidth memory architecture deadlines, while analog IDMs in trailing-node facilities exhibit highest sensitivity to chamber refurbishment economics.
Supply Chain Analysis
Japan's domestic-content mandates for energy-efficient equipment imports are reshaping sourcing patterns for thermal management-optimized chamber architectures. Component fabrication concentrates in Japan, South Korea, and the United States for vacuum chambers, gas delivery subsystems, and plasma generation modules. Feedstock for fluorinated chamber cleaning chemistry draws from Osaka and Tokyo prefecture specialty gas suppliers, creating single-source vulnerability for European fabs under REACH authorization delays. Distribution runs through direct vendor-fab relationships with long-term service agreements, supplemented by regional refurbishment centers in Taiwan and Arizona.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor CVD equipment functions as a stable compounder anchored by irreversible node transitions below 7nm that mandate systematic chamber refresh cycles regardless of cyclical memory pricing.
For Market Incumbents: Extend chamber architecture roadmaps to capture ALD-CVD hybrid process convergence for high-aspect-ratio DRAM capacitors, locking in integrated tool configurations before technology silos dissolve. Deepen backward integration into gas delivery subsystems to offset fluorinated compound feedstock volatility from Japanese and Belgian suppliers. Prioritize thermal management R&D investments that satisfy METI import standards while creating switching costs for foundries in Hsinchu Science Park. For New Entrants and Emerging Players: Silicon carbide foundries in Bavaria and Baden-Württemberg represent an underserved buyer archetype seeking refurbished atmospheric pressure CVD systems for automotive power module production. Target trailing-node batch retrofit demand in German and Austrian power semiconductor clusters where legacy 200mm automation compatibility constraints exclude leading-edge platform vendors. Pursue OEM partnerships with regional equipment fabricators to bypass direct competition with integrated platform providers in advanced logic segments. For Investors and Strategic Acquirers: Roll-up economics work for regional chamber refurbishment specialists because after-sales service unbundling is fragmenting long-term contracts and creating modular procurement opportunities. The 5-10 year viability window favors acquisition targets with established spare parts logistics in Taiwanese memory house supply chains. Monitor EPA NESHAP implementation timelines in Arizona and Texas as the signal for accelerated capital deployment into point-of-use abatement retrofit providers.| Strategic Initiative | Industry Significance |
|---|---|
| Chamber Architecture Roadmap Extension | Captures ALD-CVD hybrid demand from Samsung and SK Hynix memory transitions. |
| Backward Integration into Gas Delivery Subsystems | Reduces exposure to Osaka and Tokyo prefecture specialty gas supply concentration. |
| Thermal Management R&D Investment | Unlocks preferential METI certification for equipment imports into Japanese fabs. |
| Regional Refurbishment Center Expansion | Captures unbundled service procurement from TSMC and UMC multi-vendor installed bases. |
| Point-of-Use Abatement Retrofit Deployment | Addresses EPA NESHAP compliance deadlines for Intel and GlobalFoundries Arizona facilities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fab process engineers, equipment vendor sales directors, specialty gas procurement leads, and EPA regulatory affairs specialists with secondary validation. SEC 10-K filings from deposition equipment manufacturers, customs data on fluorinated compound imports, METI energy efficiency certification databases, and ECHA REACH authorization status registers provided foundational inputs. Bottom-up wafer demand modeling and top-down fab capital expenditure triangulation anchored volume estimates.
Historical reference periods spanning pre-pandemic through current cycle peaks established baseline utilization rates and replacement cadences across the projection horizon. The analytical framework modeled equipment type, process technology, end-user category, and application function as core segmentation dimensions, with regional regulatory cluster and automation compatibility tier as industry-specific overlays. CAGRs derived from equipment shipment trajectories and fab construction pipelines incorporated atomic layer deposition penetration curves and EPA compliance-driven replacement elasticities as key forecast inputs.
Underlying measurement precision varies by segment; single-wafer system forecasts for leading-edge logic carry tighter precision than batch system projections for trailing-node power devices due to visibility into TSMC and Samsung announced fab schedules. Forecasts reflect documented assumptions regarding node transition timelines and regulatory implementation dates, with revision risk concentrated in REACH authorization delays for European memory fabs and potential METI standard tightening. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Wire Bonder Equipment Market
Semiconductor Equipment
Africa Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
SMT Machine Market
Semiconductor Equipment
Temperature Calibration Equipment Market
Semiconductor Equipment
Automatic Laser PCB Depaneling Machines Market
Semiconductor Equipment
Global Wafer Processing and Assembly Equipment Market
Semiconductor Equipment
DUV Lithography Systems Market
Semiconductor Equipment
Laser Annealing System Market
Semiconductor Equipment
Slide Processing System Market
Semiconductor Equipment
Vacuum Soldering System Market
Semiconductor Equipment
Thin Wafer Processing and Dicing Equipment Market
Semiconductor Equipment
Pulsed Laser Deposition Systems Market
Semiconductor Equipment
Global Sputtering Equipment Market
Semiconductor Equipment
Nanoimprint Lithography System Market
Semiconductor Equipment
SMT Reflow Soldering Equipment Market
Semiconductor Equipment
Photolithography Equipment Market