
 Asia-Pacific Semiconductor Manufacturing Equipment Market | 2026-2036
Asia-Pacific Semiconductor Manufacturing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Semiconductor Manufacturing Equipment Market Analysis
Advanced node specifications is bifurcating the Asia-Pacific semiconductor manufacturing equipment landscape into leading-edge and trailing-edge supply tiers. Applied Materials Inc leverages its materials engineering breadth to sustain dominance in atomic layer deposition systems. Tokyo Electron Ltd anchors its position through etch and clean equipment specialization for 3nm processes. ASML Holding NV controls the extreme ultraviolet lithography segment where no alternative supplier exists.
Semiconductor manufacturing equipment encompasses the precision machinery used to fabricate, assemble, test, and package integrated circuits on silicon wafers, operating at tolerances measured in angstroms with vacuum environments and plasma-based processes essential for transistor formation. Wafer fabrication equipment commands the largest value share as foundries in Taiwan and South Korea deploy billion-dollar tool lines for sub-5nm production. Test equipment exhibits the fastest structural expansion due to heterogeneous integration complexity in chiplets and 3D stacking architectures. Assembly and packaging equipment captures concentrated margin pools as advanced packaging shifts from wire bonding to flip-chip and fan-out wafer-level formats.
Japan's METI subsidizes domestic equipment makers through the Semiconductor and Digital Industry Strategy, while China's MIIT enforces GB standards and localization quotas that redirect procurement toward domestic suppliers like ACM Research Inc. South Korea's K-Belt strategy and Taiwan's National Science and Technology Council funding shape fab expansion timelines and equipment certification requirements. Stakeholders must monitor how export control alignments between Washington, Tokyo, and Seoul reshape tool availability for Chinese memory and logic fabs.
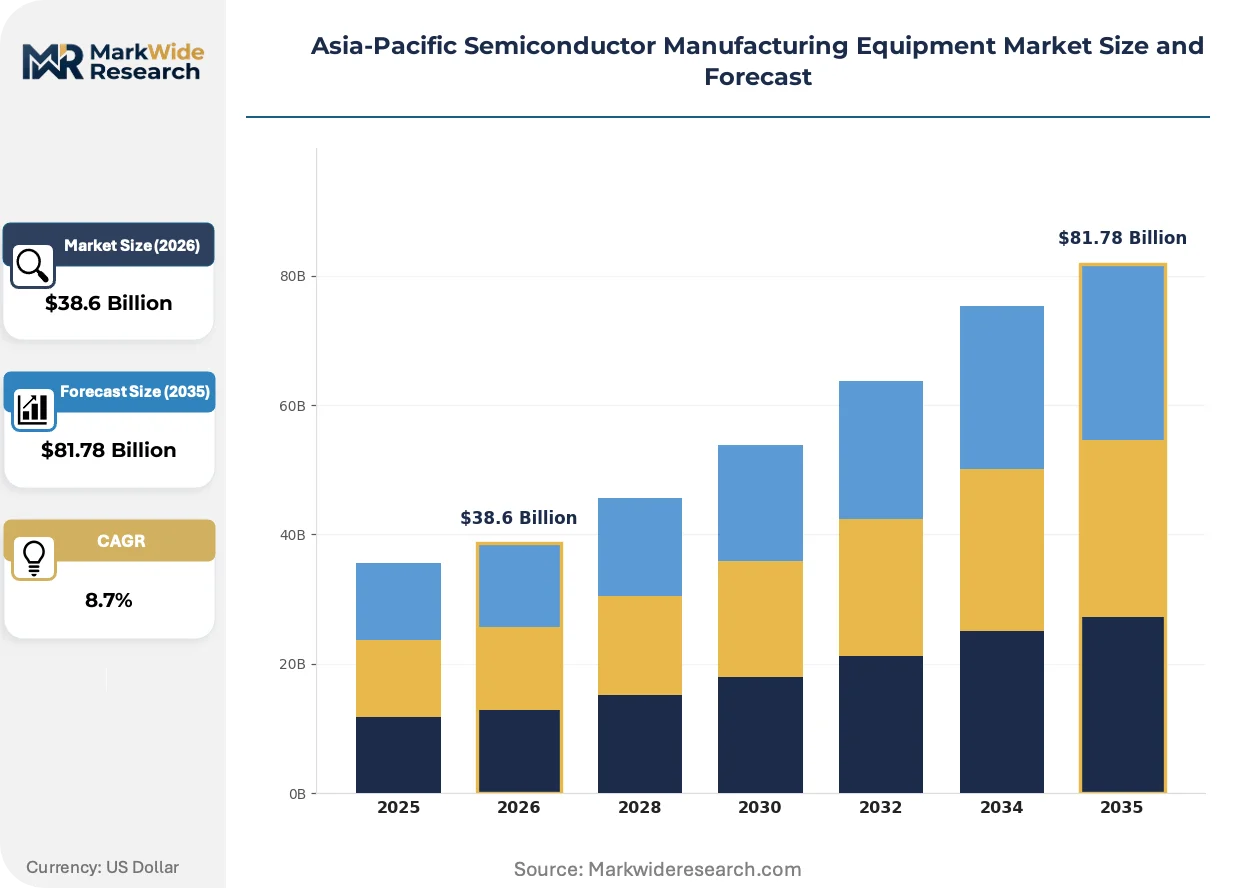
Market Dynamics
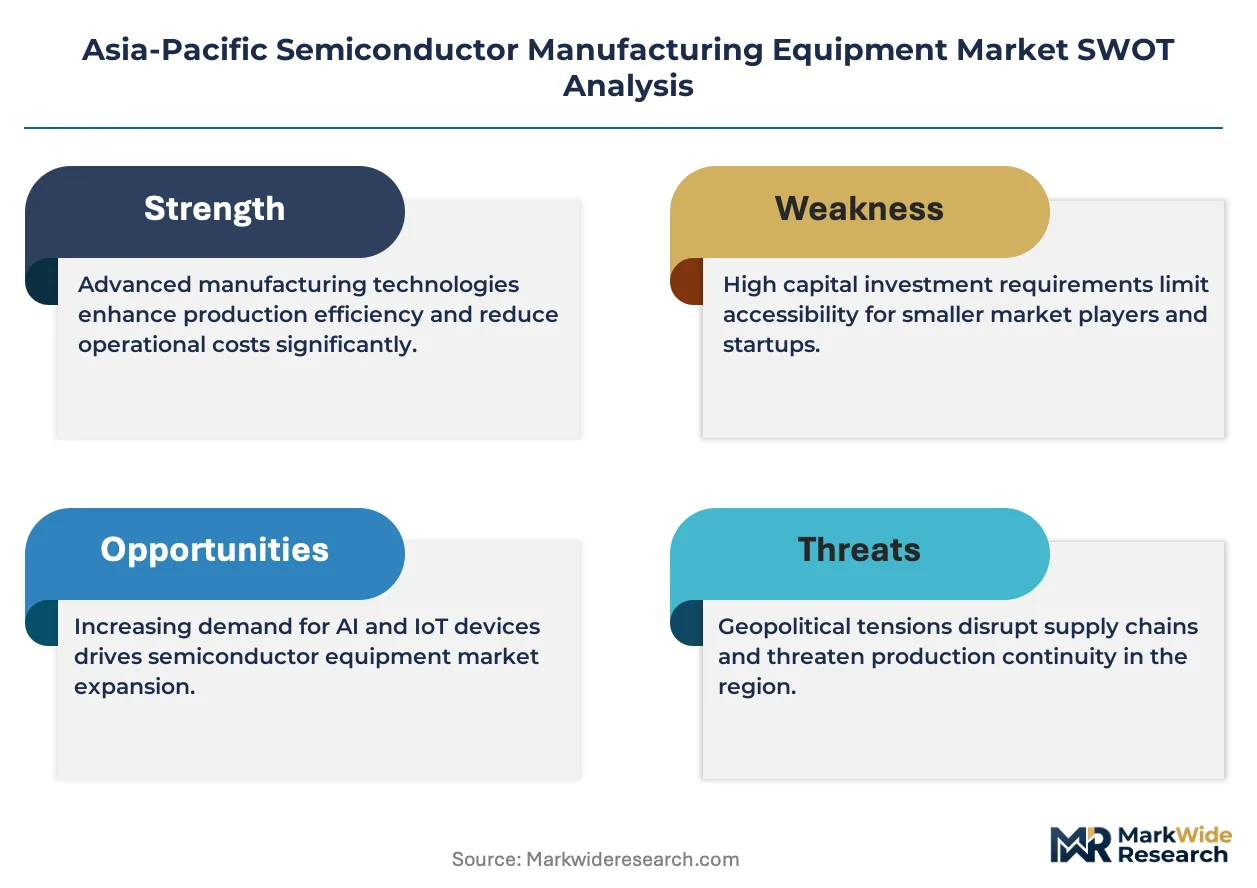
Advanced node migration below 3nm is fragmenting equipment demand between leading-edge foundries in Taiwan and South Korea and trailing-edge legacy fabs across Southeast Asia, creating divergent procurement cycles and certification requirements.
Growth Catalysts
- Sub-5nm Logic Capacity:Taiwan Semiconductor Manufacturing and Samsung Foundry are commissioning multi-billion-dollar tool lines for 2nm pilot production, pulling in atomic layer deposition and extreme ultraviolet lithography systems.
- Japan's METI Semiconductor Strategy:Subsidies under the Semiconductor and Digital Industry Strategy are reshoring equipment component manufacturing to Kyushu and Tohoku clusters.
- China's Localization Mandates:MIIT-enforced GB standards and procurement quotas for domestic etch and clean equipment are redirecting fab capital expenditure toward certified local suppliers.
Market Restraints
- Neon Gas Supply Concentration:Ukrainian and Russian neon purification facilities historically supplied over half of semiconductor-grade neon for laser lithography, creating input cost volatility since supply chain reconfiguration began.
- Extreme Ultraviolet Monopoly:Single-source dependency for high-numerical-aperture EUV scanners limits foundry expansion timelines and creates concentration risk in Veldhoven's supply chain.
- Export Control Alignment:Coordinated restrictions between Washington, Tokyo, and Seoul on deposition and etch tools are constraining equipment availability for Chinese memory fabs.
Strategic Opportunities
- Vietnam and Malaysia Fab Investment:Intel and Amkor are expanding advanced packaging capacity in Ho Chi Minh City and Penang, creating demand for flip-chip bonders and fan-out wafer-level equipment.
- Compound Semiconductor Convergence:Silicon carbide and gallium nitride power device manufacturing is merging with legacy silicon processes, opening equipment retrofit markets.
- South Korea's K-Belt Incentives:Tax credits and accelerated depreciation for domestic equipment procurement are incentivizing Samsung and SK Hynix to qualify local deposition tool suppliers.
Industry Challenges
- Atomic-Scale Process Engineering Talent:Shortages of plasma physics and vacuum systems specialists are extending equipment installation and qualification timelines at new fabs.
- Multi-Node Certification Burden:Tool suppliers must simultaneously validate systems for 5nm, 3nm, and 2nm processes, compressing R&D cycles and straining field service organizations.
- Legacy Tool Integration:Heterogeneous integration architectures require bonding 200mm and 300mm wafer processing equipment, creating automation and contamination control complexities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Semiconductor Manufacturing Equipment Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wafer Fabrication Equipment, Assembly and Packaging Equipment, Test Equipment, Others Technology: Photonics, MEMS, Nanoelectronics, Quantum Computing End User: Consumer Electronics, Automotive, Telecommunications, Industrial Electronics Application: Computing Devices, Mobile Devices, IoT Devices, Artificial Intelligence |
| Companies Covered | Applied Materials Inc, ASML Holding NV, Tokyo Electron Ltd, Lam Research Corp, KLA Corp, Advantest Corp, Screen Holdings Co Ltd, ACM Research Inc, Tokyo Seimitsu, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Semiconductor Manufacturing Equipment Market Emerging Trajectories
Equipment architectures are adapting to transistor scaling beyond FinFET and the proliferation of chiplet-based designs, with process control and packaging systems experiencing the most rapid specification evolution.
High-numerical-aperture extreme ultraviolet lithography is extending optical resolution to 8nm half-pitch for critical layers. Samsung Foundry and Intel are prioritizing qualification of ASML's EXE:5200 systems for 2026 production ramps. This wavelength reduction is bifurcating the lithography market between immersion DUV for mature nodes and EUV-only for advanced logic.
Japan's METI has expanded subsidy eligibility to include equipment for 300mm silicon carbide wafer processing. This policy redirection is accelerating domestic tool development for power electronics applications. Kyocera and Showa Denko are the primary beneficiaries, with qualification timelines compressing from 36 to 24 months.
Foundry customers are consolidating procurement authority at headquarters level, displacing site-level equipment purchasing. Taiwan Semiconductor Manufacturing now centralizes lithography and deposition tool decisions in Hsinchu, with regional fabs executing pre-approved vendor contracts. This concentration is most visible in South Korea, where Samsung Device Solutions has absorbed previously independent memory and foundry procurement teams.
Asia-Pacific Semiconductor Manufacturing Equipment Market Segmentation
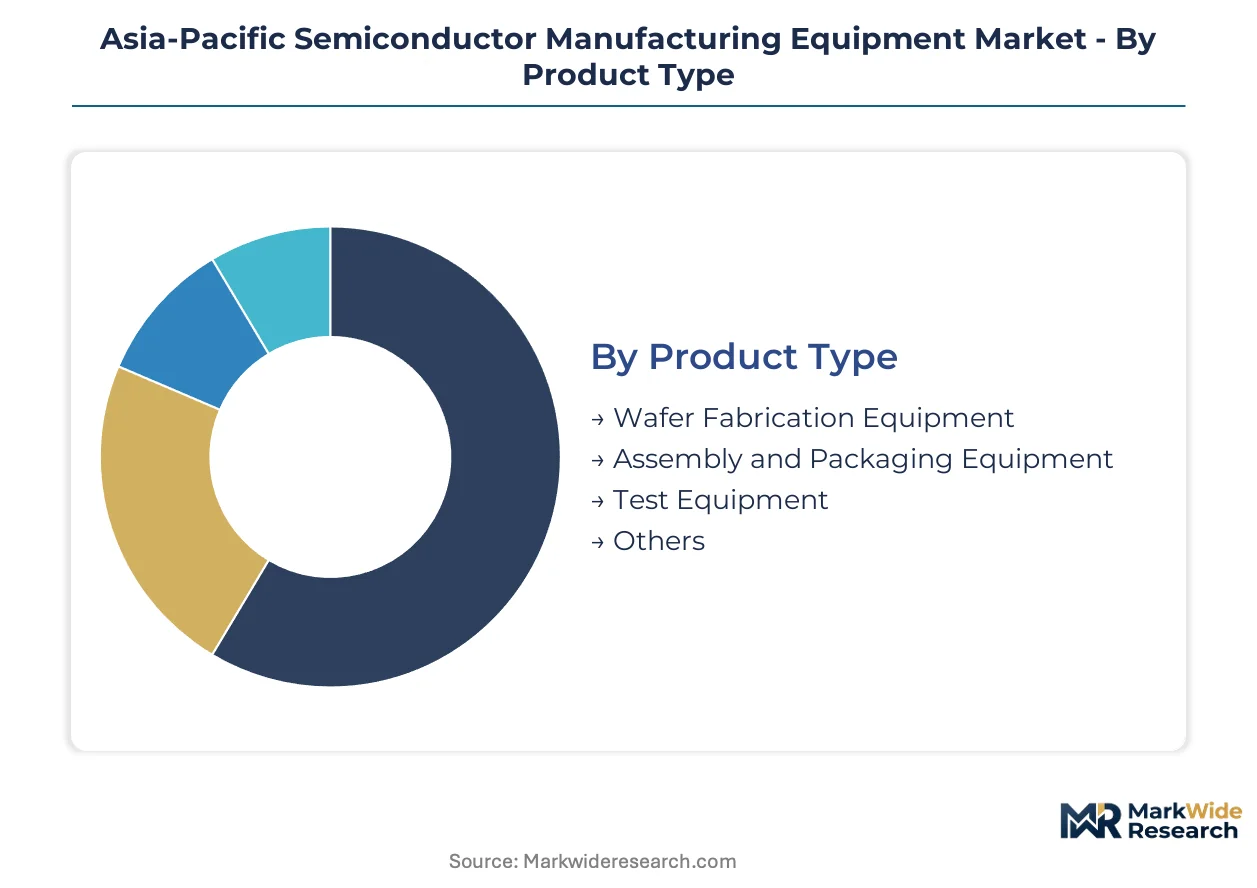
Equipment segmentation in the Asia-Pacific semiconductor manufacturing equipment market reveals how regulatory mandates and process complexity concentrate procurement decisions. Japan's METI subsidies, China's MIIT localization quotas, and South Korea's K-Belt incentives each favor distinct equipment categories based on domestic certification status and technology sovereignty goals.
Product Type:
Regulatory differentiation across Taiwan, South Korea, and China creates divergent procurement patterns for each equipment category, with import licensing and domestic content requirements reshaping vendor selection.
- Wafer Fabrication Equipment:Atomic layer deposition, extreme ultraviolet lithography, and etch systems operate at angstrom-scale tolerances in vacuum environments. Taiwan Semiconductor Manufacturing and Samsung Foundry in South Korea are deploying multi-billion-dollar tool lines for sub-3nm production, pulling equipment procurement toward ASML, Applied Materials, and Tokyo Electron despite China's MIIT pushing localization mandates for domestic alternatives.
- Test Equipment:Probe stations, automatic test equipment, and system-level testers validate die functionality across heterogeneous integration architectures. Demand concentrates in South Korea's Suwon and Hwaseong corridors where Samsung and SK Hynix are expanding 3D NAND and HBM qualification capacity, with Japan's METI subsidies accelerating domestic tester development by Advantest.
- Assembly and Packaging Equipment:Flip-chip bonders, fan-out wafer-level packaging tools, and wire bonding systems handle die interconnect. Malaysia's Penang and Vietnam's Ho Chi Minh City clusters are absorbing Intel and Amkor expansion for advanced packaging.
- Others:Wafer handling robots, metrology systems, and factory automation software support fab operations. Japan's Kyushu equipment component cluster benefits from METI reshoring incentives.
Wafer fabrication equipment handles the majority of throughput; test equipment is the fastest mover on share.
Technology:
Cost tier differentiation separates government-subsidized frontier development from commercially funded volume production across the Asia-Pacific region.
- Photonics:Silicon photonics and optical interconnect fabrication equipment enables high-speed data transmission for AI clusters. Taiwan's Hsinchu Science Park anchors demand as foundries integrate photonic chiplets with electronic dies.
- MEMS:Microelectromechanical systems equipment produces sensors, actuators, and resonators on 200mm and 300mm wafers. Japan's Tohoku region maintains process leadership in gyroscope and pressure sensor fabrication.
- Nanoelectronics:Sub-7nm transistor and interconnect processing defines the leading edge. South Korea's K-Belt tax credits are accelerating domestic equipment qualification for 2nm-class production.
- Quantum Computing:Cryogenic control electronics and superconducting qubit fabrication requires specialized deposition and etch tools. Australia's Sydney and Melbourne university labs collaborate with Taiwan foundries on pilot production.
Nanoelectronics commands the premium pricing tier; quantum computing is expanding most quickly from negligible base.
End User:
Application volume separates high-unit consumer markets from stringent-automotive qualification cycles across Asia-Pacific procurement.
- Consumer Electronics:Smartphone, tablet, and wearable chip fabrication drives the largest equipment volume. China's Yangtze Memory and ChangXin Memory are expanding NAND and DRAM capacity despite export control constraints on deposition and etch tools.
- Automotive:Silicon carbide power device and automotive MCU manufacturing requires extended temperature-range qualification. Japan's METI 300mm SiC subsidy program is redirecting equipment investment toward Kyocera and Showa Denko.
- Telecommunications:5G baseband and RF front-end chip production concentrates in Taiwan and South Korea foundries serving Qualcomm and MediaTek.
- Industrial Electronics:Motor driver, power supply, and sensor interface chips favor mature-node equipment with longer depreciation schedules. Southeast Asian legacy fabs in Singapore and Malaysia serve this demand.
Consumer electronics absorbs the greatest equipment throughput; automotive is gaining share fastest on electrification mandates.
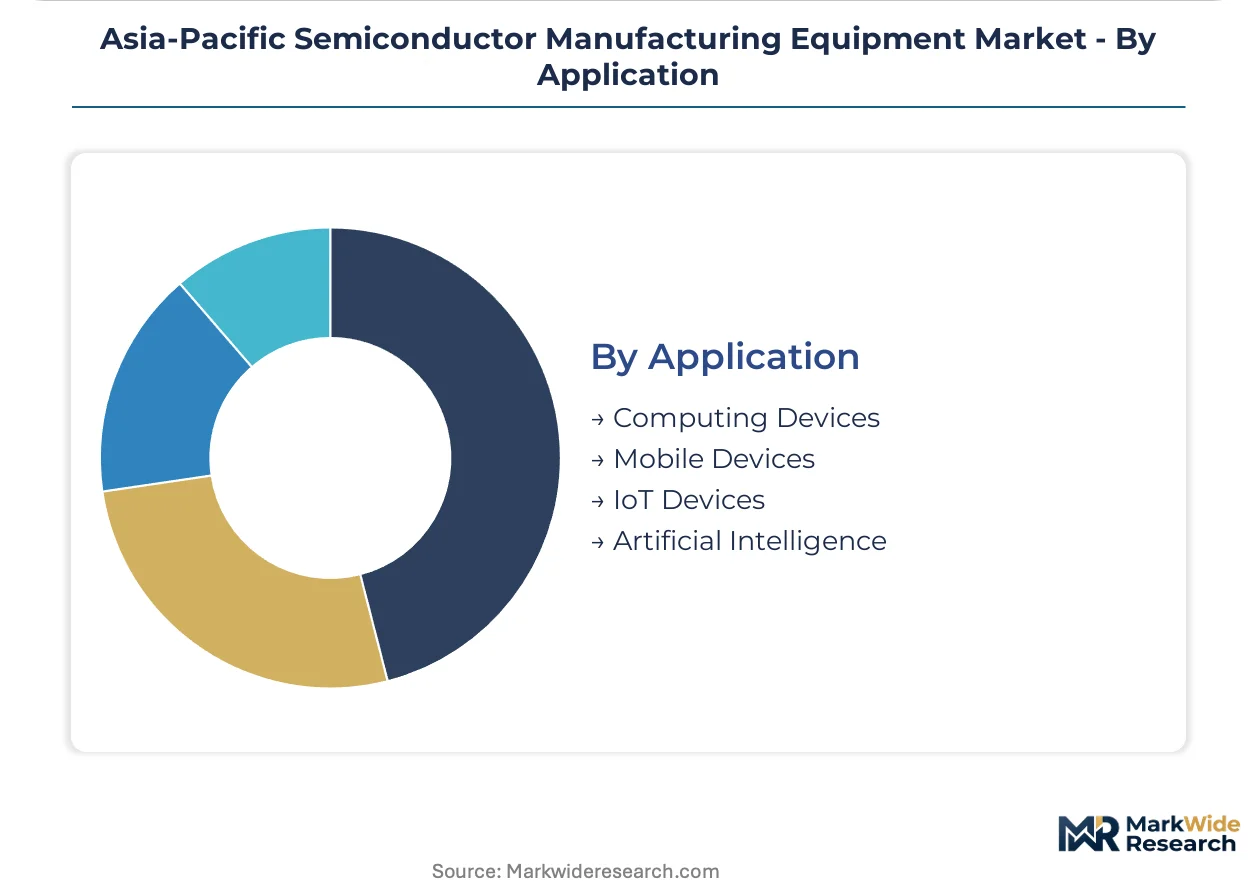
Application:
Customer type differentiation separates hyperscaler-driven AI accelerator demand from volume mobile and distributed IoT procurement.
- Computing Devices:Server CPU, GPU, and AI accelerator fabrication requires the most advanced lithography and packaging. Taiwan's TSMC and South Korea's Samsung Foundry are the primary demand centers for high-numerical-aperture EUV systems.
- Mobile Devices:Smartphone SoC and modem production sustains the largest single application volume for leading-edge foundry capacity. MediaTek and Qualcomm designs drive TSMC's N3 and N2 node ramps.
- IoT Devices:Low-power microcontroller and connectivity chip manufacturing favors 40nm-130nm mature nodes with cost-optimized equipment. China's SMIC and Hua Hong are expanding this capacity under localization directives.
- Artificial Intelligence:Training and inference accelerator demand is concentrating in CoWoS and HBM packaging equipment. Taiwan's Taichung and South Korea's Icheon are the primary advanced packaging investment zones.
Computing devices maintains the dominant throughput position; artificial intelligence is climbing the fastest on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances across Asia-Pacific semiconductor manufacturing equipment markets are diverging as regional self-sufficiency policies reshape trade flows. Equipment import dependency is falling in China and rising in Southeast Asia, while Japan and South Korea consolidate their positions as net exporters of high-value tools.
China
Domestic etch and deposition equipment procurement is accelerating under MIIT localization quotas for memory and logic fabs. The country's national semiconductor regulator enforces GB standards that redirect capital expenditure toward certified local suppliers. Yangtze River Delta clusters in Shanghai and Wuxi are absorbing the majority of tool qualification programs for 28nm and above processes.
Japan
Kyushu and Tohoku equipment component manufacturing is reshoring under METI Semiconductor and Digital Industry Strategy subsidies. Japan's Ministry of Economy, Trade and Industry directs funding toward 300mm silicon carbide wafer processing tools. Nagoya and Osaka metropolitan areas anchor precision machinery supply chains serving Tokyo Electron and Screen Holdings qualification timelines.
South Korea
Samsung Foundry and SK Hynix are commissioning multi-billion-dollar tool lines for 2nm pilot production and HBM expansion. The country's national semiconductor regulator administers K-Belt tax credits accelerating domestic equipment procurement. Seoul Capital Area and Icheon corridors concentrate EUV lithography and advanced packaging equipment demand.
Taiwan
TSMC is centralizing lithography and deposition procurement decisions in Hsinchu while regional fabs execute pre-approved vendor contracts. The National Science and Technology Council shapes fab expansion timelines through targeted funding programs. Taichung and Tainan science parks are absorbing the majority of CoWoS and fan-out wafer-level packaging equipment investment.
Vietnam
Intel and Amkor are expanding advanced packaging capacity in Ho Chi Minh City, creating demand for flip-chip bonders and metrology systems. The country's national investment regulator coordinates special economic zone incentives for semiconductor assembly operations. Northern Bac Ninh and Bac Giang provinces are emerging as secondary clusters for legacy packaging equipment deployment.
Asia-Pacific Semiconductor Manufacturing Equipment Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and technology access dimensions. The Asia-Pacific semiconductor manufacturing equipment market exhibits tiered consolidation, with lithography and deposition segments dominated by scale-driven incumbents while test and metrology categories sustain specialist fragmentation. Three archetypes define competitive positioning: integrated platform providers, process-specific specialists, and regional challengers serving localization mandates. Dominant competitive moves include strategic partnerships for high-numerical-aperture EUV qualification and capacity expansion in Southeast Asian packaging corridors.
Within the integrated platform tier, Applied Materials Inc and Lam Research Corp exemplify breadth-driven positioning across multiple process steps. Tokyo Electron Ltd occupies a specialist position in etch and clean equipment, representing Japanese precision engineering capabilities. Among China-based challengers, ACM Research Inc anchors regional localization efforts under MIIT procurement directives.
| Leading Market Players |
|---|
| Applied Materials Inc |
| ASML Holding NV |
| Tokyo Electron Ltd |
| Lam Research Corp |
| KLA Corp |
| Advantest Corp |
| Screen Holdings Co Ltd |
| ACM Research Inc |
| Tokyo Seimitsu |
| Others |
Supply Flow & Price Mechanics
Multi-billion-dollar tool line deployments in Taiwan and South Korea create scale economies that compress unit economics for atomic layer deposition and extreme ultraviolet lithography systems, establishing price floors that trailing-edge fabs in Southeast Asia cannot match while concentrating procurement leverage among TSMC and Samsung.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock in capacity years ahead of delivery. Pricing stratifies across high-numerical-aperture EUV systems, standard immersion DUV tools, and economy-tier legacy equipment based on certification level and volume scale. Cost compression in trailing-edge deposition tools is intensifying because Chinese MIIT localization mandates redirect demand toward domestic suppliers. Memory fabs exhibit highest price sensitivity due to cyclical margin pressure, while leading-edge foundries prioritize performance over unit cost.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication equipment supply through TSMC and Samsung Foundry capacity expansion, while Japan's Kyushu cluster feeds precision components upstream. Critical inputs include semiconductor-grade neon from reconfigured Ukrainian supply chains, high-purity fluoropolymers for vacuum seals, and specialized ceramics for plasma chambers. Single-source vulnerability for ASML's EUV scanners creates concentration risk in Veldhoven's engineering pipeline. Distribution runs through direct foundry procurement with centralized vendor qualification in Hsinchu and Seoul.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment interoperability standards for heterogeneous integration architectures are creating platform-economics inflection points where tool vendors must bundle process control software with hardware to capture recurring service revenue.
For Market Incumbents: Shield lithography and deposition market positions by accelerating high-numerical-aperture EUV qualification timelines before Chinese domestic alternatives mature. Deepen backward integration into vacuum pump and ceramic component manufacturing to reduce exposure to Japan's Kyushu supply bottlenecks. Prioritize field service organization expansion in Vietnam and Malaysia packaging corridors.
For New Entrants and Emerging Players: Lead with compound semiconductor retrofit solutions targeting silicon carbide power device fabs in Japan's automotive supply chain. White-space opportunities concentrate in 300mm SiC wafer processing tools under METI subsidy eligibility and cryogenic control electronics for quantum computing pilots in Australian university labs. Pursue qualification partnerships with second-tier foundries before attempting TSMC or Samsung certification.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among test equipment vendors with long-term service contracts tied to heterogeneous integration complexity. Five-to-ten-year viability favors specialists in advanced packaging metrology and atomic-scale process control software. Monitor export control alignment between Washington, Tokyo, and Seoul as inflection indicator for Chinese memory fab equipment availability.
| Strategic Initiative | Industry Significance |
|---|---|
| High-NA EUV Qualification Partnership | ASML's EXE:5200 deployment at Samsung Foundry secures 2nm production ramp positioning. |
| Domestic Equipment Certification Program | China's MIIT localization quotas redirect Yangtze Memory procurement toward ACM Research etch tools. |
| Advanced Packaging Capacity Expansion | Intel's Ho Chi Minh City investment creates demand for flip-chip bonders and fan-out equipment. |
| 300mm SiC Tool Development | Kyocera and Showa Denko benefit from METI subsidy compression of qualification timelines. |
| Field Service Organization Regionalization | Penang and Taichung service hubs reduce equipment installation timelines at new fab sites. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with fab operations directors, equipment procurement managers, plasma physics specialists, and aftermarket service heads; and secondary validation through SEMI equipment shipment data, METI subsidy disbursement records, MIIT GB standard filings, and foundry capital expenditure disclosures. Bottom-up equipment unit forecasts triangulated against top-down fab investment pipeline analysis.
The projection horizon spans equipment delivery cycles and foundry construction timelines. Segmentation dimensions modeled include product type, technology node tier, end-use application, and regional regulatory cluster. CAGRs derive from equipment intensity ratios per thousand wafer starts and foundry capacity expansion schedules. Forecast inputs incorporate neon gas supply reconfiguration impacts and export control policy alignment scenarios.
Forecasts assume regulatory continuity in Japan's METI Semiconductor Strategy, China's MIIT localization mandates, and South Korea's K-Belt tax credit regime; material policy shifts would require re-modeling. Specific risks include coordinated export control expansion, Ukrainian neon supply disruption, and 2nm yield ramp delays. Recalibration cycles align with material shifts in foundry capital expenditure announcements and subsidy program revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Wet Based Wafer Cleaning Equipment Market
Semiconductor Equipment
Thin Film Deposition Equipment Market
Semiconductor Equipment
Global Laser Dicing Systems Market
Semiconductor Equipment
FOUP Load Port Market
Semiconductor Equipment
Semiconductor Process and Control Equipment Market
Semiconductor Equipment
Quantum Annealing Equipment Market
Semiconductor Equipment
Die Attach Equipment Market
Semiconductor Equipment
Single Wafer Wet Cleaning Equipment Market
Semiconductor Equipment
Partition Inserter Machines Market
Semiconductor Equipment
Semiconductor LPCVD Furnaces Market
Semiconductor Equipment
Thin Wafer Processing and Dicing Equipment Market
Semiconductor Equipment
Global Atomic Layer Deposition (ALD) Equipment Market
Semiconductor Equipment
Dry Reactor Market
Semiconductor Equipment
Wafer Processing Equipment Market
Semiconductor Equipment
Wet Station Market
Semiconductor Equipment
Chip Mounter Market