
 Semiconductor Assembly and Testing Services Market | 2026-2036
Semiconductor Assembly and Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Assembly and Testing Services Market Intelligence
The rising proportion of demand from the telecommunications sector for 5G components is hardening the requirement for advanced testing services. ASE Technology Holding Co. Ltd. leverages its scale in System in Package (SiP) and flip-chip technologies to serve this segment. Amkor Technology Inc. competes by offering a broad portfolio of packaging and test solutions across key end markets. Meanwhile, JCET Group Co Ltd specializes in high-density packaging for mobile and computing applications.
Semiconductor assembly and testing services encompass the back-end manufacturing processes that transform a silicon wafer into a finished, functional integrated circuit. This includes critical processes like die attach, wire bonding, and encapsulation, followed by rigorous electrical and reliability testing. Within service types, final testing and wafer testing constitute the largest revenue streams for providers. Advanced packaging types like Flip Chip and System in Package represent the fastest-growing categories, driven by device miniaturization trends in consumer electronics.
Quality and reliability are governed by global standards like ISO 9001 and specific industry requirements such as AEC-Q100 for automotive. Market access is shaped by US export controls on advanced semiconductor technology and China's GB standards for electronic components. These frameworks influence material sourcing and testing parameters for OSAT vendors. Success for providers depends on navigating geopolitical trade policies while investing in next-generation test capabilities for emerging chip architectures.
Market Dynamics
The industry's structural evolution is defined by the transition toward heterogeneous integration and advanced packaging. This shift from monolithic SoCs to complex System-in-Package (SiP) and 3D IC designs fundamentally increases test complexity, cost, and capital investment requirements for OSAT providers.
Growth Catalysts
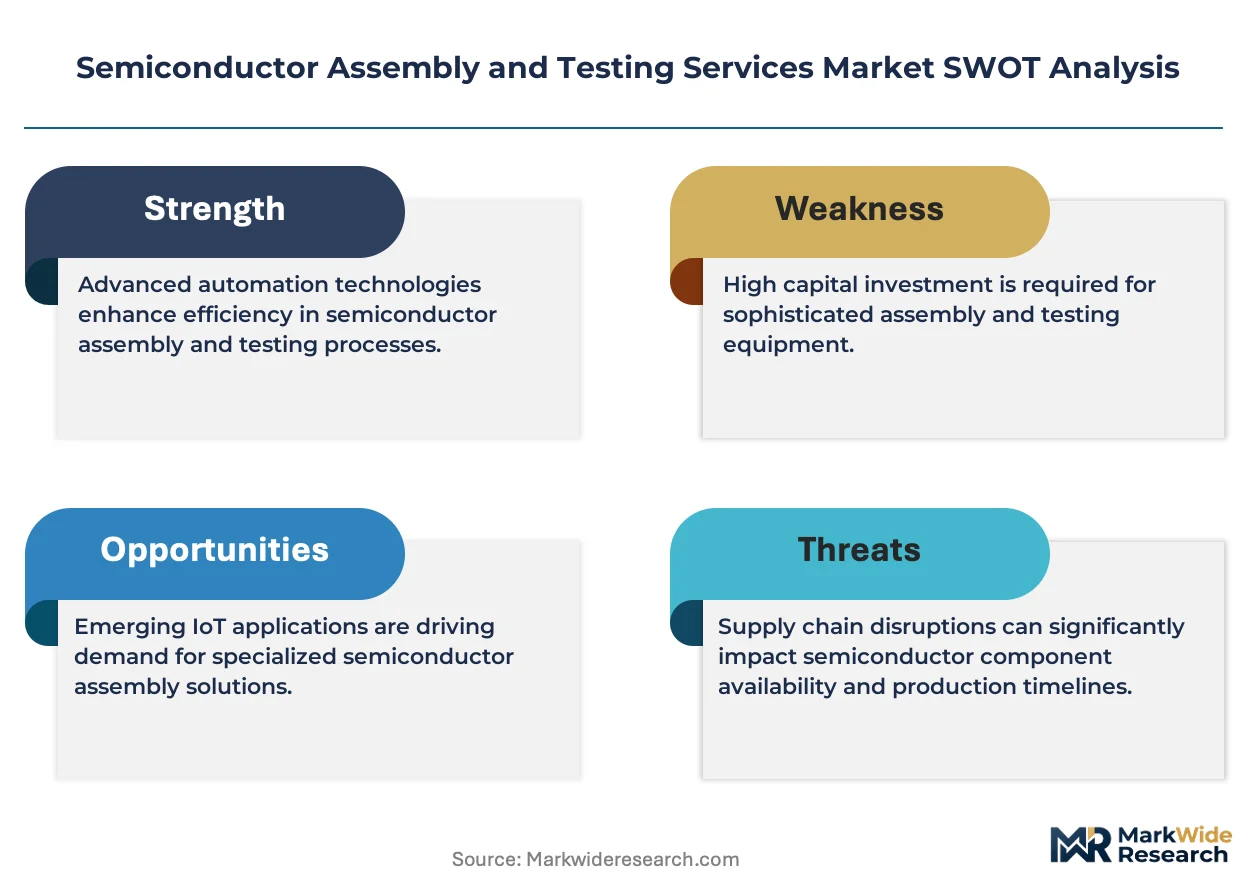
- 5G Proliferation:Demand from the telecommunications sector for 5G millimeter-wave components and base station chipsets hardens the requirement for advanced RF and high-speed digital testing services to ensure signal integrity and performance.
- Automotive Electrification:The rising semiconductor content in electric and autonomous vehicles, governed by stringent AEC-Q100 reliability standards, creates a durable demand stream for rigorous thermal, electrical, and long-duration stress testing.
- Onshoring Policies:Government initiatives in the United States and Europe aimed at building resilient domestic semiconductor supply chains are directly stimulating investment in and demand for localized assembly and testing capabilities.
Market Restraints
- Capital Intensity:The escalating cost of automated test equipment (ATE) and inspection tools required for advanced packaging technologies like fan-out wafer-level packaging (FOWLP) creates a significant barrier to entry and strains margins.
- Geopolitical Concentration:Heavy reliance on OSAT providers located in Taiwan and South Korea exposes the global supply chain to significant disruption risks from regional political instability, trade disputes, and natural disasters.
- Failure Analysis Complexity:Identifying the root cause of failures in multi-die SiP and 3D stacked ICs is exponentially more difficult and time-consuming than with traditional monolithic chips, increasing test development costs.
Strategic Opportunities
- Photonic Integrated Circuits (PICs):Providing specialized testing services for PICs used in data centers and optical communication represents a high-growth adjacency, requiring new capabilities in optical and high-frequency electrical testing.
- Chiplet Ecosystems:The move toward chiplet-based designs opens opportunities for OSATs to offer die-sorting, known-good-die (KGD) testing, and advanced integration services, positioning them as critical ecosystem partners.
- Service Model Innovation:Developing test-as-a-service (TaaS) platforms that provide fabless customers with access to test data analytics and yield optimization insights creates a new, recurring revenue stream beyond per-unit testing fees.
Industry Challenges
- Talent Scarcity:A persistent shortage of experienced test development and radio frequency (RF) engineers capable of programming and operating complex ATE for 5G and 6G chipsets constrains capacity expansion for many providers.
- Navigating Trade Controls:OSATs must manage complex compliance requirements stemming from conflicting regulations like US export controls on advanced semiconductors and China's GB standards, which impacts equipment and material sourcing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Assembly and Testing Services Market |
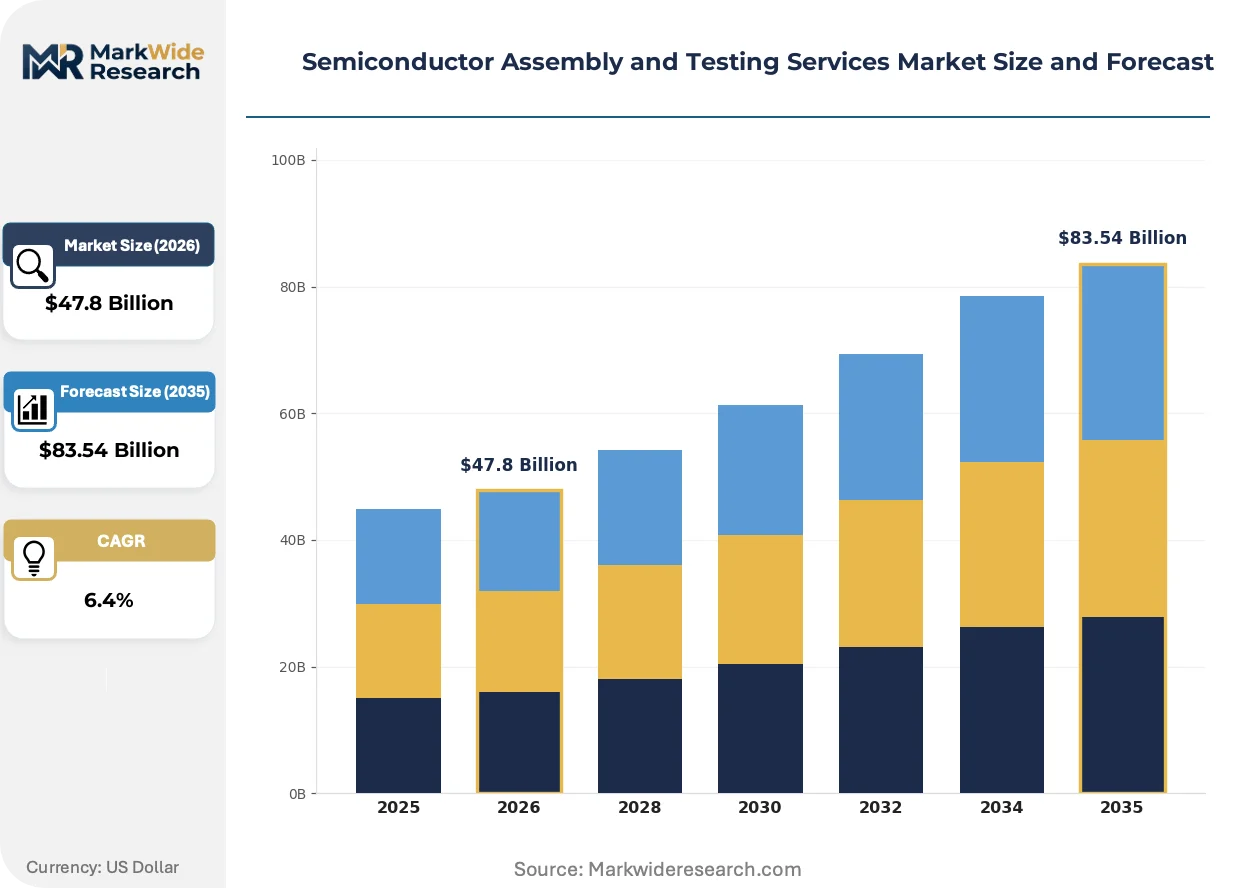
| Market Size in 2026 | $47.8 Billion |
| Market Size in 2035 | $83.54 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Wafer Testing, Final Testing, Burn-in Testing, Failure Analysis, Reliability Testing Packaging Type: Flip Chip, Wire Bonding, Ball Grid Array, Chip Scale Package, System in Package End User Industry: Consumer Electronics, Telecommunications, Industrial Automation, Aerospace & Defense, Data Centers Technology: 3D IC Packaging, Fan-Out Wafer Level Packaging, Through Silicon Via, MEMS Packaging, System on Chip |
| Companies Covered | ASE Technology Holding Co. Ltd., Amkor Technology Inc., Siliconware Precision Industries Co., Ltd., Powertech Technology Inc., Jiangsu Changjiang Electronics Technology Co., Ltd., JCET Group Co Ltd, ChipMOS Technologies Inc., Chipbond Technology Corporation, GlobalFoundries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Assembly and Testing Services Market Strategic Shifts & Innovations
Innovations in semiconductor testing are driven by the need to validate increasingly complex, multi-functional devices within a single package. This is forcing a fundamental shift from simple pass/fail screening to data-intensive characterization that informs the entire manufacturing process, from wafer fabrication to final assembly.
Wafer-level testing provides early-stage electrical validation of individual dies before they are diced from the silicon wafer. Fabless semiconductor companies and integrated device manufacturers are rapidly adopting this approach to improve overall manufacturing yield and reduce the cost of packaging faulty dies. This early-stage validation is converging with final system-level testing, enabling a holistic data-driven approach to quality control that spans the entire production flow.
The European Union's Cyber Resilience Act introduces mandatory cybersecurity requirements for products with digital elements. This policy has a direct industrial consequence, compelling manufacturers to incorporate security verification throughout the product lifecycle, including the hardware level. OSAT providers serving the automotive and Internet of Things (IoT) sectors are most impacted, now needing to integrate security-focused testing services like side-channel analysis and fault injection into their offerings.
A notable behavioral change is the move away from purely transactional test contracts toward deep, collaborative engineering partnerships. This model disrupts the traditional arm's-length vendor relationship, replacing it with integrated teams that use test data for continuous yield improvement and design-for-test optimization. This collaborative engagement is most pronounced in the high-performance computing (HPC) segment in North America, where extreme chip complexity necessitates a shared-risk, shared-data approach.
Semiconductor Assembly and Testing Services Market Segmentation
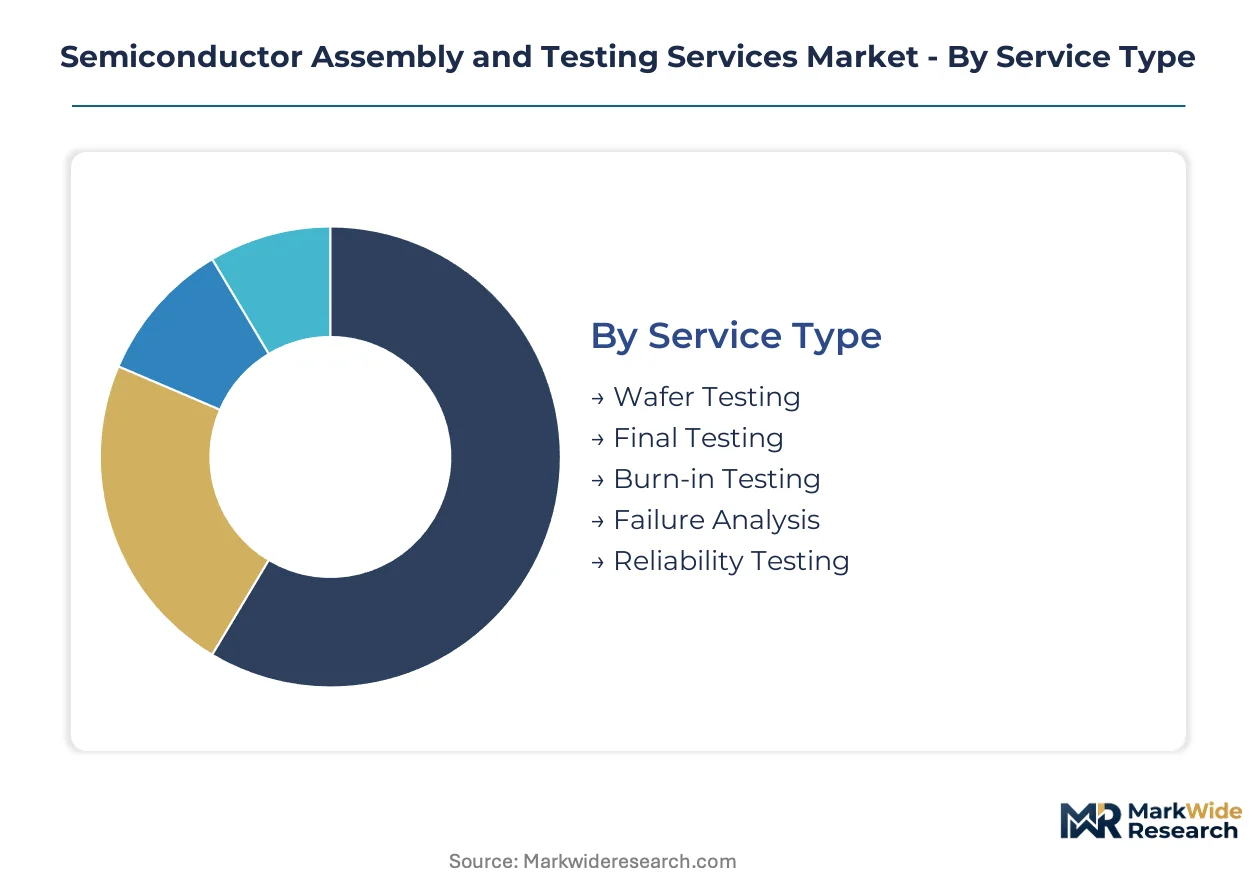
The Semiconductor Assembly and Testing Services market segments across various critical dimensions, reflecting the diverse requirements of chip manufacturers and end-user industries. Understanding these distinctions is essential for OSAT providers to tailor their capabilities and investment strategies effectively. Each segment represents a unique set of technical challenges and market opportunities within the back-end manufacturing ecosystem.
Service Type:
Providers differentiate their offerings based on the specific stage of the semiconductor manufacturing lifecycle.
- Wafer Testing:This service electrically validates individual dies on a silicon wafer before dicing and packaging. Demand intensifies from fabless companies and integrated device manufacturers aiming to improve manufacturing yield and reduce costs by identifying faulty dies early.
- Final Testing:This process validates the integrated circuit's full functionality and performance after packaging. Demand concentrates from consumer electronics and automotive sectors, driven by stringent quality standards and high-volume production.
- Burn-in Testing:This service accelerates the aging of devices under stress conditions to screen out early-life failures and ensure long-term reliability.
- Failure Analysis:This involves detailed investigation into the root causes of device malfunctions or defects, crucial for yield improvement and quality control.
- Reliability Testing:This evaluates a device's ability to perform under specified conditions for a defined period, including environmental and operational stress tests.
Volume sits with Final Testing; growth tilts toward Wafer Testing.
Packaging Type:
Technological advancements in miniaturization and integration shape the selection of packaging solutions.
- Flip Chip:This method attaches the die face-down to the substrate using solder bumps, providing superior electrical performance and thermal dissipation. Demand is strong in high-performance computing and telecommunications for compact, high-frequency applications.
- System in Package (SiP):This integrates multiple active semiconductor devices, passive components, and other modules into a single package. Its adoption is accelerating in consumer electronics and medical devices due to miniaturization trends and functional integration requirements.
- Wire Bonding:This traditional packaging method connects the die to the package substrate using fine wires, remaining cost-effective for many applications.
- Ball Grid Array:This package type uses an array of solder balls on its underside for electrical connection to the printed circuit board, offering high I/O density.
- Chip Scale Package:This package is nearly the same size as the silicon die itself, enabling compact designs for mobile and portable devices.
Conventional packaging methods like Wire Bonding still hold significant market share, while advanced types like System in Package are expanding most quickly.
End User Industry:
The diverse performance and reliability requirements of end-user industries dictate specialized testing protocols.
- Data Centers:This sector requires rigorous testing for high-performance computing chips, ensuring reliability and speed for server processors and networking components. Hyperscale cloud providers drive demand for complex thermal and electrical validation.
- Telecommunications:This segment demands specialized RF and high-speed digital testing for 5G millimeter-wave components and base station chipsets. ASE Technology Holding Co. Ltd. serves this segment with SiP and flip-chip expertise.
- Consumer Electronics:This industry relies on cost-effective, high-volume testing for components in smartphones, tablets, and wearables.
- Industrial Automation:This sector requires robust and reliable testing for semiconductors used in control systems, robotics, and sensors.
- Aerospace & Defense:This industry mandates extremely stringent reliability and environmental testing for mission-critical components, often with extended operational lifetimes.
Consumer electronics represents a substantial end-user segment, but Data Centers and Telecommunications are experiencing the steepest expansion trajectory.
Technology:
Innovations in semiconductor manufacturing processes create distinct categories for advanced packaging technology.
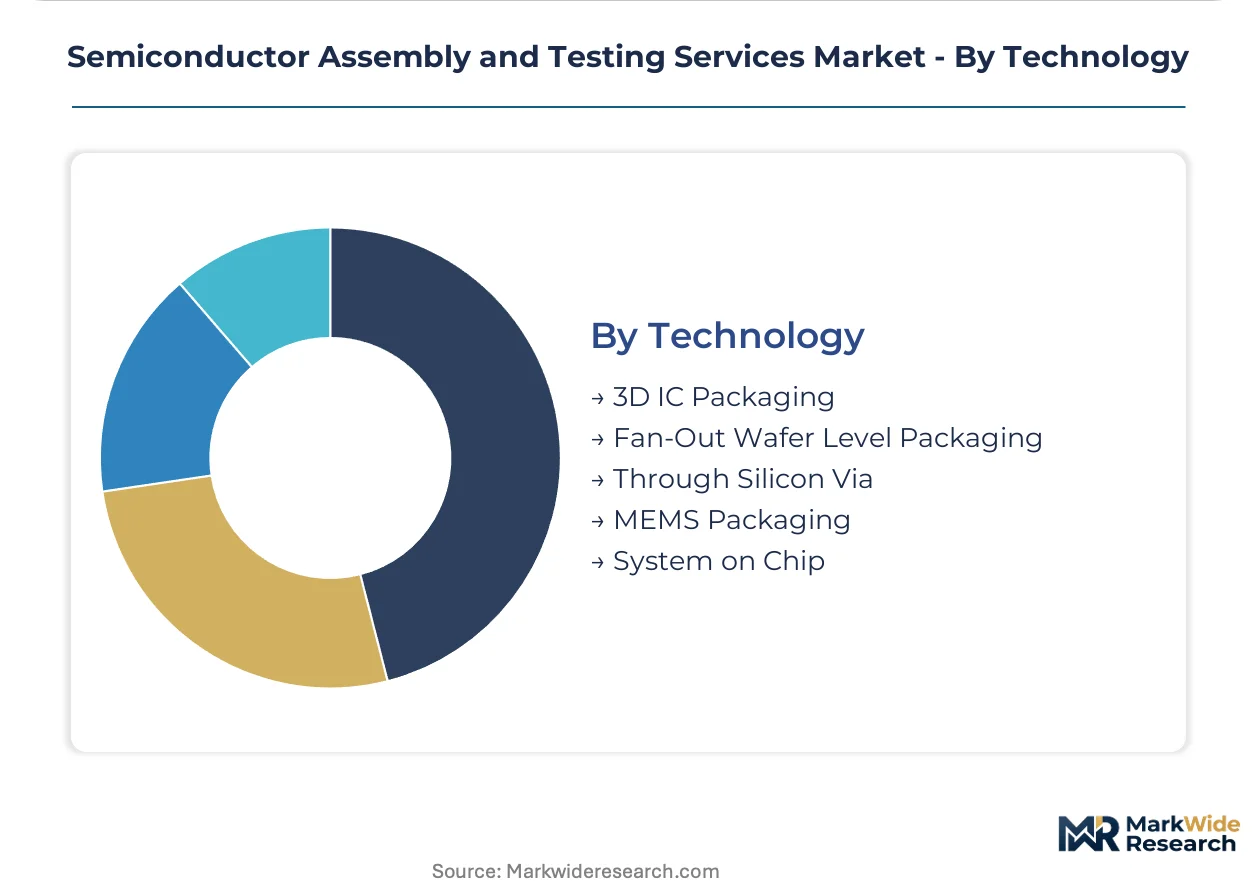
- 3D IC Packaging:This stacks multiple integrated circuit dies vertically, interconnected by Through Silicon Vias (TSVs), enabling higher bandwidth and reduced form factor. This technology is critical for high-bandwidth memory and advanced processors.
- Fan-Out Wafer Level Packaging (FOWLP):This extends the redistribution layer beyond the chip's perimeter, allowing for more I/O connections and smaller package sizes. It is increasingly adopted in mobile devices and wearables for its thin profile and performance benefits.
- Through Silicon Via:These vertical electrical connections pass completely through a silicon wafer or die, forming the basis for 3D IC integration.
- MEMS Packaging:This specialized packaging protects micro-electromechanical systems, which are sensitive to environmental factors, ensuring their precise functionality.
- System on Chip:This integrates all or most components of a computer or other electronic system into a single integrated circuit, requiring comprehensive functional testing.
Traditional System on Chip designs remain prevalent, but advanced integration technologies like 3D IC Packaging are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government-backed industrial parks, such as those in Taiwan, drive significant concentration for semiconductor assembly and testing services. These zones foster specialized ecosystems for advanced packaging and testing. They attract substantial investment due to strategic national importance and infrastructure support.
Taiwan
Taiwanese providers meet the robust demand for high-performance computing chips and advanced packaging technologies. The Taiwanese government actively supports the semiconductor industry through various incentives and strategic planning. Hsinchu Science Park, for instance, remains a critical hub for OSAT innovation and capacity expansion.
South Korea
South Korean firms address the specialized requirements for memory chips and sophisticated 5G components. The South Korean government implements policies aimed at strengthening domestic semiconductor capabilities and research and development. Gyeonggi-do province hosts major OSAT operations, continually advancing packaging and testing methodologies.
United States
American demand for data center processors and automotive electrification components stimulates investment in advanced testing. The US CHIPS Act directly incentivizes localized assembly and testing capabilities. Arizona and New York are emerging as key locations for new semiconductor manufacturing and packaging facilities.
China
Chinese domestic demand for mobile and computing applications fuels significant growth in local OSAT services. China's GB standards influence testing parameters for electronic components within the country. The Yangtze River Delta region, including Shanghai, sees substantial investment in high-density packaging and testing infrastructure.
Germany
German automotive electrification and industrial automation sectors create durable demand for rigorous semiconductor testing. The European Chips Act supports the establishment of resilient domestic semiconductor supply chains. Dresden, known as "Silicon Saxony," is a prominent cluster for advanced packaging and test development in Europe.
Semiconductor Assembly and Testing Services Market Key Industry Players
Top-tier vendors anchor the global semiconductor assembly and testing market, while specialized mid-tier players address niche segments with tailored solutions. The industry structure features scale-driven integrated players and focused technology specialists. Archetypes include large-scale outsourced semiconductor assembly and test (OSAT) providers, pure-play test houses, and vertically integrated foundries offering comprehensive back-end services. Dominant competitive moves include significant capacity expansion for advanced packaging and continuous portfolio diversification into next-generation test capabilities.
Within the scale-driven OSAT archetype, Taiwan-based ASE Technology Holding Co. Ltd. exemplifies market leadership through its extensive System in Package and flip-chip capabilities. Amkor Technology Inc., a global provider, occupies a similar position by offering a broad portfolio of packaging and test solutions across diverse end markets. Jiangsu Changjiang Electronics Technology Co., Ltd. (JCET Group Co Ltd) sits within the specialized segment, focusing on high-density packaging for mobile and computing applications.
| Leading Market Players |
|---|
| ASE Technology Holding Co. Ltd. |
| Amkor Technology Inc. |
| Siliconware Precision Industries Co., Ltd. |
| Powertech Technology Inc. |
| Jiangsu Changjiang Electronics Technology Co., Ltd. |
| JCET Group Co Ltd |
| ChipMOS Technologies Inc. |
| Chipbond Technology Corporation |
| GlobalFoundries Inc. |
| Others |
Cost & Logistics Intelligence
Experienced test development and radio frequency engineers concentrated in Taiwan and South Korea create labor-cost differentials, influencing pricing-tier spreads for advanced testing services compared to conventional offerings.
Pricing Analysis
Premium pricing for short lead times on advanced packaging services reflects high capital expenditure requirements for specialized equipment. The dominant pricing model remains per-unit transactional, shifting to project-based for complex heterogeneous integration. Price differentiation drivers include advanced packaging complexity for System in Package (SiP) and 3D ICs, specific AEC-Q100 automotive certifications, and geographic delivery costs. Pricing pressure stems from the escalating capital intensity of automated test equipment. Consumer electronics customers exhibit the most price sensitivity, while aerospace and defense sectors are least sensitive.
Supply Chain Analysis
Rigorous ISO 9001 and AEC-Q100 certification gates shape the semiconductor assembly and testing supply chain, demanding stringent quality controls. Geographic supply concentration remains high in Taiwan, South Korea, and increasingly China for back-end services. The industry draws from critical raw materials like silicon wafers and relies heavily on specialized automated test equipment. Geopolitical concentration in East Asia presents a significant structural supply chain risk. Distribution runs through direct contractual agreements with fabless semiconductor companies and integrated device manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The semiconductor assembly and testing market operates under significant supply constraints, where the escalating cost of automated test equipment props pricing for advanced services.
For Market Incumbents: Hedge against geopolitical trade policy shifts by diversifying advanced packaging capacity outside concentrated regions. Invest strategically in next-generation test capabilities for photonic integrated circuits (PICs) and chiplet ecosystems. Pursue strategic mergers and acquisitions to secure specialized talent pools in areas like RF engineering. Drive R&D in AI-driven test automation to improve efficiency and mitigate rising labor costs.
For New Entrants and Emerging Players: The European Union's Cyber Resilience Act in Europe opens a window for new entrants to offer security-focused testing services for IoT and automotive components. Target specialized known-good-die (KGD) testing for chiplet architectures as a white-space opportunity. Penetrate niche applications requiring highly specialized, low-volume optical or high-frequency electrical testing. Implement test-as-a-service (TaaS) models with integrated data analytics for differentiated market entry.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking to consolidate fragmented testing capabilities and gain access to specialized talent pools for advanced packaging. Long-term viability remains high for advanced assembly and testing due to increasing chip complexity over the next decade. Identify specialized mid-tier OSATs with unique test intellectual property or established customer relationships in high-growth segments. The signal to watch is increased fabless customer investment in co-development partnerships with OSAT providers.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Advanced Packaging | Addresses the surging demand from data centers for high-performance computing chips. |
| Investment in AI-Driven Test Automation | Improves test efficiency and reduces operational costs for complex multi-die packages. |
| Strategic Partnerships for Chiplet Testing | Enables known-good-die (KGD) validation, critical for emerging chiplet ecosystems. |
| Geographic Diversification of OSAT Facilities | Mitigates geopolitical supply chain risks concentrated in Taiwan and South Korea. |
| Development of Test-as-a-Service Platforms | Creates new, recurring revenue streams by offering data analytics and yield optimization insights. |
Research Approach
Multi-period observation of OSAT capital expenditure and packaging technology adoption rates anchored the trend analysis, supplemented by interviews with OSAT executives, fabless design engineers, and supply chain managers. Secondary validation drew from industry association reports, financial disclosures of public OSAT providers, government semiconductor policy documents, and academic research. A comprehensive bottom-up and top-down triangulation approach ensured data consistency.
An input-output matrix model integrated historical performance with projected market shifts, segmenting the forecast across service type, packaging type, end-user industry, technology, and geographic region. Compound annual growth rates were derived from historical growth patterns and projected technology roadmaps across the analysis window. Key forecast inputs included semiconductor content per device and advanced packaging penetration rates.
The model assumes a particular technology adoption path; alternative pathways for chiplet integration would alter the outlook for advanced packaging services. Forecasts reflect assumptions regarding geopolitical trade policies and the pace of talent development. A model refresh is warranted upon material change in global semiconductor manufacturing capacity or regulatory frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Global Electromagnetic Flow Meter Market
Test and Measurement
Asia-Pacific Nondestructive Testing Equipment Market
Test and Measurement
3D Automatic Optical Inspection Machine Market
Test and Measurement
High Rate Discharge Test Machine Market
Test and Measurement
Automated Test Equipment Market
Test and Measurement
United States Probe Station Market
Test and Measurement
Global Micrometer Market
Test and Measurement
Advanced Probe Card and Wafer Probing Test Systems Market
Test and Measurement
Flow Meter Market
Test and Measurement
Density Tester Market
Test and Measurement
Glow Wire Test Apparatus Market
Test and Measurement
Environmental Test Chambers Market
Test and Measurement
Pump Testers Market
Test and Measurement
State Transition Testing Market
Test and Measurement
Metrology Services Market
Test and Measurement
Printed Circuit Board Inspection Equipment Market