
 Optical Wafer Inspection Systems Market | 2026-2036
Optical Wafer Inspection Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Wafer Inspection Systems Market Analytics
A capital-intensity divergence between lithography-integrated metrology specialists and standalone optical inspection vendors is rotating competitive dynamics toward bundled platform offerings. KLA Corporation leverages its dominant installed base in patterned wafer inspection to cross-sell adjacent process control modules. ASML Holding N.V. anchors its market position through deep integration of wafer inspection data into EUV scanner feedback loops, tightening process windows for leading-edge nodes.
Optical wafer inspection systems employ high-resolution optical imaging, laser scanning, and spectroscopic techniques to detect sub-micron defects, measure critical dimensions, and verify overlay alignment on semiconductor substrates during fabrication. These systems operate at ultraviolet and deep-ultraviolet wavelengths to resolve features below the diffraction limit through advanced algorithmic reconstruction, serving as the primary yield assurance mechanism in multi-billion-dollar cleanroom environments. Inline systems capture the majority of capital deployment as foundries prioritize real-time defect detection over offline sampling, while automated systems displace manual platforms across all but the lowest-volume research settings. Laser scanning technology leads revenue contribution for patterned wafer applications, though spectroscopy-based methods are gaining traction for thin-film metrology in advanced packaging lines.
The FDA's quality system regulation for medical device semiconductors and China's NMPA traceability requirements for automotive-grade chips are elevating inspection data retention and calibration documentation to contractual prerequisites. REACH substance restrictions on optical coating materials and Japan's METI semiconductor resilience framework are reshaping supplier qualification timelines across the equipment supply chain. Stakeholders must weigh the capital efficiency of incremental optical upgrades against the disruptive potential of hybrid electron-optical platforms before committing to next-generation fab inspection architectures.
Market Dynamics
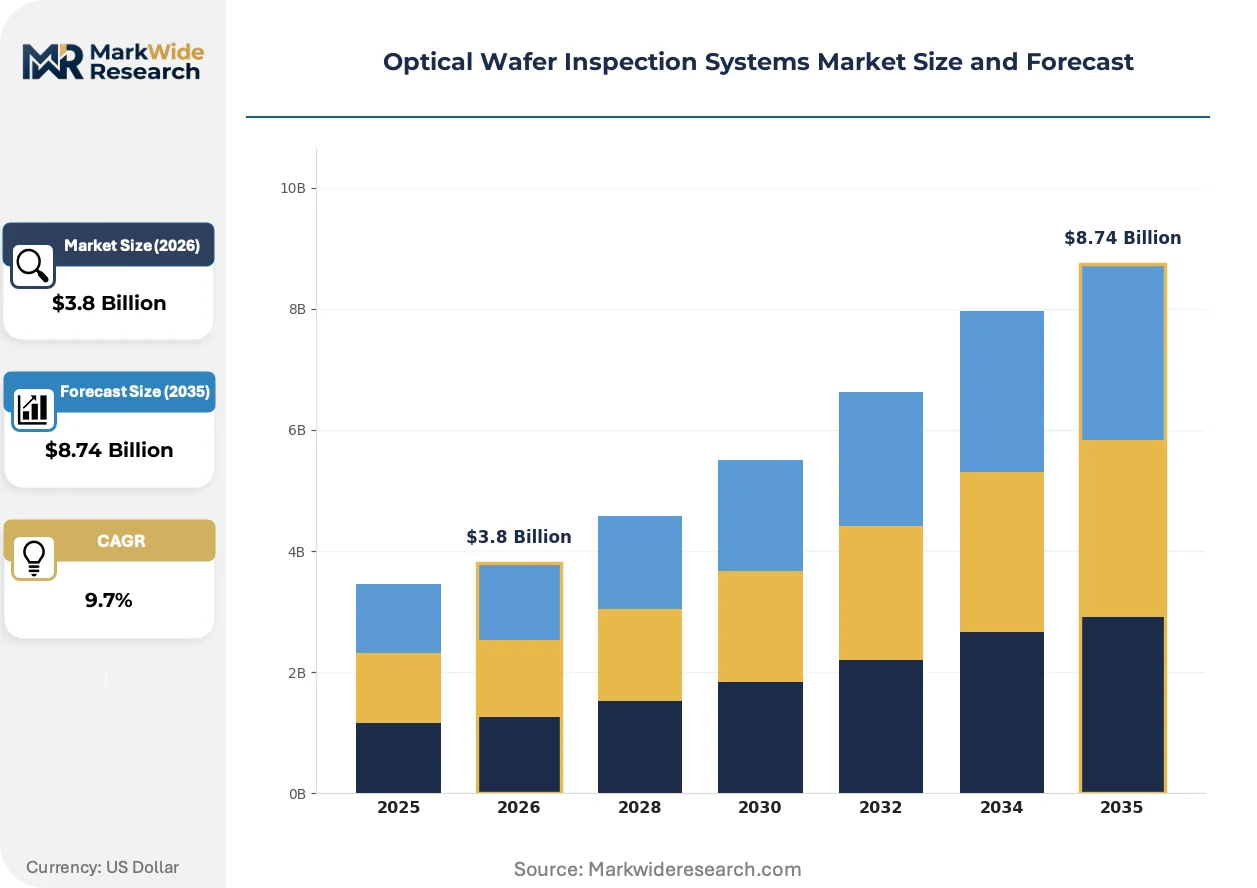
EUV lithography adoption at Taiwan Semiconductor Manufacturing and Samsung Foundry is compressing defect detection tolerances below 5nm, forcing simultaneous upgrades across patterned wafer inspection, overlay metrology, and thin-film characterization platforms.
Growth Catalysts
- Advanced Node Proliferation:EUV scanner deployment at leading foundries widens the addressable base for multi-beam optical inspection modules. South Korea's semiconductor cluster accounts for concentrated capital deployment.
- Medical Device Traceability Mandates:FDA quality system regulations for implantable chip supply chains mandate certified inspection data retention. Procurement contracts now specify ISO 17025-calibrated platforms.
- Automotive-Grade Certification:China's NMPA traceability requirements for automotive semiconductors redirect foundry procurement toward qualified inspection architectures with full genealogy documentation.
Market Restraints
- Optical Component Supply Concentration:Deep-ultraviolet laser sources and specialized optical coatings concentrate among German and Japanese suppliers. REACH substance restrictions on coating materials extend qualification timelines.
- Capital Intensity Barrier:Single advanced optical inspection tools exceed $15 million installed cost. Memory fabs in China face financing constraints for full-fleet replacement cycles.
- Electron-Beam Substitution Threat:Hybrid electron-optical platforms from applied materials vendors capture sub-3nm defect detection applications currently served by pure optical systems.
Strategic Opportunities
- Advanced Packaging Metrology:Heterogeneous integration in Taiwan and U.S. facilities creates demand for spectroscopy-based thin-film measurement on chiplets and interposers.
- India PLI Scheme:India's production-linked incentive scheme for semiconductor manufacturing attracts inspection equipment vendors to establish local calibration and service infrastructure.
- AI-Assisted Defect Classification:Machine learning integration with optical inspection hardware reduces false positives. Foundries in Japan adopt neural network-enhanced pattern recognition for yield ramp acceleration.
Industry Challenges
- Specialized Technician Scarcity:Deep-ultraviolet optical alignment and algorithmic reconstruction expertise concentrates among veteran engineers at KLA, Applied Materials, and Hitachi High-Tech. Talent poaching inflates compensation costs.
- Legacy Tool Integration Complexity:Foundries in Malaysia and Singapore operate mixed-vendor inspection fleets. Data format incompatibilities between 200mm-era tools and modern platforms obstruct unified yield management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Wafer Inspection Systems Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inline Systems, Offline Systems, Automated Systems, Manual Systems Technology: Optical Imaging, Laser Scanning, Spectroscopy, Digital Cameras End User: Semiconductor Manufacturers, Research Institutions, Electronic Component Fabricators, Foundries Application: Defect Inspection, Thickness Measurement, Critical Dimension Measurement, Overlay Measurement |
| Companies Covered | ASML Holding N.V., Nikon Corporation, KLA Corporation, SCREEN Semiconductor Solutions, Lasertec Corporation, Applied Materials, Inc., Camtek Ltd., Leica Microsystems, Hitachi High-Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Wafer Inspection Systems Market Evolving Landscape
Computational imaging and machine learning are compressing the resolution gap between optical and electron-beam inspection, while regulatory traceability mandates reshape data architecture requirements across the equipment supply chain.
Deep-ultraviolet light sources with wavelengths below 193nm are miniaturizing defect detection thresholds for sub-7nm logic nodes. Taiwan Semiconductor Manufacturing deploys these sources across its N3 and N2 production lines. The technology is miniaturizing the economic viability of optical inspection against electron-beam alternatives at leading-edge nodes.
REACH substance restrictions on fluorinated optical coating materials are forcing reformulation of deep-ultraviolet lens assemblies. Equipment vendors face extended qualification timelines with ECHA-registered alternatives. Memory manufacturers in South Korea accelerate procurement of pre-certified coating supply chains to avoid production interruptions.
Foundry buyers are consolidating inspection equipment procurement under multi-year platform agreements with embedded upgrade pathways. Equipment-as-a-service models displace traditional capital purchase cycles for mid-tier logic fabs. This shift concentrates most visibly among U.S.-based specialty foundries serving aerospace and defense end-uses with long-term volume commitments.
Optical Wafer Inspection Systems Market Segmentation
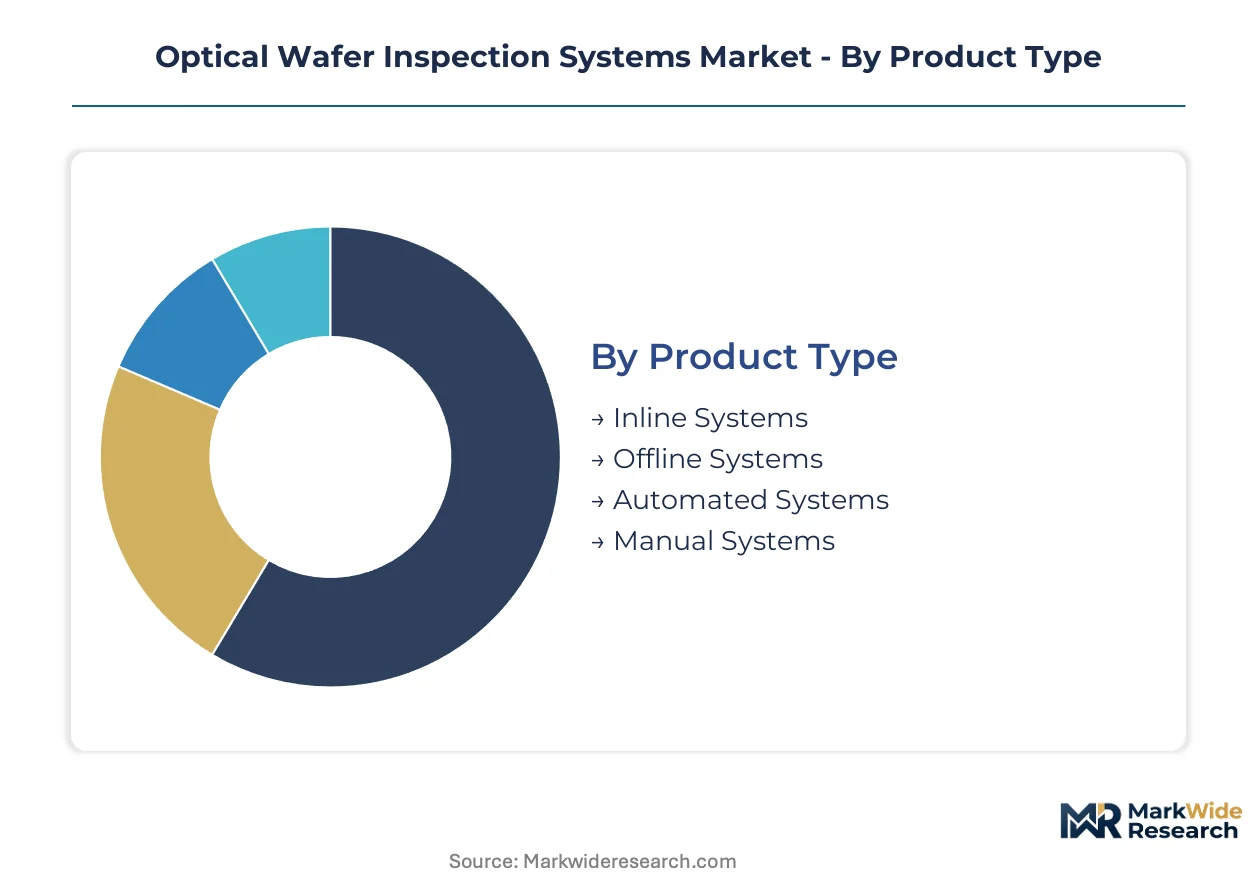
Segmentation in optical wafer inspection systems reveals how capital allocation priorities diverge between real-time process control and offline quality assurance. Equipment buyers weigh throughput requirements against detection sensitivity thresholds when selecting across product architectures and technology modalities.
Product Type:
Laser scanning and electron-beam substitution pressures weigh most heavily on inline platforms, where throughput demands intensify competitive displacement risk from hybrid inspection modalities.
- Inline Systems:These platforms integrate directly into fabrication line sequences for real-time defect capture without wafer removal. Taiwan Semiconductor Manufacturing and Samsung Foundry deploy these across EUV lithography bays where process window compression demands immediate feedback loops.
- Automated Systems:Robotic wafer handling and algorithmic classification reduce operator dependency in high-volume cleanroom environments. Foundries in South Korea prioritize these for 24/7 operation cycles where labor cost arbitrage justifies capital intensity.
- Offline Systems:Sampling-based inspection for process development and failure analysis applications.
- Manual Systems:Research settings and legacy 200mm fabs with low-volume, high-mix production requirements.
Inline systems retain volume leadership; automated systems hold the steepest expansion curve as labor constraints intensify across East Asian fabrication clusters.
Technology:
Cost tier stratification separates capital-intensive deep-ultraviolet modalities from emerging spectroscopy platforms targeting advanced packaging economics.
- Laser Scanning:High-speed photon detection across patterned wafer surfaces enables sub-5nm defect resolution at production throughputs. KLA Corporation dominates installed base concentration for logic node applications where pattern density challenges optical diffraction limits.
- Spectroscopy:Thin-film thickness and composition analysis through wavelength-dependent reflectance measurement. Taiwan and U.S. heterogeneous integration facilities deploy these for interposer and chiplet metrology where vertical stacking creates new measurement planes.
- Optical Imaging:Broadband illumination with computational reconstruction for overlay and critical dimension verification.
- Digital Cameras:CMOS and CCD sensor arrays for lower-resolution macro defect detection in mature node applications.
Laser scanning commands the premium pricing tier; spectroscopy is climbing the fastest as advanced packaging capacity expands.
End User:
Customer type segmentation tracks how procurement authority concentrates among capital-intensive foundry operators versus fragmented research and specialty manufacturing demand pools.
- Foundries:Merchant semiconductor manufacturers purchasing at fleet scale with multi-year platform agreements. Taiwan Semiconductor Manufacturing, Samsung Foundry, and Intel Foundry Services account for concentrated equipment absorption where yield management directly determines wafer economics.
- Semiconductor Manufacturers:Integrated device operators with captive fabrication for memory and logic products. SK Hynix and Micron Technology prioritize inspection capital for 3D NAND layer stacking where defect propagation risks multiply with vertical cell count.
- Electronic Component Fabricators:Discrete and analog specialists with lower-resolution requirements and extended tool depreciation cycles.
- Research Institutions:Universities and national laboratories with manual platform preferences and grant-dependent procurement timelines.
Foundries retain volume leadership; semiconductor manufacturers hold the steepest expansion curve as memory capital expenditure accelerates.
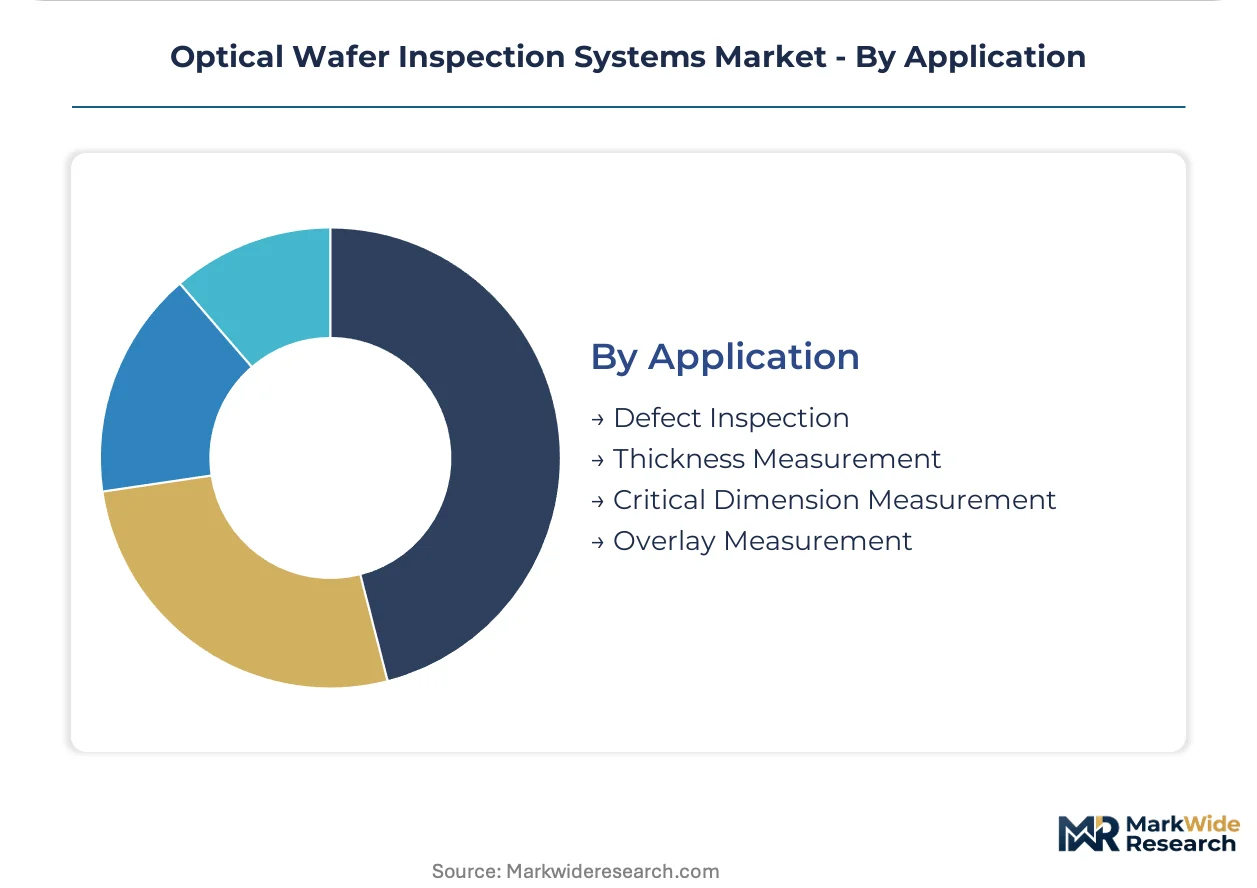
Application:
Application segmentation aligns with process step criticality, from pattern transfer verification to final outgoing quality assurance.
- Defect Inspection:Particle, scratch, and pattern anomaly detection across bare and patterned wafer surfaces. EUV lithography adoption at leading-edge nodes compresses detection tolerances below previous optical platform capabilities, forcing simultaneous metrology architecture upgrades.
- Critical Dimension Measurement:Line width and spacing verification for transistor gate and interconnect layers. Samsung Foundry deploys these systems across its 3nm GAA transistor ramps where edge placement error budgets tighten with each node transition.
- Overlay Measurement:Layer-to-layer alignment verification for multi-patterning and 3D integration sequences.
- Thickness Measurement:Film stack characterization for deposition process control in memory and power device fabrication.
Defect inspection retains volume leadership; critical dimension measurement holds the steepest expansion curve as gate-all-around architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in South Korea and Taiwan where foundry capital expenditure absorbs premium inspection platforms, while secondary markets in Southeast Asia negotiate on service bundling and extended payment terms.
Taiwan
EUV lithography deployment at Taiwan Semiconductor Manufacturing drives multi-beam optical inspection procurement for N3 and N2 node ramps. The National Development Council's semiconductor resilience initiatives subsidize advanced metrology infrastructure in Hsinchu Science Park. Tainan's Southern Taiwan Science Park hosts concentrated capacity expansion where defect detection tolerances compress below 5nm.
South Korea
Samsung Foundry and SK Hynix anchor fleet-scale procurement of laser scanning platforms for 3nm GAA transistor and 3D NAND layer stacking applications. METI-aligned bilateral technology agreements with Japan accelerate coating material qualification timelines. Pyeongtaek and Yongin semiconductor clusters absorb the majority of capital deployment for real-time process control systems.
United States
Intel Foundry Services and specialty aerospace-defense fabs prioritize automated inspection platforms with embedded upgrade pathways under multi-year agreements. The CHIPS and Science Act directs federal procurement toward domestic metrology supply chain resilience. Arizona's Phoenix metro and Oregon's Hillsboro facilities concentrate leading-edge capacity where overlay metrology demand intensifies.
Japan
Hitachi High-Tech and Lasertec anchor domestic demand for spectroscopy-based thin-film measurement in heterogeneous integration lines. METI's semiconductor resilience framework mandates inspection data retention for automotive-grade chip genealogy. Kyushu's Kumamoto and Hiroshima prefectures host advanced packaging capacity where interposer metrology requirements expand.
China
Memory fabs in Yangtze River Delta and Pearl River Delta face financing constraints for full-fleet replacement cycles amid capital intensity barriers. NMPA traceability requirements for automotive semiconductors redirect procurement toward certified platforms with full documentation. Shanghai and Beijing municipal governments subsidize local inspection equipment vendors through integrated circuit industry funds.
Optical Wafer Inspection Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with lithography-integrated metrology specialists commanding premium positioning while standalone optical vendors compete on throughput economics. The market structure consolidates around three tiers: EUV-integrated platform providers, dedicated inspection pure-plays, and emerging hybrid electron-optical challengers. Dominant competitive moves include strategic partnerships for coating material supply security and geographic expansion into India via PLI-aligned local service infrastructure.
Within the lithography-integrated tier, ASML Holding N.V. and Nikon Corporation exemplify platform bundling strategies that embed inspection data into scanner feedback loops. Among dedicated inspection specialists, KLA Corporation occupies a position representing installed base leverage for cross-selling adjacent process control modules. Lasertec Corporation represents the precision optics archetype with concentrated expertise in deep-ultraviolet light source miniaturization.
| Leading Market Players |
|---|
| ASML Holding N.V. |
| Nikon Corporation |
| KLA Corporation |
| SCREEN Semiconductor Solutions |
| Lasertec Corporation |
| Applied Materials, Inc. |
| Camtek Ltd. |
| Leica Microsystems |
| Hitachi High-Technologies Corporation |
| Others |
Value Network & Pricing Analysis
Twelve-to-eighteen-month qualification timelines for deep-ultraviolet optical coatings concentrate pricing power among German and Japanese suppliers, while foundry buyers absorb premium configured-to-order pricing for EUV-integrated inspection modules.
Pricing Analysis
Configured-to-order pricing for lithography-integrated platforms commands spreads exceeding 40 percent above standard standalone optical inspection configurations. Three-tier pricing structure across premium lithography-bundled, standard fleet-scale, and economy refurbished tiers segments buyer archetypes by node criticality and capital intensity. Pricing pressure stems from memory fab financing constraints in China, where capital intensity barriers compress procurement budgets for full-fleet replacement cycles. IDM memory manufacturers exhibit lowest price sensitivity due to yield-loss economics at 3D NAND layer stacking depths, while mid-tier analog fabs negotiate hardest on extended payment terms.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication demand concentration, while Germany and Japan supply specialized deep-ultraviolet laser sources and fluorinated optical coatings. The equipment supply chain draws from rare earth elements for laser crystal substrates, high-purity fused silica for lens assemblies, and precision motion control systems for wafer staging. Single-source vulnerability concentrates in German suppliers for sub-193nm laser architectures, where REACH substance restrictions on coating materials extend qualification timelines. Distribution runs through direct sales forces for leading foundry accounts, with regional service subsidiaries handling calibration and spare parts logistics for secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The optical wafer inspection market sits in early-stage cyclical recovery, with EUV lithography deployment waves at Taiwan Semiconductor Manufacturing and Samsung Foundry driving capital expenditure normalization after memory sector retrenchment.
For Market Incumbents: Consolidate installed base leverage through embedded upgrade pathways in multi-year platform agreements, cross-selling adjacent process control modules to KLA Corporation's patterned wafer inspection fleet. Defend against hybrid electron-optical substitution by deepening computational imaging R&D to compress resolution gaps at sub-3nm nodes. Prioritize certification investment for FDA and NMPA traceability mandates to lock in medical and automotive-grade procurement specifications. For New Entrants and Emerging Players: Differentiate on AI-assisted defect classification capabilities, targeting Japan-based foundries where neural network-enhanced pattern recognition accelerates yield ramp timelines. Penetrate India's PLI-aligned semiconductor manufacturing incentives by establishing local calibration infrastructure ahead of fab commissioning cycles. White-space concentration sits in spectroscopy-based thin-film metrology for heterogeneous integration lines, where interposer and chiplet architectures create new measurement plane requirements underserved by incumbent laser scanning dominance. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with underoptimized precision optics divisions, particularly Japanese manufacturers with deep-ultraviolet light source expertise stranded outside semiconductor core strategies. Long-term viability hinges on electron-optical hybrid technology transitions and regulatory data architecture mandates reshaping equipment specifications. Monitor EUV scanner deployment cadence at Intel Foundry Services as inflection indicator for North American capital expenditure normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration with EUV Scanners | ASML Holding N.V. tightens process windows by embedding inspection data into scanner feedback loops. |
| AI-Assisted Defect Classification | Machine learning integration reduces false positives for Japan-based foundries accelerating yield ramps. |
| Geographic Expansion into India | PLI scheme alignment attracts calibration infrastructure investment ahead of domestic fab commissioning. |
| Coating Material Supply Security | Pre-certified supply chains mitigate REACH restriction risks for South Korean memory manufacturers. |
| Equipment-as-a-Service Transition | U.S. aerospace-defense foundries adopt subscription models under long-term volume commitment structures. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with fab operations directors, metrology procurement managers, process control engineers, and EUV lithography specialists; and secondary validation through SEC equipment vendor filings, SEMI capital expenditure databases, and national semiconductor industry association reports. Bottom-up triangulation across wafer fab equipment spending patterns and top-down reconciliation against lithography tool deployment schedules anchored volume estimates.
Across the projection horizon, the analytical framework modeled segmentation dimensions including inline versus offline platform architecture, laser scanning versus spectroscopy technology modalities, foundry versus IDM customer type, and defect inspection versus critical dimension measurement application categories. CAGRs derived from equipment vendor order backlog analysis and foundry capital intensity ratios normalized by wafer starts. Industry-specific forecast inputs incorporated EUV node transition timelines and regulatory traceability mandate implementation schedules.
Decision-makers should treat outputs as directional under assumptions of sustained EUV lithography adoption and stable REACH coating material qualification pathways; material deviation in memory sector capital expenditure or trade restriction intensity would warrant model refresh. Recalibration cycles align with material shifts in foundry node transition cadence and regulatory data retention requirement enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Semiconductor Test Socket Market
Test and Measurement
North America Electrical Testing Services Market
Test and Measurement
Sound Level Measurement Meter Market
Test and Measurement
High Rate Discharge Test Machine Market
Test and Measurement
In-Circuit Test Market
Test and Measurement
Surface Vision and Inspection Equipment Market
Test and Measurement
Flow Meter Calibration Market
Test and Measurement
Digital Weighing Terminal Market
Test and Measurement
Creep and Stress Rupture Testers Market
Test and Measurement
AI-Enabled Testing Market
Test and Measurement
Psophometer Market
Test and Measurement
EMC Testing Market
Test and Measurement
Europe NDT Equipment Market
Test and Measurement
DSL Tester Market
Test and Measurement
Liquid Immersion Cooling Fluid Compatibility Test Equipment Market
Test and Measurement
Melt Flow Tester Market