
 Density Tester Market | 2026-2036
Density Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Density Tester Market Analysis
ISO 17025 laboratory accreditation is unwinding competitive access for density tester suppliers without certified calibration traceability. Anton Paar GmbH leverages its Austrian manufacturing base to dominate high-precision digital density meter production. Mettler-Toledo International Inc. sustains R&D intensity across gravimetric and vibrational measurement platforms. Thermo Fisher Scientific Inc. extends its channel control through integrated laboratory workflow solutions that bundle density testing with complementary analytical instruments.
A density tester measures the mass per unit volume of liquids, solids, or gases using oscillating U-tube, buoyancy, or gas pycnometry principles with precision typically reaching 0.0001 g/cm³ for laboratory-grade instruments. The device serves primarily to verify material consistency, purity, and compliance with formulated product specifications across industrial quality control and research settings. Digital density meters lead product type revenue due to automation advantages and data logging integration, while pycnometers retain niche dominance in porous solid characterization where gas displacement methods prove essential. Gravimetric technique technology commands mature margin pools in food industry applications, whereas ultrasonic measurement is displacing legacy hydrometers in chemical sector inline process monitoring.
EPA methods and FDA cGMP guidelines shape density tester specifications in the United States, particularly for pharmaceutical companies validating active ingredient concentrations. EMA's ICH Q2(R1) analytical validation requirements and REACH substance identification protocols drive European demand for certified reference-standard traceability. Stakeholders must monitor evolving ISO standards for digital calibration certificates and decide whether cloud-connected density meters justify premium positioning against standalone laboratory units.
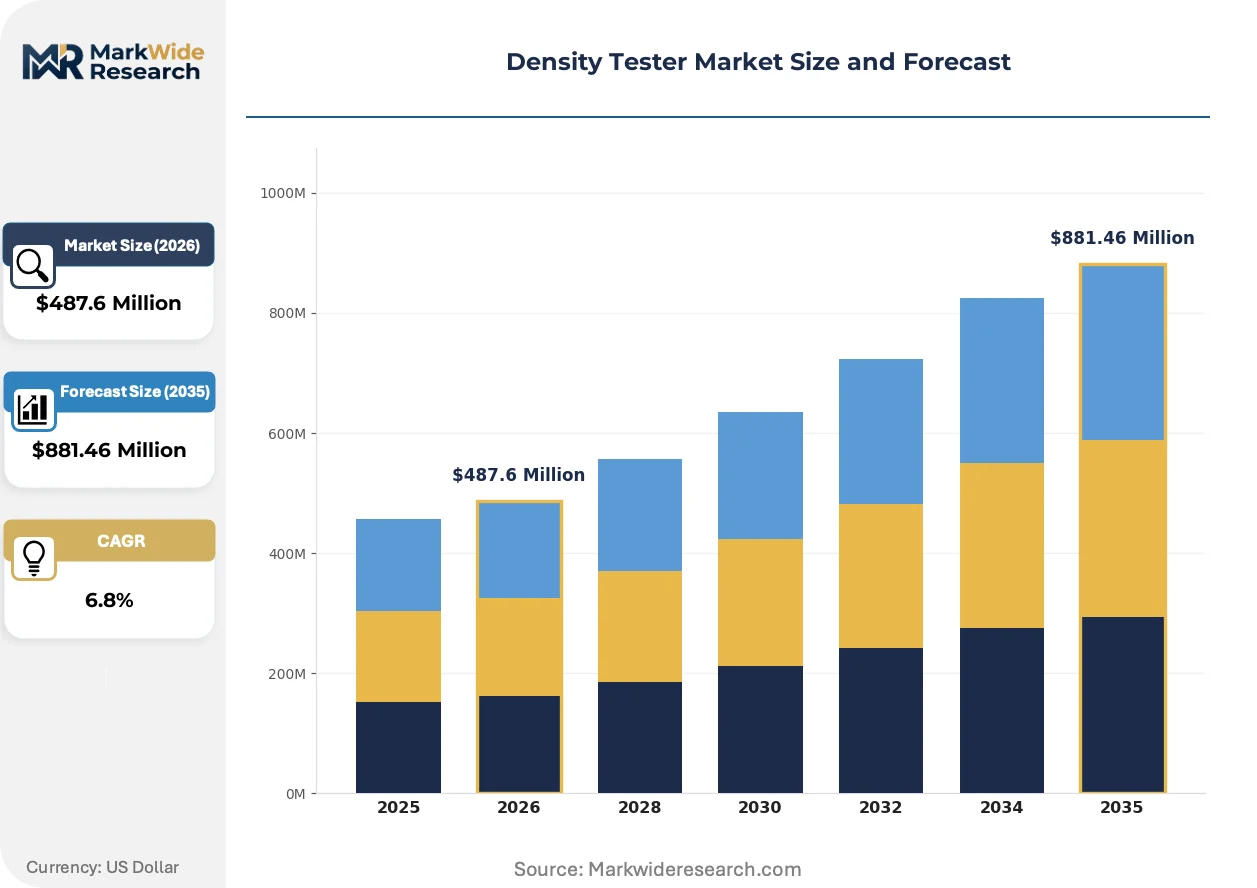
Market Dynamics
Digital calibration certificate mandates under ISO/IEC 17025 are compressing supplier access and forcing capital upgrades across laboratory instrumentation networks.
Growth Catalysts
- REACH substance identification:ECHA's purity verification protocols compel chemical manufacturers to deploy certified digital density meters for batch consistency documentation.
- Inline process monitoring:Ultrasonic measurement adoption in chemical sector continuous production lines eliminates manual sampling bottlenecks.
- Pharmaceutical cGMP:FDA validation requirements for active ingredient concentration testing drive replacement cycles of legacy hydrometer installations.
Market Restraints
- Precision sensor supply:Oscillating U-tube quartz components concentrate among Japanese and Austrian specialty glass suppliers, creating input vulnerability.
- Calibration infrastructure:ISO 17025-accredited service capacity remains structurally limited outside Germany, Switzerland, and Massachusetts.
- Gravimetric substitution:Food industry quality control retains mature buoyancy methods where automation returns fail to justify digital meter capex.
Strategic Opportunities
- Cloud-connected meters:Remote diagnostics and automated data logging create premium positioning against standalone laboratory units for multi-site pharmaceutical networks.
- Porous solid characterization:Gas pycnometry demand accelerates in battery materials and additive manufacturing powder verification applications.
- India PLI scheme:Domestic chemical and pharmaceutical manufacturing incentives expand quality control instrumentation procurement from import-dependent bases.
Industry Challenges
- Metrology talent scarcity:Certified calibration technicians with ISO 17025 traceability expertise command premium wages and extended recruitment timelines.
- Legacy system integration:Digital density meter deployment in existing LIMS environments requires custom API development and validation documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Density Tester Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Density Meters, Hydrometers, Pycnometers, Laboratory Balance End User: Chemical Sector, Food Industry, Pharmaceutical Companies, Educational Institutions Technology: Optical Density Measurement, Gravimetric Technique, Ultrasonic Measurement, Vibrational Method Application: Quality Control, Research & Development, Product Formulation, Compliance Testing |
| Companies Covered | Anton Paar GmbH, Mettler-Toledo International Inc., Emerson Electric Co., Endress+Hauser Group Services AG, Yokogawa Electric Corporation, Thermo Fisher Scientific Inc., AMETEK Inc., Horiba Scientific, Rudolph Research Analytical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Density Tester Market Emerging Trajectories
Measurement modality diversification and regulatory data integrity requirements are restructuring competitive advantage around calibration traceability rather than hardware specifications alone.
MEMS-based density sensing is fragmenting the traditional oscillating U-tube architecture by enabling portable, battery-operated units for field deployment in remote chemical processing facilities. Pipeline operators and offshore platform engineers are piloting these devices for real-time crude oil characterization where laboratory access is impractical. The technology is fragmenting service revenue models by shifting calibration dependency from manufacturer-controlled networks toward distributed, accredited third-party providers.
EMA's ICH Q2(R1) analytical validation requirements are tightening documentation standards for pharmaceutical density testing across European manufacturing sites. Batch release protocols now mandate electronic records with audit trails, disqualifying analog hydrometers from regulatory submissions. German and Swiss contract manufacturing organizations are consolidating supplier relationships around vendors offering integrated validation packages.
Service unbundling is separating hardware procurement from calibration contracts in large pharmaceutical and chemical accounts. Buyers are negotiating multi-year metrology service agreements independent of initial instrument purchase, pressuring vendor margin structures. This pattern concentrates in North American and Western European markets where laboratory outsourcing and centralized metrology functions have matured.
Density Tester Market Segmentation
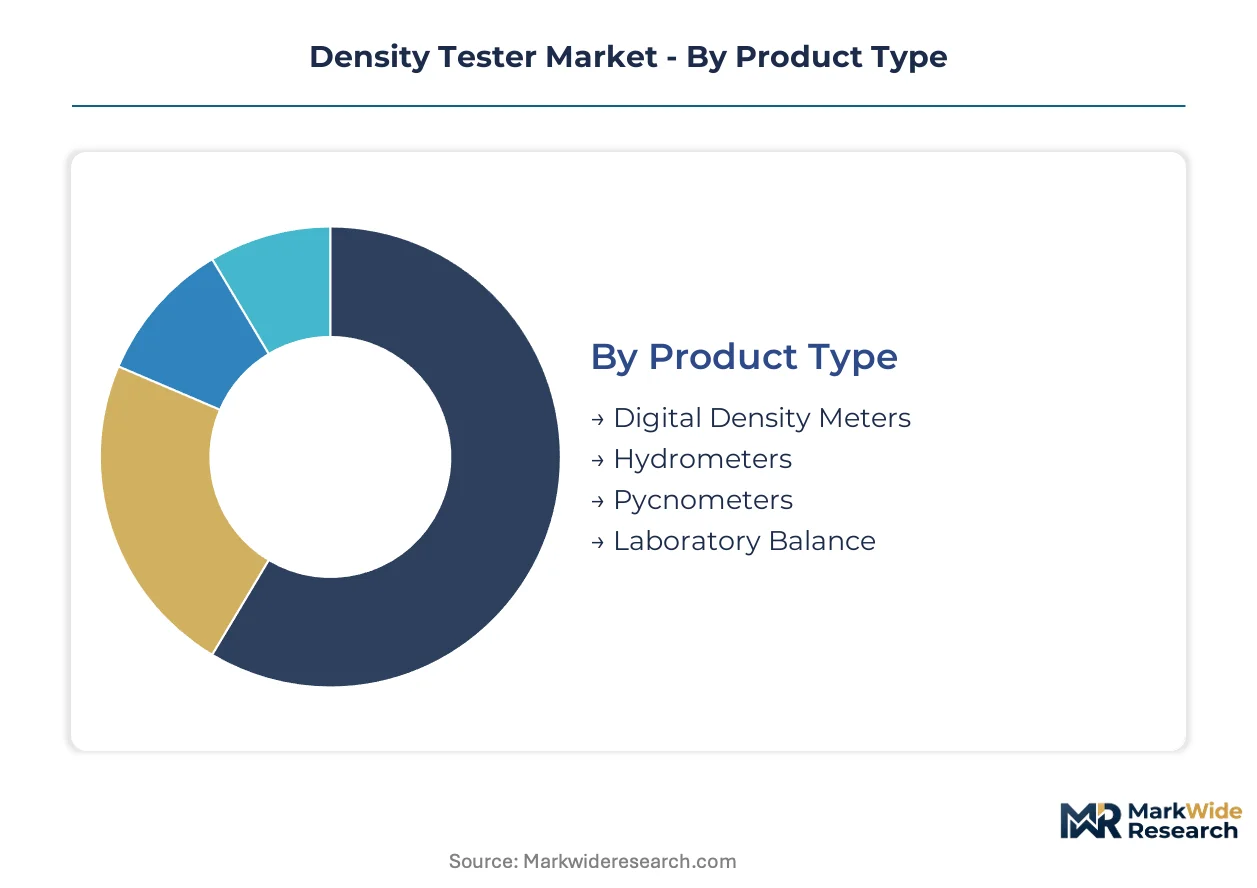
Segmentation in the density tester market reveals distinct margin architectures across measurement technologies and compliance-driven end-use verticals. Procurement patterns diverge sharply between automated laboratory networks and manual field applications, creating tiered pricing power that favors vendors with integrated calibration ecosystems.
Product Type:
Digital density meters command premium pricing through automation advantages and regulatory data integrity features, while legacy instruments defend position in cost-sensitive applications.
- Digital Density Meters:Oscillating U-tube and vibrating element architectures deliver precision to 0.0001 g/cm³ with automated temperature compensation and electronic data logging. Pharmaceutical companies in Germany and Switzerland are consolidating procurement around these units to satisfy EMA audit trail requirements for batch release documentation.
- Hydrometers:Glass float instruments based on Archimedes' principle remain entrenched in food industry applications where manual sampling protocols persist and capital constraints limit digital meter adoption. Breweries and dairy processors across Bavaria and Wisconsin continue specifying traditional hydrometers for routine density checks.
- Pycnometers:Gas displacement systems dominate porous solid characterization in battery materials and additive manufacturing powder verification.
- Laboratory Balance:Gravimetric density determination using precision weighing and known-volume vessels retains niche presence in educational settings.
The dominant share belongs to Digital Density Meters, while Pycnometers are closing the gap fastest through battery materials demand.
End User:
Volume concentration varies dramatically by compliance intensity, with regulated industries absorbing price premiums for certified traceability that commodity sectors reject.
- Chemical Sector:Continuous production facilities deploy inline ultrasonic sensors for real-time density monitoring, eliminating manual sampling delays. REACH substance identification mandates from ECHA are forcing German and Dutch chemical manufacturers to document batch consistency through certified digital meters with ISO 17025 calibration chains.
- Pharmaceutical Companies:cGMP validation requirements from FDA and EMA drive replacement cycles and cloud-connected meter adoption for multi-site data integration. Swiss contract manufacturing organizations are bundling density testing into integrated laboratory workflow solutions.
- Food Industry:Mature buoyancy methods persist where automation returns fail to justify digital meter capital expenditure.
- Educational Institutions:Training laboratories prioritize cost-effective hydrometers and basic pycnometers for undergraduate instruction.
Chemical Sector procurement leads absolute volume, though Pharmaceutical Companies generate the steepest expansion trajectory through regulatory upgrade cycles.
Technology:
Measurement modality selection directly determines service revenue attachment and calibration dependency structures.
- Vibrational Method:Oscillating U-tube and vibrating fork technologies achieve highest precision for liquid samples in pharmaceutical quality control. Austrian and Japanese quartz component suppliers concentrate input supply, creating vulnerability for manufacturers without captive glassmaking capacity.
- Ultrasonic Measurement:Transit-time and Doppler principles enable non-contact inline monitoring in chemical process piping. Offshore platform engineers in the North Sea are piloting portable MEMS-based units for crude oil characterization where laboratory access is impractical.
- Gravimetric Technique:Weighing-based density determination retains installed base in food industry applications with established manual protocols.
- Optical Density Measurement:Refractive index correlation methods serve specialized applications in beverage and petroleum testing.
Vibrational Method holds the revenue concentration, yet Ultrasonic Measurement is gaining share fastest through process automation adoption.
Application:
Regulatory documentation requirements are restructuring competitive advantage around electronic record capabilities rather than raw measurement precision.
- Quality Control:Routine batch testing in manufacturing environments demands high-throughput automation with LIMS integration. FDA cGMP and EMA ICH Q2(R1) protocols now mandate electronic records with audit trails, disqualifying analog instruments from regulatory submissions.
- Compliance Testing:REACH, RoHS, and EPA method verification requires certified reference-standard traceability and documented calibration chains. German testing laboratories are consolidating supplier relationships around vendors offering integrated validation packages.
- Research & Development:Method development and materials characterization drive demand for flexible, multi-technique platforms.
- Product Formulation:Consistency verification during recipe optimization prioritizes speed and repeatability over absolute precision.
Quality Control commands the dominant procurement volume, while Compliance Testing shows the sharpest growth acceleration through regulatory tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical quality control directors and chemical plant engineers represent the dominant buyer archetypes across major density tester procurement markets. Their purchasing decisions center on calibration traceability and regulatory documentation capabilities rather than hardware specifications alone.
United States
FDA cGMP validation requirements and EPA method compliance drive pharmaceutical and environmental testing demand. The country's national pharmaceutical regulator mandates electronic records with audit trails for batch release documentation. Massachusetts hosts concentrated laboratory instrumentation procurement from biotechnology clusters around Cambridge and Worcester.
Germany
REACH substance identification protocols and ECHA purity verification standards compel chemical manufacturers to upgrade quality control infrastructure. The country's chemical sector regulator enforces strict batch consistency documentation requirements. Bavarian industrial zones around Munich and Ludwigshafen anchor elevated investment in certified digital density meters.
Switzerland
Swissmedic pharmaceutical manufacturing standards and contract research organization expansion accelerate precision instrumentation adoption. The national pharmaceutical regulator requires validated analytical methods for active ingredient concentration testing. Basel and Zurich pharmaceutical manufacturing corridors concentrate procurement of cloud-connected meters for multi-site data integration.
Japan
METI industrial standards and PMDA pharmaceutical quality guidelines shape density tester specifications for domestic manufacturers. The country's pharmaceutical and medical device agency mandates rigorous analytical validation for product registration submissions. Osaka and Tokyo industrial clusters sustain demand for oscillating U-tube precision instruments.
India
CDSCO pharmaceutical manufacturing standards and PLI scheme domestic production incentives expand quality control instrumentation procurement. The national pharmaceutical regulator tightens documentation requirements for export-oriented formulations. Maharashtra and Gujarat chemical-pharmaceutical corridors transition from import-dependent bases toward certified calibration infrastructure.
Density Tester Market Vendor Landscape
Player mix skews toward precision instrumentation specialists with captive calibration ecosystems and diversified industrial conglomerates with process automation portfolios. Market structure concentrates around Austrian and Swiss precision manufacturers with ISO 17025-accredited service networks. Three archetypes dominate: quartz-component precision specialists, integrated laboratory workflow providers, and process automation industrialists. Competitive moves center on calibration service unbundling and cloud connectivity feature differentiation.
Among Austrian and Swiss precision specialists, Anton Paar GmbH and Mettler-Toledo International Inc. exemplify the calibration-anchored archetype with manufacturing bases in Graz and Greifensee respectively. Thermo Fisher Scientific Inc. represents the integrated laboratory workflow model, bundling density testing within broader analytical instrumentation portfolios. These three occupy positions where service revenue attachment and regulatory validation packages determine pricing power rather than hardware specifications alone.
| Leading Market Players |
|---|
| Anton Paar GmbH |
| Mettler-Toledo International Inc. |
| Emerson Electric Co. |
| Endress+Hauser Group Services AG |
| Yokogawa Electric Corporation |
| Thermo Fisher Scientific Inc. |
| AMETEK Inc. |
| Horiba Scientific |
| Rudolph Research Analytical |
| Others |
Supply Flow & Price Mechanics
Quartz-component manufacturing scale in Graz and Greifensee anchors pricing floors for precision digital density meters, with ISO 17025 calibration infrastructure concentration in Germany and Switzerland reinforcing margin premiums for certified traceability. Austrian and Swiss captive glassmaking capacity insulates Anton Paar GmbH and Mettler-Toledo International Inc. from input volatility that compresses pricing power for assembly-only competitors.
Pricing Analysis
Cost-plus contracts with quartz-component indexation dominate procurement for oscillating U-tube instruments, with pricing stratifying across ISO 17025-certified premium tiers, standard laboratory-grade units, and economy hydrometers lacking electronic data logging. Price differentiation hinges on calibration certificate grade and after-sales service bundling, with pharmaceutical companies in Basel and Cambridge absorbing premiums for audit-trail compliance. Pricing pressure stems from MEMS-based portable units displacing field-service revenue models. Educational institutions in Bavaria and Wisconsin exhibit highest price sensitivity, prioritizing basic hydrometers over digital meters.
Supply Chain Analysis
Austrian and Japanese quartz component supply underwrites precision instrument manufacturing, with specialty glass concentrate in Hoya and Schott AG facilities creating single-source vulnerability for oscillating U-tube manufacturers. Raw material dependencies encompass high-purity quartz tubing, platinum-temperature sensors, and precision-machined U-tube housings. Supply chain risk centers on tariff exposure for Japanese quartz imports into European assembly facilities. Distribution runs through manufacturer-direct service networks for pharmaceutical accounts, with regional distributors handling food industry and educational procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around ISO 17025 calibration traceability constructs defensive moats for incumbents with accredited service networks, as FDA cGMP and EMA ICH Q2(R1) requirements elevate switching costs for pharmaceutical buyers.
For Market Incumbents: Shield installed base revenue by embedding cloud-connected meters within multi-site LIMS architectures, raising substitution costs for pharmaceutical contract manufacturers. Deepen backward integration into quartz component production to offset Japanese supply concentration. Prioritize certification investment in India PLI scheme corridors to capture domestic chemical sector procurement transitioning from import dependency. For New Entrants and Emerging Players: CDSCO fast-track accreditation for export-oriented pharmaceutical manufacturers in Maharashtra and Gujarat offers white-space entry with lower incumbent saturation than European markets. Target ultrasonic inline monitoring for chemical sector continuous production lines where legacy hydrometer displacement creates procurement windows. Pursue gas pycnometry specialization for battery materials characterization, leveraging porous solid demand acceleration outside established vibrational-method strongholds. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among calibration-anchored precision specialists with ISO 17025-accredited service networks, suggesting durable cash-flow quality through regulatory upgrade cycles. Long-term viability favors acquisition targets combining captive quartz manufacturing with cloud-connected meter portfolios. Monitor EMA electronic-record mandate enforcement as inflection signal for analog instrument obsolescence acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Accreditation Expansion | CDSCO and EMA tightening secure multi-year calibration contracts with pharmaceutical exporters in Gujarat. |
| MEMS Sensor Platform Development | Portable battery-operated units capture offshore platform crude oil testing outside laboratory infrastructure. |
| Cloud-Connected Meter Deployment | FDA audit-trail requirements drive LIMS-integrated procurement from Swiss contract manufacturing organizations. |
| Gas Pycnometry Capacity Addition | Battery materials and additive manufacturing powder verification absorb capital outside saturated liquid-testing segments. |
| India PLI Localization Partnership | Domestic chemical sector incentives redirect procurement from import-dependent bases toward certified local calibration. |
Methodological Framework
Desk research of FDA cGMP guidance documents, EMA ICH Q2(R1) validation protocols, and ISO 17025 accreditation registries preceded structured interviews with pharmaceutical quality control directors, chemical plant engineers, and laboratory instrumentation procurement managers. Secondary validation drew from SEC 10-K instrument segment disclosures, REACH substance identification filings, and customs trade data for quartz component flows. Bottom-up unit economics for digital density meter installations triangulated against top-down chemical and pharmaceutical sector capital expenditure patterns.
Variance decomposition across product type, end-user vertical, measurement technology, and geographic regulatory cluster shaped analytical framework construction over the projection horizon. CAGRs derived from segment-level replacement cycle analysis, regulatory mandate phase-in schedules, and capital expenditure intention surveys. Industry-specific forecast inputs encompassed EMA electronic-record enforcement timelines and India PLI scheme disbursement trajectories for quality control infrastructure.
Underlying assumptions cover REACH and FDA cGMP continuity, with deviation risk concentrated in MEMS sensor substitution pace and ISO 17025 accreditation capacity expansion outside Germany and Switzerland. Practitioners should keep alternative scenarios live as EMA audit-trail mandate enforcement intensity and India domestic manufacturing incentive durability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
AI-Enabled Semiconductor Defect Classification and Review Systems Market
Test and Measurement
Compression Testing Machines Market
Test and Measurement
Electromagnetic Compatibility Test Equipment and Testing Services Market
Test and Measurement
Digital Thickness Gauge Market
Test and Measurement
Tribometer Market
Test and Measurement
High-Throughput Liquid Handling Robot Performance Test Equipment Market
Test and Measurement
5G Testing Equipment Market
Test and Measurement
Gigabit Ethernet Test Equipment Market
Test and Measurement
Digital Depth Gauges Market
Test and Measurement
Production Testing Market
Test and Measurement
Electrolyzer Test System Market
Test and Measurement
Dosimeter Market
Test and Measurement
Rohs Tester Market
Test and Measurement
Insulation Testing Instrument Market
Test and Measurement
Sand Abrasion Tester Market
Test and Measurement
Permeation Testing Machines Market