
 Semiconductor Assembly Equipment Market | 2026-2036
Semiconductor Assembly Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Assembly Equipment Market Analysis
ISO 14644 cleanroom certification is redrawing competitive boundaries for semiconductor assembly equipment suppliers. ASM Pacific Technology leverages its integrated die bonding and packaging portfolio to sustain leadership in advanced fan-out wafer-level packaging. Tokyo Electron Limited anchors its position through precision plasma processing tools that feed into assembly workflows. Kulicke & Soffa Industries specializes in wire bonding systems that dominate legacy interconnect segments while navigating transitions to copper pillar and thermocompression bonding.
Semiconductor assembly equipment encompasses the machinery used to attach, interconnect, encapsulate, and test individual die after front-end wafer fabrication, operating at placement accuracies below 5 micrometers and throughput rates exceeding 20,000 units per hour for high-volume memory packaging. Its primary purpose is converting bare silicon into functional packaged components ready for surface mount or through-hole board assembly. Die bonding equipment captures the largest margin pool as heterogeneous integration and chiplet architectures drive demand for high-precision placement of thinned die. Wire bonding equipment retains volume dominance in automotive and industrial power devices where gold and copper ball bonding remain cost-optimal. Test equipment represents the fastest-growing segment as known-good-die requirements intensify for AI accelerator and advanced driver-assistance system applications.
The EPA regulates hazardous substance handling in U.S. assembly facilities, while REACH restricts lead and halogenated compounds in European packaging materials, and China's GB standards mandate energy efficiency benchmarks for production equipment imports. These frameworks shape equipment specifications, material compatibility requirements, and facility qualification timelines across manufacturing locations. Stakeholders must monitor how divergent chemical substance regulations affect bonding wire metallurgy choices and encapsulant formulations in multi-region supply chains.
Market Dynamics
Heterogeneous integration architectures are compressing traditional packaging hierarchies, forcing assembly equipment suppliers to merge front-end precision with back-end throughput in single-platform configurations. Taiwan's concentration of advanced packaging capacity is amplifying equipment qualification bottlenecks as vendors compete for limited cleanroom validation slots.
Growth Catalysts
- EU Chips Act capital subsidies:European governments are funding greenfield assembly facilities in Germany and Spain, mandating ISO 14644 Class 5 cleanroom standards that favor precision equipment suppliers with established contamination control protocols.
- Electric vehicle power modules:Automotive OEMs require thermocompression bonding systems for silicon carbide die attachment, pulling equipment specifications toward higher force accuracy and real-time temperature profiling.
- Chiplet disaggregation:AMD and Intel architectures are fragmenting monolithic dies into multiple chiplets, multiplying die bonding steps per packaged unit and extending equipment utilization cycles.
Market Restraints
- Gold wire price volatility:Precious metal fluctuations compress margin predictability for wire bonding equipment operators serving automotive and industrial segments where gold ball bonding remains specification-locked.
- Sub-5 micrometer placement tolerance:Fan-out wafer-level packaging demands strain the mechanical limits of conventional die bonding architectures, extending development timelines and qualification costs.
- Taiwan supply concentration:Over 60 percent of advanced packaging capacity resides in Hsinchu and Taichung Science Parks, creating single-point vulnerability to seismic or geopolitical disruption.
Strategic Opportunities
- India PLI scheme for semiconductors:Central government incentives are attracting OSAT investment in Gujarat and Karnataka, opening virgin demand for wire bonding and test equipment without incumbent vendor lock-in.
- Copper pillar interconnect migration:High-performance computing and AI accelerators are transitioning from wire bonding to copper pillar flip-chip, creating replacement demand for thermocompression and mass reflow systems.
- Known-good-die test integration:2.5D and 3D packaging is merging die bonding with in-line electrical test, enabling equipment suppliers to capture adjacent margin pools through subsystem consolidation.
Industry Challenges
- Mechatronics engineering scarcity:The intersection of precision motion control, thermal management, and vision systems requires specialized talent concentrated in Japan and Germany, constraining equipment development velocity.
- Cleanroom certification timelines:ISO 14644 Class 3 and Class 5 qualifications for new equipment platforms extend 18-24 months, delaying revenue recognition for next-generation bonding systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Assembly Equipment Market |
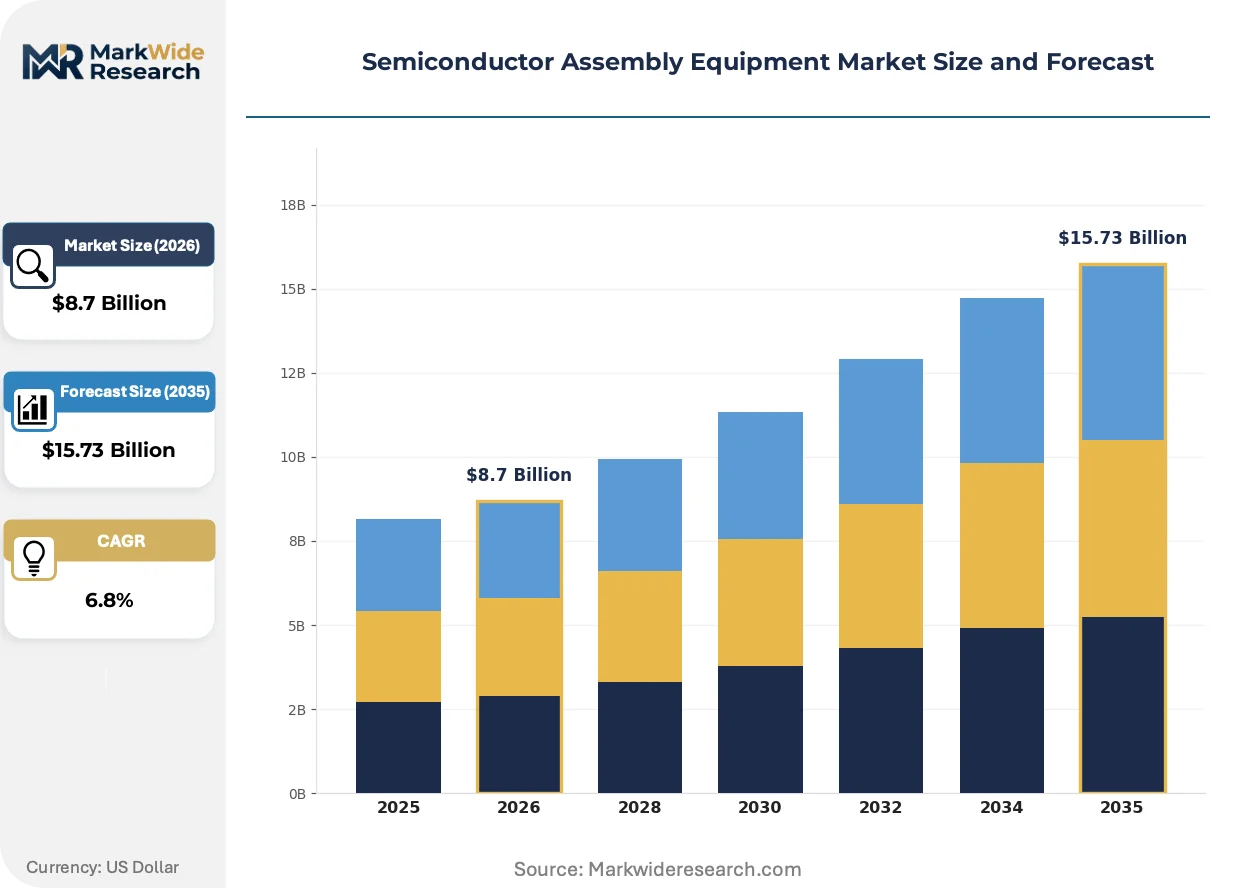
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Die Bonding Equipment, Wire Bonding Equipment, Test Equipment, Packaging Equipment Technology: Flip Chip, Surface Mount Technology, Through-Hole Technology, Chip-on-Board End User: Consumer Electronics, Automotive, Telecommunications, Industrial Application: Microprocessors, Memory Devices, Sensors, Power Devices |
| Companies Covered | Applied Materials, ASM Pacific Technology, Tokyo Electron Limited, Teradyne, Kulicke & Soffa Industries, Disco Corporation, Besi, Veeco Instruments, SUSS MicroTec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Assembly Equipment Market Emerging Trajectories
Thermocompression bonding architectures are overtaking traditional wire bonding in high-value compute segments, while regulatory chemical restrictions and buyer consolidation are reshaping equipment specifications and commercial relationships.
Hybrid bonding technology is supplanting microbump interconnects in 3D NAND and high-bandwidth memory stacks. Samsung and SK Hynix are qualifying equipment for wafer-to-wafer and die-to-wafer bonding at sub-2 micrometer pitch. This shift is compressing the addressable market for conventional flip-chip bonders while expanding demand for plasma activation and precision alignment subsystems.
REACH restrictions on lead and halogenated flame retardants are forcing encapsulant reformulation across European packaging facilities. Equipment suppliers must validate material compatibility with new molding compound chemistries, extending qualification protocols. Automotive power module packaging in Germany and France faces the tightest compliance timelines, pushing OSATs toward equipment vendors with established green material process libraries.
Consolidated procurement by tier-one OSATs is displacing fragmented equipment purchasing across mid-tier packaging houses. ASE Group and Amkor are negotiating enterprise-level service contracts bundling die bonding, wire bonding, and test platforms with predictive maintenance analytics. This concentration is most pronounced in Taiwan and Singapore, where scale economics favor single-vendor relationships over best-of-breed equipment sourcing.
Semiconductor Assembly Equipment Market Segmentation
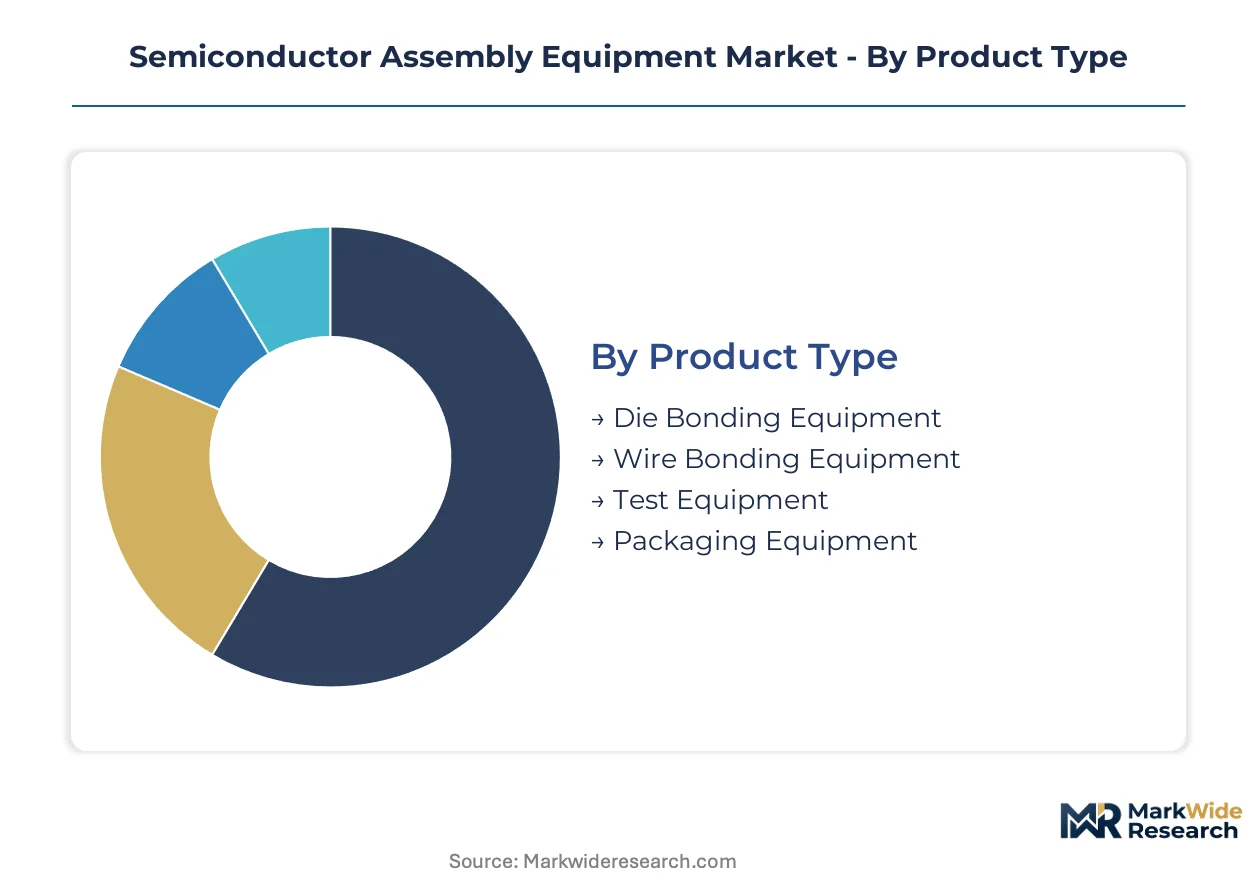
Segmentation reveals how heterogeneous integration and automotive electrification are fragmenting demand across equipment categories. Each dimension exposes distinct pressure points where substitute technologies threaten incumbent segments while opening adjacent margin pools.
Product Type:
Wire bonding equipment faces the most acute substitution pressure as copper pillar and thermocompression architectures displace gold ball interconnects in high-performance compute packaging.
- Die Bonding Equipment:Precision placement systems handle thinned die at sub-5 micrometer accuracy for chiplet architectures. Demand concentrates in Taiwan's advanced packaging facilities where ASE Group and Amkor are expanding fan-out wafer-level packaging capacity for AI accelerators.
- Wire Bonding Equipment:Ball and wedge bonding systems dominate automotive power module assembly where gold and copper wire interconnects remain cost-optimal. German and Japanese automotive OSATs specification-lock these systems for reliability-critical engine control and inverter modules.
- Test Equipment:In-line electrical verification systems for known-good-die requirements.
- Packaging Equipment:Encapsulation and molding systems for protective component housing.
Wire bonding equipment anchors the volume base while die bonding equipment gains share at the steepest rate.
Technology:
Cost tier stratification separates premium flip-chip platforms from commodity through-hole systems serving price-sensitive industrial segments.
- Flip Chip:Direct die-to-substrate interconnect using solder bumps or copper pillars eliminates wire bond loops for improved electrical performance. High-bandwidth memory and AI accelerator packaging in South Korea and Taiwan are pulling equipment specifications toward sub-100 micrometer bump pitch capability.
- Surface Mount Technology:Automated placement and reflow of packaged components onto printed circuit boards. Consumer electronics assembly in Vietnam and Mexico relies on high-throughput SMT lines where equipment utilization rates determine contract manufacturer margins.
- Through-Hole Technology:Component leads inserted through board holes for mechanical robustness in industrial applications.
- Chip-on-Board:Bare die directly mounted to substrates for miniaturized sensor and LED packaging.
Surface mount technology anchors the volume base while flip chip gains share at the steepest rate.
End User:
Application maturity varies sharply across end-use sectors, with automotive qualification timelines extending equipment replacement cycles versus consumer electronics velocity.
- Automotive:Power module and sensor packaging for electric vehicle platforms and advanced driver-assistance systems. German OEMs and tier-one suppliers in Stuttgart and Munich are mandating AEC-Q100 qualification protocols that extend equipment validation timelines.
- Consumer Electronics:High-volume smartphone and wearable packaging where annual product cycles drive equipment refresh rates. Chinese OSATs in Shenzhen and Dongguan prioritize throughput over precision for mid-range device assembly.
- Telecommunications:Base station and optical module packaging for 5G infrastructure deployment.
- Industrial:Ruggedized component assembly for factory automation and power conversion systems.
Consumer electronics anchors the volume base while automotive gains share at the steepest rate.
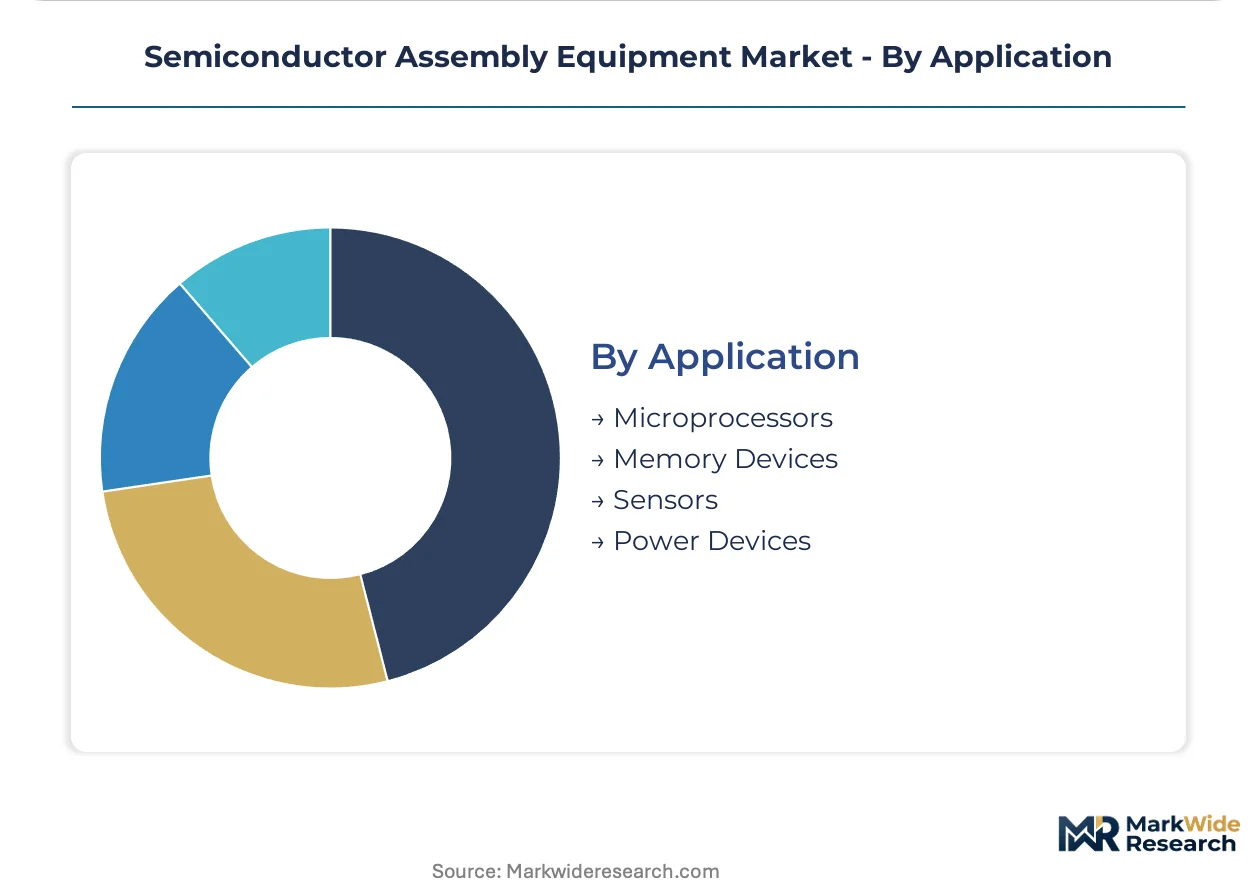
Application:
Customer type fragmentation separates memory manufacturers with captive equipment procurement from fabless designers outsourcing to OSAT consortiums.
- Memory Devices:3D NAND and high-bandwidth memory stacking require hybrid bonding and thermocompression equipment. Samsung and SK Hynix in South Korea are qualifying wafer-to-wafer bonding systems for sub-2 micrometer pitch interconnects.
- Power Devices:Silicon carbide and gallium nitride module packaging for electric vehicle traction inverters. Japanese power semiconductor manufacturers in Kyoto and Aichi prefectures specification-lock wire bonding systems for thermal cycling reliability.
- Microprocessors:Central processing unit and graphics processing unit packaging with complex multi-chiplet architectures.
- Sensors:Miniaturized environmental and inertial sensing element assembly for mobile and automotive applications.
Memory devices anchor the volume base while power devices gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capital subsidies from the EU Chips Act and India's PLI scheme are redirecting assembly equipment procurement toward greenfield facilities in Germany, Spain, Gujarat, and Karnataka. Taiwan retains dominant concentration for advanced packaging validation, while South Korea and Japan anchor hybrid bonding development for memory stacking.
Taiwan
Over 60 percent of advanced packaging capacity concentrates in Hsinchu and Taichung Science Parks, where ASE Group and Amkor compete for limited ISO 14644 Class 3 cleanroom validation slots. The National Development Council's semiconductor initiative funds local equipment testing infrastructure. Kaohsiung's emerging packaging corridor is absorbing thermocompression bonding systems for AI accelerator production.
South Korea
Samsung and SK Hynix are qualifying wafer-to-wafer bonding equipment for sub-2 micrometer pitch 3D NAND and high-bandwidth memory stacks. The Ministry of Trade, Industry and Energy's K-Semiconductor Belt program subsidizes domestic equipment procurement. Pyeongtaek and Icheon host the primary concentration of hybrid bonding cleanroom qualification activity.
Germany
Automotive power module packaging for silicon carbide traction inverters is pulling thermocompression specifications toward higher force accuracy. The EU Chips Act directly funds Infineon and Bosch greenfield assembly facilities in Dresden and Reutlingen. Stuttgart OEMs mandate AEC-Q100 qualification protocols that extend equipment replacement cycles versus consumer electronics velocity.
India
Central government PLI incentives are attracting OSAT investment in Gujarat's Dholera Semiconductor Park and Karnataka's Mysuru cluster without incumbent vendor lock-in. The Ministry of Electronics and Information Technology mandates phased manufacturing programs for bonding equipment localization. Tamil Nadu's Sriperumbudur electronics corridor is emerging as a secondary test equipment demand center.
Japan
Kyoto and Aichi prefectures specification-lock wire bonding systems for thermal cycling reliability in power semiconductor applications. METI's semiconductor equipment subsidy program supports domestic bonding tool development for 2.5D packaging. Nagoya's industrial automation ecosystem supplies precision motion control subsystems to global equipment vendors.
Semiconductor Assembly Equipment Market Vendor Landscape
Player mix skews toward precision equipment specialists with integrated cleanroom certification capabilities and diversified industrial conglomerates with captive semiconductor tool divisions. The vendor base separates into three strategic archetypes: die bonding precision specialists, wire bonding volume suppliers, and test equipment integrators. Competitive positioning hardens through 18-24 month ISO 14644 qualification timelines that lock customer relationships. Consolidated procurement by tier-one OSATs is displacing fragmented purchasing across mid-tier packaging houses.
Within the precision equipment tier, ASM Pacific Technology and Tokyo Electron Limited exemplify archetypes with established contamination control protocols for fan-out wafer-level packaging. Kulicke & Soffa Industries occupies a position representing wire bonding specialists navigating metallurgy transitions. Among test equipment providers, Teradyne anchors the segment addressing known-good-die requirements for heterogeneous integration architectures.
| Leading Market Players |
|---|
| Applied Materials |
| ASM Pacific Technology |
| Tokyo Electron Limited |
| Teradyne |
| Kulicke & Soffa Industries |
| Disco Corporation |
| Besi |
| Veeco Instruments |
| SUSS MicroTec |
| Others |
Supply Flow & Price Mechanics
Equipment utilization rates above 80 percent at Taiwan's advanced packaging facilities compress per-unit depreciation costs while simultaneously concentrating pricing power among ISO 14644-certified suppliers. This scale dynamic locks in price floors for precision die bonding platforms and amplifies margin pressure on second-tier wire bonding vendors without established cleanroom validation track records.
Pricing Analysis
Certification level creates the primary spread between equipment tiers, with ISO 14644 Class 3-validated platforms commanding substantial premiums over Class 5 alternatives. Transactional per-unit pricing dominates, though tier-one OSATs negotiate enterprise service contracts bundling predictive maintenance analytics. Price differentiation rests on contamination control pedigree and geographic proximity to validation infrastructure. Cost compression runs through legacy wire bonding segments as copper pillar migration intensifies. Automotive OSATs in Germany exhibit lowest price sensitivity due to AEC-Q100 specification-lock, while Chinese consumer electronics assemblers in Shenzhen prioritize throughput economics over precision premiums.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication and advanced packaging capacity, while Japan supplies precision motion control subsystems and Germany feeds automotive qualification protocols. Equipment manufacturing draws from high-grade granite for vibration-dampening bases, specialized ceramics for thermal management components, and precision ball screws from Swiss and Japanese suppliers. Single-source vulnerability concentrates in sub-5 micrometer vision systems sourced from German and Japanese optics specialists. Distribution runs through direct sales engineers embedded at ASE Group, Amkor, and Samsung facilities, supplemented by regional service hubs in Singapore and Dresden.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where ISO 14644 certification timelines create 18-24 month switching costs that cement incumbent relationships. Equipment vendors with validated cleanroom protocols and established service footprints hold durable defensive moats against unqualified challengers.
For Market Incumbents: Consolidate service contract penetration at ASE Group and Amkor through predictive maintenance analytics bundling. Expand thermocompression bonding capacity in Kaohsiung's emerging packaging corridor to capture AI accelerator demand. Defensive positioning requires countering hybrid bonding substitution in 3D NAND stacking through plasma activation subsystem integration. For New Entrants and Emerging Players: Anchor in India's Gujarat and Karnataka greenfield OSAT facilities where PLI incentives attract investment without incumbent vendor lock-in. Target wire bonding and test equipment segments where specification requirements remain less stringent than advanced packaging. A precision motion control partnership with Nagoya's industrial automation ecosystem offers credible qualification pathway. For Investors and Strategic Acquirers: Cleanroom-certified precision equipment specialists with established fan-out wafer-level packaging track records represent priority acquisition archetypes. Long-term viability hinges on exposure to heterogeneous integration and chiplet architectures rather than legacy interconnect segments. Watch hybrid bonding qualification timelines at Samsung and SK Hynix as inflection indicator for conventional flip-chip bonder obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 14644 Class 3 Certification Investment | 18-24 month qualification timelines lock tier-one OSAT relationships at ASE Group and Amkor facilities. |
| Plasma Activation Subsystem Integration | Hybrid bonding migration at Samsung and SK Hynix demands wafer surface preparation capabilities. |
| Predictive Maintenance Analytics Bundling | Enterprise service contracts with consolidated procurement teams displace fragmented equipment purchasing. |
| Gujarat Greenfield Facility Partnership | India PLI scheme attracts OSAT investment without established vendor relationships or incumbent lock-in. |
| Thermocompression Bonding Capacity Expansion | Silicon carbide power module demand from Stuttgart OEMs pulls equipment specifications toward higher force accuracy. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OSAT procurement directors, equipment engineering leads at ASE Group and Amkor, cleanroom facility managers in Hsinchu and Taichung Science Parks, and automotive power module packaging specialists at Infineon and Bosch. Secondary validation drew from SEC 10-K filings of listed equipment vendors, EU Chips Act subsidy disclosure documents, India's PLI scheme administrative records, and ISO 14644 certification registries. Bottom-up equipment shipment data triangulated against top-down capital expenditure disclosures from tier-one packaging houses.
Across the analysis window, the forecasting framework modeled demand by product type, technology node, end-use sector, and regional regulatory cluster. Segmentation dimensions included die bonding precision tier, wire bonding metallurgy specification, cleanroom classification requirement, and automotive qualification protocol. CAGRs were derived from equipment replacement cycle analysis, capacity expansion announcements, and technology transition velocity. Industry-specific inputs incorporated heterogeneous integration adoption curves, chiplet architecture proliferation, and thermocompression bonding penetration in power module applications.
Underlying assumptions cover sustained EU Chips Act funding disbursement, stable Taiwan seismic risk profiles, and continued gold wire price volatility within historical bands, with deviation risk concentrated in geopolitical disruption to Hsinchu-Taichung capacity concentration and accelerated hybrid bonding substitution timelines. Recalibration cycles align with material shifts in cleanroom certification backlogs, PLI scheme incentive revisions, and automotive OEM platform standardization announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Single Wafer Wet Cleaning Equipment Market
Semiconductor Equipment
300 Mm Front Opening Unified Pods (Foups) Market
Semiconductor Equipment
Photolithography Equipment Market
Semiconductor Equipment
Global Wafer Processing and Assembly Equipment Market
Semiconductor Equipment
Semiconductor Capital Equipment Market
Semiconductor Equipment
Dicing Equipment Market
Semiconductor Equipment
Vacuum Soldering System Market
Semiconductor Equipment
Reticle Pod Cleaning System Market
Semiconductor Equipment
North America Semiconductor Etch Equipment Market
Semiconductor Equipment
Nanoimprint Lithography System Market
Semiconductor Equipment
Dry Reactor Market
Semiconductor Equipment
Selective Soldering Equipment Market
Semiconductor Equipment
Cathode Stripping Machines Market
Semiconductor Equipment
Semiconductor Bonding Equipment Market
Semiconductor Equipment
Lithography Equipment Market
Semiconductor Equipment
Laser Annealing System Market