
 High Rate Discharge Test Machine Market | 2026-2036
High Rate Discharge Test Machine Market Size, Share, and Industry Trends Forecast 2026-2036
High Rate Discharge Test Machine Market Insights
Silicon carbide power conversion is rewriting how high rate discharge test machines manage thermal loads during pulsed current events. Arbin Instruments leverages its Texas-based R&D footprint to anchor custom test protocol development for next-generation solid-state cells. Chroma ATE dominates Taiwan's electronics testing ecosystem, extending its reach into mainland Chinese battery foundries through localized service networks.
A high rate discharge test machine evaluates battery cell and pack performance under extreme current draw conditions, typically executing pulse profiles exceeding 5C rates while capturing millisecond-resolution voltage and temperature telemetry for safety validation and cycle-life prediction. Benchtop configurations lead academic and small-lot manufacturing settings where flexibility outweighs throughput, while modular architectures represent the fastest-growing category as gigafactories scale test floors without full line replacement. Digital control technology occupies the premium tier, commanding margin pools from battery manufacturers seeking programmable waveform fidelity for EV cell qualification.
China's SAMR enforces GB standards that mandate high-rate abuse testing for traction battery certification, directly shaping equipment procurement specifications for domestic and export-bound manufacturers. The EU's Battery Regulation and CE marking requirements create parallel compliance pathways that European test service providers must satisfy for cross-border laboratory accreditation. Stakeholders should monitor how solid-state cell architectures alter pulse discharge signature requirements, as this transition will determine which test equipment platforms retain relevance across the next technology cycle.
Market Dynamics
Silicon carbide power conversion is compressing thermal management architectures across high rate discharge test equipment, forcing manufacturers to redesign current-handling subsystems around wide-bandgap semiconductors rather than legacy silicon IGBTs.
Growth Catalysts
- GB standards enforcement:China's SAMR mandates high-rate abuse testing for traction battery certification, compelling domestic and export-bound manufacturers to expand test floor capacity with compliant equipment.
- Solid-state cell qualification:Next-generation solid-state architectures require pulsed discharge protocols exceeding conventional lithium-ion parameters, driving replacement cycles among established battery foundries.
- Shenzhen-Nagoya manufacturing density:Cell production clusters in these metropolitan regions generate localized procurement of high-rate test machines to minimize logistics costs and enable rapid technical support.
Market Restraints
- Silicon carbide supply concentration:Wide-bandgap semiconductor fabrication concentrates among a limited supplier base, exposing test machine OEMs to input cost volatility and allocation constraints.
- CE marking complexity:The EU Battery Regulation creates parallel compliance pathways that extend laboratory accreditation timelines for European test service providers seeking cross-border certification.
- Legacy equipment substitution:Modular retrofit kits for existing test floors partially displace full-system replacement demand, compressing revenue per installation for incumbent suppliers.
Strategic Opportunities
- Indian battery manufacturing:PLI scheme incentives for domestic cell production create virgin demand for high-rate discharge validation equipment as greenfield gigafactories commission test infrastructure.
- Digital twin integration:Convergence of physical test hardware with predictive simulation platforms enables equipment vendors to capture recurring software revenue alongside capital sales.
- Second-life battery testing:Emerging aftermarket applications for repurposed EV cells require modified pulse profiles, opening specialized equipment segments distinct from virgin cell qualification.
Industry Challenges
- Power electronics talent scarcity:Design and commissioning of silicon carbide-based current sources demands specialized expertise that outpaces available engineering pipelines in East Asian manufacturing hubs.
- Multi-protocol firmware complexity:Equipment must simultaneously support evolving GB, IEC, and OEM-specific test scripts, straining software development resources and extending validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Rate Discharge Test Machine Market |
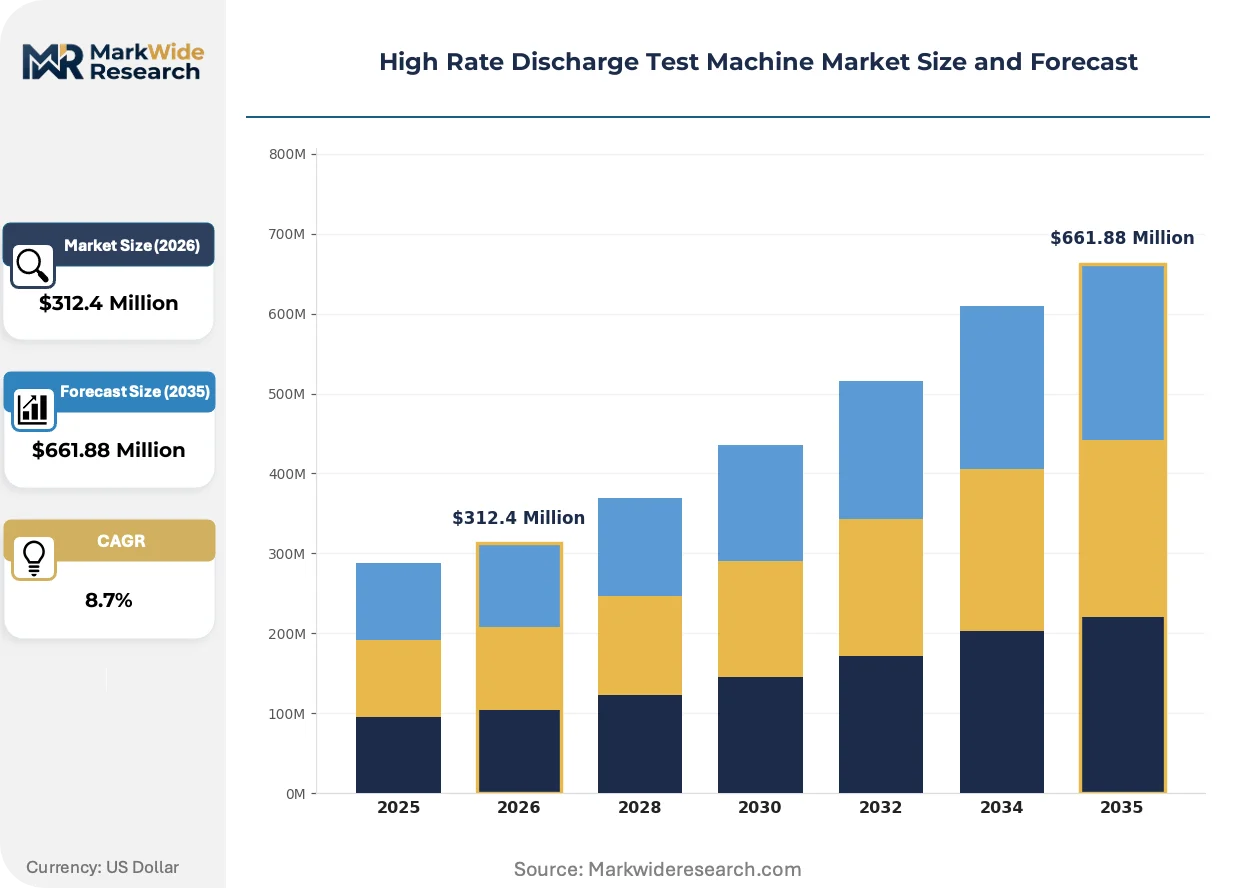
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Benchtop, Modular, Integrated, Battery Analyzer Technology: Digital Control, Analog Control, Microcontroller Based, Embedded System, PLC Controlled Application: Consumer Electronics, Aerospace Equipment, Defense Systems, Renewable Energy, Electric Mobility End User: Battery Manufacturers, Research Laboratories, Quality Assurance Centers, Test Service Providers |
| Companies Covered | Arbin Instruments, MACCOR, Digatron Power Electronics, Chroma ATE, Bitrode, Neware Technology, HIOKI E.E. Corporation, Kikusui Electronics Corporation, DV Power, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Rate Discharge Test Machine Market Trends and Innovations
Test equipment architectures are bifurcating between closed proprietary ecosystems and open-protocol platforms, with procurement decisions increasingly hinging on API accessibility and third-party integration flexibility rather than hardware specifications alone.
Silicon carbide MOSFETs enable sub-millisecond current slew rates while halving switching losses compared to silicon IGBTs. Tier 1 battery manufacturers in South Korea and Japan are standardizing on SiC-based test channels for 10C+ pulse applications. This semiconductor transition is rendering obsolete thermal derating strategies that previously limited sustained high-rate testing.
The EU Battery Regulation's digital passport requirements mandate granular test data traceability from cell qualification through end-of-life. European test laboratories must now deploy equipment with embedded data integrity features to satisfy CSRD-aligned documentation standards. Modular test platforms with native blockchain logging capabilities are capturing preference among export-focused Chinese cell producers seeking CE-marked compliance pathways.
Cell manufacturers are consolidating vendor relationships around full-stack test service partnerships rather than discrete equipment purchases. Arbin Instruments and Chroma ATE have reorganized sales organizations to bundle hardware, calibration contracts, and protocol consulting. This bundling trend concentrates procurement authority among technical procurement teams in Shenzhen and Nagoya, displacing traditional capital-equipment purchasing channels that prioritized unit economics over lifecycle service integration.
High Rate Discharge Test Machine Market Segmentation
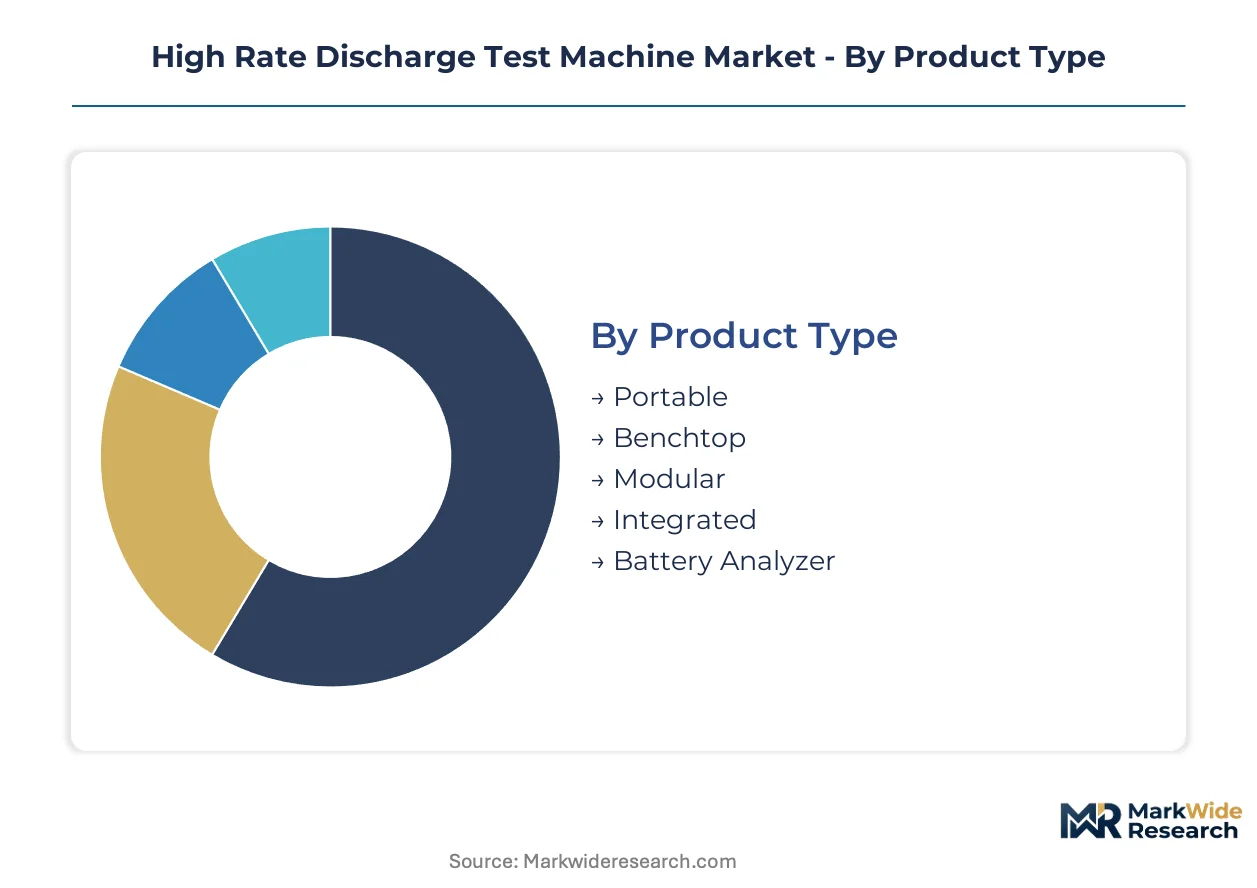
Segmentation in high rate discharge test equipment reflects divergent thermal management requirements and certification protocols across battery chemistries. Equipment specifications vary sharply between academic validation environments and production-line abuse testing floors.
Product Type:
Portable units address field diagnostics and incoming inspection workflows; benchtop systems dominate laboratory settings where protocol flexibility outweighs throughput.
- Portable:Handheld configurations with reduced channel counts serve aftermarket battery diagnostics and logistics hub spot-checking. Demand concentrates in service networks across Germany and Japan where mobile technicians validate warranty claims for second-life EV packs.
- Benchtop:Self-contained chassis housing 4-16 test channels with integrated thermal chambers suit R&D laboratories and small-lot manufacturing. Academic procurement in the United States and South Korea favors these units for solid-state cell protocol development where waveform programmability takes priority over channel density.
- Modular:Rack-mountable channel cards enable gigafactories to scale test floors incrementally without full line replacement. Shenzhen and Nagoya manufacturing clusters drive procurement as cell producers expand capacity in phased buildouts.
- Integrated:Turnkey systems combining formation, aging, and discharge testing occupy dedicated abuse-testing facilities. These installations require custom facility integration and dominate OEM qualification laboratories in Japan.
- Battery Analyzer:Multi-function instruments merging impedance spectroscopy with pulse discharge capabilities serve quality assurance workflows. European test service providers deploy these for CSRD-aligned documentation requirements.
Established volume favors Modular architectures; emerging adoption favors Portable configurations.
Technology:
Control architectures determine waveform fidelity, thermal efficiency, and compliance documentation capabilities across certification pathways.
- Digital Control:FPGA-based current sources with sub-millisecond telemetry resolution command premium positioning for EV cell qualification. South Korean battery manufacturers standardize on these platforms for 10C+ pulse applications where silicon carbide power stages enable precise slew rate control.
- Analog Control:Legacy linear amplifier designs persist in cost-sensitive academic environments with lower channel utilization requirements. Indian research institutes under PLI scheme incentives favor these units for initial infrastructure buildouts.
- Microcontroller Based:Mid-tier architectures balance programmability with unit economics for quality assurance centers in Taiwan and mainland China.
- Embedded System:Dedicated processing units with deterministic timing suit high-throughput production testing where jitter tolerance is tight.
- PLC Controlled:Industrial automation integration enables synchronized thermal chamber and safety interlock management for integrated test lines.
Digital Control platforms are climbing the fastest as wide-bandgap semiconductor adoption accelerates; Analog Control retains share in budget-constrained segments.
Application:
Current magnitude, pulse duration, and safety envelope requirements diverge substantially across end-use categories.
- Consumer Electronics:Lower C-rate testing with emphasis on cycle-life prediction dominates smartphone and laptop battery validation. Chinese contract manufacturers in the Pearl River Delta concentrate procurement for GB standard compliance.
- Aerospace Equipment:Extreme temperature range protocols and DO-311A derived test matrices govern equipment specifications. Suppliers to Boeing and Airbus qualification chains demand traceable calibration hierarchies.
- Defense Systems:MIL-STD-810G environmental conditioning combined with high-rate abuse testing requires hardened instrumentation. US defense contractors drive specialized procurement through NHTSA-influenced safety standards.
- Renewable Energy:Stationary storage systems with 4-8 hour discharge profiles prioritize energy efficiency validation over peak power testing.
- Electric Mobility:Traction battery qualification demands the highest current handling and most complex pulse profiles. This segment concentrates procurement authority among technical teams in South Korea and Japan.
Electric Mobility commands the steepest expansion trajectory; Consumer Electronics maintains the largest installed base.
End User:
Procurement authority and lifecycle service expectations vary sharply across organizational types.
- Battery Manufacturers:In-house test floors with 24/7 utilization demand modular scalability and predictive maintenance contracts. CATL and BYD expansion drives concentrated procurement in Fujian and Guangdong provinces.
- Research Laboratories:Protocol flexibility and academic pricing structures dominate purchasing criteria. National laboratories in the United States and Max Planck Institute networks in Germany favor open-architecture platforms.
- Quality Assurance Centers:Third-party certification bodies require multi-protocol firmware supporting simultaneous GB, IEC, and OEM-specific test scripts.
- Test Service Providers:Commercial laboratories serving cross-border certification needs prioritize equipment with embedded blockchain logging for EU Battery Regulation compliance.
Battery Manufacturers represent the deepest account relationships; Test Service Providers are gaining share fastest as outsourcing trends accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Battery manufacturers in East Asia dominate procurement volumes for high rate discharge test equipment, while European and North American laboratories drive demand for compliance-grade instrumentation with embedded data traceability features.
China
CATL and BYD expansion in Fujian and Guangdong provinces sustains the world's largest installed base of modular test channels. SAMR enforcement of GB standards for traction battery certification compels domestic producers and export-bound manufacturers to maintain high-rate abuse testing capacity. Shenzhen manufacturing clusters concentrate procurement authority among technical teams co-located with cell production facilities.
Japan
Toyota and Panasonic qualification laboratories anchor demand for integrated turnkey systems combining formation, aging, and discharge testing. METI industrial policy supports next-generation solid-state cell development requiring pulsed discharge protocols beyond conventional lithium-ion parameters. Nagoya metropolitan region hosts dense concentrations of OEM test floors serving domestic and Southeast Asian battery supply chains.
South Korea
LG Energy Solution and Samsung SDI standardize on digital control platforms with silicon carbide power stages for 10C+ pulse applications. The country's national industrial regulator aligns test equipment specifications with MFDS battery safety guidelines for domestic and export markets. Seoul Capital Area manufacturing sites drive localized procurement to minimize logistics costs and enable rapid technical support.
Germany
BMW and Volkswagen qualification chains demand traceable calibration hierarchies for equipment serving EU Battery Regulation compliance. KBA vehicle type-approval processes create parallel certification pathways that extend laboratory accreditation timelines for cross-border test service providers. Bavaria and Baden-Württemberg host concentrated procurement from automotive OEMs integrating test data into CSRD-aligned documentation systems.
United States
NHTSA-influenced safety standards govern specialized procurement through defense contractors requiring MIL-STD-810G hardened instrumentation. National laboratories favor open-architecture platforms for solid-state cell protocol development where waveform programmability takes priority. Greater Boston and Pacific Northwest research clusters sustain academic demand for benchtop configurations with reduced channel counts.
High Rate Discharge Test Machine Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that concentrates procurement authority among technical teams in Shenzhen and Nagoya. The vendor base organizes around three strategic archetypes: Texas-based custom protocol developers, Taiwan-centered electronics testing ecosystems, and European precision instrumentation houses. Dominant competitive moves include geographic expansion through localized service networks and portfolio diversification into digital twin integration platforms.
Within the custom protocol development tier, Arbin Instruments exemplifies the archetype of R&D-anchored equipment vendors serving next-generation solid-state qualification requirements. Chroma ATE occupies a position representing Taiwan's electronics testing ecosystem extension into mainland Chinese battery foundries. Digatron Power Electronics sits within the European precision instrumentation tradition, anchoring compliance-grade equipment supply for cross-border laboratory accreditation pathways.
| Leading Market Players |
|---|
| Arbin Instruments |
| MACCOR |
| Digatron Power Electronics |
| Chroma ATE |
| Bitrode |
| Neware Technology |
| HIOKI E.E. Corporation |
| Kikusui Electronics Corporation |
| DV Power |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Shenzhen test machine fabrication is compressing channel margins and forcing OEMs toward extended service contracts as the primary profit reservoir. Equipment utilization rates below 70% across Guangdong province are accelerating bundling of calibration and protocol consulting into upfront pricing structures.
Pricing Analysis
Cost-plus contracts with silicon carbide MOSFET indexation dominate procurement agreements between tier-1 battery manufacturers and test equipment vendors. Three-tier pricing structure across premium, standard, and economy levels separates FPGA-based digital control platforms from legacy analog architectures. Pricing pressure stems from modular retrofit kits displacing full-system replacement demand. Academic and small-lot manufacturers exhibit highest price sensitivity, while South Korean gigafactories prioritize waveform fidelity over unit economics.
Supply Chain Analysis
Supplier-financing facilities with 180-day payment terms have become standard for channel card procurement from Taiwanese electronics testing ecosystems. Silicon carbide wafer fabrication concentrates in Japan, Germany, and the United States, while power electronics assembly clusters in Shenzhen and Nagoya. Single-source vulnerability around wide-bandgap semiconductor substrates exposes test machine OEMs to allocation constraints. Distribution runs through direct technical sales teams co-located with battery manufacturing clusters rather than traditional capital equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from calibration contracts and protocol consulting is expanding faster than hardware sales as gigafactories outsource test floor optimization. Recurring software revenue through digital twin integration platforms represents the fastest-growing margin layer.
For Market Incumbents: Harden silicon carbide supply relationships through multi-year offtake agreements with Japanese and German wafer fabricators. Defend against modular retrofit competitors by embedding predictive maintenance algorithms into native equipment firmware. Capacity addition in South Korea's Seoul Capital Area reinforces proximity to LG Energy Solution and Samsung SDI qualification laboratories.
For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme-funded greenfield gigafactories where virgin test infrastructure demand outpaces established vendor service capacity. Target second-life battery testing applications with modified pulse profile equipment distinct from virgin cell qualification. Partner with European test service providers seeking CE-marked compliance pathways for cross-border laboratory accreditation.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across digital control platforms as FPGA and silicon carbide power stage development costs escalate. Long-term viability favors vendors with captive software revenue streams and embedded data integrity features for EU Battery Regulation compliance. Monitor solid-state cell architecture transitions as the inflection indicator for test protocol obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Agreement | Secures wide-bandgap semiconductor allocation from Rohm or Infineon for 10C+ pulse channels. |
| Digital Twin Platform Launch | Captures recurring software revenue alongside capital equipment sales to CATL and BYD. |
| GB Standard Certification Investment | Enables SAMR-compliant equipment supply for domestic and export-bound Chinese manufacturers. |
| Service Network Localization | Positions technical support teams within Shenzhen and Nagoya manufacturing clusters. |
| Solid-State Protocol Development | Anticipates next-generation cell qualification requirements beyond conventional lithium-ion parameters. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SAMR regulatory filings, MFDS battery safety guidelines, SEC equipment vendor disclosures, and IEA stationary storage deployment data. Interviews with test floor managers at CATL and LG Energy Solution, procurement leads at Chroma ATE and Arbin Instruments, calibration service directors, and solid-state cell R&D heads inform demand-side validation. Bottom-up channel count estimates from Shenzhen and Nagoya manufacturing clusters triangulate against top-down equipment spending projections from battery capacity expansion announcements.
Forecast inputs incorporate product type segmentation across portable, benchtop, modular, integrated, and battery analyzer configurations; technology tiers spanning digital, analog, microcontroller, embedded, and PLC control architectures; and application splits between consumer electronics, aerospace, defense, renewable energy, and electric mobility. CAGRs derive from regression analysis of historical equipment procurement against cell manufacturing capacity additions. Solid-state cell transition timelines and GB standard enforcement intensity represent key industry-specific forecast inputs across the analysis window.
Sensitivities concentrate around silicon carbide supply allocation, solid-state cell commercialization pace, and EU Battery Regulation digital passport implementation timelines. Forecasts reflect documented assumptions regarding equipment replacement cycles and modular retrofit penetration rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
State Transition Testing Market
Test and Measurement
Active Dosimeter Market
Test and Measurement
Density Meter Market
Test and Measurement
Automatic Impact Testing Machine Market
Test and Measurement
Environmental Test Chambers Market
Test and Measurement
Anechoic Chamber Market
Test and Measurement
APAC NDT Equipment Market
Test and Measurement
Ultrasonic NDT Equipment Market
Test and Measurement
Asia-Pacific Nondestructive Testing Equipment Market
Test and Measurement
Digital Inspection Tools Market
Test and Measurement
Semiconductor Metrology and Inspection Market
Test and Measurement
Video Test Equipment Market
Test and Measurement
Industrial X-Ray Inspection System Market
Test and Measurement
Hearing Aid and True Wireless Earbud Acoustic Performance Test Systems Market
Test and Measurement
Clamp Meters Market
Test and Measurement
Global General Purpose Test Equipment (GPTE) Market