
 Asia-Pacific Nondestructive Testing Equipment Market | 2026-2036
Asia-Pacific Nondestructive Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Nondestructive Testing Equipment Market Insights
Aftermarket service revenue is fragmenting across the Asia-Pacific Nondestructive Testing Equipment Market as OEMs and third-party providers compete for calibration contracts and equipment refurbishment. Olympus Corporation leverages its established service network across Japan and Southeast Asia to sustain recurring revenue streams. Fujifilm Corporation anchors its position through digital radiography plate technology leadership, while SGS Group competes on third-party inspection credibility in cross-border trade corridors.
Nondestructive testing equipment encompasses ultrasonic flaw detectors, radiographic imaging systems, magnetic particle inspection units, and visual inspection apparatus designed to evaluate material integrity without causing damage, typically operating at frequencies from 0.5 to 25 MHz for ultrasonic modalities and requiring compliance with ISO 17640 weld examination protocols. Ultrasonic testing dominates capital allocation due to its versatility across metal thickness ranges and emerging composite applications. Digital technology segments are capturing margin pools as legacy analog systems face obsolescence, while portable configurations are expanding into field-based oil and gas pipeline monitoring where stationary installations prove impractical.
Japan's METI enforces JIS Z 2343 ultrasonic testing standards that shape product certification requirements for domestic suppliers and importers alike. China's SAMR aligns GB standards with international norms, creating dual compliance burdens for multinational equipment vendors. Australia's TGA and South Korea's MFDS maintain divergent electromagnetic compatibility rules that complicate regional platform standardization. Stakeholders must monitor how ASEAN harmonization initiatives resolve these regulatory fractures to optimize manufacturing footprints and service localization strategies.
Market Dynamics
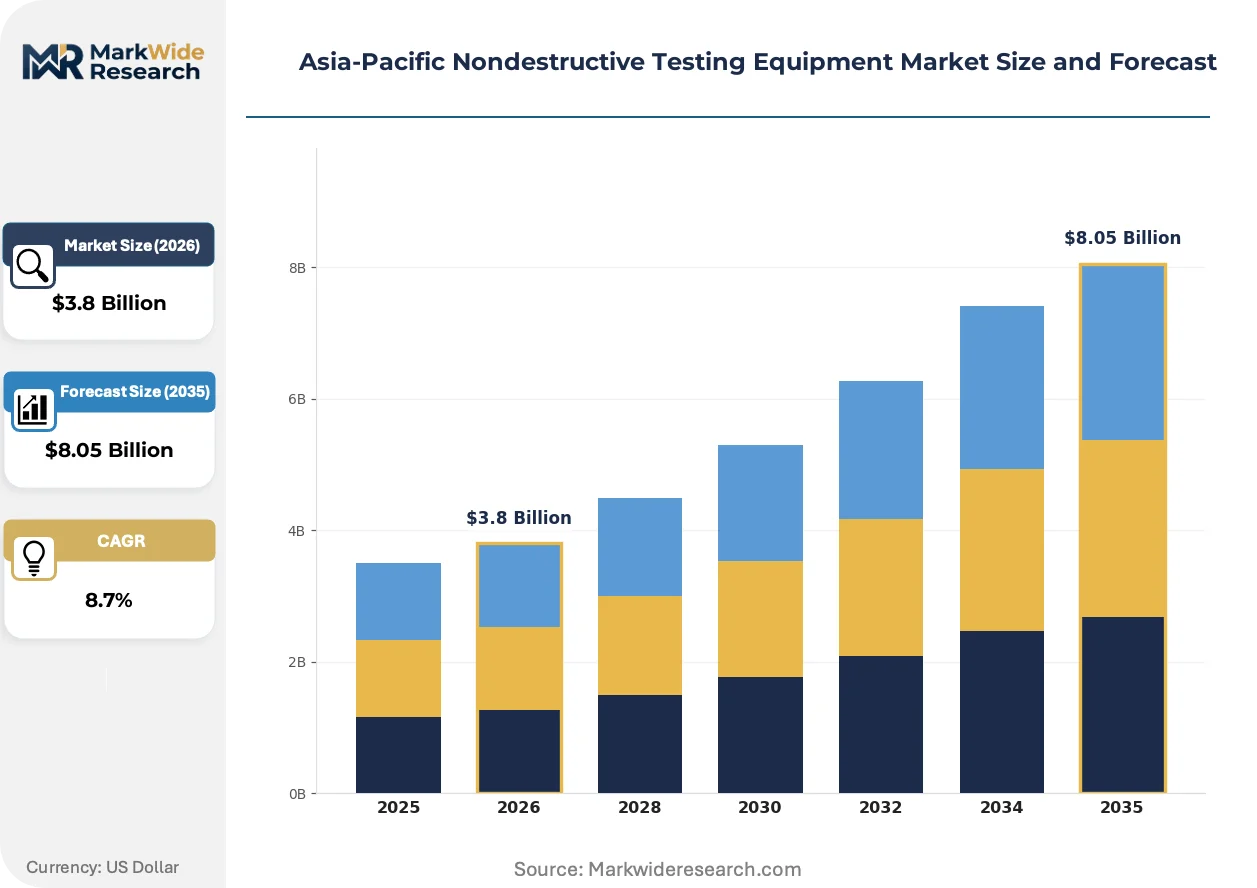
The Asia-Pacific Nondestructive Testing Equipment Market is undergoing structural compression as digital radiography systems displace analog film-based inspection workflows across petrochemical and aerospace supply chains. Regulatory mandates for traceable weld documentation are accelerating equipment replacement cycles in China's eastern industrial corridors and India's infrastructure belt.
Growth Catalysts
- Composite airframe inspection protocols:Aerospace manufacturers in Japan and South Korea are expanding ultrasonic testing programs for carbon-fiber reinforced polymer structures. This drives demand for phased-array systems capable of detecting delamination at multiple ply depths.
- BIS structural steel certification:India's Bureau of Indian Standards has tightened compliance requirements for bridge and high-rise construction. Infrastructure contractors must deploy radiographic or ultrasonic verification for weld joints exceeding specified thickness thresholds.
- East China industrial cluster density:Petrochemical and power generation facilities concentrated in Jiangsu and Zhejiang provinces are entering replacement cycles for aging radiographic equipment. Facility operators prioritize digital detector arrays to reduce exposure times and chemical processing costs.
Market Restraints
- Isotope supply concentration:Radioactive source materials for gamma radiography remain concentrated among a limited set of international suppliers. Geopolitical friction disrupts shipment schedules and forces Asian inspection providers to maintain costly buffer inventories.
- Electromagnetic compatibility divergence:Australia's TGA and South Korea's MFDS maintain non-aligned certification requirements for portable ultrasonic units. Equipment vendors must engineer region-specific variants, fragmenting production scale and extending development timelines.
- Phased-array technician scarcity:Advanced ultrasonic modalities require certified operators capable of interpreting sector-scan displays. Training pipeline capacity lags equipment deployment rates across Southeast Asian markets.
Strategic Opportunities
- ASEAN harmonization initiatives:Regional regulatory alignment discussions create pathways for standardized equipment platforms across Thailand, Vietnam, and Indonesia. Vendors that pre-certify to emerging unified standards capture first-mover positioning.
- Pipeline robotics integration:Oil and gas operators in Australia and Malaysia are deploying crawler-mounted ultrasonic systems for subsea and remote terrestrial inspection. Convergence of robotics and NDT modalities opens service contract expansion.
- Cloud-based data archiving:Japanese METI guidelines increasingly emphasize digital record retention for critical infrastructure. Equipment providers that bundle secure cloud storage with hardware sales differentiate against standalone product competitors.
Industry Challenges
- Multi-standard certification timelines:Equipment manufacturers targeting Japan, China, and Australia simultaneously face sequential JIS Z 2343, GB, and TGA approval processes. Parallel-track submission strategies require dedicated regulatory affairs capacity.
- Legacy analog system integration:Petrochemical facilities with decades-old film-based radiography workflows resist full digital migration. Hybrid inspection protocols create operational complexity and training burdens for site-level quality teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Nondestructive Testing Equipment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Testing, Radiographic Testing, Magnetic Particle Testing, Visual Inspection Technology: Automated, Portable, Remote, Digital End User: Aerospace, Construction, Automotive, Oil & Gas Application: Manufacturing, Maintenance, Quality Control, Research |
| Companies Covered | Olympus Corporation, Fujifilm Corporation, SGS Group, Bureau Veritas S.A., Nikon Metrology NV, MISTRAS Group, General Electric Company, Applus Services, S.A., Intertek Group Plc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Nondestructive Testing Equipment Market Trends and Innovations
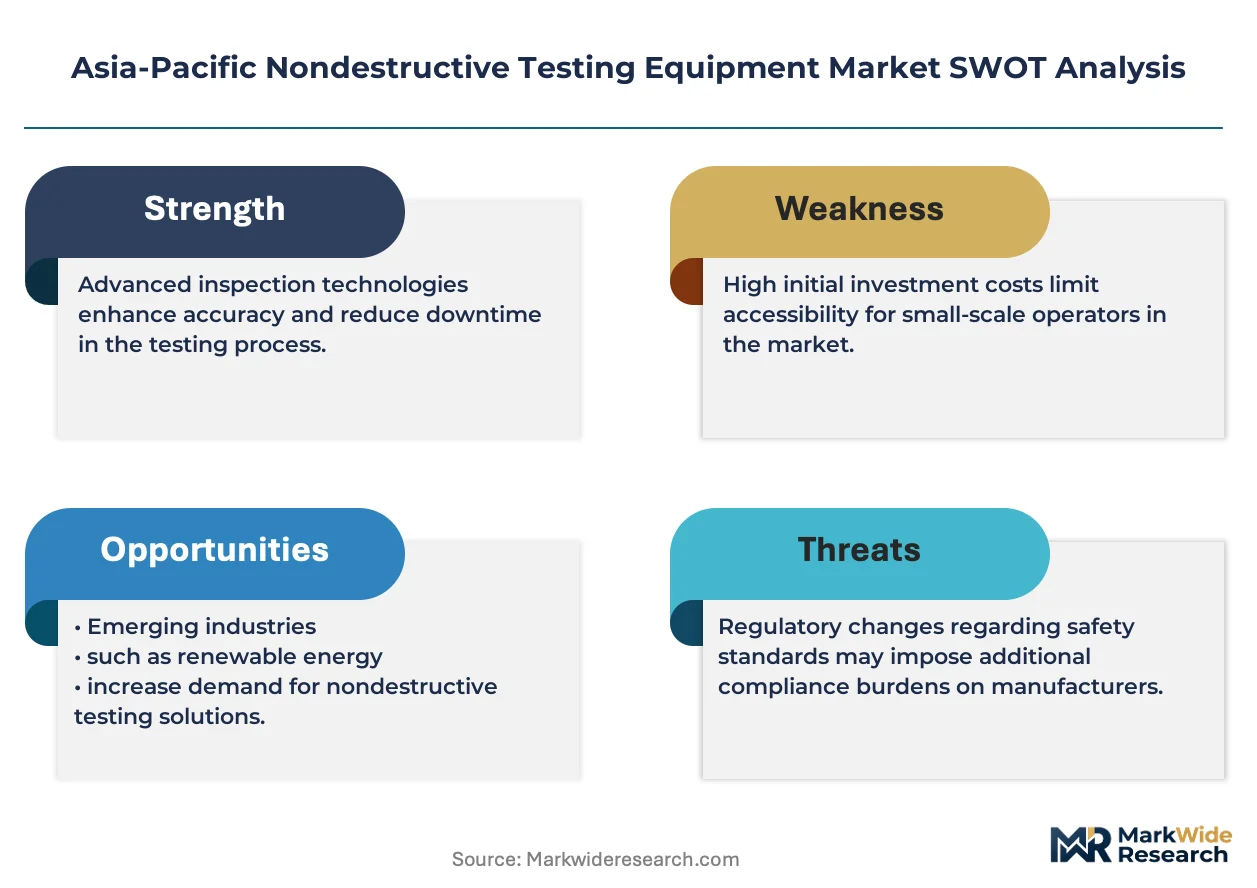
Digital detector technology is compressing inspection cycle times while artificial intelligence-enabled defect recognition is reducing operator interpretation variability. Equipment form factors are shrinking to accommodate confined-space and rope-access deployment scenarios.
Phased-array ultrasonic testing is hybridizing conventional pulse-echo methods with full-matrix capture algorithms to generate three-dimensional volumetric reconstructions of weld geometries. Japanese shipyards and Korean automotive stamping facilities are adopting these systems for thick-section pressure vessel verification. The technology is hybridizing inspection workflows by collapsing multiple probe configurations into single-scan operations, reducing setup labor and accelerating throughput.
China's SAMR has accelerated GB standard alignment with ISO 17640 weld examination protocols, creating dual compliance obligations for multinational equipment vendors. Domestic Chinese manufacturers gain competitive positioning through native GB certification, while foreign suppliers absorb additional testing and documentation costs. Japanese and Australian importers are most affected, with some vendors establishing localized calibration laboratories to satisfy in-country verification requirements.
Asset owner purchasing patterns are fragmenting equipment procurement from long-term service agreements. Large petrochemical operators in Singapore and Thailand now source hardware through competitive tender while negotiating calibration and refurbishment contracts separately with regional service specialists. This unbundling is most visible in pipeline inspection segments, where third-party providers compete directly with OEM service networks for recurring revenue streams.
Asia-Pacific Nondestructive Testing Equipment Market Segmentation
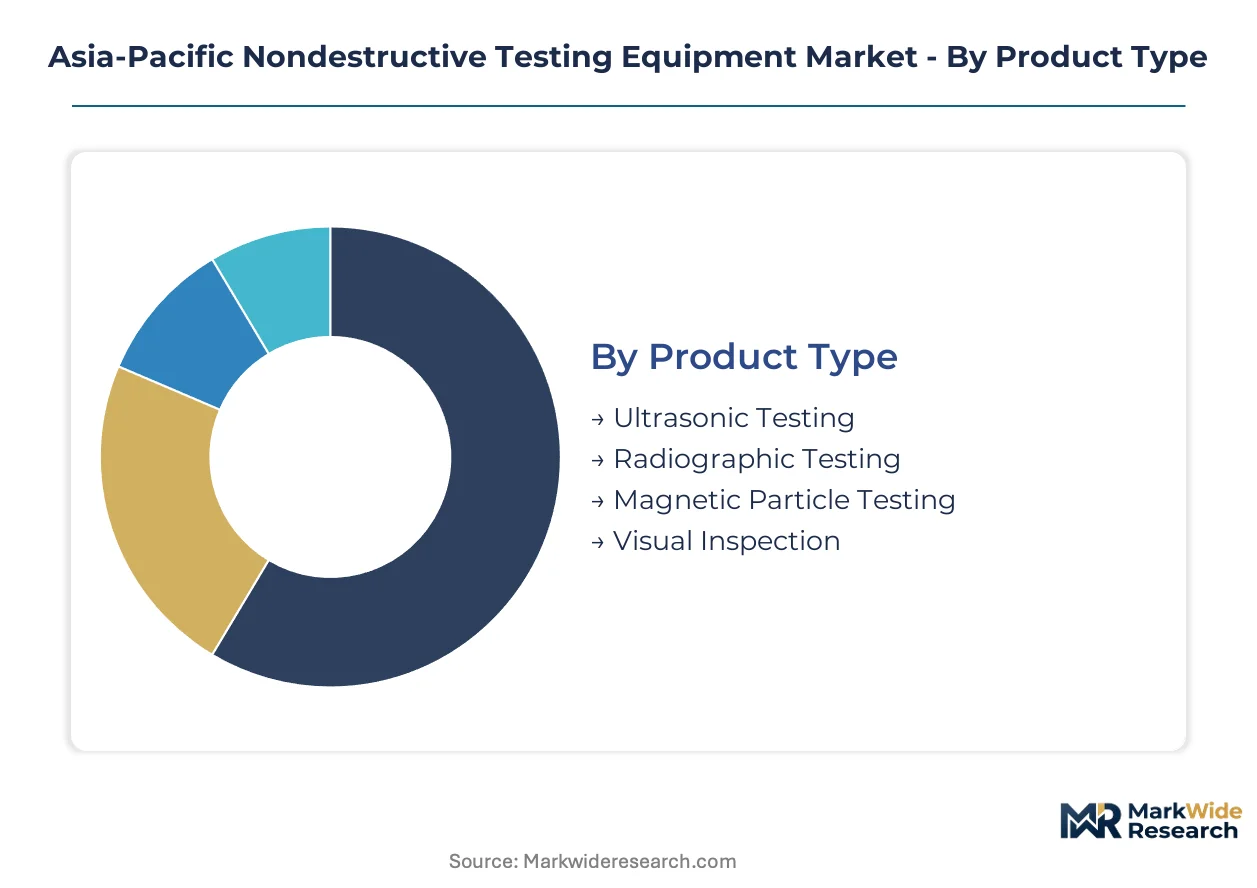
Equipment configuration and service attachment rates vary sharply across segment boundaries in the Asia-Pacific Nondestructive Testing Equipment Market. Procurement patterns in Japan favor bundled calibration contracts with ultrasonic systems, while Indian infrastructure contractors prioritize low-acquisition-cost radiographic units with third-party service sourcing.
Product Type:
After-sales service intensity diverges significantly across modalities, with ultrasonic systems demanding frequent probe replacement and phased-array software updates while radiographic equipment requires isotope logistics management and darkroom maintenance.
- Ultrasonic Testing:Phased-array and conventional pulse-echo systems operate at 0.5 to 25 MHz for metal thickness verification and composite delamination detection. Japanese aerospace manufacturers in Nagoya and South Korean shipyards in Ulsan drive capital allocation toward multi-element probe configurations capable of sector-scan imaging. Service revenue concentrates in probe refurbishment and software licensing renewals.
- Radiographic Testing:Digital detector arrays and film-based systems employ gamma or X-ray sources for volumetric defect visualization. China's petrochemical clusters in Jiangsu province are replacing aging film processors with computed radiography plates to eliminate chemical handling costs. Isotope supply chain management creates recurring service dependencies for gamma radiography operators.
- Magnetic Particle Testing:Portable yoke and bench-mounted coil systems detect surface-breaking cracks in ferromagnetic components through magnetic field distortion visualization.
- Visual Inspection:Borescopes, videoscopes, and automated optical systems provide direct surface examination for inaccessible geometries and weld crown assessment.
Ultrasonic Testing holds the largest share; momentum sits with Radiographic Testing as digital detector adoption accelerates.
Technology:
Cost tier stratification separates premium automated installations from economy portable units, with pricing spreads reflecting sensor density, computing architecture, and certification grade rather than geographic origin alone.
- Automated:Robotic crawler and gantry-mounted systems execute programmed inspection sequences without operator intervention. Australian subsea pipeline operators deploy crawler-mounted ultrasonic units for remote terrestrial and offshore asset monitoring. Capital intensity limits deployment to high-volume production environments with standardized geometries.
- Portable:Battery-powered handheld units enable field deployment across construction sites and in-service infrastructure. Indian bridge inspection contractors favor lightweight ultrasonic flaw detectors for rope-access deployment on high-rise structures. Battery chemistry and display durability determine replacement cycles.
- Remote:Network-connected systems transmit inspection data to centralized analysis centers, reducing on-site specialist requirements.
- Digital:Solid-state detector and software-defined signal processing architectures displace analog film and cathode-ray display workflows.
Portable configurations dominate unit volume; Automated systems are climbing the fastest as robotics integration expands.
End User:
Application maturity varies by sector, with aerospace maintaining the most stringent certification requirements and construction exhibiting the widest spread between premium and economy equipment tiers.
- Aerospace:Composite airframe and jet engine component inspection protocols mandate phased-array ultrasonic and digital radiography verification. Japanese manufacturers under METI oversight enforce JIS Z 2343 compliance for supplier equipment qualification. Defect traceability requirements drive digital record retention and cloud archiving adoption.
- Construction:Structural steel weld verification for bridges and high-rise buildings operates under India's tightening BIS certification mandates. Contractors in Mumbai and Delhi procurement corridors balance equipment cost against compliance documentation requirements. Third-party inspection outsourcing fragments equipment ownership patterns.
- Automotive:Stamping die and powertrain component inspection prioritizes cycle time reduction through automated eddy current and ultrasonic testing.
- Oil & Gas:Pipeline integrity management programs combine in-line inspection tools with field-deployable verification systems for corrosion monitoring and weld assessment.
Construction generates the highest unit demand; Aerospace commands the steepest expansion trajectory from composite inspection protocol expansion.
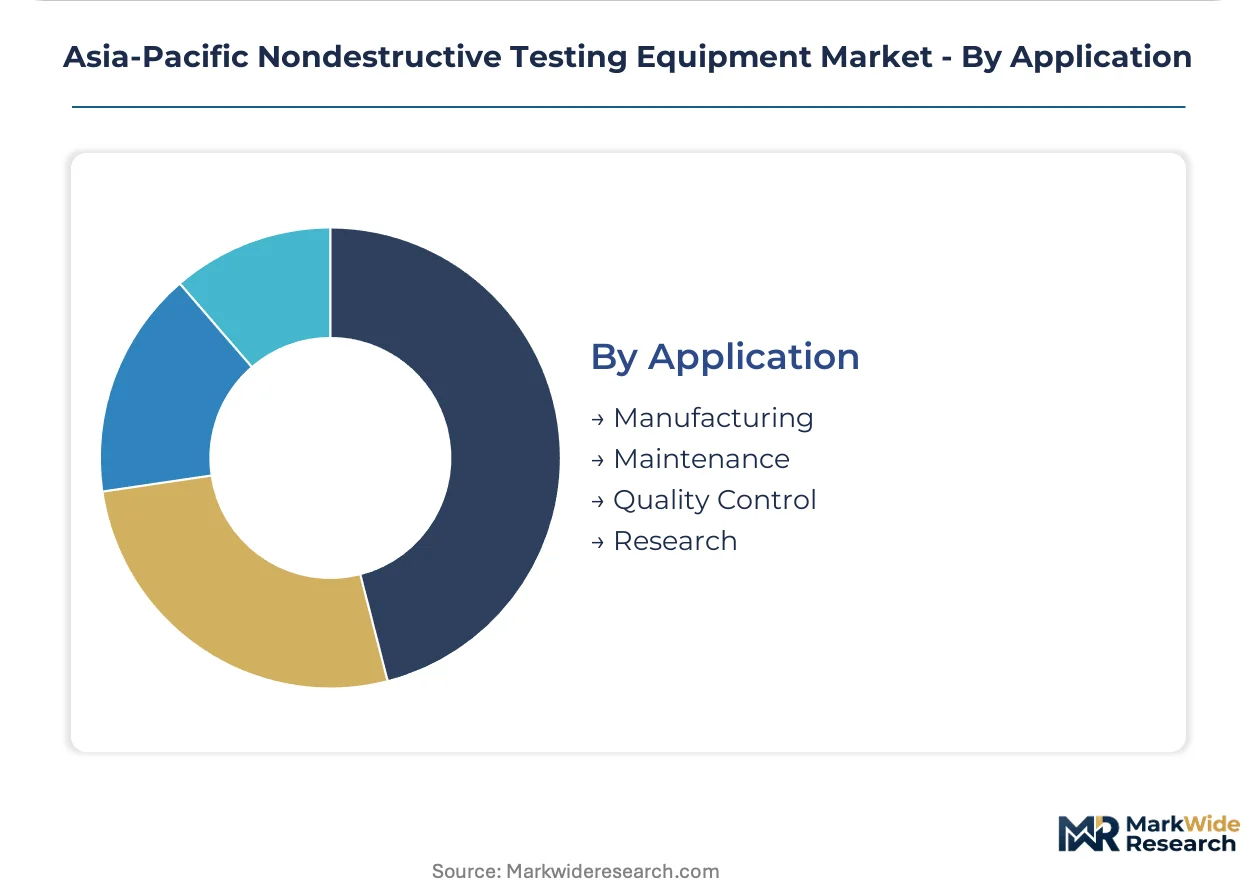
Application:
Customer type differentiation separates capital-equipment purchasers from service-contract buyers, with manufacturing organizations favoring in-house capability and maintenance operators preferring outsourced inspection delivery.
- Manufacturing:In-process inspection integration at welding stations and machining centers prevents defect propagation downstream. South Korean automotive stamping facilities deploy full-matrix capture ultrasonic systems for thick-section pressure vessel verification. Real-time feedback loops enable immediate process parameter adjustment.
- Maintenance:In-service inspection of operating assets detects degradation before functional failure. Malaysian oil terminal operators schedule radiographic and ultrasonic campaigns during turnaround windows to minimize production interruption. Scheduling coordination with operations teams determines contract profitability.
- Quality Control:Final acceptance testing verifies conformance to material specifications and dimensional tolerances before shipment.
- Research:Academic and corporate R&D laboratories evaluate novel materials and validate inspection methodology for future standardization.
Manufacturing absorbs the largest equipment investment; Maintenance is gaining share fastest as asset life extension priorities intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across the Asia-Pacific Nondestructive Testing Equipment Market. Indian infrastructure contractors prioritize low-acquisition-cost radiographic units, while Japanese aerospace manufacturers absorb premium pricing for phased-array certification-grade systems.
China
Petrochemical and power generation facilities in Jiangsu and Zhejiang provinces are replacing aging radiographic equipment with digital detector arrays. SAMR's accelerated GB standard alignment with ISO 17640 creates dual compliance obligations for multinational vendors. Domestic manufacturers gain positioning through native certification while foreign suppliers absorb additional testing costs.
Japan
Aerospace manufacturers in Nagoya and automotive stamping facilities in Toyota City drive capital allocation toward multi-element probe configurations. METI enforces JIS Z 2343 ultrasonic testing standards that shape product certification requirements for domestic suppliers and importers. Japanese shipyards are adopting full-matrix capture systems for thick-section pressure vessel verification.
India
Infrastructure contractors in Mumbai and Delhi procurement corridors balance equipment cost against BIS certification documentation requirements. The Bureau of Indian Standards has tightened compliance mandates for bridge and high-rise construction weld verification. Third-party inspection outsourcing fragments equipment ownership patterns across the infrastructure belt.
South Korea
Shipyards in Ulsan and automotive facilities in Gwangju-Geoje drive demand for automated inspection integration at welding stations. MFDS maintains electromagnetic compatibility rules that diverge from Australian TGA requirements, complicating regional platform standardization. Korean manufacturers are expanding ultrasonic testing programs for carbon-fiber reinforced polymer airframe structures.
Australia
Subsea pipeline operators deploy crawler-mounted ultrasonic systems for remote terrestrial and offshore asset monitoring. TGA certification requirements for portable ultrasonic units remain non-aligned with South Korean MFDS rules, forcing equipment vendors to engineer region-specific variants. Oil terminal operators schedule radiographic campaigns during turnaround windows to minimize production interruption.
Asia-Pacific Nondestructive Testing Equipment Market Competitive Landscape
Capability concentration sits with specialized ultrasonic technology developers; scale advantage sits with diversified industrial conglomerates. The Asia-Pacific Nondestructive Testing Equipment Market structures around three tiers: precision instrument specialists, integrated testing service providers, and broad-based industrial technology groups. Two strategic archetypes dominate competitive positioning: OEMs leveraging established service networks for recurring calibration revenue, and third-party inspection firms competing on cross-border trade corridor credibility. Consolidation pressure intensifies through M&A activity among service providers and technology licensing partnerships between equipment vendors and robotics integrators.
Within the precision instrument tier, Olympus Corporation and Fujifilm Corporation exemplify contrasting geographic anchoring strategies. Olympus leverages its Japan and Southeast Asia service network presence to sustain aftermarket revenue streams. Fujifilm occupies a position defined by digital radiography plate technology leadership. Among integrated testing service providers, SGS Group represents the third-party inspection archetype competing directly with OEM service networks for recurring calibration and refurbishment contracts across Singapore and Thailand pipeline segments.
| Leading Market Players |
|---|
| Olympus Corporation |
| Fujifilm Corporation |
| SGS Group |
| Bureau Veritas S.A. |
| Nikon Metrology NV |
| MISTRAS Group |
| General Electric Company |
| Applus Services, S.A. |
| Intertek Group Plc. |
| Others |
Pricing and Supply Chain Analysis
Radioactive source materials for gamma radiography concentrate among limited international suppliers, anchoring margin pools in isotope logistics management and forcing Asian inspection providers to absorb costly buffer inventory positions. This upstream concentration cascades into downstream pricing power for service providers capable of securing reliable supply contracts.
Pricing Analysis
After-sales service revenue tiers—spanning probe refurbishment, software licensing renewals, and calibration contracts—drive lifetime value capture across ultrasonic and radiographic modalities. Three-tier pricing structure across premium certification-grade, standard commercial, and economy portable levels separates Japanese aerospace manufacturers from Indian infrastructure contractors. Cost compression in economy radiographic units is intensifying because domestic Chinese manufacturers leverage native GB certification advantages. Indian bridge contractors exhibit the highest price sensitivity, while Japanese METI-regulated aerospace programs absorb premium phased-array system pricing.
Supply Chain Analysis
Tariff exposure between North American isotope suppliers and Asian processing facilities dominates supply chain risk planning for gamma radiography operators. Manufacturing concentration in Japan, Germany, and the United States feeds precision ultrasonic probe and digital detector array production. Component dependencies center on piezoelectric ceramics, scintillator crystals, and specialized X-ray tubes. Single-source vulnerability in medical-grade isotope supply creates contingency planning requirements. Distribution runs through OEM-direct channels for large petrochemical operators and regional distributor networks for construction contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified phased-array technician shortages across Southeast Asian markets constrain equipment utilization rates and service expansion timelines. This capability gap shapes competitive positioning for vendors able to field qualified operators.
For Market Incumbents: Harden service network density in Japan and Southeast Asia against third-party inspection firm encroachment. Lock in exclusive calibration contracts with Chinese petrochemical clusters before GB-ISO harmonization completes. Invest in localized training academy capacity to address technician scarcity and accelerate customer equipment deployment. For New Entrants and Emerging Players: Vietnam and Indonesia infrastructure corridors offer the most penetrable geographic underpenetration for portable ultrasonic flaw detector deployment. Target Indian state-level bridge construction programs where BIS certification mandates are tightening but equipment ownership remains fragmented. Pursue third-party service outsourcing contracts with Mumbai and Delhi procurement corridors rather than direct equipment sales. For Investors and Strategic Acquirers: Capital is best deployed toward precision instrument specialists with established JIS Z 2343 and GB dual-certification capabilities. Long-term viability hinges on software-defined signal processing architectures displacing analog legacy systems. Watch for inflection in cloud-based data archiving attachment rates as Japanese METI digital record retention guidelines tighten.| Strategic Initiative | Industry Significance |
|---|---|
| Phased-Array Technician Training Academy Buildout | Addresses certified operator scarcity constraining Southeast Asian equipment deployment rates. |
| Dual-Certification Laboratory Investment | Captures GB-ISO harmonization timing advantage in Jiangsu and Zhejiang industrial clusters. |
| Cloud-Archiving Service Bundling | Differentiates hardware sales against standalone competitors under METI digital retention guidelines. |
| Robotics Integration Partnership | Opens subsea pipeline inspection contracts with Australian and Malaysian oil terminal operators. |
| Third-Party Service Network Acquisition | Consolidates fragmented calibration market share against SGS Group and Bureau Veritas positioning. |
Research Methodology
The analysis maps ultrasonic, radiographic, magnetic particle, and visual inspection modalities, each validated through equipment procurement managers, plant maintenance directors, aftermarket service heads, and regulatory compliance officers at aerospace manufacturers, petrochemical operators, and infrastructure contractors. Primary interview intelligence triangulates against customs trade data, SAMR and METI regulatory filings, ISO certification registries, and BIS mandate documentation. Bottom-up equipment shipment tracking and top-down industrial capital expenditure analysis converge on segment-level sizing.
Assumptions held fixed include continued GB standard alignment with ISO 17640 protocols, stable isotope supply chain operations, and phased-array technician training pipeline expansion at historical rates. Variables tested across the analysis window encompass ASEAN regulatory harmonization timing, composite airframe inspection protocol adoption curves, and cloud-archiving attachment rate trajectories. CAGRs derive from equipment replacement cycle modeling, technology substitution curves, and end-user capital allocation surveys. Mode-specific penetration rates and service attachment intensity inform segment trajectory differentiation.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles, infrastructure stimulus timing, or aerospace production rates would shift the trajectory. Forecasts reflect documented assumptions subject to revision upon regulatory acceleration, supply disruption, or technology substitution inflection. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Uniaxial Tester Market
Test and Measurement
Sand Abrasion Tester Market
Test and Measurement
One-Box Testers Market
Test and Measurement
Ultrasonic Flaw Detector Market
Test and Measurement
APAC NDT Equipment Market
Test and Measurement
Height Measurement Devices Market
Test and Measurement
Global Micrometer Market
Test and Measurement
Additively Manufactured Lattice Structure Mechanical Test Systems Market
Test and Measurement
Digital Inspection Market
Test and Measurement
Global Conductivity Meters Market
Test and Measurement
Field Inspection Tester Market
Test and Measurement
Sound Level Measurement Meter Market
Test and Measurement
Next-Generation Industrial Metrology and Inspection Market
Test and Measurement
Microhardness Testing System Market
Test and Measurement
Protective Earth Resistance Meter Market
Test and Measurement
Dosimeter Market