
 Metrology Services Market | 2026-2036
Metrology Services Market Size, Share, and Industry Trends Forecast 2026-2036
Metrology Services Market Intelligence
The expansion of calibration laboratories in emerging economies is repositioning the competitive landscape for outsourced measurement services. Hexagon AB leverages its extensive software portfolio to offer integrated hardware and software solutions. Carl Zeiss AG specializes in high-precision optical and CMM systems for automotive and aerospace clients. Mitutoyo Corporation sustains its market presence through a broad distribution network and a focus on dimensional measurement tools for diverse industrial applications.
Metrology services encompass the scientific study and application of measurement, ensuring that instruments and components conform to established standards. These services often involve calibration to an uncertainty level of a few micrometers for critical industrial processes. Within the service mix, demand for dimensional measurement and calibration remains foundational for quality assurance. The aerospace and semiconductor manufacturing end-user segments are driving adoption of advanced technologies like laser scanning and vision systems for complex inspection tasks.
Regulatory frameworks such as ISO/IEC 17025 accreditation for testing and calibration laboratories are fundamental to market access. In specific sectors, compliance with standards like the FDA's requirements in the US for medical devices or CE marking in Europe mandates traceable and validated measurements. Service providers must now decide whether to specialize in high-margin, complex applications or scale operations to serve high-volume, standardized calibration needs.
Market Dynamics
The central force shaping the market is the relentless miniaturization in the semiconductor and electronics industries. This trend necessitates a parallel evolution in measurement capabilities, pushing demand for services that can validate components at sub-micrometer precision levels.
Growth Catalysts
- Advanced Semiconductor Packaging:The shift to 3D-IC and heterogeneous integration in semiconductors requires ultra-high-precision dimensional and overlay metrology to ensure yield, creating intense demand from foundries in Taiwan and South Korea.
- Aerospace Lightweighting:Demand for verification of complex composite and additively manufactured components in the aerospace industry, driven by fuel efficiency targets, necessitates advanced non-contact inspection services.
- Medical Device Regulation:Stringent regulatory frameworks, including the FDA's requirements in the US and the EU's Medical Device Regulation (MDR), mandate fully traceable and validated measurements for all critical components, compelling manufacturers to outsource validation.
Market Restraints
- High Capital Investment:The acquisition, maintenance, and environmentally controlled housing of cutting-edge metrology equipment, such as high-accuracy CMMs or X-ray CT scanners, present a significant capital barrier for service providers.
- Technical Measurement Limits:Current technologies face limitations in rapidly and non-destructively measuring internal features, transparent materials, or highly complex freeform surfaces, creating bottlenecks in certain inspection workflows.
- Accreditation Scarcity:A limited number of national and primary laboratories can provide the highest-echelon calibrations (lowest measurement uncertainty), creating dependencies for commercial labs seeking to establish their own traceability.
Strategic Opportunities
- Additive Manufacturing Integration:Providing in-process monitoring and post-build qualification services for 3D-printed metal and polymer parts represents a significant growth area, particularly for aerospace and medical implant applications.
- Service Expansion in Southeast Asia:Emerging manufacturing hubs in countries like Vietnam and Thailand, focused on electronics and automotive assembly, present underpenetrated markets for outsourced calibration and inspection services.
- Metrology as a Service (MaaS):The development of cloud-based platforms that integrate measurement data with AI for predictive analytics offers a new service model moving beyond simple pass/fail inspection to process optimization.
Industry Challenges
- Metrology Skills Gap:A persistent shortage of technicians and engineers who possess a dual skill set in classical measurement principles and modern data science or automation programming hinders service expansion and innovation.
- Data Interoperability:The absence of a universal standard for 3D measurement data formats complicates workflows, requiring costly data conversion and custom software development to integrate systems from different vendors.
- Legacy System Integration:Implementing modern in-line or automated metrology solutions into existing factory floors with older manufacturing execution systems (MES) poses significant technical and software integration challenges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metrology Services Market |
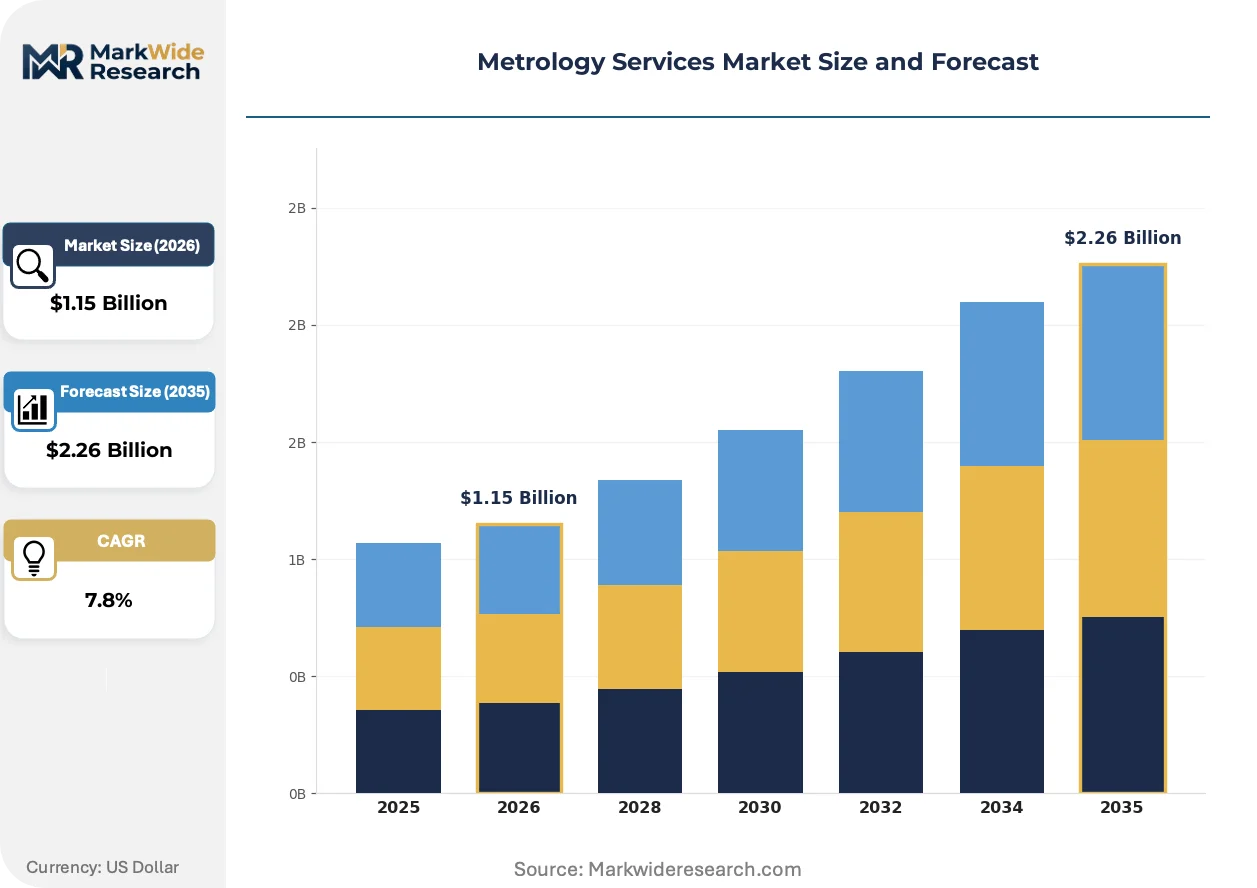
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $2.26 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Calibration, Inspection, Dimensional Measurement, Geometric Measurement, Material Testing Technology: Coordinate Measuring Machines, Laser Scanning, Optical Comparators, Vision Systems, CMM Software End User: Aerospace OEMs, Semiconductor Manufacturers, Pharmaceutical Producers, Construction Equipment Suppliers, Consumer Electronics Makers Application: Quality Assurance, Reverse Engineering, Process Control, Product Development, Compliance Verification |
| Companies Covered | Nikon Metrology Inc., Mitutoyo Corporation, Hexagon AB, SGS, Intertek Group plc, Carl Zeiss AG, FARO Technologies, Bureau Veritas, Renishaw plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metrology Services Market Strategic Shifts & Innovations
The market's evolution is defined by the integration of measurement technology directly into the manufacturing process. This shift transforms metrology from a post-production quality check into a real-time tool for process control and optimization.
In-line metrology provides real-time measurement data directly within the production environment, often using non-contact sensors like laser scanners and vision systems. Automotive and electronics manufacturers are rapidly adopting this approach to enable 100% inspection without sacrificing cycle time. This technology is expanding into closed-loop process control, where measurement feedback is used to automatically adjust upstream parameters like machine tool paths or deposition rates.
Global adherence to ISO/IEC 17025 accreditation is becoming a non-negotiable prerequisite for service providers. The standard enforces strict protocols for demonstrating technical competence, measurement traceability, and the rigorous calculation of measurement uncertainty. The aerospace and medical device end-user segments, in particular, mandate this accreditation from their service partners, driving significant investment in quality management systems.
A notable behavioral shift is the move from procuring discrete inspection tasks to contracting for comprehensive quality data management. This service model, which bundles hardware, software, and analytical support, is displacing transactional, project-based work. This pattern is most pronounced in high-tech manufacturing clusters in the United States and Germany, where metrology data is a critical asset for digital twin and factory automation initiatives.
Metrology Services Market Segmentation
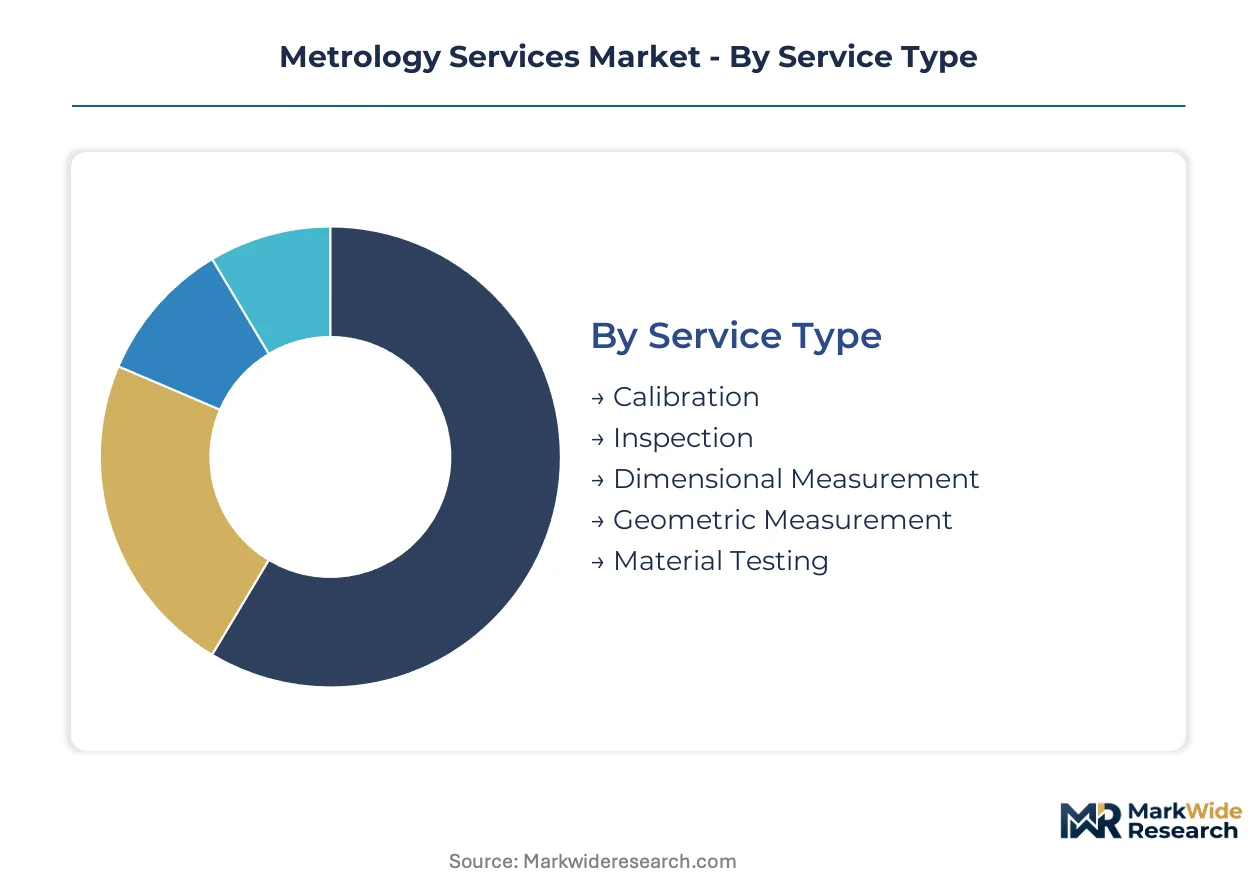
The Metrology Services market is diverse, with distinct needs and preferences driving demand across various dimensions. Understanding these segmentations is crucial for service providers to tailor offerings, optimize resource allocation, and identify high-growth opportunities within the evolving industrial landscape.
Service Type:
Buyer requirements for metrology services are primarily differentiated by the specific measurement task and the level of precision or validation needed for components.
- Calibration:This foundational service ensures instruments and reference standards provide accurate measurements, maintaining traceability to national and international standards. Demand for calibration services remains high in regulated industries like aerospace and medical devices, where compliance is paramount for product integrity.
- Inspection:This service involves detailed examination of parts and assemblies to verify conformance to design specifications, often employing advanced non-contact technologies. Semiconductor manufacturers in Taiwan and South Korea rely on sophisticated inspection for advanced packaging, ensuring sub-micrometer precision in critical components.
- Dimensional Measurement:This service focuses on precise geometric characterization of physical objects, including length, width, height, and form. Automotive suppliers frequently utilize dimensional measurement to validate component tolerances and ensure proper fit and function in complex assemblies.
- Geometric Measurement:This service quantifies the shape, orientation, and position of features on an object, such as flatness, roundness, and perpendicularity. Tool and die makers require accurate geometric measurements to produce high-precision molds and jigs.
- Material Testing:This service assesses the physical and mechanical properties of materials, including hardness, tensile strength, and chemical composition. Aerospace companies use material testing to confirm the integrity of composite structures and additively manufactured parts.
Calibration leads volumes today; Inspection is gaining share fastest.
Technology:
Metrology service providers select technologies based on the application's complexity, required accuracy, and the material properties of the items being measured.
- Coordinate Measuring Machines:These highly precise electromechanical devices measure the physical geometric characteristics of an object by probing points on its surface. Automotive component manufacturers in Germany widely use CMMs for verifying complex part geometries and ensuring tight tolerances.
- Laser Scanning:This non-contact technology captures millions of data points from an object's surface to create detailed 3D models, ideal for complex shapes and large components. Aerospace OEMs in the United States increasingly deploy laser scanning for inspecting turbine blades and airframe structures, supporting lightweighting initiatives.
- Optical Comparators:These devices project a magnified silhouette of a part onto a screen, allowing for visual inspection and measurement of dimensions against a reference. Small parts manufacturers in China frequently use optical comparators for rapid, cost-effective quality checks on production lines.
- Vision Systems:These automated systems use cameras and image processing software to perform rapid, non-contact measurements and inspections of parts. Consumer electronics makers rely on vision systems for high-volume inspection of circuit boards and display components.
- CMM Software:This specialized software controls CMM hardware, processes measurement data, and generates comprehensive inspection reports. Software integration with manufacturing execution systems is becoming critical for automated quality control in smart factories.
Coordinate Measuring Machines hold the largest share; Vision Systems exhibit the steepest expansion trajectory.
End User:
The type of customer dictates the specific metrology services required, driven by industry standards, regulatory demands, and production volumes.
- Aerospace OEMs:These manufacturers require highly accurate and traceable measurements for critical components, driven by stringent safety regulations and complex material science. Demand from aerospace OEMs in France and the United States focuses on non-contact inspection for composite and additively manufactured parts to ensure structural integrity.
- Semiconductor Manufacturers:These companies operate at the forefront of miniaturization, demanding ultra-high-precision metrology for wafer inspection, advanced packaging, and process control. Foundries in Taiwan and South Korea are intensely driving the need for sub-micrometer dimensional and overlay metrology to maximize yield in 3D-IC integration.
- Pharmaceutical Producers:This segment requires validated measurement services for drug delivery systems, packaging, and manufacturing equipment calibration to comply with regulatory bodies like the FDA in the US. Pharmaceutical companies utilize metrology to ensure product quality and patient safety.
- Construction Equipment Suppliers:These manufacturers need robust measurement solutions for large-scale components, ensuring durability and functional performance in demanding environments. Suppliers often outsource calibration of heavy machinery sensors and structural component inspection.
- Consumer Electronics Makers:This industry demands high-volume, rapid inspection for small, intricate components, with a focus on functional testing and cosmetic quality. Manufacturers in Vietnam and Thailand use metrology services for quality control in assembly lines.
Semiconductor Manufacturers represent the largest segment; Pharmaceutical Producers are expanding most quickly.
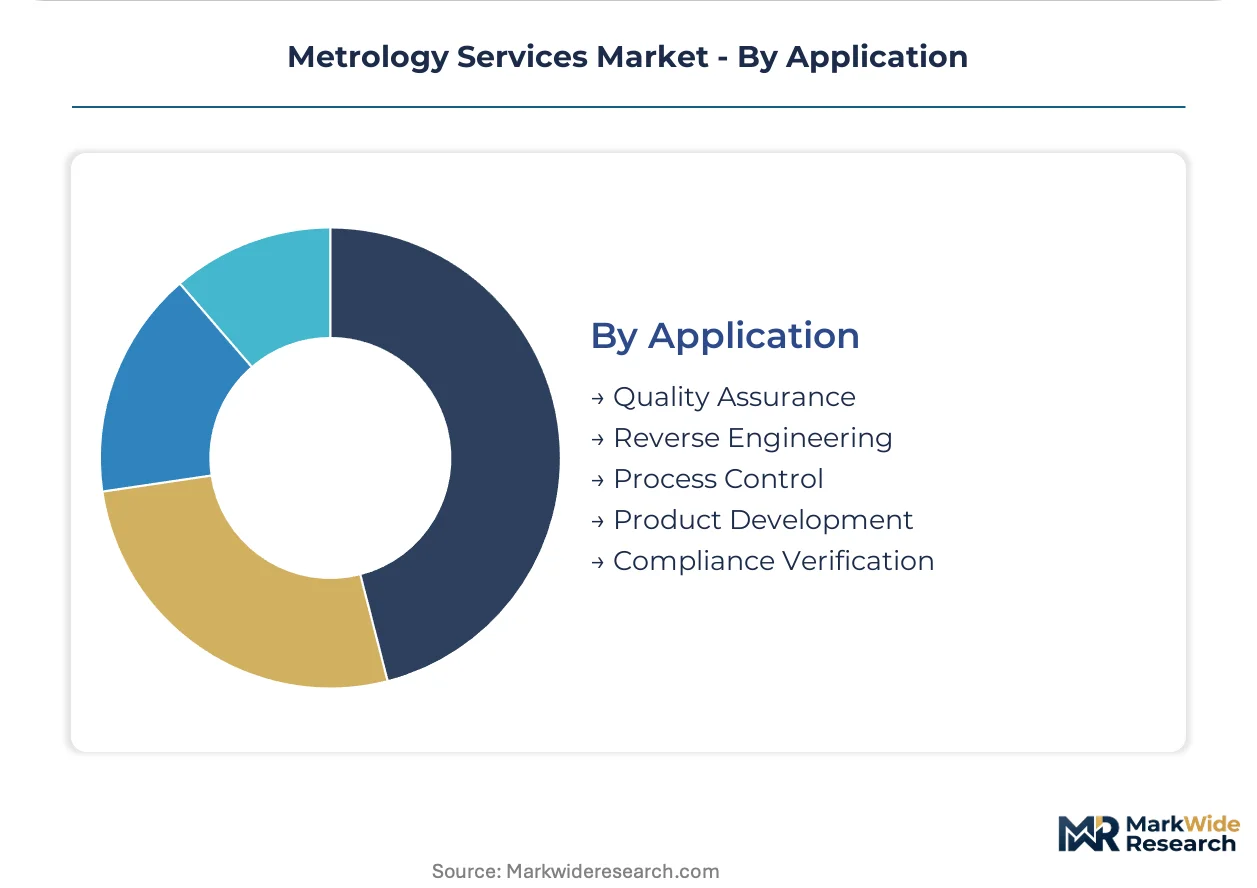
Application:
The application of metrology services defines the ultimate purpose of the measurement, ranging from ensuring product quality to improving manufacturing efficiency.
- Quality Assurance:This application ensures products and processes meet specified standards and requirements, often involving post-production inspection and verification. Quality assurance remains a foundational driver for metrology services across all industrial sectors.
- Reverse Engineering:This application involves creating a digital model of an existing physical object for design analysis, reproduction, or modification. Automotive aftermarket parts suppliers frequently use reverse engineering services to replicate components without original design data.
- Process Control:This application integrates real-time measurement data into manufacturing processes to monitor and adjust parameters, minimizing defects and optimizing production efficiency. Electronics manufacturers in Japan leverage process control metrology to maintain tight tolerances in automated assembly.
- Product Development:This application supports the design and prototyping phases of new products, providing critical measurement feedback for iterative improvements. Medical device companies use metrology during product development to validate new implant designs and ensure functional performance.
- Compliance Verification:This application ensures products and processes adhere to specific regulatory standards or industry certifications. Aerospace component suppliers must demonstrate compliance with FAA regulations through traceable measurement data.
Quality Assurance holds the largest volume; Process Control is demonstrating robust expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While the United States drives metrology service demand through advanced aerospace and medical device sectors, Germany's automotive and industrial machinery industries necessitate equally stringent measurement capabilities. This global market exhibits diverse regional drivers, shaped by distinct manufacturing specializations and regulatory landscapes. Each area contributes uniquely to the overall metrology services ecosystem.
United States
The United States experiences significant demand from aerospace OEMs and medical device manufacturers. FDA requirements mandate fully traceable measurements for critical medical components. High-tech manufacturing clusters across the Pacific Northwest prioritize comprehensive quality data management for digital twin initiatives.
Germany
Germany's robust automotive and industrial machinery sectors drive consistent demand for precision metrology. CE marking for industrial equipment mandates rigorous measurement validation. Automotive component manufacturers in Bavaria widely use CMMs for verifying complex part geometries.
Taiwan
Taiwan's dominant semiconductor industry necessitates ultra-high-precision metrology for advanced packaging. Local industry standards demand sub-micrometer precision to maximize yield in 3D-IC integration. Foundries in Hsinchu Science Park intensely drive the need for dimensional and overlay metrology.
South Korea
South Korea's advanced semiconductor and consumer electronics industries generate substantial metrology demand. The MFDS oversees medical device validation, while national quality standards ensure electronics product integrity. Electronics manufacturing clusters in Gyeonggi Province rely on sophisticated inspection for high-volume production.
Japan
Japan's electronics manufacturers and automotive industry require precise metrology for quality assurance. JIS standards for industrial products ensure component reliability, supported by METI guidelines for advanced manufacturing. Electronics manufacturers in the Kanto region leverage process control metrology for automated assembly.
Metrology Services Market Key Industry Players
European producers anchor one tier of the metrology services market; Asian specialists hold another significant position. The market exhibits a tiered structure, with established players offering comprehensive solutions alongside niche providers focusing on specific technologies. Strategic archetypes include integrated hardware-software providers and specialized calibration laboratories. Competitive moves primarily involve portfolio diversification and geographic expansion into emerging manufacturing hubs.
Within the integrated hardware and software solutions archetype, Hexagon AB exemplifies a strategy leveraging an extensive software portfolio to offer comprehensive services. Carl Zeiss AG, a European entity, occupies a position specializing in high-precision optical and CMM systems, particularly for automotive and aerospace clients. Mitutoyo Corporation, a Japanese manufacturer, sits within the category of broad distribution networks and a focus on dimensional measurement tools for diverse industrial applications. These entities collectively underscore the market's differentiation between holistic solution providers and precision instrumentation specialists.
| Leading Market Players |
|---|
| Nikon Metrology Inc. |
| Mitutoyo Corporation |
| Hexagon AB |
| SGS |
| Intertek Group plc |
| Carl Zeiss AG |
| FARO Technologies |
| Bureau Veritas |
| Renishaw plc |
| Others |
Cost & Logistics Intelligence
The shift towards in-line metrology simultaneously reshapes cost economics and supply concentration by demanding specialized equipment and highly skilled technicians. This transition requires significant upfront capital investment for service providers, influencing their operational scale and geographic reach.
Pricing Analysis
Capacity additions in emerging economies are reshaping price floors for standardized calibration services. Project-based pricing dominates for complex inspection tasks, reflecting the customization and precision required. Price differentiation stems from the level of ISO/IEC 17025 accreditation and the speed of service delivery. Pricing softness is intensifying due to increased competition for high-volume, standardized calibration needs. Pharmaceutical producers, driven by stringent regulatory compliance, exhibit the least price sensitivity for validated measurements.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns characterize the metrology service delivery model. Geographic supply concentration for advanced metrology equipment centers on Germany, Japan, and the United States. Key raw material dependencies include specialized optical components and high-purity materials for sensor manufacturing. A structural supply chain risk is the single-source vulnerability for ultra-high-precision components. The dominant distribution model involves direct sales and service networks for complex systems, supplemented by third-party calibration labs for routine tasks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a late-cycle quality story, as demand shifts toward ultra-high-precision specifications in advanced semiconductor manufacturing.
For Market Incumbents: Deploy strategic acquisitions to consolidate fragmented niche providers specializing in complex applications like additive manufacturing qualification. This defends against margin erosion from commoditized calibration services. Leverage existing software portfolios to offer comprehensive data management solutions, addressing the data interoperability challenge. Invest in advanced training programs to mitigate the persistent metrology skills gap.
For New Entrants and Emerging Players: Cloud-based platforms offer a digital-channel route to deliver Metrology as a Service (MaaS), targeting underpenetrated manufacturing hubs in Southeast Asia. Focus on specialized inspection services for additive manufacturing, where established players face technical measurement limits. A go-to-market angle could involve offering AI-driven predictive analytics for process optimization, moving beyond simple pass/fail inspections.
For Investors and Strategic Acquirers: Roll-up economics work for specialized calibration laboratories because of the fragmented nature of the market and the high demand for ISO/IEC 17025 accreditation. Long-term viability is strong due to relentless miniaturization in electronics and stringent regulatory demands across multiple industries. An acquisition target archetype is a regional provider with strong technical expertise in non-contact technologies. Watch for increasing consolidation activity among mid-sized service providers as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquire Niche Non-Contact Inspection Firms | This expands service portfolios into high-growth areas like additive manufacturing and complex geometries. |
| Invest in AI-Powered Data Analytics Platforms | This shifts offerings from transactional services to comprehensive process optimization for clients. |
| Expand Accredited Calibration Laboratories in Southeast Asia | This addresses unmet demand in emerging manufacturing hubs for outsourced validation services. |
| Develop Specialized Training Programs for Metrology Engineers | This mitigates the critical skills gap hindering service expansion and technological adoption. |
| Integrate Metrology Data with Client MES Systems | This facilitates closed-loop process control and supports smart factory initiatives for manufacturers. |
Research Approach
Bottom-up end-user modeling reconciled against top-down supply-side tracking forms the analytical core for this market. Primary interviews with metrology engineers, quality assurance managers, procurement leads, and regulatory affairs specialists provided qualitative insights. Secondary validation drew from industry association reports, technical journals, and regulatory body publications like FDA guidance documents.
The input-output matrix framing guided the analytical framework across the projection horizon. Segmentation dimensions modeled included service type, technology, end-user, and application, alongside the regional manufacturing specialization. Compound annual growth rates were derived through a weighted average of segment-specific growth drivers. Industry-specific forecast inputs included semiconductor fab expansion plans and aerospace production rates.
The model assumes a particular technology adoption path; alternative pathways for in-line metrology could alter the outlook. Forecasts reflect assumptions regarding regulatory stability and sustained investment in advanced manufacturing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
One-Box Testers Market
Test and Measurement
Hardness Testing Machine Market
Test and Measurement
Semiconductor Curve Tracer Market
Test and Measurement
Quantum Key Distribution System Performance and Security Test Equipment Market
Test and Measurement
Moisture Analyzer Market
Test and Measurement
PXI SMU Market
Test and Measurement
Electronic Measuring Device Market
Test and Measurement
High-Temperature Furnace Refractory Lining Inspection Systems Market
Test and Measurement
Micro Ohmmeter Market
Test and Measurement
Millimeter-Wave and Sub-THz Semiconductor Device Characterization Platforms Market
Test and Measurement
Continuous Friction Tester Market
Test and Measurement
Test and Measurement Market
Test and Measurement
Over-The-Air (OTA) Testing Market
Test and Measurement
Europe Signal Generator Market
Test and Measurement
High-Aspect-Ratio 3D NAND Metrology Equipment Market
Test and Measurement
Battery Test Equipment Market