
 Automated Test Equipment Market | 2026-2036
Automated Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Test Equipment Market Analysis
EU AI Act and CE marking under the MDR framework is hardening the cost-of-entry calculus for ATE vendors serving European aerospace and medical device clients. Teradyne Inc. leverages its dominant position in system-on-chip test handlers to sustain premium pricing in advanced packaging applications. Advantest Corporation anchors its competitive position through deep specialization in memory test systems for high-bandwidth DRAM and NAND flash.
Automated Test Equipment comprises programmable instrumentation systems that apply electrical signals, measure responses, and classify device performance against parametric limits, typically operating across frequency ranges from DC to 110 GHz depending on application. These systems serve primarily to screen manufacturing defects, validate design margins, and ensure compliance with industry-specific reliability standards before devices enter downstream assembly. RF testing commands expanding capital allocation as mmWave and beamforming architectures proliferate in 5G baseband and radar modules, while functional testers retain the largest installed base due to their versatility across automotive electronics and telecommunications end users. Mixed signal testing occupies a concentrated margin pool where vendors combine precision analog stimulus with high-speed digital capture for complex SoC validation.
FCC equipment authorization rules shape demand for electromagnetic compatibility pre-compliance testing in US-bound consumer electronics, while ETSI harmonized standards under the EU Radio Equipment Directive mandate specific spectral efficiency benchmarks for telecommunications ATE configurations. China's GB standards and MIIT radio transmission certifications create parallel test protocol requirements for vendors accessing domestic production networks. Stakeholders must monitor how divergent spectrum allocation timelines across the US, EU, and China reshape RF test capacity planning and instrument refresh cycles.
Market Dynamics
RF testing architectures are consolidating market power as 5G baseband and automotive radar modules force semiconductor manufacturers to abandon legacy digital-only platforms. The shift toward millimeter-wave validation and beamforming verification is compressing refresh cycles across Taiwan, South Korea, and US production networks.
Growth Catalysts
- ISO 26262 functional safety mandates:Automotive electronics suppliers in Germany and Japan are expanding test capacity to meet ASIL-D certification requirements for autonomous driving systems and battery management controllers.
- Memory test specialization:High-bandwidth DRAM and NAND flash validation demands are pulling capital toward advanced packaging applications where parametric limits tighten with each process node shrink.
- China:GB standards and MIIT radio transmission certifications create parallel test protocol requirements that domestic foundries must satisfy before accessing consumer electronics assembly networks.
Market Restraints
- Instrument input cost volatility:Precision analog stimulus components and high-speed digital capture modules face supply concentration risks from specialized Japanese and German component suppliers.
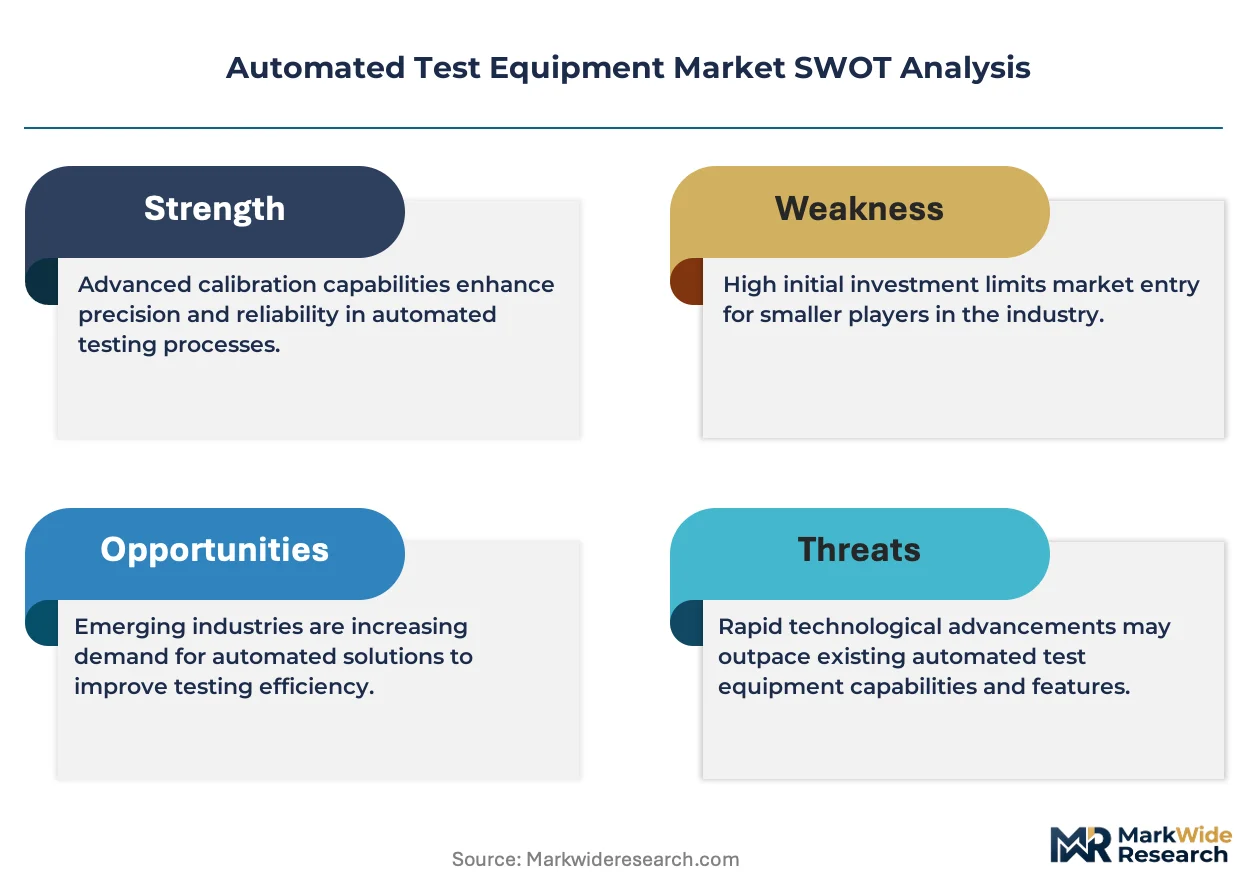
- Technical limitation:Electromagnetic interference shielding for 110 GHz test heads remains prohibitively expensive for mid-tier contract manufacturers serving industrial sensor markets.
- Regulatory friction:EU AI Act and CE marking under the MDR framework harden cost-of-entry calculus for ATE vendors attempting to serve European aerospace and medical device clients.
Strategic Opportunities
- Underpenetrated geography:India semiconductor test infrastructure remains nascent despite PLI scheme incentives for domestic electronics manufacturing and chip assembly.
- Technology convergence:Mixed-signal testers combining RF stimulus with precision analog measurement are capturing margin pools previously split between discrete instrument categories.
- Regulatory tailwind:FCC equipment authorization rules for electromagnetic compatibility pre-compliance testing are creating dedicated capacity demand among US-bound consumer electronics exporters.
Industry Challenges
- Calibration technician scarcity:mmWave test head alignment and vector network analyzer verification require specialized skill sets concentrated among veterans of defense and telecommunications equipment sectors.
- Capex intensity:Single advanced packaging test cell deployments demand capital commitments that strain balance sheets of tier-two OSATs competing for automotive semiconductor contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Test Equipment Market |
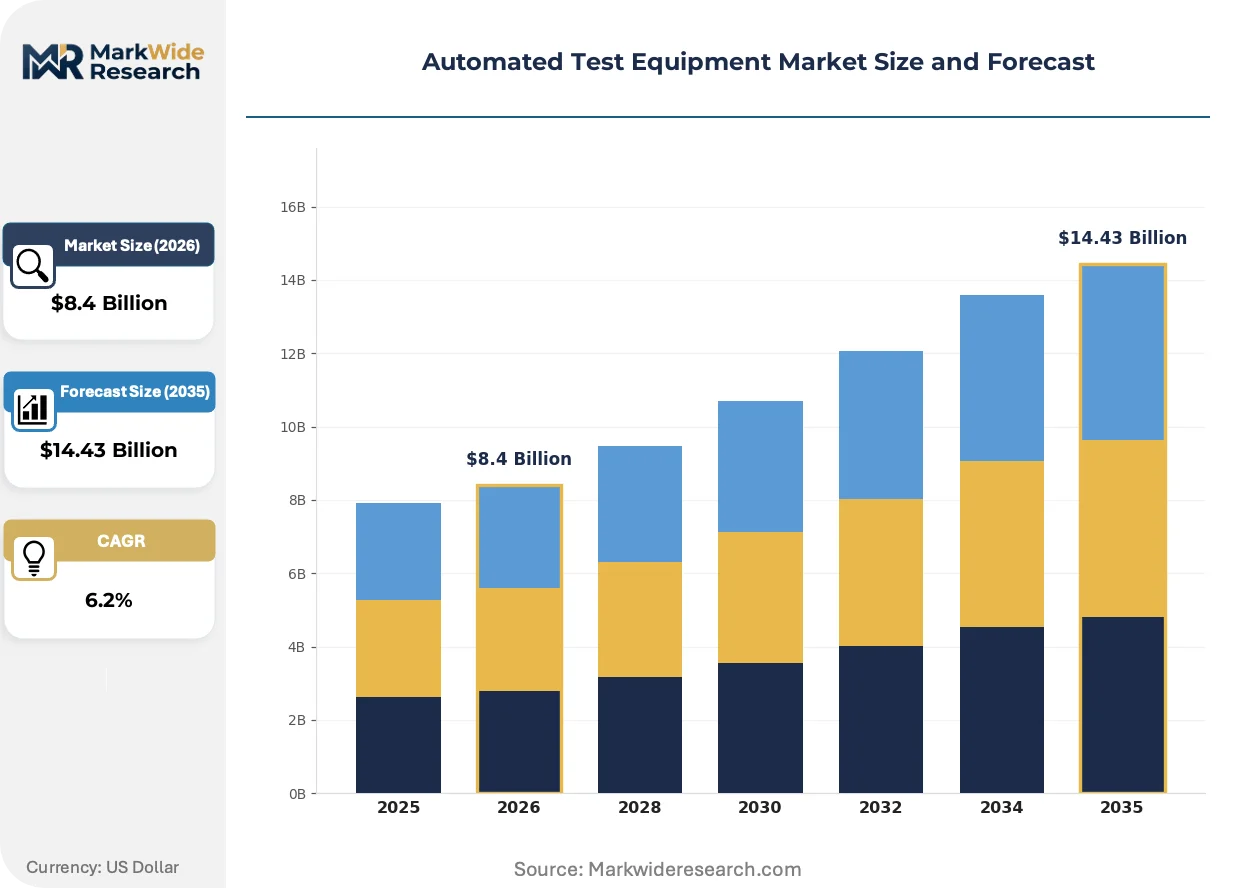
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Functional Testers, In-Circuit Testers, Burn-In Testers, Automated Optical Inspection Technology: RF Testing, Digital Testing, Mixed Signal Testing, Low Voltage Testing End User: Aerospace, Automotive Electronics, Telecommunications, Consumer Electronics Installation: On-Premises, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Chroma ATE Inc., Astronics Corporation, Advantest Corporation, Roos Instruments Inc., Aemulus Holdings, Teradyne Inc., National Instruments Corporation, Marvin Test Solutions Inc., Cohu Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Test Equipment Market Emerging Trajectories
Test system architectures are fragmenting along frequency-domain lines as digital-centric legacy platforms lose relevance. The convergence of 5G deployment timelines with automotive radar mandates is forcing instrument vendors to recalibrate R&D priorities.
Modular RF test instrumentation is consolidating functional blocks previously served by discrete spectrum analyzers, signal generators, and network analyzers into unified PXIe and AXIe chassis configurations. Defense contractors and telecommunications equipment manufacturers are adopting these platforms fastest. This consolidation is compressing the addressable market for standalone instruments while expanding per-site test throughput capacity.
EU AI Act conformity assessment procedures are mandating traceable test documentation for machine-learning-enabled diagnostic equipment. Medical device manufacturers must demonstrate algorithm validation through reproducible test protocols. European aerospace suppliers are responding by embedding ATE data logging directly into production execution systems rather than treating test as a discrete quality gate.
Buying patterns among foundry customers are compressing equipment refresh cycles from seven-year norms toward four-year replacement schedules. Contract manufacturers in Taiwan and South Korea are leasing test capacity through equipment-as-a-service arrangements rather than capital purchases. This shift is most visible among OSATs serving Apple and Qualcomm supply chains where volume volatility demands operational flexibility over asset ownership.
Automated Test Equipment Market Segmentation
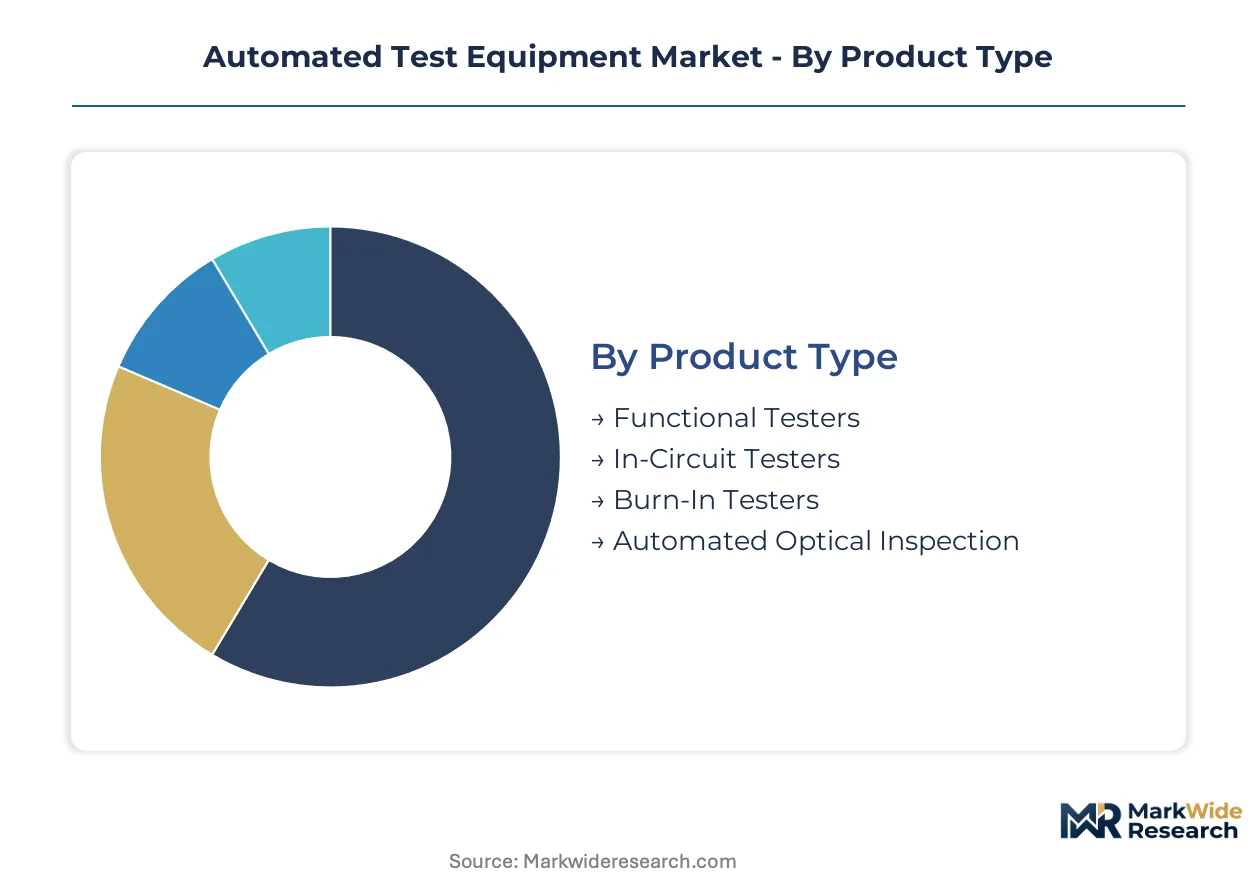
Segmentation in the Automated Test Equipment market reveals how test architectures fragment across frequency domains, deployment models, and end-use reliability requirements. Equipment vendors calibrate R&D portfolios against these divisions to capture margin pools in high-growth validation categories.
Product Type:
Standardization dominates high-volume functional testing while customization concentrates in specialized burn-in and optical inspection configurations.
- Functional Testers:Programmable systems apply electrical stimuli and measure parametric responses against device specifications, typically spanning DC to multi-gigahertz ranges. Automotive electronics suppliers in Germany and Japan deploy these most intensively for ISO 26262 ASIL-D certification of autonomous driving controllers.
- In-Circuit Testers:Bed-of-nails fixtures verify component placement and solder integrity on populated printed circuit boards without powering the full assembly. Taiwan and South Korea contract manufacturers favor these for high-mix consumer electronics where defect isolation speed determines line throughput economics.
- Burn-In Testers:Accelerated life testing under thermal and electrical stress screens early-life failures in semiconductor devices.
- Automated Optical Inspection:Machine vision systems detect solder joint defects, component orientation errors, and placement misalignment.
Most installed capacity flows through Functional Testers. Expansion is steepest in Automated Optical Inspection.
Technology:
Cost tiers separate legacy digital platforms from premium RF and mixed-signal architectures where precision analog components drive capital intensity.
- RF Testing:Millimeter-wave vector network analyzers and spectrum analyzers validate 5G baseband and automotive radar modules up to 110 GHz. Taiwan, South Korea, and United States production networks are consolidating capacity here as beamforming verification demands displace legacy digital-only platforms.
- Digital Testing:Pattern generators and logic analyzers verify digital integrated circuit functionality at speed. Mature automotive and telecommunications applications in Japan retain substantial installed base despite shrinking share of new capital allocation.
- Mixed Signal Testing:Combined precision analog stimulus with high-speed digital capture serves complex SoC validation.
- Low Voltage Testing:Specialized instrumentation for sub-1V power management and battery-powered device characterization.
RF Testing commands the steepest capital allocation growth trajectory. Digital Testing retains the largest cumulative installed base.
End User:
Application-specific reliability mandates create divergent procurement patterns across aerospace certification rigor and consumer electronics volume sensitivity.
- Aerospace:DO-178C and DO-254 compliance requirements drive exhaustive test documentation and traceability protocols. European suppliers embedding ATE data logging directly into production execution systems rather than treating test as discrete quality gates.
- Automotive Electronics:Functional safety mandates under ISO 26262 and emerging cybersecurity standards are expanding test capacity for battery management systems and autonomous driving platforms.
- Telecommunications:5G base station and optical transport equipment validation demands high-throughput RF and mixed-signal test cells.
- Consumer Electronics:FCC equipment authorization rules for electromagnetic compatibility pre-compliance testing shape US-bound exporter procurement decisions.
Automotive Electronics absorbs the fastest capacity expansion. Consumer Electronics maintains the broadest geographic distribution of installed equipment.
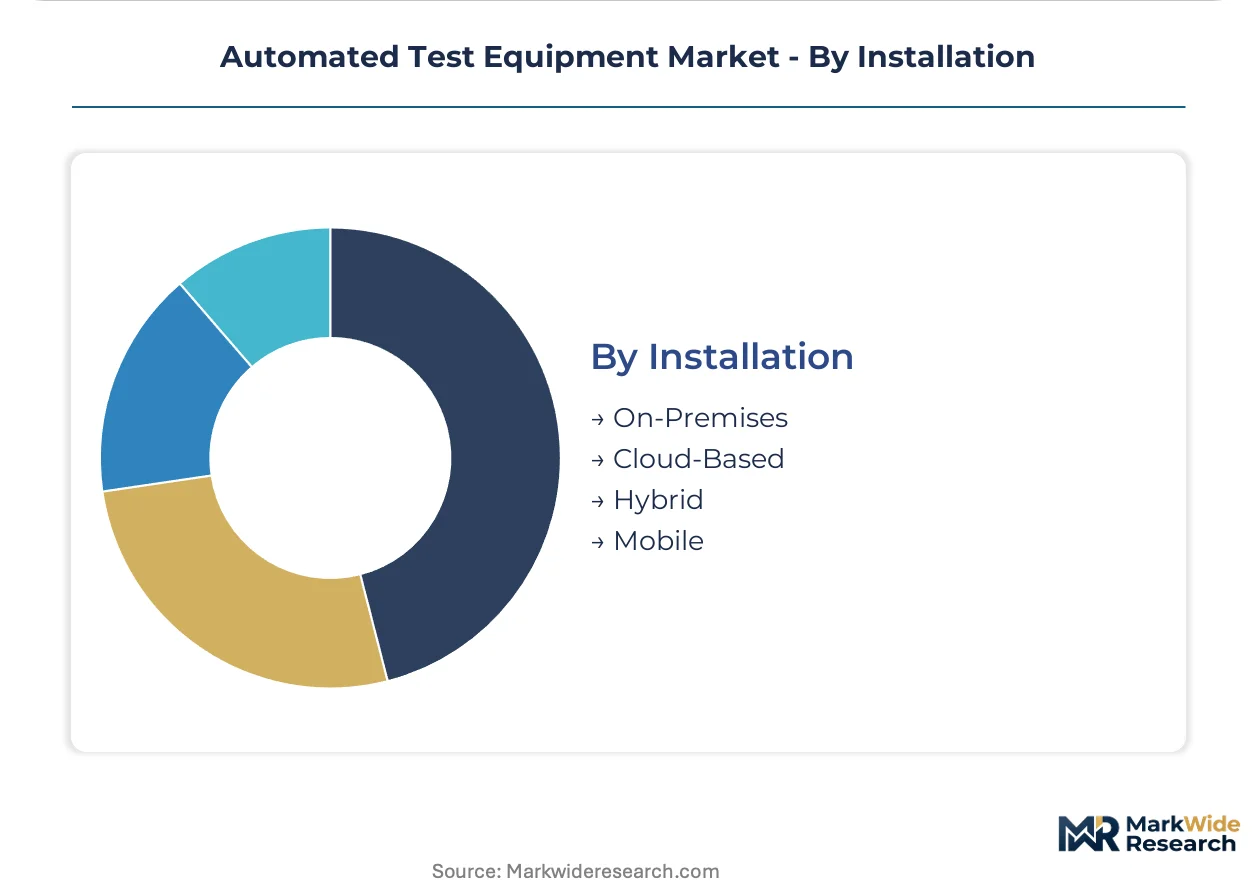
Installation:
Volume concentration favors on-premises deployments while operational flexibility demands pull toward hybrid and cloud-adjacent configurations.
- On-Premises:Capital-intensive test floor installations with dedicated environmental chambers and handler integration dominate high-volume semiconductor manufacturing. Taiwan and South Korea foundries prefer ownership for core process control.
- Cloud-Based:Remote test orchestration and data analytics platforms enable centralized management of distributed test operations.
- Hybrid:Edge test execution with cloud-based result aggregation and algorithmic analysis balances latency sensitivity with computational scale.
- Mobile:Portable test instrumentation for field service, depot repair, and distributed manufacturing quality verification.
On-Premises deployments retain dominant capacity share. Hybrid architectures are climbing fastest among OSATs serving volume-volatile supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Calibration technicians with mmWave test head expertise cluster in Taiwan, South Korea, and the United States, anchoring the geographic distribution of advanced ATE deployment. These talent concentrations align with foundry and OSAT investments in 5G baseband and automotive radar validation capacity.
United States
FCC equipment authorization rules for electromagnetic compatibility pre-compliance testing drive dedicated capacity demand among consumer electronics exporters. The IRA semiconductor manufacturing incentives are expanding domestic foundry buildouts in Arizona and Texas. Phoenix and Austin metro areas are absorbing test cell investments from OSATs serving Apple and Qualcomm supply chains.
Taiwan
TSMC-led advanced packaging roadmaps are compressing equipment refresh cycles from seven-year norms toward four-year replacement schedules. The National Development Council's semiconductor initiative prioritizes test infrastructure for 3D chiplet architectures. Hsinchu Science Park hosts the densest concentration of RF test handler deployments for mmWave device validation.
South Korea
Samsung Electronics and SK Hynix memory test specialization demands are pulling capital toward high-bandwidth DRAM and NAND flash validation systems. KOSPI-listed equipment vendors are leasing test capacity through equipment-as-a-service arrangements to manage volume volatility. Pyeongtaek and Icheon semiconductor clusters are prioritizing mixed-signal testers for complex SoC verification.
China
GB standards and MIIT radio transmission certifications create parallel test protocol requirements for domestic foundries accessing consumer electronics assembly networks. The dual carbon goals are accelerating energy-efficient test floor retrofits in Yangtze River Delta facilities. Shanghai and Wuxi industrial zones are expanding burn-in tester capacity for automotive-grade semiconductor qualification.
Japan
METI's semiconductor resilience strategy is preserving digital tester installed bases for mature automotive and telecommunications applications. JIS standards compliance requirements sustain demand for precision analog stimulus components from domestic suppliers. Kyushu and Tohoku regions maintain specialized calibration technician pipelines for legacy platform maintenance.
Automated Test Equipment Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across fragmented tier structures. Market concentration is moderate, with three to five vendors capturing disproportionate share in memory test and RF validation subsegments. Strategic archetypes include full-stack system integrators, component-specialized instrument vendors, and handler-focused automation suppliers. Competitive moves center on portfolio diversification into adjacent test modalities and geographic expansion through localized service partnerships.
Among Japan-based test system specialists, Advantest Corporation and Teradyne Inc. exemplify contrasting scale archetypes. Chroma ATE Inc. represents Taiwan-based challengers integrating power electronics test expertise with semiconductor handler platforms. These three anchors demonstrate how regional industrial specialization shapes competitive positioning without requiring identical capability portfolios.
| Leading Market Players |
|---|
| Chroma ATE Inc. |
| Astronics Corporation |
| Advantest Corporation |
| Roos Instruments Inc. |
| Aemulus Holdings |
| Teradyne Inc. |
| National Instruments Corporation |
| Marvin Test Solutions Inc. |
| Cohu Inc. |
| Others |
Supply Flow & Price Mechanics
Foundry procurement teams in Taiwan and South Korea are consolidating vendor relationships to secure priority allocation of precision analog stimulus components, forcing mid-tier ATE suppliers to absorb input cost volatility or cede share to integrated system vendors.
Pricing Analysis
Bundled test cell deployments combining handlers, instrumentation, and calibration services command premiums over unbundled component sales. Three-tier pricing structure across premium, standard, and economy levels separates RF/mmWave configurations from legacy digital platforms and refurbished installed base equipment. Price differentiation rests on ISO 26262 certification tier and after-sales service bundling. Cost compression in standard-tier functional testers is intensifying because OSATs serving automotive contracts demand shorter payback periods. Contract manufacturers in Taiwan exhibit highest price sensitivity; aerospace qualification labs in Germany and the United States show least.
Supply Chain Analysis
Regional distribution centers in Yokohama, Singapore, and Amsterdam anchor hub-and-spoke patterns for precision analog components and high-speed digital capture modules. Manufacturing concentration in Japan, Germany, and the United States feeds specialized instrument input dependencies on ceramic substrates, GaAs semiconductors, and precision coaxial connectors. Single-source vulnerability from Japanese component suppliers for 110 GHz test head assemblies creates structural exposure. Distribution runs through authorized service partners with localized calibration capabilities rather than direct OEM fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in automated test equipment rests on the shift toward equipment-as-a-service leasing models that capture recurring revenue streams while transferring utilization risk to OSAT customers.
For Market Incumbents: Acquire mmWave calibration technician training pipelines and certification assets to lock in scarce alignment expertise before defense contractor retirements accelerate. Consolidate backward integration into precision analog stimulus component production to offset Japanese supplier concentration risk. Anchor defensive positioning through embedded data logging integrations that raise switching costs for European aerospace clients facing EU AI Act documentation mandates. For New Entrants and Emerging Players: OSAT service partnerships in India offer the most penetrable geographic entry point given PLI scheme incentives and nascent domestic test infrastructure. Target mixed-signal tester white space where RF stimulus and precision analog measurement convergence creates margin pools previously split between discrete categories. Pursue FCC equipment authorization pre-compliance testing as a beachhead service before expanding into full system sales. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized RF test subsystem vendors possessing 110 GHz intellectual property and automotive radar validation protocols. Long-term viability favors acquisition targets with recurring calibration service revenue anchoring hardware placements. Monitor equipment refresh cycle compression from seven-year toward four-year norms as the inflection signal for leasing model adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Calibration Firm | Secures scarce mmWave technician expertise concentrated in defense and telecommunications veterans. |
| Equipment-as-a-Service Platform Launch | Captures recurring revenue from OSATs serving Apple and Qualcomm volume-volatile supply chains. |
| Backward Integration into Precision Components | Reduces exposure to Japanese and German ceramic substrate and GaAs supplier concentration. |
| EU AI Act Compliance Documentation Suite | Addresses hardened cost-of-entry for European aerospace and medical device qualification labs. |
| India Service Partnership Network | Positions for PLI scheme semiconductor test infrastructure buildouts in domestic electronics manufacturing. |
Methodological Framework
Bottom-up semiconductor end-use modeling reconciled against top-down ATE shipment tracking forms the analytical core of this study. Primary interviews with test floor managers at Taiwan and South Korea foundries, calibration technicians at Japanese OSATs, procurement leads at German automotive electronics suppliers, and regulatory affairs specialists at European aerospace manufacturers combined with secondary validation from SEC filings, MIIT certification databases, and ETSI harmonized standards documentation. Triangulation across these sources anchored volume and value estimates.
Historical trendline analysis of equipment refresh cycles, capital expenditure patterns, and foundry utilization rates informed projection parameters across the analysis window. Segmentation dimensions modeled include product type, technology architecture, end-user reliability tier, and installation deployment mode. CAGRs derived from slope analysis of normalized capital intensity trends and semiconductor content-per-vehicle trajectories. RF test capacity expansion timelines and memory process node roadmaps served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to spectrum allocation divergence across US, EU, and Chinese regulators and to mmWave component supply disruptions. Forecasts reflect documented assumptions regarding foundry buildout schedules and automotive functional safety mandate implementation pacing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Chiplet Integration and Die-to-Die Interconnect Test Solutions Market
Test and Measurement
Semiconductor Metrology and Inspection Market
Test and Measurement
Non-Destructive Testing Market
Test and Measurement
Optical Critical Dimension (OCD) Measurements System Market
Test and Measurement
Fogging Tester Market
Test and Measurement
Battery Testing and Inspection Equipment Market
Test and Measurement
LTE Testing Equipment Market
Test and Measurement
Creep and Stress Rupture Testers Market
Test and Measurement
Microwave Power Meters Market
Test and Measurement
Distortion Meter Market
Test and Measurement
Brightness Meter Market
Test and Measurement
VXI Testing Equipment Market
Test and Measurement
Cooling Laser Power Measurement Sphere Market
Test and Measurement
Asia-Pacific Nondestructive Testing Equipment Market
Test and Measurement
Hearing Aid and True Wireless Earbud Acoustic Performance Test Systems Market
Test and Measurement
Bursting Strength Tester Market