
 Self-Service Kiosk Market | 2026-2036
Self-Service Kiosk Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Service Kiosk Market Intelligence
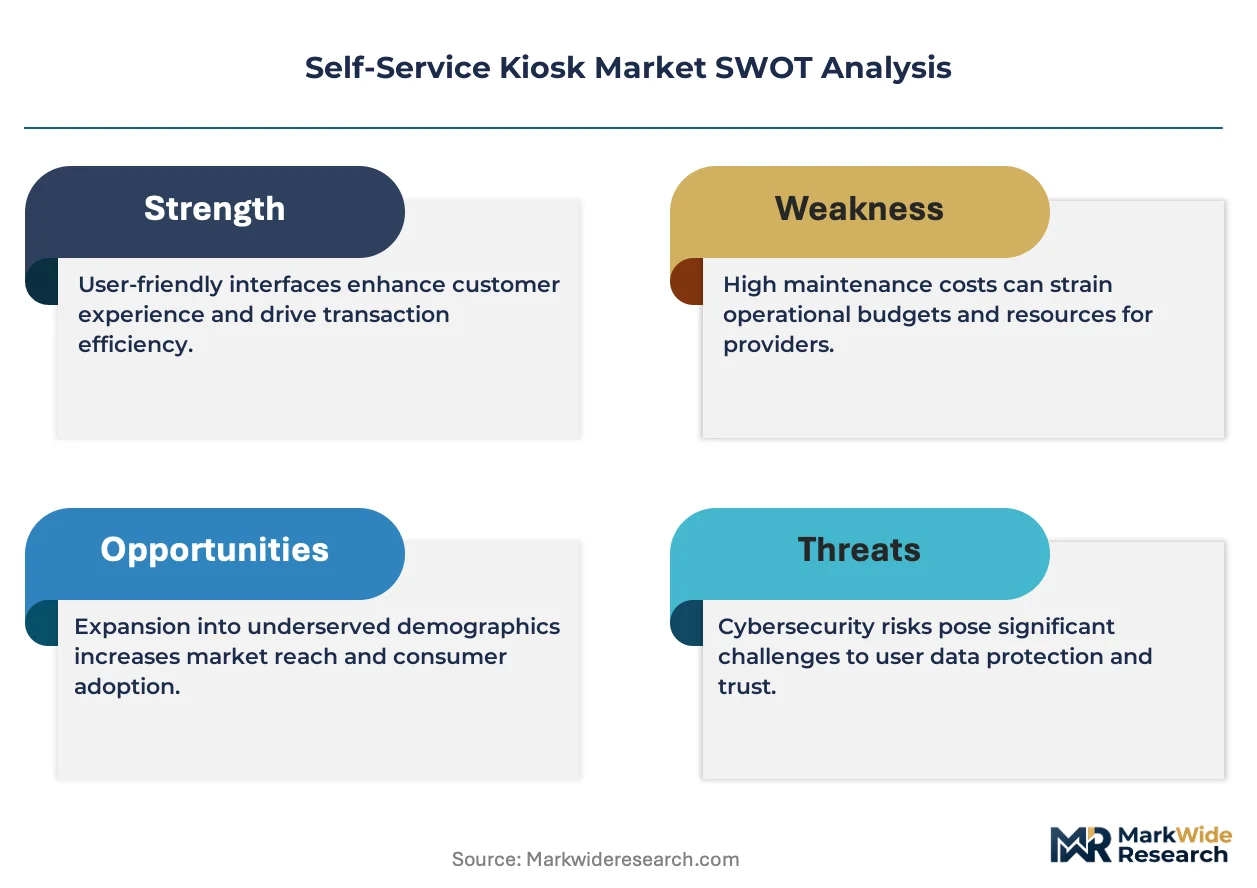
Leasing and hardware-as-a-service contracting is narrowing the capital barrier for mid-size retail and food-service chains that previously could not afford upfront kiosk deployments. NCR Voyix Corporation leverages its installed base of point-of-sale systems to bundle software and managed services. Diebold Nixdorf, Incorporated anchors its position through manufacturing scale and bank-grade security certifications. Zebra Technologies Corporation specializes in ruggedized mobile and stationary units for warehouse and logistics environments.
A self-service kiosk is an interactive, freestanding or wall-mounted terminal that integrates a touchscreen display, compute module, payment reader, and peripheral enclosure to execute transactions or dispense information without staffed assistance. Industrial-grade units typically employ IP54-rated steel housings, projected capacitive touch layers, and thermal receipt printers engineered for continuous daily operation. Stationary kiosks dominate current installed value because they occupy high-traffic fixed locations with reliable power and network connectivity. Mobile kiosks represent the fastest-expanding category as event venues, pop-up retail, and field healthcare adopt battery-powered, wheeled, or cart-integrated form factors. Interactive kiosks concentrate margin pools in software licensing, remote monitoring, and content management subscriptions rather than hardware alone.
The ADA in the United States, the EU Web Accessibility Directive, and Japan's JIS standards collectively mandate perceptible information, operable interfaces, and robust compatibility for public-facing terminals. These frameworks compel manufacturers to redesign input methods, certify assistive-technology integration, and document compliance before securing procurement contracts. Stakeholders must monitor how biometric authentication and facial-recognition capabilities trigger emerging privacy regulations that could restrict deployment scope or require consent-management infrastructure.
Market Dynamics
Leasing and hardware-as-a-service contracting is narrowing the capital barrier for mid-size retail and food-service chains that previously could not afford upfront kiosk deployments. This structural shift toward operational expenditure models is compressing sales cycles and expanding addressable demand beyond enterprise buyers.
Growth Catalysts
- ADA Accessibility Mandates:The Americans with Disabilities Act and comparable European and Japanese standards require voice guidance, tactile controls, and screen-reader compatibility, compelling hardware upgrades across installed bases.
- Quick-Service Restaurant Automation:Ordering terminals reduce labor costs and compress transaction times as QSR chains deploy self-checkout to offset wage pressure and throughput constraints.
- China Municipal Digitization:Metro systems, hospital networks, and retail chains are digitizing citizen-facing services through tens of thousands of municipal and privately operated terminals.
Market Restraints
- Semiconductor Supply Concentration:Touch controller and compute module fabrication concentrates in Taiwan and South Korea, exposing kiosk manufacturers to single-source disruption risk.
- Steel Input Volatility:IP54-rated steel housings face price swings from energy-intensive European and Chinese metallurgy, compressing hardware margins on fixed-price contracts.
- Biometric Privacy Friction:Emerging facial-recognition capabilities trigger GDPR and state-level privacy regulations that restrict deployment scope or require consent-management infrastructure.
Strategic Opportunities
- Mobile Kiosk Form Factors:Battery-powered, wheeled, or cart-integrated units are penetrating event venues, pop-up retail, and field healthcare where fixed infrastructure is unavailable.
- Software Subscription Models:Remote monitoring and content management subscriptions concentrate margin pools beyond hardware, creating recurring revenue streams.
- Rural Healthcare Networks:Underpenetrated hospital systems in India and Southeast Asia present white space for patient check-in and pharmacy dispensing terminals.
Industry Challenges
- Embedded Systems Engineering Talent:Shortage of firmware developers capable of integrating payment readers, thermal printers, and assistive-technology interfaces slows product cycles.
- Certification Timeline Compression:Bank-grade security certifications and accessibility compliance documentation extend procurement-to-deployment intervals, straining working capital.
- Legacy POS Integration Complexity:Middleware development for interoperability with incumbent point-of-sale architectures consumes engineering resources and delays customer onboarding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Service Kiosk Market |
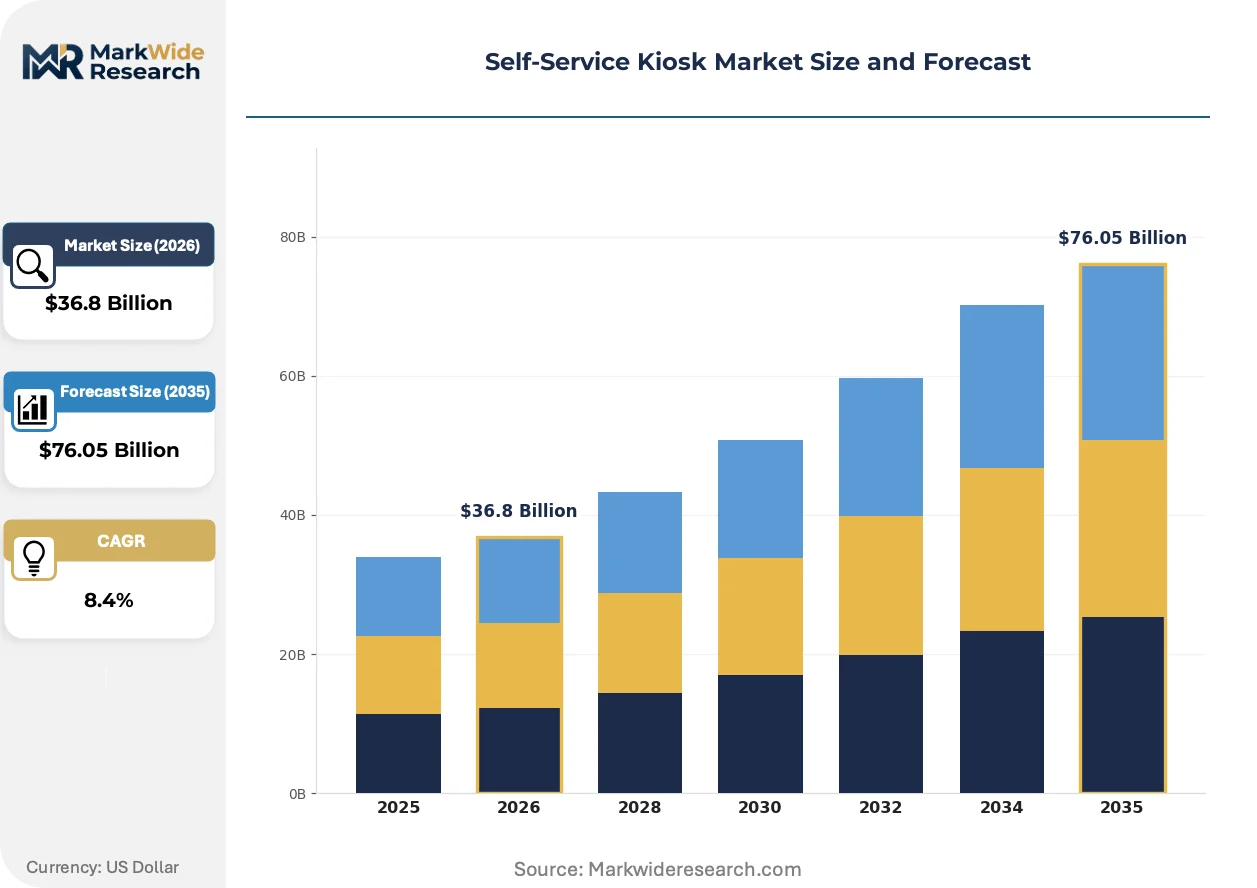
| Market Size in 2026 | $36.8 Billion |
| Market Size in 2035 | $76.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stationary Kiosks, Mobile Kiosks, Outdoor Kiosks, Interactive Kiosks End User: Retail Stores, Restaurants, Airports, Healthcare Facilities Technology: Touchscreen, NFC, QR Code Scanners, Biometric Application: Ticketing, Ordering, Check-in, Information Distribution |
| Companies Covered | Zebra Technologies Corporation, Advantech Co., Ltd., NCR Voyix Corporation, Olea Kiosks Inc, Fuji Electric Co., Ltd., Diebold Nixdorf, Incorporated, Glory Ltd., Meridian Kiosks, KIOSK Information Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Service Kiosk Market Strategic Shifts & Innovations
Cloud-native kiosk management platforms are displacing on-premise server architectures, enabling centralized content deployment and predictive maintenance across distributed terminal fleets. This infrastructure shift is reshaping vendor competitive positioning toward software and services.
Computer vision and edge AI processors are digitizing customer identification, age verification, and inventory recognition at the terminal. Quick-service restaurants and convenience stores are deploying these capabilities fastest, compressing transaction authentication steps and reducing staffed intervention requirements.
REACH and RoHS substance restrictions in Europe are forcing enclosure manufacturers to reformulate coatings and solder compositions. Kiosk OEMs serving EU procurement contracts must document material compliance through supply chain audits, with medical and transit applications facing the strictest enforcement timelines.
Hospital networks and municipal transit authorities are consolidating vendor relationships around full-stack service contracts. Equipment procurement with separate maintenance agreements is yielding to bundled subscriptions covering hardware, software, remote monitoring, and field service, with this pattern most visible in Germany and Japan where facility management outsourcing is mature.
Self-Service Kiosk Market Segmentation
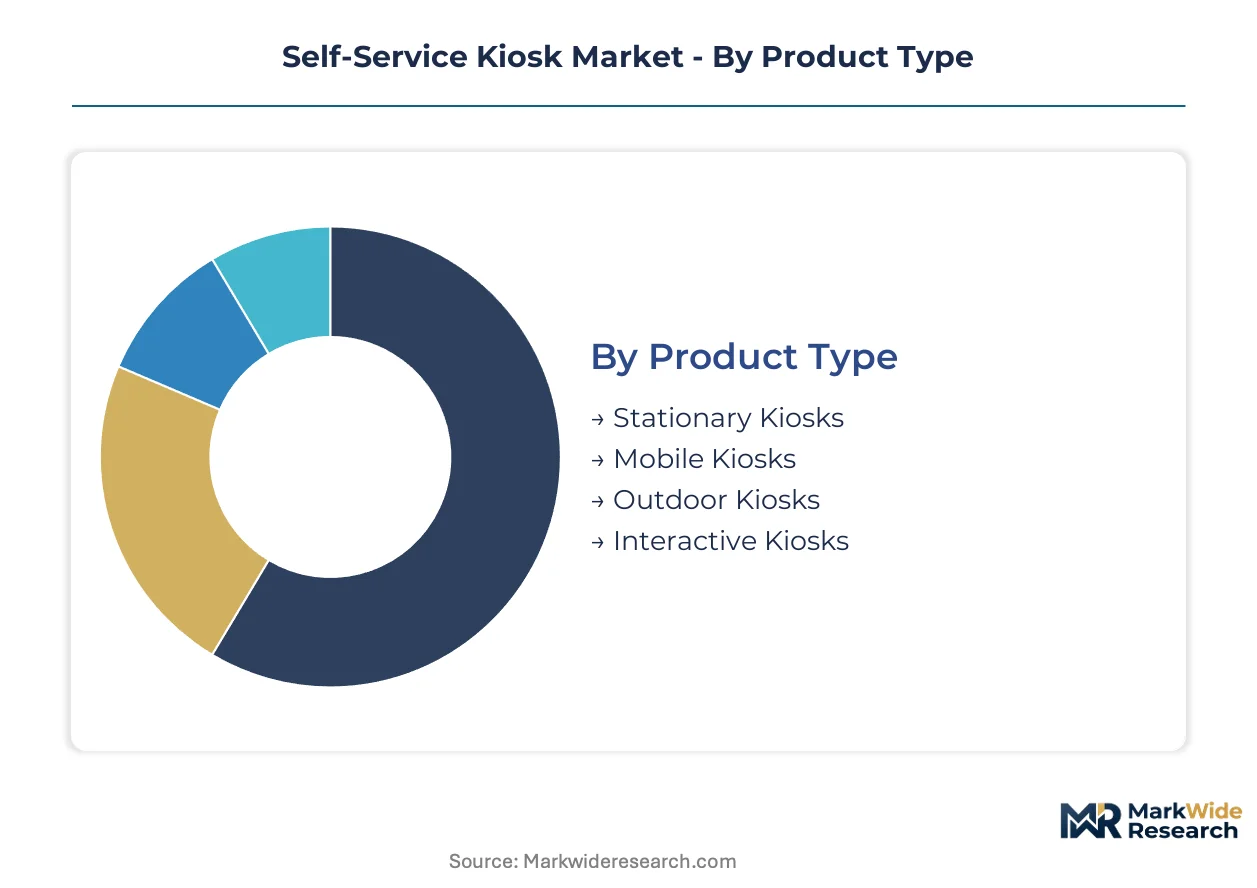
Self-service kiosk deployment patterns diverge sharply across hardware configurations, customer environments, and authentication methods. Procurement decisions hinge on traffic density, infrastructure availability, and regulatory compliance requirements rather than unit economics alone.
Product Type:
Hardware form factor determines capital intensity, installation complexity, and operational flexibility across deployment scenarios.
- Stationary Kiosks:Fixed-location units with IP54-rated steel housings, projected capacitive touch layers, and continuous power connectivity anchor high-throughput environments. Metro systems in China and hospital networks in Japan specify these for reliability under 16-hour daily operation cycles.
- Mobile Kiosks:Battery-powered, wheeled, or cart-integrated configurations penetrate event venues, pop-up retail, and field healthcare where fixed infrastructure is unavailable. Demand concentrates in Germany and the United States for temporary vaccination sites and seasonal retail activation.
- Outdoor Kiosks:Weather-resistant enclosures with extended temperature tolerances serve transit shelters and municipal wayfinding installations.
- Interactive Kiosks:Software-heavy terminals concentrate margin pools in content management and remote monitoring subscriptions rather than hardware margins.
Stationary kiosks command the established base. The steepest expansion runs through mobile kiosks.
End User:
Customer environment shapes durability specifications, payment integration requirements, and accessibility compliance obligations.
- Retail Stores:Self-checkout terminals with barcode scanners and receipt printers reduce staffed lane requirements. Deployment concentrates in China and the United States as labor costs and shrinkage prevention drive capital allocation.
- Restaurants:Quick-service ordering terminals compress transaction times and offset wage pressure. Chains in Japan and South Korea deploy these fastest for throughput optimization during peak hours.
- Airports:Check-in and boarding pass dispensing units face strict security certification timelines and multilingual interface requirements.
- Healthcare Facilities:Patient check-in and pharmacy dispensing terminals demand HIPAA compliance and assistive-technology integration under ADA mandates.
Retail stores command the established base. The steepest expansion runs through restaurants.
Technology:
Interface and authentication methods determine user friction, fraud exposure, and hardware bill-of-materials composition.
- Touchscreen:Projected capacitive layers dominate as the baseline interface for ordering, ticketing, and information retrieval. Municipal contracts in China and retail deployments in Germany specify these for universal accessibility under local disability mandates.
- NFC:Contactless payment readers enable tap-to-pay transaction completion without physical card insertion. Transit authorities in Japan and convenience store chains in South Korea standardize on NFC for sub-second authentication speed.
- QR Code Scanners:Camera-based code recognition supports mobile wallet integration and loyalty program enrollment.
- Biometric:Facial recognition and fingerprint authentication trigger GDPR and state-level privacy regulations that restrict deployment scope or require consent-management infrastructure.
Touchscreen commands the established base. The steepest expansion runs through biometric.
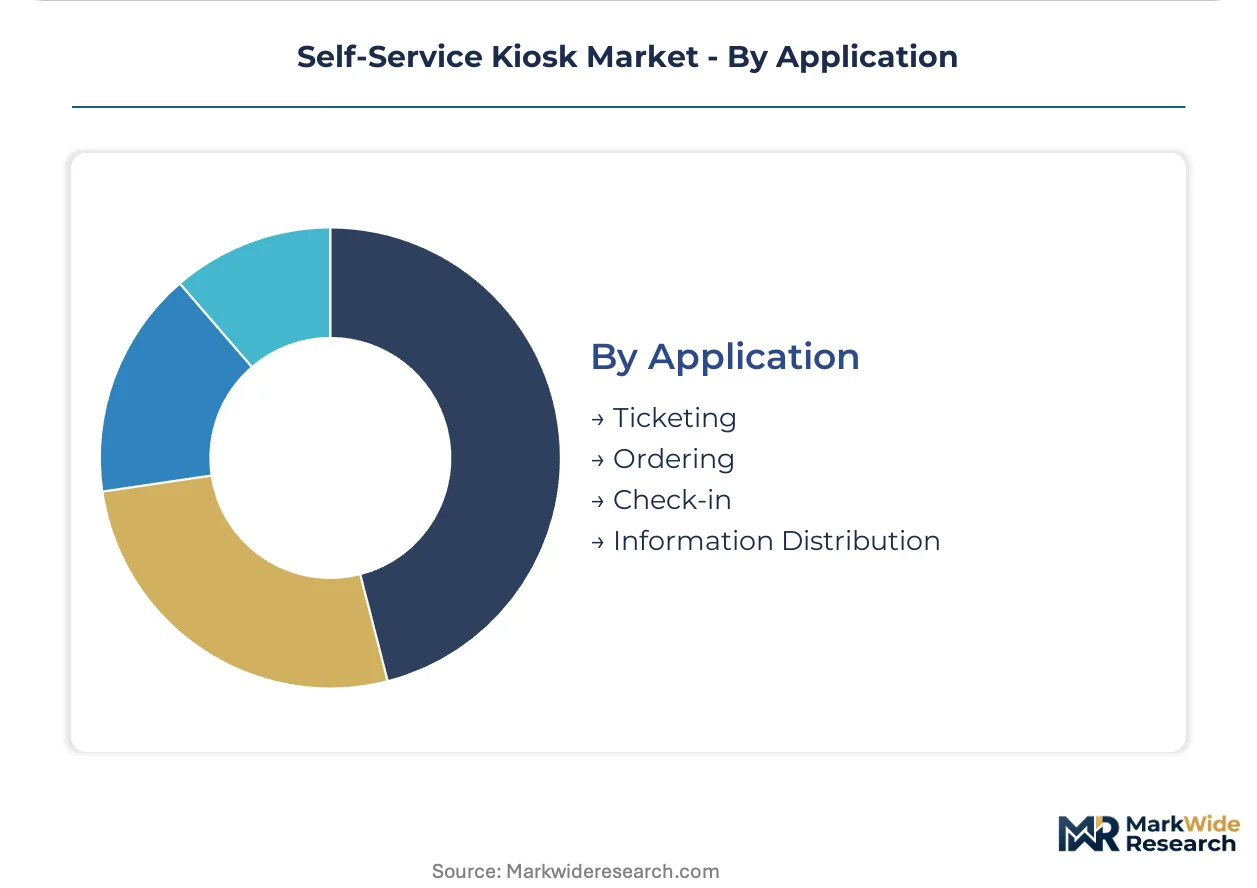
Application:
Use case determines software architecture, peripheral integration, and revenue model structure across terminal fleets.
- Ticketing:Transit and entertainment venues require thermal printers, payment readers, and real-time inventory synchronization. Metro systems in China and railway networks in Japan deploy these at scale for commuter volume management.
- Ordering:Food-service and retail applications integrate kitchen display systems or warehouse management APIs for fulfillment coordination. Quick-service chains in the United States and convenience stores in South Korea compress transaction times through these deployments.
- Check-in:Patient and passenger identity verification demands document scanners and biometric capture peripherals.
- Information Distribution:Wayfinding and directory terminals concentrate margin in content management subscriptions and advertising revenue shares.
Ticketing commands the established base. The steepest expansion runs through ordering.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese and German procurement markets where bundled service contracts command premiums, while Chinese municipal tenders compress hardware margins through volume aggregation. This asymmetry shapes divergent vendor strategies across major deployment zones.
United States
Quick-service restaurant chains and hospital networks drive kiosk deployment, with ADA accessibility mandates compelling voice guidance and tactile control integration. The Department of Justice enforces ADA Title III compliance for public accommodations, extending procurement timelines. Deployment clusters concentrate in Texas and Florida where healthcare systems digitize patient check-in workflows.
China
Metro authorities and municipal governments deploy tens of thousands of terminals for transit ticketing and citizen service digitization. SAMR oversees payment security certification under national financial infrastructure standards. Manufacturing gravity centers on the Yangtze River Delta where enclosure fabricators and touch module assemblers co-locate.
Japan
Convenience store chains and railway operators standardize on NFC-integrated terminals for sub-second transaction authentication. METI administers JIS accessibility standards that mandate screen-reader compatibility in public-facing installations. Industrial concentration in the Kansai region around Osaka sustains precision metalworking for kiosk enclosures.
Germany
Facility management outsourcing maturity drives bundled hardware-software-service contracts across hospital and transit applications. REACH and RoHS substance restrictions enforce supply chain documentation requirements for EU procurement. The Ruhr industrial corridor hosts steel enclosure specialists serving bank-grade security specifications.
South Korea
Retail chains and convenience stores deploy ordering terminals for peak-hour throughput optimization. MFDS regulates medical kiosk applications while the central bank oversees payment terminal security standards. Seoul Capital Area concentration supports rapid field service response for enterprise fleet deployments.
Self-Service Kiosk Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying touch modules, thermal printers, and payment readers. The vendor base organizes around three archetypes: full-stack service providers bundling hardware with remote monitoring, enclosure fabricators differentiating on IP ratings and steel grades, and software houses licensing cloud-native management platforms. Competitive moves concentrate on strategic partnerships for POS middleware integration and geographic expansion through local system integrators.
Among North American platform integrators, NCR Voyix Corporation and Diebold Nixdorf, Incorporated exemplify the full-stack service archetype, while Zebra Technologies Corporation represents the ruggedized hardware specialization vector. These three entities anchor distinct competitive positions without overlapping core value propositions.
| Leading Market Players |
|---|
| Zebra Technologies Corporation |
| Advantech Co., Ltd. |
| NCR Voyix Corporation |
| Olea Kiosks Inc |
| Fuji Electric Co., Ltd. |
| Diebold Nixdorf, Incorporated |
| Glory Ltd. |
| Meridian Kiosks |
| KIOSK Information Systems |
| Others |
Cost & Logistics Intelligence
Overcapacity in Chinese enclosure fabrication is compressing supplier margins while enabling aggressive pricing from kiosk OEMs serving municipal transit tenders, creating divergent pricing postures between volume-aggregated public procurement and premium bundled service contracts in Germany and Japan.
Pricing Analysis
Configured-to-order pricing commands a substantial premium over standard catalogue units due to accessibility compliance documentation and bank-grade security certification requirements. Three-tier pricing structure across premium, standard, and economy levels stratifies by after-sales service bundling and remote monitoring subscription inclusion. Cost compression in the standard tier is intensifying because Chinese municipal tenders aggregate volume and squeeze hardware margins. Quick-service restaurant chains exhibit the highest price sensitivity, prioritizing per-unit capital expenditure minimization, while hospital networks in Japan demonstrate lowest sensitivity due to facility management outsourcing maturity and total-cost-of-ownership procurement criteria.
Supply Chain Analysis
Extended payment terms from Taiwanese touch-controller suppliers and supply-chain finance facilities from South Korean compute-module vendors are reshaping working capital dynamics for enclosure fabricators. Component sourcing draws from Taiwan for projected capacitive layers, South Korea for edge processors, and China for IP54-rated steel housings. Single-source vulnerability concentrates in touch-controller fabrication, where earthquake exposure in Taiwan creates disruption risk. Distribution runs through direct OEM relationships for enterprise fleets and local system integrators for mid-market retail and food-service deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware engineering talent capable of integrating payment readers, thermal printers, and assistive-technology interfaces commands scarcity premiums, constraining product development velocity across the vendor base and creating acquisition leverage for firms with captive embedded-systems capabilities.
For Market Incumbents: Entrench market position through backward integration into touch-module assembly and predictive maintenance software development, countering margin pressure from Chinese volume aggregators and semiconductor supply concentration. Prioritize certification investment for ADA, JIS, and EU Web Accessibility Directive compliance to defend premium pricing in German hospital and Japanese railway procurement. For New Entrants and Emerging Players: Pursue mobile kiosk form factors for event venues and field healthcare in the United States and Germany, where fixed infrastructure gaps create deployable white space. Target rural healthcare networks in India and Southeast Asia for patient check-in terminals, leveraging hardware-as-a-service contracting to narrow capital barriers. Establish go-to-market partnerships with local system integrators possessing incumbent POS middleware relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among full-stack service providers bundling remote monitoring, content management, and field service contracts, warranting premium valuation multiples relative to hardware-centric competitors. Acquisition focus should center on cloud-native kiosk management platforms with proven hospital or transit authority deployments. Monitor biometric privacy regulation enforcement in EU member states and US state legislatures as inflection indicator for facial-recognition deployment scope restrictions.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Displaces on-premise architectures and enables predictive maintenance across distributed terminal fleets in China and Germany. |
| ADA Accessibility Certification | Secures procurement eligibility for US hospital networks and quick-service restaurant chains under Department of Justice enforcement. |
| Biometric Consent Infrastructure | Addresses GDPR and state-level privacy friction before facial-recognition capabilities trigger deployment restrictions. |
| Mobile Form Factor Development | Captures event venue and pop-up retail demand in Germany and the United States where fixed infrastructure is unavailable. |
| Hardware-as-a-Service Contracting | Expands addressable demand beyond enterprise buyers to mid-size retail chains previously excluded by upfront capital requirements. |
Research Approach
The analysis maps stationary kiosks, mobile kiosks, interactive terminals, and outdoor enclosures, each validated through procurement managers at hospital networks, quick-service restaurant operators, transit authority technology directors, and kiosk OEM product strategists. Primary interview findings triangulate against secondary sources including SAMR payment security filings, METI JIS standard documentation, EU Web Accessibility Directive implementation reports, and SEC 10-K disclosures from listed platform integrators. Bottom-up unit deployment estimates and top-down procurement budget aggregation cross-validate market sizing across the analysis window.
The forecast framework holds semiconductor supply availability and ADA enforcement intensity as fixed boundary conditions while varying municipal digitization spending rates and hardware-as-a-service adoption curves. Segmentation modeling spans hardware form factor, end-use environment, authentication technology, and application type, with CAGRs derived from deployment trajectory extrapolation and replacement cycle analysis. Industry-specific inputs include QSR wage pressure indices and China metro system capital expenditure disclosures.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by Taiwanese touch-module suppliers or South Korean compute vendors would shift outcomes beyond projected ranges. Macroeconomic deviation in Chinese municipal budgets, regulatory acceleration in biometric privacy frameworks, or technological disruption in edge AI processors would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Data Catalog Market
Digital Solutions
Digital Assistant Market
Digital Solutions
North America 3D Rendering Services Market
Digital Solutions
Global Sharing Economy Market
Digital Solutions
Interactive Projector Market
Digital Solutions
Web Based E-Detailing Market
Digital Solutions
Everything As a Service (Xaas) Market
Digital Solutions
Accounts Receivable Automation Market
Digital Solutions
APAC Smart Office Market
Digital Solutions
Cultivation Management Software Market
Digital Solutions
Drone Mapping Software for Agriculture Market
Digital Solutions
Voice Remote Control Market
Digital Solutions
Boat Navigation Software Market
Digital Solutions
Kubernetes Solutions Market
Digital Solutions
Global Smart Workplace Market
Digital Solutions
Core Graphics Market