
 Global Robot Kitchen Market | 2026-2036
Global Robot Kitchen Market Size, Share, and Industry Trends Forecast 2026-2036
Global Robot Kitchen Market Foresight
Cloud-native orchestration software is rewriting how robot kitchens coordinate multi-appliance workflows. Miso Robotics Inc. leverages computer vision to sustain fry-station automation in high-throughput environments. Moley Robotics anchors premium residential deployments with dexterous manipulator arms. Karakuri Ltd. competes on compact modular systems designed for space-constrained European food halls.
Robot kitchens integrate articulated manipulators, thermal sensors, and AI-driven recipe execution engines to prepare, cook, and plate food with minimal human intervention. Stainless steel food-contact surfaces, IP-rated enclosures, and HACCP-aligned temperature monitoring ensure compliance with commercial food safety protocols. Cooking robots dominate current installation value due to their complexity and replacement of skilled labor, while cleaning robots represent the fastest-expanding category as operators prioritize end-to-end automation. AI Integration commands the technology premium, though machine vision adoption accelerates as accuracy thresholds improve for ingredient identification and quality control.
The FDA governs food-contact materials and sanitation protocols for robot kitchen deployments in the United States, while the EU AI Act imposes risk-classification requirements on autonomous decision-making systems in European commercial kitchens. China's SAMR enforces GB standards for electrical safety and food hygiene that shape product certification requirements for manufacturers targeting domestic cloud kitchen chains. Stakeholders must monitor diverging regulatory timelines for AI transparency mandates and food safety automation standards across these jurisdictions to align R&D roadmaps with market access conditions.
Market Dynamics
Cloud kitchen operators are compressing deployment timelines for robotic food preparation systems as labor cost inflation and real estate scarcity force kitchen footprint minimization across dense urban corridors.
Growth Catalysts
- FDA Food-Contact Material Rules:Standardized stainless steel and polymer specifications reduce supplier qualification friction for robot kitchen manufacturers seeking US commercial deployment.
- Quick Service Restaurant Automation:Burger chains and fried-chicken operators deploy fry-station robots to offset wage pressure in high-turnover back-of-house environments.
- Computer Vision Integration:Machine learning models trained on ingredient recognition tasks enable autonomous quality control without human line supervision.
Market Restraints
- Articulated Manipulator Costs:Six-axis robotic arms with food-grade IP ratings command premium pricing that extends payback periods for independent restaurant operators.
- EU AI Act Risk Classification:Autonomous decision-making systems in European commercial kitchens face heightened transparency documentation requirements that slow product certification.
- Skilled Maintenance Scarcity:Field service technicians capable of diagnosing mechatronic faults in thermal-enclosed environments remain concentrated in Germany, the United States, and Japan.
Strategic Opportunities
- India Cloud Kitchen Expansion:FSSAI-aligned automation standards create a regulatory pathway for compact cooking robots in Bangalore and Mumbai delivery-only facilities.
- Cleaning Robot Category:End-to-end automation demand positions autonomous sanitation systems as the fastest-expanding installation segment behind cooking equipment.
- AI-Driven Recipe Execution:Convergence of thermal sensors and cloud-native orchestration enables dynamic menu adaptation without hardware reconfiguration.
Industry Challenges
- HACCP Temperature Monitoring Integration:Real-time data logging systems must interface with legacy kitchen management software that lacks standardized API architectures.
- Cross-Jurisdictional Certification Burden:Manufacturers targeting simultaneous FDA, EU AI Act, and China SAMR compliance face divergent documentation timelines that compress product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Robot Kitchen Market |
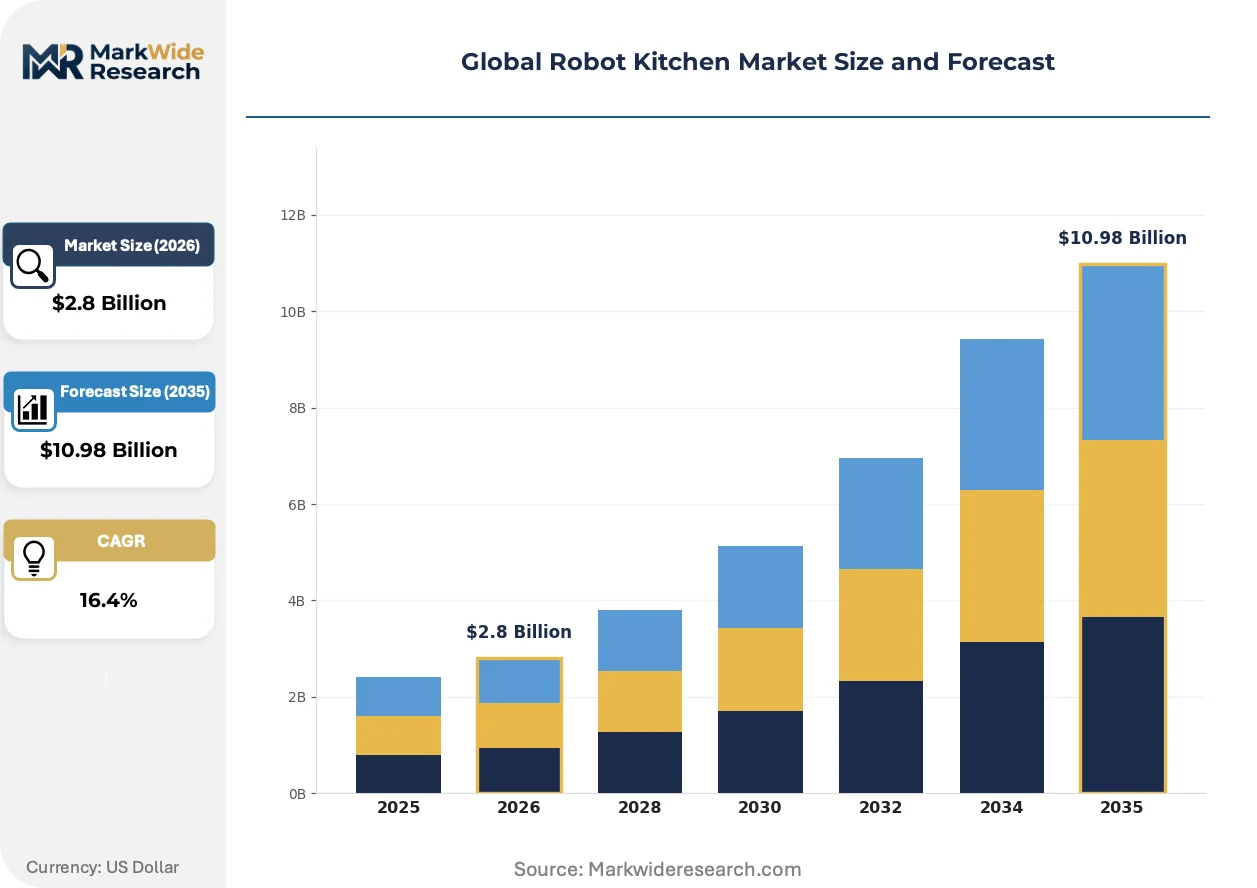
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Robot Type: Cooking Robots, Cutting Robots, Cleaning Robots, Serving Robots, Mixing Robots Technology: AI Integration, Machine Vision, Autonomous Navigation, Sensor Technology, Voice Recognition Application: Quick Service Restaurants, Institutional Catering, Food Trucks, Cafes, Corporate Canteens Customer Type: Food Service Chains, Independent Restaurants, Hospitality Providers, Event Caterers, Meal Kit Suppliers |
| Companies Covered | Connected Robotics Inc., Zimplistic Pte. Ltd., Moley Robotics, Chowbotics, Picnic Works Inc., Miso Robotics Inc., Karakuri Ltd., Nala Robotics Inc., Dexai Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Robot Kitchen Market Shifts & Advancements
Cloud-native orchestration platforms are redefining how distributed kitchen fleets coordinate multi-site robotic operations, compressing the gap between centralized menu engineering and localized execution.
Digital twin simulation is digitizing robot kitchen deployment planning by modeling thermal load profiles, workflow bottlenecks, and maintenance intervals before physical installation. Large cloud kitchen operators in the United States and China now require virtual commissioning as a procurement gate, reducing on-site integration failures and accelerating revenue recognition timelines for equipment vendors.
The EU AI Act imposes mandatory risk documentation on autonomous food preparation systems making unsupervised cooking decisions in European commercial environments. Kitchen operators in Germany and France must maintain algorithmic audit trails that explain temperature adjustments and ingredient substitutions, driving demand for interpretable machine learning architectures over black-box neural networks in EU-bound product lines.
Equipment-as-a-service contracting is displacing capital purchase models among mid-scale restaurant groups seeking to preserve liquidity for real estate expansion. Robot kitchen vendors in the United States now bundle preventive maintenance, software updates, and performance guarantees into per-meal pricing structures, with cloud kitchen aggregators in Los Angeles and New York representing the most concentrated adoption of this procurement shift.
Global Robot Kitchen Market Segmentation
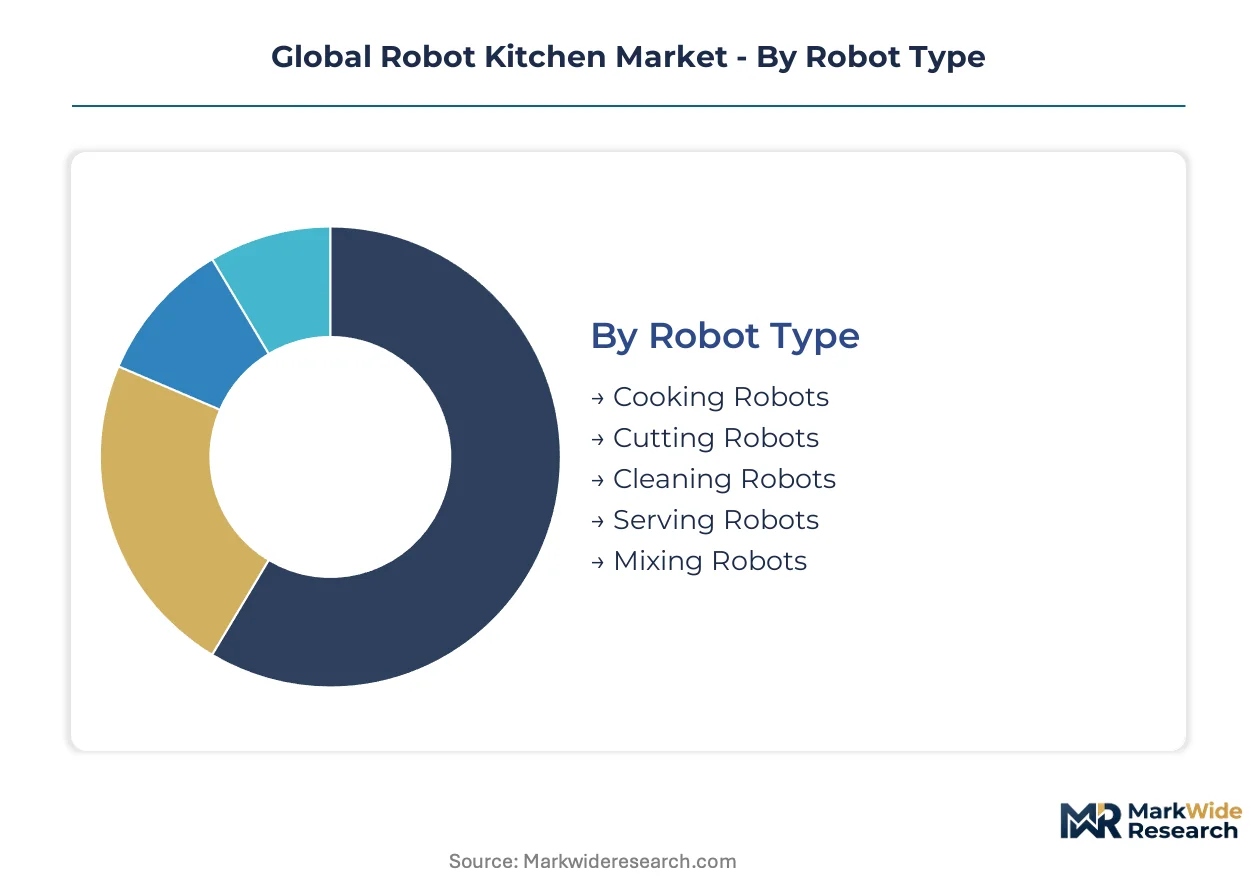
Robot kitchen procurement decisions diverge sharply across operational contexts. Equipment specification, technology bundling, and deployment scale vary by kitchen format, regulatory exposure, and labor substitution priorities.
Robot Type:
Commercial kitchens deploy differentiated mechanical systems based on task complexity and throughput requirements.
- Cooking Robots:Articulated manipulators with thermal sensors execute frying, grilling, and plating operations in high-volume environments. Quick service chains in the United States and Germany concentrate demand where wage pressure and turnover strain back-of-house operations.
- Cleaning Robots:Autonomous sanitation systems integrate HACCP-aligned temperature logging and chemical dosing for end-to-end workflow completion. Cloud kitchen operators in China prioritize this category to minimize human contact points and accelerate health inspection compliance.
- Cutting Robots:Precision blade systems with machine vision handle vegetable and protein portioning for standardized output.
- Serving Robots:Mobile platforms with tray stabilization navigate dining floors and food halls for front-of-house automation.
- Mixing Robots:Programmable stand-mixer derivatives execute dough and batter preparation for bakery and pasta applications.
Established volume favors cooking robots; emerging adoption favors cleaning robots.
Technology:
Technology stacking determines system autonomy levels and compliance documentation burdens.
- AI Integration:Recipe execution engines with dynamic thermal adjustment command pricing premiums across all deployment scales. European operators under EU AI Act jurisdiction must maintain algorithmic audit trails for unsupervised cooking decisions, complicating vendor selection.
- Machine Vision:Camera-based ingredient recognition enables quality control without line supervision. Deployment accelerates in the United States where FDA food-contact rules standardize sanitation protocols for vision-equipped stations.
- Autonomous Navigation:Lidar and SLAM-based positioning support serving robot mobility in cluttered kitchen environments.
- Sensor Technology:Temperature, pressure, and proximity arrays feed closed-loop control for safety-critical operations.
- Voice Recognition:Natural language interfaces allow kitchen staff to command equipment during high-stress service periods.
AI Integration captures margin concentration; machine vision gains share fastest among mid-scale operators.
Application:
Kitchen format dictates footprint constraints, throughput targets, and regulatory scrutiny intensity.
- Quick Service Restaurants:Fry-station and burger-line automation dominates capital allocation as labor costs compress margins in high-turnover environments. Chains across the United States, China, and Germany deploy coordinated robot fleets to standardize output across franchise networks.
- Institutional Catering:University and hospital kitchens with predictable menu cycles favor batch-cooking robots with recipe libraries. China's SAMR enforces GB electrical safety standards that shape certification requirements for equipment targeting this segment.
- Food Trucks:Compact modular systems with rapid deployment protocols serve mobile operators with severe space constraints.
- Cafes:Beverage-focused automation and pastry finishing robots address specialty coffee and bakery formats.
- Corporate Canteens:Multi-station orchestration platforms support high-volume, short-window service for office campus dining.
Quick service restaurants anchor current installation value; institutional catering presents the steepest expansion trajectory as public sector procurement normalizes automation.
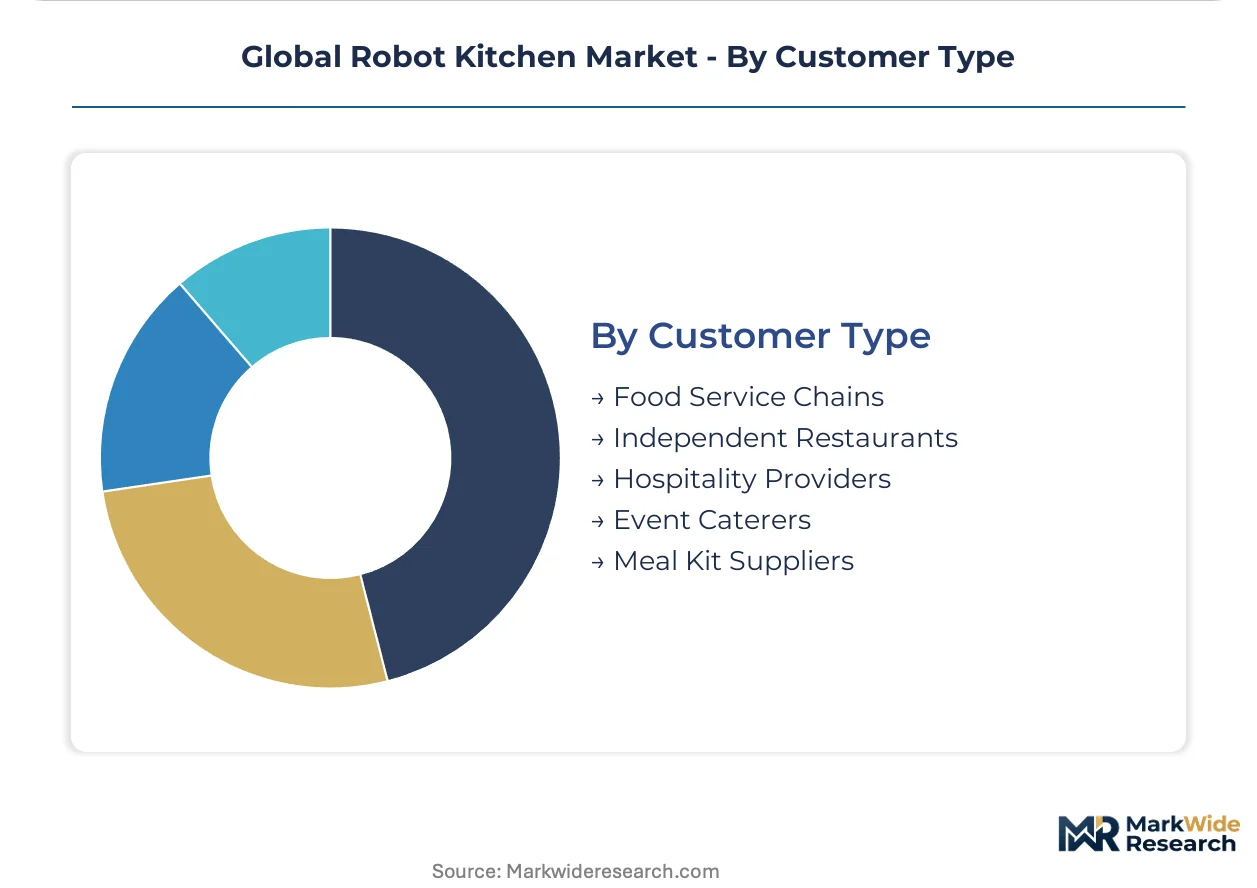
Customer Type:
Procurement sophistication and contracting flexibility vary by organizational scale and capital access.
- Food Service Chains:Centralized engineering teams negotiate equipment-as-a-service contracts with preventive maintenance bundling. Cloud kitchen aggregators in Los Angeles and New York drive adoption of per-meal pricing structures that preserve liquidity for real estate expansion.
- Independent Restaurants:Owner-operators face extended payback periods due to premium articulated manipulator pricing, constraining penetration outside high-labor-cost urban corridors.
- Hospitality Providers:Hotel and resort groups deploy serving robots for guest-facing differentiation and labor arbitrage in seasonal markets.
- Event Caterers:Mobile robot kitchens with rapid reconfiguration support temporary high-volume service at stadiums and convention centers.
- Meal Kit Suppliers:Portioning and packaging automation aligns with centralized production models for subscription food delivery.
Food service chains concentrate procurement volume; meal kit suppliers climb fastest as vertical integration into production displaces third-party commissary reliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German robot kitchen manufacturers export precision automation systems to cloud kitchen operators across the United States and China, establishing a transatlantic trade corridor in food-service robotics.
United States
Cloud kitchen aggregators in Los Angeles and New York compress deployment timelines for robotic fry stations as labor costs strain back-of-house margins. FDA food-contact material rules standardize stainless steel specifications, reducing supplier qualification friction for equipment vendors. Quick service chains across Texas and Florida deploy coordinated robot fleets to standardize output across franchise networks.
Germany
Industrial automation investment concentrates demand for articulated manipulators with IP-rated thermal enclosures in Baden-Württemberg and Bavaria. The EU AI Act imposes risk-classification documentation requirements on autonomous cooking systems, slowing product certification for vendors targeting European commercial kitchens. Stuttgart-based engineering clusters develop interpretable machine learning architectures to satisfy algorithmic audit trail mandates.
China
Cloud kitchen density in Shanghai and Beijing drives procurement of compact modular systems with rapid deployment protocols. SAMR enforces GB standards for electrical safety and food hygiene that shape certification requirements for domestic equipment manufacturers. Shenzhen automation suppliers integrate thermal sensors and AI-driven recipe execution engines for high-throughput delivery-only facilities.
India
FSSAI-aligned automation standards create regulatory pathways for cooking robots in Bangalore and Mumbai cloud kitchens. Mid-scale restaurant groups in Delhi-NCR and Hyderabad face extended payback periods due to premium manipulator pricing, constraining penetration outside high-labor-cost urban corridors. Meal kit suppliers in Maharashtra climb fastest as in-house production displaces third-party commissary reliance.
Japan
Precision manufacturing heritage supports development of dexterous manipulator arms for residential and premium commercial deployments. METI industrial policy channels R&D funding toward food-service automation as demographic contraction intensifies labor scarcity. Tokyo and Osaka engineering clusters specialize in sensor fusion technologies for closed-loop temperature control in safety-critical cooking operations.
Global Robot Kitchen Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tiers in the robot kitchen market. The vendor base stratifies between integrated solution providers bundling hardware, software, and maintenance, and component-focused suppliers of manipulators, sensors, or vision systems. Three archetypes dominate: cloud-native orchestration platforms, precision manipulator specialists, and compact modular system fabricators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as vendors seek to compress deployment timelines and secure cloud kitchen operator relationships.
Within the computer vision tier, Miso Robotics Inc. and Karakuri Ltd. occupy positions exemplifying divergent geographic and format strategies. Moley Robotics anchors the premium residential segment with dexterous arm architectures. Among Asia-Pacific-based developers, Connected Robotics Inc. and Nala Robotics Inc. sit within the compact system archetype targeting space-constrained urban food halls. Dexai Robotics and Picnic Works Inc. represent the cloud-native orchestration vector with software-first approaches to multi-appliance workflow coordination.
| Leading Market Players |
|---|
| Connected Robotics Inc. |
| Zimplistic Pte. Ltd. |
| Moley Robotics |
| Chowbotics |
| Picnic Works Inc. |
| Miso Robotics Inc. |
| Karakuri Ltd. |
| Nala Robotics Inc. |
| Dexai Robotics |
| Others |
Supply & Pricing Matrix
German precision-engineering clusters for articulated manipulators and thermal sensor arrays anchor upstream supply concentration, directing margin capture toward vendors bundling cloud-native orchestration software with hardware deployments.
Pricing Analysis
Current-generation AI-integrated cooking robots with EU AI Act-compliant audit trails command substantial premiums over prior-generation vision-only systems, while next-generation autonomous navigation serving robots remain pre-commercial. Three-tier pricing structure across premium, standard, and economy levels separates enterprise cloud kitchen fleets from mid-scale restaurant groups and independent operators. Price differentiation hinges on certification tier—FDA food-contact material compliance versus baseline CE marking—and after-sales service bundling including preventive maintenance. Pricing pressure stems from equipment-as-a-service contracting displacing capital purchases among liquidity-constrained buyers. Independent restaurants exhibit highest price sensitivity due to extended payback periods on six-axis manipulator investments.
Supply Chain Analysis
Contract manufacturing for robot kitchen systems concentrates with Foxconn and Jabil facilities in China, Flex operations in Mexico, and specialized EMS providers in Germany. Component sourcing draws from Japanese precision motor suppliers, South Korean machine vision module fabricators, and Chinese stainless steel enclosure manufacturers. Supply chain risk centers on single-source vulnerability for food-grade IP-rated thermal sensors qualified under FDA and SAMR protocols. Distribution runs through direct vendor relationships with cloud kitchen aggregators, equipment-as-a-service platforms, and regional distributor networks serving independent restaurant operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The robot kitchen market represents high-growth automation disruption justified by EU AI Act transparency mandates forcing algorithmic architecture redesigns across European deployments.
For Market Incumbents: Entrench cloud-native orchestration platform dominance through backward integration into sensor fusion hardware and preemptive EU AI Act certification investments. Lock in cloud kitchen aggregator relationships with per-meal pricing structures that raise switching costs. Counter emerging compact modular system vendors by expanding rapid-deployment service protocols for space-constrained urban food halls. For New Entrants and Emerging Players: Build out India cloud kitchen presence around FSSAI-aligned automation standards before incumbent certification documentation advantages solidify. Target Bangalore and Mumbai delivery-only facilities with compact cooking robots optimized for 24-hour operation cycles. Pursue white-label manufacturing partnerships with Shenzhen automation suppliers to compress hardware development timelines. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cloud-native orchestration platforms seeking exit liquidity as equipment-as-a-service contracting matures. Long-term viability favors vendors controlling both interpretable machine learning architectures and HACCP-aligned temperature monitoring IP. Monitor FDA food-contact material rule expansion timelines as inflection signal for US market access conditions.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Orchestration Platform Launch | Miso Robotics and Karakuri leverage centralized fleet management to compress multi-site deployment timelines for quick service chains. |
| EU AI Act Compliance Certification | Interpretable machine learning architectures from Stuttgart engineering clusters satisfy algorithmic audit trail mandates for German and French operators. |
| Equipment-as-a-Service Contracting Expansion | Per-meal pricing structures preserve liquidity for Los Angeles and New York cloud kitchen aggregators pursuing real estate expansion. |
| Compact Modular System Development | Space-constrained European food halls and China urban delivery facilities drive demand for rapid-deployment cooking robots. |
| Backward Integration into Sensor Hardware | Vertical control over thermal sensor arrays reduces supplier qualification friction under FDA food-contact material rules. |
Research Methodology
The analysis maps cooking robots, cleaning robots, cutting robots, serving robots, and mixing robots, each validated through chief technology officers at cloud kitchen operators, quick service restaurant engineering directors, food safety compliance officers, and equipment procurement managers at institutional catering facilities. Primary interview findings triangulate against FDA 510(k) food-contact material filings, SAMR GB standard certification databases, EU AI Act implementation guidance documents, and cloud kitchen operator capex disclosures. Bottom-up installation volume estimates reconcile with top-down market value projections across vendor revenue reporting.
Assumptions held fixed include current regulatory enforcement intensity for FDA, EU AI Act, and SAMR compliance; labor cost inflation trajectories in United States, China, and Germany; and cloud kitchen real estate expansion rates in dense urban corridors. Variable conditions span AI transparency mandate timeline acceleration, equipment-as-a-service contracting penetration rates, and interpretable machine learning architecture development costs. Segmentation modeling covers robot type, technology stack, application format, and customer scale across the projection horizon. CAGRs derive from unit economics analysis of payback periods and replacement cycle frequencies.
Stress conditions across EU AI Act risk classification escalations, stainless steel commodity price volatility, and skilled maintenance technician availability constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factor sensitivities. Quarterly review of FDA food-contact material rule amendments, SAMR GB standard updates, and cloud kitchen operator bankruptcy filings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Singapore Cloud Robotics Market
Robotics and Automation
Disinfectant Robot Market
Robotics and Automation
North America AUV and ROV Market
Robotics and Automation
Global All Terrain Robots Market
Robotics and Automation
Smart Personal Assistance Devices Market
Robotics and Automation
United Kingdom Cloud Robotics Market
Robotics and Automation
Robotic Air Purifier Market
Robotics and Automation
Autonomous Navigation Robots Market
Robotics and Automation
Robot Coffee Kiosk Market
Robotics and Automation
Global Adaptive Robot Market
Robotics and Automation
Robotic Desktop Automation (RDA) Market
Robotics and Automation
Asia Pacific Industrial Robots Market
Robotics and Automation
Asrs and Ruos Market
Robotics and Automation
Europe Agricultural Robots and Mechatronics Market
Robotics and Automation
Bionic Glove's Market
Robotics and Automation
Robotics in Shipbuilding Market