
 Web Based E-Detailing Market | 2026-2036
Web Based E-Detailing Market Size, Share, and Industry Trends Forecast 2026-2036
Web Based E-Detailing Market Outlook
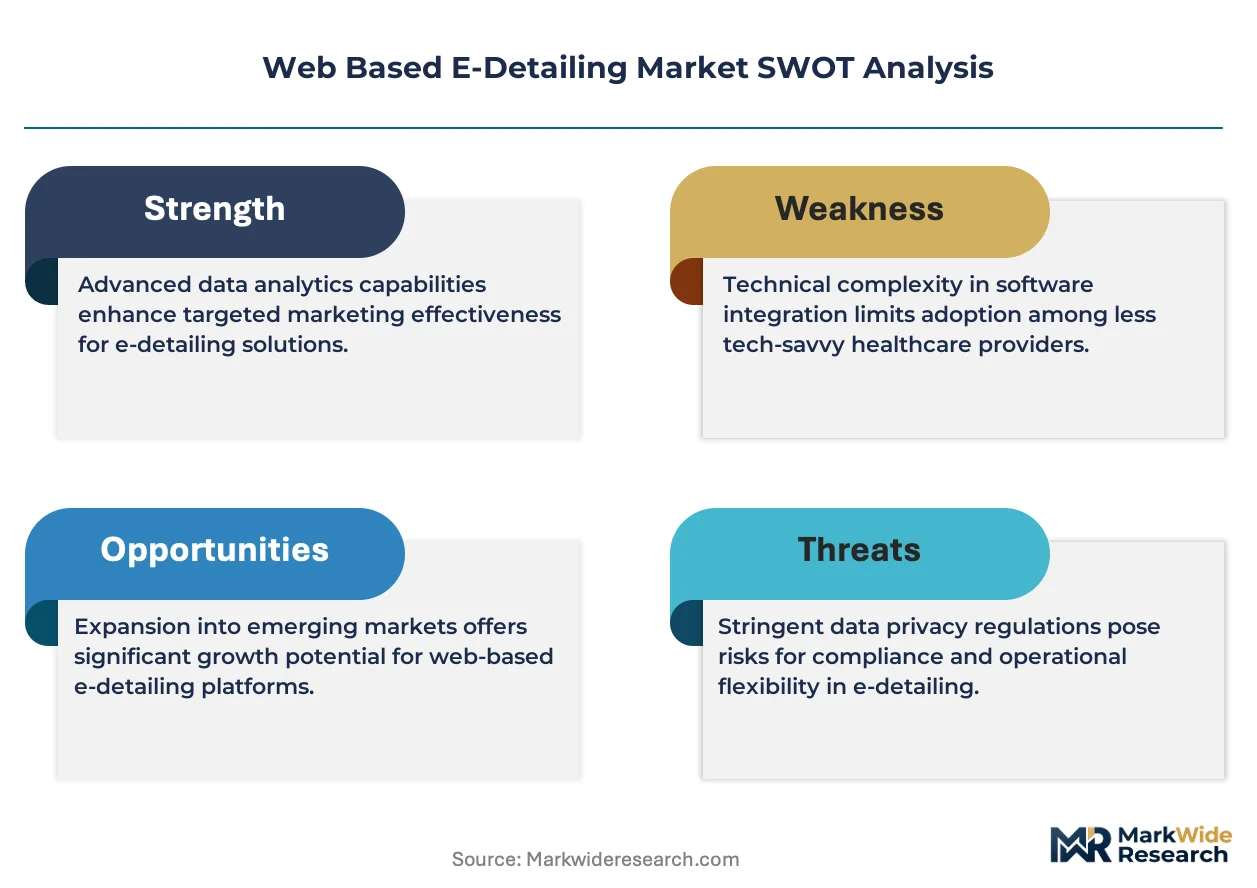
GDPR is repositioning the cost-of-entry calculus for web-based e-detailing platforms serving European healthcare professionals, forcing vendors to rebuild data architectures around consent management and cross-border transfer protocols. Veeva Systems Inc. anchors its competitive position through deep vertical integration into life sciences CRM workflows. IQVIA Holdings Inc. leverages its real-world data assets to differentiate physician targeting algorithms. Adobe Inc. competes on creative cloud infrastructure that powers interactive content production at pharmaceutical scale.
Web-based e-detailing denotes a digital pharmaceutical sales channel delivering interactive product presentations, clinical evidence, and promotional content to healthcare professionals through browser-based interfaces rather than face-to-face representative visits. These platforms typically integrate video streaming, real-time analytics dashboards, and closed-loop marketing automation to track physician engagement duration, content preferences, and prescribing intent signals. The delivery model dimension shows SaaS architectures capturing the majority of new deployments as biotech firms prioritize subscription flexibility over capital-intensive on-premises installations. Content format segmentation reveals video and interactive presentations commanding premium positioning against static PDF brochures, reflecting physician preference for immersive clinical storytelling over document downloads.
The FDA regulates promotional content accuracy and adverse event reporting obligations for e-detailing platforms targeting U.S. physicians, while EMA's digital communication guidelines shape European deployment standards. HIPAA and GDPR compliance costs now function as structural barriers that favor established platforms with dedicated legal-technical teams over emerging entrants. Stakeholders must monitor evolving regulator interpretations of AI-generated content in physician-facing channels as machine learning personalizes e-detailing recommendations.
Market Dynamics
Physician access restrictions in major markets are compressing traditional pharmaceutical sales channels, forcing vendors to re-architect engagement models around asynchronous digital touchpoints and consent-based data flows.
Growth Catalysts
- SaaS Delivery Models:Biotech firms prioritize subscription flexibility over capital-intensive on-premises installations, reducing deployment friction for emerging platforms.
- FDA Digital Guidance Evolution:Clarified frameworks for off-label communication and adverse event reporting in virtual channels reduce compliance ambiguity for U.S. deployments.
- Video-First Content Preferences:Healthcare professionals demonstrate measurable engagement preference for immersive clinical storytelling formats over static document downloads.
Market Restraints
- GDPR Compliance Architecture:European data protection mandates force costly rebuilds of consent management and cross-border transfer protocols for platforms serving German and French physicians.
- HIPAA Technical Safeguards:U.S. healthcare privacy requirements impose structural barriers favoring established vendors with dedicated legal-technical teams over emerging entrants.
- Static PDF Legacy Inertia:Budget-constrained pharmaceutical marketing departments resist migration from low-cost brochure formats despite inferior engagement metrics.
Strategic Opportunities
- Japanese Digital Infrastructure Maturity:METI-supported healthcare digitization initiatives create favorable deployment conditions for platforms targeting PMDA-regulated therapeutic areas.
- AI-Generated Content Personalization:Machine learning recommendation engines enable real-time physician preference adaptation, though regulator interpretations remain unresolved.
- Closed-Loop Marketing Automation:Integration of engagement duration tracking with prescribing intent signals creates measurable ROI attribution for pharmaceutical procurement teams.
Industry Challenges
- Cross-Functional Talent Scarcity:Platforms require rare combinations of clinical content expertise, regulatory compliance knowledge, and cloud architecture skills.
- Legacy CRM Integration Complexity:Pharmaceutical IT environments demand costly middleware development to connect browser-based interfaces with entrenched sales force automation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Web Based E-Detailing Market |
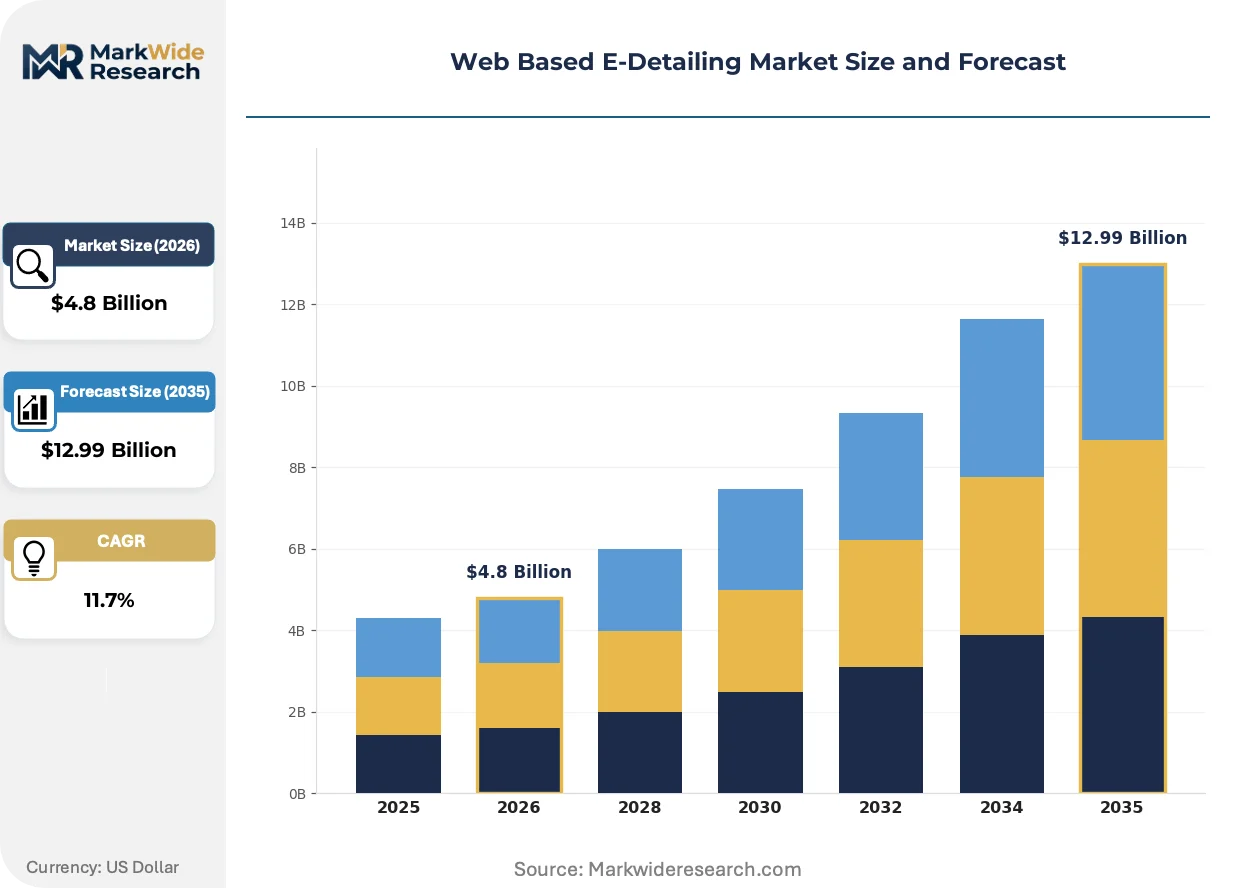
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Client Type: Pharmaceutical Companies, Biotech Firms, Medical Device Manufacturers, Cosmeceuticals Delivery Model: SaaS, On-Premises, Cloud-Based, Hybrid Device Type: Mobile Devices, Tablets, Laptops, Desktops Content Format: Video, Interactive Presentations, PDF Brochures, Infographics |
| Companies Covered | Veeva Systems Inc., IQVIA Holdings Inc., Adobe Inc., Cisco Systems, Inc., ON24, Inc., Oracle, Salesforce, P360 Management Solutions, Aktana Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Web Based E-Detailing Market Strategic Shifts
Interactive content architectures are displacing static promotional materials as the primary engagement mechanism between pharmaceutical manufacturers and healthcare professionals across developed markets.
Real-time analytics dashboards are unifying physician behavioral signals with clinical content consumption patterns. Mid-tier biotech firms deploy these tools within eighteen-month implementation cycles. The technology is unifying previously siloed marketing and medical affairs functions into single orchestration layers.
EMA's digital communication guidelines are reshaping European deployment standards for promotional content accuracy. The framework mandates explicit adverse event capture mechanisms within virtual engagement channels. German and Swiss affiliates face the steepest adaptation requirements as national implementations diverge from baseline Brussels guidance.
Healthcare professional preference for on-demand content access is fragmenting synchronous meeting schedules. Self-service portal models displace representative-driven appointment calendars in therapeutic areas with well-established safety profiles. Japanese physician associations report the highest adoption velocity for asynchronous clinical review formats.
Web Based E-Detailing Market Segmentation
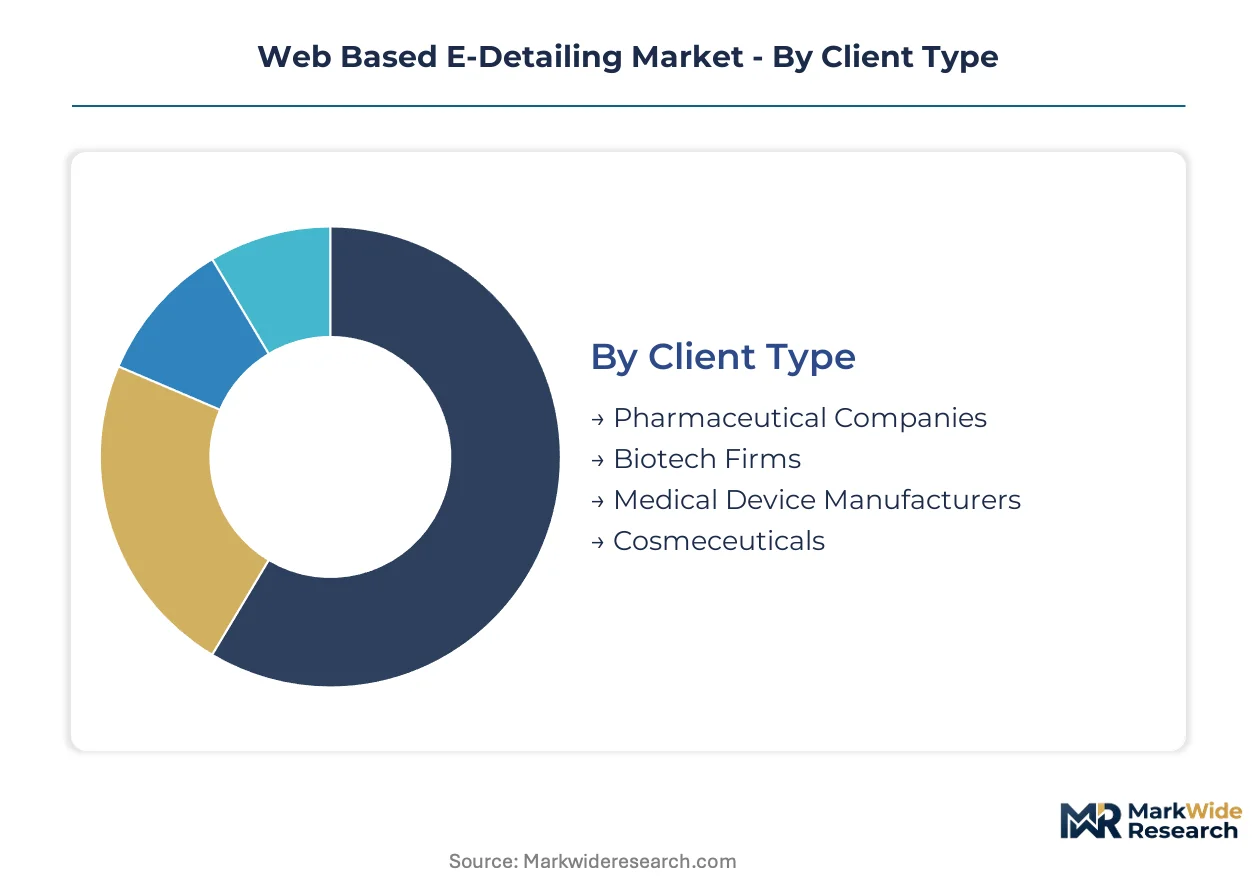
Web-based e-detailing platforms serve heterogeneous client needs across regulatory environments, technical infrastructures, and physician engagement preferences. Segmentation reveals where capital deployment concentrates and which technical architectures capture procurement priority from pharmaceutical commercial operations.
Client Type:
Capital intensity varies sharply across client categories, with enterprise-scale deployments demanding dedicated compliance infrastructure and mid-market segments prioritizing configurable subscription tiers.
- Pharmaceutical Companies:These organizations operate the most complex e-detailing stacks, integrating multi-therapeutic area content libraries with global adverse event reporting workflows. Demand concentrates among top-20 manufacturers seeking FDA-compliant virtual engagement channels for U.S. physician access restrictions.
- Biotech Firms:Emerging therapeutic developers favor modular SaaS architectures that scale from single-product launches to portfolio expansion without on-premises hardware commitments. Their procurement prioritizes rapid deployment timelines over deep customization.
- Medical Device Manufacturers:These clients require specialized content formats supporting procedural training and implant technique demonstration alongside traditional promotional messaging.
- Cosmeceuticals:Aesthetic and dermatology-focused brands deploy lighter-weight platforms with stronger visual storytelling capabilities and reduced clinical data integration requirements.
Most installed capacity flows through Pharmaceutical Companies. Expansion is steepest in Biotech Firms.
Delivery Model:
Technical architecture choices determine ongoing operational expenditure profiles and regulatory audit complexity for life sciences IT organizations.
- SaaS:Browser-accessible platforms with vendor-managed infrastructure dominate new procurement decisions. Biotech procurement teams value subscription flexibility and rapid feature iteration without capital allocation committees.
- On-Premises:Legacy installations persist among manufacturers with stringent data residency mandates or existing sunk investments in private data center capacity.
- Cloud-Based:These deployments offer intermediate control, with pharmaceutical IT teams managing application configuration while outsourcing underlying compute and storage to hyperscale providers.
- Hybrid:Split architectures segregate sensitive physician identity data on-premises while pushing content delivery and analytics processing to cloud infrastructure.
SaaS architectures carry the lowest upfront capital burden. Hybrid models are gaining share fastest among European manufacturers navigating GDPR cross-border transfer constraints.
Device Type:
Endpoint diversity shapes content production requirements and user experience design investments for platform developers.
- Mobile Devices:Smartphone-optimized interfaces require responsive design frameworks and compressed video delivery protocols. Japanese physician associations report highest mobile-first engagement rates.
- Tablets:Touch-optimized form factors support representative-guided presentations in clinical waiting areas where laptops prove cumbersome.
- Laptops:Full-featured browser experiences remain standard for asynchronous physician self-service and medical affairs detail sessions.
- Desktops:Hospital workstation deployments dominate institutional purchasing decisions with strict IT security policies limiting portable device connectivity.
Tablet installations lead in representative-mediated settings. Mobile Devices show the steepest expansion trajectory as asynchronous engagement models proliferate.
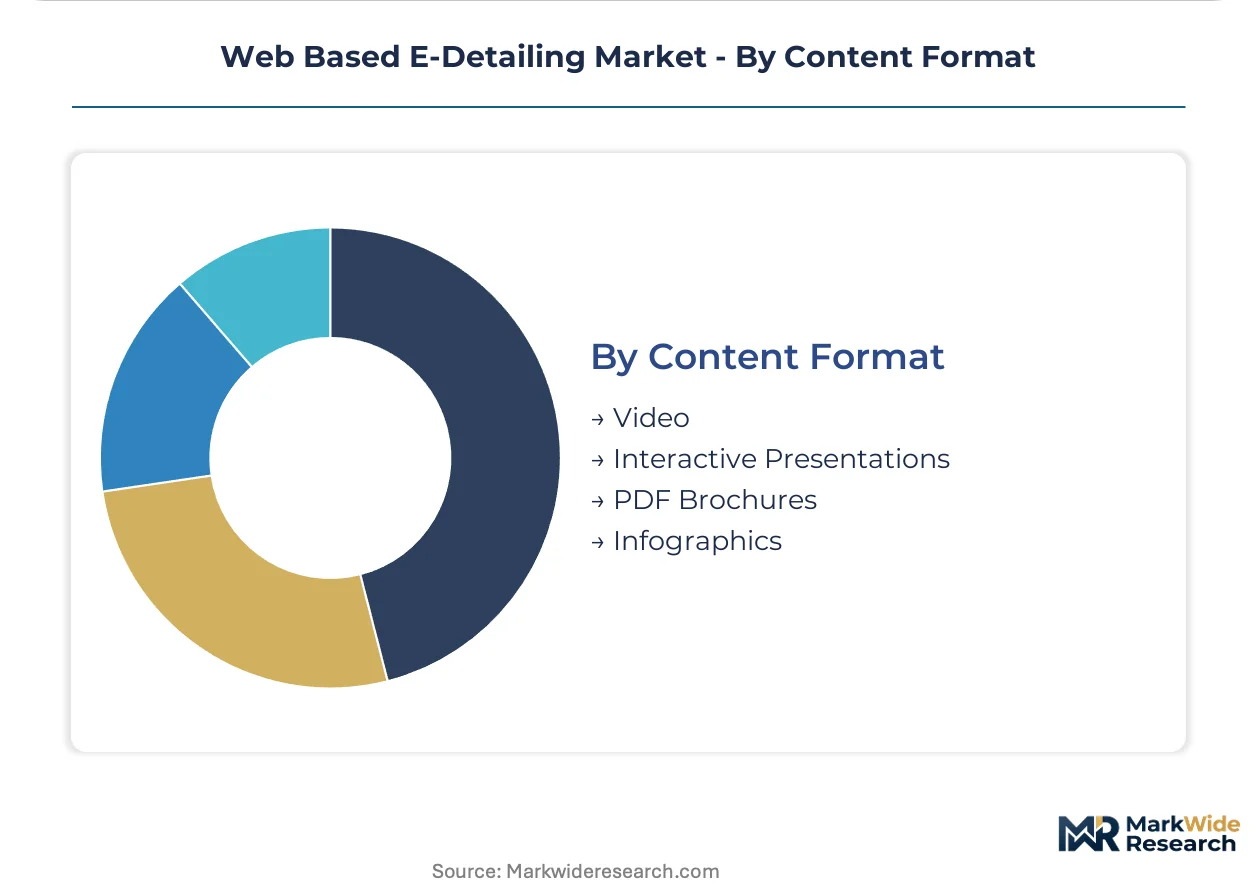
Content Format:
Production investment and engagement analytics capabilities diverge substantially across format categories.
- Video:Cinematic clinical storytelling with animated mechanism-of-action sequences commands premium production budgets. German and U.S. physicians demonstrate measurably longer session durations with video-first platforms.
- Interactive Presentations:Branching narrative structures allow physicians to self-direct through clinical data hierarchies. These formats require specialized authoring tools and real-time analytics integration.
- PDF Brochures:Static document formats persist in budget-constrained therapeutic areas and legacy compliance environments with limited multimedia infrastructure.
- Infographics:Visual data summaries support rapid clinical evidence comprehension but lack the engagement depth of interactive or video alternatives.
Video content absorbs the largest production capital allocations. Interactive Presentations are expanding most quickly as personalization engines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The web-based e-detailing industry traces its commercial roots to early digital physician engagement experiments in the United States during the late 1990s, with European and Japanese markets subsequently adapting these models to local regulatory environments.
United States
Pharmaceutical manufacturers face tightening physician access restrictions that compress traditional sales channels and accelerate virtual engagement adoption. FDA digital guidance evolution clarifies off-label communication frameworks and adverse event reporting obligations for virtual channels. The Boston-Cambridge biotech corridor and New Jersey's pharmaceutical corridor host dense concentrations of platform procurement decision-makers.
Germany
Healthcare professional demand concentrates on compliant virtual engagement channels as statutory health insurance cost pressures limit representative face-time. GDPR mandates force costly rebuilds of consent management and cross-border data transfer protocols for platforms serving German physicians. The Frankfurt-Düsseldorf pharmaceutical cluster drives enterprise-scale e-detailing procurement for European affiliates.
Japan
Physician associations report the highest adoption velocity for asynchronous clinical review formats among developed markets. METI-supported healthcare digitization initiatives create favorable deployment conditions for platforms targeting PMDA-regulated therapeutic areas. The Tokyo-Osaka corridor anchors domestic platform development and pharmaceutical headquarters procurement decisions.
Switzerland
Global pharmaceutical headquarters concentration generates premium demand for multi-jurisdictional compliance architectures. Swissmedic and EMA dual regulatory alignment requirements shape platform specification for European launches. Basel and Zurich host procurement teams managing cross-border e-detailing standardization across affiliate networks.
United Kingdom
NHS digital transformation programs accelerate physician comfort with browser-based clinical content consumption. MHRA promotional content guidelines establish baseline compliance requirements for virtual engagement channels targeting UK prescribers. The London-Oxford-Cambridge life sciences triangle concentrates biotech platform adoption and medical affairs digital investment.
Web Based E-Detailing Market Competitive Environment
The competitive structure tilts toward vertically integrated life sciences specialists with embedded regulatory compliance capabilities. Tier-one positions concentrate among platforms with dedicated legal-technical teams capable of navigating HIPAA and GDPR audit complexity. Three archetypes dominate: CRM-native suites with medical affairs integration, data-centric targeting platforms leveraging real-world evidence assets, and creative infrastructure providers powering interactive content production. Consolidation pressure favors acquisition of niche compliance modules by established vendors, while partnership strategies dominate mid-market expansion efforts.
Within the life sciences-native tier, Veeva Systems Inc. and IQVIA Holdings Inc. exemplify divergent strategic positions—one anchored in CRM workflow verticalization, the other in real-world data asset monetization for physician targeting. Adobe Inc. occupies a distinct creative-infrastructure position, supplying rendering engines and authoring tools that power pharmaceutical-scale interactive content production rather than delivering end-to-end engagement platforms.
| Leading Market Players |
|---|
| Veeva Systems Inc. |
| IQVIA Holdings Inc. |
| Adobe Inc. |
| Cisco Systems, Inc. |
| ON24, Inc. |
| Oracle |
| Salesforce |
| P360 Management Solutions |
| Aktana Inc. |
| Others |
Value Chain & Pricing Dynamics
SaaS delivery model migration simultaneously compresses upfront platform economics and concentrates supplier power among hyperscale cloud providers serving life sciences workloads. This shift rewards vendors with existing HIPAA and GDPR compliance architectures while forcing price discipline on emerging entrants lacking dedicated legal-technical teams.
Pricing Analysis
Platform vendors unbundle compliance infrastructure from core content delivery, creating distinct pricing tiers for GDPR-ready deployments versus standard configurations. Three-tier pricing structure across premium, standard, and economy levels separates enterprise pharmaceutical contracts with dedicated adverse event reporting modules from mid-market biotech subscriptions. Cost compression in economy tiers is intensifying because budget-constrained marketing departments resist migration from static PDF formats despite inferior engagement metrics. Biotech procurement teams demonstrate highest price sensitivity due to single-product launch economics, while top-20 pharmaceutical manufacturers prioritize compliance certification over per-seat cost.
Supply Chain Analysis
FDA and EMA qualification requirements gate platform vendor participation, filtering supply toward established players with dedicated regulatory affairs capabilities. Cloud infrastructure concentrates in the United States, Ireland, and Germany where hyperscale providers maintain healthcare-compliant data center footprints. Platform development draws from specialized talent pools combining clinical content expertise, regulatory compliance knowledge, and browser-based architecture skills. Single-source vulnerability runs through AWS and Azure healthcare sovereign cloud instances serving European deployments. Distribution runs through direct enterprise sales teams for pharmaceutical accounts and self-service portals for emerging biotech procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Web-based e-detailing has matured into a late-cycle quality market where physician preference for video-first immersive formats favors vendors with premium interactive content production capabilities.
For Market Incumbents: Acquire specialized consent management modules to neutralize GDPR compliance differentiation among European competitors. Consolidate around closed-loop marketing automation capabilities that unify engagement duration tracking with prescribing intent signals. Emerging AI-generated content personalization engines threaten established creative production workflows.
For New Entrants and Emerging Players: The mid-tier pricing gap between Veeva Systems enterprise contracts and economy PDF-legacy platforms offers white-space for modular SaaS architectures targeting single-product biotech launches. Focus initial penetration on Japanese physician associations reporting highest adoption velocity for asynchronous clinical review formats. Deploy rapid eighteen-month implementation cycles as competitive wedge against legacy CRM integration complexity.
For Investors and Strategic Acquirers: Valuations sit cheapest among compliance-specialist vendors with dedicated legal-technical teams capable of navigating HIPAA audit complexity. Long-term viability over the next decade hinges on AI-generated content regulatory clarity and physician preference fragmentation toward self-service portals. Monitor FDA guidance evolution on off-label communication in virtual channels as inflection indicator for platform differentiation value.
| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Module Acquisition | Neutralizes GDPR differentiation cost among vendors serving German and French physicians. |
| Closed-Loop Marketing Integration | Creates measurable ROI attribution linking Veeva CRM engagement data to prescribing signals. |
| AI Content Personalization Engine | Enables real-time physician preference adaptation pending FDA regulatory interpretation clarity. |
| Japanese Market Entry Partnership | Accelerates deployment through METI-supported healthcare digitization infrastructure channels. |
| Hybrid Cloud Architecture Deployment | Segregates sensitive physician identity data on-premises while pushing analytics to cloud infrastructure. |
Study Parameters
Coverage spans the United States, Germany, Japan, Switzerland, and the United Kingdom, with primary inputs from each market's pharmaceutical commercial operations. The analysis combines structured interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers alongside secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up platform deployment counts triangulate against top-down pharmaceutical marketing spend allocations.
Granularity-level framing models client type, delivery model, device type, and content format dimensions at the country-regulatory cluster level. CAGRs derive from physician access restriction tightening trajectories, SaaS subscription growth curves, and video content production capacity expansion across the projection horizon. Forecast inputs incorporate METI digitization initiative timelines, FDA digital guidance evolution, and GDPR enforcement pattern shifts affecting cross-border data transfer economics.
Caveats apply where FDA AI-generated content guidance, EMA adverse event capture mandate interpretations, or PMDA asynchronous engagement approvals could materially shift the outlook. Forecasts reflect assumptions around physician preference stabilization and regulatory audit standardization without anticipating disruptive platform technology substitution. A model refresh is warranted upon material change in FDA off-label communication frameworks or hyperscale cloud provider healthcare sovereign cloud pricing restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Digital Art Software Market
Digital Solutions
Digital BSS Market
Digital Solutions
Contact Tracing Application Market
Digital Solutions
Physical-Digital Integration Market
Digital Solutions
Healthcare Computerized Maintenance Management System Market
Digital Solutions
Europe Warranty Management System Market
Digital Solutions
US Digital Market
Digital Solutions
Virtual Workspace Solutions Market
Digital Solutions
Function As a Service (Faas) Market
Digital Solutions
Product Data Management Market
Digital Solutions
Digital Twin in Construction Market
Digital Solutions
Image Recognition in Retail Market
Digital Solutions
Hybrid Events Software Market
Digital Solutions
Digital Onboarding Market
Digital Solutions
Asia-Pacific Route Optimization Software Market
Digital Solutions
Real-Time Temperature and Location Monitoring Platforms for Cold Chain Market