
 Cultivation Management Software Market | 2026-2036
Cultivation Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Cultivation Management Software Market Outlook
Cloud infrastructure is hardening as the dominant delivery substrate for cultivation management platforms, displacing legacy on-premise installations that carried heavy server maintenance burdens. Deere & Company leverages its equipment-installed base to bundle software subscriptions with precision agriculture hardware. AGRIVI anchors its competitive position through crop-specific compliance modules tailored to regional pesticide registries. Trimble Inc. extends its GNSS expertise into field-level task management for row-crop operators.
Cultivation management software denotes digital platforms that orchestrate crop planning, resource scheduling, environmental monitoring, and regulatory documentation across controlled and open-field agricultural operations. These systems typically integrate sensor telemetry, prescription mapping algorithms, and batch-level traceability databases to optimize yield consistency and certify chain-of-custody claims. Cloud-based deployment represents the fastest-expanding delivery mode as operators prioritize remote access and API interoperability with third-party climate control hardware. Commercial farms command the deepest margin pools among end-user categories, driven by enterprise-scale licensing and multi-year service contracts. IoT Integration functions as the most technically demanding technology layer, requiring real-time edge computing pipelines to process sub-minute sensor intervals from distributed greenhouse networks.
The EPA governs pesticide application logging requirements that cultivation software must automate for audit readiness, while the USDA enforces organic certification traceability standards that shape platform data architecture. State agriculture departments in California, Florida, and Washington impose additional batch-tracking mandates that filter software procurement specifications. Stakeholders must monitor how emerging federal climate-smart agriculture incentives reshape subsidy eligibility criteria and the corresponding documentation burdens placed on software vendors.
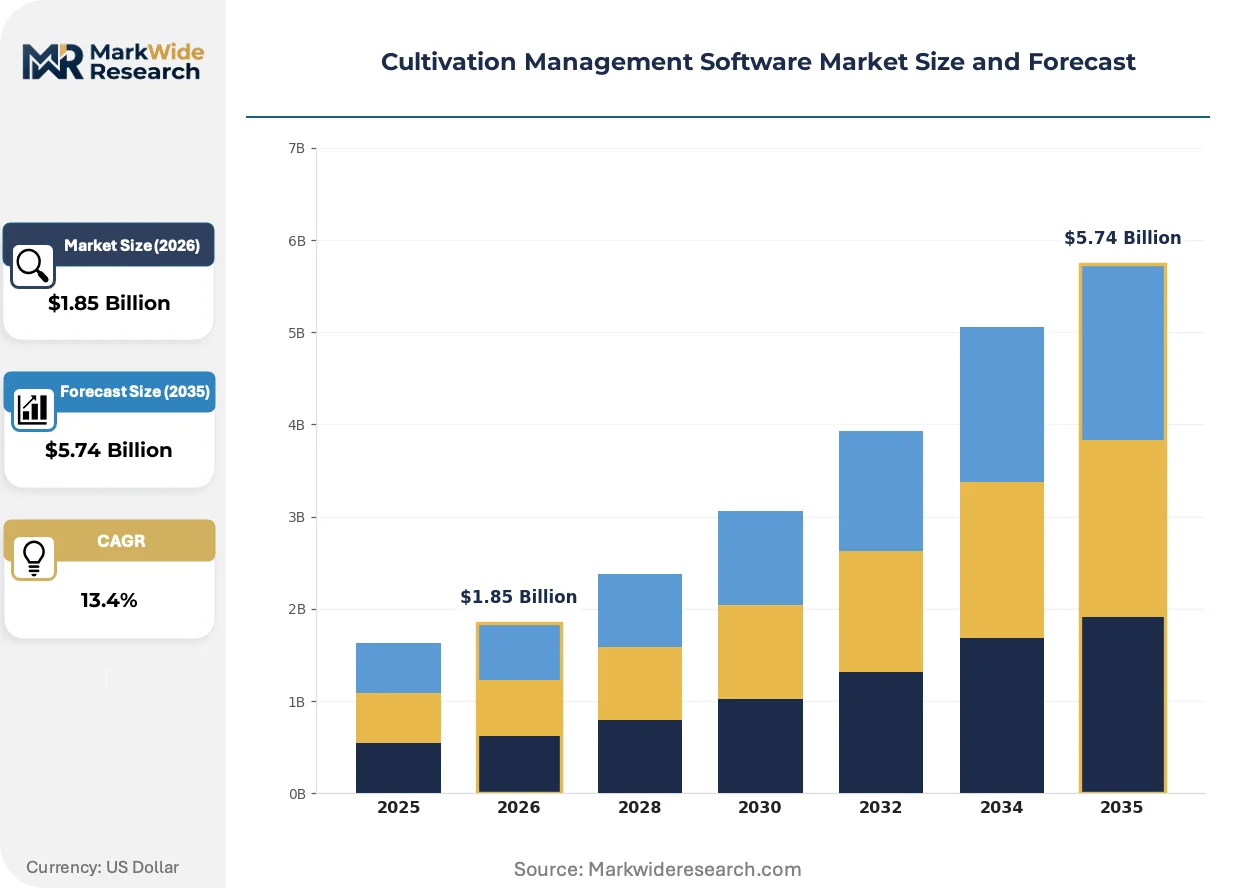
Market Dynamics
Cloud-native architecture is compressing deployment cycles for cultivation management platforms as commercial farms abandon server-heavy on-premise systems. The shift forces vendors to restructure pricing around API call volumes rather than perpetual licenses.
Growth Catalysts
- EPA pesticide logging mandates:Automated audit trails for chemical application records now drive software procurement specifications among row-crop operators in the US Corn Belt.
- Greenhouse sensor density:Sub-minute telemetry intervals from Dutch glasshouse networks create demand for edge-computing pipelines that cultivation platforms must integrate.
- California water accounting:State-level groundwater sustainability agencies require volumetric irrigation tracking that software vendors embed as compliance modules.
Market Restraints
- Legacy data silos:Proprietary formats from decade-old farm management systems block clean API handoffs to modern cloud platforms.
- Connectivity dead zones:Cellular gaps across Nebraska and Kansas plains degrade real-time synchronization for field-level task management.
- Specialized agronomist scarcity:Crop-specific calibration of prescription algorithms requires expertise concentrated in university extension programs.
Strategic Opportunities
- Carbon credit verification:USDA climate-smart agriculture incentives reward documented input reductions that cultivation software can automate for offset markets.
- Smallholder bundling:Cooperative purchasing structures in Brazil's Mato Grosso soy belt create volume channels for lightweight SaaS tiers.
- Computer vision convergence:Drone-mounted multispectral imagery fused with growth-stage databases enables automated pest pressure alerts without manual scouting.
Industry Challenges
- Interoperability certification lag:Missing ISO standards for sensor data formats force vendors into costly bilateral integration agreements.
- Seasonal cash flow mismatch:Annual harvest payment cycles clash with monthly SaaS billing, requiring vendor financing programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cultivation Management Software Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.74 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premise, Cloud-Based, Mobile Apps, Hybrid Solutions End User: Greenhouses, Nurseries, Commercial Farms, Research Institutions Technology: IoT Integration, Artificial Intelligence, Data Analytics, Blockchain Deployment: Public Cloud, Private Cloud, Multi-Tenant, Single-Tenant |
| Companies Covered | Trimble Inc., Deere & Company, Granular Inc., AGRIVI, Topcon Corporation, Raven Industries, AGCO Corporation, Conservis, Ag Leader Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cultivation Management Software Market Strategic Shifts
Artificial intelligence is penetrating cultivation workflows through predictive yield modeling and autonomous environmental adjustments. Vendors race to embed machine learning without inflating per-acre pricing beyond mid-size operator tolerance.
Digital twin architecture is rewriting how greenhouse operators simulate crop responses before committing to climate setpoint changes. Large-scale tomato and pepper producers in the Netherlands deploy these virtual replicas to compress trial cycles from months to days. The technology is compressing R&D timelines for varietal adaptation and forcing seed companies to share phenotypic data with software partners.
EU Green Deal Farm-to-Fork targets are mandating 50% pesticide reduction benchmarks that reshape data architecture priorities. Cultivation platforms must now track untreated buffer zones and biological control release schedules with the same granularity as chemical applications. Specialty crop exporters in Spain and Italy face the tightest compliance windows as import markets harden residue tolerance thresholds.
Subscription unbundling is fragmenting how commercial farms acquire cultivation capabilities. Operators in California's Central Valley now procure sensing hardware, analytics layers, and compliance modules from separate vendors rather than accepting monolithic suites. This pattern concentrates integration burden on internal IT staff and creates openings for middleware specialists bridging incompatible cloud services.
Cultivation Management Software Market Segmentation
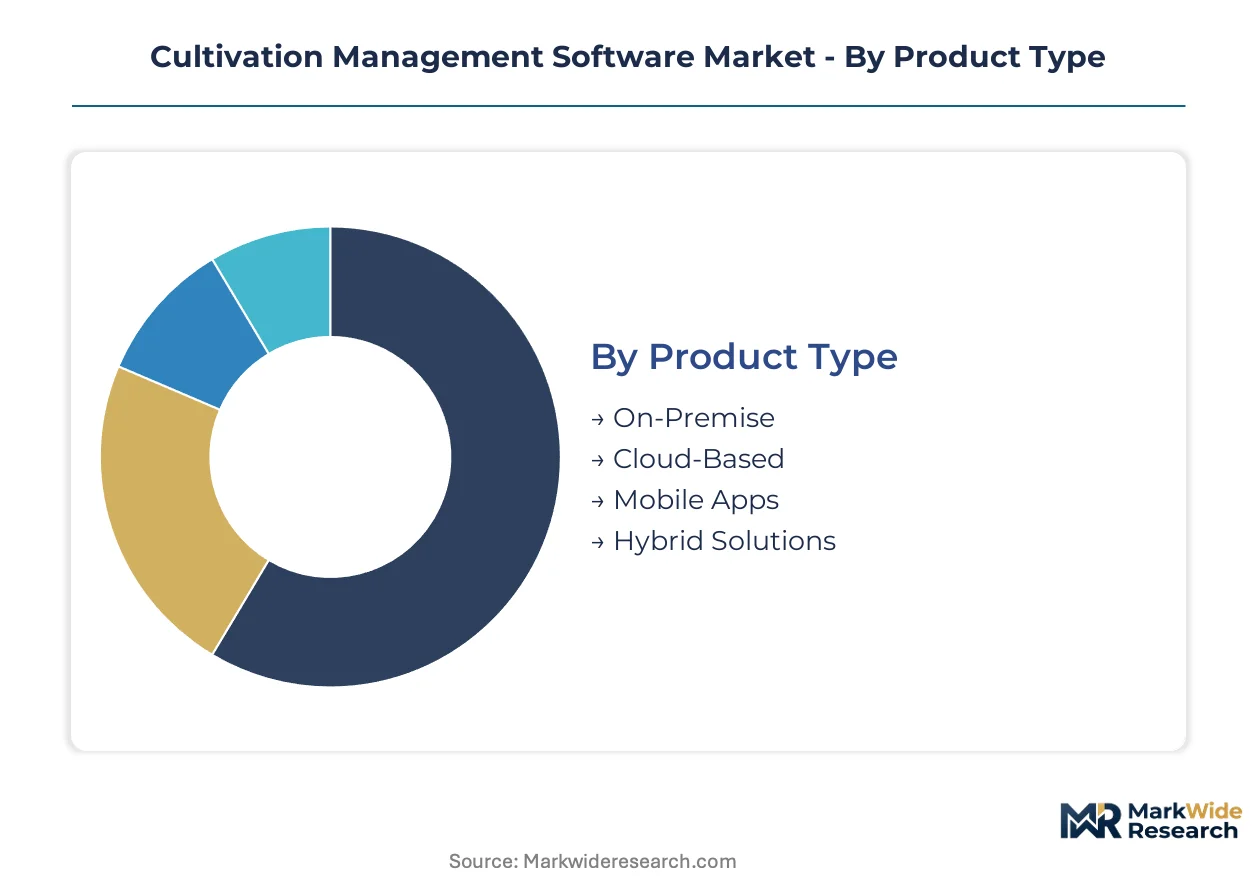
Cultivation management software segments diverge sharply in compliance architecture. EPA audit-readiness requirements favor cloud-native platforms with automated pesticide logging, while USDA organic certification drives demand for blockchain-anchored traceability chains.
Product Type:
Certification burdens fall heaviest on segments handling restricted-use pesticide records and organic chain-of-custody documentation. EPA mandates for chemical application audit trails shape procurement specifications across deployment modes.
- Cloud-Based:Browser-accessible platforms with API interoperability for third-party climate control hardware. Demand concentrates in California's Central Valley, where multi-site operators require real-time synchronization across distributed facilities. State groundwater sustainability agencies mandate volumetric irrigation tracking that these platforms embed as compliance modules.
- On-Premise:Server-installed systems retaining data within facility firewalls. Legacy installations persist in Nebraska and Kansas plains where cellular dead zones degrade cloud synchronization. Operators face heavy maintenance burdens and delayed software updates compared to cloud alternatives.
- Mobile Apps:Field-level task management tools running on ruggedized tablets and smartphones. Scout teams in Florida citrus groves use these for immediate pest pressure documentation.
- Hybrid Solutions:Architectures combining local edge computing with cloud analytics layers. Dutch glasshouse networks deploy these for sub-minute sensor telemetry processing.
Leading the category by volume: Cloud-Based. Growing fastest: Hybrid Solutions.
End User:
Margin pools vary dramatically by operator scale and documentation intensity. Enterprise licensing structures concentrate revenue in large-scale deployments with multi-year service contracts.
- Commercial Farms:Row-crop and specialty operations spanning thousands of acres. These operators drive demand for prescription mapping algorithms and batch-level traceability databases. USDA climate-smart agriculture incentives reward documented input reductions that cultivation software automates for carbon offset markets.
- Greenhouses:Controlled-environment agriculture facilities requiring environmental monitoring and climate setpoint automation. Netherlands tomato and pepper producers deploy digital twin architecture to compress varietal trial cycles.
- Nurseries:Propagation-focused operations managing inventory across growth stages. California ornamental producers face state agriculture department batch-tracking mandates.
- Research Institutions:University extension programs and seed company R&D facilities. These users require phenotypic data integration and growth-stage database fusion with drone-mounted multispectral imagery.
Commercial Farms generate the deepest revenue concentration. Greenhouses exhibit the steepest expansion trajectory as controlled-environment agriculture scales.
Technology:
Technical complexity escalates with real-time processing demands and cross-platform data integrity requirements.
- IoT Integration:Edge computing pipelines processing sensor telemetry from distributed networks. Sub-minute intervals from Dutch glasshouse operations create demand for specialized data architecture.
- Artificial Intelligence:Predictive yield modeling and autonomous environmental adjustment algorithms. Vendors embed machine learning without inflating per-acre pricing beyond mid-size operator tolerance.
- Data Analytics:Growth-stage benchmarking and resource optimization dashboards.
- Blockchain:Immutable batch-tracking for organic certification and export residue compliance. EU Green Deal Farm-to-Fork targets mandate 50% pesticide reduction benchmarks that these systems document.
IoT Integration commands the highest technical investment. Blockchain is climbing the fastest as import markets harden residue tolerance thresholds.
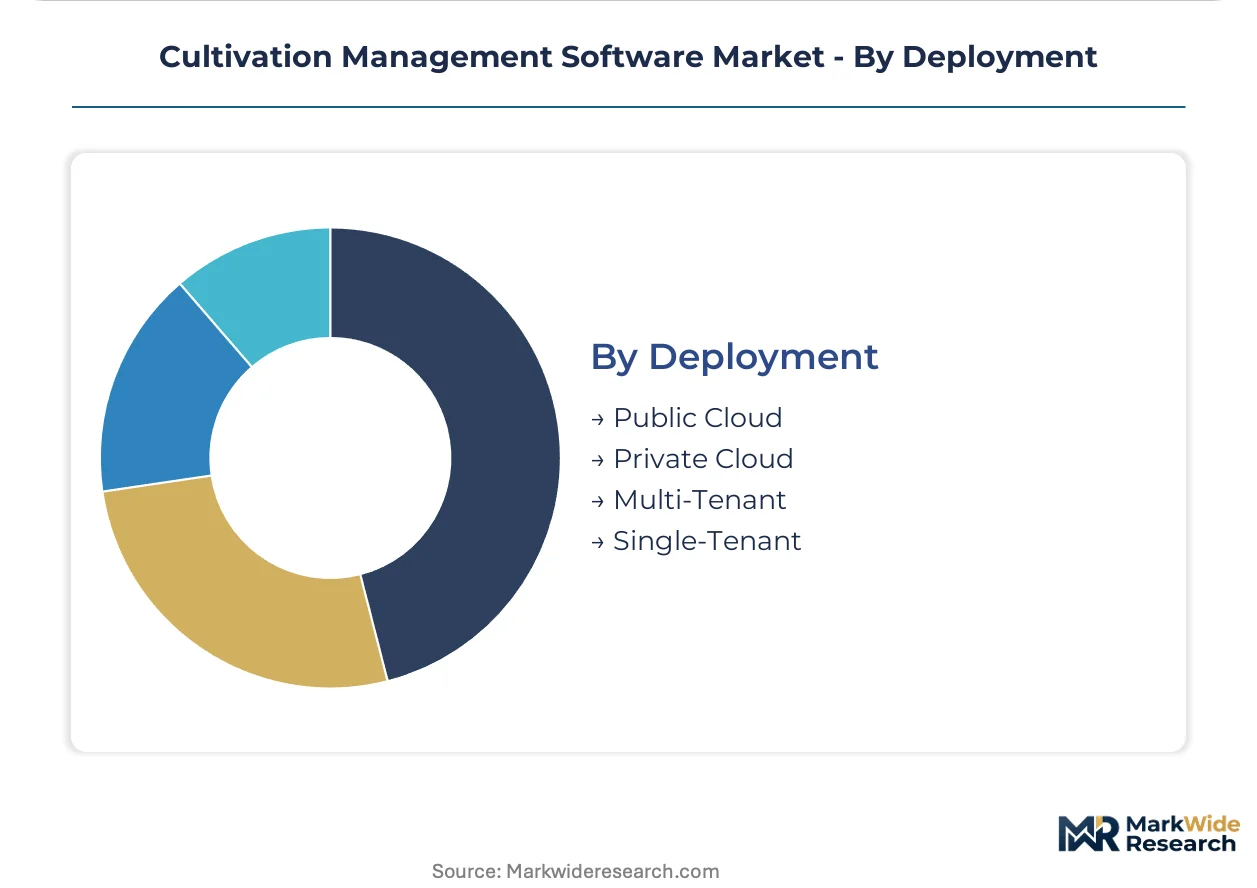
Deployment:
Infrastructure choices reflect data sovereignty requirements and API interoperability priorities.
- Public Cloud:Shared infrastructure with pay-per-use pricing. California Central Valley operators prioritize remote access and rapid scaling during seasonal peaks.
- Private Cloud:Dedicated single-tenant environments. Research institutions handling proprietary varietal data favor these for intellectual property protection.
- Multi-Tenant:Shared application instances with logical data separation.
- Single-Tenant:Isolated deployments for maximum customization.
Public Cloud dominates current installations. Private Cloud is gaining share fastest among institutions with sensitive phenotypic data.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial farm consolidation in California's Central Valley and the Netherlands' greenhouse corridor concentrates software procurement decisions among multi-site operators demanding real-time inventory synchronization.
United States
Row-crop operators across the Corn Belt drive demand for automated pesticide logging systems. EPA mandates for chemical application audit trails shape procurement specifications for cloud-native platforms. California's Central Valley operators deploy volumetric irrigation tracking modules to comply with state groundwater sustainability agency requirements.
Netherlands
Tomato and pepper producers in Dutch glasshouse networks require sub-minute sensor telemetry processing through edge-computing pipelines. EU Green Deal Farm-to-Fork pesticide reduction targets force platforms to document untreated buffer zones and biological control schedules. The Westland greenhouse corridor anchors digital twin adoption for varietal trial compression.
Brazil
Soy belt cooperatives in Mato Grosso create volume channels for lightweight SaaS tiers through collective purchasing structures. The national agricultural regulator enforces traceability documentation that cultivation platforms must automate for export compliance. São Paulo-based agritech clusters concentrate middleware development bridging incompatible cloud services.
Germany
Precision agriculture hardware bundling accelerates among Bavarian and Lower Saxony farm equipment dealerships. ECHA chemical registry integration requirements shape compliance module architecture for EU market access. The Munich-Stuttgart corridor hosts R&D facilities fusing drone-mounted multispectral imagery with growth-stage databases.
China
Controlled-environment agriculture scaling in Shandong and Jiangsu provinces generates demand for environmental monitoring platforms. National dual carbon goals pressure operators to document input reductions for offset market participation. Yangtze River Delta greenhouse clusters pilot autonomous climate adjustment algorithms.
Cultivation Management Software Market Competitive Environment
Strategic partnerships dominate the current landscape as vendors bridge hardware-software gaps through API interoperability agreements. The vendor base organizes around three tiers: equipment manufacturers bundling subscriptions with precision agriculture machinery, pure-play SaaS vendors anchoring compliance-specific modules, and middleware specialists resolving data format incompatibilities. Equipment-led bundling and cloud-native unbundling represent the primary competitive vectors reshaping procurement patterns.
Within the equipment-led tier, Deere & Company and Trimble Inc. exemplify manufacturers leveraging installed machinery bases to capture recurring software revenue. AGRIVI occupies a position among pure-play vendors, representing the compliance-specialist archetype through crop-specific regulatory modules. These three anchors illustrate how competitive positioning diverges between hardware-coupled and standalone platform strategies.
| Leading Market Players |
|---|
| Trimble Inc. |
| Deere & Company |
| Granular Inc. |
| AGRIVI |
| Topcon Corporation |
| Raven Industries |
| AGCO Corporation |
| Conservis |
| Ag Leader Technology |
| Others |
Value Chain & Pricing Dynamics
API call volume pricing in cloud-native cultivation platforms flows from hyperscaler compute costs through SaaS vendor margins to per-acre subscription tiers paid by row-crop operators. This cost cascade concentrates pricing power among vendors with direct fiber connectivity to California's Central Valley server farms, while Nebraska plains operators absorb cellular dead-zone premiums.
Pricing Analysis
Volume concentration in enterprise licensing splits from margin capture in modular unbundling. Three-tier pricing structure across premium compliance suites, standard environmental monitoring, and economy task-management tiers anchors the market. Price differentiation hinges on EPA audit-ready pesticide logging certification and multi-site API interoperability. Cost compression in the economy tier intensifies because lightweight SaaS competitors from Brazil's agritech clusters undercut per-seat rates. Smallholder cooperatives in Mato Grosso exhibit highest price sensitivity; Dutch greenhouse networks with carbon credit verification budgets show lowest.
Supply Chain Analysis
Reverse logistics for ruggedized field tablets and sensor hardware refurbishment flows from California Central Valley depots through Dallas repair hubs to redeployment in Kansas wheat operations. Hardware supply concentrates in Taiwan semiconductor fabs, Shenzhen sensor assembly plants, and German precision engineering facilities for climate control actuators. Component dependencies include ARM-based edge processors, LoRaWAN radio modules, and stainless-steel irrigation valve assemblies. Single-source vulnerability in Dutch glasshouse-specific environmental sensors creates chokepoint exposure. Distribution runs through Deere dealership networks bundling software with precision agriculture equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
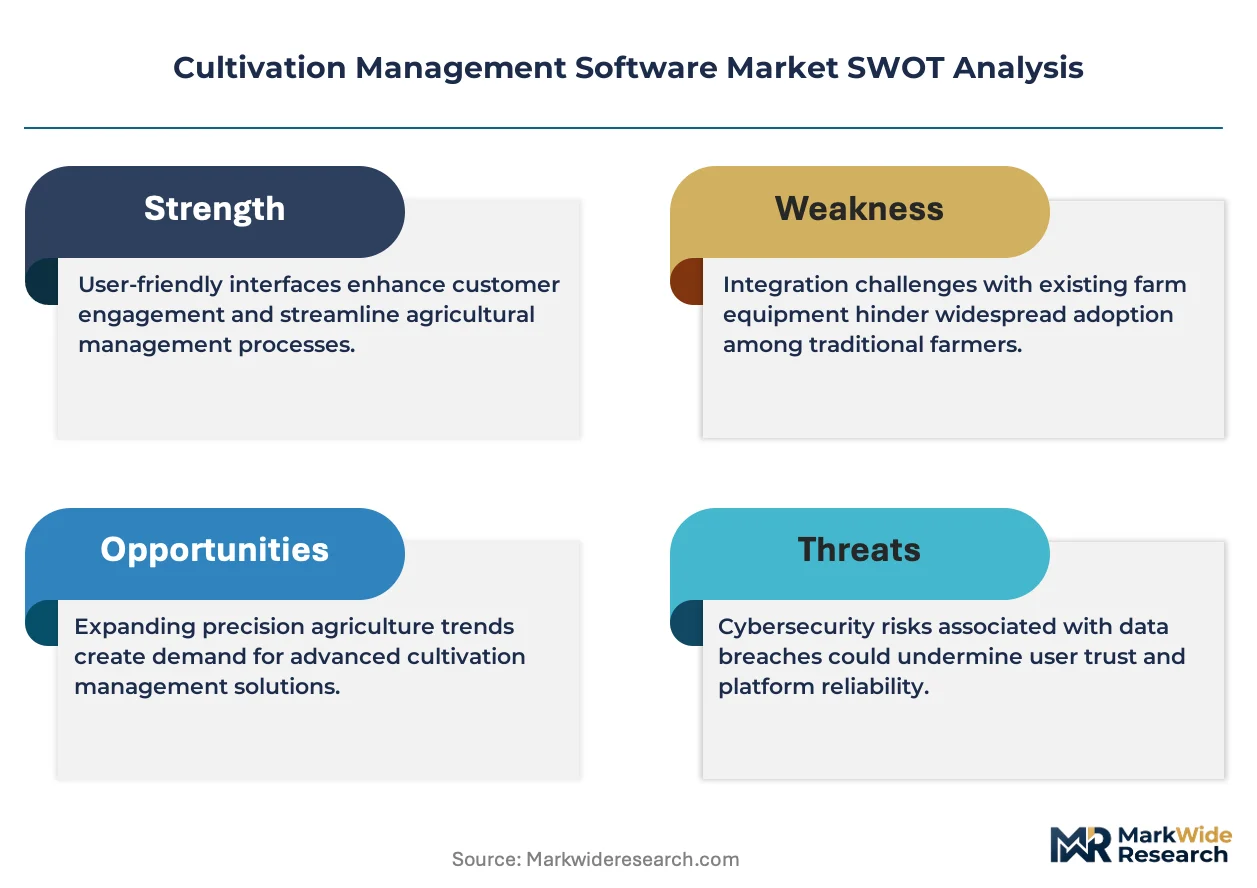
This market functions as a cost-of-compliance story where EPA pesticide logging mandates erect barrier-to-entry moats favoring vendors with pre-certified audit trail architectures.
For Market Incumbents: Extend compliance module depth into state-level groundwater sustainability tracking before pure-play SaaS vendors capture California Central Valley irrigation accounting contracts. Defensive consolidation through API interoperability partnerships with climate control hardware manufacturers neutralizes subscription unbundling threats from middleware specialists. Vertical integration into edge computing hardware secures margin pools currently captured by Taiwanese sensor suppliers. For New Entrants and Emerging Players: USDA climate-smart agriculture incentives in the United States open a window for carbon credit verification modules targeting mid-size operators excluded from enterprise pricing tiers. White-space concentration sits in Brazilian Mato Grosso cooperative purchasing structures and Chinese Yangtze River Delta autonomous climate adjustment pilots. Go-to-market leverage through cooperative agronomist extension programs bypasses direct sales force buildout costs. For Investors and Strategic Acquirers: ECHA chemical registry integration announcements from German vendors signal the leading indicator that EU market access certification is becoming acquisition currency. Long-term viability frames around climate-smart agriculture incentive permanence and import market residue tolerance tightening. Acquisition target archetype: middleware specialists bridging incompatible cloud services with ISO interoperability certification pipelines. Monitor EPA audit trail mandate expansion into fertilizer application logging as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API interoperability with Dutch climate control hardware compresses deployment cycles for greenhouse operators. |
| Compliance Module Expansion | EPA pesticide logging automation captures Corn Belt row-crop procurement specifications. |
| Edge Computing Partnership | Sub-minute sensor telemetry processing secures Netherlands glasshouse network contracts. |
| Geographic Expansion | Brazilian cooperative bundling structures unlock Mato Grosso soy belt volume channels. |
| Acquisition of Specialist Firm | Middleware developers resolving legacy data silo incompatibilities consolidate integration burden. |
Study Parameters
USDA enforcement bulletins, EPA compliance guidance documents, and state agriculture department regulatory filings formed the secondary backbone validating primary intelligence. Cultivation software vendor executives, precision agriculture equipment procurement leads at commercial farm cooperatives, and university extension program agronomists supplied operational perspective. SEC 10-K disclosures from equipment manufacturers and hyperscaler capex reports provided infrastructure scaling indicators. Bottom-up acreage deployment estimates triangulated against top-down addressable market calculations.
Historical trendline analysis of cloud adoption rates in agricultural software tracked deployment mode shifts across the projection horizon. Segmentation dimensions modeled include deployment architecture, operator scale tier, crop type specialization, and regional regulatory cluster intensity. CAGRs derived from fitted growth curves incorporating IoT sensor density trajectories and climate-smart agriculture incentive appropriation schedules. Carbon credit verification demand curves and EU Farm-to-Fork pesticide reduction compliance timelines fed scenario-weighted outputs.
Caveats apply where EPA mandate scope expansion or ECHA chemical registry revision could materially shift the outlook. Forecasts assume sustained hyperscaler pricing discipline and stable cellular infrastructure buildout in Plains states. Practitioners should monitor USDA climate-smart agriculture incentive reauthorization debates and Dutch groundwater sustainability agency enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Mobile Dating Apps Market
Digital Solutions
Desktop Virtualization Market
Digital Solutions
Web Content Management Market
Digital Solutions
Global Service Delivery Platform Market
Digital Solutions
Europe Digital Signage Market
Digital Solutions
Asia-Pacific API Management Market
Digital Solutions
North America Enterprise Information Archiving (EIA) Market
Digital Solutions
Europe IT Asset Disposition Market
Digital Solutions
Global Enterprise Mobility Management (EMM) Market
Digital Solutions
Product Lifecycle Management Consumer Packaged Goods and Retail (PLM Cpandr) Market
Digital Solutions
Enterprise Mobility in Energy Sector Market
Digital Solutions
South Korea Digital Twin Market
Digital Solutions
Voice Remote Control Market
Digital Solutions
Messaging Platform Market
Digital Solutions
Global Online Reputation Management Software Market
Digital Solutions
IPTV Market