
 Boat Navigation Software Market | 2026-2036
Boat Navigation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Boat Navigation Software Market Insights
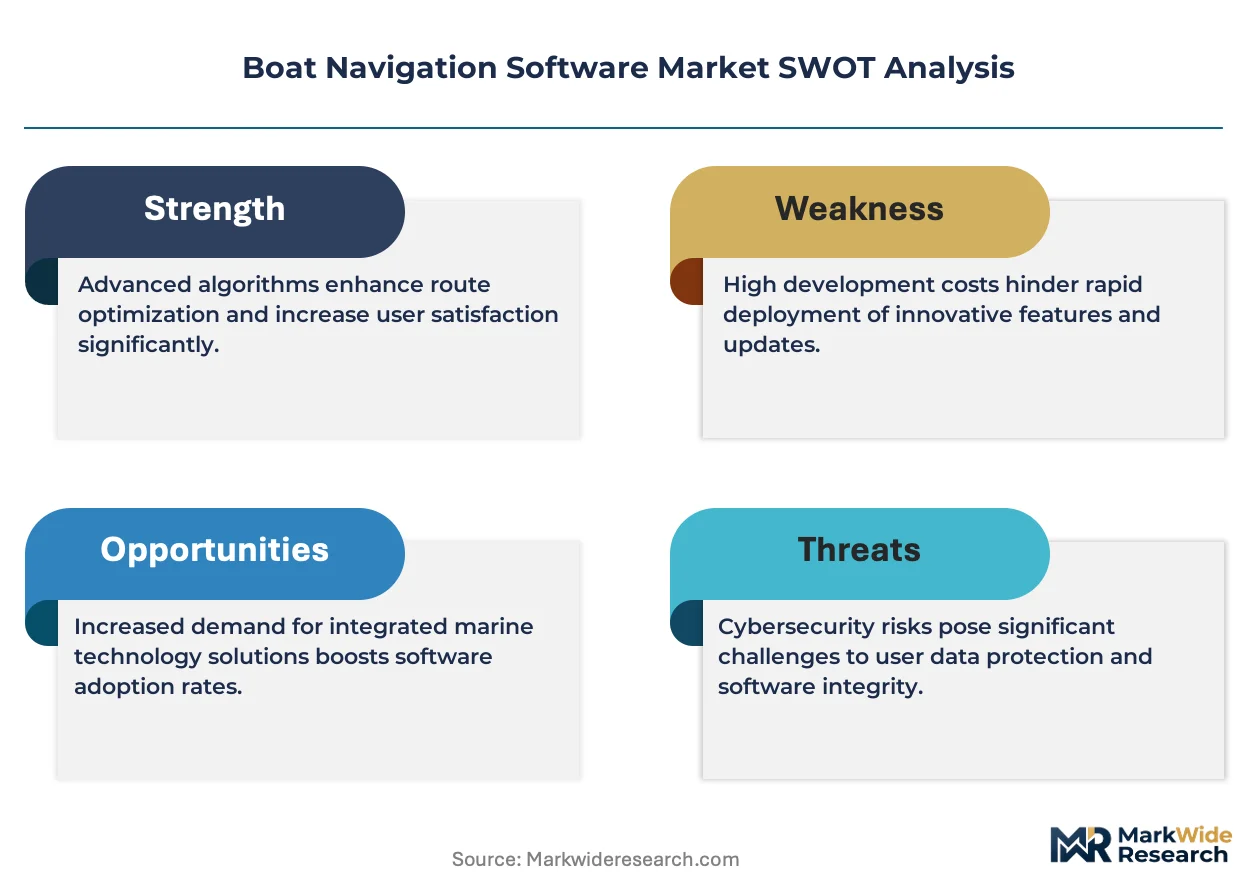
Shortages of certified maritime software engineers is redrawing competitive boundaries in the Boat Navigation Software Market. Garmin leverages its vertically integrated hardware-software ecosystem to dominate integrated bridge systems for leisure yachts. Raymarine sustains technology leadership through specialized radar-overlay capabilities that merge traditional navigation with real-time collision avoidance. C-MAP competes on chart data density, anchoring its position in commercial shipping corridors where hydrographic accuracy determines operational safety.
Boat navigation software encompasses electronic systems that process GPS coordinates, AIS transponder data, and sonar depth readings to generate real-time positional awareness and route recommendations for watercraft operators. These platforms integrate vector chart databases with sensor fusion algorithms to prevent grounding incidents and optimize passage planning across variable bathymetry. Chartplotters and electronic navigational charts command the largest installed base among product categories, though cloud-based delivery models are expanding fastest as satellite connectivity penetrates offshore zones. Mobile applications represent an emerging margin pool, particularly among leisure yacht owners seeking tablet-based alternatives to dedicated bridge hardware.
The International Maritime Organization's e-navigation framework and the US Coast Guard's Electronic Charting Requirements shape product certification pathways and mandate minimum data interoperability standards for vessels operating in regulated waters. The EU's MRV and IMO's DCS emissions reporting rules further tighten integration demands between navigation logs and fuel monitoring systems. Stakeholders must monitor how forthcoming cybersecurity standards for shipboard networks reshape software architecture requirements and vendor qualification criteria.
Market Dynamics
The International Maritime Organization's e-navigation mandate is compressing replacement cycles for legacy paper-based systems while simultaneously fragmenting vendor qualification pathways across flag-state jurisdictions.
Growth Catalysts
- IMO E-Navigation Framework:Mandatory digital carriage requirements for SOLAS-class vessels are forcing systematic replacement of outdated chart systems across commercial fleets operating in regulated waters.
- Offshore Wind Expansion:Service vessel operators in the North Sea are deploying advanced dynamic positioning integration to maintain station-keeping precision amid turbine array complexity.
- Sensor Fusion Architectures:Multi-source data integration combining AIS, radar, and sonar inputs is reducing grounding incidents in shallow-water corridors with variable bathymetry.
Market Restraints
- Certified Engineer Scarcity:Maritime software development requires specialized expertise in both naval architecture and embedded systems, constraining vendor scaling capacity.
- Type Approval Costs:IEC 61162 and IEC 62288 certification expenses for new hardware-software combinations disproportionately burden mid-tier system integrators.
- Satellite Connectivity Pricing:Persistent L-band and VSAT service costs limit cloud-based feature deployment for coastal fishing operators with thin margin structures.
Strategic Opportunities
- Recreational Tablet Migration:Leisure yacht owners are abandoning dedicated bridge hardware for iOS and Android applications with downloadable chart regions.
- EU MRV Integration:Emissions reporting mandates are creating demand for navigation-fuel monitoring data fusion in European commercial shipping corridors.
- Autonomous Vessel Preparedness:Remote-operated and unmanned surface vehicle developers require redundant navigation stacks with deterministic latency guarantees.
Industry Challenges
- Cybersecurity Architecture Redesign:IEC 62443 maritime security standards are forcing software vendors to reengineer legacy codebases with segmented network zones.
- Multi-Flag Certification Burden:Vessel operators registered under Panama, Liberia, and Marshall Islands face divergent equipment approval timelines that complicate fleet standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boat Navigation Software Market |
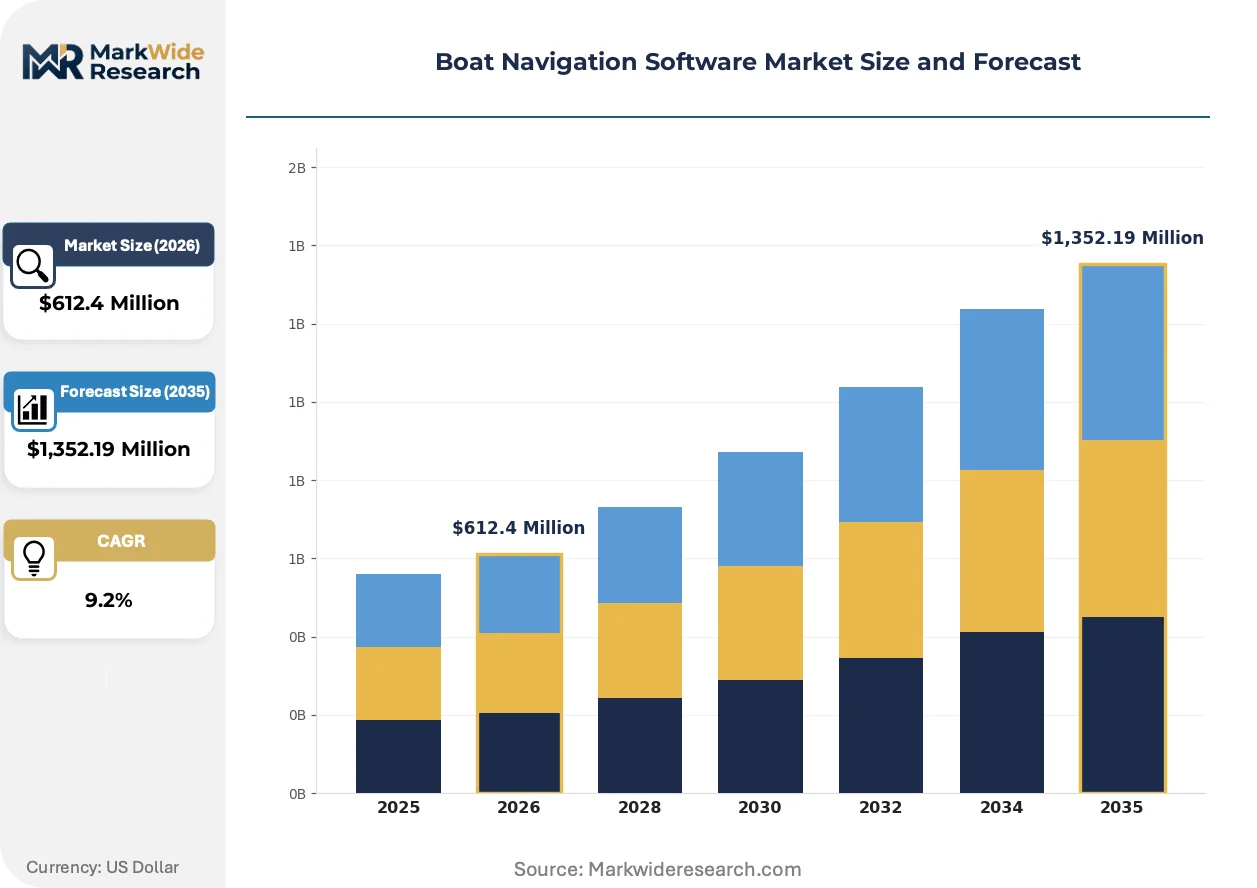
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,352.19 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chartplotters, Marine GPS, Electronic Navigational Charts, Mobile Applications End User: Commercial Vessels, Fishing Boats, Leisure Yachts, Research Vessels Delivery Model: On-Premise, Cloud-Based, Hybrid, Subscription-Based Technology: GPS, AIS, Radar, Sonar |
| Companies Covered | Timezero, i-Boating, Rose Point, Expedition Marine, Navionics, Garmin, Raymarine, C-MAP, OpenCPN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boat Navigation Software Market Trends and Innovations
Navigation software architectures are splitting between high-integrity commercial stacks and consumer-grade recreational platforms, with connectivity infrastructure determining which path dominates in each waterway segment.
Cloud-native chart delivery is bifurcating the installed base between vessels with persistent satellite links and those reliant on pre-loaded vector databases. Offshore supply operators in Norway's North Sea fields are adopting streaming updates for real-time hazard notification, while coastal fishing fleets retain offline-first architectures due to connectivity cost constraints. This technical schism is compressing pricing power for mid-range hybrid systems that attempt to serve both installation types.
REACH restrictions on hazardous substances in electronics are reshaping hardware-software bundling strategies for European-market chartplotters. Manufacturers must now certify entire integrated bridge systems rather than discrete components, extending product development timelines. Commercial shipping operators are responding by consolidating procurement around vendors with established EU notified body relationships.
Subscription pricing for chart updates is displacing perpetual license models among recreational boaters in Mediterranean charter markets. Fleet managers for yacht rental operators in Croatia and Greece are unbundling hardware acquisition from data service contracts. This procurement pattern shift is most visible in seasonal boating corridors where vessel utilization rates justify operational expenditure treatment over capital deployment.
Boat Navigation Software Market Segmentation
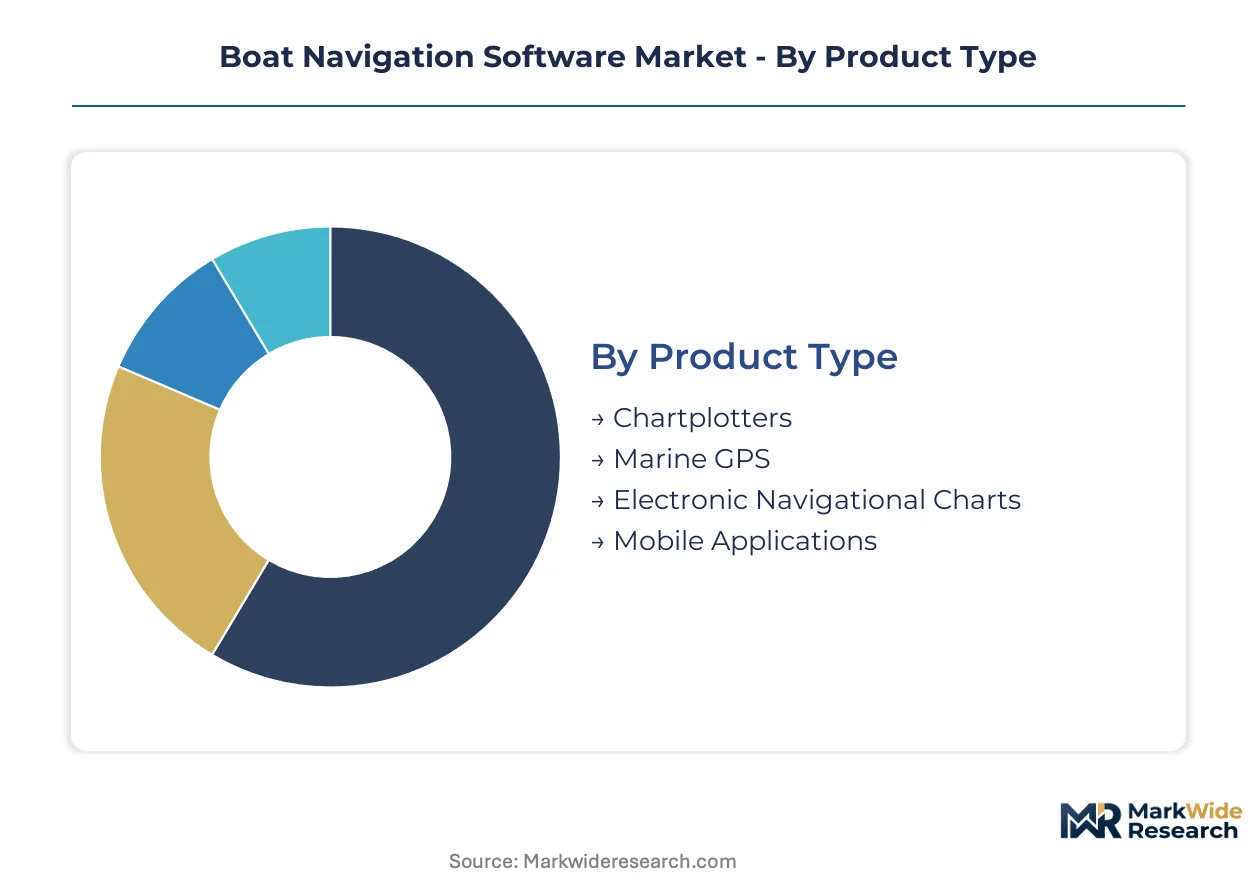
Boat navigation software vendors face divergent margin structures across hardware-integrated systems versus pure software plays. Channel strategy determines which segments warrant direct sales investment versus distribution partnerships.
Product Type:
Integrated hardware-software bundles flow through marine electronics distributors, while standalone software licenses reach end-users via direct download portals and app stores.
- Chartplotters:Multifunction displays combining GPS receivers with vector chart rendering engines dominate commercial bridge installations. Norwegian offshore supply operators specify these for redundant navigation stacks in North Sea conditions where IEC 61162 compliance is mandatory.
- Electronic Navigational Charts:Vector and raster databases certified to S-57 and S-101 standards form the data layer beneath all other navigation products. Commercial shipping corridors between Rotterdam and Singapore generate concentrated update subscription demand due to frequent bathymetric changes.
- Marine GPS:Dedicated position-fixing hardware with differential correction capabilities.
- Mobile Applications:Tablet and smartphone software with downloadable chart regions for recreational use.
Chartplotters dominate installed base. Mobile applications are where expansion concentrates.
End User:
Cost tier separation is pronounced: SOLAS-class vessels absorb five-figure system costs while leisure operators cluster below thousand-dollar price points.
- Commercial Vessels:Cargo ships and tankers require type-approved integrated bridge systems with redundant data feeds. The US Coast Guard's Electronic Charting Requirements and IMO e-navigation mandates force systematic replacement cycles in this segment.
- Leisure Yachts:Recreational craft owners prioritize touchscreen interfaces and smartphone integration over certification depth. Mediterranean charter fleets in Croatia and Greece are unbundling hardware from subscription services.
- Fishing Boats:Coastal and deep-water operators with thin margin structures.
- Research Vessels:Scientific platforms requiring specialized bathymetric and oceanographic data fusion.
Commercial vessels absorb the highest per-unit expenditure. Leisure yachts are climbing the fastest in unit volume terms.
Delivery Model:
Volume concentration favors perpetual licenses in legacy installed bases, though recurring revenue models are gaining share in new deployments.
- On-Premise:Perpetually licensed software with local chart database storage serves vessels operating beyond persistent satellite coverage. Coastal fishing fleets across Indonesia and Philippines rely on this architecture due to L-band service cost constraints.
- Cloud-Based:Streaming chart delivery and real-time hazard notification require continuous connectivity. Norway's North Sea offshore wind service vessels have adopted this model for dynamic positioning integration with turbine array navigation.
- Hybrid:Offline-first core systems with intermittent synchronization for updates.
- Subscription-Based:Recurring payment structures for chart updates and feature access.
On-premise systems retain the largest active fleet. Cloud-based deployment is gaining share fastest among new installations.
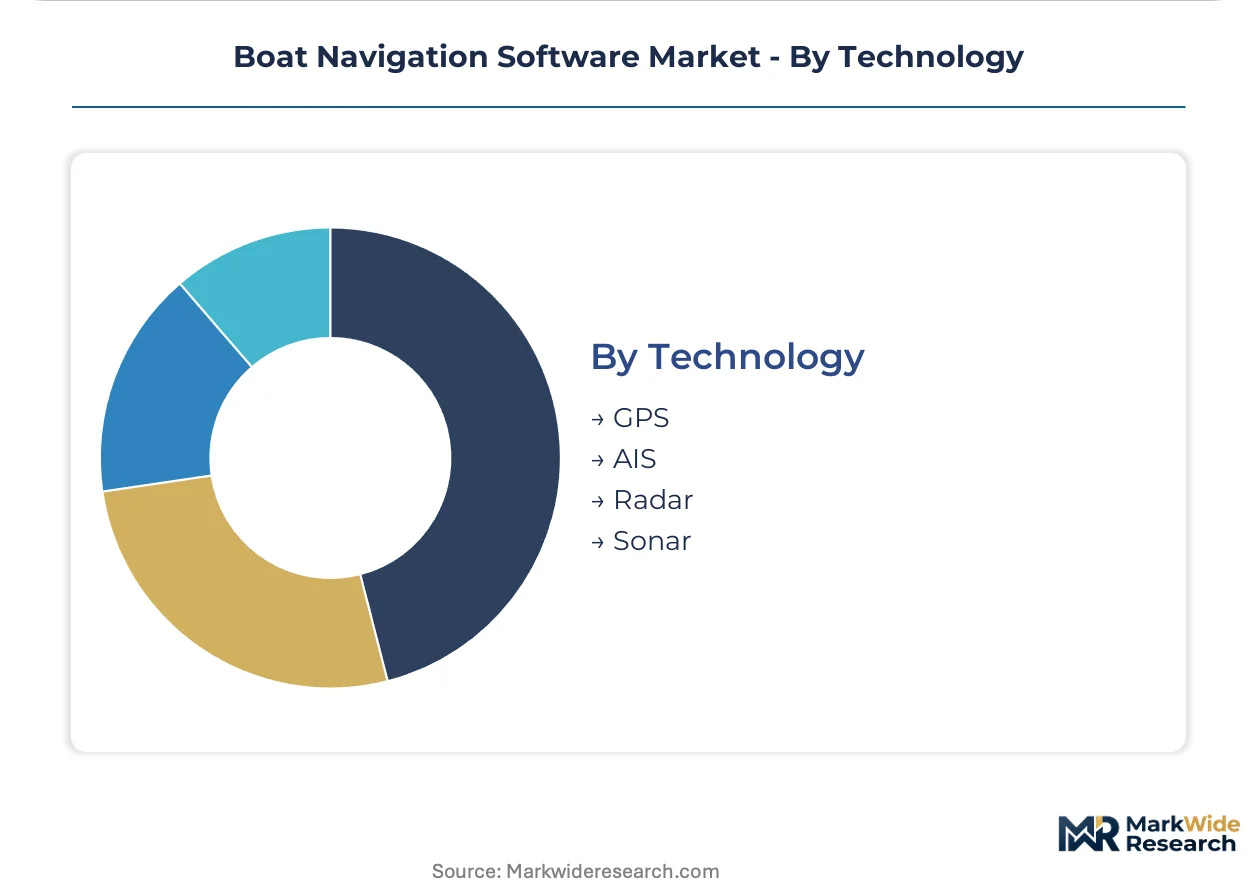
Technology:
Application context determines which sensor fusion combinations command premium pricing versus commodity positioning.
- GPS:Satellite-based position fixing with differential correction for sub-meter accuracy remains the foundational layer. All vessel categories require GPS, though precision demands vary from recreational wayfinding to commercial dynamic positioning.
- AIS:Automatic Identification System transponder integration enables collision avoidance and fleet tracking. Mandatory carriage requirements for SOLAS vessels create regulated demand concentration.
- Radar:Active microwave sensing for target detection in reduced visibility.
- Sonar:Acoustic depth sounding and bottom mapping for shallow-water navigation.
GPS and AIS form the universal baseline. Radar-overlay integration commands the steepest expansion trajectory in high-integrity commercial stacks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The International Maritime Organization's e-navigation mandate anchors regulatory momentum in Norway, where North Sea offshore operations drive premium system demand. Commercial fleets across multiple jurisdictions face synchronized compliance deadlines that compress replacement cycles.
Norway
Offshore wind service vessels and supply boat operators require dynamic positioning integration for turbine array navigation. The Norwegian Maritime Authority enforces strict IEC 61162 compliance for vessels operating in harsh North Sea conditions. Bergen and Stavanger host concentrated clusters of system integrators serving energy sector demand.
United States
Recreational boaters in Florida and California are migrating to tablet-based navigation applications with downloadable chart regions. The US Coast Guard's Electronic Charting Requirements mandate digital carriage for regulated commercial vessels. Seattle and Fort Lauderdale anchor marine electronics distribution networks serving both leisure and commercial segments.
Germany
Commercial shipping operators along the Rhine corridor and North Sea ports require emissions-integrated navigation systems for EU MRV compliance. The Federal Maritime and Hydrographic Agency enforces type approval standards that extend product development timelines. Hamburg concentrates fleet management headquarters demanding bundled hardware-software procurement.
Japan
Coastal fishing fleets and commercial shipping lines seek sensor fusion architectures combining radar, AIS, and sonar inputs. METI guidelines on maritime digitalization shape domestic certification pathways. Nagoya and Osaka harbor industrial clusters where shipbuilders specify integrated bridge systems for export vessels.
United Kingdom
Leisure yacht charter operators in the Solent and Mediterranean cruising grounds unbundle hardware from subscription chart services. The Maritime and Coastguard Agency implements IMO e-navigation standards with flag-state specific modifications. Southampton anchors marine electronics retail networks serving seasonal boating demand.
Boat Navigation Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with vertically integrated hardware-software bundles commanding premium positioning against pure software challengers. The vendor base stratifies across three tiers: multinational electronics conglomerates with captive distribution, specialized marine software houses with chart data depth, and open-source community projects with zero acquisition cost. Dominant competitive moves include backward integration into sensor manufacturing and geographic expansion through flag-state certification partnerships.
Within the integrated systems tier, Garmin and Raymarine occupy positions defined by hardware-software ecosystem control. C-MAP exemplifies the specialized chart data archetype, anchoring commercial shipping corridor demand through hydrographic density. Rose Point represents the mid-tier software specialist segment serving regional fleet operators with configurable platform architectures.
| Leading Market Players |
|---|
| Timezero |
| i-Boating |
| Rose Point |
| Expedition Marine |
| Navionics |
| Garmin |
| Raymarine |
| C-MAP |
| OpenCPN |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Taiwanese semiconductor foundries shapes component scarcity timelines for marine electronics manufacturers, compressing margin buffers for mid-tier chartplotter assemblers while elevating pricing power among vertically integrated bridge system vendors. This scale asymmetry forces smaller system integrators toward modular procurement strategies that sacrifice cost efficiency for supply security.
Pricing Analysis
Geographic price spreads between Norwegian offshore supply operators and Mediterranean leisure charter fleets exceed three-to-one for functionally equivalent sensor fusion architectures. Three-tier pricing structure across premium, standard, and economy levels separates IEC 61162-certified integrated bridge systems from recreational tablet applications and coastal fishing plotters. Pricing pressure stems from subscription chart services displacing perpetual licenses in seasonal boating corridors. Commercial vessel operators demonstrate lowest price sensitivity due to regulatory compliance mandates, while coastal fishing fleets in Indonesia and Philippines cluster at economy tier ceilings.
Supply Chain Analysis
Strait of Malacca transit congestion elevates logistics risk for display panel shipments originating from South Korean and Chinese manufacturing clusters. Marine electronics supply chains draw from Taiwanese GPS chipset fabricators, Japanese radar component specialists, and German precision sensor manufacturers. Single-source vulnerability concentrates in S-band radar magnetron supply from legacy industrial facilities. Distribution runs through marine electronics distributors concentrated in Fort Lauderdale, Hamburg, and Singapore harbor zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet consolidation among European container shipping lines concentrates procurement leverage, compressing vendor margins and forcing standardization around fewer integrated bridge platforms. This buyer-power shift rewards scale and punishes fragmentation.
For Market Incumbents: Shield installed base retention by accelerating IEC 62443 cybersecurity certification ahead of flag-state enforcement timelines. Deepen backward integration into AIS transponder manufacturing to capture margin pools currently flowing to component suppliers. Channel control through exclusive distributor agreements in Bergen and Stavanger clusters defends against pure-software challengers.
For New Entrants and Emerging Players: Cloud-native chart delivery for offshore wind service vessels represents the most penetrable white-space target, as incumbent hardware vendors lag streaming update architectures. Target Norway's North Sea corridor with dynamic positioning integration modules that retrofit existing bridge systems. Go-to-market leverage rests on flag-state certification partnerships that accelerate type approval timelines relative to established players.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized chart data houses with S-101 standard compliance and established EU notified body relationships. Long-term viability hinges on navigation-fuel monitoring fusion capabilities for emissions compliance regimes. Acquisition archetype: marine software specialists with deterministic latency engineering for autonomous vessel stacks. Watch IEC 61162-450 Ethernet standard adoption rates as inflection signal for cloud-native architecture viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Sensor fusion architectures combining AIS, radar, and sonar reduce grounding incidents in shallow-water corridors. |
| Acquisition of Specialist Firm | Chart data density capabilities anchor position in Rotterdam-Singapore commercial shipping corridors. |
| Geographic Expansion | Flag-state certification partnerships in Panama, Liberia, and Marshall Islands enable fleet standardization contracts. |
| Strategic Partnership | Satellite connectivity providers unlock cloud-based feature deployment for offshore wind service vessels. |
| Product Launch | Tablet-based navigation applications with downloadable chart regions capture Mediterranean charter fleet demand. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with marine electronics distributors, fleet procurement managers, and naval software engineers, alongside secondary validation through US Coast Guard Electronic Charting Requirements documentation, IMO e-navigation framework publications, and customs records for marine GPS equipment trade flows. Bottom-up vessel fleet segmentation triangulated against top-down market size estimates from hardware shipment data and chart update subscription disclosures.
Across the modeling period, forecast outputs reflect analytical frameworks segmenting by product type, end-user category, delivery model, and regional adoption pattern. CAGRs derived from replacement cycle analysis of SOLAS-class vessel fleets and penetration curve modeling for recreational tablet migration. Industry-specific inputs included IEC 61162 compliance timelines and satellite connectivity cost trajectories for L-band and VSAT services.
Underlying assumptions cover regulatory enforcement consistency for e-navigation mandates, with deviation risk concentrated in multi-flag certification timeline divergence and cybersecurity standard implementation delays. Practitioners should keep alternative scenarios live as flag-state jurisdiction fragmentation and autonomous vessel regulatory frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
India Digital Twin Market
Digital Solutions
IT Operations and Service Management (ITOSM) Market
Digital Solutions
Returnless Refund Fraud Detection Market
Digital Solutions
Smart Dictation Systems Market
Digital Solutions
Cloud-Based POS Market
Digital Solutions
Global Application Container Market
Digital Solutions
Virtual Closet Market
Digital Solutions
Marketing Automation Market
Digital Solutions
Graph Technology Market
Digital Solutions
Digital Manufacturing Market
Digital Solutions
Global Domain and Hosting Market
Digital Solutions
Global Genealogy Products and Services Market
Digital Solutions
North America Product Design and Development Services Market
Digital Solutions
France Digital Twin Market
Digital Solutions
System Integration Market
Digital Solutions
Digital Signage Systems Market