
 Kubernetes Solutions Market | 2026-2036
Kubernetes Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Kubernetes Solutions Market Outlook
The EU Green Deal is repositioning enterprise procurement criteria toward energy-efficient infrastructure, compelling data center operators to prioritize container density and workload optimization. Red Hat OpenShift leverages its hybrid cloud platform to anchor multi-environment deployments for regulated industries. Google Kubernetes Engine dominates public cloud container orchestration through deep integration with carbon-aware computing APIs and custom silicon.
Kubernetes solutions provide automated container orchestration through control plane scheduling, pod lifecycle management, and declarative configuration via YAML manifests, enabling organizations to deploy scalable microservices architectures across heterogeneous infrastructure. Managed Services commands the largest revenue pool as enterprises offload control plane complexity to hyperscaler platforms, while Self-Managed Services captures the fastest expansion among sovereign cloud deployments in defense and critical infrastructure sectors. Hybrid Cloud configurations concentrate margin pools where consulting and integration services attach to complex multi-environment implementations.
The EU AI Act, GDPR, and ISO 27001 standards collectively shape Kubernetes deployment architectures by mandating audit trails, data residency controls, and automated compliance verification within CI/CD pipelines. NIST cybersecurity frameworks in the United States further harden requirements for runtime security scanning and zero-trust network policies across containerized workloads. Stakeholders must evaluate whether their orchestration strategies accommodate emerging regulatory mandates for algorithmic transparency and cross-border data governance before platform commitments solidify.
Market Dynamics
The EU AI Act is compressing deployment timelines for financial services firms modernizing core banking infrastructure through automated container pipelines. Sovereign cloud mandates in Germany and France are fragmenting procurement patterns across European industrial manufacturers.
Growth Catalysts
- GDPR audit mandates:European data residency requirements are compelling enterprises to adopt self-managed Kubernetes control planes with embedded compliance verification.
- Industrial edge computing:German automotive manufacturers are deploying lightweight K3s distributions for factory-floor workload orchestration.
- Carbon-aware scheduling:Google Cloud's integration with carbon intensity APIs is pulling public sector buyers toward managed container services.
Market Restraints
- Control plane specialization:The scarcity of certified Kubernetes administrators in France and Italy is inflating implementation timelines.
- Hyperscaler concentration:Three cloud providers dominate managed Kubernetes revenue pools, creating vendor lock-in risk for regulated enterprises.
- Legacy mainframe integration:COBOL-dependent banking cores resist containerization without expensive middleware layers.
Strategic Opportunities
- Defense sovereign clouds:NATO member states are funding air-gapped Kubernetes platforms for classified workload orchestration.
- GitOps convergence:The merging of infrastructure-as-code with declarative deployment is opening consulting attach opportunities.
- EU Green Deal procurement:Public tenders now weight energy-efficient container density, favoring workload optimization tooling.
Industry Challenges
- Platform engineering talent:Site reliability engineering expertise remains concentrated in Amsterdam and Berlin, constraining rollout velocity.
- Runtime security tooling:Falco and eBPF implementation complexity is delaying zero-trust network policy enforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kubernetes Solutions Market |
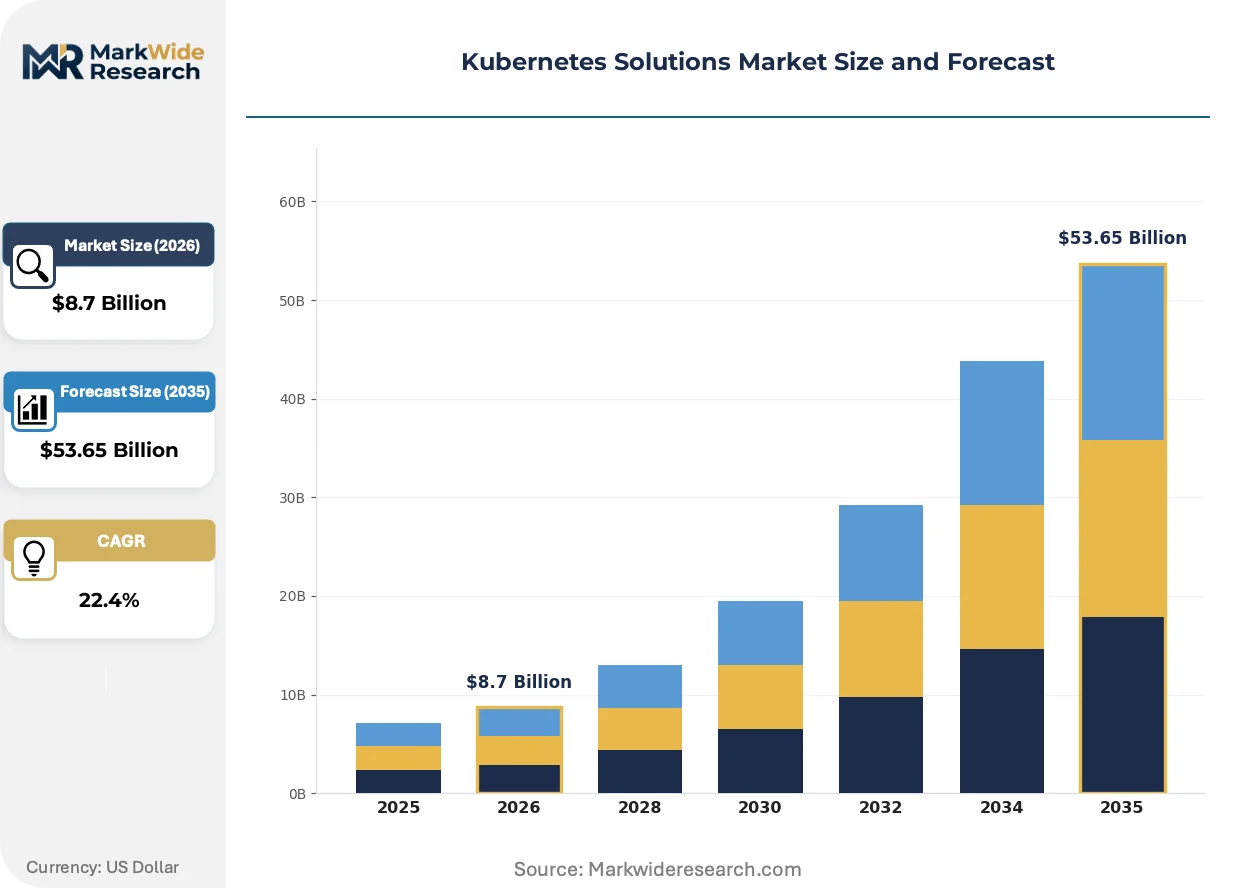
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $53.65 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Type: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Service Model: Managed Services, Self-Managed Services, Consulting Services, Support Services Use Case: DevOps, CI/CD, Microservices, Application Modernization Industry Vertical: Financial Services, Retail, Healthcare, Telecommunications |
| Companies Covered | Amazon Elastic Kubernetes Service, Azure Kubernetes Service, Red Hat OpenShift, Spectro Cloud, Rafay, Rancher, Google Kubernetes Engine, Mirantis, VMware Tanzu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kubernetes Solutions Market Strategic Shifts
Container runtime architectures are fragmenting as WebAssembly modules challenge traditional Linux containers for edge and serverless workloads. This shift is compressing the boundary between Kubernetes and emerging lightweight orchestration layers.
eBPF-based observability is consolidating telemetry collection, security enforcement, and network policy implementation into a single kernel instrumentation layer. Financial services firms in Frankfurt and London are adopting Cilium-based service meshes to replace sidecar proxies. This consolidation is reducing operational overhead and compressing vendor stacks in the observability segment.
The EU AI Act's algorithmic governance requirements are mandating immutable audit trails for model deployment pipelines. Container image signing and attestation frameworks are becoming mandatory for automated decision systems in healthcare and credit scoring. French regulators at CNIL are inspecting Kubernetes API server logs for evidence of human-in-the-loop verification.
FinOps tooling integration is reshaping how platform teams allocate infrastructure costs to internal business units. Chargeback models based on pod-level resource consumption are displacing flat-rate VM pricing in German manufacturing conglomerates. This behavioral shift is most pronounced in Bavaria, where industrial IoT deployments require granular workload cost attribution.
Kubernetes Solutions Market Segmentation
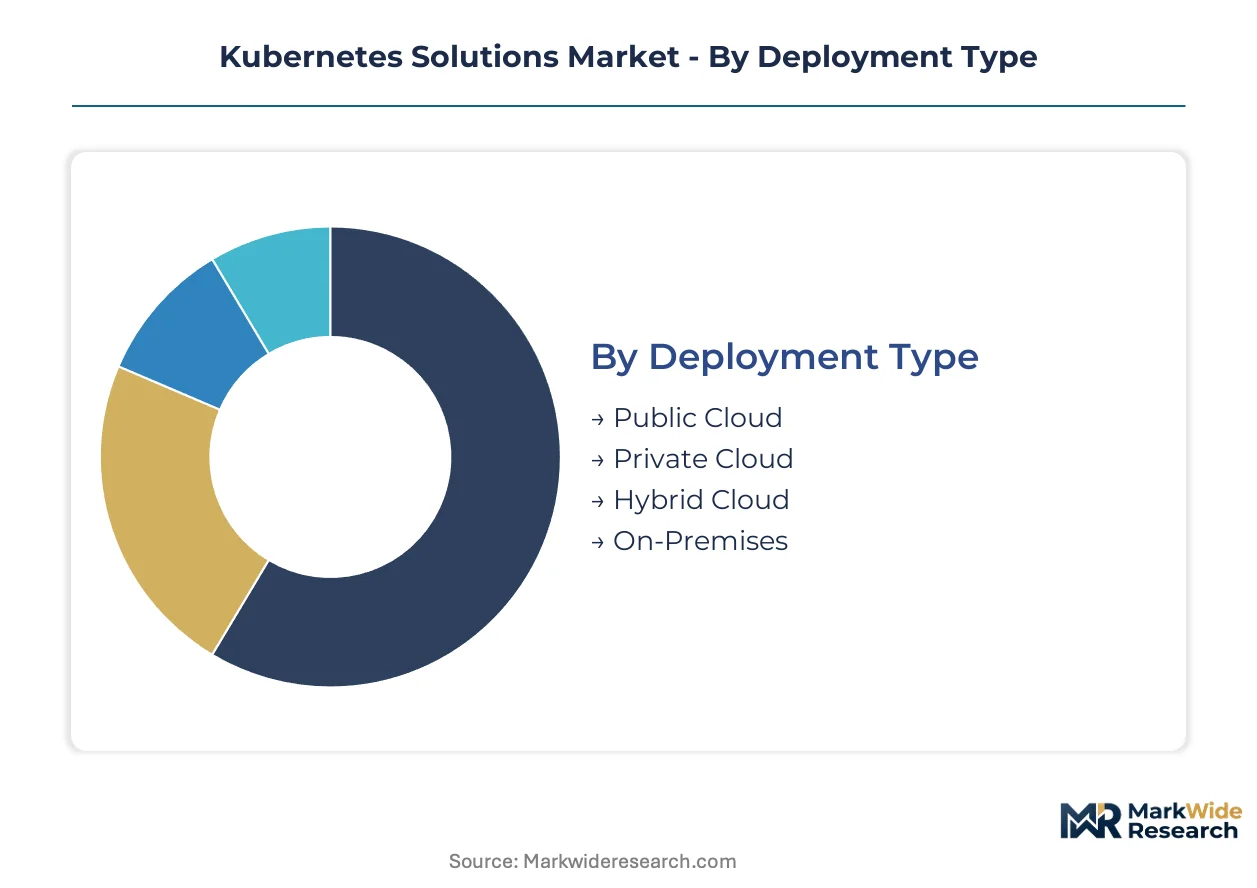
Kubernetes solutions fragment across deployment architectures, operational models, and compliance postures. Each segment carries distinct certification burdens and infrastructure requirements that shape procurement decisions in regulated industries.
Deployment Type:
GDPR, EU AI Act, and ISO 27001 certifications apply differentially across deployment modes, with private and hybrid configurations demanding the most extensive audit documentation.
- Public Cloud:Hyperscaler-managed control planes abstract infrastructure compliance, with shared responsibility models transferring audit burden to cloud providers. German automotive suppliers favor this mode for non-sovereign development workloads to accelerate time-to-market.
- Hybrid Cloud:Split orchestration across on-premises and cloud environments requires dual compliance frameworks and cross-environment policy synchronization. French healthcare networks deploy this architecture to maintain patient data residency while bursting analytics workloads to public infrastructure.
- Private Cloud:Dedicated infrastructure mandates full ISO 27001 scope and CNIL-aligned audit trails for API server access logs.
- On-Premises:Air-gapped deployments in defense and critical infrastructure sectors require NATO-aligned security certifications and physical access controls.
Hybrid Cloud sits at the top of the volume ranking, with On-Premises climbing the fastest among sovereign cloud mandates.
Service Model:
Margin pools concentrate where professional services attach to complex implementations, with consulting and integration work commanding premium pricing in multi-environment deployments.
- Managed Services:Hyperscaler platforms assume control plane operations, embedding automated patching and compliance verification into SLAs. Italian mid-market manufacturers adopt this model to bypass certified administrator scarcity.
- Self-Managed Services:Enterprises retain full control plane ownership, requiring in-house SRE expertise and custom security tooling. German defense contractors select this path to satisfy classified workload requirements under national security frameworks.
- Consulting Services:Platform engineering and migration advisory attach to hybrid and private cloud transformations.
- Support Services:Tiered technical assistance contracts cover break-fix scenarios and upgrade orchestration.
Managed Services captures the largest revenue pool, with Self-Managed Services gaining share fastest in regulated verticals.
Use Case:
Application architecture maturity determines which use cases dominate procurement, with legacy modernization projects carrying the longest implementation timelines.
- Microservices:Fine-grained service decomposition demands advanced service mesh capabilities and distributed tracing infrastructure. London-based fintech firms deploy Istio and Cilium to replace sidecar-heavy architectures with eBPF-based observability.
- Application Modernization:Containerization of legacy monoliths requires middleware layers and strangler fig patterns for COBOL-dependent banking cores. Frankfurt financial institutions allocate multi-year timelines for mainframe integration.
- DevOps:Platform engineering teams standardize internal developer platforms atop Kubernetes abstractions.
- CI/CD:GitOps-driven deployment pipelines embed compliance verification and image signing into automated workflows.
Microservices leads current deployment volume, with Application Modernization showing steepest expansion trajectory as banking core renovation accelerates.
Industry Vertical:
Regulatory intensity varies sharply across verticals, with financial services and healthcare facing the most stringent algorithmic governance and data residency mandates.
- Financial Services:Core banking modernization drives container adoption, with EU AI Act audit requirements mandating immutable deployment logs for credit scoring algorithms. Dutch banks invest in Falco runtime security and zero-trust network policies to satisfy DNB supervisory expectations.
- Healthcare:Patient data residency controls and clinical decision system transparency requirements shape architecture choices. French hospital networks implement CNIL-inspected API logging for diagnostic AI deployments.
- Retail:Seasonal demand elasticity favors public cloud burst patterns and FinOps chargeback models.
- Telecommunications:5G edge orchestration and network function containerization drive lightweight K3s distributions.
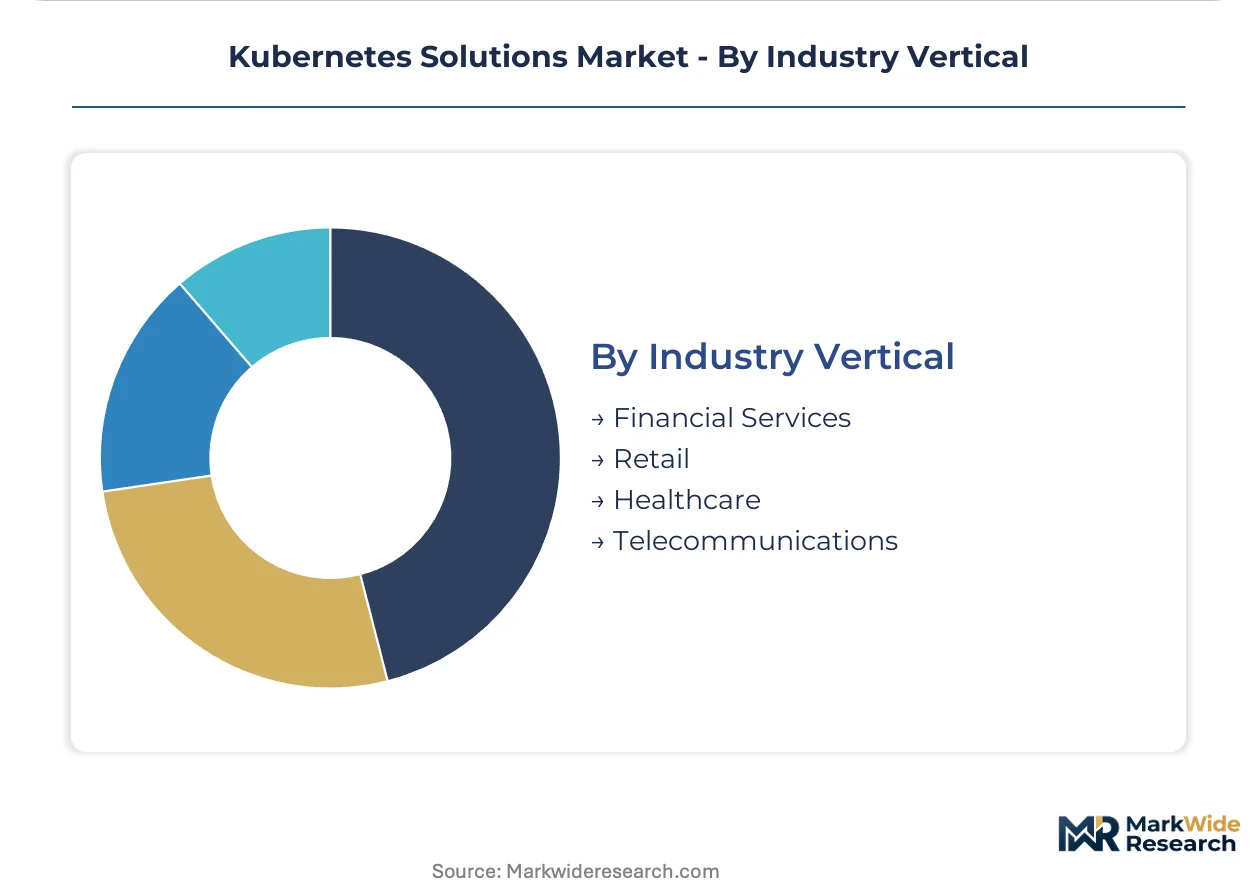
Financial Services dominates current spend, with Healthcare expanding most quickly under tightening algorithmic governance frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Container orchestration technology originated in Google's Borg and Omega systems before achieving commercial scale through the Kubernetes open-source release. The technology's diffusion pattern traces cloud infrastructure investment density, concentrating in economies with advanced hyperscaler penetration and regulated industrial bases requiring sovereign data control.
United States
Financial services modernization and defense classified workloads drive demand across the Federal Reserve banking system and Pentagon cloud contracts. NIST cybersecurity frameworks mandate zero-trust network policies and runtime security scanning for containerized workloads. Northern Virginia's data center corridor hosts the densest concentration of managed Kubernetes control planes, with Virginia-based contractors securing air-gapped deployments for intelligence community requirements.
Germany
Industrial manufacturers deploy sovereign cloud-native platforms to maintain data residency for factory-floor automation and automotive supply chains. The EU AI Act and national IT-SiG 2.0 cybersecurity law impose algorithmic transparency mandates and critical infrastructure protection standards. Bavaria's automotive engineering clusters around Munich and Ingolstadt lead K3s edge deployments, with Stuttgart-based suppliers building private container platforms for predictive maintenance systems.
United Kingdom
London's fintech ecosystem and NHS digital transformation programs generate dual demand streams for microservices architectures and clinical decision system orchestration. The UK National Cyber Security Centre publishes container security guidance aligning with ISO 27001 and emerging algorithmic governance standards. The Square Mile's banking cores drive application modernization timelines, with Edinburgh-based insurers adopting GitOps pipelines for regulatory reporting automation.
France
Healthcare networks and credit scoring institutions face CNIL inspections of Kubernetes API server logs for human-in-the-loop verification evidence. The EU AI Act's immutable audit trail requirements reshape deployment pipelines for diagnostic AI and automated lending decisions. Paris-based hospital systems implement private cloud configurations, while Toulouse's aerospace sector builds air-gapped platforms for defense export-controlled workloads.
Netherlands
Dutch banks invest in Falco runtime security and eBPF-based observability to satisfy De Nederlandsche Bank supervisory expectations for core banking containerization. GDPR audit mandates compel self-managed control planes with embedded compliance verification. Amsterdam's platform engineering talent concentration supports SRE team buildouts, with Eindhoven's semiconductor equipment manufacturers deploying hybrid configurations for intellectual property protection.
Kubernetes Solutions Market Competitive Environment
Premium-margin players sit above commodity-margin players across control plane abstraction depth and compliance automation sophistication. Hyperscaler-managed services capture volume through carbon-aware APIs and shared responsibility models, while self-managed specialists command consulting premiums in sovereign cloud deployments. Three archetypes dominate: hyperscale platforms with custom silicon integration, hybrid cloud enablers with multi-environment orchestration, and edge-focused lightweight distributors. Competitive moves concentrate on strategic partnerships with systems integrators and technology licensing for air-gapped defense variants.
Within the hyperscale platform tier, Amazon Elastic Kubernetes Service and Google Kubernetes Engine exemplify carbon-aware scheduling integration and public sector procurement pull-through. Red Hat OpenShift occupies a position anchoring hybrid cloud configurations for regulated industries with multi-environment policy synchronization requirements. These three entities represent distinct strategic postures: infrastructure abstraction at scale, developer experience optimization, and enterprise compliance enablement.
| Leading Market Players |
|---|
| Amazon Elastic Kubernetes Service |
| Azure Kubernetes Service |
| Red Hat OpenShift |
| Spectro Cloud |
| Rafay |
| Rancher |
| Google Kubernetes Engine |
| Mirantis |
| VMware Tanzu |
| Others |
Value Chain & Pricing Dynamics
EU AI Act audit mandates for automated decision systems are compelling financial services buyers to prioritize certified control plane configurations over commodity container orchestration, forcing hyperscalers to embed compliance tooling into premium service tiers and compressing margins on baseline managed offerings. This regulatory-driven procurement shift concentrates pricing power with vendors possessing pre-validated ISO 27001 and CNIL-aligned architectures while squeezing undifferentiated self-managed distribution channels.
Pricing Analysis
Three-tier pricing structure across enterprise premium, standard managed, and lightweight edge tiers dominates Kubernetes solutions, with differentiation anchored in control plane abstraction depth, embedded compliance automation, and carbon-aware scheduling API access. Price differentiation hinges on certification grade—ISO 27001, EU AI Act attestation, and NATO-aligned security clearance—and vertical integration of professional services attach rates. Cost compression in the standard managed tier is intensifying because hyperscalers are absorbing control plane operational overhead to capture volume, while German defense contractors and French healthcare networks exhibit lowest price sensitivity due to sovereign cloud mandates and patient data residency requirements.
Supply Chain Analysis
Certification and qualification gating through ISO 27001, GDPR, and EU AI Act compliance frameworks concentrates supply chain influence among hyperscalers with pre-validated shared responsibility models and specialized sovereign cloud integrators with national security clearances. Control plane software development centers on the United States, Germany, and the Netherlands, with hardware dependencies drawing from Taiwan semiconductor foundries and Intel custom silicon fabrication. Supply chain risk manifests as single-source vulnerability in certified administrator talent pools concentrated in Amsterdam and Berlin. Distribution runs through hyperscaler direct sales, systems integrator partnerships, and defense contractor prime-subcontractor arrangements for air-gapped deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kubernetes solutions function as a regulatory compounder where the EU AI Act's algorithmic governance mandates are accelerating procurement cycles for compliant container orchestration platforms across European financial services and healthcare verticals.
For Market Incumbents: Hedge against hyperscaler margin compression by deepening professional services attach rates in hybrid cloud configurations and acquiring boutique platform engineering consultancies with existing CNIL and BSI certifications. The threat of carbon-aware scheduling API commoditization by Google Cloud and AWS demands defensive certification investment in energy-efficient workload optimization tooling. For New Entrants and Emerging Players: EU AI Act implementation timelines in France and Germany open a window for sovereign cloud specialists offering air-gapped Kubernetes distributions with pre-built audit trail automation for credit scoring and diagnostic AI deployments. The most penetrable white-space sits with mid-market Italian manufacturers bypassing certified administrator scarcity through fully-managed edge orchestration, with go-to-market execution best anchored through Milan-based systems integrator partnerships. For Investors and Strategic Acquirers: Asymmetric upside sits with platform engineering consultancies possessing embedded compliance verification IP and existing relationships with Bundesamt für Sicherheit in der Informationstechnik. Long-term viability over the next decade favors acquisition targets with demonstrable revenue from NATO-aligned defense contracts and healthcare algorithmic governance implementations, with the critical inflection signal being accelerated public tender issuance weighting energy-efficient container density under EU Green Deal procurement frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Red Hat OpenShift's hybrid cloud anchoring enables multi-environment policy synchronization for regulated French healthcare networks. |
| Strategic Partnership | Google Kubernetes Engine's carbon-aware API integration pulls German public sector buyers toward managed container services procurement. |
| Acquisition of Specialist Firm | Boutique platform engineering consultancies with CNIL certifications command premium multiples in Paris and Frankfurt markets. |
| Geographic Expansion | Bavarian automotive clusters drive K3s edge deployment demand for factory-floor predictive maintenance orchestration. |
| Product Launch | eBPF-based Cilium service meshes replace Istio sidecars in London fintech microservices architectures, reducing operational overhead. |
Study Parameters
Coverage spans the United States, Germany, France, the United Kingdom, and the Netherlands, with primary inputs from each market combining structured interviews with platform engineering directors, Kubernetes SRE team leads, cloud procurement officers at financial institutions, healthcare CIOs managing diagnostic AI deployments, and defense contractor program managers responsible for air-gapped classified workloads. Secondary validation draws from hyperscaler capex disclosures, EU regulatory filings documenting AI Act implementation timelines, SEC 10-K infrastructure software segments, and hospital procurement database records of container platform investments. Bottom-up deployment volume estimates triangulate against top-down addressable market sizing across managed services, self-managed distributions, and professional services attach rates.
Granularity-level modeling disaggregates revenue across deployment type, service model, use case maturity, and industry vertical regulatory intensity, with additional dimensioning by organization size tier and regional cloud adoption pattern. CAGRs derive from regression analysis of historical hyperscaler Kubernetes revenue growth, sovereign cloud mandate implementation velocity, and banking core modernization project pipeline data. Industry-specific forecast inputs include EU AI Act audit requirement rollout schedules and German IT-SiG 2.0 critical infrastructure protection standard adoption curves.
Revisions become necessary when regulatory implementation timelines accelerate or delay, hyperscaler pricing architecture shifts materially, or sovereign cloud mandate scope expands beyond current defense and healthcare verticals. A model refresh is warranted upon material change in NATO member state defense procurement patterns for classified workload orchestration platforms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Change and Configuration Management Market
Digital Solutions
Middle East and Africa Digital Scent Technology Market
Digital Solutions
Service Fulfillment Market
Digital Solutions
Commercial P2P CDN Market
Digital Solutions
Product Lifecycle Management Consumer Packaged Goods and Retail (PLM Cpandr) Market
Digital Solutions
Global Digital Art Software Market
Digital Solutions
Construction Design App Market
Digital Solutions
Global Asset Reliability Software Market
Digital Solutions
Barcode Software Market
Digital Solutions
Electronic Data Interchange (EDI) Market
Digital Solutions
Canada Digital Twin Market
Digital Solutions
Cheque Scanner Market
Digital Solutions
Digital Manufacturing Market
Digital Solutions
AI Marketing Tool Market
Digital Solutions
Electronic Data Interchange [EDI] Solution Market
Digital Solutions
Global E-Filing Platforms Market