
 APAC Smart Office Market | 2026-2036
APAC Smart Office Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Smart Office Market Outlook
Multi-source procurement of IoT sensor arrays and edge computing hardware is repositioning how system integrators assemble smart office stacks. Huawei anchors its regional position through captive semiconductor design for building automation controllers. Schneider Electric leverages its Pacific Rim distribution network to sustain project-level competitiveness across Southeast Asian commercial developments. Siemens differentiates through IEC-compliant energy management software that integrates with legacy building infrastructure.
A smart office denotes a commercial workspace environment where interconnected sensor networks, automated environmental controls, and data-driven building management systems optimize energy consumption, occupant comfort, and operational security through real-time analytics and remote programmability. Lighting Control and HVAC Control product categories command the largest installed base due to immediate utility cost reduction, while Security Systems generates premium margins from biometric and AI-enhanced access platforms. Corporate Offices and Enterprises dominate end-user demand, with Co-Working Spaces representing the fastest-growing deployment segment as flexible workspace operators standardize on cloud-based building management across multi-site portfolios.
China's MIIT enforces GB standards for networked building equipment interoperability, while Japan's METI administers Top Runner efficiency benchmarks that directly shape HVAC and lighting procurement specifications. Australia's TGA-equivalent building regulator and South Korea's MFDS-aligned smart city frameworks add compliance layers for cross-border system vendors. Stakeholders must weigh cloud-versus-edge deployment architectures against each jurisdiction's data sovereignty requirements and evolving cybersecurity disclosure rules.
Market Dynamics
Corporate office adoption of integrated building management platforms is accelerating across APAC as China's dual carbon goals and Japan's METI energy efficiency mandates tighten building performance standards, forcing system integrators to reposition procurement strategies for IoT sensor arrays and edge computing hardware.
Growth Catalysts
- MIIT GB Standards:China's networked building equipment interoperability mandates are accelerating replacement cycles for legacy HVAC and lighting controllers in tier-one commercial hubs.
- Co-Working Space Standardization:Flexible workspace operators across Singapore and Australia are deploying cloud-based building management across multi-site portfolios, creating concentrated demand for unified platform architectures.
- Edge Computing Hardware:Real-time occupancy analytics and automated environmental controls are compressing deployment timelines for premium-grade smart building projects in Shanghai and Shenzhen.
Market Restraints
- Semiconductor Supply Concentration:Captive chip design capabilities concentrate among a limited set of system integrators, constraining hardware procurement flexibility for mid-tier commercial developments.
- Data Sovereignty Compliance Costs:Cross-border cloud-versus-edge deployment decisions must navigate Australia's TGA-equivalent building regulator requirements alongside South Korea's MFDS-aligned smart city frameworks.
- Legacy Infrastructure Lock-In:IEC-compliant energy management software integration with aging building systems extends project timelines and inflates customization costs for retrofit installations.
Strategic Opportunities
- Southeast Asian Commercial Developments:Vietnam and Indonesia's emerging commercial construction pipelines remain underpenetrated for integrated building automation, offering first-mover positioning for platform vendors.
- Biometric Access Convergence:AI-enhanced security platforms are merging with occupancy analytics, opening premium-margin service layers in Japan's financial district office towers.
- Top Runner Efficiency Benchmarks:METI's procurement specifications for HVAC and lighting equipment are creating regulatory tailwinds for vendors with pre-certified product portfolios.
Industry Challenges
- Cybersecurity Disclosure Rules:Evolving data protection requirements across multiple APAC jurisdictions are extending compliance timelines and fragmenting platform certification pathways.
- Integration Skill Scarcity:System integrators face acute shortages of technicians capable of bridging legacy building infrastructure with modern IoT sensor networks and cloud-based management interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Smart Office Market |
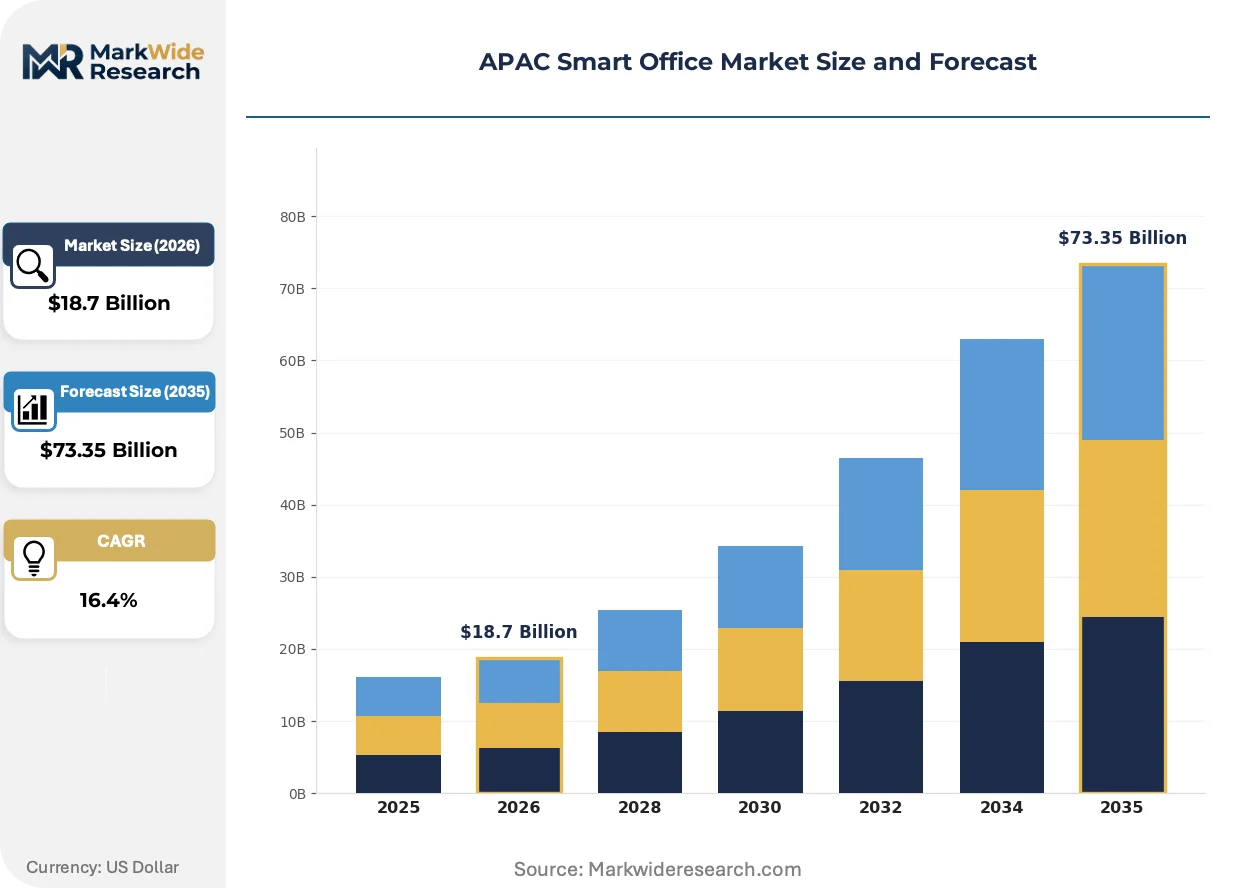
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lighting Control, Smart Thermostats, Security Systems, HVAC Control End User: Corporate Offices, Co-Working Spaces, SMEs, Enterprises Technology: IoT, Cloud Computing, Artificial Intelligence, Automation Deployment: On-Premise, Hybrid, Cloud-Based, Edge Computing |
| Companies Covered | Honeywell, Philips Lighting, Johnson Controls, Huawei, ABB, Siemens, Cisco Systems, Panasonic, Schneider Electric, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Smart Office Market Strategic Shifts
Interconnected sensor networks and automated environmental controls are actively reshaping how commercial workspaces optimize energy consumption and occupant comfort, with three distinct forces compressing technology adoption cycles and reconfiguring competitive positioning across the region.
Digital twin platforms for building performance simulation are integrating real-time sensor feeds with predictive HVAC load balancing algorithms. Large-scale corporate headquarters in Singapore and Sydney are deploying these systems at accelerated paces to meet sustainability disclosure requirements. This convergence is integrating previously siloed facility management functions into unified command interfaces that compress operational decision latency.
METI's Top Runner program and China's dual carbon implementation frameworks are mandating granular energy consumption reporting for commercial buildings exceeding specified floorplates. These policies are forcing procurement specification rewrites across Japan's property development sector and China's state-owned enterprise real estate portfolios. Premium-grade new construction in Osaka and Beijing is responding by specifying IEC-compliant energy management software as baseline architectural requirements.
Building-as-a-service contracting models are displacing traditional capital expenditure approaches for smart office technology deployment. Flexible workspace operators and enterprise real estate teams in Melbourne and Kuala Lumpur are favoring subscription-based platform access over hardware ownership. This shift is most visible in co-working space expansions where multi-site portfolio standardization demands predictable operational technology costs rather than lumpy infrastructure investments.
APAC Smart Office Market Segmentation
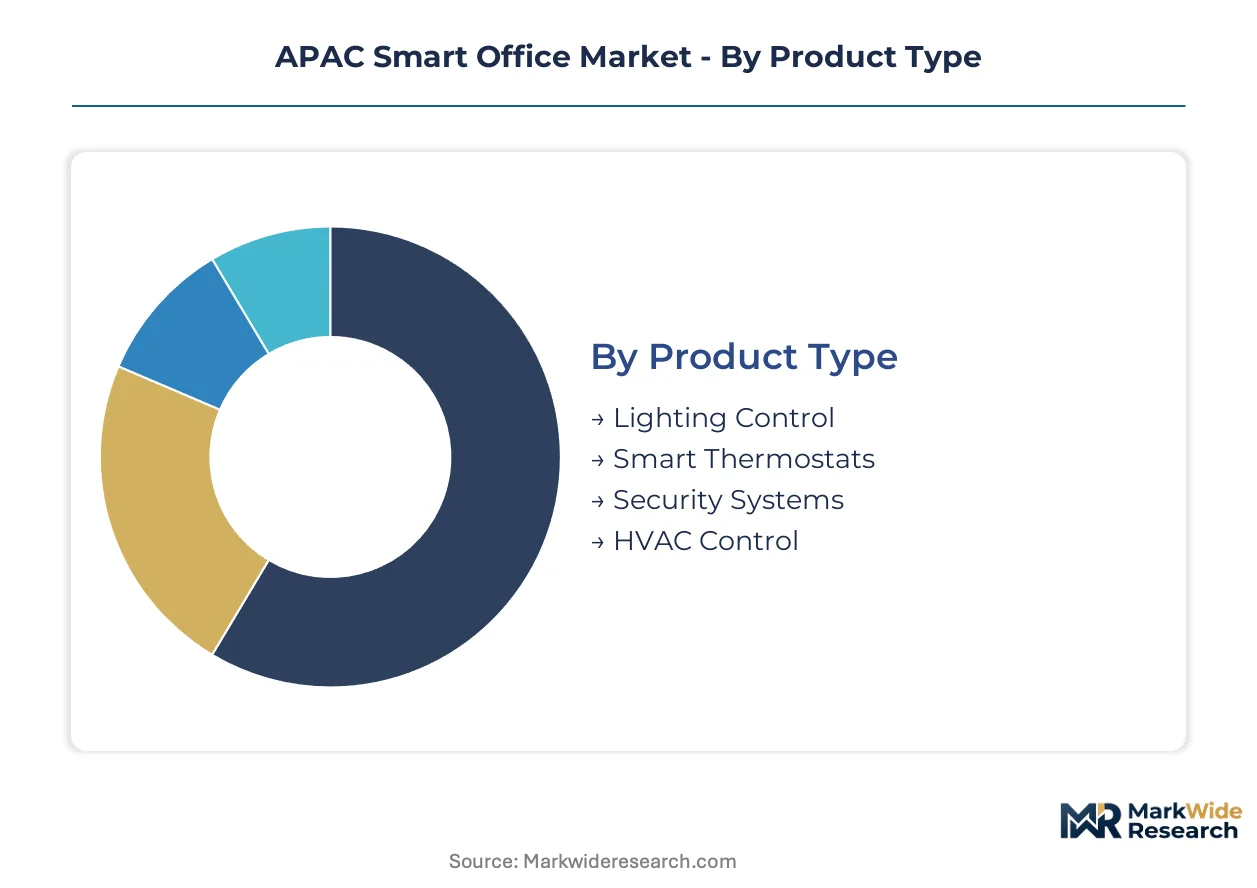
Smart office procurement patterns diverge sharply between cost-driven utility retrofits and premium new-build specifications. Understanding these segment boundaries clarifies where platform vendors can defend margin positions versus where volume aggregation strategies dominate.
Product Type:
Volume concentrates in environmental controls with immediate payback visibility. Premium margins accrue to security platforms with AI-enhanced differentiation.
- Lighting Control:Occupancy-responsive LED dimming and daylight harvesting systems reduce commercial electricity loads. Demand clusters in China's tier-one commercial hubs where MIIT GB standards mandate networked interoperability for new construction.
- HVAC Control:Zone-level climate management with predictive load balancing commands the largest installed base. Japan's METI Top Runner benchmarks directly shape procurement specifications for equipment replacement cycles in Osaka and Tokyo financial districts.
- Smart Thermostats:Individual workspace temperature adjustment interfaces with centralized building management. SME deployments across Southeast Asia favor these entry-level retrofit solutions.
- Security Systems:Biometric access and AI-enhanced surveillance platforms generate premium service layers. Financial district office towers in Singapore and Sydney specify these for compliance with evolving cybersecurity disclosure frameworks.
Mature deployment sits with HVAC Control. Newer deployment is concentrated in Security Systems.
End User:
Enterprise procurement favors unified platform architectures. Flexible workspace operators prioritize multi-site standardization over feature depth.
- Corporate Offices:Single-tenant headquarters with dedicated facility management teams demand deep customization. Australia's TGA-equivalent building regulator requirements extend compliance timelines for these complex installations.
- Enterprises:Multi-building portfolios with centralized real estate functions drive standardization mandates. Cloud-based building management adoption is climbing the fastest in this segment as operational technology costs shift from capital to operational budgets.
- Co-Working Spaces:Flexible workspace operators across Melbourne and Kuala Lumpur favor subscription-based platform access. Multi-site portfolio expansion demands predictable per-seat technology costs rather than lumpy infrastructure investments.
- SMEs:Smaller commercial tenants with limited facility management resources gravitate toward modular point solutions. Entry-level IoT sensor deployments in Vietnam and Indonesia target this price-sensitive tier.
Deployment maturity clusters with Corporate Offices. Expansion velocity is highest in Co-Working Spaces.
Technology:
Edge architectures are gaining share fastest where latency constraints matter. Cloud concentration dominates where multi-site visibility is paramount.
- IoT:Distributed sensor networks for occupancy, air quality, and energy monitoring form the physical layer. Procurement of these arrays is repositioning how system integrators assemble smart office stacks across the region.
- Cloud Computing:Centralized data aggregation with remote programmability enables portfolio-level management. South Korea's MFDS-aligned smart city frameworks add compliance layers for cross-border cloud deployments.
- Artificial Intelligence:Predictive analytics for HVAC load balancing and anomaly detection in security feeds. Premium-grade new construction in Beijing and Shanghai specifies AI-enhanced platforms as baseline architectural requirements.
- Automation:Rule-based environmental control without machine learning components. Legacy building retrofits in Japan's aging commercial stock rely on these proven, lower-complexity systems.
Established deployment rests with Automation. Steepest expansion trajectory belongs to Artificial Intelligence.
Deployment:
Data sovereignty requirements are fragmenting cloud-versus-edge decisions across jurisdictions. Hybrid architectures are emerging as the compromise default.
- On-Premise:Local server infrastructure with no external data transmission. Financial institutions in Tokyo and Singapore specify these for sensitive biometric access data.
- Cloud-Based:Fully externalized processing with browser-based management interfaces. Co-working space operators standardize on these for rapid multi-site provisioning.
- Edge Computing:Local processing at sensor gateways with selective cloud synchronization. Real-time occupancy analytics in Shanghai and Shenzhen compress deployment timelines for premium projects.
- Hybrid:Tiered architecture with time-critical functions local and archival analytics cloud-resident. Australia's data sovereignty requirements and South Korea's smart city frameworks push integrators toward this middle path.
Concentrated legacy deployment remains On-Premise. Fastest adoption velocity is in Hybrid configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the largest share of smart office procurement volume, with tier-one commercial hubs driving premium-grade deployments. Japan and South Korea follow with regulatory-mandated efficiency retrofits. Southeast Asian markets remain underpenetrated for integrated building automation.
China
Shanghai and Shenzhen dominate new construction pipelines for premium-grade smart buildings. MIIT enforces GB standards for networked building equipment interoperability, accelerating replacement cycles for legacy HVAC and lighting controllers. State-owned enterprise real estate portfolios in Beijing specify IEC-compliant energy management software as baseline architectural requirements.
Japan
Tokyo and Osaka financial districts drive demand for AI-enhanced security platforms with biometric access integration. METI administers Top Runner efficiency benchmarks that directly shape HVAC and lighting procurement specifications. Aging commercial stock in Nagoya relies on proven automation systems for legacy building retrofits.
South Korea
Seoul Capital Area leads cloud-based building management adoption for multi-site enterprise portfolios. MFDS-aligned smart city frameworks add compliance layers for cross-border system vendors. Daejeon-Sejong corridor concentrates edge computing deployments for real-time occupancy analytics in government-backed developments.
Australia
Melbourne and Sydney favor subscription-based platform access over hardware ownership for flexible workspace expansions. TGA-equivalent building regulator requirements extend compliance timelines for complex corporate installations. New South Wales pushes hybrid cloud-edge architectures to satisfy data sovereignty mandates.
Singapore
Downtown commercial towers deploy digital twin platforms for building performance simulation at accelerated paces. Co-working space operators standardize on cloud-based building management across multi-site portfolios. Biometric access convergence with occupancy analytics opens premium-margin service layers in financial district developments.
APAC Smart Office Market Competitive Environment
Strategic partnerships dominate the current landscape as system integrators reposition procurement strategies for IoT sensor arrays and edge computing hardware. The vendor base clusters around three tiers: diversified industrial conglomerates with captive semiconductor capabilities, specialized building automation houses with Pacific Rim distribution networks, and cloud-native platform vendors targeting flexible workspace operators. Two competitive vectors define positioning: backward integration into chip design for controller hardware, and geographic expansion into Vietnam and Indonesia's emerging commercial construction pipelines.
Among diversified technology conglomerates, Huawei anchors the regional position through in-house semiconductor design for building automation controllers. Schneider Electric exemplifies the distribution-heavy archetype, leveraging Pacific Rim networks to sustain project-level competitiveness across Southeast Asian commercial developments. Siemens occupies a position within the standards-compliant tier, differentiating through IEC-aligned energy management software that integrates with legacy building infrastructure.
| Leading Market Players |
|---|
| Honeywell |
| Philips Lighting |
| Johnson Controls |
| Huawei |
| ABB |
| Siemens |
| Cisco Systems |
| Panasonic |
| Schneider Electric |
| Others |
Value Chain & Pricing Dynamics
China's dual carbon goals and Japan's METI Top Runner benchmarks gate qualified supply for premium-tier smart office deployments, forcing system integrators to source only from vendors with pre-certified product portfolios while compressing margins on economy-grade sensor arrays.
Pricing Analysis
Volume concentrates in HVAC and lighting controllers where project-based pricing dominates, while premium margins accrue to AI-enhanced security platforms with biometric differentiation. Price differentiation rests on IEC certification tier and after-sales service bundling. Pricing pressure stems from semiconductor supply concentration constraining hardware procurement flexibility. SME deployments across Vietnam and Indonesia exhibit acute price sensitivity, whereas financial district towers in Singapore and Tokyo absorb premium positioning.
Supply Chain Analysis
China's MIIT GB standards and South Korea's local-content preferences for smart city frameworks are reshaping sourcing decisions for edge computing hardware and IoT sensor arrays. Manufacturing concentrates in China, South Korea, and Taiwan for controller semiconductors and sensor modules. Component dependencies include silicon wafers, rare earth elements for sensor magnets, and specialized HVAC compressor electronics. Single-source vulnerability runs through captive chip design capabilities at diversified conglomerates. Distribution runs through Pacific Rim project integrators with direct relationships to commercial developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-based building management platforms are displacing legacy automation systems across APAC flexible workspace portfolios, compressing technology refresh cycles and repositioning vendor competitive dynamics.
For Market Incumbents: To counter cloud-native platform vendors capturing co-working space subscriptions, deepen backward integration into edge computing chip design and expand certification investment for China's evolving GB standards. Prioritize channel control through captive distribution networks across Southeast Asian commercial developments. For New Entrants and Emerging Players: AI-enhanced occupancy analytics offers a technology-first wedge for penetrating Japan's financial district retrofit market and Vietnam's emerging commercial construction pipeline. Target subscription-based service models for multi-site portfolio standardization in Melbourne and Kuala Lumpur. For Investors and Strategic Acquirers: METI's tightening Top Runner procurement specifications are the leading indicator that pre-certified HVAC and lighting vendors will command sustained premium positioning. Within a multi-year viability window, acquisition targets should exhibit backward integration into controller hardware and established Pacific Rim distribution. Watch for cybersecurity disclosure rule harmonization across Australia and South Korea as the signal for platform consolidation readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Hardware Integration | Local processing at sensor gateways satisfies South Korea's MFDS-aligned data sovereignty requirements for government-backed developments. |
| Biometric Access Platform Launch | AI-enhanced security convergence with occupancy analytics opens premium-margin service layers in Singapore's financial district towers. |
| Pacific Rim Distribution Expansion | Direct project relationships in Vietnam and Indonesia secure first-mover positioning in underpenetrated commercial construction pipelines. |
| IEC Certification Investment | Pre-certified energy management software qualifies vendors for China's state-owned enterprise real estate procurement mandates. |
| Hybrid Cloud-Edge Architecture Deployment | Tiered processing satisfies Australia's TGA-equivalent data sovereignty requirements while enabling multi-site portfolio visibility. |
Study Parameters
Independent corroboration across facility management directors, system integration specialists, commercial real estate procurement officers, and cloud platform engineers underwrites the qualitative findings. Secondary validation draws from MIIT GB standard filings, METI Top Runner equipment registrations, SEC disclosures by listed building automation vendors, and Pacific Rim commercial construction permit databases. Bottom-up project pipeline enumeration triangulates against top-down spending estimates from enterprise real estate budgets.
Rate-of-change decomposition separates replacement cycle acceleration from new-build penetration across the projection horizon. Segmentation dimensions modeled include product category, end-user archetype, deployment architecture, and regional regulatory cluster. CAGRs derive from fitted adoption curves calibrated to policy mandate timelines and technology cost trajectories. Forecast inputs incorporate semiconductor supply lead times and evolving cybersecurity disclosure rule implementation schedules.
Several conditions sit outside the modeled scope, including macroeconomic disruptions to commercial construction financing, geopolitical fracture of cross-border cloud service provision, and unanticipated technology substitution beyond the cloud-edge continuum. Forecasts reflect documented assumptions regarding policy implementation fidelity and supply chain normalization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Demand Signal Repository Solutions Market
Digital Solutions
Ad Intelligence Software Market
Digital Solutions
Global Handwriting Digital Pen Market
Digital Solutions
Self-Service Kiosk Market
Digital Solutions
GCC and Africa ICT Market
Digital Solutions
North America Digital Pen Market
Digital Solutions
Australia Digital Twin Market
Digital Solutions
Green IT Services Market
Digital Solutions
Smart Signage Market
Digital Solutions
Asia-Pacific Digital Twin Market
Digital Solutions
Community Forum Market
Digital Solutions
Big Data As a Service (Bdaas) Market
Digital Solutions
Commodity Supply Chain Management Solution Market
Digital Solutions
Cloud Based Manufacturing Market
Digital Solutions
Digital Business Support System Market
Digital Solutions
Ticketing Solution Market