
 Drone Mapping Software for Agriculture Market | 2026-2036
Drone Mapping Software for Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Mapping Software for Agriculture Market Insights
Centimeter-grade accuracy is bifurcating the competitive landscape into survey-precision and operational-efficiency tiers. Pix4D leverages its photogrammetry engine to dominate high-accuracy mapping contracts for agronomic research institutions. DroneDeploy sustains a cloud-first platform strategy that extends real-time field analytics to cooperative-scale deployments across multiple growing regions.
Drone mapping software for agriculture comprises photogrammetric processing engines that convert multi-spectral and RGB imagery captured by unmanned aerial vehicles into georeferenced orthomosaics, digital elevation models, and vegetation index maps with sub-decimeter ground sampling distance. These platforms serve the primary commercial purpose of converting raw aerial imagery into actionable agronomic intelligence for variable-rate input application and field-level decision support. Cloud-based deployment leads the architecture mix by enabling elastic processing of large image datasets without local GPU infrastructure, while crop monitoring applications command the strongest margin pools due to recurring subscription attach rates and integration demands with farm management information systems. Yield prediction modules represent the fastest-expanding segment category as insurers and commodity traders seek independent verification of production forecasts prior to harvest settlement.
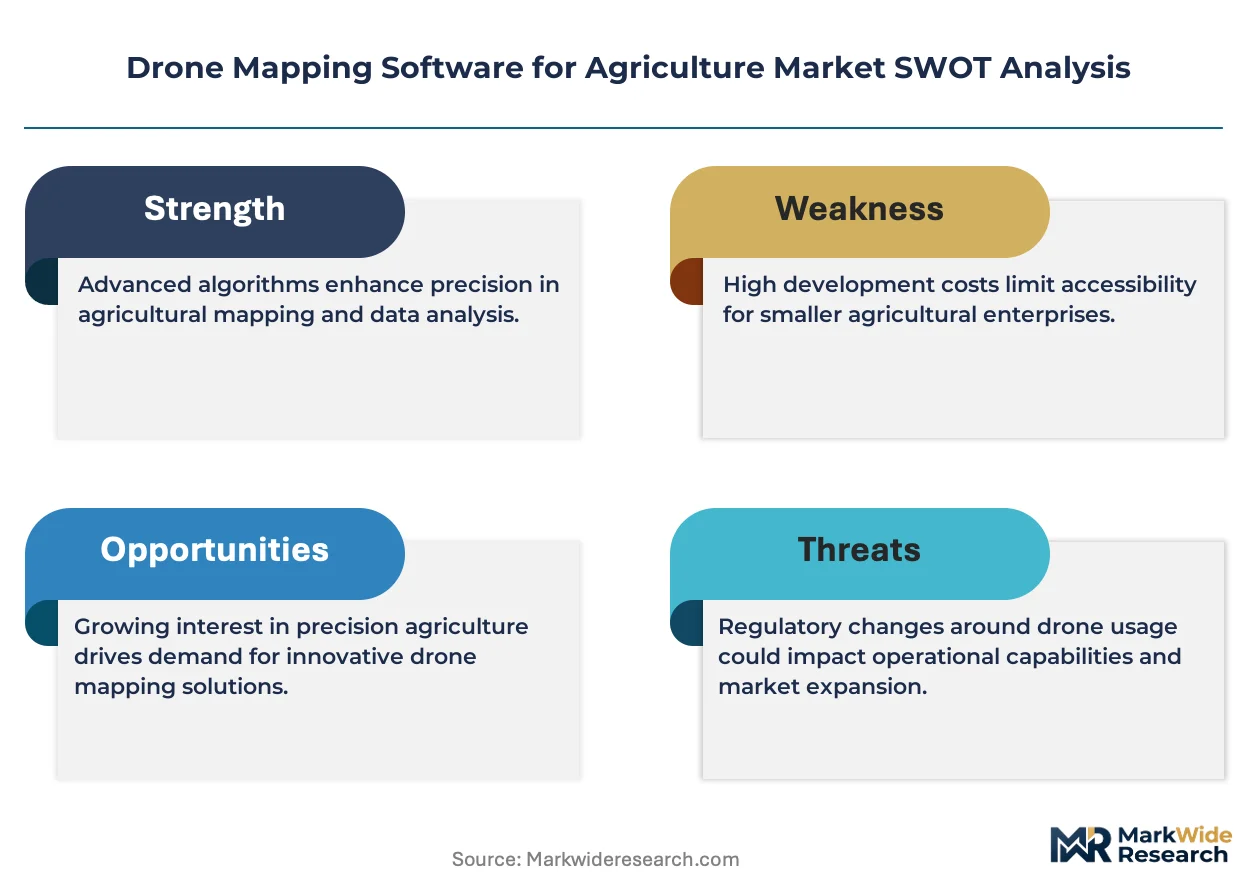
The FAA governs commercial drone operations through Part 107 certification requirements that mandate pilot qualifications and operational limitations for agricultural surveying missions, while the EASA U-space framework establishes standardized airspace integration protocols affecting cross-border service scalability in European farming corridors. Brazil's ANAC and ANVISA jointly oversee aerial application compliance, creating a dual-track regulatory environment that shapes product localization requirements for software vendors entering Latin American markets. Stakeholders must monitor evolving beyond-visual-line-of-sight rulemakings and data sovereignty mandates as these will determine which platform architectures achieve regulatory clearance for autonomous large-field mapping operations.
Market Dynamics
Centimeter-grade photogrammetry accuracy is splitting vendor positioning into survey-precision and operational-efficiency tiers, forcing platform providers to choose between research-institution contracts and cooperative-scale farm deployments.
Growth Catalysts
- Large-scale commercial farming:Soybean and sugarcane producers in Brazil are scaling drone-based field analytics for variable-rate input application.
- FAA Part 107 framework:Pilot certification requirements for commercial agricultural surveying missions are standardizing operational protocols across US farming corridors.
- Cloud-based deployment architecture:Elastic processing of large image datasets without local GPU infrastructure is lowering entry barriers for mid-sized agricultural cooperatives.
Market Restraints
- Regulatory fragmentation:Brazil's ANAC and ANVISA dual-track aerial application compliance creates localization burdens for software vendors entering Latin American markets.
- Data sovereignty mandates:Cross-border service scalability in European farming corridors faces friction from evolving EASA U-space airspace integration protocols.
- Beyond-visual-line-of-sight limitations:Pending rulemakings for autonomous large-field mapping operations delay regulatory clearance for fully autonomous platform architectures.
Strategic Opportunities
- Yield prediction modules:Insurers and commodity traders seek independent verification of production forecasts prior to harvest settlement, creating recurring revenue attach rates.
- EU U-space regulatory tailwind:Standardized airspace integration protocols will eventually enable cross-border service scalability for vendors with compliant platform architectures.
- Farm management information system integration:Crop monitoring applications with recurring subscription models are deepening integration demands with legacy agricultural ERP systems.
Industry Challenges
- Photogrammetry expertise gap:Multi-spectral imagery processing and vegetation index calibration require specialized agronomic data science skills scarce in rural service territories.
- Certification timeline compression:FAA Part 107 pilot qualification requirements and recurrent testing create operational bottlenecks for seasonal agricultural surveying windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Mapping Software for Agriculture Market |
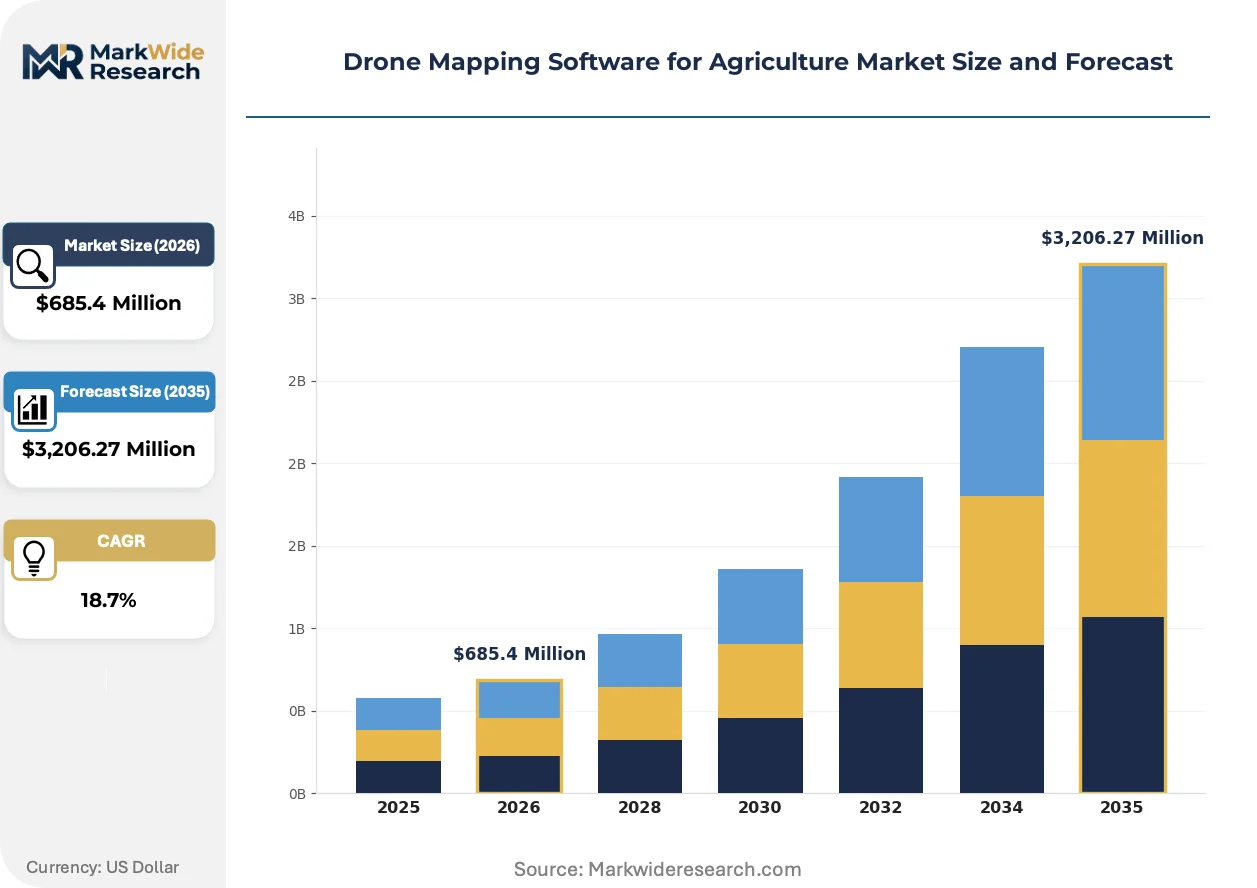
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $3,206.27 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Data Analytics, Crop Monitoring, Soil Analysis, Yield Prediction Deployment: Cloud-Based, On-Premises, Hybrid, Mobile End User: Farmers, Agronomists, Agricultural Researchers, Cooperatives Application: Irrigation Management, Pest Control, Crop Health Assessment, Land Mapping |
| Companies Covered | Pix4D, DroneDeploy, Agremo, DJI Terra, Agisoft Metashape, Skippy Scout, WEZOM, Drone Nerds, Pix4Dfields, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Mapping Software for Agriculture Market Trends and Innovations
Real-time field analytics and edge-computing architectures are compressing the decision cycle between image capture and agronomic intervention, reshaping how precision agriculture platforms deliver value.
Real-time kinematic positioning is bifurcating the accuracy-performance landscape. Survey-grade GNSS correction services enable sub-decimeter ground sampling distance for agronomic research institutions demanding georeferenced orthomosaic precision. Operational-efficiency tier platforms sacrifice absolute accuracy for cloud-processing speed, targeting cooperative-scale deployments where relative vegetation health mapping suffices. The structural consequence is compressing mid-tier vendors into uncomfortable positioning between these diverging performance specifications.
EASA U-space framework implementation is reshaping European operational compliance. Standardized airspace integration protocols mandate detect-and-avoid capabilities and remote identification systems for agricultural UAV corridors. Cross-border service providers in the Netherlands, France, and Germany are consolidating platform architectures to meet unified certification requirements, displacing country-specific operational variations that previously fragmented vendor roadmaps.
Subscription unbundling from hardware bundles is altering procurement patterns among agricultural cooperatives. Buyers increasingly separate drone platform acquisition from software analytics licensing, favoring modular cloud subscriptions over perpetual licenses tied to specific UAV manufacturers. This pattern concentrates in Brazilian soybean operations and US Midwest grain cooperatives, where seasonal usage patterns make fixed-cost software ownership economically inefficient.
Drone Mapping Software for Agriculture Market Segmentation
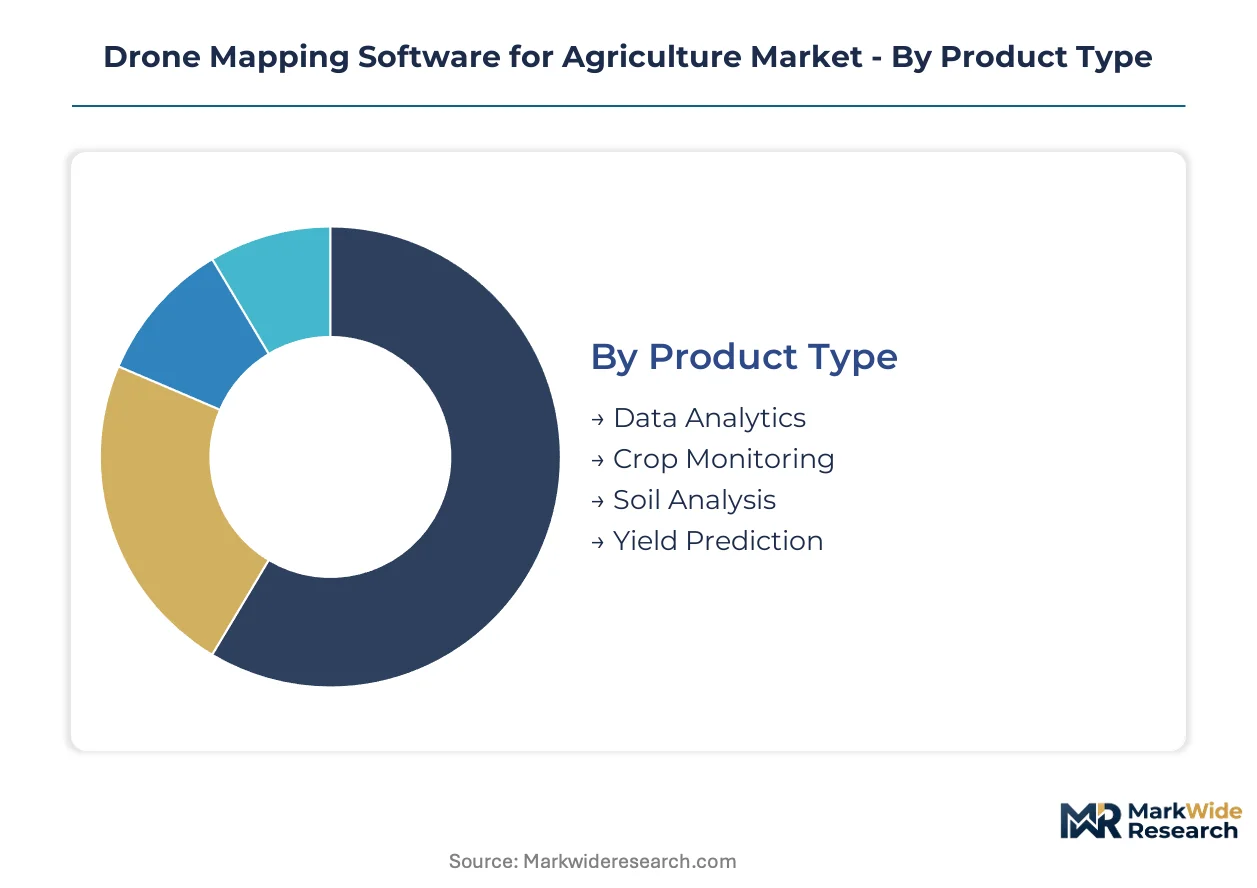
Segmentation in drone mapping software reflects divergent buyer capabilities and operational scales. Platform providers must architect pricing and feature tiers around deployment infrastructure, user sophistication, and application criticality rather than treating agriculture as a monolithic vertical.
Product Type:
Crop Monitoring commands dominant deployment volumes across Brazilian soybean belts and US Midwest grain regions, while Yield Prediction attracts speculative investment from commodity trading desks. Data Analytics and Soil Analysis serve more fragmented, research-intensive demand patterns concentrated in university extension networks and precision agriculture consultancies.
- Crop Monitoring:Multi-spectral vegetation index processing with sub-decimeter ground sampling distance enables real-time field health mapping. Brazilian sugarcane cooperatives and US corn-soybean operations deploy this for variable-rate nitrogen application, driving recurring subscription attach rates with farm management information systems.
- Yield Prediction:Machine learning models integrate historical yield data with real-time imagery to forecast production volumes pre-harvest. Commodity traders and crop insurers in Chicago and São Paulo underwriting desks purchase independent verification services to price futures contracts and revenue protection policies.
- Data Analytics:Photogrammetric processing engines convert raw UAV imagery into georeferenced orthomosaics and digital elevation models for agronomic research institutions.
- Soil Analysis:Terrain modeling and moisture mapping applications support irrigation infrastructure planning in arid growing regions.
Crop Monitoring holds the largest share; momentum sits with Yield Prediction as financial institutions seek production transparency.
Deployment:
Cost tier differentiation separates enterprise-grade cloud elasticity from constrained infrastructure environments. Cloud-Based deployment eliminates local GPU capital expenditure for mid-sized cooperatives, while On-Premises installations persist in data-sensitive research contexts and regions with unreliable connectivity.
- Cloud-Based:Elastic processing architectures handle terabyte-scale imagery datasets without client-side hardware investment. The model dominates Brazilian agricultural cooperatives and US Midwest grain elevators where seasonal surge capacity outweighs data sovereignty concerns.
- On-Premises:Local GPU clusters process imagery within institutional firewalls, satisfying university research data governance requirements and Chinese agricultural stations operating under data localization mandates.
- Hybrid:Edge preprocessing with cloud refinement balances latency sensitivity against computational depth for large-field operations.
- Mobile:Tablet-native analytics support in-field decision validation by agronomists without returning to office infrastructure.
Cloud-Based deployment captures the greatest volume; Hybrid architectures are climbing the fastest as BVLOS autonomy requirements evolve.
End User:
Customer type stratification mirrors technology sophistication and procurement authority concentration. Cooperatives aggregate fragmented farmer demand into enterprise-scale contracts, while Agricultural Researchers validate platform accuracy for downstream commercial adoption.
- Cooperatives:Member-owned grain and sugarcane operations in Brazil's Mato Grosso and US Iowa pool capital for fleet-scale drone deployments and centralized analytics subscriptions. Procurement committees negotiate multi-year platform licenses with volume-tiered pricing.
- Agricultural Researchers:University extension services and USDA ARS stations demand survey-grade photogrammetry precision for peer-reviewed agronomic studies, accepting higher per-acre processing costs for methodological reproducibility.
- Farmers:Individual operators purchase modular subscriptions scaled to acreage tiers, with seasonal activation patterns.
- Agronomists:Independent crop consultants license platforms to deliver variable-rate recommendations as a billable service.
Cooperatives hold the largest share; Agricultural Researchers are gaining share fastest as validation requirements intensify for insurance-linked yield forecasting.
Application:
Application segmentation tracks input timing and economic leverage points in the growing cycle. Irrigation Management delivers immediate water cost savings in drought-prone regions, while Land Mapping underpins multi-year field infrastructure investment decisions.
- Irrigation Management:Thermal and multi-spectral imagery identifies moisture stress patterns before visible crop damage, enabling precision variable-rate irrigation in California Central Valley almond orchards and Australian Murray-Darling Basin cotton operations.
- Crop Health Assessment:Vegetation index trending detects nutrient deficiencies, disease pressure, and pest infestations for targeted intervention. Brazilian soybean producers deploy weekly flight schedules during critical reproductive growth stages.
- Pest Control:Early-stage infestation mapping supports targeted pesticide application, reducing chemical volume and resistance pressure.
- Land Mapping:Topographic and boundary survey applications support drainage tile installation and field consolidation investments.
Crop Health Assessment holds the largest share; Irrigation Management shows the steepest expansion trajectory as water scarcity intensifies in major growing basins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian soybean and sugarcane exports to Asian protein markets are accelerating precision agriculture adoption across South American growing corridors. Demand concentration in Mato Grosso and São Paulo is reshaping software localization requirements for drone mapping vendors.
United States
Midwest grain cooperatives in Iowa and Illinois are deploying cloud-based analytics for variable-rate nitrogen application across corn-soybean rotations. FAA Part 107 certification requirements standardize pilot qualifications for seasonal surveying windows. Chicago commodity trading desks purchase yield prediction services to price futures contracts ahead of harvest settlement.
Brazil
Sugarcane processors in São Paulo state and soybean mega-farms in Mato Grosso scale fleet-based field analytics for input optimization. ANAC and ANVISA dual-track aerial application compliance creates localization burdens for foreign software entrants. Piracicaba agritech clusters host validation partnerships between mapping platforms and cooperative procurement committees.
Germany
Precision viticulture in Rhineland-Palatinate and large-scale arable farming in Lower Saxony drive demand for survey-grade photogrammetry. EASA U-space framework implementation mandates detect-and-avoid capabilities for agricultural UAV corridors. Munich-area research institutions validate vegetation index calibration protocols for downstream commercial adoption.
Australia
Murray-Darling Basin cotton operations and Western Australia wheat belts deploy thermal imagery for irrigation stress mapping under water scarcity constraints. Civil Aviation Safety Authority regulations govern beyond-visual-line-of-sight permissions for large-station properties. Toowoomba agritech hubs connect drone service providers with export-oriented grain cooperatives.
China
Xinjiang cotton plantations and Northeast China corn belts adopt domestic mapping platforms under data localization requirements. MIIT standards and provincial agricultural modernization subsidies shape procurement patterns for state-affiliated farming enterprises. Nanjing and Hangzhou technology corridors host development clusters for multi-spectral processing engines.
Drone Mapping Software for Agriculture Market Competitive Landscape
Listed leaders compete with private specialists across cloud-processing scalability and photogrammetry accuracy dimensions. The vendor base separates into survey-precision tier providers targeting research institutions and operational-efficiency platforms serving cooperative-scale deployments. Three archetypes dominate: photogrammetry engine specialists, cloud-native SaaS platforms, and hardware-integrated software bundlers. Competitive moves concentrate on subscription unbundling from drone hardware and cross-border regulatory certification partnerships.
Within the photogrammetry engine tier, Pix4D and Agisoft Metashape exemplify survey-grade accuracy positioning for agronomic research validation requirements. DroneDeploy occupies a position representing cloud-first platform strategies extending real-time analytics to distributed cooperative deployments. DJI Terra anchors the hardware-integrated archetype where software licensing remains coupled to manufacturer drone ecosystems.
| Leading Market Players |
|---|
| Pix4D |
| DroneDeploy |
| Agremo |
| DJI Terra |
| Agisoft Metashape |
| Skippy Scout |
| WEZOM |
| Drone Nerds |
| Pix4Dfields |
| Others |
Pricing and Supply Chain Analysis
FAA Part 107 certification requirements gate both vendor qualification and price differentiation in agricultural drone mapping software, compressing margins for uncertified operators while enabling premium positioning for compliant platforms serving research institutions and large cooperatives.
Pricing Analysis
Cooperative-scale buyers anchor subscription pricing across three tiers: survey-grade photogrammetry for research institutions, operational-efficiency platforms for mid-sized farms, and modular cloud subscriptions for seasonal users. Price differentiation rests on certification level and integration depth with farm management information systems. Pricing pressure stems from subscription unbundling from hardware bundles, as Brazilian soybean cooperatives and US Midwest grain elevators favor modular SaaS licensing over perpetual licenses. Individual farmers and small agronomist consultancies exhibit highest price sensitivity, while agricultural researchers and commodity trading desks underwriting yield prediction services demonstrate lowest sensitivity due to methodological reproducibility requirements.
Supply Chain Analysis
Inventory cycles for GPU processing hardware and multi-spectral camera modules stretch 8-14 weeks during Northern Hemisphere planting seasons, compressing deployment windows for agricultural software vendors. Component sourcing concentrates in Taiwan for semiconductor fabrication, China for UAV airframe manufacturing, and Germany for precision optics. Raw material dependencies include rare earth elements for sensor calibration, lithium-ion cells for extended flight batteries, and high-purity silicon for photogrammetric processing chips. Single-source vulnerability sits with Taiwanese GPU foundries supplying cloud-processing infrastructure. Distribution runs through direct enterprise sales for research institutions, cooperative procurement committees for Brazilian and US agricultural aggregators, and OEM bundling arrangements with DJI and Autel drone manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Agricultural input cost cyclicality is driving precision agriculture investment recovery, as fertilizer price volatility from 2022-2023 peak levels pushes Brazilian and US farmers toward variable-rate application technologies that optimize input deployment.
For Market Incumbents: Fortify cloud-processing infrastructure investments against edge-computing challengers by expanding elastic capacity in São Paulo and Iowa data center regions. Deepen API integration with legacy farm management information systems to raise switching costs for cooperative subscribers. Prioritize EASA U-space compliance certification ahead of standardized European airspace integration protocols to preempt cross-border service scalability for competitors. For New Entrants and Emerging Players: FAA Part 107 certification fast-tracks for seasonal pilot networks unlock cooperative-scale deployment opportunities in US Midwest grain corridors with lower incumbent saturation. Target yield prediction modules for commodity trading desks and crop insurers in Chicago and São Paulo, where independent production verification commands premium pricing absent methodological standardization. Pursue white-label partnerships with established drone service providers rather than direct platform competition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native SaaS architectures as GPU-as-a-service models displace owned infrastructure, improving cash conversion metrics for platform vendors. Long-term viability favors vendors with regulatory certification moats spanning FAA, EASA, and Brazil's ANAC/ANVISA dual-track compliance. Monitor beyond-visual-line-of-sight rulemaking progress as the critical inflection signal for autonomous large-field mapping scalability and associated platform valuation expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Stack | Multi-jurisdiction FAA-EASA-ANAC compliance unlocks cross-border cooperative contracts in Brazil, Germany, and US Midwest corridors. |
| Farm Management System Integration | API partnerships with John Deere Operations Center and Climate FieldView raise subscription renewal rates among precision agriculture adopters. |
| Yield Prediction Module Development | Machine learning forecasting attracts commodity trading desk contracts from Chicago Board of Trade and São Paulo B3 exchange participants. |
| Edge Computing Architecture | On-drone preprocessing reduces cloud transmission costs for Australian and Brazilian large-station properties with limited connectivity. |
| Photogrammetry Accuracy Tiering | Survey-grade positioning captures USDA ARS and university extension validation contracts with methodological reproducibility requirements. |
Research Methodology
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings in this analysis. Primary fieldwork engaged agronomic research directors at USDA ARS stations, cooperative procurement committee members in Mato Grosso and Iowa, FAA-certified commercial drone pilots, platform engineering leads at cloud-native vendors, and commodity risk officers at Chicago trading desks. Secondary sources incorporated FAA Part 107 enforcement data, EASA U-space implementation timelines, ANAC aerial application compliance records, SEC filings from publicly traded precision agriculture technology providers, and Brazilian agricultural cooperative annual procurement disclosures. Bottom-up segmentation sizing triangulated against top-down market aggregation across deployment models, end-user categories, and application types.
Sensitivity analysis tested forecast robustness across alternative regulatory implementation scenarios for beyond-visual-line-of-sight autonomy permissions. The analytical framework modeled volume and value trajectories across product type, deployment architecture, end-user sophistication tier, and application timing in the growing cycle throughout the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macroeconomic agricultural input expenditure patterns. Industry-specific forecast inputs included seasonal flight hour constraints from FAA pilot certification bottlenecks and cloud-processing cost curves from hyperscaler infrastructure pricing disclosures.
Underlying assumptions cover sustained commodity price volatility driving precision agriculture ROI calculations, with deviation risk concentrated in regulatory timeline delays for autonomous mapping operations and data sovereignty mandate expansions affecting cross-border service architectures. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
UX Services Market
Digital Solutions
Global Logistics Software Market
Digital Solutions
Global Dock and Yard Management System Market
Digital Solutions
Asia-Pacific Digital Twin Market
Digital Solutions
Global Process Orchestration Market
Digital Solutions
Data Converter Market
Digital Solutions
OSS/BSS Market
Digital Solutions
Ad Intelligence Software Market
Digital Solutions
Global Product Design and Development Market
Digital Solutions
Product As a Service Market
Digital Solutions
Trade Management Software Market
Digital Solutions
Global Application Container Market
Digital Solutions
Game Engines Market
Digital Solutions
Online Home Service Market
Digital Solutions
Asia-Pacific Multichannel Order Management Market
Digital Solutions
India PLM Market