
 CNC Controller Market | 2026-2036
CNC Controller Market Size, Share, and Industry Trends Forecast 2026-2036
CNC Controller Market Intelligence
Demand from high-precision sectors like aerospace manufacturing and custom tooling is consolidating around controllers that offer multi-axis and simultaneous machining capabilities. FANUC Corporation dominates the high-volume machine tool segment with its integrated hardware and software ecosystem. Siemens AG competes on the basis of open architecture and enterprise-level system integration for smart factories. HEIDENHAIN GmbH specializes in high-precision measurement and control systems for the most demanding applications, particularly in Europe.
A CNC controller is the central processing unit of a computer numerical control machine, translating digital instructions into precise physical movements. These systems interpret G-code to direct axis motion, spindle speed, and tool changes with accuracy often measured in micrometers. Integrated controllers continue to gain share over standalone controllers in new machine builds due to simpler installation and maintenance. Within applications, aerospace manufacturing and precision molding command higher margins, reflecting their stringent tolerance and surface finish requirements.
Compliance with Europe's CE marking for machine safety and electromagnetic compatibility is a critical market access requirement for vendors. Global interoperability is guided by ISO standards for programming languages, while manufacturers in China must also adhere to specific GB standards for industrial equipment. Vendor selection will increasingly hinge on the ability to support open communication protocols and integrate with factory-wide data analytics platforms.
Market Dynamics
The imperative for factory-wide automation under Industry 4.0 frameworks is the central force shaping the CNC controller market. Demand for controllers that function as intelligent nodes within a networked production environment is concentrating in advanced manufacturing sectors seeking enhanced data exchange and process optimization.
Growth Catalysts
- Government Industrial Policy:Extensive support from China's government for industrial automation and robotics provides a direct stimulus for upgrading machine tools with advanced controllers, particularly in automotive and electronics manufacturing hubs.
- Aerospace Sector Requirements:The manufacturing of complex aerospace components from materials like titanium and composites necessitates controllers with superior multi-axis and simultaneous machining capabilities to meet stringent geometric tolerance and surface finish standards.
- Miniaturization in Electronics:The trend toward smaller, more complex consumer electronics and medical devices requires machine tools with higher precision and speed, a demand met by controllers offering sub-micron accuracy and advanced motion control algorithms.
Market Restraints
- High Capital Investment:The significant upfront cost of advanced 5-axis and multi-channel CNC controllers, along with associated software and training, presents a substantial barrier for small and medium-sized machine shops.
- Proprietary System Lock-in:End-users often face high switching costs and limited flexibility due to the proprietary nature of controller hardware and software ecosystems, hindering integration with third-party solutions and equipment.
- Semiconductor Supply Volatility:The reliance of CNC controllers on specialized microprocessors and FPGAs creates vulnerability to supply chain disruptions and price fluctuations within the global semiconductor market, impacting production schedules and costs.
Strategic Opportunities
- Additive Manufacturing Integration:The convergence of CNC machining with additive manufacturing in hybrid systems creates an opportunity for controllers that can manage both subtractive and additive processes within a single machine setup.
- Medical Device Manufacturing:Growth in the orthopedic and dental implant markets offers a high-margin application for precision controllers capable of machining complex, custom geometries from biocompatible materials like PEEK and titanium alloys.
- Emerging Economies' Industrialization:Manufacturing expansion in Southeast Asian nations like Vietnam and Thailand presents a new geographic frontier for controller sales as these countries build out their industrial and export capabilities.
Industry Challenges
- Skilled Labor Scarcity:A persistent shortage of qualified CNC programmers, machinists, and maintenance technicians capable of operating and servicing complex multi-axis machines limits the effective deployment of advanced controller technology.
- Legacy System Integration:Connecting new, data-intensive CNC controllers with older, disparate factory floor equipment and enterprise resource planning systems poses significant technical and software compatibility challenges for manufacturers.
- Cybersecurity Vulnerabilities:The increasing network connectivity of CNC machines for remote monitoring and data collection exposes them to cybersecurity threats, requiring vendors to address complex security protocols and potential production disruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CNC Controller Market |
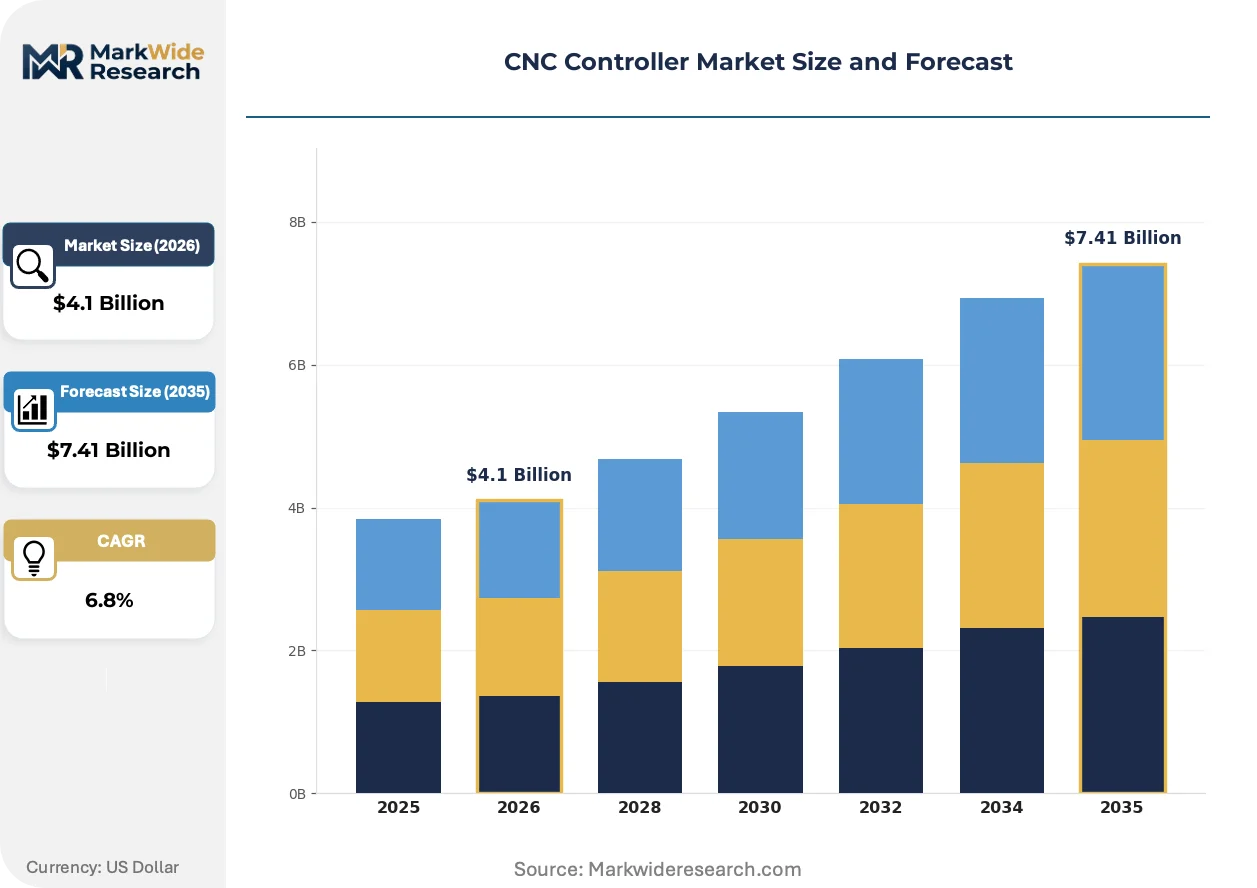
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Controllers, Integrated Controllers, Open-Architecture Controllers, Modular Controllers Technology: Lathe Control, Milling Control, Plasma Cutting, Wire EDM, 3D Printing Control Application: Metal Fabrication, Aerospace Manufacturing, Electronics Assembly, Custom Tooling, Precision Molding End User Industry: Machine Shops, Aerospace OEMs, Electronics Manufacturers, Plastic Molders, Fabrication Workshops |
| Companies Covered | HEIDENHAIN GmbH, Yaskawa Electric Corporation, Siemens AG, DMG Mori Co., Ltd., Okuma Corporation, FANUC Corporation, Bosch Rexroth AG, NUM AG, Mitsubishi Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CNC Controller Market Strategic Shifts & Innovations
The evolution from isolated machine operation to integrated, data-driven production systems is the defining theme in the market. Controller technology is advancing to support the requirements of smart factories, emphasizing connectivity, intelligence, and open communication standards.
Edge computing is a transformative technology enabling on-machine data processing. High-volume automotive and electronics manufacturers are adopting this to analyze sensor data in real time. Edge computing is integrating predictive maintenance algorithms and adaptive machining capabilities directly into the control loop, minimizing latency and improving process reliability without relying on cloud-based computation.
New cybersecurity regulations are reshaping product development. The European Union's proposed Cyber Resilience Act, for example, mandates stringent security features for connected devices, including industrial controls. This forces vendors to embed security-by-design principles, such as encrypted communications and access controls, into their controller architectures, particularly for systems used in critical infrastructure sectors.
A shift toward software and service-centric value propositions is altering purchasing decisions. End-users are increasingly evaluating controllers based on the accompanying software ecosystem, including CAM integration, simulation tools, and digital twin capabilities. This trend is most apparent in high-mix job shops in Germany and the United States, where software flexibility is critical for rapid changeovers.
CNC Controller Market Segmentation
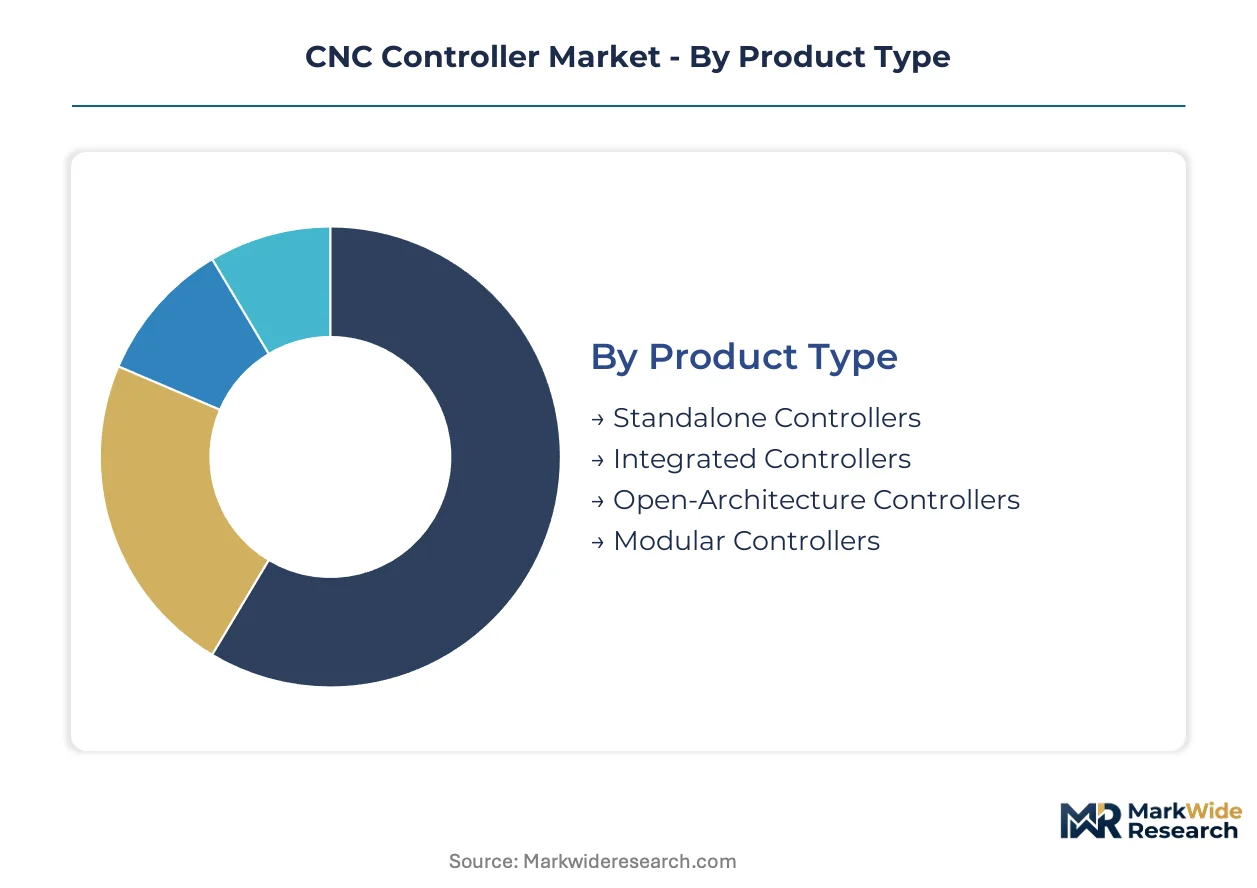
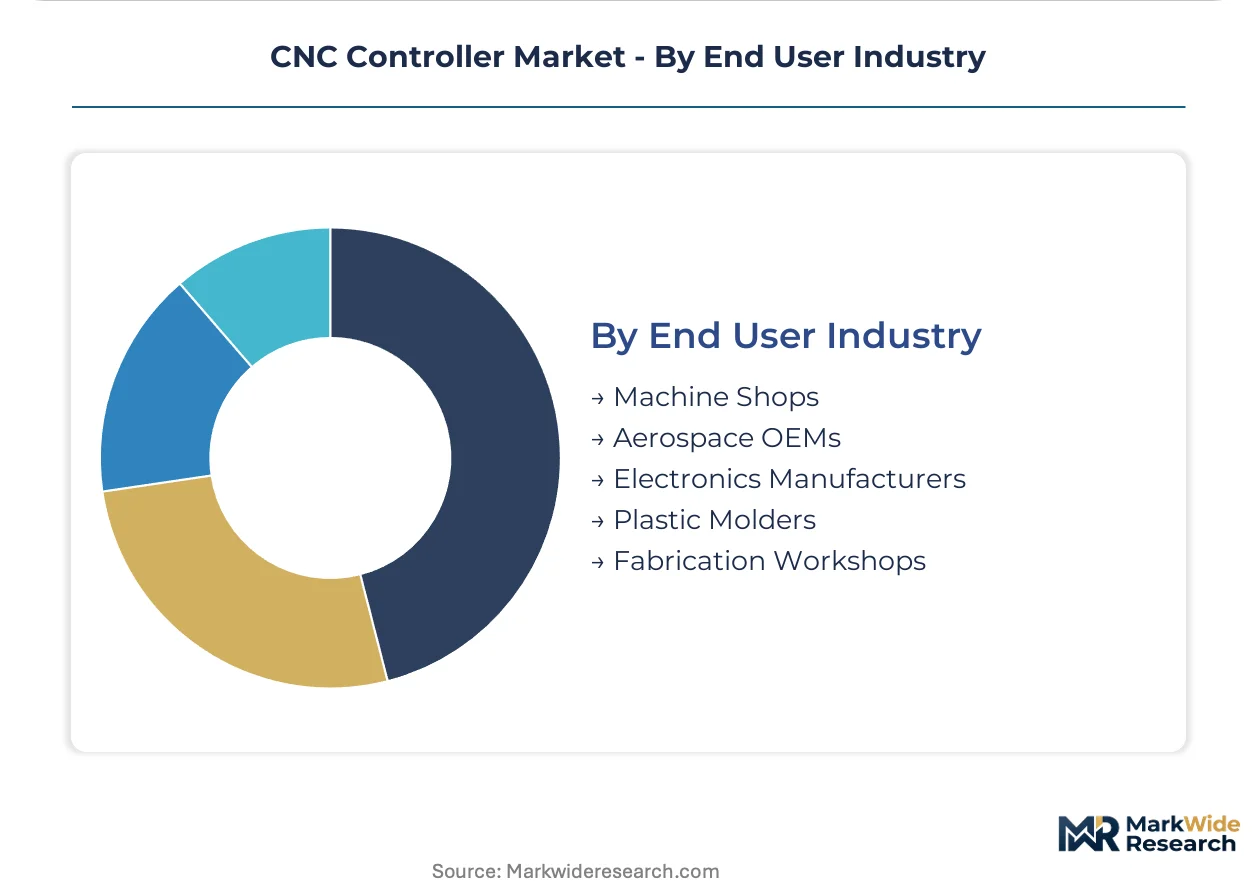
The CNC controller market segments across various dimensions, reflecting the diverse operational requirements and technological sophistication within manufacturing. Understanding these distinctions helps delineate demand patterns and the competitive positioning of different controller solutions.
Product Type:
The product type segmentation differentiates controllers by their level of integration and architectural flexibility within machine tool systems.
- Integrated Controllers:These systems combine hardware and software into a single unit, simplifying machine design and maintenance. Demand concentrates in new machine builds across China, driven by government support for industrial automation.
- Open-Architecture Controllers:These offer flexible programming interfaces and allow third-party software integration, facilitating custom solutions. Advanced manufacturing sectors in Germany increasingly adopt these for smart factory initiatives.
- Standalone Controllers:These units operate independently, often retrofitted to existing machinery for basic automation.
- Modular Controllers:These systems allow for configurable hardware and software components, enabling scalability for various machine functions.
Standalone Controllers lead volumes today; Integrated Controllers are gaining share fastest.
Technology:
Technology segmentation highlights the specific machining processes controllers are designed to manage, reflecting varied precision and operational demands.
- Milling Control:These controllers manage multi-axis material removal processes, essential for complex part geometries in aerospace manufacturing. Demand is high in aerospace manufacturing hubs for producing intricate components.
- 3D Printing Control:These systems orchestrate additive manufacturing processes, building parts layer by layer with high precision. Medical device manufacturing increasingly utilizes these controllers for custom implants.
- Lathe Control:These controllers manage rotational machining operations, primarily used for cylindrical parts in general fabrication.
- Plasma Cutting:These systems direct high-temperature plasma torches for cutting conductive materials in heavy industrial applications.
- Wire EDM:These controllers guide thin electrified wires for precise material removal, critical for intricate tooling and mold making.
Precision requirements dictate the adoption of specialized control technologies across diverse manufacturing environments.
Application:
Application segmentation differentiates controller use based on the end product's required tolerances and surface finish standards.
- Aerospace Manufacturing:This application requires controllers with multi-axis and simultaneous machining capabilities for complex components made from advanced materials like titanium. Stringent geometric tolerance standards drive demand in this sector.
- Precision Molding:This segment utilizes controllers for creating highly accurate molds and dies, critical for industries such as medical devices and consumer electronics. Surface finish requirements in this area are exceptionally stringent.
- Metal Fabrication:This broad application employs controllers for general cutting, bending, and forming operations in various industrial sectors.
- Electronics Assembly:Controllers here manage precise pick-and-place operations and micro-machining for miniature electronic components.
- Custom Tooling:This application demands controllers capable of producing unique, specialized tools and fixtures for bespoke manufacturing processes.
High-precision applications command premium controller features and drive technological advancements.
End User Industry:
End user industry segmentation categorizes demand based on the operational scale and specific production needs of different customer types.
- Aerospace OEMs:These manufacturers require advanced controllers for producing critical airframe and engine components, emphasizing reliability and certification. Their demand is concentrated in regions with significant aerospace production, such as the United States.
- Electronics Manufacturers:This segment uses controllers for high-speed, high-precision micro-machining and assembly of intricate electronic devices. Miniaturization trends in consumer electronics drive controller demand here.
- Machine Shops:These diverse entities utilize a range of controllers for general machining, often prioritizing flexibility and ease of programming.
- Plastic Molders:This industry employs controllers for injection molding and other plastic forming processes, focusing on repeatability and cycle times.
- Fabrication Workshops:These workshops use controllers for various metalworking tasks, from prototyping to small-batch production.
Specialized industries drive demand for bespoke controller solutions, while general manufacturing seeks versatile platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence across global markets influences manufacturing location decisions, driving demand for CNC controllers. Differing compliance costs and industrial policies create opportunities for production shifts. This dynamic shapes regional investment in advanced automation technologies.
China
Government industrial policy provides significant stimulus for advanced CNC controller adoption, particularly in automotive and electronics manufacturing. Manufacturers must adhere to specific GB standards for industrial equipment and increasingly align with dual carbon goals. The Yangtze River Delta region drives extensive investment in new machine builds and integrated controllers for high-volume production.
Germany
Advanced manufacturing sectors in Germany drive demand for open-architecture controllers to support smart factory initiatives and enterprise-level system integration. Compliance with CE marking for machine safety and the proposed EU Cyber Resilience Act are critical market access requirements. The Baden-Württemberg region, a hub for machine tool builders, focuses on integrating advanced controllers for demanding applications.
United States
Aerospace manufacturing and custom tooling sectors in the United States demand multi-axis and simultaneous machining capabilities from CNC controllers. Compliance with FAA regulations for critical components mandates stringent reliability and precision from control systems. The Midwest manufacturing belt shows strong adoption of software-centric controllers for rapid changeovers in high-mix job shops.
Japan
Precision manufacturing and the high-volume machine tool segment in Japan necessitate advanced CNC controllers with integrated hardware and software ecosystems. METI initiatives promote smart manufacturing and robotics integration, influencing controller technology development. Aichi Prefecture, a major automotive and machine tool cluster, actively deploys controllers supporting advanced automation and productivity gains.
CNC Controller Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the CNC controller market. The market exhibits a tiered structure, with a few dominant integrated solution providers alongside numerous niche players. Strategic archetypes include integrated hardware-software ecosystems, open-architecture system providers, and high-precision measurement specialists. Companies pursue strategic partnerships and portfolio diversification to enhance their market reach and technological offerings.
Within the integrated hardware-software ecosystem archetype, FANUC Corporation anchors a significant market share, especially in the high-volume machine tool segment with its comprehensive offerings. Siemens AG, a German industrial conglomerate, exemplifies the open-architecture approach, positioning itself for enterprise-level system integration crucial for smart factories and networked production environments. HEIDENHAIN GmbH, another German-based entity, represents specialists in high-precision measurement and control systems, serving the most demanding applications where stringent tolerances are critical, particularly across Europe. These players define distinct competitive vectors based on their foundational technological philosophies.
| Leading Market Players |
|---|
| HEIDENHAIN GmbH |
| Yaskawa Electric Corporation |
| Siemens AG |
| DMG Mori Co., Ltd. |
| Okuma Corporation |
| FANUC Corporation |
| Bosch Rexroth AG |
| NUM AG |
| Mitsubishi Electric Corporation |
| Others |
Cost & Logistics Intelligence
Industry 4.0 integration mandates that CNC controllers support open communication protocols, influencing vendor selection and pricing. This demand for interoperability shifts pricing power towards solutions offering greater flexibility and ecosystem compatibility.
Pricing Analysis
Distributor margins reflect the value-added services provided, such as installation and technical support. A value-based pricing model dominates for advanced multi-axis controllers, where performance and precision justify higher costs. Price differentiation stems from customization levels and compliance with specific certifications like CE marking. Pricing softness reflects intense competition in the high-volume machine tool segment. Small and medium-sized machine shops are generally more price-sensitive than aerospace OEMs.
Supply Chain Analysis
Refurbishment and recycling initiatives for industrial electronics are gaining traction, driven by sustainability goals. The supply chain for CNC controllers draws from concentrated manufacturing bases in China, Japan, and Germany. Key component dependencies include specialized microprocessors and FPGAs. Semiconductor supply volatility represents a significant structural risk for production schedules. Direct sales to OEMs and specialized distributors form the dominant downstream distribution model.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CNC controller market functions as a stable compounder, driven by the persistent industrial automation imperative across diverse manufacturing sectors. This sustained demand provides a robust foundation for long-term growth and technological evolution.
For Market Incumbents: Cement market leadership through strategic investment in open-architecture solutions and advanced software ecosystems. This approach actively counters the threat of proprietary system lock-in, fostering broader integration with factory-wide data analytics platforms. Expand R&D into edge computing capabilities and embedded cybersecurity features to meet evolving regulatory demands like the EU Cyber Resilience Act.
For New Entrants and Emerging Players: Launch via strategic partnerships with local machine tool builders and system integrators in emerging economies like Vietnam and Thailand. Target the underpenetrated general fabrication and custom tooling segments with modular, cost-effective controller solutions. A compelling go-to-market angle focusing on ease of integration, localized technical support, and GB standards compliance offers a strong value proposition.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized software providers offering advanced simulation, digital twin capabilities, and robust CAM integration. The long-term viability of high-precision manufacturing ensures sustained demand for high-performance control systems. Monitor the accelerating adoption rate of open communication protocols as a key inflection indicator for future platform dominance and ecosystem value.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Open-Architecture Platforms | Enhances interoperability and reduces proprietary lock-in for end-users. |
| Invest in Edge Computing Capabilities | Improves real-time data processing and predictive maintenance on machines. |
| Strengthen Cybersecurity Features | Addresses new regulations like the EU Cyber Resilience Act for connected devices. |
| Expand into Emerging Economies | Captures growth from industrialization efforts in Southeast Asian nations. |
| Acquire Software Analytics Firms | Integrates advanced CAM, simulation, and digital twin functionalities. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, informing market dynamics and competitive positioning. Primary research involved discussions with plant engineers, R&D directors, procurement managers, and system integrators. Secondary data validation drew from ISO standards documents, national industrial policy reports, and OEM financial filings. Bottom-up market sizing was triangulated with top-down validation against macroeconomic indicators.
The forecast period was anchored to historical reference periods, establishing a baseline for future projections across the analysis window. The analytical framework modeled market evolution across product type, technology, application, end-user industry, and regional regulatory frameworks. Compound annual growth rates were derived from historical trends and projected future demand. Key industry-specific forecast inputs included manufacturing capital expenditure and industrial automation investment rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geopolitical shifts and raw material price volatility. These projections reflect assumptions regarding technological adoption and policy stability. Practitioners should monitor new regulatory mandates and major technological breakthroughs for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
North America Marketing Automation Software Market
Automation
North America Home Automation Systems Market
Automation
Automation Testing Market
Automation
Marketing Automation Solutions Market
Automation
Self Bag Drop Machine Market
Automation
Global Sales Force Automation (SFA) Market
Automation
Middle East and Africa Workforce Management Market
Automation
Automatic Message Handling System Market
Automation
Global Warehouse Execution System Market
Automation
AR Automation Market
Automation
Terminal Automation Systems Market
Automation
Cognitive Process Automation Market
Automation
Global Database Automation Systems Market
Automation
Modular Laboratory Automation Market
Automation
IoT Home Automation Market
Automation
Network Automation Market