
 Digital Kiosk Market | 2026-2036
Digital Kiosk Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Kiosk Market Analytics
Self-service retail channels are tilting toward automated checkout and order-point systems as labor costs and consumer convenience expectations reshape front-end operations. NCR Voyix Corporation dominates self-checkout hardware deployments across grocery and convenience chains. Diebold Nixdorf, Incorporated anchors financial services kiosk networks with its ATM-adjacent platform expertise. Zebra Technologies Corp. specializes in ruggedized outdoor units for logistics and transportation hubs.
A digital kiosk is an interactive, freestanding terminal combining touchscreen displays, embedded computing, payment modules, and network connectivity to execute transactions, dispense information, or facilitate navigation without human assistance. Units typically integrate LCD or LED panels from 15 to 55 inches, ARM or x86 processors, and PCI-compliant payment enclosures for secure card and contactless processing. Interactive kiosks lead product type deployment in retail and healthcare settings where user-directed workflows reduce staffing needs. Self-service kiosks represent the fastest-growing segment in quick-service restaurants and transit ticketing as throughput and labor efficiency drive capital allocation. Touchscreen technology anchors the installed base, while NFC and QR code modules are gaining share where mobile wallet penetration is highest.
FCC certification governs wireless connectivity modules in US-deployed units, while the EU Accessibility Act and CE marking mandate inclusive design and electromagnetic compliance for European installations. FDA guidelines shape healthcare kiosk sanitation and data handling protocols where patient information interfaces with HIPAA-covered systems. Stakeholders must monitor evolving payment security standards and accessibility requirements as procurement specifications tighten across public-sector and regulated private deployments.
Market Dynamics
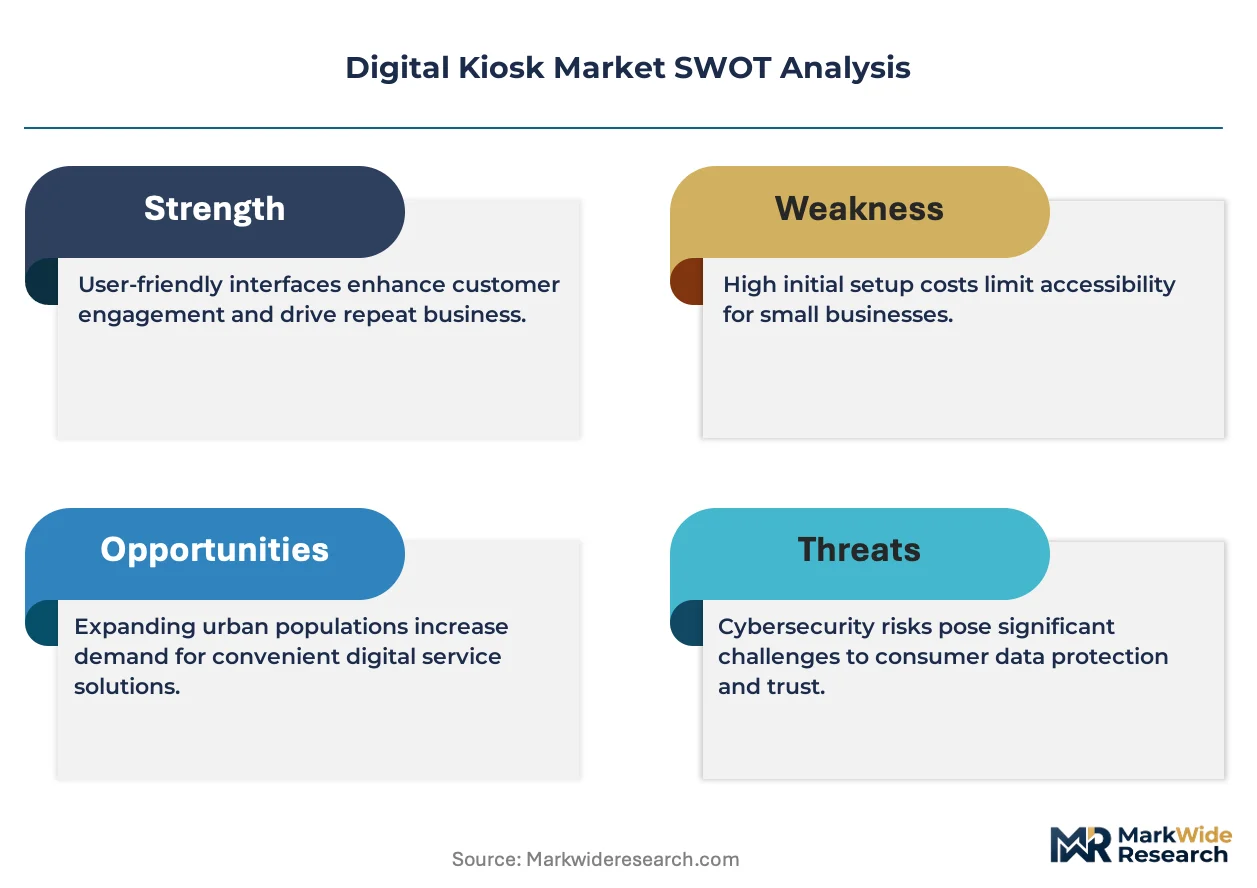
Retail labor cost compression and the EU Accessibility Act's inclusive design mandates are forcing hardware refresh cycles and interface standardization across kiosk deployments. Procurement specifications now embed accessibility compliance as a non-negotiable gate, reshaping vendor qualification criteria.
Growth Catalysts
- EU Accessibility Act:Mandates WCAG-compliant touchscreen interfaces across member states, creating replacement demand for legacy units in transit and healthcare settings.
- Quick-service restaurants:Labor shortages in the United States are accelerating order-point kiosk rollouts to maintain throughput with reduced staffing.
- Contactless payment modules:NFC and QR code integration is expanding addressable use cases where mobile wallet penetration exceeds card-present transactions.
Market Restraints
- Semiconductor supply concentration:ARM and x86 processor sourcing depends on concentrated East Asian foundry capacity, exposing lead time volatility.
- FCC certification timelines:Wireless module approval processes in the United States extend deployment schedules by 4-8 months for connected units.
- Tablet substitution:Low-cost consumer tablets with ruggedized enclosures compete for low-interaction information kiosk applications.
Strategic Opportunities
- Healthcare sanitation protocols:FDA guidelines for patient-facing terminals create premium positioning for antimicrobial surface treatments and sealed enclosure designs.
- Outdoor logistics hubs:Zebra Technologies' ruggedized platform success indicates expansion potential at ports, rail yards, and last-mile distribution centers.
- HIPAA-aligned data handling:Healthcare systems require kiosk architectures that isolate PHI from payment processing, favoring specialized system integrators.
Industry Challenges
- Embedded systems engineering talent:Shortage of developers experienced in PCI-DSS compliant payment firmware constrains vendor scaling.
- Legacy POS integration:Quick-service franchise operators face middleware complexity connecting new kiosks to decades-old back-office systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Kiosk Market |
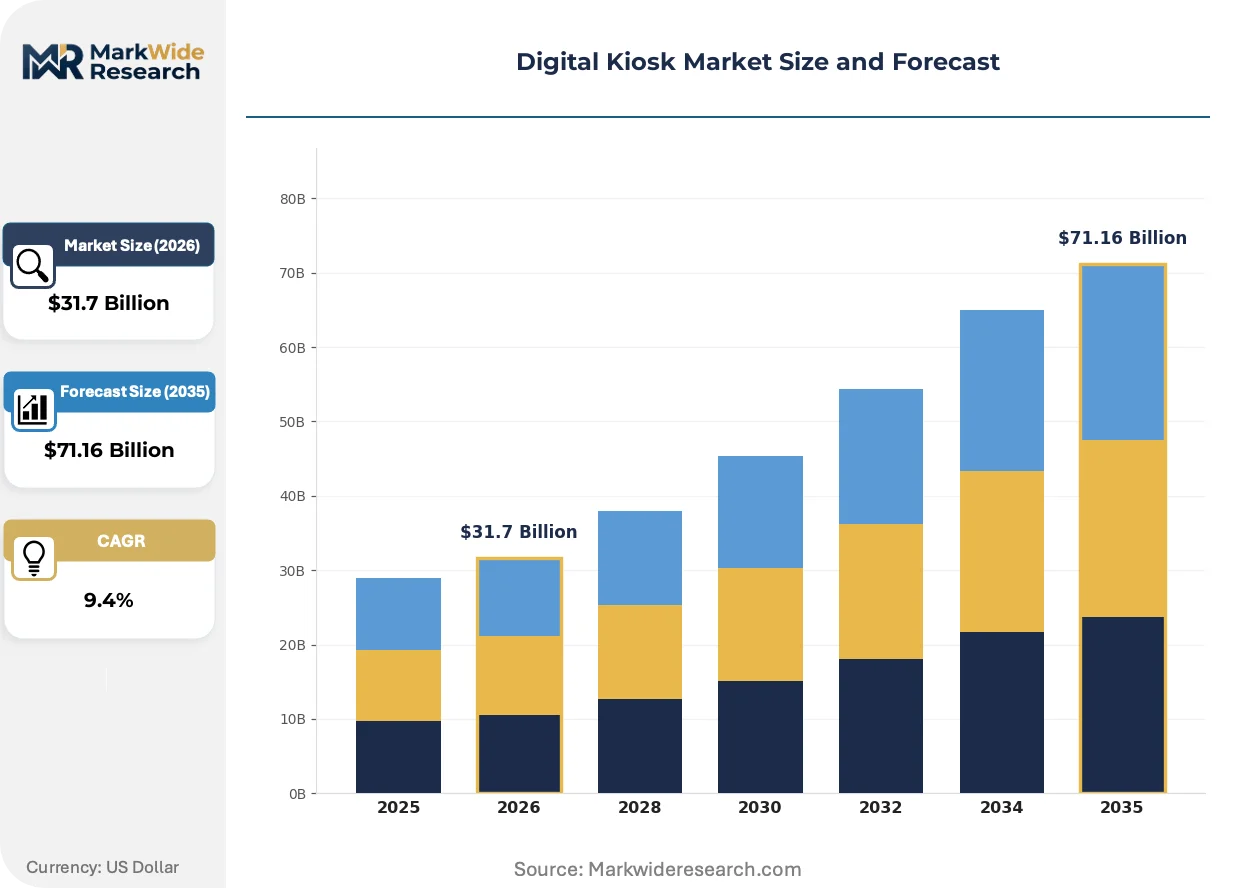
| Market Size in 2026 | $31.7 Billion |
| Market Size in 2035 | $71.16 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interactive Kiosks, Self-Service Kiosks, Wayfinding Kiosks, Ticketing Kiosks Technology: Touchscreen, Augmented Reality, NFC, QR Code End User: Retail, Transportation, Hospitality, Healthcare Deployment: Indoor, Outdoor, Mobile, Fixed |
| Companies Covered | NCR Voyix Corporation, Diebold Nixdorf, Incorporated, KIOSK Information Systems, Advantech Co., Ltd., Olea Kiosks, Inc., Meridian Kiosks, Glory Ltd., Fujitsu Limited, Zebra Technologies Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Kiosk Market Evolving Landscape
Touchscreen technology is converging with biometric and computer vision modules to enable frictionless authentication. These integrations are compressing transaction times while raising hardware complexity and security certification requirements.
Biometric authentication modules are embedding fingerprint and facial recognition directly into payment enclosures. Quick-service restaurants and transit agencies in the United States are piloting these units to reduce card-present fraud. The technology is hybridizing physical security layers with digital identity verification, collapsing separate authentication steps into single-touch workflows.
CE marking requirements under the EU Accessibility Act are mandating haptic feedback and voice navigation capabilities for all public-facing deployments. Manufacturers must redesign interface architectures to support screen reader compatibility and adjustable touch sensitivity. Healthcare and transit procurement in Germany, France, and the Netherlands now disqualify bids lacking certified inclusive design documentation.
Buyer consolidation among national retail chains is shifting procurement toward multi-year managed service agreements rather than capital equipment purchases. Grocery and convenience operators are bundling hardware, software, and remote monitoring under per-transaction fee structures. This model is most advanced in the United States, where NCR Voyix and Diebold Nixdorf compete on service-level guarantees rather than unit economics alone.
Digital Kiosk Market Segmentation
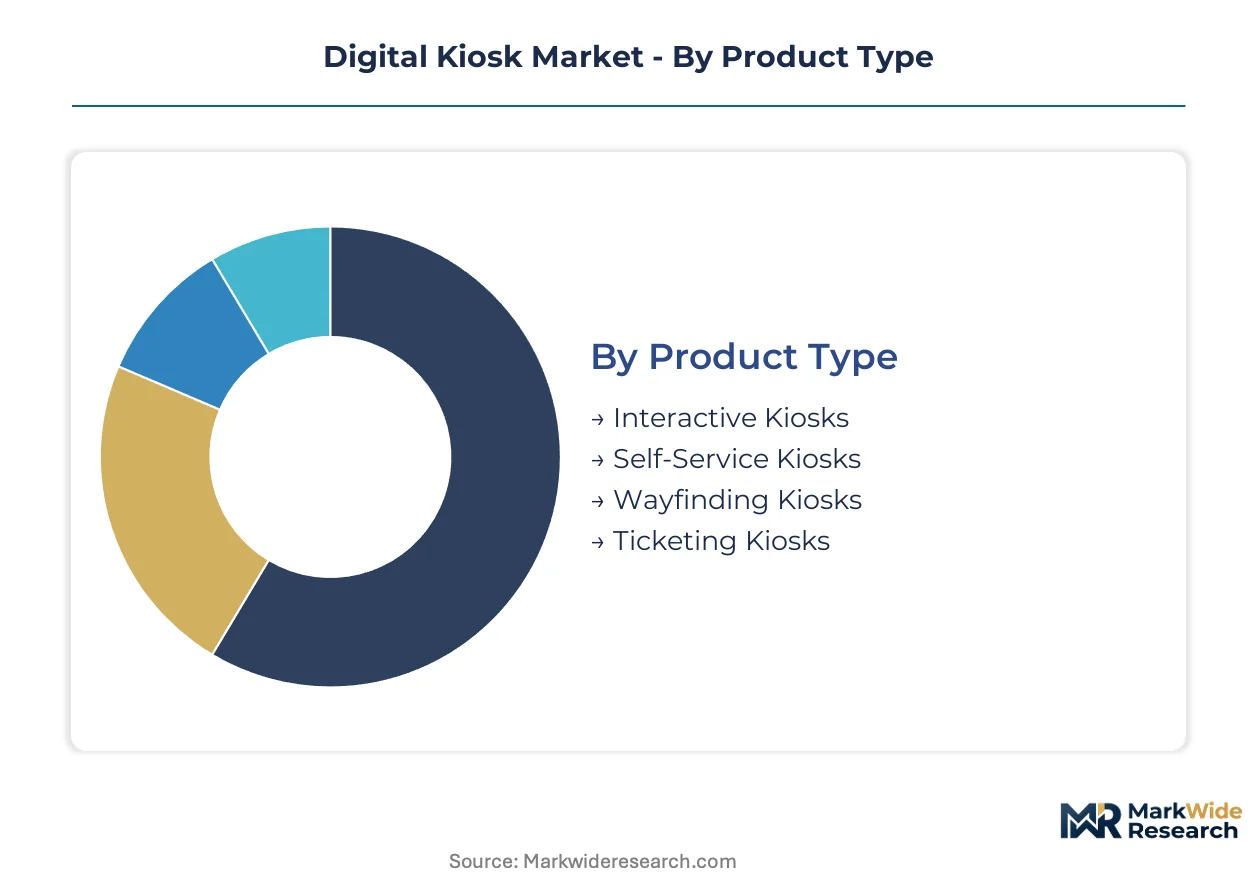
Segmentation in the Digital Kiosk Market reveals how hardware specifications, interface technologies, and deployment environments shape procurement patterns across distinct operational contexts. Each dimension carries unique compliance burdens and integration requirements that filter vendor eligibility.
Product Type:
The maturity spectrum spans from established transactional terminals to emerging navigation-focused deployments in complex physical environments.
- Interactive Kiosks:These units combine 15-55 inch LCD or LED panels with ARM or x86 processors to support user-directed workflows in retail and healthcare settings. Demand concentrates in United States hospital systems and pharmacy chains where patient check-in and wayfinding reduce administrative staffing. FCC certification for embedded wireless modules extends deployment timelines.
- Self-Service Kiosks:Purpose-built terminals with PCI-compliant payment enclosures execute transactions without human assistance. Quick-service restaurants across the United States are deploying these units at scale to maintain throughput amid labor shortages. The EU Accessibility Act mandates WCAG-compliant touchscreen interfaces for European deployments.
- Wayfinding Kiosks:Navigation terminals with interactive mapping capabilities guide users through complex facilities like airports and medical campuses.
- Ticketing Kiosks:Transit-focused units with integrated payment modules and thermal printers serve rail, bus, and parking applications.
Interactive Kiosks retain volume leadership; Self-Service Kiosks hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium biometric-integrated modules from baseline touchscreen configurations.
- Touchscreen:Capacitive and resistive touch panels anchor the installed base across retail and hospitality deployments. United States quick-service restaurants and grocery chains specify these interfaces for order-point and self-checkout applications. CE marking requirements under EU regulations mandate haptic feedback compatibility for public-facing units.
- NFC:Near-field communication modules enable contactless payment and mobile wallet integration. Transit agencies in the United States are standardizing these readers for fare collection where mobile penetration exceeds card-present transactions. PCI-DSS compliance requirements constrain firmware development timelines.
- Augmented Reality:Overlay interfaces that merge physical environments with digital information layers for immersive product visualization.
- QR Code:Optical scanning modules support mobile-driven workflows with lower hardware cost than NFC alternatives.
Touchscreen technology commands the largest installed base; NFC modules are climbing the fastest.
End User:
Application-specific requirements drive divergence in enclosure durability, payment certification, and data handling protocols.
- Retail:Self-checkout and order-point deployments dominate capital allocation as labor cost compression accelerates automation. United States grocery and convenience chains are expanding footprints under multi-year managed service agreements. FDA guidelines shape sanitation protocols where food service interfaces with patient-facing terminals.
- Transportation:Transit ticketing and wayfinding applications require ruggedized enclosures for high-traffic environments. Airports and rail systems in the United States specify these units for passenger flow management. FCC certification governs wireless connectivity modules for real-time schedule updates.
- Hospitality:Check-in and concierge terminals serve hotels and event venues with guest-facing service workflows.
- Healthcare:Patient-facing terminals must isolate PHI from payment processing under HIPAA-aligned architectures.
Retail captures the largest revenue share; Healthcare is expanding most quickly.
Deployment:
Environmental exposure determines enclosure IP ratings, thermal management, and network connectivity approaches.
- Indoor:Climate-controlled installations in retail, healthcare, and hospitality settings specify standard commercial enclosures. These deployments concentrate in United States quick-service restaurants and hospital systems where EU Accessibility Act compliance is irrelevant. PCI-DSS payment security standards govern all card-present configurations.
- Outdoor:Ruggedized units with sealed enclosures and wide-temperature operation serve logistics hubs and transit stops. Ports and rail yards in the United States are expanding deployments for cargo tracking and driver check-in. FCC certification extends lead times for connected field units.
- Mobile:Battery-powered or vehicle-mounted terminals support temporary events and roaming service applications.
- Fixed:Permanently installed units with hardwired power and network connections anchor permanent infrastructure.
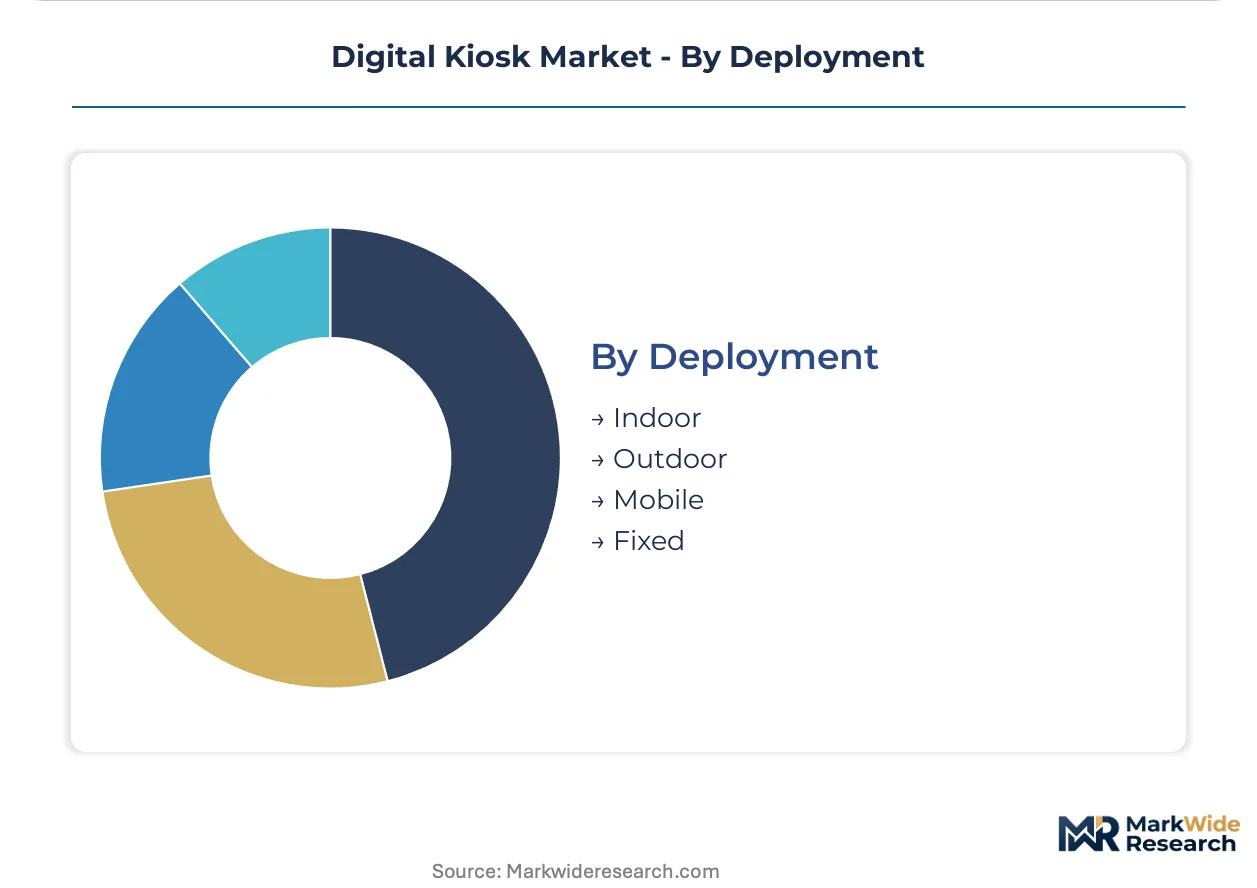
Indoor deployments retain volume leadership; Outdoor configurations hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC certification requirements govern wireless connectivity modules in United States-deployed units, creating a regulatory anchor for the dominant geography while the EU Accessibility Act and CE marking reshape European procurement specifications.
United States
Quick-service restaurants and transit agencies are deploying self-service kiosks at scale to compress labor costs and maintain throughput. FDA guidelines shape healthcare kiosk sanitation protocols where patient-facing terminals interface with HIPAA-covered systems. Deployment clusters concentrate in Texas and California, where hospital systems and grocery chains are expanding self-checkout footprints under multi-year managed service agreements.
Germany
Transit authorities and healthcare systems are replacing legacy units to comply with EU Accessibility Act mandates for WCAG-compliant touchscreen interfaces. CE marking requirements enforce electromagnetic compatibility and inclusive design standards for all public-facing installations. Procurement activity concentrates in Berlin and Munich, where rail operators and university hospitals are disqualifying vendors lacking certified accessibility documentation.
France
Retail chains and municipal transit operators are refreshing kiosk estates to meet haptic feedback and voice navigation requirements under EU regulations. ANSM oversight shapes healthcare terminal specifications where patient data handling intersects with national privacy frameworks. Industrial activity clusters in Paris and Lyon, where pharmacy networks and airport operators are specifying antimicrobial surface treatments for high-traffic deployments.
Japan
Transportation hubs and hospitality venues are integrating NFC modules to capture mobile wallet transactions exceeding card-present volumes. METI standards govern embedded computing specifications for transit ticketing and wayfinding applications. Manufacturing and deployment activity concentrates in Tokyo and Osaka, where rail operators and hotel chains are piloting biometric authentication modules to compress transaction times.
United Kingdom
Healthcare systems and retail operators are aligning procurement with EU Accessibility Act compliance requirements despite post-Brexit regulatory divergence. MHRA guidelines influence medical device classification for patient-facing terminals in hospital settings. Deployment activity clusters in London and Manchester, where NHS trusts and grocery cooperatives are specifying sealed enclosure designs for infection control protocols.
Digital Kiosk Market Competitive Landscape
Payment-integrated hardware specialists and ruggedized outdoor terminal fabricators split the market between indoor transactional deployments and logistics-focused field applications. Vendor qualification criteria are tightening around accessibility compliance certification and PCI-DSS firmware expertise, compressing the addressable supplier base. Three archetypes dominate: self-checkout platform providers, ATM-adjacent financial services specialists, and industrial-grade enclosure manufacturers. Competitive positioning hinges on multi-year managed service agreements and strategic partnerships with national retail chains.
Among United States-based platform providers, NCR Voyix Corporation and Diebold Nixdorf, Incorporated exemplify the self-checkout and financial services archetypes respectively. Zebra Technologies Corp. anchors the ruggedized outdoor segment. Japanese fabricators Fujitsu Limited and Glory Ltd. occupy positions within the payment-integrated hardware tier. KIOSK Information Systems and Meridian Kiosks represent specialist integrators focused on custom enclosure design and vertical-specific software stacks.
| Leading Market Players |
|---|
| NCR Voyix Corporation |
| Diebold Nixdorf, Incorporated |
| KIOSK Information Systems |
| Advantech Co., Ltd. |
| Olea Kiosks, Inc. |
| Meridian Kiosks |
| Glory Ltd. |
| Fujitsu Limited |
| Zebra Technologies Corp. |
| Others |
Value Network & Pricing Analysis
Overcapacity in East Asian display panel fabrication is compressing component costs while simultaneously eroding supplier pricing power across the digital kiosk value chain. This utilization dynamic forces contract manufacturers to absorb margin pressure rather than pass through to OEMs, creating favorable procurement conditions for kiosk deployers in the United States and European Union.
Pricing Analysis
United States-deployed units command a 15-25% premium over European equivalents due to FCC certification costs and extended wireless module approval timelines. Three-tier pricing structure across premium, standard, and economy levels segments by enclosure durability and payment certification tier. Cost compression in standard-tier interactive kiosks is intensifying because tablet substitution threats constrain OEM pricing flexibility. Quick-service restaurant chains exhibit highest price sensitivity, while healthcare systems prioritize antimicrobial surface treatments over unit cost.
Supply Chain Analysis
Contract manufacturing concentrates with Foxconn, Pegatron, and Compal Electronics holding dominant capacity for embedded computing and display assembly. Component sourcing draws from Taiwan and South Korea for LCD panels, China for metal enclosures and thermal management systems, and Japan for precision payment module components. ARM and x86 processor dependencies create single-source vulnerability concentrated in TSMC and Samsung foundry capacity. Distribution runs through direct OEM relationships with national retail chains and value-added resellers serving mid-market healthcare and hospitality verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital kiosk market is recovering from pandemic-induced deployment freezes as quick-service restaurant labor shortages and EU Accessibility Act compliance deadlines synchronize replacement cycles. This cyclical upturn favors vendors with pre-certified accessibility documentation and established managed service infrastructure.
For Market Incumbents: Build switching-cost moats through multi-year managed service agreements bundling hardware, software, and remote monitoring under per-transaction fee structures. Incumbents should deepen backward integration into payment firmware development to constrain emerging fintech-entrant threats. Certification investment in EU Accessibility Act WCAG compliance creates procurement gatekeeping advantages against uncertified competitors.
For New Entrants and Emerging Players: Pursue outdoor logistics hub deployments where Zebra Technologies' ruggedized platform success validates expansion potential at ports and rail yards. The most penetrable white-space sits in mid-tier healthcare systems requiring HIPAA-aligned kiosk architectures that isolate PHI from payment processing. A specialized system integrator positioning around antimicrobial surface treatments and sealed enclosure designs offers differentiated go-to-market entry.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among managed service providers with national retail chain relationships. Long-term viability across the analysis window hinges on PCI-DSS firmware expertise and accessibility compliance certification depth. Acquisition targets should demonstrate embedded systems engineering talent scarcity. The signal to watch as inflection indicator is procurement specification tightening around inclusive design documentation in European transit and healthcare tenders.
| Strategic Initiative | Industry Significance |
|---|---|
| Accessibility Certification Investment | EU Accessibility Act WCAG compliance creates non-negotiable procurement gates across German and French transit authorities. |
| Payment Firmware Backward Integration | In-house PCI-DSS compliant development constrains fintech-entrant substitution threats in quick-service restaurant deployments. |
| Outdoor Ruggedized Platform Expansion | Sealed enclosure designs with wide-temperature operation capture port and rail yard logistics hub demand in the United States. |
| Managed Service Agreement Conversion | Per-transaction fee structures shift revenue from capital equipment to recurring streams with national grocery chains. |
| Healthcare Antimicrobial Specialization | FDA-guided sanitation protocols and sealed designs command premium positioning in hospital system patient check-in deployments. |
Research Methodology
Desk research of SEC 10-K filings, FCC equipment authorization databases, and EU procurement tender archives preceded structured interviews with kiosk OEM product managers, retail chain IT procurement officers, and healthcare system biomedical engineers. Primary fieldwork with transit authority technology directors and quick-service restaurant franchise operators validated secondary demand signals. Bottom-up unit deployment tracking across quick-service restaurant chains and hospital systems was triangulated against top-down market sizing from component supplier revenue disclosures.
Assumptions around EU Accessibility Act enforcement timelines and quick-service restaurant labor cost compression trajectories were held fixed across the projection horizon, while semiconductor supply availability and mobile wallet penetration rates were stress-tested through sensitivity scenarios. Segmentation modeling incorporated product type, interface technology, end-use vertical, and deployment environment dimensions. CAGRs were derived from fitted growth curves against historical deployment trajectories, with inputs from ARM and x86 processor shipment forecasts and LCD panel capacity utilization reports.
Macroeconomic conditions sit as an overlay; deviation in quick-service restaurant labor market tightness or EU regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding replacement cycle timing and accessibility compliance adoption curves. Quarterly review of transit authority tender awards and healthcare GPO contract announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Technology
Smart Shelves Market
Retail Technology
Connected Retail Market
Retail Technology
Ticket Machine Market
Retail Technology
United States Grocery and Pharmacy Point of Sale (POS) Terminal Market
Retail Technology
Data-Driven Retail Solution Market
Retail Technology
Internet of Things (IoT) in Retail Market
Retail Technology
E-Retail Market
Retail Technology
Smart Kitchen Solutions Market
Retail Technology
Smart Grocery Cart Market
Retail Technology
Enterprise Mobility in Retail Market
Retail Technology
US Retail Recon Software Market
Retail Technology
Selfservice Technologies Market
Retail Technology
AR in Retail Market
Retail Technology
Smart Shelf Market
Retail Technology
Omni-Channel Retail Solutions Market
Retail Technology
Self-Checkout System Market