
 Global Data Catalog Market | 2026-2036
Global Data Catalog Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Catalog Market Foresight
The gap between enterprise-grade data catalog platforms and lightweight metadata tools is repositioning vendor strategy across the market. Informatica leverages its integration heritage to anchor complex hybrid deployments. Alation differentiates through behavioral metadata intelligence that captures actual query patterns. Collibra sustains governance-centric positioning with policy automation depth.
A data catalog is a metadata management system that indexes data assets across distributed repositories, applying automated tagging, lineage tracing, and semantic layer mapping to enable discovery and governance at petabyte scale. Its primary commercial purpose is collapsing the latency between data existence and data usability for analytics and compliance workflows. Cloud deployment leads solution uptake as enterprises retire on-premises data warehouses, while data governance application commands the deepest enterprise investment due to regulatory pressure. Services and consulting offerings capture expanding margin pools as buyers lack internal expertise to implement lineage automation.
The EU AI Act and GDPR impose strict provenance and explainability mandates that directly expand catalog deployment scope across European enterprises. The US SEC climate disclosure rules and HIPAA data tracking requirements similarly shape North American procurement specifications. FDA 21 CFR Part 11 in pharmaceutical manufacturing adds validation-layer complexity that favors catalog vendors with GxP-ready audit trails. Stakeholders must weigh interoperability against specialization as buyers consolidate around platforms that span governance, analytics enablement, and emerging AI readiness.
Market Dynamics
Hybrid cloud migration is fragmenting data estates across on-premises lakes and multi-cloud warehouses, forcing catalog vendors to federate lineage across incompatible metadata formats. This architectural pressure is restructuring procurement priorities toward interoperability layers.
Growth Catalysts
- EU AI Act explainability mandates:European enterprises must document training data provenance for high-risk AI systems, expanding catalog deployment into MLOps pipelines.
- Healthcare analytics modernization:HIPAA-covered entities in the United States are automating data access auditing to satisfy OCR enforcement priorities, prioritizing lineage granularity.
- India's data localization push:RBI guidelines on financial data storage are compelling banks to map shadow IT data assets previously invisible to central governance.
Market Restraints
- Metadata standard fragmentation:Apache Atlas, DataHub, and proprietary formats lack native interoperability, inflating integration labor costs.
- Scarce data steward talent:Enterprise buyers face 18-month hiring cycles for professionals fluent in both SQL lineage and business glossary curation.
- Open-source substitution:DataHub and Apache Atlas deployments are capturing mid-market share from commercial platforms in cost-constrained sectors.
Strategic Opportunities
- Generative AI data preparation:Catalog vendors can embed vector search and embedding lineage to serve retrieval-augmented generation pipelines.
- Saudi Arabia's Vision 2030:SFDA and NCA mandates for pharmaceutical data integrity are creating greenfield demand for GxP-validated catalog implementations.
- Real-time streaming lineage:Convergence of Kafka metadata with batch warehouse catalogs addresses the gap in event-driven architecture governance.
Industry Challenges
- Legacy warehouse schema drift:Decades-old Teradata and Oracle implementations resist automated metadata extraction without custom connector development.
- Cross-functional alignment friction:Data engineering teams and legal/compliance officers operate on mismatched timelines for lineage depth versus audit readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Catalog Market |
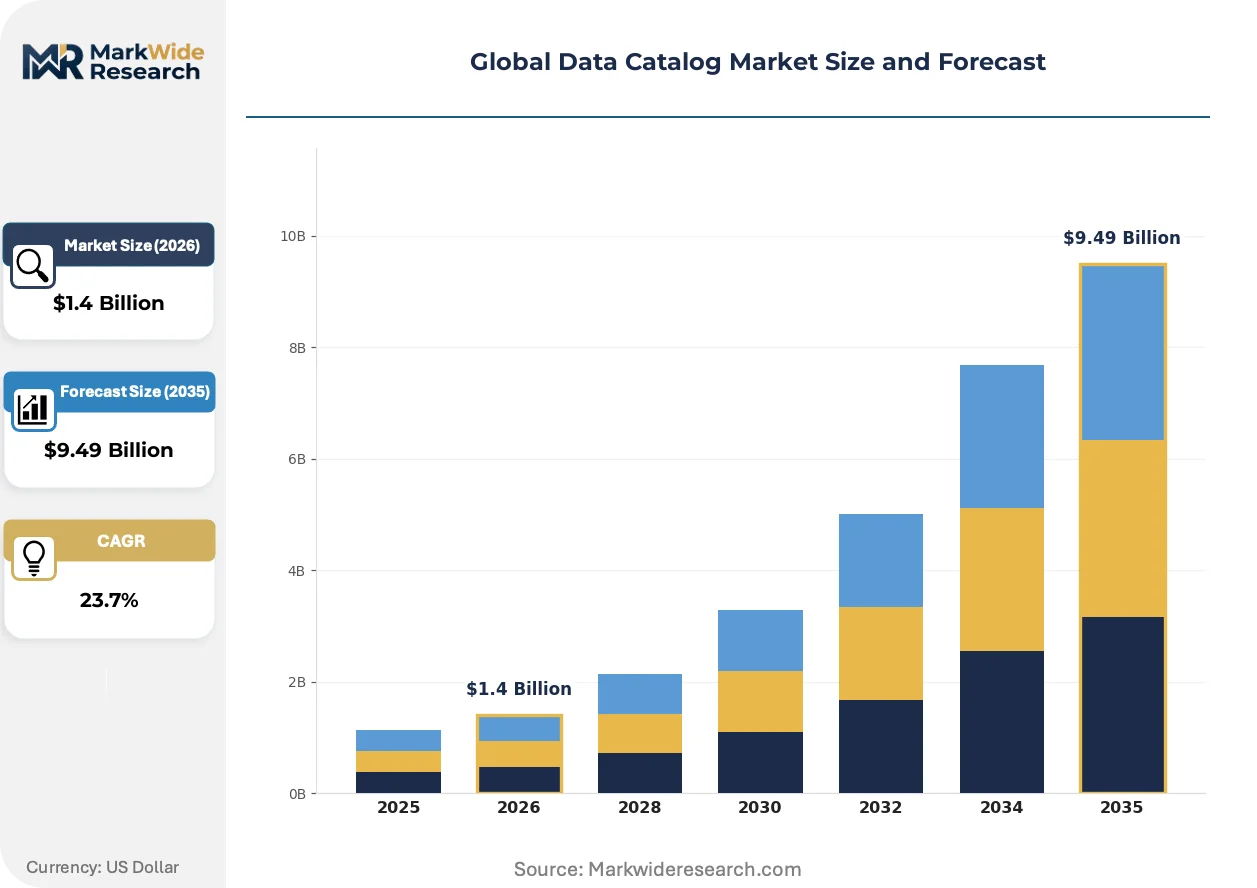
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $9.49 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud, On-premises, Hybrid, Multi-cloud Solution/Offering: Software, Services, Support & Maintenance, Consulting Application: Data Governance, Analytics Enablement, Metadata Management, Compliance Tracking, Business Intelligence End User Industry: BFSI, Telecommunication, Manufacturing, Government, Education |
| Companies Covered | Informatica, Collibra, Alation, IBM, Microsoft, Atlan, TIBCO Software, Oracle, Amazon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Catalog Market Shifts & Advancements
Active metadata systems are displacing passive inventory approaches, with platforms now generating recommendations rather than merely indexing assets. This intelligence layer is compressing the time from data discovery to analytical deployment.
Machine learning-based tagging is automating semantic classification at ingestion, eliminating manual business glossary maintenance. Financial services firms in Germany and Singapore are deploying these capabilities at scale, cutting metadata curation overhead by half. The technology is automating the translation between technical schemas and business-consumable definitions.
The EU AI Act's risk-based classification system is mandating algorithmic documentation that catalogs must now support. High-risk AI deployers in France and the Netherlands are retrofitting platforms to capture model-card metadata and training-set provenance. Pharmaceutical manufacturers face overlapping EMA validation requirements that favor catalog vendors with pre-built GxP audit templates.
Enterprise buying committees are consolidating vendor relationships, demanding that catalog platforms absorb adjacent governance functions. Data marketplace procurement in the United States is shifting from standalone discovery tools toward integrated governance suites spanning quality, privacy, and access control. This pattern is most pronounced among Fortune 500 manufacturers with distributed analytics teams across multiple states.
Global Data Catalog Market Segmentation
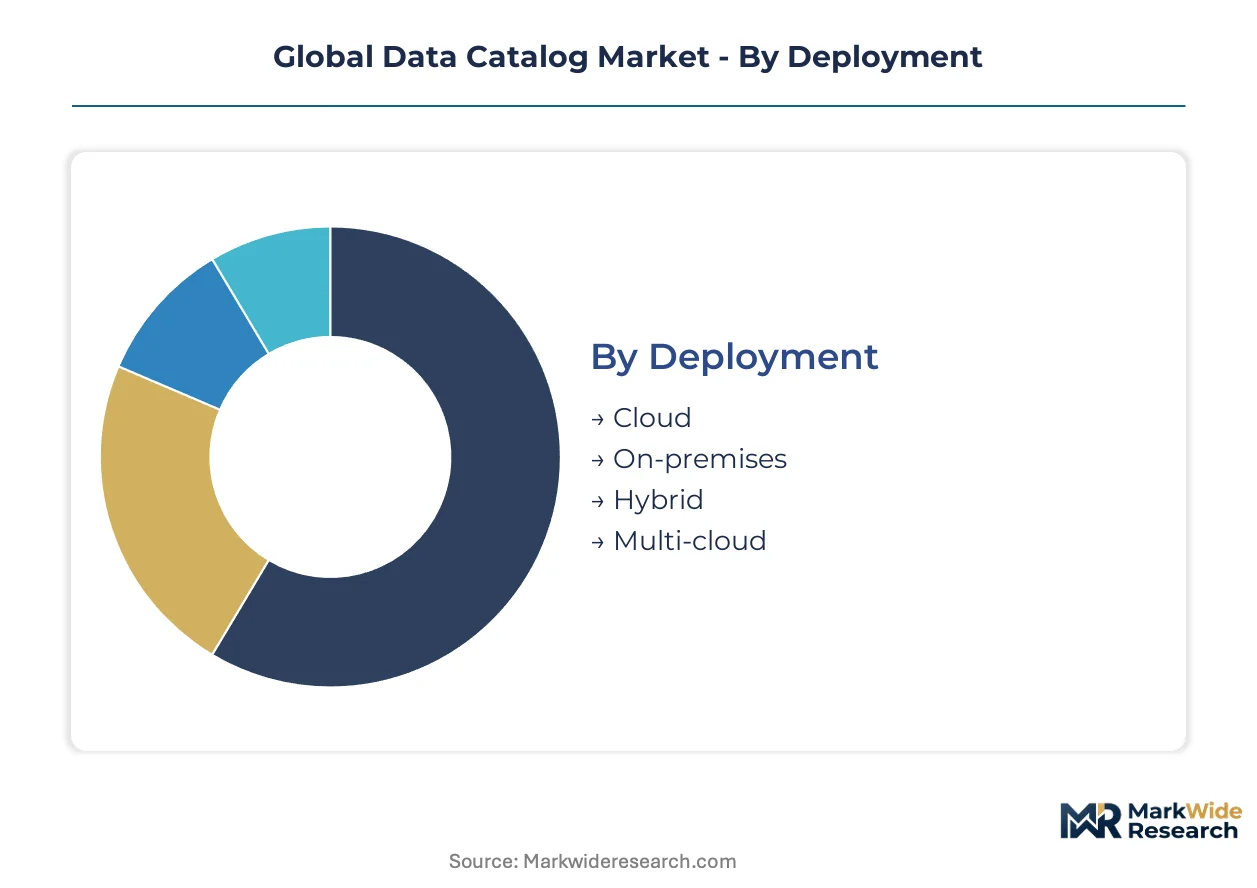
Deployment architecture determines integration complexity and recurring revenue structure for catalog vendors. Solution packaging separates platform licensing from high-margin services. Application focus dictates whether buyers prioritize governance automation or analytics acceleration.
Deployment:
Cloud deployments dominate transaction volume while hybrid configurations command premium pricing for architectural complexity.
- Cloud:Fully managed SaaS instances eliminate infrastructure overhead for mid-market enterprises. Demand concentrates among United States healthcare providers modernizing HIPAA-compliant data lakes under OCR enforcement pressure.
- On-premises:Air-gapped installations serve classified government environments and pharmaceutical manufacturers requiring GxP-validated audit trails. German automotive suppliers favor this model to satisfy BSI IT-Grundschutz requirements for supplier data sovereignty.
- Hybrid:Split architectures federate lineage across legacy warehouses and cloud warehouses. India's RBI-mandated data localization drives bank adoption for shadow IT asset discovery.
- Multi-cloud:Cross-provider deployments abstract metadata across AWS, Azure, and GCP estates. Singaporean financial institutions deploy these to satisfy MAS Technology Risk Management guidelines for vendor concentration limits.
Today's leader: Cloud. Tomorrow's challenger: Multi-cloud.
Solution/Offering:
Software licensing anchors recurring revenue while professional services capture implementation complexity premiums.
- Software:Core platform licenses for metadata ingestion, lineage visualization, and policy enforcement. United States Fortune 500 manufacturers prioritize embedded AI readiness for EU AI Act compliance documentation.
- Services:Implementation, integration, and change management engagements. Scarce data steward talent extends project timelines for European GDPR Article 30 record-keeping deployments.
- Support & Maintenance:Technical assistance and version upgrade entitlements. Pharmaceutical manufacturers require 24/7 coverage for FDA 21 CFR Part 11 validated environments.
- Consulting:Advisory on data governance operating models and business glossary design. Saudi SFDA mandates for pharmaceutical data integrity create greenfield demand for GxP-validated implementations.
Software licenses generate the recurring base. Services margins expand fastest as buyers lack internal lineage automation expertise.
Application:
Governance automation commands the deepest enterprise investment due to regulatory enforcement timelines.
- Data Governance:Policy enforcement, access control, and stewardship workflows. EU AI Act explainability mandates in France and the Netherlands expand deployment into MLOps pipelines for high-risk system documentation.
- Analytics Enablement:Self-service discovery and semantic layer provisioning. German financial services firms deploy behavioral metadata intelligence to compress time from data existence to analytical deployment.
- Metadata Management:Automated tagging, technical lineage, and business glossary curation. Machine learning-based classification cuts curation overhead for Singaporean banking consortia.
- Compliance Tracking:Audit trail generation and regulatory reporting automation. United States SEC climate disclosure rules shape procurement specifications for emissions data provenance.
- Business Intelligence:Semantic layer mapping for BI tool consumption. Manufacturing analytics teams across multiple United States states consolidate vendor relationships around integrated governance suites.
Data Governance absorbs the largest share of current procurement. Analytics Enablement is gaining share fastest as self-service demands intensify.
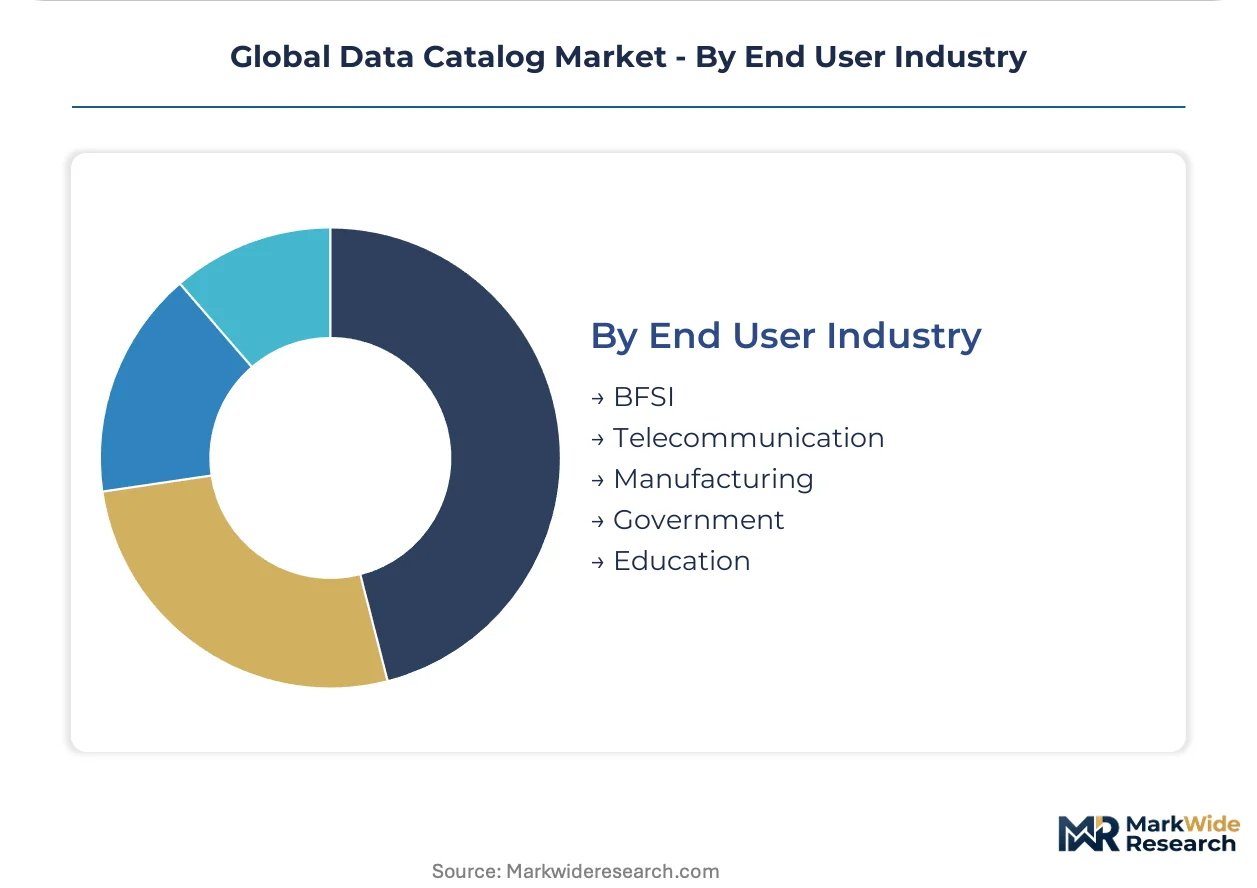
End User Industry:
Regulatory intensity and data fragmentation determine segment profitability and implementation complexity.
- BFSI:Banking, insurance, and capital markets with strict lineage requirements. RBI guidelines compel Indian banks to map previously invisible shadow IT assets for data localization compliance.
- Telecommunication:Network data lakes and customer analytics platforms. GDPR Article 17 erasure requests drive automated lineage for subscriber data across distributed repositories.
- Manufacturing:Industrial IoT streams and supply chain analytics. United States FDA 21 CFR Part 11 adds validation-layer complexity favoring vendors with pre-built GxP audit templates.
- Government:Citizen data integration and classified intelligence fusion. India's data localization push and BSI IT-Grundschutz in Germany shape sovereign cloud procurement.
- Education:Research data repositories and student analytics modernization. FERPA compliance tracking for United States universities prioritizes access auditing granularity.
BFSI anchors current revenue concentration. Manufacturing represents the steepest expansion trajectory as industrial AI readiness mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data catalog specialists cluster in technology hubs across the United States, Germany, India, Singapore, and Saudi Arabia, where regulatory pressure and cloud migration create concentrated demand for metadata governance expertise.
United States
Healthcare providers and Fortune 500 manufacturers drive cloud catalog adoption. HIPAA enforcement by OCR compels automated data access auditing. Boston's biotech corridor deploys lineage automation for FDA 21 CFR Part 11 compliance.
Germany
Automotive suppliers and financial services firms anchor European demand. BSI IT-Grundschutz requirements favor on-premises installations for supplier data sovereignty. Munich's industrial IoT cluster integrates behavioral metadata intelligence for analytics acceleration.
India
RBI-mandated data localization pushes banks to map shadow IT assets. Mumbai's financial district and Bangalore's technology corridor lead hybrid deployment adoption for cross-border data governance.
Singapore
MAS Technology Risk Management guidelines drive multi-cloud catalog procurement. Banking consortia deploy machine learning-based tagging to compress metadata curation cycles.
Saudi Arabia
Vision 2030 pharmaceutical mandates create greenfield demand for GxP-validated implementations. SFDA data integrity requirements favor catalog vendors with pre-built audit templates.
Global Data Catalog Market Competitive Landscape
Top-tier vendors anchor enterprise governance suites, while mid-market specialists and open-source alternatives fragment the lower tiers. The market exhibits tiered concentration around integration heritage, behavioral intelligence, and governance automation archetypes. Strategic moves center on M&A for lineage capabilities and partnerships for multi-cloud federation.
Within the integration-centric tier, Informatica and IBM occupy positions anchored by hybrid deployment heritage. Alation exemplifies the behavioral metadata intelligence archetype. Collibra sits within governance-centric positioning with policy automation depth. These three represent distinct competitive vectors rather than overlapping functionality.
| Leading Market Players |
|---|
| Informatica |
| Collibra |
| Alation |
| IBM |
| Microsoft |
| Atlan |
| TIBCO Software |
| Oracle |
| Amazon |
| Others |
Supply & Pricing Matrix
Fortune 500 manufacturers consolidating vendor relationships around integrated governance suites favor subscription-based SaaS tiers over perpetual licensing. This buyer concentration compresses pricing power for standalone discovery tools while rewarding platforms bundling lineage automation with policy enforcement.
Pricing Analysis
Software-vendor pricing separates core platform licensing from high-margin professional services engagements. Three-tier pricing structure across enterprise, mid-market, and departmental levels reflects deployment complexity and data estate scale. Cost compression in the mid-market tier intensifies because open-source alternatives capture share from commercial platforms. Healthcare providers under OCR enforcement pressure exhibit the lowest price sensitivity due to compliance-driven procurement timelines.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Singapore anchor cloud infrastructure delivery for catalog deployments. Software development draws from engineering talent pools in India, Poland, and Portugal. Single-source vulnerability concentrates in specialized connector development for legacy warehouse formats like Teradata and Oracle. Distribution runs through hyperscaler marketplaces and direct enterprise sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Data Catalog Market represents a late-cycle quality story as EU AI Act explainability mandates shift procurement toward platforms with pre-built GxP audit templates and MLOps lineage capabilities.
For Market Incumbents: Acquire behavioral metadata intelligence assets to defend against Alation's query-pattern differentiation. Build hybrid deployment expertise for RBI-mandated data localization in Indian banking. Invest in vector search and embedding lineage capabilities for retrieval-augmented generation pipelines. For New Entrants and Emerging Players: System integrators with GxP validation expertise offer the fastest channel to pharmaceutical manufacturers facing FDA 21 CFR Part 11 requirements. Target Saudi Arabia's Vision 2030 greenfield implementations where SFDA data integrity mandates create first-mover advantages. Lead with consulting-led change management to overcome scarce data steward talent bottlenecks. For Investors and Strategic Acquirers: Hyperscaler cloud providers are the most active acquirer in this space, seeking governance-layer capabilities to complement warehouse infrastructure. Five-to-ten year viability favors vendors with multi-cloud federation architecture and pre-built regulatory templates. Watch for EU AI Act enforcement actions against high-risk AI deployers as the inflection indicator for compliance-documentation demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding catalog capabilities into MLOps pipelines addresses EU AI Act training-data provenance mandates for French and Dutch high-risk AI deployers. |
| Acquisition of Specialist Firm | Behavioral metadata intelligence assets compress time-to-insight for German financial services firms automating query-pattern analysis. |
| Geographic Expansion | GxP-validated implementations in Saudi Arabia capture Vision 2030 pharmaceutical infrastructure spending under SFDA data integrity requirements. |
| Strategic Partnership | Hyperscaler alliances enable multi-cloud lineage federation for Singaporean banks satisfying MAS Technology Risk Management vendor concentration limits. |
| Product Launch | Real-time streaming lineage for Kafka metadata closes governance gaps in event-driven architectures adopted by United States healthcare providers. |
Research Methodology
Direct dialogue with chief data officers, enterprise architects, compliance officers, and data stewards grounds qualitative findings in procurement decision-making realities. Secondary validation draws from SEC 10-K filings, EMA validation guidance documents, RBI circulars on data localization, and hyperscaler capex disclosures. Bottom-up deployment estimates triangulate against top-down regulatory mandate timelines.
Segment-level outputs across deployment architecture, solution packaging, application focus, and end-user industry feed into the analytical framework over the projection horizon. CAGRs derive from regression against cloud migration velocity and regulatory enforcement intensity. Model inputs include GDPR Article 30 record-keeping compliance deadlines and EU AI Act risk-classification rollout schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to open-source platform maturation and hyperscaler bundling strategies. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Outsourced Digital Workplace Service Market
Digital Solutions
Global Procurement-As-A-Service (PAAS) Market
Digital Solutions
Virtual Office Market
Digital Solutions
Global Online Dating Services Market
Digital Solutions
Asia Pacific Smart Card Market
Digital Solutions
Mobile Marketing Market
Digital Solutions
G2P Systems Market
Digital Solutions
Global DDI Market
Digital Solutions
Global Cloud Monitoring Tools Market
Digital Solutions
Global Recommendation Search Engine Market
Digital Solutions
Data Integration Market
Digital Solutions
On-Shelf Availability Solutions Market
Digital Solutions
Product Information Management Market
Digital Solutions
Session Replay Software Market
Digital Solutions
Automatic Identification and Data Capture Market
Digital Solutions
Equipment Tracking Software Market