
 Digital Assistant Market | 2026-2036
Digital Assistant Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Assistant Market Insights
Enterprise buyer concentration is expanding as Fortune 500 firms consolidate vendor relationships around full-stack AI platforms rather than point solutions. Amazon leverages its AWS infrastructure and Alexa enterprise tools to anchor cloud-based assistant deployments across retail and logistics clients. Google competes through deep integration of natural language models into Workspace productivity suites, while Microsoft sustains advantage via Copilot embedding across Office 365 and Dynamics ecosystems.
A digital assistant is an AI-powered software agent that processes natural language inputs through speech or text to execute tasks, retrieve information, or control connected systems, typically operating with latency under 300 milliseconds for real-time interaction. Its primary commercial purpose is reducing operational friction in human-computer interfaces across customer service, scheduling, and device control workflows. Smart speakers represent the most mature product category with compressed margins, whereas chatbots targeted at enterprise customer service command higher value per seat due to integration complexity. Cloud deployment dominates volume but edge architectures are gaining traction in healthcare and automotive settings where data residency and response speed prove critical.
The EU AI Act imposes risk-tiered compliance obligations on general-purpose AI systems, directly affecting how European enterprises procure and deploy virtual assistants with embedded machine learning. In the United States, HIPAA governs voice-enabled tools processing protected health information, while the FDA evaluates clinical decision-support functions that certain healthcare assistants perform. Stakeholders must monitor evolving liability frameworks as regulators distinguish between passive information retrieval and active recommendation systems that influence consequential decisions.
Market Dynamics
Enterprise procurement of conversational AI is consolidating around full-stack platforms as buyers reject fragmented point solutions that demand costly integration labor. This vendor consolidation pressure is compressing margins for standalone chatbot providers while rewarding ecosystem players with captive cloud infrastructure.
Growth Catalysts
- HIPAA-compliant voice workflows:US healthcare providers deploy ambient clinical documentation tools to reduce physician administrative burden. The FDA's expanding oversight of clinical decision-support functions is accelerating validation investments.
- EU AI Act risk-tiering:European enterprises face procurement mandates for high-risk AI systems, creating compliant vendor certification demand. General-purpose assistant platforms must document training data provenance and human oversight protocols.
- Edge architecture migration:Automotive and healthcare settings prioritize on-device inference to satisfy data residency requirements. NVIDIA and Qualcomm silicon enable sub-100 millisecond response without cloud round-trips.
Market Restraints
- GPU supply concentration:Training and inference workloads depend on TSMC-fabricated NVIDIA accelerators subject to US export controls. Chinese and Middle Eastern deployments face hardware access restrictions.
- GDPR data localization:Cross-border voice data flows trigger European adequacy assessments and standard contractual clause negotiations. Multinational enterprises maintain redundant regional infrastructure to satisfy divergent national implementations.
- Large language model energy intensity:Datacenter power consumption for training runs strains grid capacity in Ireland, Singapore, and Northern Virginia. Sustainability disclosures under CSRD expose Scope 3 emissions from cloud provider partners.
Strategic Opportunities
- India's BIS certification pathway:Domestic data center buildout and PLI scheme incentives attract assistant platform localization. Hindi and regional language model fine-tuning creates differentiation against English-centric imports.
- Multimodal agent convergence:Vision-language-action models unify text, image, and robotic control interfaces. Manufacturing and logistics buyers pilot warehouse automation through unified natural language commands.
- Outcome-based pricing penetration:Customer service seat licenses migrate to per-resolution or CSAT-linked contracts. Financial services and telecom verticals in Germany and the UK pilot performance-guaranteed deployments.
Industry Challenges
- Prompt engineering talent scarcity:Enterprises compete for practitioners capable of optimizing retrieval-augmented generation pipelines. Compensation premiums exceed 40 percent above conventional ML engineering roles.
- ISO 42001 alignment complexity:AI management system certification demands documented risk assessment and continuous monitoring infrastructure. Mid-market vendors lack compliance resources to pursue audit readiness.
- Legacy CRM integration friction:Salesforce and SAP connector development consumes 6-12 month implementation timelines. Professional services margins erode as buyers demand fixed-price deployment guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Assistant Market |
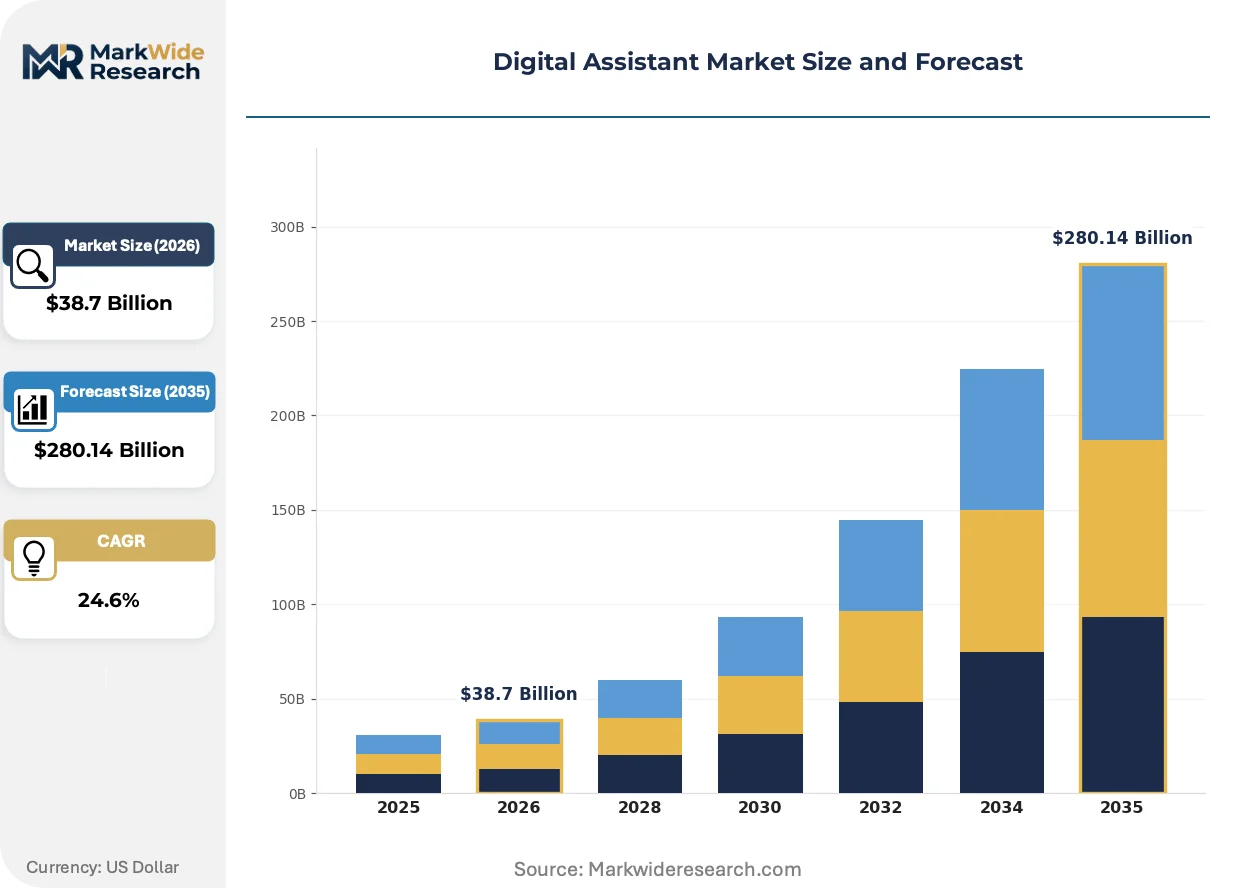
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $280.14 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Speakers, Virtual Assistants, Chatbots, Mobile Apps End User: Consumers, Enterprises, Healthcare Providers, Educational Institutions Deployment: Cloud, On-Premises, Hybrid, Edge Technology: Natural Language Processing, Machine Learning, Voice Recognition, AI |
| Companies Covered | Microsoft, Meta, Amazon, Belay, Wishup, Google, Samsung, Athena, Apple, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Assistant Market Trends and Innovations
Foundation model commoditization is compressing differentiation timelines while shifting competitive advantage toward proprietary data pipelines and vertical-specific fine-tuning. Vendors race to embed assistants within existing productivity workflows rather than demanding standalone adoption.
Multimodal large language models are unifying speech, text, and visual understanding within single inference architectures. Healthcare systems at Mayo Clinic and Kaiser Permanente pilot diagnostic imaging dialogue where clinicians query radiology findings through natural language. This convergence is collapsing the separate vendor stacks historically maintained for voice recognition, NLP, and computer vision.
The EU AI Act's general-purpose AI system obligations took effect in August 2025, imposing systemic risk documentation and red-teaming requirements on models exceeding computational thresholds. European enterprises now require vendor attestations of conformity before procurement authorization. Healthcare and financial services deployments face heightened scrutiny given their classification as high-risk use cases under Annex III.
Buyers increasingly demand consumption-based pricing tied to measurable operational outcomes rather than per-seat subscriptions. German automotive suppliers and US insurance carriers negotiate contracts linking fees to deflected support tickets or reduced average handle time. This shift transfers implementation risk to platform vendors while compressing upfront professional services revenue recognition.
Digital Assistant Market Segmentation
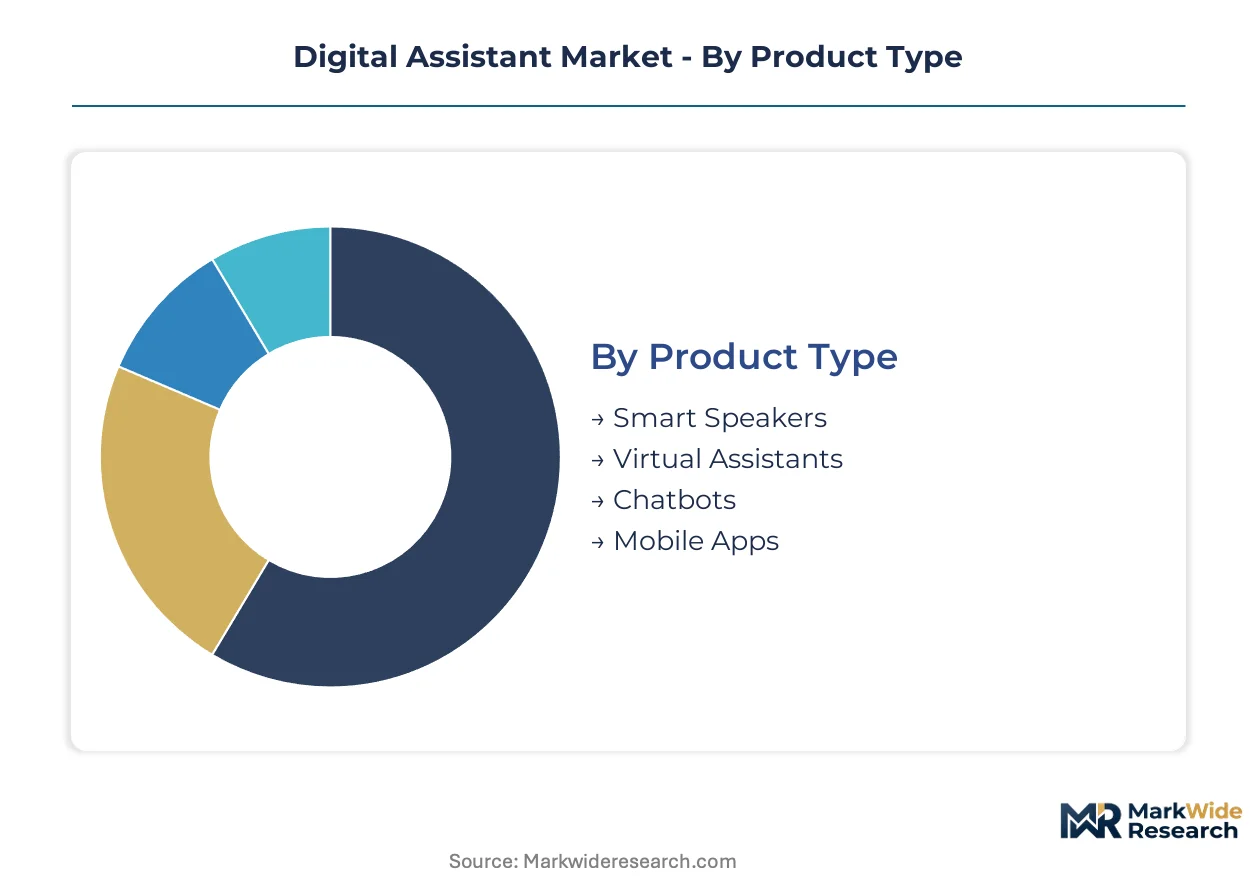
Segmentation in the digital assistant market reveals divergent margin profiles and deployment complexity. Product architecture, end-user sophistication, and infrastructure topology each create distinct competitive arenas with separate vendor qualification requirements.
Product Type:
Volume concentrates in mass-market hardware while premium economics flow to enterprise software integrations.
- Smart Speakers:Standalone voice-enabled hardware devices with embedded microphones and speakers processing ambient audio commands. Amazon Echo and Google Nest installations dominate US consumer kitchens and living rooms, though retail margins compress below 15 percent due to semiconductor cost exposure and platform subsidy strategies.
- Chatbots:Text-based conversational interfaces deployed through web portals and messaging applications. Banking and telecom sectors in Germany and the UK drive procurement, with integration into legacy CRM systems commanding implementation premiums that sustain 40-60 percent gross margins for specialized vendors.
- Virtual Assistants:Software agents embedded within operating systems and productivity suites. Enterprise licensing bundles with cloud infrastructure contracts reduce standalone visibility.
- Mobile Apps:Smartphone-native assistant applications leveraging on-device processing capabilities. Consumer distribution depends on iOS and Android platform gatekeeping.
Mature deployment sits with Smart Speakers. Newer deployment is concentrated in Chatbots.
End User:
Procurement authority separates consumer impulse purchases from enterprise security reviews and clinical validation cycles.
- Healthcare Providers:Hospitals and physician practices deploying ambient documentation and clinical query tools. US systems including Mayo Clinic and Kaiser Permanente pilot diagnostic imaging dialogue, with FDA oversight of clinical decision-support functions extending sales cycles to 18-24 months.
- Enterprises:Fortune 500 firms automating customer service and internal knowledge management. Financial services and logistics buyers in the United States consolidate vendor relationships around full-stack platforms with captive cloud infrastructure.
- Consumers:Individual purchasers activating assistants through retail channels and bundled device sales. Price sensitivity limits subscription attach rates.
- Educational Institutions:Universities and K-12 districts deploying tutoring and administrative automation. Procurement depends on state-level funding allocations with elongated RFP timelines.
Healthcare Providers command the steepest expansion trajectory as regulatory validation investments mature into deployable products.
Deployment:
Infrastructure topology determines data residency compliance, latency performance, and capital intensity for buyers and vendors alike.
- Cloud:Centralized processing through hyperscaler datacenters with API-based access. Volume dominance reflects scalability advantages, though GDPR cross-border transfer restrictions force European enterprises toward regional instance isolation.
- Edge:On-device inference without network round-trips. Automotive cabin assistants and surgical documentation tools in Germany and Japan prioritize sub-100 millisecond response and patient data containment.
- On-Premises:Dedicated hardware installations within buyer-controlled facilities. Defense and classified government workflows mandate air-gapped deployments with 6-figure minimum commitments.
- Hybrid:Orchestrated workloads splitting sensitive processing locally and scalable tasks to cloud. Complexity burdens internal IT organizations with 12-18 month integration timelines.
Cloud architectures anchor current volume. Edge deployment is gaining share fastest in regulated verticals with data sovereignty requirements.
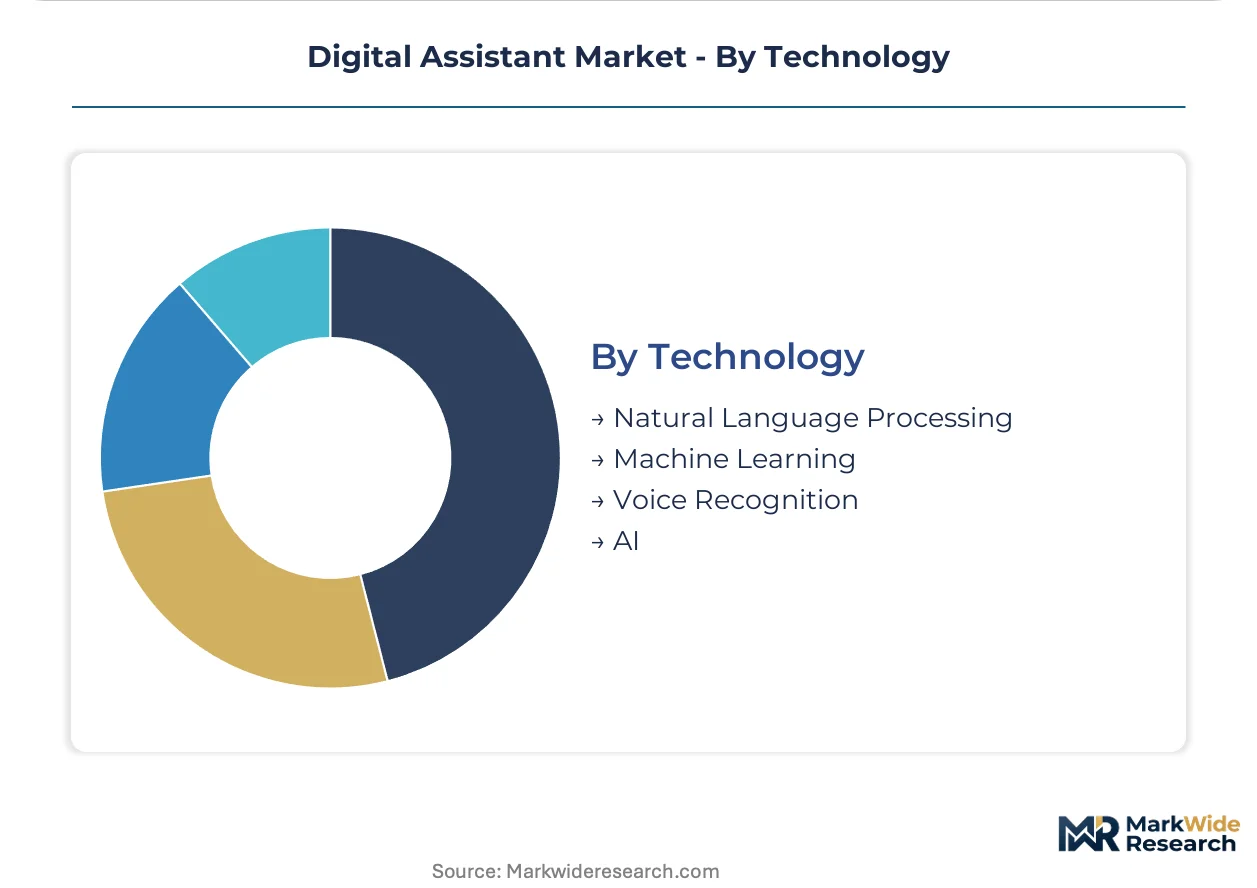
Technology:
Foundation model capabilities are collapsing historically separate technology stacks into unified inference architectures.
- Natural Language Processing:Syntactic parsing, semantic understanding, and context maintenance across multi-turn dialogue. Enterprise customer service platforms differentiate through domain-specific fine-tuning on proprietary conversation logs.
- Machine Learning:Statistical pattern recognition enabling intent classification and entity extraction. Healthcare documentation tools train on clinician note corpora requiring HIPAA-compliant data handling.
- Voice Recognition:Acoustic signal processing converting speech to text with speaker identification. Automotive applications in Japan and Germany demand multi-language support with road noise robustness.
- AI:General-purpose artificial intelligence encompassing generative and multimodal capabilities. EU AI Act systemic risk obligations apply above computational thresholds, triggering red-teaming and documentation requirements for European deployments.
Voice Recognition represents mature, margin-compressed functionality. AI capabilities are climbing the fastest as foundation model commoditization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US healthcare providers and financial institutions anchor current procurement volume for voice-enabled automation platforms. European enterprises face compliance-driven vendor consolidation under the EU AI Act. Edge deployment architectures are gaining traction in automotive and healthcare settings across Germany and Japan where data residency requirements prove non-negotiable.
United States
Mayo Clinic and Kaiser Permanente pilot diagnostic imaging dialogue tools that reduce physician administrative burden through ambient clinical documentation. FDA oversight of clinical decision-support functions extends sales cycles to 18-24 months while validating product safety. Silicon Valley clusters concentrate cloud infrastructure investment for enterprise customer service automation.
Germany
Automotive suppliers negotiate outcome-based contracts linking platform fees to deflected support tickets or reduced average handle time. The EU AI Act's risk-tiered obligations impose systemic risk documentation requirements on general-purpose assistant platforms deployed in manufacturing workflows. Munich and Stuttgart industrial corridors prioritize edge architectures for cabin assistants with sub-100 millisecond response requirements.
Japan
Automotive OEMs demand multi-language voice recognition with road noise robustness for cabin assistant deployment. METI guidelines shape domestic AI procurement standards for enterprise and consumer applications. Nagoya and Osaka manufacturing clusters pilot warehouse automation through unified natural language commands for vision-language-action models.
India
Domestic data center buildout and PLI scheme incentives attract assistant platform localization for Hindi and regional language model fine-tuning. BIS certification pathways create regulatory barriers against English-centric import competition. Bangalore and Hyderabad technology corridors concentrate engineering talent for retrieval-augmented generation pipeline optimization.
United Kingdom
Telecom and financial services verticals pilot performance-guaranteed deployments with CSAT-linked contract structures. GDPR data localization requirements trigger cross-border voice data flow assessments and standard contractual clause negotiations. London fintech clusters drive demand for compliant customer service automation with documented training data provenance.
Digital Assistant Market Competitive Landscape
US technology conglomerates anchor one tier through captive cloud infrastructure and productivity suite embedding; Asian electronics specialists hold hardware-integrated positions through smart speaker and mobile device distribution. The vendor base stratifies across three tiers: hyperscaler platforms with full-stack AI capabilities, enterprise software vendors with CRM-embedded assistants, and specialized chatbot providers serving vertical workflows. Dominant competitive moves include strategic partnerships with legacy system integrators and portfolio diversification into multimodal agent architectures.
Within the hyperscaler tier, Microsoft and Amazon exemplify platform consolidation strategies that bundle assistant capabilities with cloud infrastructure contracts. Google occupies a position representing productivity suite integration approaches that embed natural language models within collaborative workflows. These three entities anchor the competitive structure through divergent ecosystem strategies rather than direct product substitution.
| Leading Market Players |
|---|
| Microsoft |
| Meta |
| Amazon |
| Belay |
| Wishup |
| Samsung |
| Athena |
| Apple |
| Others |
Pricing and Supply Chain Analysis
Prompt engineering talent concentration in Bangalore and Hyderabad feeds labor-cost differentials that widen pricing-tier spreads between premium enterprise deployments and commoditized consumer hardware. US healthcare providers absorbing 40 percent compensation premiums for retrieval-augmented generation specialists pass these costs through to per-seat SaaS rates, while mass-market smart speaker margins compress below 15 percent under platform subsidy strategies.
Pricing Analysis
Volume concentrates in consumer smart speakers with compressed margins, while premium economics flow to enterprise chatbot integrations with 40-60 percent gross margins. Three-tier pricing structure across premium, standard, and economy levels separates HIPAA-compliant clinical documentation tools from basic customer service automation and subsidized hardware. Cost compression in the consumer tier is intensifying because semiconductor cost exposure and Amazon-Google platform rivalry erode residual margin. Healthcare providers exhibit the least price sensitivity given FDA validation requirements and administrative burden reduction ROI, whereas educational institutions and small enterprises drive procurement through elongated RFP cycles with heavy discount demands.
Supply Chain Analysis
Reverse-logistics flows for smart speaker refurbishment and trade-in programs concentrate in China, Vietnam, and Mexico, where electronics remanufacturing clusters process end-of-life devices for component recovery. NVIDIA and Qualcomm silicon for edge inference draws from TSMC fabrication in Taiwan, while microphone arrays and speaker drivers source from Chinese acoustic component specialists. Single-source vulnerability sits with TSMC-fabricated accelerators subject to US export controls restricting Chinese and Middle Eastern deployments. Distribution runs through hyperscaler cloud marketplaces for enterprise software, retail electronics channels for consumer hardware, and direct sales teams for regulated healthcare and automotive verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise procurement consolidation around full-stack platforms is forcing standalone chatbot providers toward acquisition or exit as buyers reject fragmented point solutions demanding costly integration labor.
For Market Incumbents: Deploy proprietary data pipeline investments to defend against foundation model commoditization. Microsoft and Amazon anchor competitive position through captive cloud infrastructure bundling, while Google leverages Workspace productivity suite embedding. Incumbents should accelerate multimodal agent convergence in manufacturing and logistics workflows to displace specialized vision and robotics vendors before outcome-based pricing transfers full implementation risk to platform providers.
For New Entrants and Emerging Players: System integrators with legacy CRM connector expertise represent the fastest channel to enterprise procurement authorization. New entrants should target mid-market healthcare providers in India and Southeast Asia where BIS certification and Hindi regional language fine-tuning create differentiation against English-centric hyperscaler imports. White-space opportunity sits with edge architecture deployments for automotive cabin assistants in Germany and Japan, where sub-100 millisecond response requirements and data residency mandates exclude pure cloud solutions.
For Investors and Strategic Acquirers: Re-rating potential sits with vertical-specific fine-tuning specialists given EU AI Act compliance documentation requirements and FDA clinical decision-support validation investments. Long-term viability favors vendors with demonstrated retrieval-augmented generation pipeline optimization and ISO 42001 audit readiness rather than generic foundation model wrappers. Practitioners should monitor outcome-based contract penetration rates in German automotive and US insurance verticals as inflection indicators for vendor pricing power recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding assistants within Office 365 and Dynamics ecosystems sustains Microsoft enterprise retention against point solution rivals. |
| Edge Architecture Migration | On-device inference investments satisfy German automotive data residency requirements and sub-100 millisecond response specifications. |
| Regulatory Certification Pathway | FDA clinical decision-support validation extends sales cycles to 18-24 months while creating defensive moats for healthcare-focused vendors. |
| Strategic Partnership | Salesforce and SAP connector development with system integrators reduces 6-12 month implementation timelines eroding professional services margins. |
| Geographic Expansion | Hindi and regional language model fine-tuning in India leverages PLI scheme incentives and BIS certification barriers against import competition. |
Research Methodology
Independent corroboration across hyperscaler capex disclosures, EU regulatory filings, and hospital procurement databases underwrites the qualitative findings in this study. Primary interviews with CTOs, IT procurement officers, and platform engineers at Fortune 500 enterprises, healthcare systems, and automotive OEMs combined with secondary validation from SEC 10-K filings, FDA 510(k) submissions, and clinical documentation vendor contracts. Bottom-up triangulation across deployment volume estimates and top-down reconciliation against cloud infrastructure spending patterns anchored segmentation-specific growth projections.
Rate-of-change decomposition across the analysis window separates volume expansion in consumer hardware from value migration toward enterprise software and edge inference silicon. Segmentation dimensions modeled include product architecture, end-user sophistication, deployment topology, and technology stack convergence. CAGRs were derived from installed base growth rates, seat license expansion, and outcome-based contract penetration traversed against GPU supply constraints and regulatory compliance timeline extensions.
Several conditions sit outside the modeled scope, including unforeseen export control expansions, grid capacity constraints in Ireland and Singapore, and breakthrough architectures displacing transformer-based inference. Forecasts reflect documented assumptions regarding EU AI Act enforcement consistency and HIPAA audit intensity. Practitioners should monitor TSMC capacity allocation shifts, FDA clinical decision-support guidance updates, and German automotive outcome-based contract adoption rates for early signals warranting forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Hardware Engineering and Design Services Market
Digital Solutions
Global Online Reputation Management Software Market
Digital Solutions
Global Smart Workplace Market
Digital Solutions
Global Service Delivery Platform Market
Digital Solutions
Business Process Management As a Service Market
Digital Solutions
Digital Evidence Management System Market
Digital Solutions
Location-Based Services (LBS) Market
Digital Solutions
Desktop Virtualization Market
Digital Solutions
Product Prototyping Market
Digital Solutions
UAE ICT Market
Digital Solutions
Asia-Pacific Intelligent Document Processing Market
Digital Solutions
Legal Transcription Market
Digital Solutions
US Digital Market
Digital Solutions
Mainframe Modernization Services Market
Digital Solutions
Global IC Card/Smart Card Market
Digital Solutions
Asia Pacific B2C Legal Services Market