
 Assistive Robotics Market | 2026-2036
Assistive Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Assistive Robotics Market Analysis
Rehabilitation centers is pivoting toward robotic arms and mobility robots for stroke and spinal cord injury recovery. Boston Dynamics sustains technology leadership in dynamic locomotion systems for uneven terrain navigation. ABB Robotics dominates industrial-manufacturing crossover applications, leveraging its actuator expertise for therapeutic exoskeleton production. Universal Robots competes through lightweight collaborative arm architectures adapted for clinic and home deployment.
Assistive robotics encompasses electromechanical systems designed to augment, replace, or restore human motor or cognitive function through programmable actuation, sensor fusion, and human-machine interfaces with payload capacities from 0.5 kg to 200 kg depending on application. These systems serve medical rehabilitation, eldercare independence, and disability accommodation through force-feedback control and adaptive gait algorithms. Exoskeletons capture premium margin pools due to precision servo motor requirements and clinical certification barriers, while health companions expand fastest among elderly users seeking medication adherence and fall detection. AI integration reshapes competitive dynamics as vision systems and voice recognition enable contextual autonomy beyond pre-programmed routines.
The FDA regulates assistive robotics as Class II medical devices requiring 510(k) clearance for therapeutic claims, while the EU MDR imposes stricter clinical evidence standards for CE marking of active implantable adjacent systems. ISO 13482 safety standards for personal care robots mandate collision force limits and emergency stop protocols that directly shape hardware design costs. Stakeholders must monitor reimbursement code evolution from CMS and national health systems, as payment parity with conventional therapy determines home-use market viability.
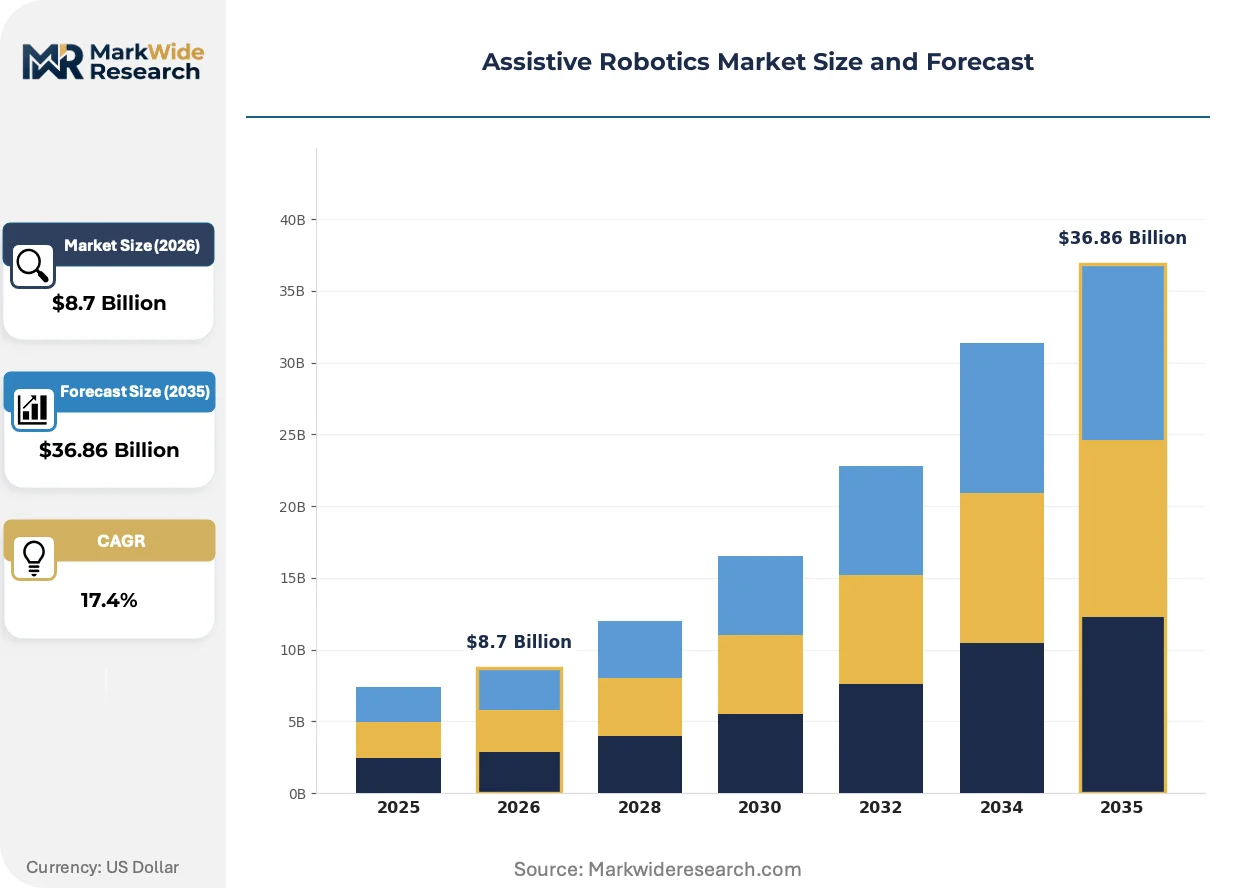
Market Dynamics
AI-integrated sensor fusion is compressing development cycles for contextual autonomy, while reimbursement code fragmentation between CMS and national health systems determines home-use viability for therapeutic robots.
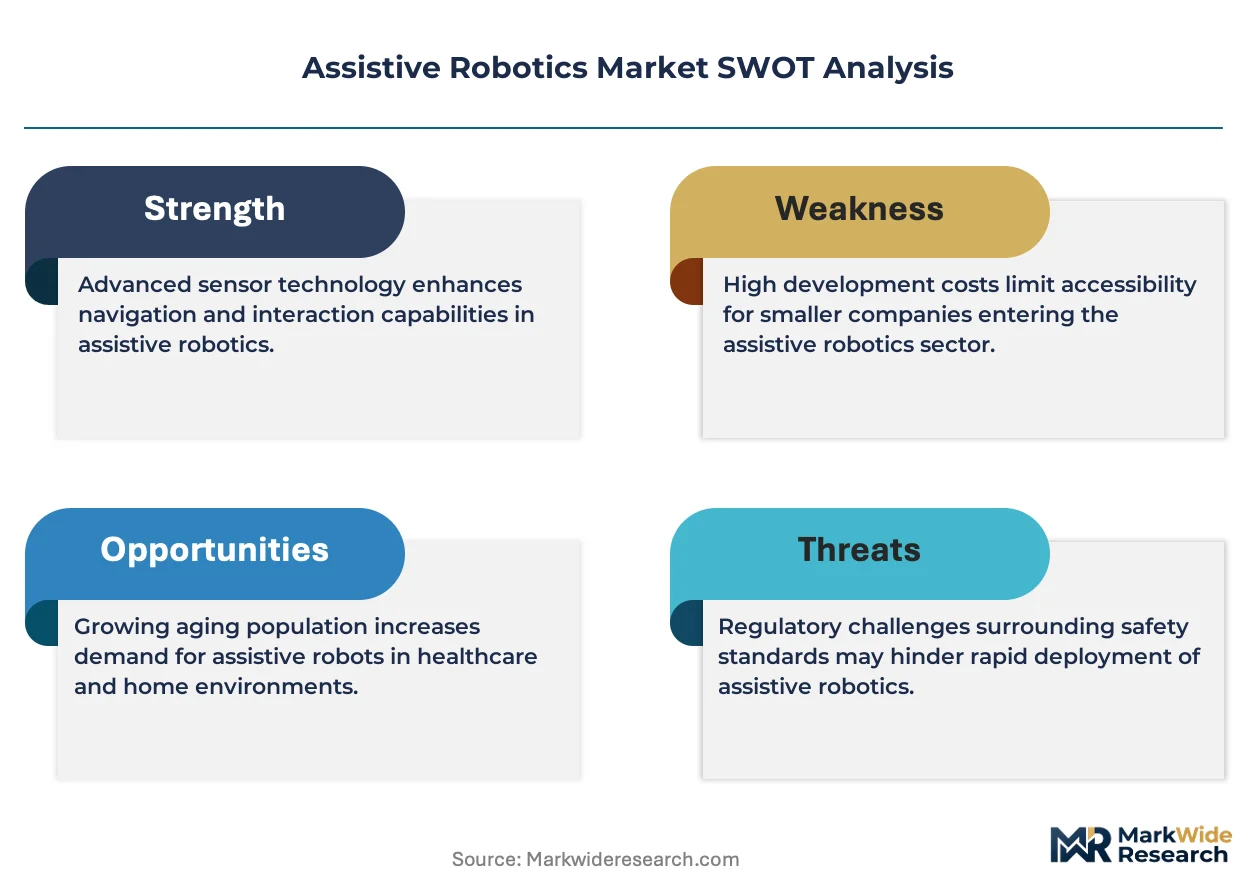
Growth Catalysts
- Japan METI eldercare automation funding:Direct subsidies for nursing facility robot deployment offset capital expenditure barriers for mobility aids and health companions. The shrinking caregiver-to-elder ratio accelerates procurement mandates.
- FDA breakthrough device designation:Accelerated review timelines for AI-integrated rehabilitation systems compress commercialization pathways from clinical trial to market entry.
- Post-surgical rehabilitation protocols:Orthopedic and neurological recovery centers are embedding robotic gait trainers into standard-of-care pathways for stroke and spinal cord injury patients.
Market Restraints
- Precision servo motor supply concentration:High-torque compact actuators for exoskeleton joints rely on Japanese and German component suppliers, creating input bottlenecks for volume scaling.
- EU MDR clinical evidence requirements:Stricter CE marking standards for active implantable-adjacent systems extend certification timelines and inflate documentation costs.
- Manual therapy substitution:Low-cost physiotherapist labor in emerging markets delays robotic adoption where wage arbitrage favors human-delivered rehabilitation.
Strategic Opportunities
- Home-based medication adherence:Voice-interactive health companions for independent elderly living represent underpenetrated deployment outside institutional settings.
- Convergence of vision systems and haptic feedback:Sensor fusion enabling real-time environmental mapping creates new product categories for visually impaired navigation assistance.
- Remote patient monitoring integration:Telehealth platform partnerships offer channel innovation for post-acute care robot deployment without direct hospital sales cycles.
Industry Challenges
- ISO 13482 safety certification complexity:Collision force limit validation and emergency stop protocol testing extend hardware design cycles for personal care robot manufacturers.
- Reimbursement code fragmentation:CMS Category III codes for robotic therapy lack payment parity with conventional CPT codes, forcing cash-pay models for home-use devices.
- Legacy EMR integration:Health companion data streams require HL7 FHIR compliance for physician workflow adoption, adding software architecture costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Assistive Robotics Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $36.86 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exoskeletons, Robotic Arms, Health Companions, Mobility Robots End User: Healthcare Providers, Elderly Users, Disabled Individuals, Rehabilitation Centers Technology: AI Integration, Vision Systems, Voice Recognition, Sensors Application: Personal Assistance, Physical Therapy, Surgical Aid, Daily Living Support |
| Companies Covered | 1X Technologies, NEURA Robotics, Boston Dynamics, ABB Robotics, Universal Robots, Agility Robotics, Unitree Robotics, Apptronik, Tesla, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Assistive Robotics Market Emerging Trajectories
Force-feedback control architectures and adaptive gait algorithms are redefining human-machine interface standards, while regulatory harmonization efforts attempt to bridge FDA and EU MDR evidence requirements.
Soft robotics actuators using pneumatic artificial muscles and dielectric elastomers are expanding into upper-limb prosthetics and grip-assist gloves. Rehabilitation centers in Germany and the Netherlands are piloting these systems for stroke patients requiring compliant, variable-resistance movement assistance. The technology is expanding into home-use markets previously blocked by rigid exoskeleton cost and comfort barriers.
The EU AI Act's risk classification framework for biometric identification and emotion recognition systems is reshaping compliance architecture for companion robots with vision-based fall detection. Manufacturers must now document algorithmic transparency and human oversight protocols before CE marking. Health companions with facial analysis capabilities face the strictest conformity requirements, driving some vendors to disable features for European launch.
Hospital procurement committees are consolidating vendor relationships around integrated service contracts that bundle hardware, software updates, and clinician training. Device manufacturers respond by unbundling after-sales support into tiered subscription tiers. This behavioral shift is most visible in Japanese eldercare chains, where METI-subsidized facilities favor single-source suppliers for multi-site standardization.
Assistive Robotics Market Segmentation
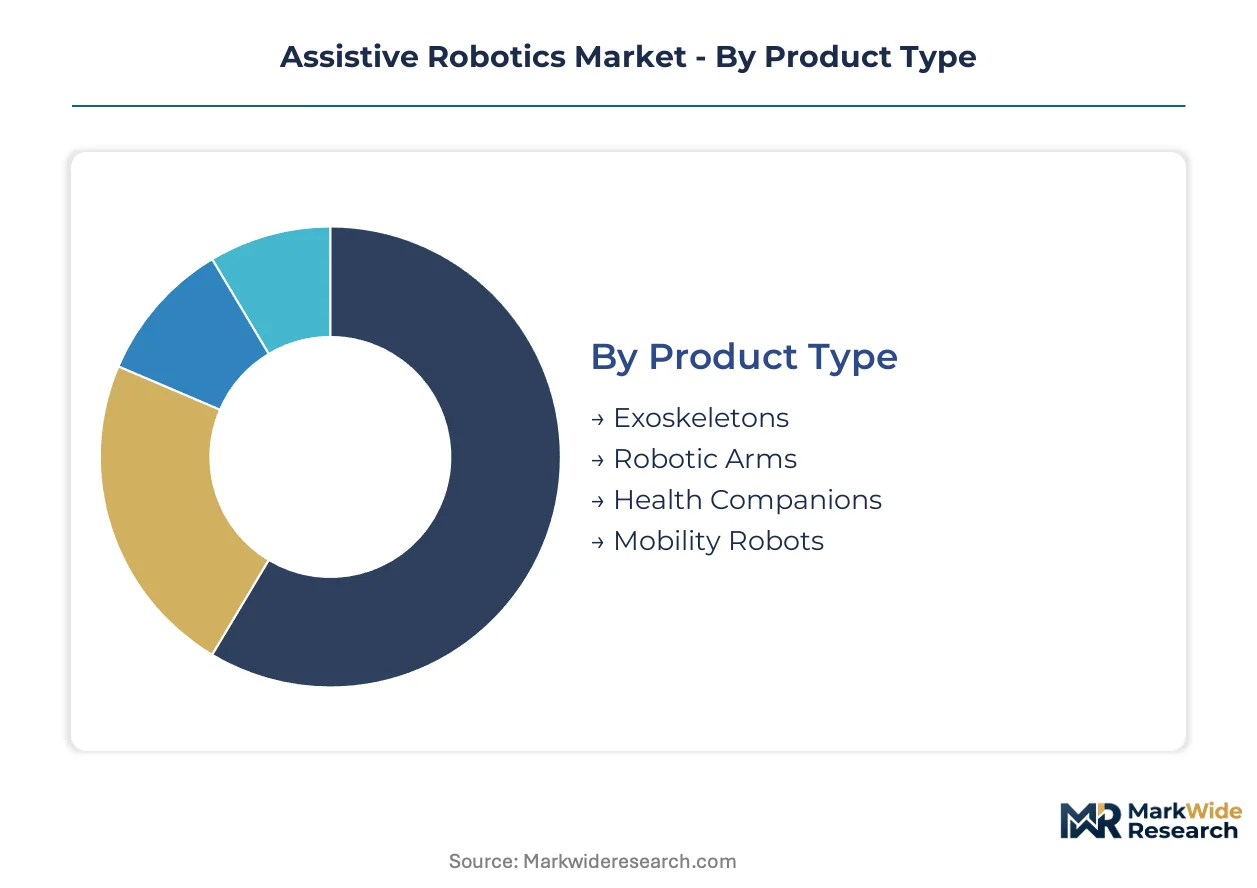
Assistive robotics segmentation reveals divergent hardware requirements between institutional deployment and consumer-grade systems. Product architecture, sensor payload, and autonomy levels vary dramatically across healthcare, eldercare, and disability accommodation use cases.
Product Type:
Exoskeletons and mobility robots function as standalone wearable systems requiring direct human interface calibration, while health companions and robotic arms embed into broader facility infrastructure or domestic environments.
- Exoskeletons:Powered orthotic frames with precision servo motors deliver gait assistance and load-bearing support for spinal cord injury and stroke rehabilitation. Demand concentrates in Japanese rehabilitation centers where METI subsidies offset acquisition costs and caregiver shortages mandate automation deployment.
- Health Companions:Voice-interactive tabletop or mobile units provide medication reminders, emergency alerts, and social engagement for independent elderly living. German and Dutch pilot programs are expanding these systems into home-use markets previously blocked by rigid hardware cost barriers.
- Robotic Arms:Collaborative manipulators adapted from industrial architectures perform feeding, object retrieval, and environmental control for mobility-impaired users.
- Mobility Robots:Autonomous wheeled or legged platforms navigate indoor environments to transport users or provide stability assistance during ambulation.
Mobility robots lead volumes today; health companions are gaining share fastest.
End User:
Customer procurement authority ranges from centralized hospital purchasing committees to individual elderly consumers, creating divergent sales cycle lengths and pricing sensitivity profiles.
- Healthcare Providers:Hospital systems and physician groups acquire surgical aid and physical therapy systems through integrated service contracts bundling hardware, software updates, and clinician training. FDA 510(k) clearance requirements and CMS reimbursement code negotiations dominate procurement timelines.
- Rehabilitation Centers:Post-acute and neurological recovery facilities embed robotic gait trainers into standard-of-care pathways for stroke and spinal cord injury patients. Japanese facilities leverage METI automation funding to standardize multi-site vendor relationships.
- Elderly Users:Independent aging consumers purchase health companions and daily living support devices through direct-to-consumer channels or eldercare facility referrals.
- Disabled Individuals:End users with congenital or acquired motor impairments seek personalized assistive configurations requiring custom fitting and ongoing calibration support.
Healthcare providers dominate current revenue; elderly users show the steepest expansion trajectory.
Technology:
Technology stacks differentiate between perception-layer capabilities enabling environmental awareness and interaction modalities determining user interface accessibility.
- AI Integration:Machine learning algorithms enable contextual autonomy beyond pre-programmed routines, including predictive fall detection and adaptive gait pattern recognition. EU AI Act compliance requirements for biometric identification systems are reshaping algorithmic transparency documentation for European launch.
- Vision Systems:Camera arrays and depth sensors provide real-time environmental mapping for navigation assistance and object manipulation. Manufacturers face strictest conformity requirements under EU AI Act risk classification frameworks for facial analysis capabilities.
- Voice Recognition:Natural language processing enables hands-free device control for users with limited dexterity or visual impairment.
- Sensors:Inertial measurement units, force-torque sensors, and pressure arrays feed closed-loop control systems for balance assistance and collision avoidance.
Sensor fusion architectures anchor current deployments; AI integration is climbing the fastest.
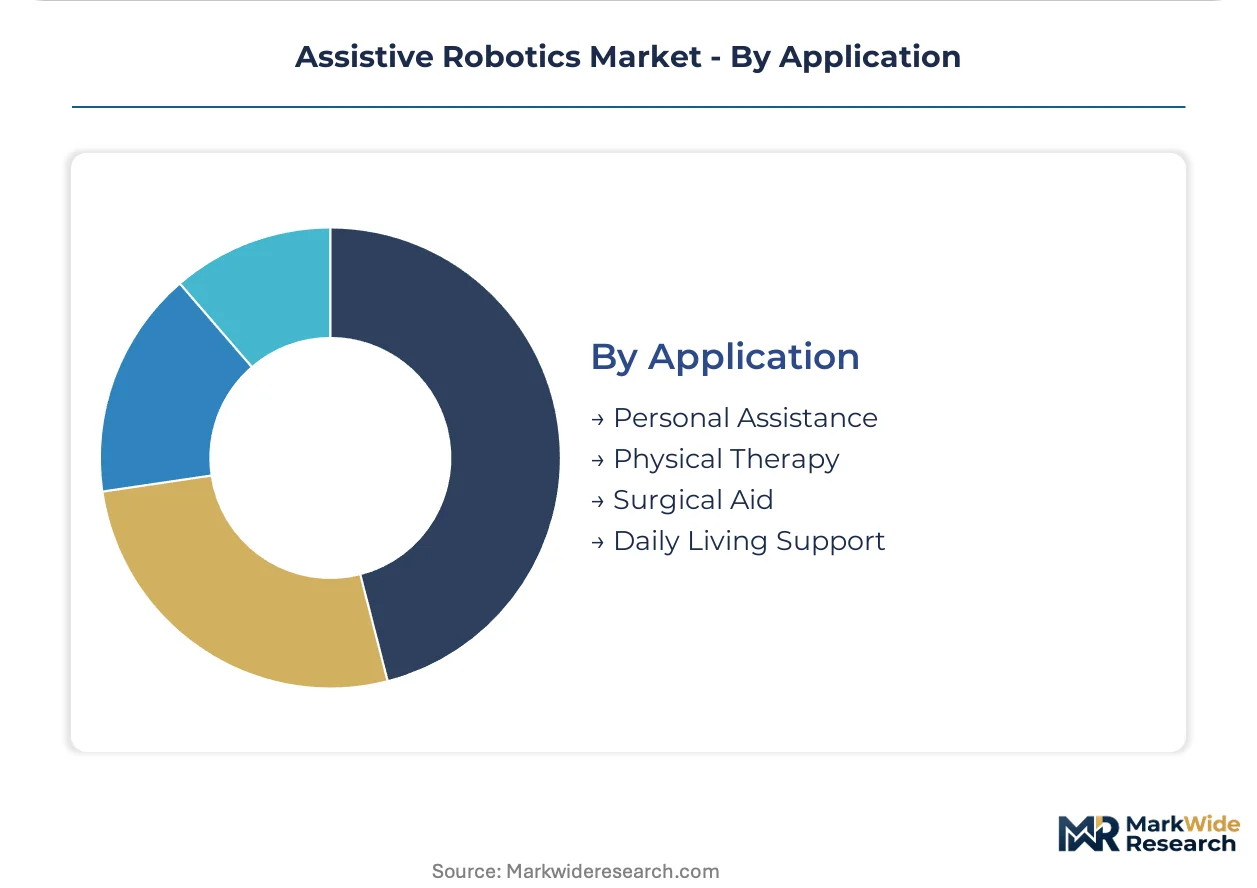
Application:
Functional use cases span acute medical intervention through chronic independence maintenance, with regulatory classification and reimbursement eligibility varying by claimed therapeutic outcome.
- Physical Therapy:Robotic systems deliver repetitive movement assistance with quantified force feedback for motor relearning after neurological injury. Post-surgical rehabilitation protocols in orthopedic and neurological centers are embedding these systems into reimbursable care pathways.
- Daily Living Support:Devices assist with feeding, grooming, dressing, and household navigation for users with permanent mobility limitations. Home-based deployment faces reimbursement code fragmentation between CMS Category III codes and conventional CPT payment parity.
- Personal Assistance:Companion functions include medication adherence monitoring, emergency response triggering, and social interaction for isolated elderly users.
- Surgical Aid:Robotic positioning and stabilization systems assist surgeons during orthopedic and neurosurgical procedures requiring sub-millimeter precision.
Physical therapy captures premium margins today; daily living support shows the strongest volume acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese eldercare automation clusters anchor the assistive robotics demand geography, with METI-funded nursing facilities driving procurement density for mobility aids and health companions. The regulatory divergence between FDA breakthrough pathways and EU MDR clinical evidence standards fragments certification timelines across major markets.
United States
Post-surgical rehabilitation centers in Florida and Arizona are embedding robotic gait trainers into orthopedic recovery protocols. The FDA's breakthrough device designation compresses commercialization timelines for AI-integrated health companions seeking 510(k) clearance. Boston Dynamics maintains technology leadership from its Massachusetts base for dynamic locomotion systems.
Germany
Rehabilitation facilities in North Rhine-Westphalia are piloting soft robotics actuators for stroke patient recovery. The EU MDR imposes stricter clinical evidence standards for CE marking of active implantable-adjacent systems than FDA equivalents. ABB Robotics leverages its actuator expertise from Baden-Württemberg for therapeutic exoskeleton production.
Japan
Shrinking caregiver-to-elder ratios in Tokyo and Osaka accelerate procurement mandates for nursing facility automation. METI direct subsidies offset capital expenditure barriers for mobility robots and health companions. Rehabilitation centers in Nagoya are standardizing multi-site vendor relationships around integrated service contracts.
Netherlands
Geriatric care pilots in Utrecht and Eindhoven are expanding health companions into home-use markets previously blocked by rigid hardware costs. The EU AI Act's risk classification framework reshapes compliance architecture for vision-based fall detection systems. Dutch rehabilitation chains favor voice-interactive tabletop units for independent elderly living.
South Korea
Seoul-based healthcare systems are integrating remote patient monitoring with assistive robotics for post-acute care deployment. The MFDS regulates therapeutic claims for rehabilitation robots under medical device frameworks similar to FDA Class II standards. Busan manufacturing clusters supply precision servo motors for exoskeleton joint actuation.
Assistive Robotics Market Vendor Landscape
Strategic partnerships dominate the current landscape as device manufacturers seek telehealth platform integrations and rehabilitation facility network access. The vendor base clusters around three archetypes: industrial robotics crossovers leveraging actuator expertise, pure-play assistive specialists, and AI-integrated autonomy developers. Consolidation pressure concentrates among health companion vendors facing EU AI Act compliance costs. M&A activity targets sensor fusion capabilities, while geographic expansion focuses on Japanese eldercare chains with METI subsidy access.
Among industrial-manufacturing crossovers, ABB Robotics and Universal Robots exemplify the therapeutic exoskeleton and collaborative arm adaptation strategy. Boston Dynamics anchors the dynamic locomotion tier with systems for uneven terrain navigation. Within the humanoid mobility segment, 1X Technologies and Agility Robotics occupy positions representing the convergence of legged platforms with institutional deployment models.
| Leading Market Players |
|---|
| 1X Technologies |
| NEURA Robotics |
| Boston Dynamics |
| ABB Robotics |
| Universal Robots |
| Agility Robotics |
| Unitree Robotics |
| Apptronik |
| Tesla |
| Others |
Supply Flow & Price Mechanics
Rare earth magnet price indices cascade through exoskeleton supply chains into three-tier pricing structures across premium, standard, and economy levels. Japanese and German precision servo motor costs propagate into rehabilitation center procurement premiums, while health companion manufacturers absorb sensor fusion component volatility through subscription bundling.
Pricing Analysis
Input-cost pass-through from high-torque compact actuators drives pricing stratification across premium, standard, and economy tiers. FDA breakthrough device designation and ISO 13482 certification grade differentiate price bands, with clinical-grade exoskeletons commanding premiums over home-use health companions. Pricing pressure stems from METI subsidy dependency in Japanese eldercare chains, where facilities negotiate volume discounts against capital expenditure offsets. Rehabilitation centers show lowest price sensitivity due to reimbursable care pathways, while independent elderly consumers face cash-pay barriers.
Supply Chain Analysis
Reverse-logistics flows for exoskeleton refurbishment and health companion software updates create secondary value recovery channels in Japanese and German markets. Component sourcing draws from Japanese precision motor suppliers, German actuator manufacturers, and South Korean sensor fabricators. Rare earth magnet and semiconductor dependencies expose manufacturers to single-source vulnerability from East Asian suppliers. Distribution runs through integrated service contracts bundling hardware, training, and maintenance subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in assistive robotics rests on AI-enabled software tiering and component cost compression from scaled sensor production. Premium-tier shifts toward predictive autonomy features justify recurring revenue models.
For Market Incumbents: Deploy backward integration into precision servo motor supply to offset Japanese component bottlenecks. Secure multi-site integrated service contracts with METI-funded eldercare chains before competitors replicate ABB Robotics' therapeutic exoskeleton adaptation strategy. Deepen ISO 13482 certification investments to maintain clinical-grade pricing premiums against emerging soft robotics substitutes. For New Entrants and Emerging Players: Telehealth platform partnerships offer channel access without direct hospital sales cycle investments. Home-based medication adherence represents the most penetrable white-space segment, with voice-interactive health companions facing minimal incumbent saturation outside Japanese institutional markets. Target Dutch and German geriatric care pilot programs seeking EU AI Act-compliant vision systems. For Investors and Strategic Acquirers: Asymmetric upside sits with sensor fusion specialists possessing FDA 510(k) clearance pathways and HL7 FHIR compliance architecture. Long-term viability favors acquisition targets with reimbursement strategy capabilities bridging CMS Category III code evolution. Monitor FDA breakthrough device designation grants as inflection indicators for commercialization timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Platform Integration | Channel innovation bypasses hospital procurement committee consolidation for post-acute care deployment. |
| FDA Breakthrough Device Pathway | Accelerated review timelines compress 510(k) clearance cycles for AI-integrated rehabilitation systems. |
| Soft Robotics Actuator Development | Pneumatic artificial muscles unlock home-use markets blocked by rigid exoskeleton cost barriers. |
| EU AI Act Compliance Architecture | Algorithmic transparency documentation enables CE marking for vision-based fall detection features. |
| Reimbursement Strategy Investment | CMS Category III code parity negotiations determine home-use device viability outside cash-pay models. |
Methodological Framework
Multiple input streams — rehabilitation facility procurement directors, biomedical engineers, FDA regulatory consultants, and METI program administrators — were reconciled against secondary validation from FDA 510(k) filings, EU MDR submission databases, Japanese eldercare automation subsidy records, and hospital GPO contract repositories. Bottom-up unit economics from exoskeleton and health companion deployments were triangulated with top-down market sizing across product type, end user, technology, and application dimensions.
Data-stream reconciliation anchored volume and value outputs across the projection horizon through segmented adoption curve modeling. Product architecture differentiation, reimbursement eligibility tiers, and regional regulatory clusters shaped the analytical framework. CAGRs were derived from installed base growth rates and replacement cycle assumptions, with AI integration penetration and soft robotics cost curves as primary forecast inputs.
Revisions become necessary when FDA reimbursement code expansions, EU AI Act enforcement interpretations, or rare earth supply disruptions materialize. Forecasts reflect assumptions about METI funding continuity and caregiver-to-elder ratio trajectories. Practitioners should monitor CMS Category III code payment parity decisions and Japanese precision motor supplier capacity announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Robot Operating System Market
Robotics and Automation
Global Automated Parcel Delivery Terminals Market
Robotics and Automation
Short-Range Drone Package Delivery Market
Robotics and Automation
Micro Robots Market
Robotics and Automation
Italy Cloud Robotics Market
Robotics and Automation
Retail Robotics Market
Robotics and Automation
China Autonomous Mobile Robot Market
Robotics and Automation
Mobile Cobots Market
Robotics and Automation
Robotics and Automation Actuators Market
Robotics and Automation
Europe Agricultural Robots and Mechatronics Market
Robotics and Automation
Healthcare Mobile Robots Market
Robotics and Automation
South America Agricultural Robots and Mechatronics Market
Robotics and Automation
US Cloud Robotics Market
Robotics and Automation
Social Robots Market
Robotics and Automation
Healthcare Assistive Robot Market
Robotics and Automation
Global Medical Robotic Systems Market