
 Core Graphics Market | 2026-2036
Core Graphics Market Size, Share, and Industry Trends Forecast 2026-2036
Core Graphics Market Insights
The EU AI Act is consolidating the cost-of-entry calculus for generative graphics platforms operating across European jurisdictions. NVIDIA Corporation leverages its CUDA ecosystem to sustain compute leadership in training-grade workloads. Advanced Micro Devices anchors its position through open-source ROCm stack differentiation against proprietary alternatives.
Core graphics encompasses hardware and software systems that render visual output through programmable shader pipelines, frame buffers with sub-20ms latency targets, and parallel compute architectures measured in teraflops of floating-point throughput. These systems enable real-time visualization for interactive media, scientific simulation, and automated design verification. 3D Graphics leads product type revenue due to gaming and spatial computing attach rates, while Vulkan adoption in mobile and embedded segments represents the fastest-expanding API technology. Enterprise end users command premium pricing for workstation-class certifications, whereas Individual Developers drive volume through subscription-based creative cloud access.
The US FCC governs spectrum allocation affecting wireless graphics streaming peripherals, while EMA and CE marking frameworks shape medical imaging display standards that cross-pollinate into professional visualization. Japan's METI subsidizes domestic semiconductor foundry capacity that feeds back into GPU supply security for regional OEMs. Stakeholders must monitor how national semiconductor subsidy programs redirect wafer allocation between consumer graphics and AI accelerator demand pools.
Market Dynamics
Real-time ray tracing APIs are restructuring the competitive calculus for rendering workloads across gaming and professional visualization, forcing hardware vendors to optimize shader pipeline density while managing thermal envelopes at sub-20ms latency thresholds.
Growth Catalysts
- EU AI Act:The regulation mandates transparency requirements for generative graphics tools, creating compliance-driven upgrade cycles for European creative studios and enterprise visualization departments.
- Vulkan API:This cross-platform graphics interface is expanding into mobile and embedded segments, reducing fragmentation across Android-based industrial displays and automotive instrument clusters.
- South Korea esports infrastructure:Government-backed arena builds and content pipeline investments are sustaining demand for broadcast-grade real-time rendering hardware.
Market Restraints
- TSMC N3B node allocation:Concentrated foundry capacity for advanced GPU silicon creates supply vulnerability when consumer graphics competes with AI accelerator wafer commitments.
- GDDR6X memory pricing:High-bandwidth memory modules required for 4K texture streaming exhibit volatility tied to commodity DRAM contract negotiations.
- RoHS substance restrictions:European limits on lead and cadmium in solder bump compositions complicate thermal interface material selection for high-TDP workstation cards.
Strategic Opportunities
- Spatial computing:Mixed-reality headset deployments in surgical training and architectural walkthroughs are opening premium-tier demand for foveated rendering ASICs.
- India PLI scheme:Domestic electronics manufacturing incentives are attracting GPU assembly and testing investments for regional OEM supply chains.
- Neural radiance fields:Convergence of volumetric capture and real-time rasterization is enabling new content formats for immersive entertainment and digital twin visualization.
Industry Challenges
- Shader compiler expertise:Scarce talent capable of optimizing compute kernels for heterogeneous architectures limits vendor differentiation in ray tracing performance benchmarks.
- ISO 9241-307 display certification:Extended validation timelines for medical imaging color accuracy standards delay workstation product launches by 8-14 months.
- Legacy OpenGL codebase:Enterprise CAD and GIS software stacks resist migration to modern low-overhead APIs, fragmenting driver development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Core Graphics Market |
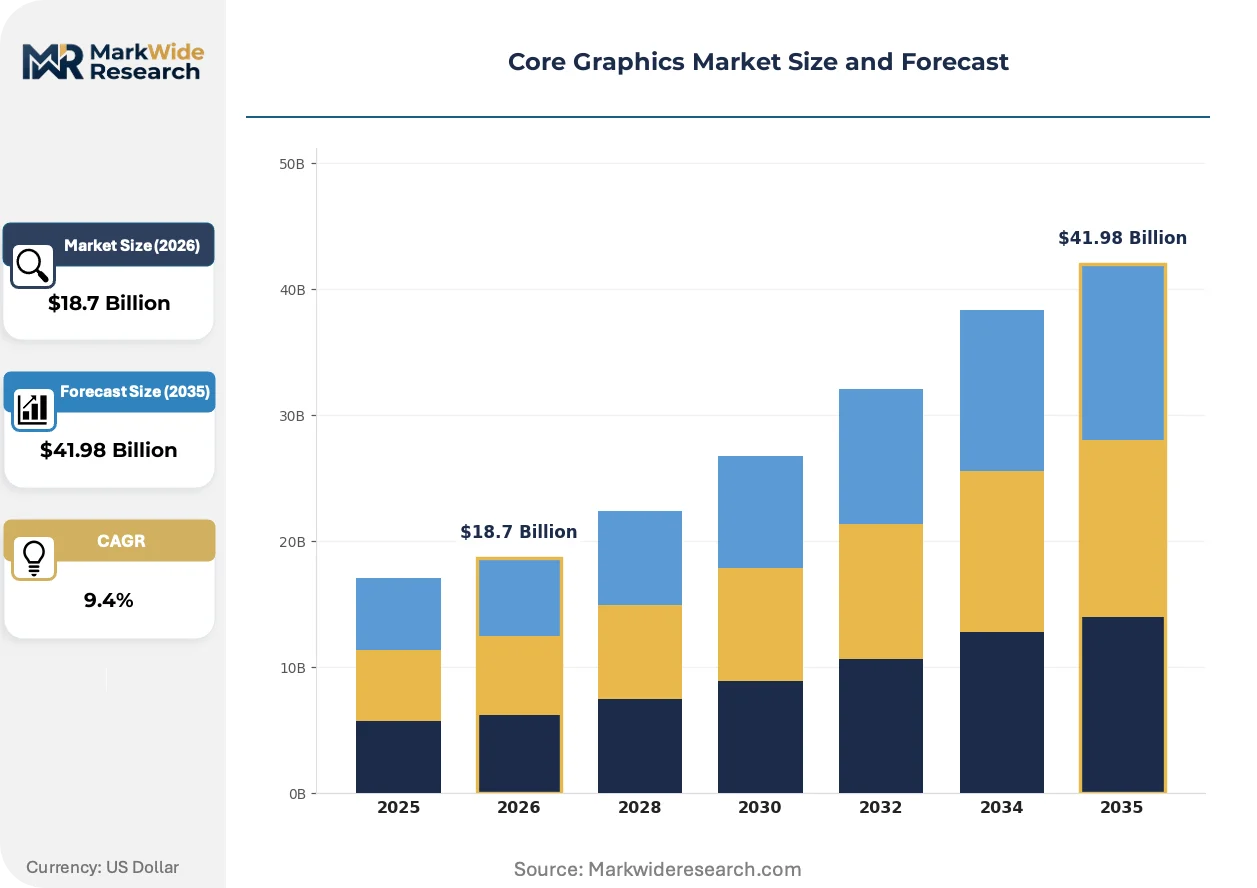
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Graphics, 3D Graphics, Vector Graphics, Raster Graphics Technology: OpenGL, DirectX, Vulkan, Metal Application: Gaming, Web Development, Mobile Apps, Graphic Design End User: Enterprises, Freelancers, Educational Institutions, Individual Developers |
| Companies Covered | NVIDIA Corporation, Advanced Micro Devices, Intel Corporation, Samsung Electronics, Qualcomm Incorporated, Imagination Technologies, Apple, Sony Corporation, Matrox Electronic Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Core Graphics Market Trends and Innovations
Path tracing hardware acceleration is compressing the quality gap between offline render farms and interactive viewports, while regulatory pressure on AI-generated content provenance is embedding cryptographic signing into frame buffer pipelines.
Mesh shading pipelines are decentralizing geometry processing from fixed-function hardware into programmable compute units. Game engine developers at mid-size studios are adopting this capability fastest, rewriting asset streaming systems to handle nanite-scale polygon densities without CPU bottlenecks. The shift is decentralizing the geometry workload and reducing draw call overhead by an order of magnitude.
The EU AI Act's transparency obligations for synthetic media are forcing generative graphics platforms to implement provenance metadata standards by 2026. Tool vendors must embed C2PA-compliant watermarking into diffusion model outputs or face market exclusion. European advertising and entertainment production houses are prioritizing compliant pipeline investments ahead of enforcement deadlines.
Subscription-based creative cloud access is displacing perpetual license models among individual developers and small studios. Adobe and Autodesk channel partners report that volume licensing through reseller networks is losing ground to direct-to-creator billing. This pattern is most pronounced in South Korea and Japan, where mobile-first payment infrastructure supports micro-transaction billing for render credits.
Core Graphics Market Segmentation
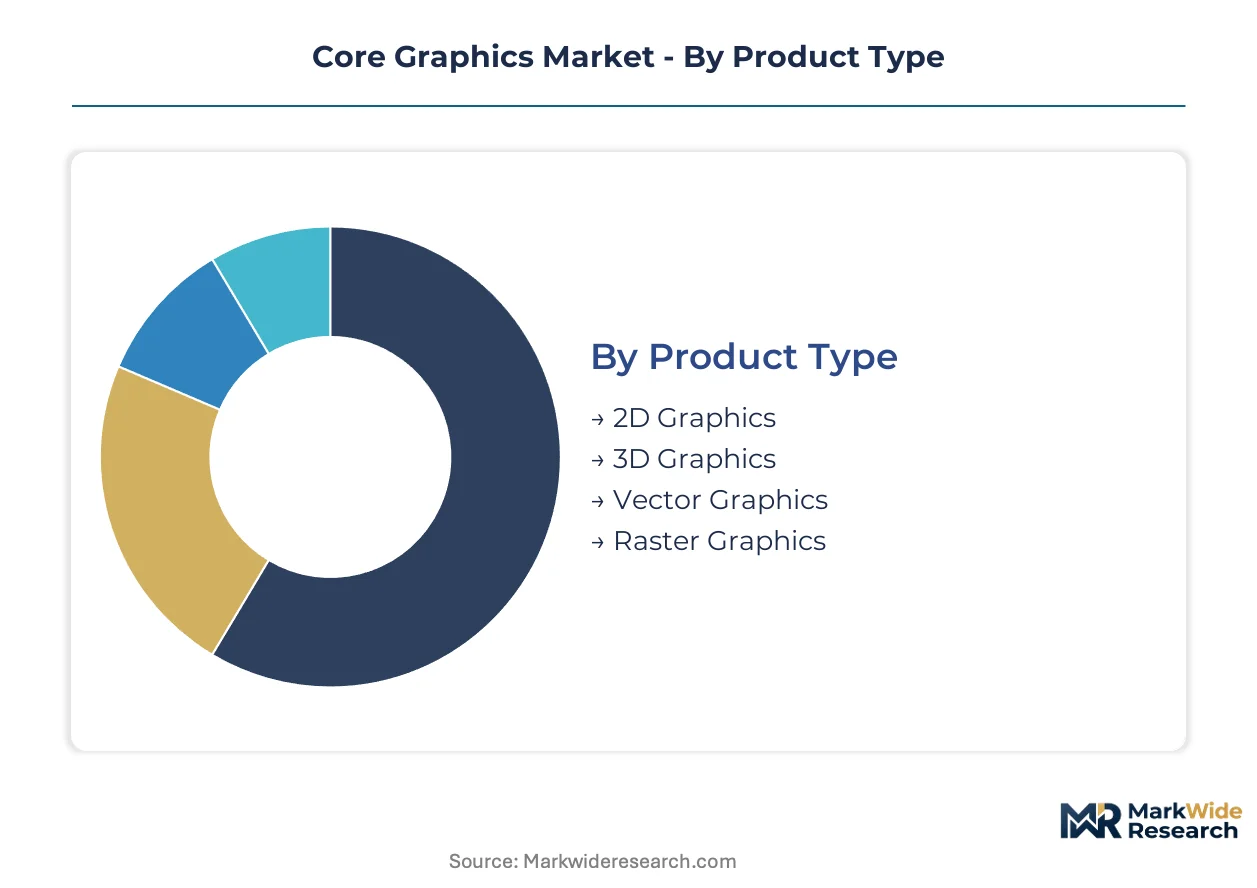
Graphics hardware and software vendors configure product roadmaps around four distinct segmentation axes. Each dimension carries different margin profiles, certification requirements, and upgrade cycle timing that reshape competitive positioning across the value chain.
Product Type:
Volume concentrates in real-time rasterization pipelines while premium tier pricing attaches to simulation-grade visualization systems.
- 3D Graphics:Polygon mesh processing with programmable shader pipelines dominates gaming and spatial computing attach rates. Demand concentrates in South Korea's esports broadcast infrastructure and Japan's automotive design studios where sub-20ms latency certification commands workstation premiums.
- 2D Graphics:Frame buffer compositing with vector-accelerated blitting serves UI rendering and digital signage backplanes. Browser engine developers and mobile OEMs in India drive volume through WebGL-optimized widget frameworks.
- Vector Graphics:Resolution-independent curve rasterization enables print-to-digital workflows. Adobe Illustrator plugin ecosystems and SVG animation tools for web advertising sustain niche demand.
- Raster Graphics:Pixel-array manipulation with fixed-function texture sampling retains legacy CAD and medical imaging display chains. HIPAA-regulated PACS workstations in the US maintain upgrade cycles for DICOM compliance.
Today's leader: 3D Graphics. Tomorrow's challenger: Vector Graphics.
Technology:
API adoption patterns split between proprietary stack control and cross-platform fragmentation reduction.
- Vulkan:Explicit multi-threading with reduced driver overhead expands into Android industrial displays and automotive instrument clusters. Khronos Group conformance testing investments by Samsung and Qualcomm accelerate embedded segment penetration.
- DirectX:Microsoft-integrated shader compilation with ray tracing extensions anchors PC gaming and Windows-based visualization. Xbox Series console attach rates and Flight Simulator modding communities sustain developer investment.
- OpenGL:Legacy immediate-mode and retained-mode contexts persist in enterprise CAD and GIS software stacks. ISO 9241-307 medical imaging delays fragment driver resources as vendors maintain backward compatibility.
- Metal:Apple-silicon-optimized command encoding with tile-based deferred rendering drives iOS gaming and macOS creative workflows. Cupertino's vertical integration into GPU design tightens ecosystem lock-in.
Vulkan gains share fastest in mobile and embedded. DirectX defends its PC gaming stronghold.
Application:
Revenue tilts toward interactive entertainment while professional visualization carries margin concentration.
- Gaming:Real-time engine licensing with asset pipeline tools generates recurring revenue through Unreal Engine royalty structures and Unity subscription tiers. Epic Games Store exclusivity contracts and Roblox creator economics reshape monetization models.
- Graphic Design:Creative cloud subscriptions for vector illustration and photo manipulation displace perpetual licenses. Adobe's direct-to-creator billing in South Korea and Japan leverages mobile-first payment infrastructure for render credit micro-transactions.
- Mobile Apps:Cross-platform framework rendering with Flutter and React Native abstracts native GPU access. India's PLI scheme assembly investments feed regional OEM demand for mid-tier Mali and Adreno silicon.
- Web Development:Canvas 2D and WebGPU standards enable browser-based visualization without plugin dependencies. Chrome's ANGLE translation layer and Firefox's WebRender compositor compete on JavaScript binding performance.
Gaming commands revenue concentration. Graphic Design offers margin expansion through subscription conversion.
End User:
Purchasing authority separates certified workstation procurement from self-service subscription activation.
- Enterprises:Volume licensing with ISV certification requirements drives Dell Precision and HP ZBook workstation deployments. EMA and CE marking frameworks for medical imaging displays cross-pollinate into professional visualization standards.
- Individual Developers:Monthly billing for render credits and asset store access sustains volume through GitHub Student Pack and indie game engine pricing. Blender Foundation's open-source tooling disrupts traditional license economics.
- Freelancers:Project-based software rental with portfolio-grade output requirements concentrates in motion graphics and architectural visualization. Upwork and Fiverr marketplace dynamics pressure tool selection toward deliverable compatibility.
- Educational Institutions:Campus-wide site licenses with curriculum integration sustain Autodesk and Adobe academic pricing. Japan's METI semiconductor education subsidies feed GPU supply security into university research clusters.
Enterprises anchor premium pricing. Individual Developers drive volume scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley established the foundational GPU architecture that scaled into gaming and professional visualization clusters. Taiwan's foundry ecosystem subsequently concentrated advanced node production for discrete graphics silicon. South Korea's memory fabrication and China's assembly capacity now complete the tripartite supply geography.
United States
Epic Games and Unity Technologies anchor real-time engine licensing from Raleigh and San Francisco. The FCC governs spectrum allocation for wireless VR streaming peripherals under Part 15 rules. Austin and Seattle house broadcast-grade rendering farms serving esports production pipelines.
South Korea
Government-backed arena infrastructure in Seoul and Busan sustains demand for 8K broadcast encoding hardware. The MFDS medical imaging standards cross-pollinate into workstation display certification requirements. Pangyo Techno Valley clusters fabless GPU design houses alongside SK Hynix memory packaging facilities.
China
Domestic cloud gaming platforms drive volume for ARM-based mobile GPU silicon. MIIT's integrated circuit industry guidelines redirect wafer allocation toward AI accelerators over consumer graphics. Shenzhen and Chengdu concentrate tablet OEM assembly lines with Mali and Adreno integration expertise.
Japan
Automotive design studios in Toyota City and Hiroshima mandate sub-20ms latency certification for virtual prototyping workstations. METI subsidizes domestic foundry capacity at Rapidus that feeds GPU supply security for regional OEMs. Tokyo's content production houses adopt path tracing hardware for anime pre-visualization workflows.
Germany
Automotive OEMs in Munich and Stuttgart deploy real-time ray tracing for digital twin factory simulations. The KBA's automotive software regulations shape functional safety requirements for instrument cluster GPUs. Berlin's creative agencies face EU AI Act compliance deadlines for generative graphics tool procurement.
Core Graphics Market Competitive Landscape
The competitive structure tilts toward vertically integrated semiconductor conglomerates with captive foundry relationships or guaranteed wafer allocation. Discrete GPU vendors compete on shader pipeline density and memory bandwidth architecture. Three archetypes dominate: fabless design houses with software ecosystem lock-in, IDMs with process-technology co-optimization, and IP licensing specialists serving mobile and embedded segments. Dominant competitive moves include strategic partnerships for cloud gaming infrastructure and portfolio diversification into AI training accelerators.
Among fabless design specialists, NVIDIA Corporation and Advanced Micro Devices occupy positions defined by compute ecosystem differentiation, while Intel Corporation exemplifies the IDM archetype with in-house fabrication integration. Samsung Electronics and Qualcomm Incorporated sit within the mobile-integrated tier where SoC GPU cores ship at billion-unit scale.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Advanced Micro Devices |
| Intel Corporation |
| Samsung Electronics |
| Qualcomm Incorporated |
| Imagination Technologies |
| Apple |
| Sony Corporation |
| Matrox Electronic Systems |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up creative software specialists enforce disciplined subscription pricing across European and Asian markets while securing long-term foundry allocation through prepayment structures that lock in wafer supply for AI-accelerator-competing GPU silicon.
Pricing Analysis
Three-tier pricing structure across premium workstation certification, standard creator subscription, and economy embedded licensing anchors revenue models. Price differentiation rests on ISO 9241-307 medical imaging certification and CUDA/ROCm ecosystem lock-in rather than raw compute metrics alone. Cost compression in the mid-tier subscription band is intensifying because Adobe and Autodesk channel partners report direct-to-creator billing displacing volume licensing. Individual developers exhibit highest price sensitivity, while enterprise procurement with ISV certification requirements absorbs premium workstation markups.
Supply Chain Analysis
Hub-and-spoke distribution through regional fulfillment centers in Singapore, Rotterdam, and Los Angeles feeds downstream system integrator assembly lines. Geographic supply concentrates in Taiwan for TSMC N3B node GPU silicon, South Korea for SK Hynix GDDR6X memory packaging, and China for tablet OEM Mali and Adreno integration. Raw material dependencies span photoresist chemicals, high-purity silicon wafers, and cobalt-free solder bump compositions. Single-source vulnerability at the TSMC foundry level creates allocation risk when AI accelerator wafer commitments surge. Distribution runs through direct OEM relationships and authorized reseller networks serving workstation certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Core Graphics Market compounds steadily as real-time ray tracing API adoption forces hardware refresh cycles across gaming and professional visualization segments.
For Market Incumbents: Anticipate shader compiler talent scarcity by acquiring specialized kernel optimization boutiques in Israel and Toronto before competitors lock in teams. Defend ecosystem position by extending CUDA and ROCm backward compatibility guarantees to enterprise CAD stacks resisting OpenGL migration, while pre-purchasing TSMC N3B allocation to secure supply against AI accelerator demand surges.
For New Entrants and Emerging Players: Capture white-space in Indian PLI scheme GPU assembly and testing investments where regional OEM supply chains lack domestic fabless design partners. Target spatial computing foveated rendering ASICs for surgical training and architectural walkthrough applications where certification barriers remain lower than medical imaging workstation tiers. Pursue direct hospital system partnerships bypassing traditional channel certification delays.
For Investors and Strategic Acquirers: Valuations sit cheapest among open-source tooling specialists with established Blender Foundation plugin ecosystems and proven Khronos Group conformance testing relationships. Five-to-ten-year viability hinges on neural radiance field convergence capabilities that bridge volumetric capture and real-time rasterization. Watch for EU AI Act enforcement deadline acceleration as the inflection signal triggering compliance-driven upgrade cycle spikes among European creative studios.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Prepayment Lock-in | TSMC N3B wafer allocation commitments secure supply against AI accelerator competition. |
| ISO 9241-307 Certification Investment | Medical imaging color accuracy validation opens premium workstation pricing tiers. |
| C2PA Provenance Metadata Integration | EU AI Act compliance embeds cryptographic signing into diffusion model output pipelines. |
| Mesh Shading Pipeline Migration | Nanite-scale geometry processing decentralization reduces CPU bottleneck dependency. |
| India PLI Assembly Localization | Domestic GPU testing investments feed regional OEM supply chain requirements. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with GPU platform engineers, game engine licensing executives, medical imaging procurement managers, and creative cloud subscription leads with secondary validation against SEC 10-K filings, Khronos Group conformance disclosures, hyperscaler capex reports, and EMA medical device guidance documents. Bottom-up segment sizing and top-down macro constraint triangulation anchored volume estimates.
Segment-weighting across product type, API technology, application vertical, and end-user purchasing authority dimensions structured the analytical framework across the projection horizon. CAGRs derived from fitted growth curves applied to attach-rate assumptions for real-time ray tracing hardware and subscription conversion patterns in South Korean and Japanese markets. Industry-specific inputs included TSMC foundry allocation disclosures and Adobe/Autodesk channel billing pattern shifts.
Foundry allocation competition from AI accelerators, EU AI Act enforcement timeline acceleration, and GDDR6X memory contract price volatility are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
North America Managed Mobility Service Market
Digital Solutions
Europe Smart Card Market
Digital Solutions
Global Service Delivery Platform Market
Digital Solutions
Assortment and Space Optimization (ASO) Market
Digital Solutions
Smart Signage Market
Digital Solutions
Crop Management Software Market
Digital Solutions
Global Advocacy Software Market
Digital Solutions
South Korea Digital Twin Market
Digital Solutions
Warranty Management System Market
Digital Solutions
System Integration Market
Digital Solutions
Global Process Orchestration Market
Digital Solutions
Global Surface Computing Market
Digital Solutions
Data Integration Market
Digital Solutions
Global Integration Platform As a Service (IPAAS) Market
Digital Solutions
Digital Project Delivery Solutions Market
Digital Solutions
AI Infrastructure Market