
 Interactive Projector Market | 2026-2036
Interactive Projector Market Size, Share, and Industry Trends Forecast 2026-2036
Interactive Projector Market Intelligence
Modular bundling of interactive projectors with wireless collaboration software and stylus kits is realigning procurement decisions across institutional buyers. Seiko Epson Corporation leverages its in-house 3LCD manufacturing to control component costs and supply stability. Panasonic Corporation anchors its position through deep integration with enterprise AV infrastructure and room-control ecosystems. BenQ Corporation differentiates by specializing in eye-care certifications and blue-light reduction for extended classroom use.
An interactive projector combines optical projection with infrared or camera-based touch detection, typically supporting multi-point input across display areas exceeding 100 inches diagonal for collaborative visualization. Laser phosphor and solid-state LED light engines now dominate new installations due to 20,000-hour maintenance-free operation cycles versus traditional lamp-based systems. Ultra short throw configurations lead volume in education deployments by eliminating shadow interference and reducing installation footprint, while portable units represent the fastest-growing category as hybrid work patterns sustain demand for reconfigurable meeting spaces. Corporate end users command the strongest margin pools due to integration requirements with unified communications platforms.
FCC equipment authorization rules in the United States govern radio-frequency emissions from embedded wireless casting modules, while REACH and RoHS frameworks in Europe restrict hazardous substances in optical components and circuit assemblies. CE marking requirements under the EU's Radio Equipment Directive further condition market access for models with Wi-Fi and Bluetooth connectivity. Stakeholders must monitor evolving energy efficiency thresholds from regulators and decide whether to absorb certification costs or narrow geographic focus.
Market Dynamics
The transition from lamp-based to solid-state illumination is compressing replacement cycles and forcing manufacturers to restructure service revenue models around laser phosphor and LED engines with 20,000-hour lifespans.
Growth Catalysts
- EU Ecodesign mandates:Energy efficiency thresholds under the Ecodesign Directive are accelerating procurement of laser-based interactive projectors in German smart classrooms and corporate training facilities.
- Touch-enabled collaboration:Multi-point infrared detection systems now support 100-inch diagonal displays, enabling real-time annotation in Bavarian and North Rhine-Westphalia educational institutions.
- Hybrid workspace reconfiguration:Portable ultra short throw units are displacing fixed installations as enterprises in the United States prioritize reconfigurable meeting spaces.
Market Restraints
- DMD chip supply concentration:Texas Instruments maintains captive production of digital micromirror devices, creating single-source dependency for DLP-based interactive projector manufacturers.
- Input cost volatility:Rare earth phosphors used in laser light engines face price instability tied to Chinese export quota policies.
- Flat-panel substitution:Interactive whiteboards and direct-view LED displays compete for wall-mounted applications in classrooms below 85-inch diagonal requirements.
Strategic Opportunities
- Underpenetrated K-12 infrastructure:Eastern European markets including Poland and Romania show low interactive display penetration relative to Western European procurement rates.
- Wireless casting integration:Wi-Fi 6E and Bluetooth 5.3 modules enable seamless screen mirroring from mobile devices, opening channel partnerships with unified communications platforms.
- India smart classroom initiatives:Central and state government digital education schemes create tender opportunities for touch-enabled projection systems in government schools.
Industry Challenges
- Calibration complexity:Multi-point touch alignment requires specialized technicians, creating service bottlenecks in remote deployment scenarios.
- CE marking timeline compression:EU Radio Equipment Directive certification for embedded wireless modules extends product launch cycles by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interactive Projector Market |
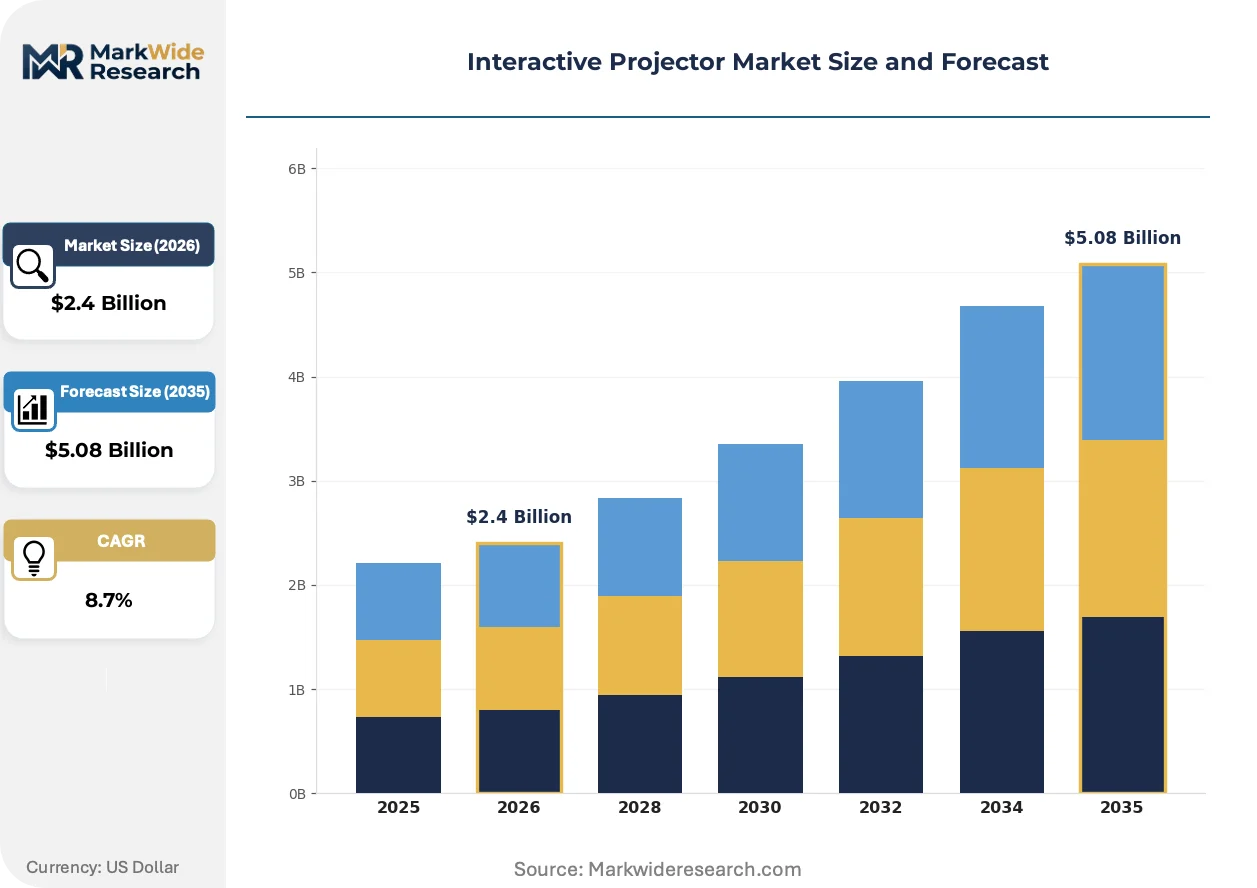
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Short Throw, Ultra Short Throw, Portable, Fixed Installation Technology: Laser, LED, LCD, DLP End User: Education, Corporate, Entertainment, Healthcare Installation Type: Wall-Mounted, Ceiling-Mounted, Mobile, Permanent |
| Companies Covered | Panasonic Corporation, Optoma Corporation, Seiko Epson Corporation, ViewSonic Corporation, Sony Corporation, BenQ Corporation, NEC Display Solutions Ltd., LG Electronics Inc., Dell Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interactive Projector Market Strategic Shifts & Innovations
Laser phosphor illumination is displacing legacy lamp architectures across institutional procurement, while regulatory pressure on hazardous substances and buyer demand for wireless integration are reshaping product development priorities.
AI-powered auto-calibration is expanding into interactive projector deployments by eliminating manual touch-point mapping. School districts in Germany are adopting self-optimizing units to reduce on-site technical support requirements. This capability is expanding into remote management platforms that enable centralized fleet monitoring across multi-campus installations.
REACH substance restrictions are forcing reformulation of optical adhesives and solder compositions in European-bound products. Manufacturers must validate alternative chemistries for RoHS compliance without degrading thermal performance in laser diode assemblies. German procurement authorities now require full material disclosure documentation as a mandatory bid evaluation criterion.
Institutional buyers are consolidating vendor relationships through framework agreements that bundle hardware, software licensing, and multi-year maintenance. This pattern is displacing transactional procurement in United States K-12 districts and corporate facilities management. Germany's federal-state cooperative purchasing structures exemplify this concentration, with Bavaria and North Rhine-Westphalia leading aggregated tender volumes.
Interactive Projector Market Segmentation
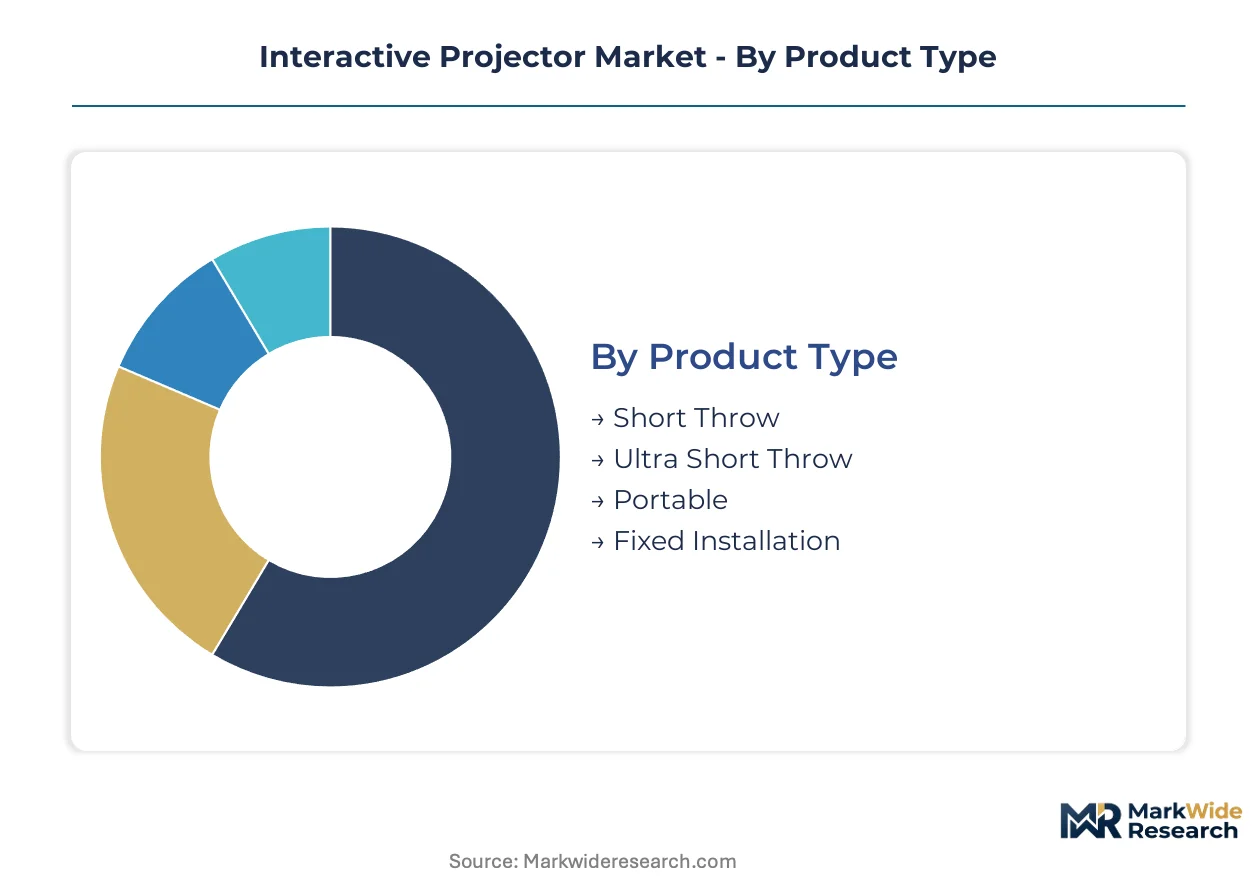
Product architecture in the Interactive Projector Market fragments across throw distance, illumination technology, and deployment flexibility. Each segment carries distinct certification burdens and margin profiles that reshape vendor positioning.
Product Type:
CE marking under the EU Radio Equipment Directive applies universally, though portable units face additional FCC equipment authorization for embedded wireless casting modules. Wall-mounted and ceiling-mounted configurations trigger separate electrical safety certifications.
- Ultra Short Throw:These projectors position inches from display surfaces, eliminating shadow interference in collaborative environments. Bavarian smart classrooms mandate these configurations to maximize usable wall space in aging school infrastructure.
- Portable:Battery-enabled and lightweight designs support reconfigurable meeting spaces. Hybrid work patterns in the United States sustain procurement velocity for units with integrated Wi-Fi 6E and Bluetooth 5.3 connectivity.
- Short Throw:Mid-range positioning requires moderate installation distance with reduced shadow effects.
- Fixed Installation:Permanent mounting with hardwired power and data connections dominates auditorium-scale deployments.
Leading the category by volume: Ultra Short Throw. Growing fastest: Portable.
Technology:
Light engine selection determines REACH and RoHS compliance complexity for European-bound shipments. Laser phosphor and LED architectures simplify hazardous substance documentation versus legacy lamp systems.
- Laser:Phosphor-converted solid-state illumination delivers 20,000-hour maintenance-free operation. German corporate training facilities prioritize these units under Ecodesign Directive procurement mandates.
- DLP:Digital micromirror devices from Texas Instruments enable high-contrast projection with compact optical engines. Supply concentration creates procurement risk for manufacturers dependent on single-source DMD chips.
- LED:RGB solid-state arrays offer instant on/off and color stability without warm-up cycles.
- LCD:3LCD architectures from in-house manufacturing lines provide cost control and supply stability.
Dominating institutional procurement: Laser. Expanding most quickly: LED.
End User:
Application context dictates performance specifications and service contract structures. Education buyers prioritize eye-care certifications; corporate buyers demand unified communications integration.
- Education:K-12 and higher education institutions drive volume through aggregated tender structures. North Rhine-Westphalia's cooperative purchasing pools specify multi-point touch detection across 100-inch diagonal displays.
- Corporate:Enterprise training rooms and reconfigurable meeting spaces command premium pricing through software integration requirements. These buyers bundle hardware with wireless collaboration platforms and multi-year maintenance agreements.
- Entertainment:Museums and immersive experience venues require high-brightness output for ambient light tolerance.
- Healthcare:Medical training and surgical simulation applications demand color accuracy and sterilizable surface compatibility.
Generating highest shipment volumes: Education. Delivering strongest margins: Corporate.
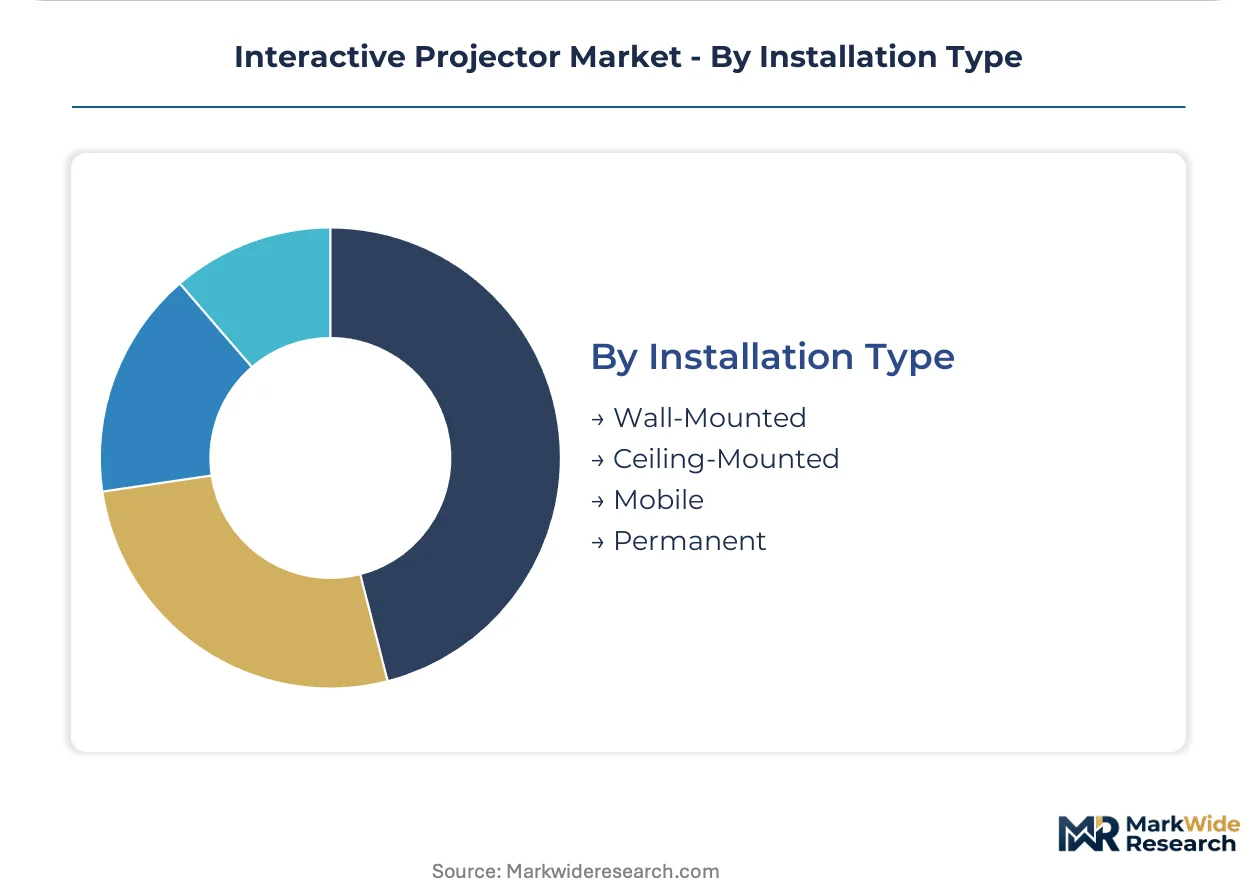
Installation Type:
Mounting configuration determines calibration complexity and ongoing service requirements. Multi-point touch alignment demands specialized technician deployment for permanent installations.
- Ceiling-Mounted:Overhead positioning maximizes floor space in compact classrooms. German procurement authorities require full material disclosure documentation for these deployments under framework agreement evaluation criteria.
- Mobile:Cart-based units with integrated computing and power enable rapid room reconfiguration. These systems reduce installation lead times for temporary training facilities and event spaces.
- Wall-Mounted:Flush surface integration competes with interactive flat panels in sub-85-inch diagonal applications.
- Permanent:Built-in architectural integration with dedicated electrical and HVAC infrastructure serves auditorium and lecture hall scales.
Capturing greatest deployment share: Ceiling-Mounted. Gaining share fastest: Mobile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of interactive projection hardware concentrates in East Asian electronics clusters, while procurement demand clusters in German smart classroom programs and United States corporate reconfiguration projects. Consumption patterns diverge sharply between mature replacement markets and first-installation growth corridors.
United States
Hybrid work patterns sustain procurement velocity for portable ultra short throw units with integrated wireless casting. FCC equipment authorization rules govern radio-frequency emissions from embedded Wi-Fi and Bluetooth modules in these devices. Corporate facilities in Austin and Seattle prioritize reconfigurable meeting spaces over fixed auditorium installations.
Germany
Bavarian and North Rhine-Westphalia state mandates accelerate aggregated tender volumes for touch-enabled projection systems. EU Ecodesign Directive thresholds filter procurement toward laser phosphor architectures with documented energy efficiency. Stuttgart's industrial automation sector sources ceiling-mounted units for training room standardization.
China
Domestic education technology budgets support volume deployment of short throw configurations in provincial urban districts. MIIT certification requirements and GB standards condition market access for wireless-enabled models. Shenzhen electronics clusters supply optical engines and DLP subassemblies to branded projector manufacturers.
India
Central and state government digital education schemes create tender opportunities for touch-enabled systems in government schools. BIS certification and CEA electrical safety standards regulate classroom equipment procurement. Hyderabad and Bangalore technology corridors pilot smart classroom infrastructure in public-private partnership models.
Japan
Corporate training facilities and museum installations sustain demand for high-brightness laser phosphor units. METI energy efficiency guidelines and JIS standards shape product specifications for domestic-bound shipments. Osaka manufacturing clusters produce precision optical components for regional projector assembly.
Interactive Projector Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the interactive projector market. The vendor base spans three tiers: diversified electronics conglomerates with captive display divisions, dedicated projection technology specialists, and regional system integrators. Strategic archetypes include in-house light engine manufacturers controlling component costs, software-integrated platform providers capturing service revenue, and eye-care certification specialists targeting education verticals. Competitive moves concentrate on wireless collaboration partnerships and laser phosphor portfolio transitions.
Among diversified Japanese electronics conglomerates, Panasonic Corporation and Seiko Epson Corporation anchor the premium institutional tier through integrated manufacturing and supply chain control. Optoma Corporation exemplifies the specialist archetype focused on projection-centric portfolios. These three occupy positions that reflect distinct strategic bets: captive component production versus platform integration versus dedicated category focus.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Optoma Corporation |
| Seiko Epson Corporation |
| ViewSonic Corporation |
| Sony Corporation |
| BenQ Corporation |
| NEC Display Solutions Ltd. |
| LG Electronics Inc. |
| Dell Technologies Inc. |
| Others |
Cost & Logistics Intelligence
Family-owned optical component specialists in Japan and Taiwan anchor upstream supply networks for interactive projection hardware, translating captive manufacturing control into pricing discipline that resists commoditization pressures from Chinese LED assemblers. Their ownership structures enable long-term supplier relationships without quarterly margin pressure, stabilizing input costs for laser phosphor engines even as rare earth phosphor markets fluctuate.
Pricing Analysis
Cost-down pressure on portable units accelerates as Wi-Fi 6E module integration raises bill-of-materials complexity without proportional buyer willingness to pay. Three-tier pricing structure across premium laser phosphor, standard LED, and economy lamp-based tiers separates buyers by maintenance contract bundling rather than hardware specifications alone. German education authorities exhibit lowest price sensitivity due to framework agreement consolidation, while Indian government tender processes drive aggressive reverse-auction dynamics. Price differentiation hinges on CE marking tier and eye-care certification grade.
Supply Chain Analysis
Refurbishment flows for laser phosphor engines create secondary supply channels that extend component lifecycles and dampen replacement demand for original equipment. Manufacturing concentrates in China, Japan, and Taiwan, with Shenzhen electronics clusters supplying DLP subassemblies and Osaka precision optics feeding laser diode assemblies. Rare earth phosphors and Texas Instruments DMD chips constitute critical dependencies, with Chinese export quotas introducing single-source vulnerability. Distribution runs through AV systems integrators and education technology resellers rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interactive projector market consolidation is accelerating as REACH compliance costs and laser phosphor R&D thresholds eliminate sub-scale competitors unable to fund dual certification and illumination technology transitions simultaneously.
For Market Incumbents: Hedge against flat-panel substitution by deepening software integration partnerships with unified communications platforms and accelerating wireless casting module standardization. Capture service revenue through multi-year maintenance contracts that offset compressed hardware margins. Prioritize in-house laser phosphor engine production to reduce rare earth supply exposure.
For New Entrants and Emerging Players: AI-powered auto-calibration capabilities offer entry wedges into German and Eastern European education markets where technical service bottlenecks constrain incumbent deployment velocity. Target underpenetrated K-12 infrastructure in Poland and Romania through channel partnerships with regional AV integrators. Lead with portable form factors and subscription-based software licensing to bypass capital-intensive fixed installation competition.
For Investors and Strategic Acquirers: Bavarian state tender volume acceleration is the leading indicator that framework agreement consolidation will concentrate procurement among three to four national vendors within the next decade. Acquire specialists with captive laser engine manufacturing and established CE marking documentation rather than pure-play software integrators. Monitor Texas Instruments DMD supply allocation announcements as inflection signals for DLP-dependent manufacturer distress.
| Strategic Initiative | Industry Significance |
|---|---|
| Laser Phosphor Portfolio Transition | REACH compliance and Ecodesign mandates in Germany render lamp-based architectures non-competitive for institutional tenders. |
| Wireless Collaboration Platform Integration | Corporate buyers in Austin and Seattle prioritize seamless screen mirroring over standalone projection specifications. |
| AI-Powered Auto-Calibration Development | German school districts adopt self-optimizing units to reduce on-site technical deployment requirements. |
| Eastern European Channel Partnership | Poland and Romania show interactive display penetration gaps versus Western European procurement rates. |
| Framework Agreement Consolidation | Bavaria and North Rhine-Westphalia cooperative purchasing pools favor vendors with multi-year maintenance bundling. |
Research Approach
SEC filings from publicly traded display technology manufacturers, EU tender documentation from TED (Tenders Electronic Daily), and MIIT certification records formed the secondary backbone of this analysis. Primary fieldwork incorporated structured interviews with education technology procurement officers, AV systems integrators, and optical component sourcing managers. Bottom-up shipment estimates by product configuration triangulated against top-down education and corporate IT spending forecasts.
Historical trendline analysis of lamp-to-laser transition cycles informed projection assumptions across the modeling period. Segmentation dimensions included throw distance architecture, illumination technology, end-user vertical, and regional regulatory cluster. CAGRs derived from weighted average of technology adoption curves and replacement cycle compression. Forecast inputs incorporated Ecodesign Directive threshold enforcement timelines and Texas Instruments DMD supply allocation patterns.
Several conditions sit outside the modeled scope, including abrupt Chinese rare earth export restrictions, breakthrough direct-view LED cost parity below 85-inch diagonal, and pandemic-scale disruptions to classroom infrastructure spending. Practitioners should monitor Bavarian tender volume trajectories and REACH substance restriction amendments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Cloud Based Manufacturing Market
Digital Solutions
Smart Recording Pen Market
Digital Solutions
Weather Information Technologies Market
Digital Solutions
Europe Digital Signage Market
Digital Solutions
Global Interactive Voice Response Market
Digital Solutions
Customer Engagement Hub (CEH) Market
Digital Solutions
Digital Commerce Software Market
Digital Solutions
Thin Client Market
Digital Solutions
Farm Management Software Market
Digital Solutions
US Supply Chain Management Software Market
Digital Solutions
Global E-Visa Market
Digital Solutions
Global Hybrid Integration Platform Market
Digital Solutions
Agent-Oriented Enterprise Architecture Market
Digital Solutions
Harbor Management Software Market
Digital Solutions
Electronic Contract Manufacturing and Design Services Market
Digital Solutions
Computer Aided Design (CAD) Market