
 Accounts Receivable Automation Market | 2026-2036
Accounts Receivable Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Accounts Receivable Automation Market Intelligence
Invoice-to-cash workflow optimization is reconfiguring margin pools away from manual processing toward automated exception handling and predictive collection scheduling. HighRadius leverages machine learning models for cash application to sustain its position in large-enterprise deployments. Versapay anchors its competitive stance through embedded B2B payment networks that connect buyers and suppliers directly. Gaviti specializes in mid-market collections automation, occupying a segment where sales-led onboarding still differentiates vendor selection.
Accounts receivable automation encompasses software platforms that digitize invoicing, payment matching, credit risk assessment, and collection workflows through rule engines and API-driven data exchange, typically processing remittance data in structured formats such as EDI 820 or ISO 20022 XML. These systems reduce days sales outstanding and manual reconciliation overhead for finance operations teams managing high transaction volumes across dispersed customer bases. Cloud-based deployment models lead adoption as enterprises prioritize elastic infrastructure and rapid ERP integration without capital expenditure commitments. Invoice Management and Payment Processing solution types capture the largest installed base, while Collection Automation represents the fastest structural expansion as predictive analytics mature.
ISO standards, SOC 2 Type II frameworks, and regional data residency requirements shape platform architecture decisions and vendor qualification criteria for finance technology procurement. The US SEC's climate disclosure rules and EU CSRD reporting obligations extend data traceability requirements into receivables data, affecting how platforms archive payment records and audit trails. Stakeholders must evaluate whether their automation investments align with evolving ESG data lineage standards before committing to multi-year ERP integration roadmaps.
Market Dynamics
ISO 20022 migration across payment networks is collapsing legacy data interchange protocols, forcing treasury departments to re-architect cash application workflows around structured XML remittance formats rather than flat-file EDI standards.
Growth Catalysts
- Embedded AI in Credit Decisioning:Machine learning models now assess buyer default probability in real time, compressing credit approval cycles from weeks to hours for mid-market manufacturers.
- US SEC Climate Disclosure Rules:Mandatory Scope 3 emissions tracking extends data lineage requirements into supplier payment records, accelerating platform investments for audit trail automation.
- India:RBI's push for digital payment infrastructure and GST e-invoicing mandates is driving ERP modernization among SME distributors, creating fertile ground for cloud-native receivables platforms.
Market Restraints
- Legacy ERP Integration Costs:SAP and Oracle on-premise instances require custom API development that consumes 40-60% of implementation budgets, slowing deployment velocity.
- Banking Network Concentration:SWIFT message standards and correspondent banking relationships remain concentrated among European and North American clearing institutions, creating single-point-of-failure risks for cross-border cash application.
- Data Residency Fragmentation:GDPR, India's DPDP Act, and China's PIPL impose conflicting localization requirements that fragment cloud architecture strategies and inflate compliance overhead.
Strategic Opportunities
- Germany's Mittelstand:Family-owned industrial exporters remain underpenetrated by automated collections, presenting white space for predictive analytics vendors with German language support and local hosting.
- Real-Time Payment Convergence:The intersection of open banking APIs and instant settlement rails (FedNow, SEPA Instant) enables dynamic discounting and supply chain finance integration previously impossible with batch processing.
- EU CSRD Reporting Obligations:Mandatory sustainability disclosures create demand for receivables platforms that can tag payment data with ESG metadata and generate auditor-ready carbon footprint reports.
Industry Challenges
- Treasury Technology Talent Scarcity:Finance operations teams lack personnel fluent in both accounting principles and API configuration, creating implementation bottlenecks that extend project timelines.
- Multi-ERP Harmonization Complexity:Enterprises running acquired subsidiaries on disparate systems (NetSuite, Microsoft Dynamics, SAP) face data model incompatibilities that break automated matching algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Accounts Receivable Automation Market |
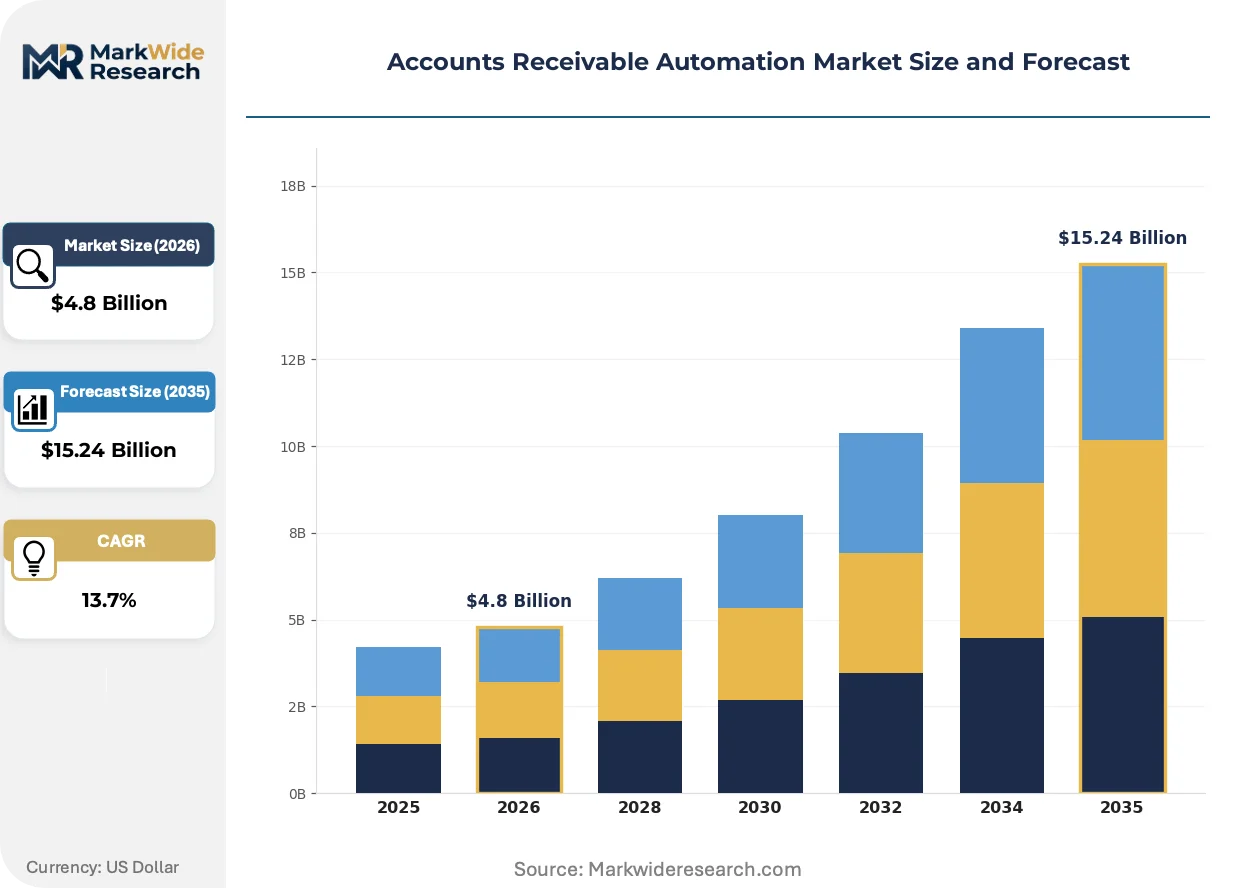
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Invoice Management, Payment Processing, Credit Management, Collection Automation, Reporting & Analytics Deployment Model: Cloud-based, On-premises, Hybrid, Hosted, SaaS End User Industry: Manufacturing, Telecommunications, Banking & Finance, Healthcare Providers, Wholesale & Distribution, Education Integration Capability: ERP Systems, CRM Platforms, Billing Software, Accounting Tools, Payment Gateways, Third-party APIs |
| Companies Covered | Quadient AR, Gaviti, HighRadius, Versapay, TreviPay, Billtrust, Tesorio, LedgerUp, FinFloh, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Accounts Receivable Automation Market Strategic Shifts & Innovations
Machine learning is collapsing traditional boundaries between payment processing, credit risk, and working capital optimization, creating unified platforms that anticipate cash flow disruptions before they materialize.
Natural language processing engines are collapsing unstructured remittance data—emails, PDFs, vendor portals—into structured cash application records without human intervention. Mid-market enterprises with 10,000+ monthly invoices but limited IT staff are adopting these tools fastest, compressing reconciliation cycles from days to minutes and eliminating offshore shared service centers previously required for manual matching.
The EU's Digital Operational Resilience Act (DORA) mandates financial entities to demonstrate continuity in critical ICT systems, including third-party payment infrastructure. Receivables automation vendors serving European banks must now certify operational resilience and incident reporting capabilities, reshaping procurement criteria toward vendors with established EU regulatory footprints rather than newer entrants.
Buyer self-service portals are displacing traditional collections call centers as the primary touchpoint for invoice disputes and payment scheduling. Industrial distributors in the United States now prioritize platforms with embedded collaboration tools that let procurement teams flag discrepancies directly, reducing DSO by eliminating email chains and phone tag between accounts payable and receivable departments.
Accounts Receivable Automation Market Segmentation
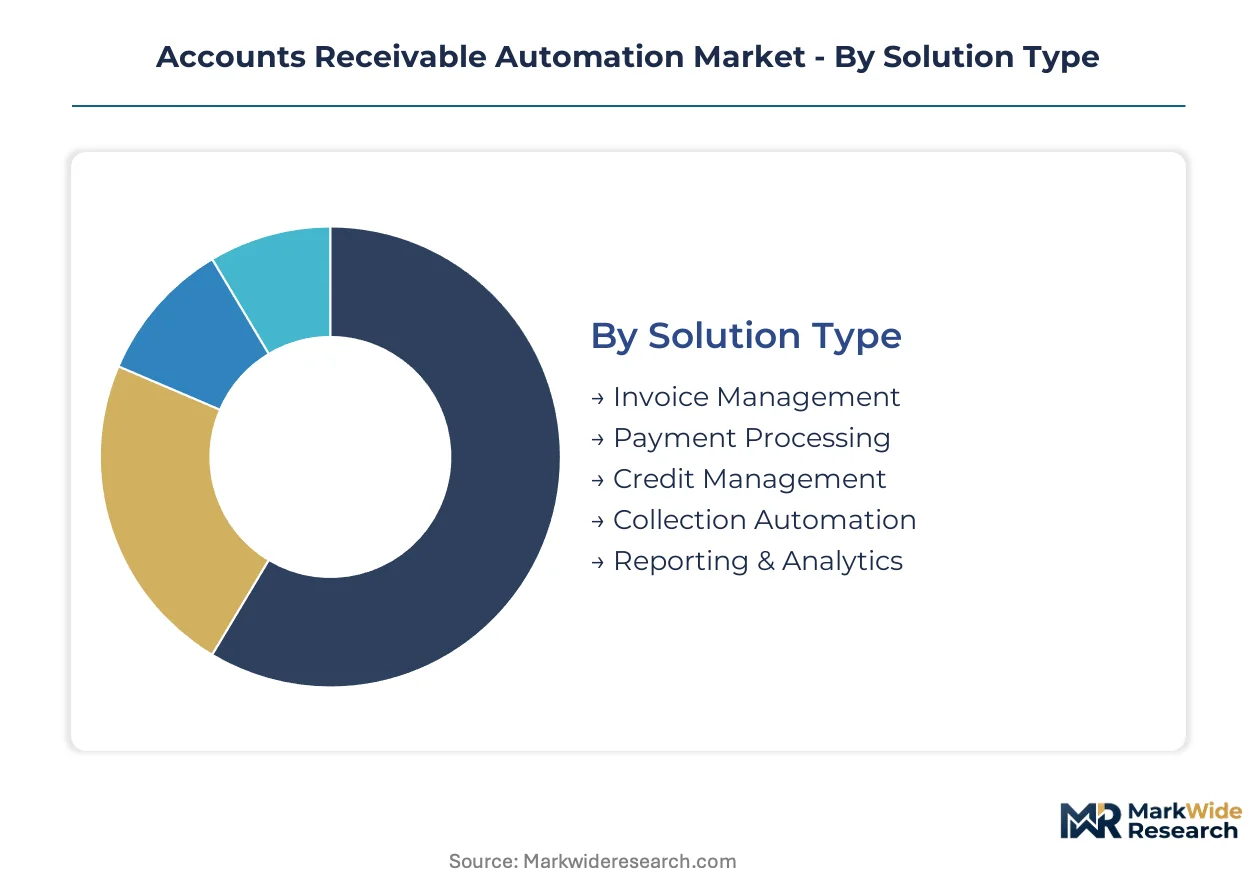
Segmentation in accounts receivable automation reveals distinct technology refresh cycles across deployment models and solution types. Invoice-to-cash workflows vary dramatically in implementation velocity between cloud-native platforms and legacy on-premise retrofits.
Solution Type:
Cycle times compress from weeks for basic invoice digitization to months for predictive collection systems requiring machine learning training data.
- Invoice Management:Core platforms digitize paper and PDF invoices through optical character recognition and validation rules against purchase orders. Manufacturing procurement teams in Germany drive demand as Mittelstand exporters modernize legacy EDI workflows to meet ISO 20022 compliance deadlines.
- Payment Processing:Systems automate remittance capture across ACH, wire, card, and instant payment rails with intelligent cash application algorithms. US healthcare providers prioritize these tools to reconcile patient payments against complex insurance adjudication records while satisfying HIPAA audit requirements.
- Credit Management:Real-time risk scoring engines integrate bureau data and trade references for automated credit limit decisions.
- Collection Automation:Predictive analytics prioritize outreach sequences and dynamically adjust dunning strategies based on payment behavior patterns.
- Reporting & Analytics:Dashboards consolidate DSO, aging, and cash flow forecasting across dispersed business units and ERP instances.
Invoice Management dominates installed base. Collection Automation is where expansion concentrates.
Deployment Model:
Cost tiers separate capital-intensive on-premise installations from operational expenditure models favored by mid-market treasury departments.
- Cloud-based:Elastic infrastructure scales transaction volumes without hardware procurement cycles, with SOC 2 Type II certification standard for finance technology procurement. Indian SME distributors adopt fastest following RBI digital payment mandates and GST e-invoicing requirements.
- SaaS:Subscription pricing eliminates upfront license fees while embedding continuous compliance updates for evolving data residency regulations. US mid-market enterprises with limited IT staff gravitate toward pre-configured ERP connectors that accelerate time-to-value.
- On-premises:Perpetual licenses retain appeal for defense contractors and government entities with classified data handling requirements.
- Hybrid:Sensitive credit data remains on-site while payment processing leverages cloud scalability.
- Hosted:Single-tenant managed deployments address data localization mandates in fragmented regulatory environments.
Cloud-based deployments capture the majority of new bookings. SaaS is climbing the fastest as procurement teams shift from CapEx to OpEx budgeting.
End User Industry:
Application complexity varies from standardized retail payment matching to intricate healthcare claims reconciliation spanning multiple payer contracts.
- Manufacturing:Complex order-to-cash cycles with international letters of credit, advance payment terms, and trade finance instruments demand sophisticated multi-currency cash application. German automotive suppliers lead adoption as they restructure workflows around SEPA Instant and supply chain finance integration.
- Banking & Finance:Institutions require real-time liquidity visibility across correspondent banking networks and regulatory reporting automation for central bank reserve requirements. EU DORA compliance is accelerating vendor consolidation toward platforms with established operational resilience certifications.
- Telecommunications:High-volume subscriber billing with recurring revenue models and complex promotional pricing structures.
- Healthcare Providers:Patient responsibility estimation, insurance eligibility verification, and denial management workflows.
- Wholesale & Distribution:Seasonal inventory financing and vendor-managed inventory programs with dynamic discounting.
- Education:Tuition payment plans, financial aid disbursement, and auxiliary service billing.
Manufacturing retains the deepest penetration. Banking & Finance is gaining share fastest as open banking APIs enable new working capital products.
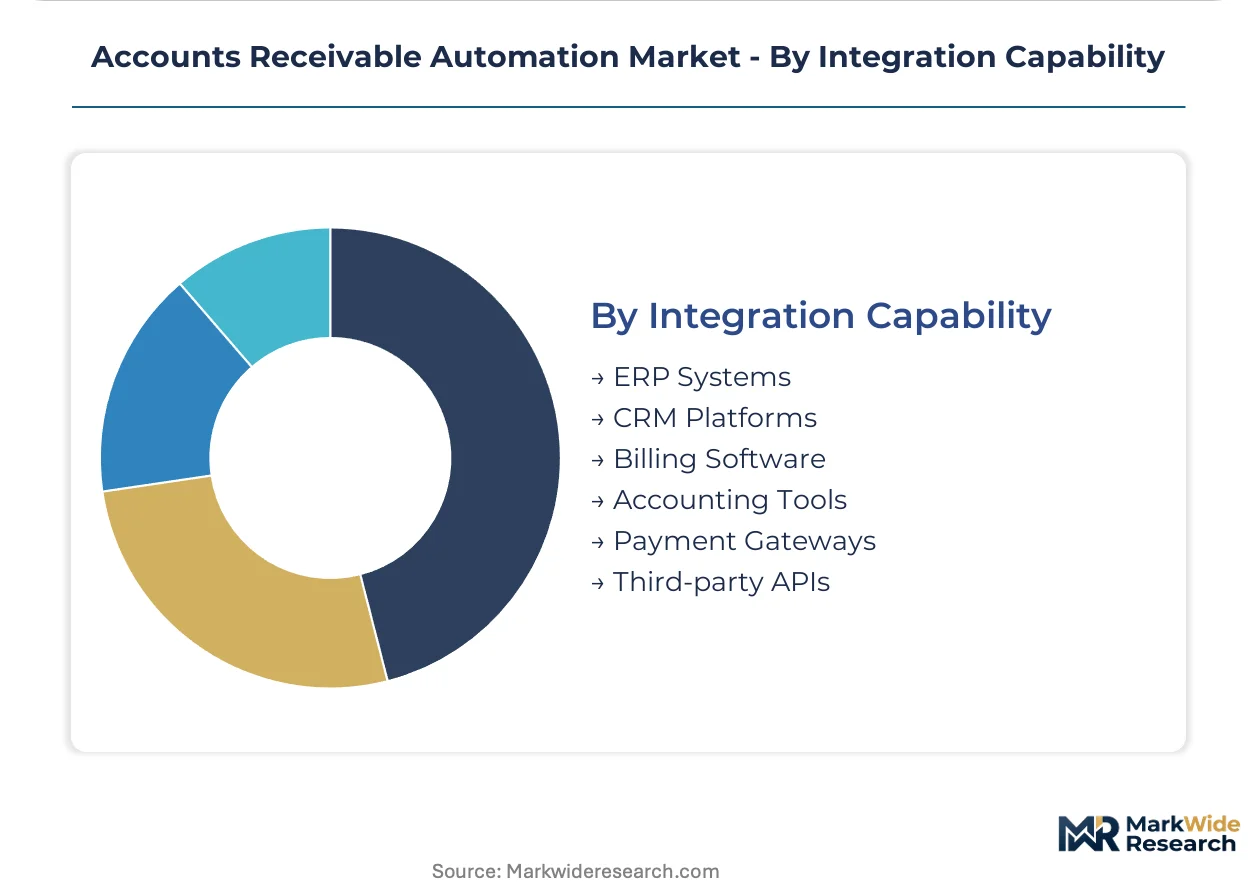
Integration Capability:
Volume concentration determines API development priorities, with SAP and Oracle connectors consuming disproportionate vendor engineering resources.
- ERP Systems:Pre-built connectors for SAP S/4HANA, Oracle NetSuite, and Microsoft Dynamics extract master data and post journal entries automatically. Implementation timelines stretch longest for SAP on-premise instances requiring custom field mapping and legacy data migration.
- Payment Gateways:Direct integration with Stripe, Adyen, and banking APIs enables real-time payment status updates and automated reconciliation. US distributors prioritize these connections to capture early payment discounts through dynamic discounting platforms.
- CRM Platforms:Salesforce and HubSpot synchronization links sales commitments to credit decisions and collection activities.
- Billing Software:Zuora, Chargebee, and specialized industry billing engines feed usage data into receivables workflows.
- Accounting Tools:QuickBooks and Xero connectivity serves the long tail of SME customers with simpler reconciliation needs.
- Third-party APIs:Credit bureaus, trade credit insurers, and supply chain finance platforms extend platform functionality.
ERP Systems integration commands the largest implementation budgets. Payment Gateways integration is where vendor R&D investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software engineering for receivables automation clusters in the United States, Germany, and India, with each geography cultivating distinct platform specializations shaped by local payment infrastructure and regulatory mandates.
United States
FedNow instant payment adoption and HIPAA audit requirements drive healthcare provider demand for automated reconciliation. The SEC's climate disclosure rules extend data lineage obligations into supplier payment records. Dallas-based distributors prioritize platforms with dynamic discounting to capture early payment incentives.
Germany
SEPA Instant migration and ISO 20022 compliance deadlines pressure Mittelstand exporters to modernize legacy EDI workflows. The EU's Digital Operational Resilience Act mandates operational continuity certifications for bank-facing platforms. Stuttgart automotive suppliers lead adoption of supply chain finance integration.
India
RBI digital payment infrastructure expansion and GST e-invoicing mandates accelerate ERP modernization among SME distributors. The Digital Personal Data Protection Act imposes localization requirements on cloud architectures. Mumbai-based manufacturing clusters adopt cloud-native receivables platforms fastest.
United Kingdom
Open banking API maturity and real-time account information services enable dynamic working capital products. The Financial Conduct Authority's operational resilience expectations shape vendor procurement criteria. London fintech clusters drive innovation in embedded B2B payment networks.
Japan
METI's push for cashless payment targets and SME digitization subsidies expand addressable market for automation vendors. JIS standards for financial data interchange create compliance benchmarks for platform entry. Osaka manufacturing exporters seek multi-currency cash application for regional trade settlement.
Accounts Receivable Automation Market Key Industry Players
Enterprise-scale platforms and mid-market specialists split the market along implementation complexity and sales motion dimensions. Consolidation pressures intensify as treasury departments prioritize pre-built ERP connectors over custom integration projects. Three archetypes dominate: cloud-native challengers with API-first architectures, legacy processors retrofitting payment infrastructure, and vertical specialists embedding industry-specific compliance rules. M&A activity concentrates on payment network access and machine learning talent acquisition.
Within the enterprise automation tier, HighRadius and Versapay exemplify divergent strategic positions. HighRadius anchors large-enterprise deployments through machine learning-intensive cash application. Versapay occupies the embedded B2B network space, connecting buyers and suppliers directly. Gaviti represents the mid-market specialist archetype, where sales-led onboarding and collections workflow depth differentiate vendor selection among manufacturers with limited IT staff.
| Leading Market Players |
|---|
| Quadient AR |
| Gaviti |
| HighRadius |
| Versapay |
| TreviPay |
| Billtrust |
| Tesorio |
| LedgerUp |
| FinFloh |
| Others |
Cost & Logistics Intelligence
Bangalore's cloud engineering clusters anchor platform development capacity for receivables automation vendors, concentrating R&D talent in a geography where salary arbitrage compresses implementation costs for mid-market buyers while premium-tier providers maintain pricing power through proprietary machine learning architectures.
Pricing Analysis
SOC 2 Type II certification dictates the pricing tier structure for enterprise procurement, separating audited platforms from uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects integration complexity and ERP connector breadth. Cost compression in the mid-market tier is intensifying because cloud-native entrants are collapsing implementation timelines. SME distributors with limited IT staff exhibit highest price sensitivity, while multinational manufacturers prioritize total cost of ownership over subscription rates.
Supply Chain Analysis
Systems integrators and specialized ERP consultancies hold implementation capacity, with Accenture, Deloitte, and regional SAP partners commanding project delivery. Platform engineering draws from India, Ireland, and Poland, where API development talent concentrates. Cloud infrastructure rests on AWS, Azure, and Google Cloud data center networks. Single-source vulnerability emerges from concentrated banking API partnerships with SWIFT and major clearing institutions. Distribution runs through direct enterprise sales, channel partners, and system integrator co-sell arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Treasury technology talent scarcity constrains deployment velocity, creating competitive advantage for vendors with pre-built ERP connectors and managed implementation services that bridge accounting knowledge with API configuration expertise.
For Market Incumbents: Insulate large-enterprise relationships by deepening machine learning differentiation in cash application algorithms and securing exclusive banking API partnerships. Acquire mid-market specialists to capture the fastest-expanding segment before cloud-native challengers establish vertical footholds. ISO 20022 migration timelines present a critical lever for locking in multi-year contracts.
For New Entrants and Emerging Players: Germany's Mittelstand exporters represent substantial underpenetrated white space, where family-owned industrial distributors still rely on manual collections workflows. Target Indian SME distributors responding to RBI digital payment mandates and GST e-invoicing requirements. Embed supply chain finance capabilities to differentiate from standalone collections tools.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertical specialists with embedded compliance rules for healthcare and manufacturing. Platforms with proven FedNow or SEPA Instant integration capabilities command premium valuations. Monitor open banking API standardization progress as an inflection indicator for working capital product expansion. Quarterly review of vendor consolidation announcements and machine learning talent acquisition activity is advised to detect inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Machine Learning Talent Acquisition | HighRadius and Versapay compete aggressively for cash application engineers with NLP and predictive analytics expertise. |
| Embedded B2B Payment Network Expansion | Direct buyer-supplier connectivity reduces DSO by eliminating invoice-to-payment friction in industrial distribution. |
| ISO 20022 Compliance Certification | SEPA Instant and FedNow migration deadlines force platform re-architecture around XML remittance standards. |
| Vertical Collections Specialization | Gaviti's mid-market focus demonstrates that sales-led onboarding depth outperforms generic automation in manufacturing. |
| Supply Chain Finance Integration | Dynamic discounting capabilities unlock new revenue streams from early payment programs and working capital optimization. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with CFOs, treasury directors, ERP integration specialists, and collections operations managers; and secondary validation against SEC 10-K filings, RBI circulars on digital payments, EU DORA regulatory texts, and vendor pricing disclosures. Bottom-up sizing of deployment volumes across cloud, SaaS, and on-premise models was triangulated with top-down expenditure estimates from finance technology procurement surveys.
Forecast inputs spanned solution type adoption curves, deployment model transition rates, and end-user industry digitization maturity across the analysis window. Segmentation dimensions modeled include solution type, deployment architecture, organization size tier, ERP integration complexity, and geographic regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to historical adoption patterns and projected infrastructure mandate timelines, incorporating ISO 20022 migration schedules and instant payment rail expansion as demand accelerants.
Practitioners should monitor central bank instant payment mandates, ESG disclosure rule enforcement, and data residency regulation fragmentation for early signals of platform requirement shifts. Forecasts reflect assumptions about ERP modernization cycles and banking network standardization progress. Quarterly review of vendor implementation timeline extensions and talent acquisition patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Indonesia Digital Software Solutions Market
Digital Solutions
Digital Workplace Technologies Market
Digital Solutions
Hardware Engineering and Design Services Market
Digital Solutions
Smart Connected Assets and Operations Market
Digital Solutions
Digital Signage Services Market
Digital Solutions
Global Interactive Voice Response Market
Digital Solutions
EHS Software Market
Digital Solutions
Weather Forecasting Systems and Solutions Market
Digital Solutions
Outsourced Digital Workplace Service Market
Digital Solutions
Crowdsourcing Market
Digital Solutions
UK Route Optimization Software Market
Digital Solutions
Online Advocacy Platform Market
Digital Solutions
India Engineering Research and Development (ER&D) Services Market
Digital Solutions
Echo Reduction Software Market
Digital Solutions
Fuel Management Software Market
Digital Solutions
On-Demand Warehousing Platforms Market