
 Security Inspection Market | 2026-2036
Security Inspection Market Size, Share, and Industry Trends Forecast 2026-2036
Security Inspection Market Outlook
Multi-source procurement for advanced screening subsystems is consolidating around vendors with captive manufacturing of sensor arrays and software stacks. Smiths Detection leverages its vertical integration in chemical detection modules to sustain long-term service contracts with aviation authorities. Leidos anchors its position through systems integration capabilities spanning checkpoint design and backend analytics. Nuctech Company Limited competes on manufacturing scale, operating one of the largest installed bases of cargo inspection systems across Belt and Road corridor ports.
Security inspection encompasses technologies and integrated systems designed to detect contraband, explosives, weapons, and unauthorized materials through non-invasive scanning methods, typically employing ionizing radiation doses below regulatory thresholds or non-ionizing electromagnetic spectra. X-ray systems with dual-energy or computed tomography architectures form the backbone of aviation checkpoint and hold baggage screening, achieving material discrimination through differential attenuation measurements at distinct energy levels. Millimeter Wave technology leads personal screening applications due to its lack of ionizing radiation and high throughput for metallic and non-metallic threat detection, while the Critical Infrastructure application segment commands concentrated investment from energy and nuclear facilities subject to mandatory perimeter security protocols.
The U.S. Transportation Security Administration sets procurement specifications that shape global product roadmaps for checkpoint equipment, while EASA and national regulators across EU member states enforce harmonized performance standards through CE marking under the EU AI Act's emerging provisions for automated threat recognition. China's MIIT and SAMR coordinate domestic certification pathways that condition market access for foreign suppliers of radiographic inspection equipment. Stakeholders must monitor divergence between U.S. TSA-certified configurations and EU regulatory frameworks as both jurisdictions advance algorithmic transparency requirements for automated screening decision support.
Market Dynamics
Computed tomography checkpoint platforms are displacing legacy dual-energy X-ray architectures across aviation security lanes, forcing incumbent suppliers to reconfigure service revenue models around software-enabled threat detection subscriptions rather than hardware replacement cycles.
Growth Catalysts
- EASA Security Framework Mandates:Enhanced screening protocols for cargo and passenger lanes across European Union member states are accelerating procurement of multi-view inspection systems with automated threat recognition capabilities.
- Energy Sector Perimeter Investment:Nuclear facilities and critical infrastructure operators in the United States face mandatory security upgrades under NRC and DHS guidelines, driving demand for vehicle and personnel screening integration.
- Millimeter Wave Personal Screening:Non-ionizing radiation properties and metallic plus non-metallic threat detection capabilities position this technology for rapid deployment at high-throughput transportation nodes.
Market Restraints
- Sensor Array Supply Concentration:Specialized photodiode and scintillator manufacturing concentrates among Japanese and German component suppliers, creating input cost volatility and extended lead times for system integrators.
- Ionizing Radiation Regulatory Thresholds:FDA and national health authority dose limits constrain throughput optimization for hold baggage screening, limiting operational efficiency gains at hub airports.
- Passive Screening Substitution:Chemical trace detection and passive millimeter wave standoff systems threaten to displace active scanning in low-threat environments where speed outweighs detection depth.
Strategic Opportunities
- Belt and Road Port Modernization:Cargo inspection system deployment across Central Asian and Southeast Asian corridor ports presents white space for suppliers with manufacturing scale and localized service networks.
- EU AI Act Algorithmic Transparency:Automated threat recognition certification pathways create first-mover advantage for vendors with documented machine learning training protocols and bias audit capabilities.
- Computed Tomography-Millimeter Wave Convergence:Integrated checkpoint architectures combining volumetric baggage scanning with biometric passenger verification are reshaping procurement specifications at tier-one aviation hubs.
Industry Challenges
- Machine Learning Engineering Talent Scarcity:Automated threat recognition development requires specialized computer vision expertise that concentrates among technology sector employers, constraining vendor R&D velocity.
- TSA Certification Timeline Compression:Extended qualification protocols for new checkpoint technologies delay revenue recognition and tie up engineering resources across multiple product development cycles.
- Legacy System Integration Complexity:Brownfield airport infrastructure with disparate baggage handling architectures demands costly customization of screening system mechanical interfaces and data protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Security Inspection Market |
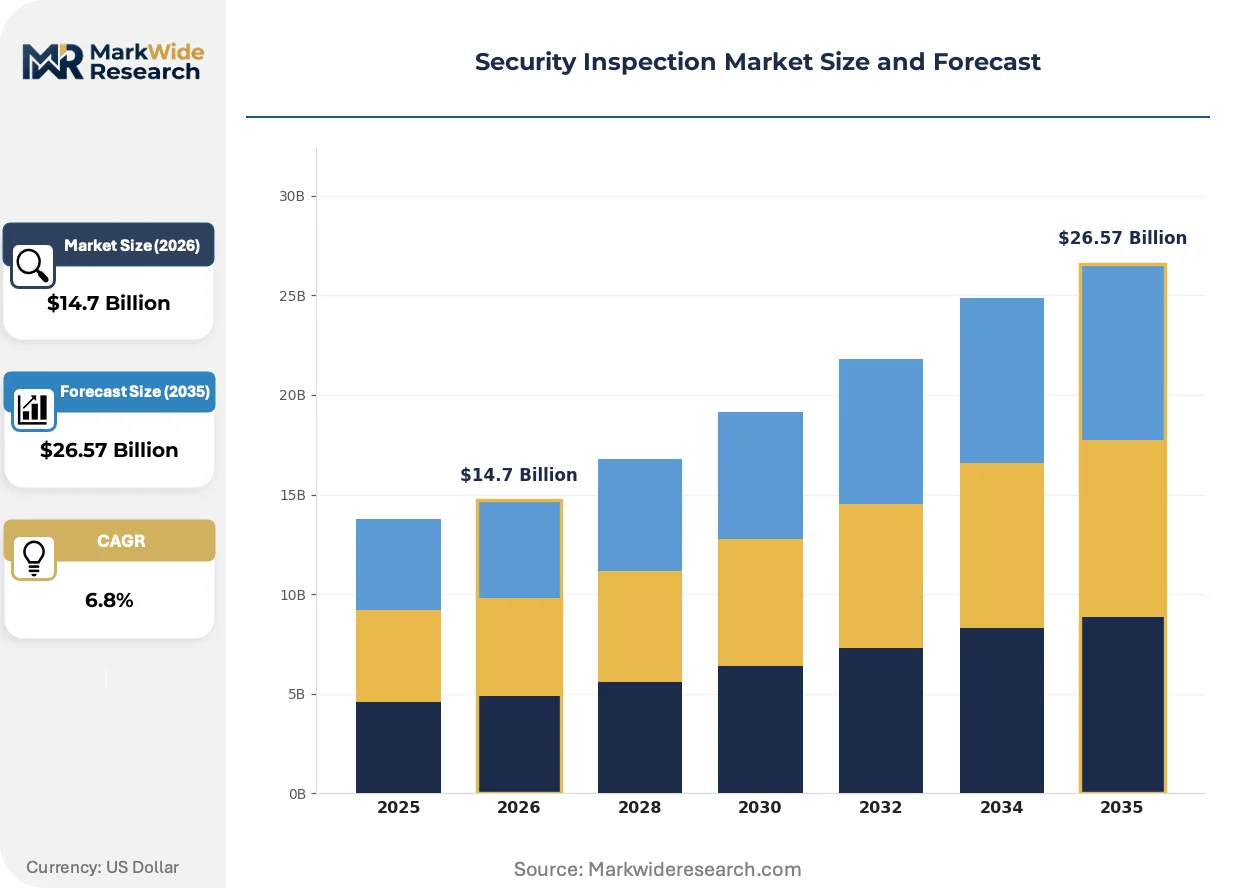
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Millimeter Wave, X-Ray, Infrared, Ultrasound Application: Aviation, Maritime, Critical Infrastructure, Public Events End User: Government, Transportation, Retail, Hospitality Installation Type: Mobile, Fixed, Handheld, Walk-Through |
| Companies Covered | Smiths Detection, OSI Systems, Leidos, Nuctech Company Limited, Thales, Analogic Corporation, L3Harris Technologies, Astrophysics, CEIA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Security Inspection Market Strategic Shifts
Software-defined detection architectures are separating hardware acquisition from algorithm performance, enabling subscription-based threat library updates that decouple vendor revenue from physical equipment replacement.
Deep learning inference at the edge is decentralizing threat recognition processing from centralized server farms to embedded GPU arrays within checkpoint units. Tier-one airports in the United States and United Arab Emirates are piloting these configurations to reduce network latency and enable real-time decision autonomy. This architecture compresses reliance on cloud connectivity for screening operations.
The EU AI Act's risk classification framework for biometric and automated decision systems is mandating algorithmic transparency documentation for screening equipment deployed at EU airports. Vendors must now submit conformity assessment packages detailing training data provenance and false positive rate validation protocols. CE marking under these provisions is extending certification timelines by twelve to eighteen months for non-EU suppliers.
Airport authorities are unbundling after-sales service contracts from initial equipment procurement, creating standalone multi-vendor maintenance competitions. Middle Eastern and Southeast Asian hub operators now separately tender for spare parts logistics, field engineering, and software support. This purchasing pattern is most visible at greenfield aviation infrastructure projects where legacy vendor lock-in does not constrain sourcing flexibility.
Security Inspection Market Segmentation
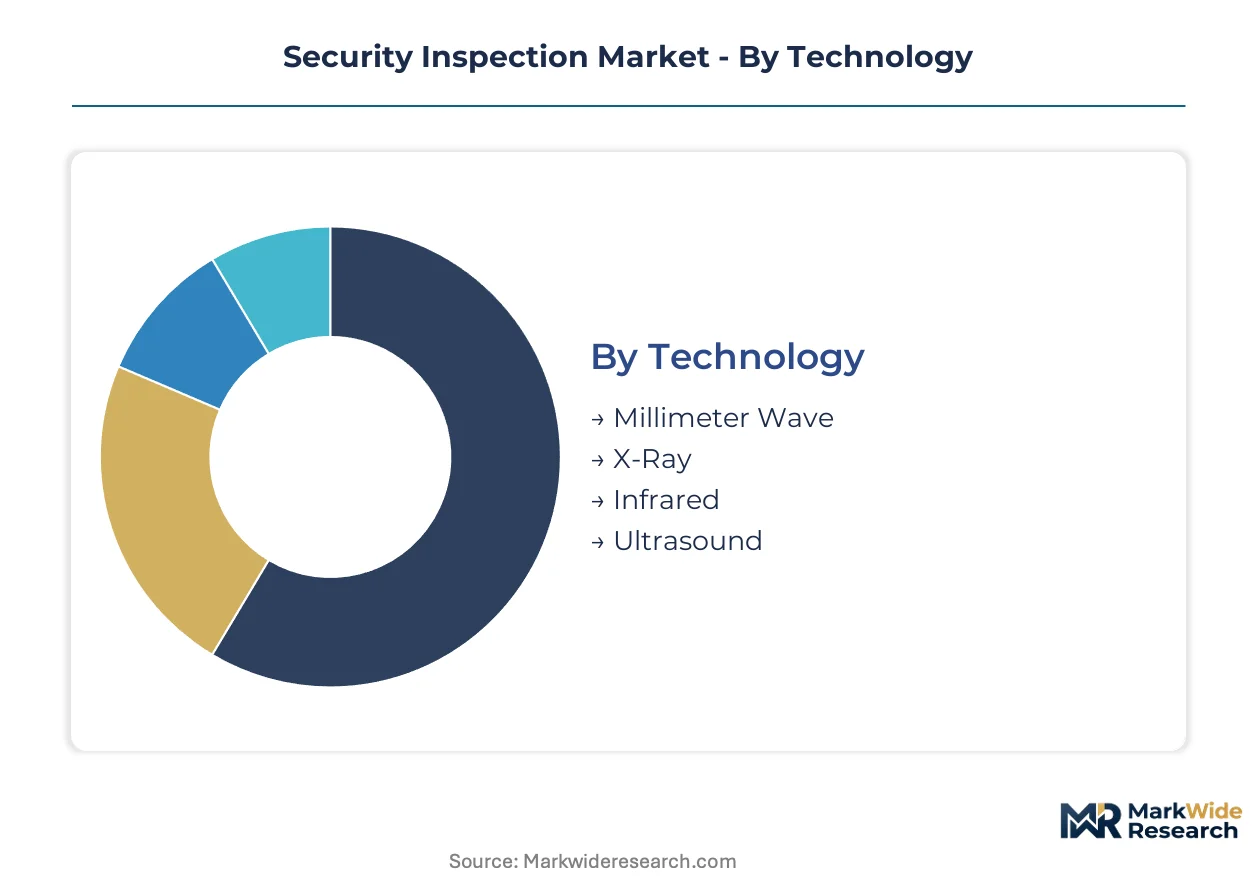
Security inspection procurement patterns diverge sharply across technology platforms and deployment contexts. Aviation authorities prioritize throughput and regulatory certification, while critical infrastructure operators emphasize perimeter integration and environmental durability. Understanding these segment-specific buying criteria exposes where vendor capabilities align with purchaser willingness-to-pay.
Technology:
Buyers in this category differentiate primarily by radiation safety requirements and material discrimination depth.
- X-Ray:Dual-energy and computed tomography architectures achieve material discrimination through differential attenuation measurements at distinct energy levels. Aviation checkpoint procurement in the United States concentrates here as TSA specifications mandate replacement of legacy systems with CT platforms capable of automated threat recognition.
- Millimeter Wave:Non-ionizing electromagnetic spectra enable metallic and non-metallic threat detection without radiation exposure concerns. Personal screening deployments at high-throughput transportation nodes in Germany and the United Arab Emirates favor this technology for passenger throughput optimization.
- Infrared:Thermal signature detection supports perimeter monitoring applications where passive surveillance outweighs active scanning requirements.
- Ultrasound:Acoustic imaging methods address specialized container inspection scenarios requiring liquid and bulk material analysis.
X-Ray leads volumes today; Millimeter Wave is gaining share fastest.
Application:
Regulatory mandate intensity and threat consequence severity separate buyers across use cases.
- Aviation:Checkpoint and hold baggage screening face mandatory performance standards under EASA security frameworks and TSA certification protocols. European Union member states are accelerating multi-view inspection system procurement with automated threat recognition capabilities.
- Critical Infrastructure:Nuclear facilities and energy sector operators in the United States face compulsory security upgrades under NRC guidelines. Vehicle and personnel screening integration commands concentrated investment from perimeter hardening mandates.
- Maritime:Container and vessel inspection requirements concentrate at Belt and Road corridor ports across Southeast Asia.
- Public Events:Temporary deployment scenarios prioritize rapid setup and teardown over detection depth.
Aviation dominates procurement value; Critical Infrastructure shows steepest expansion trajectory from baseline.
End User:
Budget authority and threat assessment sophistication create distinct purchasing behaviors.
- Government:National security agencies and customs authorities operate under classified threat specifications with extended procurement cycles. Federal budget appropriations in the United States and centralized procurement frameworks in China condition multi-year equipment deployment schedules.
- Transportation:Airport authorities and port operators balance operational throughput against detection sensitivity. Unbundled after-sales service contracts now separate from initial equipment procurement at Middle Eastern and Southeast Asian hub operators.
- Retail:Loss prevention departments deploy entry screening with emphasis on deterrent visibility over contraband recovery rates.
- Hospitality:Event venues and hotel properties prioritize guest experience compatibility in screening architecture selection.
Government absorbs the largest equipment budgets; Transportation is climbing the fastest as checkpoint modernization accelerates.
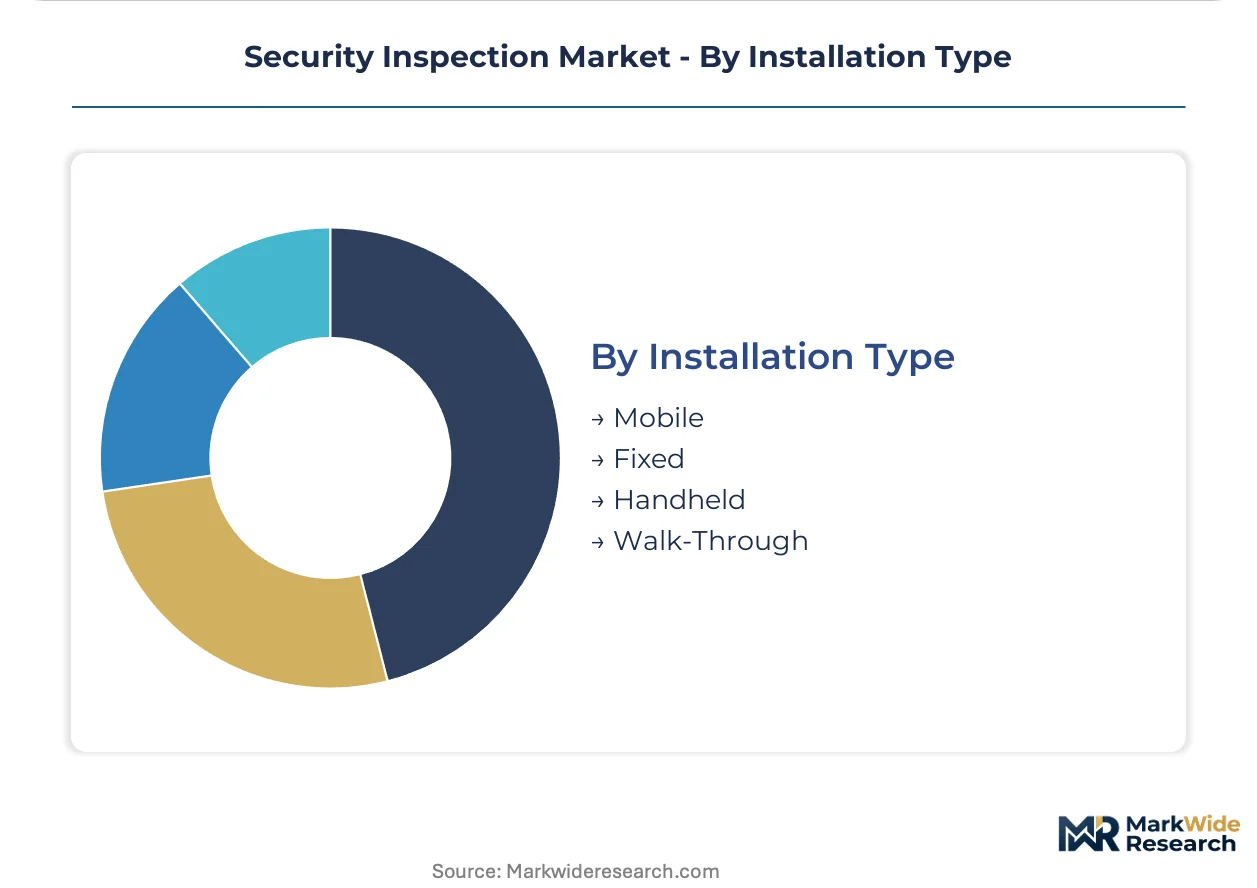
Installation Type:
Mobility requirements and infrastructure permanence drive hardware configuration choices.
- Fixed:Permanent checkpoint installations integrate with baggage handling system mechanical interfaces and data protocols. Brownfield airport infrastructure demands costly customization of screening system interfaces.
- Walk-Through:Personnel screening portals combine biometric verification with threat detection at tier-one aviation hubs. Computed tomography-millimeter wave convergence is reshaping procurement specifications for integrated checkpoint architectures.
- Mobile:Vehicle-mounted systems serve temporary security perimeters and emergency response scenarios.
- Handheld:Portable trace detection devices supplement primary screening with targeted secondary inspection capabilities.
Fixed installations anchor installed base value; Walk-Through configurations are expanding most quickly from emerging biometric integration requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States aviation security infrastructure commands the largest procurement budgets for checkpoint modernization programs. Federal appropriations through the Transportation Security Administration drive replacement cycles for legacy screening architectures. Dallas-Fort Worth International Airport and Hartsfield-Jackson Atlanta International Airport anchor the domestic deployment pipeline for computed tomography platforms.
United States
Airport authorities in Atlanta and Dallas-Fort Worth are executing multi-phase checkpoint upgrades under TSA procurement specifications. The Federal Aviation Administration coordinates security technology standards with the Department of Homeland Security. Chicago O'Hare International Airport serves as a testbed for integrated biometric passenger verification systems alongside volumetric baggage scanning.
Germany
Frankfurt Airport and Munich Airport operators prioritize passenger throughput optimization through millimeter wave personal screening deployments. The Federal Office for Information Security enforces cybersecurity standards for automated threat recognition systems under national implementation of EU AI Act provisions. Hamburg's port complex maintains one of Europe's densest concentrations of cargo inspection infrastructure for containerized freight.
China
Domestic aviation hubs in Beijing and Shanghai are expanding computed tomography checkpoint capacity ahead of international traffic recovery. The Ministry of Industry and Information Technology coordinates certification pathways for radiographic inspection equipment through SAMR technical standards. Shenzhen Bao'an International Airport exemplifies integrated screening architectures combining passenger verification with automated baggage handling.
United Arab Emirates
Dubai International Airport and Abu Dhabi International Airport operators unbundle after-sales service contracts from initial equipment procurement. The General Civil Aviation Authority mandates performance standards for multi-view inspection systems at federal aviation facilities. Dubai's logistics corridor concentrates cargo screening infrastructure serving transshipment traffic between Asia and Europe.
United Kingdom
Heathrow Airport and Gatwick Airport authorities face EASA security framework compliance deadlines for enhanced cargo and passenger lane protocols. The Civil Aviation Authority enforces harmonized screening standards through national transposition of EU regulatory requirements. Manchester Airport anchors northern England's checkpoint modernization program with phased computed tomography deployment.
Security Inspection Market Competitive Environment
Global majors compete with regional champions across certification pathways and service network density. The vendor base stratifies between integrated systems houses, component specialists, and state-affiliated equipment suppliers. Three archetypes dominate: Western defense contractors with TSA certification track records, Chinese state-linked manufacturers with Belt and Road corridor access, and European specialists in chemical detection subsystems. Competitive moves concentrate on strategic partnerships for localized service delivery and technology licensing for algorithm development.
Within the integrated systems tier, Smiths Detection, Leidos, and Nuctech Company Limited exemplify divergent geographic anchoring strategies. Smiths Detection occupies a position representing European captive manufacturing of sensor arrays. Leidos sits within the U.S. federal contractor archetype with systems integration capabilities spanning checkpoint design. Nuctech Company Limited anchors the state-linked manufacturer category with manufacturing scale advantages across Central Asian and Southeast Asian corridor ports.
| Leading Market Players |
|---|
| Smiths Detection |
| OSI Systems |
| Leidos |
| Nuctech Company Limited |
| Thales |
| Analogic Corporation |
| L3Harris Technologies |
| Astrophysics |
| CEIA |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed producers in China and state-affiliated equipment suppliers anchor supply-side concentration, compressing pricing discipline for Western integrators dependent on Japanese and German sensor components. Federal procurement frameworks in the United States and centralized purchasing in China create divergent pricing floors that reshape margin structures across certification tiers.
Pricing Analysis
Input-cost pass-through from specialized photodiode and scintillator arrays constrains margin flexibility for system integrators lacking captive manufacturing. Three-tier pricing structure across TSA-certified premium, CE-marked standard, and non-certified economy levels separates aviation authorities from critical infrastructure operators. Pricing pressure stems from unbundled after-sales service contracts at Middle Eastern and Southeast Asian hubs. Transportation end-users exhibit highest price sensitivity due to throughput optimization mandates, while government agencies absorb premium tiers for classified threat specifications.
Supply Chain Analysis
Freight cost volatility for precision radiation sensor modules elevates landed costs for European and North American system integrators sourcing from Japanese and German component specialists. Manufacturing concentrates in China for cargo inspection platforms, Germany for chemical detection subsystems, and the United States for TSA-certified checkpoint architectures. Supply chains draw from rare-earth scintillator crystals, high-purity germanium substrates, and machine learning inference processors. Single-source vulnerability concentrates in photodiode fabrication for computed tomography arrays. Distribution runs through direct federal procurement channels, airport authority tenders, and port operator frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between TSA certification timelines in the United States and EU AI Act algorithmic transparency requirements, with the latter extending conformity assessments by twelve to eighteen months for non-EU suppliers.
For Market Incumbents: Anticipate displacement risk from software-defined detection architectures that separate hardware acquisition from algorithm performance. Deepen backward integration into sensor array manufacturing to offset Japanese and German component supply concentration. Prioritize machine learning engineering recruitment to counter talent scarcity constraining automated threat recognition velocity. For New Entrants and Emerging Players: Digital-channel routes through cloud-based threat library subscriptions offer lower-barrier entry than hardware certification cycles. Target Belt and Road corridor ports in Central Asia and Southeast Asia where localized service networks outweigh TSA track record. Pursue EU AI Act algorithmic transparency documentation as first-mover positioning for automated threat recognition certification. For Investors and Strategic Acquirers: Defense contractors with established TSA certification histories are the most active acquirer in this space, consolidating systems integration capabilities and checkpoint design expertise. Five-to-ten-year viability hinges on convergence between computed tomography and millimeter wave architectures. Monitor divergence between U.S. and EU regulatory frameworks as inflection indicator for vendor competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captive photodiode production insulates Smiths Detection from Japanese component lead time volatility. |
| EU AI Act Conformity Assessment | Documented machine learning training protocols enable Leidos to secure CE marking ahead of non-EU rivals. |
| Belt and Road Service Network Expansion | Localized maintenance capabilities position Nuctech to capture cargo inspection procurement at corridor ports. |
| Software-Defined Threat Detection Platform | Subscription-based algorithm updates decouple vendor revenue from TSA hardware replacement cycles. |
| Computed Tomography-Millimeter Wave Convergence | Integrated checkpoint architectures reshape procurement specifications at Dubai and Chicago hub airports. |
Study Parameters
Direct dialogue with TSA procurement officers, airport authority engineering directors, customs technology managers, and critical infrastructure security chiefs grounded qualitative findings in operational constraints. Secondary validation drew from FAA security technology standards, EASA regulatory submissions, SAMR technical certifications, and Department of Homeland Security appropriations documentation. Bottom-up equipment deployment tallies triangulated against top-down federal budget allocations across the analysis window.
Bottom-up modeling segmented procurement by technology platform, application context, and end-user budget authority, while top-down analysis tracked regulatory mandate intensity across national aviation frameworks. Deployment schedules for computed tomography checkpoints, millimeter wave personal screening portals, and cargo inspection systems informed volume projections throughout the forecast period. CAGRs derived from replacement cycle compression for legacy X-ray architectures and algorithm performance subscription attach rates.
The model assumes a particular technology adoption path; alternative pathways for passive millimeter wave standoff systems would alter the outlook for active scanning equipment deployment. Forecasts reflect assumptions regarding TSA certification timeline compression and EU AI Act implementation pacing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Smart Security Market
Security and Surveillance
Security Holograms Market
Security and Surveillance
Swimming Pool Alarm Market
Security and Surveillance
Asia-Pacific Security Services Market
Security and Surveillance
Security Analytics Market
Security and Surveillance
North America Urban Security Screening Market
Security and Surveillance
Vietnam Private Security Market
Security and Surveillance
Security and Surveillance Equipment Market
Security and Surveillance
North America Wireless Monitoring and Surveillance Market
Security and Surveillance
Intrusion Alarm System Market
Security and Surveillance
Integrated Security Solutions Market
Security and Surveillance
Middle East and Africa Cargo and Vehicle Screening Market
Security and Surveillance
North America People Screening Market
Security and Surveillance
Global Corporate Travel Security Market
Security and Surveillance
Threat Detection Systems Market
Security and Surveillance
Home Security Sensors Market