
 Swimming Pool Alarm Market | 2026-2036
Swimming Pool Alarm Market Size, Share, and Industry Trends Forecast 2026-2036
Swimming Pool Alarm Market Analytics
The swimming pool alarm category is repositioning around a sharp split between premium integrated systems and basic audio-alert commodities. Maytronics leverages its robotics heritage to anchor high-end detection platforms with multi-sensor fusion. RJE Technologies competes through specialized marine-grade engineering that sustains reliability in saltwater environments. SPQ Brands dominates the mass-retail channel with simplified DIY installation kits that occupy price-sensitive shelf space.
Swimming pool alarms are electromechanical safety devices that detect surface disturbance, submersion events, or perimeter breach through ultrasonic, infrared, or pressure-sensing modalities, typically triggering audible alerts at 85 decibels or higher within twenty seconds of activation to meet drowning-prevention protocols. These systems serve residential and commercial aquatic facilities where unattended water access creates liability exposure. Wireless technology leads unit growth due to eliminated trenching costs and flexible placement, while video monitoring commands the highest margin pool as insurers recognize continuous visual verification. Professional installation still controls the commercial segment where integrated building management systems require certified commissioning.
The US Consumer Product Safety Commission and ASTM International shape product standards through submersion-response timing and alarm-decibel benchmarks that determine market access. State-level regulators in Florida, California, and Arizona enforce pool-barrier laws that directly mandate or incentivize alarm deployment. Stakeholders must monitor whether municipal insurers begin conditioning liability coverage on certified alarm installation, as this would restructure demand composition across all price tiers.
Market Dynamics
Wireless sensor architectures are compressing installation timelines from days to hours, eroding the installed-base advantage of legacy hardwired systems while state-level drowning-prevention mandates in Florida, California, and Texas create compliance-driven replacement cycles.
Growth Catalysts
- Florida's Residential Swimming Pool Safety Act:Municipal ordinances in Miami-Dade, Broward, and Palm Beach counties mandate audible alarms for new pool construction and substantial renovations, generating permit-linked demand spikes.
- Insurer premium reduction programs:Underwriting divisions at national carriers now document certified alarm installation for liability premium adjustments, converting discretionary purchases into financially rational investments.
- Saltwater pool conversion wave:Corrosion-resistant ultrasonic and pressure-sensing modules are penetrating the Florida and California residential retrofit segment where saline chemistry degrades legacy magnetic contacts.
Market Restraints
- Lithium battery supply concentration:Wireless sensor nodes depend on cylindrical cell formats where supply chains concentrate in East Asian manufacturing corridors, exposing margin compression during raw material allocation cycles.
- ASTM F2208 certification timelines:Third-party validation of submersion-response timing and decibel output extends product development cycles by four to six months for novel detection modalities.
- Smart home hub substitution:DIY camera systems with AI-based perimeter detection are capturing price-sensitive consumers who view dedicated pool alarms as redundant to whole-property monitoring infrastructure.
Strategic Opportunities
- Arizona municipal ordinance expansion:Phoenix, Scottsdale, and Tucson are drafting barrier-law amendments that would extend alarm mandates to existing pool inventories, opening a three-year compliance window.
- Video-verification integration:Convergence of underwater sonar with edge-computing cameras is enabling insurer-preferred continuous visual confirmation at premium price points.
- Commercial hospitality retrofit:Resort and multi-family property managers in Orlando and Las Vegas are consolidating alarm procurement with building automation tenders, favoring certified integrators over retail channels.
Industry Challenges
- RF interference mitigation:Dense suburban Wi-Fi and mesh network saturation in California coastal counties degrades wireless sensor range, requiring firmware-intensive coexistence engineering.
- Multi-protocol integration complexity:Commercial bids increasingly specify BACnet or Modbus compatibility for pool alarm status integration with facility management dashboards, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Swimming Pool Alarm Market |
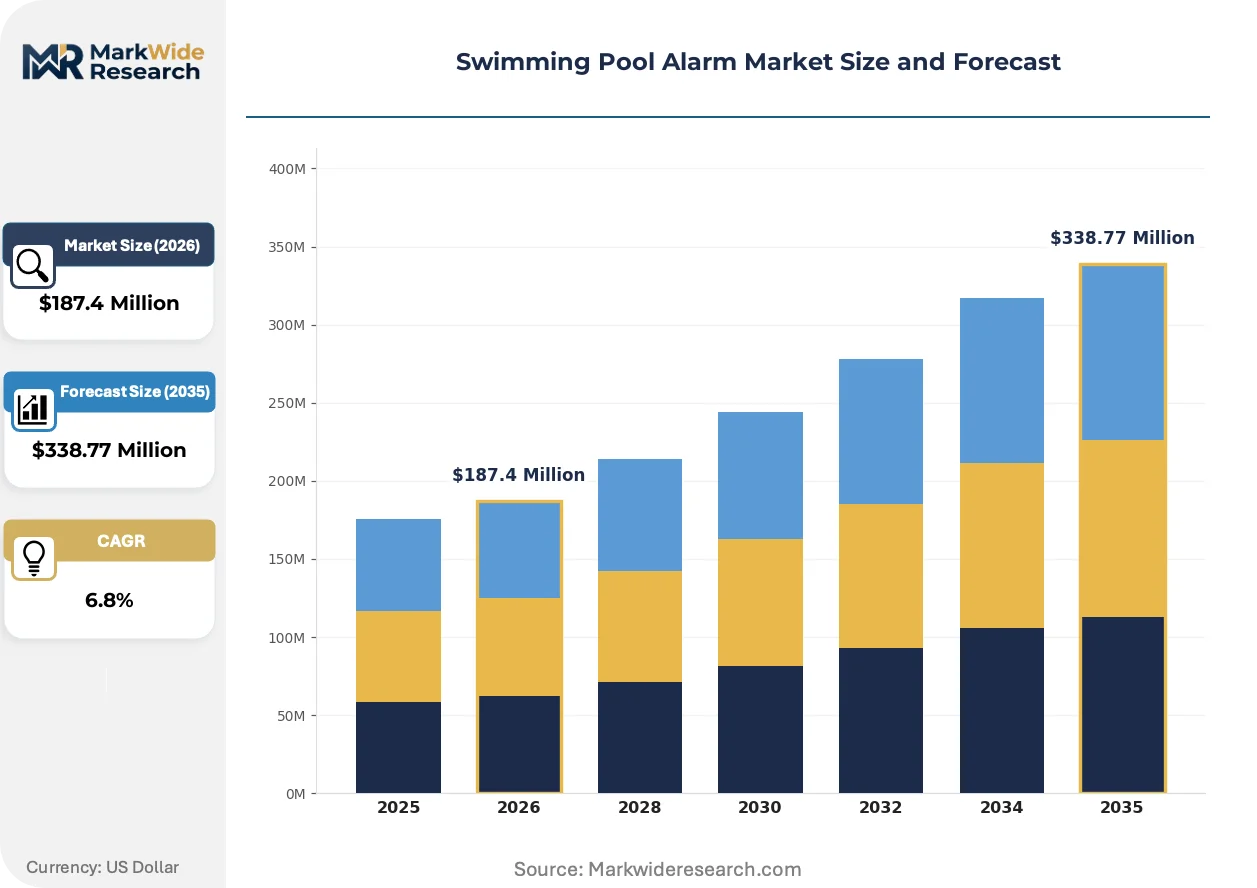
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floating Alarms, Ground Sensors, Audio Alarms, Video Monitoring End User: Residential Users, Commercial Pools, Hotels, Water Parks Technology: Ultrasonic, Infrared, Wireless, Hardwired Installation: DIY, Professional, Integrated Systems, Retrofit |
| Companies Covered | Maytronics, RJE Technologies, SPQ Brands, Driven Designs, Blue Wave Products Inc, PBM Industries, Safety Turtle, Piscines MAGILINE SAS, Coral Detection Systems Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Swimming Pool Alarm Market Evolving Landscape
Detection modalities are converging around multi-sensor fusion platforms that reduce false-positive rates while regulatory pressure accelerates certification requirements for connected safety systems.
Multi-sensor fusion architectures combining subsurface pressure transducers, surface wave detection, and passive infrared are unifying previously separate alarm categories into single-platform offerings. High-end residential buyers in gated Florida communities are specifying these integrated systems at triple the rate of standalone ultrasonic units. The technology is unifying hardware procurement decisions with whole-home automation specifications, compressing vendor selection cycles and elevating integrator influence over manufacturer brand preference.
ASTM International is revising F2208 to incorporate connectivity and cybersecurity benchmarks for networked pool alarms, extending compliance scope beyond acoustic performance to data transmission integrity. Manufacturers serving the Texas and California markets are pre-emptively engineering encrypted firmware update channels to satisfy anticipated validation requirements. The commercial segment, where networked alarms integrate with property management systems, faces the steepest adaptation burden as certification bodies develop audit protocols for cloud-connected safety devices.
Buyer research behavior has migrated from big-box retail consultation to pre-purchase video validation, with installation tutorial viewership predicting purchase intent more reliably than traditional demographic segmentation. The shift is compressing brand loyalty windows and elevating YouTube and TikTok content creators as de facto product gatekeepers. Texas and Arizona markets exhibit the highest correlation between tutorial engagement and direct-to-consumer conversion, bypassing traditional pool supply distribution.
Swimming Pool Alarm Market Segmentation
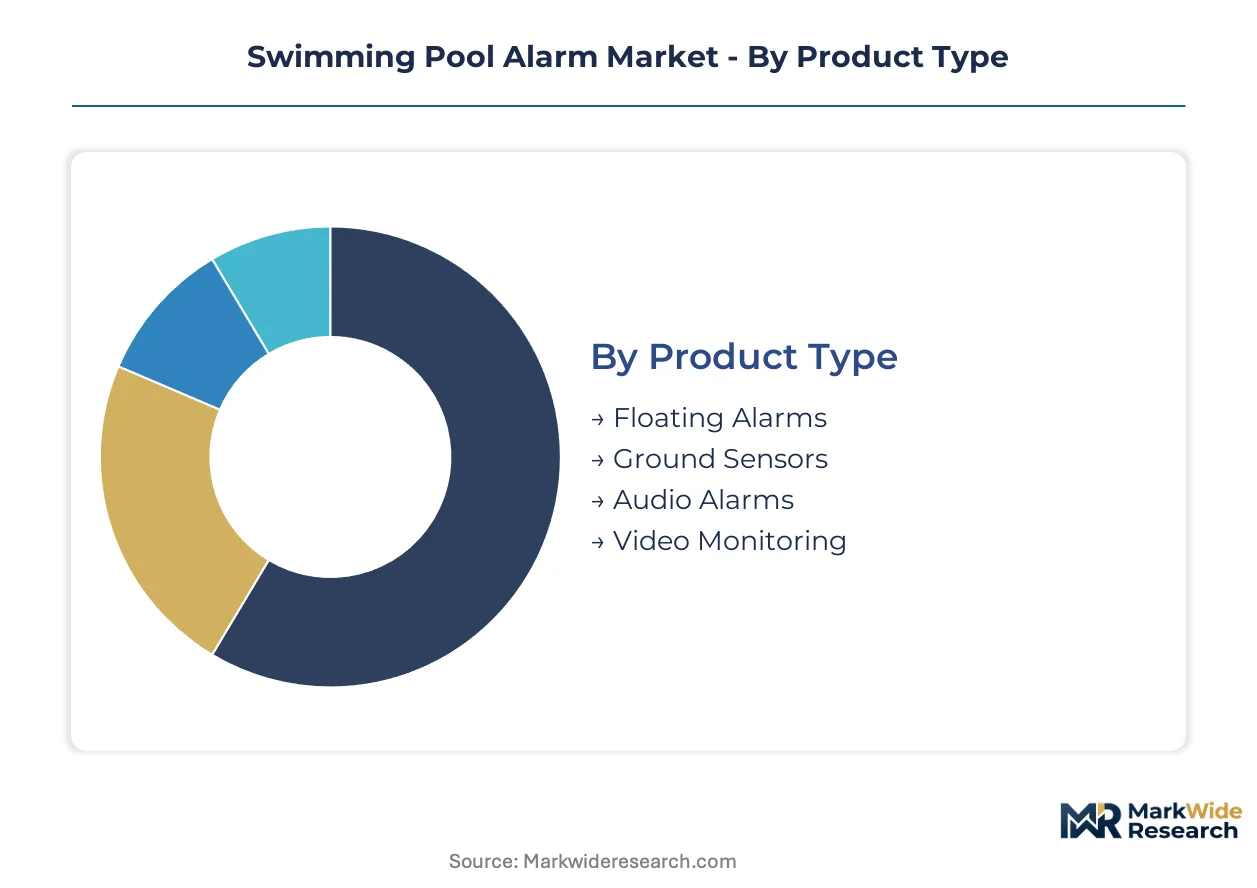
Segmentation in swimming pool alarms reveals how detection modality, deployment context, and buyer sophistication reshape procurement patterns. Each category exposes distinct margin structures and regulatory compliance pathways that determine vendor positioning.
Product Type:
Floating alarms and ground sensors anchor opposite ends of the customization spectrum, with integrated platforms commanding premium specification while standalone units serve price-sensitive retrofit demand.
- Floating Alarms:Buoy-mounted ultrasonic transducers detect surface displacement through water-borne acoustic reflection. Residential demand concentrates in Florida counties where permit-linked mandates for new construction favor rapid-deploy solutions. ASTM F2208 certification requirements limit supplier entry.
- Ground Sensors:Perimeter-mounted pressure transducers and infrared beams establish invisible detection boundaries around pool decks. Commercial hospitality properties in Las Vegas and Orlando specify these for integrated building management compatibility. Installation complexity sustains professional channel margins.
- Audio Alarms:Standalone 85+ decibel sirens triggered by surface wave detection.
- Video Monitoring:Edge-computing camera systems with AI-based perimeter detection.
Most installed capacity flows through Floating Alarms. Expansion is steepest in Video Monitoring.
End User:
Cost tier stratification separates liability-driven commercial specification from discretionary residential purchasing, with insurer incentives bridging the gap for upscale homeowners.
- Residential Users:Single-family homeowners in Texas, Florida, and California drive volume through municipal ordinance compliance and premium reduction documentation. DIY installation preference elevates retail channel importance.
- Commercial Pools:Municipal and institutional aquatic facilities require certified commissioning and BACnet integration. Professional installation controls this segment where liability exposure justifies recurring maintenance contracts.
- Hotels:Resort properties in Orlando and Las Vegas consolidate alarm procurement with building automation tenders.
- Water Parks:High-occupancy entertainment venues with complex aquatic geometries.
Residential Users absorb the majority of unit shipments. Hotels are gaining share fastest as hospitality capital expenditure recovers.
Technology:
Volume concentration favors wireless architectures while margin accrues to multi-protocol systems that satisfy commercial integration specifications.
- Wireless:Battery-powered sensor nodes eliminate trenching costs and enable flexible placement. Saltwater pool conversions in Florida and California accelerate corrosion-resistant ultrasonic module demand. Lithium cell supply concentration creates procurement risk.
- Hardwired:Legacy trench-dependent systems retain installed-base presence in pre-2010 residential construction. Replacement cycles are compressing as wireless reliability improves and municipal mandates trigger system overhauls.
- Ultrasonic:Surface wave detection through water-borne acoustic ranging.
- Infrared:Passive thermal detection of perimeter breach events.
Wireless dominates new installation volume. Ultrasonic is climbing the fastest as multi-sensor fusion platforms standardize on acoustic ranging cores.
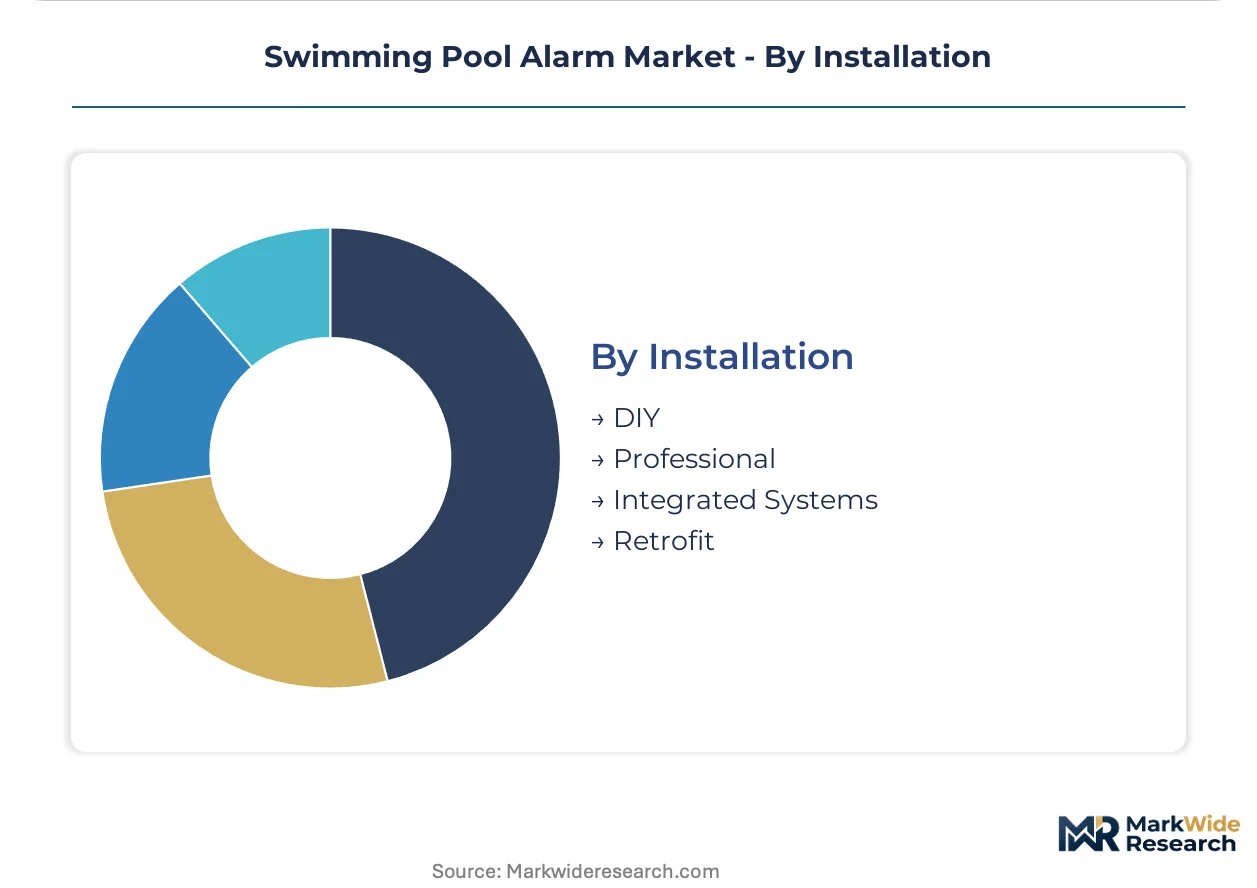
Installation:
Customer type and application maturity determine whether procurement flows through retail self-service or certified integrator channels.
- DIY:Simplified mounting kits with smartphone-guided calibration capture price-sensitive demand. Tutorial viewership on YouTube and TikTok predicts purchase intent more reliably than demographic segmentation in Texas and Arizona markets.
- Professional:Certified technicians handle commercial bids requiring BACnet or Modbus compatibility. Commissioning timelines extend when facility management dashboard integration is specified.
- Integrated Systems:Whole-home automation convergence elevates integrator influence over manufacturer brand preference.
- Retrofit:Existing pool inventory upgrades driven by municipal ordinance expansion in Phoenix, Scottsdale, and Tucson.
DIY commands the greatest unit volume. Integrated Systems show the steepest expansion trajectory as smart home convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pool safety engineering talent clusters in coastal states with stringent drowning-prevention codes, concentrating product development and compliance expertise in jurisdictions with mature regulatory frameworks.
United States
State-level mandates in Florida, California, and Texas generate permit-linked demand spikes for new construction and renovation projects. The US Consumer Product Safety Commission and ASTM International enforce submersion-response timing and alarm-decibel benchmarks that determine market access. Miami-Dade, Broward, and Palm Beach counties anchor compliance-driven procurement, while Orlando resort properties consolidate alarm tenders with building automation systems.
Germany
Technical engineering capabilities in precision sensor manufacturing support corrosion-resistant module development for saltwater environments. CE marking requirements under EU machinery directives establish baseline safety protocols for electromechanical pool devices. Bavaria and Baden-Württemberg host industrial automation clusters where multi-protocol integration expertise serves commercial hospitality specifications.
France
Pool safety consciousness in Mediterranean coastal regions drives residential alarm penetration among second-home owners. ANSM and CNIL oversight shapes data protection requirements for connected monitoring systems. The Provence-Alpes-Côte d'Azur corridor concentrates luxury pool construction where integrated automation specifications elevate premium system demand.
Australia
Mandatory pool barrier legislation across New South Wales, Victoria, and Queensland creates consistent baseline demand for perimeter detection systems. State-level building codes administered by local councils incorporate alarm provisions in compliance checklists. Sydney and Melbourne metropolitan areas exhibit highest retrofit activity as existing pool inventories face inspection cycles.
Canada
Seasonal pool operation patterns concentrate demand in Ontario and Quebec during compressed installation windows. Health Canada and provincial building authorities coordinate barrier-law enforcement that varies by municipality. The Greater Toronto Area experiences permit-linked demand spikes aligned with spring construction seasons.
Swimming Pool Alarm Market Competitive Landscape
Top-tier vendors anchor integrated automation platforms, while mass-retail specialists occupy price-sensitive shelf space with simplified installation kits. Mid-tier engineering houses sustain positions through marine-grade reliability certifications. Three archetypes dominate: robotics heritage platforms, corrosion-resistant specialists, and DIY retail channel leaders. Consolidation pressure intensifies as smart home convergence elevates integrator influence over manufacturer brand preference, while ASTM certification timelines extend barriers for novel detection modality entrants.
Within the robotics-heritage tier, Maytronics exemplifies premium positioning through multi-sensor fusion expertise. RJE Technologies and Coral Detection Systems Ltd represent marine-grade engineering specialists with saltwater reliability credentials. SPQ Brands occupies the retail-channel vector with simplified DIY installation formats. These three anchors illustrate how detection modality specialization, distribution channel control, and regulatory compliance speed stratify competitive positioning across price tiers.
| Leading Market Players |
|---|
| Maytronics |
| RJE Technologies |
| SPQ Brands |
| Driven Designs |
| Blue Wave Products Inc |
| PBM Industries |
| Safety Turtle |
| Piscines MAGILINE SAS |
| Coral Detection Systems Ltd |
| Others |
Value Network & Pricing Analysis
Wireless sensor miniaturization is compressing bill-of-materials costs while simultaneously shifting procurement leverage toward East Asian battery cell manufacturers. This dual transformation concentrates margin pressure on mid-tier alarm assemblers who lack scale advantages in lithium chemistry sourcing.
Pricing Analysis
Installation bundling separates professional-grade systems from retail self-service kits. Three-tier pricing structure across premium, standard, and economy levels reflects ASTM F2208 certification grade and after-sales service depth. Cost compression in DIY tiers is intensifying because lithium supply bottlenecks squeeze component margins. Residential retrofit buyers in Texas and Florida exhibit highest price sensitivity, while Orlando resort properties prioritize liability coverage over unit cost.
Supply Chain Analysis
Domestic-content thresholds in municipal procurement specifications are redirecting component sourcing toward North American final assembly. Lithium cells from China, South Korea, and Japan feed ultrasonic transducer production in Florida and California. Supply chains draw from corrosion-resistant housings, pressure-sensing membranes, and mesh-network chipsets. Single-source vulnerability concentrates in cylindrical battery formats. Distribution runs through pool supply distributors, big-box retail, and certified automation integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
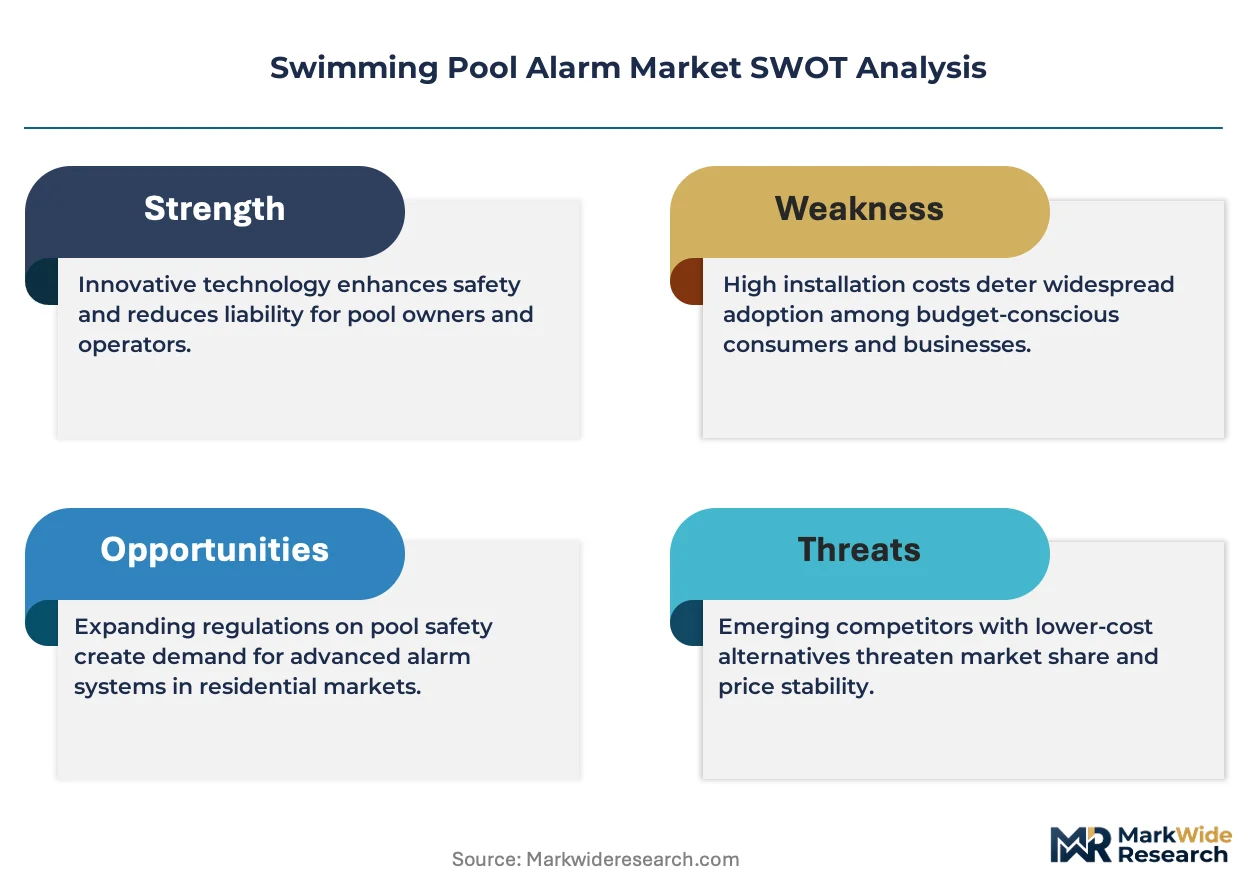
The Swimming Pool Alarm Market functions as a geographic-arbitrage play where Arizona's pending ordinance expansion offers three-year compliance windows absent from mature Florida and California markets. Installation labor cost differentials between Sun Belt states create margin expansion opportunities for regional service consolidators.
For Market Incumbents: Hedge ASTM F2208 recertification exposure by pre-engineering encrypted firmware channels before connectivity mandates finalize. Secure lithium supply through long-term offtake agreements with Korean cell manufacturers to defend against raw material allocation cycles. Channel control through certified integrator networks protects premium positioning against DIY camera substitution.
For New Entrants and Emerging Players: YouTube and TikTok tutorial ecosystems offer direct-to-consumer bypass of established pool supply distribution. Target Arizona's municipal retrofit wave before compliance deadlines harden vendor relationships. White-space exists in saltwater-corrosion specialization for California and Florida residential conversions. Go-to-market through influencer partnerships converts tutorial engagement into purchase intent more efficiently than traditional retail shelf placement.
For Investors and Strategic Acquirers: Valuations sit cheapest among marine-grade engineering specialists with saltwater reliability credentials but limited brand recognition. Long-term viability hinges on multi-protocol integration capability as commercial hospitality consolidation favors BACnet-compatible platforms. Acquisition targets should demonstrate encrypted firmware architecture and cloud-connected safety device audit readiness. Watch for insurer premium incentive expansion as the inflection signal that restructures demand composition across all price tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol Integration Development | BACnet and Modbus compatibility secures Orlando and Las Vegas hospitality tenders requiring building automation convergence. |
| Encrypted Firmware Architecture Investment | ASTM F2208 connectivity revisions position vendors ahead of cybersecurity validation requirements in Texas and California. |
| Saltwater Corrosion Specialization | Marine-grade engineering captures Florida and California residential retrofit demand as saline pool conversions accelerate. |
| Direct-to-Consumer Channel Launch | YouTube and TikTok tutorial ecosystems convert Arizona and Texas buyer research behavior into bypass of traditional distribution. |
| Lithium Supply Security Program | Long-term cell offtake agreements with Korean manufacturers mitigate East Asian supply concentration risk. |
Research Methodology
Multiple input streams — regulatory filing analysis, distributor shipment data, and municipal permit records — were reconciled against primary interviews with pool safety officers, automation integrators, and alarm manufacturer product managers. Secondary validation drew from ASTM International standard revision dockets, Florida building department permit databases, and insurer underwriting guideline disclosures. Bottom-up unit shipment modeling and top-down market sizing triangulated volume estimates across the projection horizon.
Historical permit issuance patterns were cross-referenced against panel input from certified installation contractors to establish replacement cycle assumptions. Segmentation dimensions modeled include detection modality, deployment context, buyer sophistication tier, and regional regulatory cluster. CAGRs were derived from slope analysis of ordinance-driven demand spikes and technology substitution curves. Forecast inputs incorporated lithium cell supply allocation cycles and smart home hub substitution elasticity.
The model assumes a particular technology adoption path; alternative pathways for AI-based perimeter detection would alter the outlook if insurer recognition shifts toward whole-property monitoring systems. Forecasts reflect assumptions about municipal ordinance enforcement intensity and ASTM certification timeline stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Radar Security Market
Security and Surveillance
Europe Border Security Market
Security and Surveillance
Asia-Pacific Urban Security Screening Market
Security and Surveillance
Anti-Piracy Protection Market
Security and Surveillance
Global Security Advisory Services Market
Security and Surveillance
Door and Window Alarm Market
Security and Surveillance
X-Ray Security Screening System Market
Security and Surveillance
Global Intrusion Detection System Market
Security and Surveillance
Global Manned Security Service Market
Security and Surveillance
Air Cargo Screening Systems Market
Security and Surveillance
Europe Rockfall Radar Market
Security and Surveillance
Home Security Sensors Market
Security and Surveillance
India Perimeter Intrusion Detection and Prevention Market
Security and Surveillance
Signal Jammer Market
Security and Surveillance
Security Operations Center Market
Security and Surveillance
Global Police and Law Enforcement Equipment Market