
 Security Holograms Market | 2026-2036
Security Holograms Market Size, Share, and Industry Trends Forecast 2026-2036
Security Holograms Market Outlook
Single-source hologram procurement from dedicated security printers is decoupling from brand owners' legacy vendor lock-ins. Holostik India Limited leverages domestic manufacturing scale to anchor government ID and excise stamp contracts across South Asia. Leonhard Kurz Stiftung differentiates through metallization and micro-optics integration that extends beyond holography into full-brand protection systems. De La Rue plc dominates banknote substrate security, sustaining long-dated central bank relationships that competitors struggle to displace.
Security holograms are optically variable devices manufactured through laser interference patterning, typically embossed into metallized polyester or hot-stamp foils with resolutions below one micron, functioning as machine-readable and visually verifiable anti-counterfeiting layers. Tamper-evident labels command the largest product-type volume pool due to pharmaceutical and food-packaging mandates, while 3D holography captures premium pricing in banknote protection where central banks demand multi-axis depth perception. Laser holography remains the most mature technology base, though reflective holography grows fastest in consumer goods as brands seek shelf-visible authentication without dedicated reader infrastructure.
FDA's Drug Supply Chain Security Act and the EU's MDR traceability requirements both shape hologram specification, with the former pushing serialized aggregation and the latter mandating Unique Device Identification on high-risk medical packaging. India's BIS certification for holographic products and CDSCO's import licensing for labeled pharmaceuticals create a dual compliance burden that filters out uncertified suppliers. ISO 14298 and IHMA standards provide the interoperability baseline that determines which manufacturers qualify for cross-border tenders. Stakeholders must monitor whether central bank digital currency pilots reduce physical banknote volumes faster than hologram unit value can compensate.
Market Dynamics
Pharmaceutical serialization mandates across multiple jurisdictions are forcing hologram manufacturers to integrate machine-readable layers with optical security features, compressing development cycles and raising certification barriers for uncertified suppliers.
Growth Catalysts
- EU Falsified Medicines Directive:Delegated regulations on safety features mandate tamper-evident verification for prescription drugs across member states, creating baseline demand for holographic authentication layers.
- India CDSCO traceability rules:Export corridor compliance requirements push contract manufacturers toward integrated holographic labeling systems for pharmaceutical packaging destined for regulated markets.
- Reflective holography:Consumer goods brands adopt shelf-visible authentication without dedicated reader infrastructure, expanding addressable market beyond high-security applications.
Market Restraints
- Metallized polyester supply concentration:Substrate production clusters in East Asian petrochemical corridors expose hologram manufacturers to input cost volatility and freight disruption.
- Central bank digital currency pilots:Reduced physical banknote volume trajectories in multiple jurisdictions threaten long-term demand for premium holographic substrate security.
- Laser interference patterning capex:Master origination equipment requires specialized cleanroom facilities that filter out mid-scale entrants.
Strategic Opportunities
- ISO 14298 certification gaps:Uncertified suppliers in Southeast Asian pharmaceutical packaging corridors create acquisition targets for quality-accredited hologram producers.
- Micro-optics convergence:Integration of metallization with holographic layers enables full-brand protection system bundling beyond standalone optical devices.
- IHMA standard harmonization:Emerging interoperability baselines open cross-border tender participation for previously regional security printers.
Industry Challenges
- Master origination talent scarcity:Laser interference patterning requires optical engineering specialists with sub-micron resolution experience that training pipelines have not scaled.
- Dual compliance timelines:India's BIS certification for holographic products runs parallel to CDSCO import licensing, extending qualification cycles for labeled pharmaceuticals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Security Holograms Market |
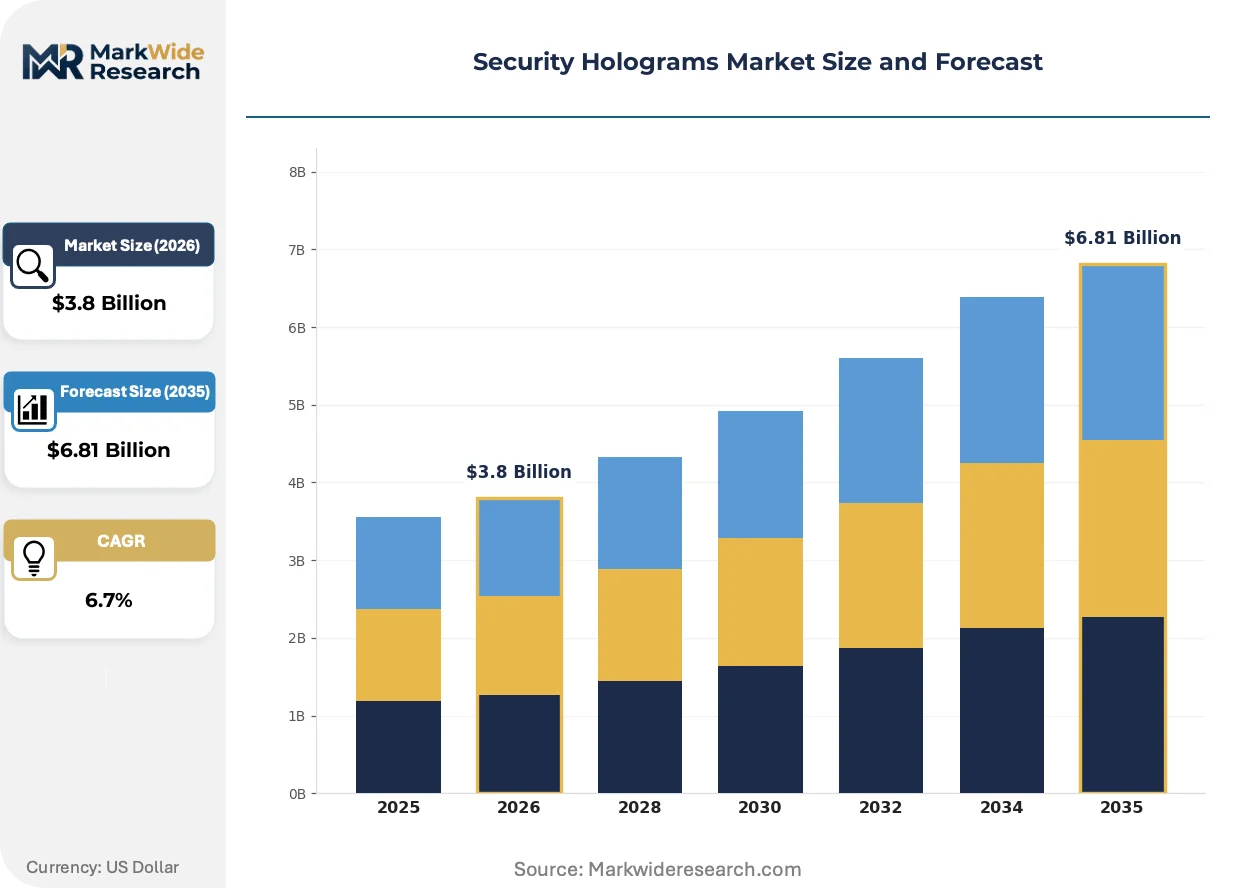
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tamper-Evident Labels, Holographic Films, Security Features, Authenticity Markers Application: Banknote Protection, Product Packaging, Brand Authentication, Anti-Counterfeiting Technology: Reflective Holography, Transmission Holography, Laser Holography, 3D Holography End User: Banking, Consumer Goods, Pharmaceuticals, Government |
| Companies Covered | Holostik India Limited, Wavefront Technology Inc., Leonhard Kurz Stiftung, Integraf LLC, Spectratek Technologies Inc., K Laser Technology, OpSec Security Group, Holography Sciences Inc., De La Rue plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Security Holograms Market Strategic Shifts
Authentication technology is bifurcating between high-security machine-readable layers for regulated pharmaceuticals and visually verifiable features for consumer goods brand protection. This divergence is reshaping R&D allocation and partnership structures across the supplier base.
Nanostructured surface relief holography embeds covert forensic markers detectable through polarized light analysis without specialized readers. Pharmaceutical packaging lines in Germany and Switzerland embed these layers at accelerating rates. The technology is converging with serialized aggregation systems required under FDA's Drug Supply Chain Security Act, compressing the window between optical authentication and digital traceability.
REACH restrictions on heavy metal pigments in metallized substrates force reformulation of traditional hot-stamp foils used in European pharmaceutical and tobacco excise applications. Reformulated polyester films with vacuum-deposited aluminum alternatives now dominate new tender specifications. High-risk medical packaging under EU MDR traceability requirements shows the strongest compliance response, with contract manufacturers pre-qualifying alternative substrate suppliers.
Brand protection procurement now separates optical security specification from label converting, with end-users direct-contracting hologram master origination while retaining legacy converters for application. Food and beverage multinationals in North America lead this unbundling, disintermediating integrated security printers who previously controlled both origination and converting. The shift is most visible in high-volume consumer goods where unit cost sensitivity outweighs single-source convenience.
Security Holograms Market Segmentation
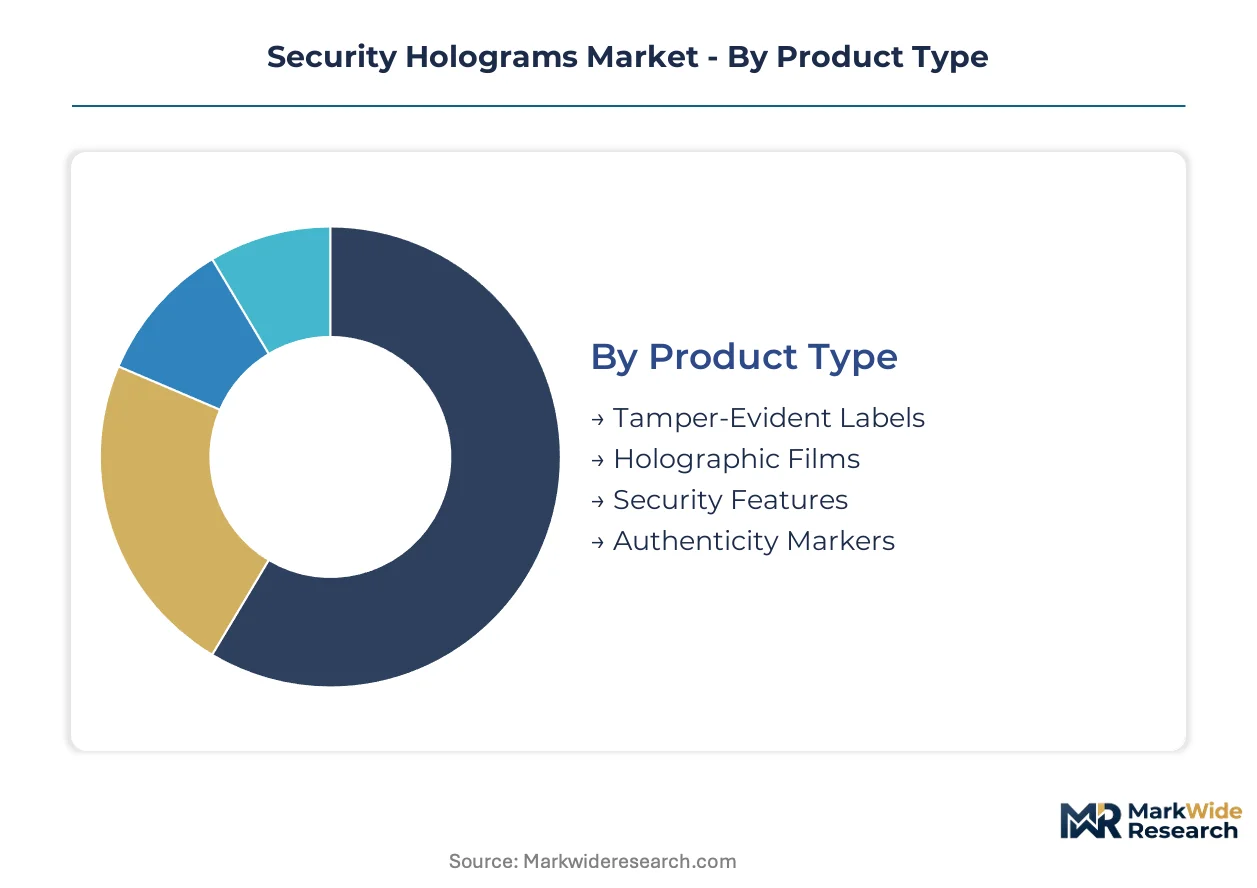
Security hologram procurement patterns diverge sharply between regulated applications demanding machine-readable authentication and consumer-facing uses prioritizing visual verification. Capital allocation across these segments reflects fundamentally different equipment requirements, certification barriers, and customer concentration profiles.
Product Type:
Master origination equipment and cleanroom infrastructure requirements vary dramatically across product categories, with metallized substrate handling demanding the heaviest fixed-cost commitments.
- Tamper-Evident Labels:These self-adhesive constructions integrate holographic layers with destructible substrates that fracture upon removal. Pharmaceutical packaging lines in India and Southeast Asia embed these markers at accelerating rates to satisfy CDSCO traceability rules and EU Falsified Medicines Directive compliance for export-bound products.
- Holographic Films:Continuous roll formats serve high-volume converting operations with resolutions below one micron embossed into metallized polyester. Demand concentrates in tobacco excise and government ID applications where substrate security must survive harsh environmental exposure.
- Security Features:Discrete optical elements embedded within broader packaging systems. Banking and high-value document applications drive specification.
- Authenticity Markers:Standalone verification devices for brand protection programs. Consumer goods manufacturers deploy these for shelf-visible authentication without reader infrastructure.
Tamper-evident labels absorb the bulk of installed capacity; authenticity markers are expanding most quickly as brand owners unbundle optical security from legacy converter relationships.
Application:
Customer procurement sophistication spans from central bank technical committees with decade-long qualification cycles to consumer goods brand managers seeking rapid deployment flexibility.
- Banknote Protection:Multi-axis depth perception requirements demand 3D holography with sub-micron resolution and specialized metallization. Central bank relationships sustain long-dated contracts that competitors struggle to displace, though digital currency pilots threaten volume trajectories in multiple jurisdictions.
- Product Packaging:Food and beverage multinationals in North America lead the unbundling of optical security specification from label converting. Shelf-visible authentication without dedicated readers dominates procurement criteria.
- Brand Authentication:Covert forensic markers detectable through polarized light analysis embed within luxury goods and high-value consumer products. Nanostructured surface relief holography shows accelerating adoption in German and Swiss packaging lines.
- Anti-Counterfeiting:Integrated machine-readable and optical layers for high-risk applications. Pharmaceutical serialization mandates compress development cycles and raise certification barriers.
Banknote protection commands premium unit economics; product packaging shows the steepest expansion trajectory as brand protection procurement separates origination from converting.
Technology:
Development cycle length and specialized talent requirements create divergent competitive moats across holographic platforms.
- Laser Holography:The most mature technology base with established master origination protocols and broad supplier availability. REACH restrictions on heavy metal pigments in metallized substrates force continuous reformulation of traditional hot-stamp foils in European applications.
- Reflective Holography:Shelf-visible authentication without dedicated reader infrastructure drives fastest adoption in consumer goods. Brands seek immediate visual verification that does not complicate retail workflows.
- Transmission Holography:Backlit viewing requirements limit deployment to specialized document and display applications. Niche demand from security printers serving government credential markets.
- 3D Holography:Multi-axis depth perception commands premium pricing where central banks demand sophisticated anti-counterfeiting layers. Optical engineering specialists with sub-micron resolution experience remain scarce.
Laser holography retains the deepest installed base; reflective holography is climbing the fastest as consumer goods brands prioritize convenience over maximum security.
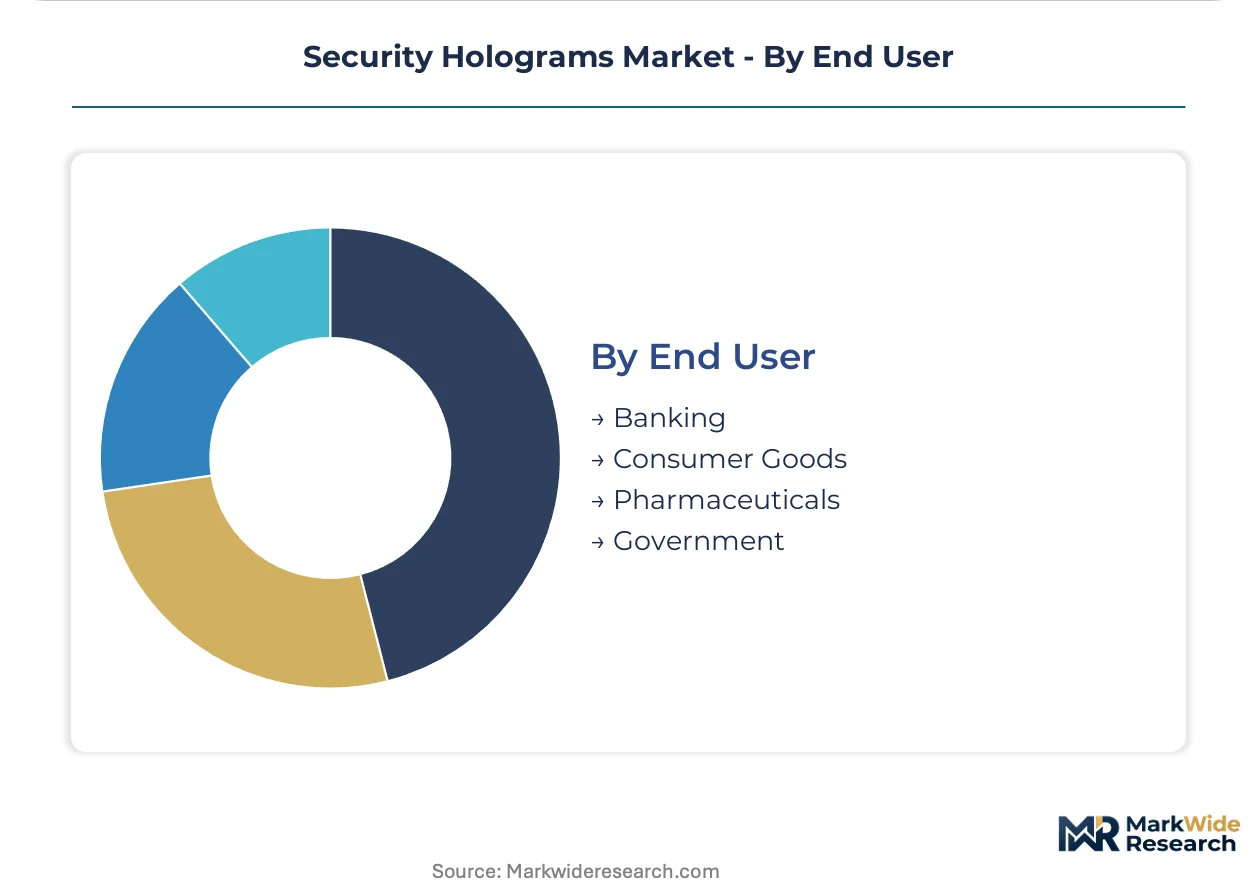
End User:
Procurement concentration and qualification timeline intensity vary from single-source central bank relationships to fragmented consumer goods brand portfolios.
- Pharmaceuticals:Dual compliance burdens from BIS certification and CDSCO import licensing extend qualification cycles for labeled pharmaceuticals in India. FDA's Drug Supply Chain Security Act and EU MDR traceability requirements both shape hologram specification with serialized aggregation mandates.
- Government:Long-dated contracts for excise stamps, tax labels, and identity documents. Holostik India Limited leverages domestic manufacturing scale to anchor government ID contracts across South Asia.
- Banking:Central bank substrate security demands sustained by De La Rue plc's entrenched relationships. Threatened by digital currency volume reductions.
- Consumer Goods:Direct contracting of hologram master origination while retaining legacy converters for application. Food and beverage multinationals lead this procurement restructuring.
Pharmaceuticals absorb the bulk of current R&D investment; consumer goods is gaining share fastest as authentication technology bifurcates between machine-readable and visually verifiable layers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metallized polyester substrate production clusters in East Asian petrochemical corridors, yet demand generation and regulatory specification authority concentrate in distinct Western and South Asian markets. National pharmaceutical regulators and central banks across five countries drive procurement patterns and compliance architecture.
United States
FDA's Drug Supply Chain Security Act mandates serialized aggregation for pharmaceutical packaging, compressing hologram development cycles. The regulation pushes contract manufacturers toward integrated machine-readable optical layers. New Jersey and Massachusetts pharmaceutical corridors embed authentication markers at accelerating rates to satisfy traceability requirements.
Germany
REACH restrictions on heavy metal pigments force reformulation of traditional hot-stamp foils in metallized substrates. EMA pharmaceutical packaging standards and EU MDR traceability requirements shape hologram specification for high-risk medical devices. Stuttgart and Munich packaging lines pre-qualify alternative substrate suppliers with vacuum-deposited aluminum solutions.
India
CDSCO traceability rules and DGFT export compliance push contract manufacturers toward holographic labeling systems for regulated markets. BIS certification for holographic products runs parallel to pharmaceutical import licensing, extending qualification cycles. Mumbai and Ahmedabad pharmaceutical export corridors embed tamper-evident markers to satisfy destination market mandates.
Switzerland
Swissmedic pharmaceutical standards and proximity to EU regulatory frameworks position the country as a specification hub for premium authentication layers. Nanostructured surface relief holography shows accelerating adoption in Basel and Zurich packaging lines. Covert forensic markers detectable through polarized light analysis embed within high-value pharmaceutical exports.
United Kingdom
De La Rue plc sustains long-dated central bank relationships for banknote substrate security, though digital currency pilots threaten volume trajectories. The Bank of England's technical committees maintain decade-long qualification cycles for holographic features. London remains a procurement center for government ID and excise stamp contracts across Commonwealth markets.
Security Holograms Market Competitive Environment
Global majors compete with regional champions across certification barriers and master origination capacity. The vendor base stratifies between integrated security printers controlling substrate metallization and specialized hologram originators selling master designs to third-party converters. Three archetypes dominate: scale-driven substrate metallizers, certification-accredited regional printers, and technology-specialized originators. Competitive moves concentrate on ISO 14298 certification acquisition and micro-optics portfolio diversification.
Within the regional-accredited tier, Holostik India Limited anchors government ID and excise stamp contracts across South Asia through domestic manufacturing scale. Leonhard Kurz Stiftung exemplifies the integrated metallization archetype, extending capabilities beyond holography into full-brand protection systems. De La Rue plc occupies a position at the central bank security vector, sustaining relationships that competitors struggle to displace. These three represent distinct strategic positions: regional scale, technology integration, and institutional entrenchment.
| Leading Market Players |
|---|
| Holostik India Limited |
| Wavefront Technology Inc. |
| Leonhard Kurz Stiftung |
| Integraf LLC |
| Spectratek Technologies Inc. |
| K Laser Technology |
| OpSec Security Group |
| Holography Sciences Inc. |
| De La Rue plc |
| Others |
Value Chain & Pricing Dynamics
Reflective holography adoption in consumer goods packaging is compressing cost structures while fragmenting procurement relationships, simultaneously lowering entry barriers for specialized originators and eroding integrated printers' pricing power. Metallized polyester substrate reformulation under REACH restrictions adds parallel cost pressures that concentrate margin recovery among scale-accredited producers.
Pricing Analysis
Master origination warranties and ISO 14298 certification maintenance are increasingly unbundled from per-unit foil pricing, with pharmaceutical buyers direct-contracting for optical security specification while sourcing application through legacy converters. Pricing stratifies across certified premium tiers for serialized aggregation compatibility, standard tiers for tamper-evident pharmaceutical labels, and economy tiers for shelf-visible consumer goods authentication. Cost compression in economy tiers is intensifying because brand owners pit specialized hologram originators against integrated security printers in competitive tender. Consumer goods manufacturers show highest price sensitivity, while central bank technical committees prioritize multi-axis depth perception and decade-long supplier relationships over unit cost.
Supply Chain Analysis
Vacuum-deposited aluminum supply rests on German and Japanese specialty metallization equipment producers, with polyester film substrate production anchored in South Korean and Taiwanese petrochemical corridors. Master origination equipment draws from Swiss and German precision optics manufacturers, while cleanroom infrastructure components source from Dutch and American suppliers. Single-source vulnerability concentrates in laser interference patterning systems where sub-micron resolution capabilities remain scarce. Distribution runs through regional security printers who combine origination, metallization, and converting, though unbundling trends are fragmenting this structure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 14298 certification barriers and serialized aggregation complexity are forcing uncertified regional printers toward exit or acquisition, consolidating viable supply among quality-accredited producers with integrated metallization capabilities.
For Market Incumbents: Anchor government ID and excise stamp relationships through domestic manufacturing scale in South Asia, while acquiring ISO 14298-certified originators in Southeast Asian pharmaceutical corridors to fill certification gaps. Central bank digital currency pilots threaten banknote substrate volumes; offset this through micro-optics portfolio diversification into full-brand protection systems for consumer goods. For New Entrants and Emerging Players: E-commerce authentication platforms offer route-to-market acceleration for nanostructured surface relief holography with covert forensic markers, bypassing legacy converter relationships. Target Swiss and German pharmaceutical packaging lines where serialized aggregation mandates create urgent demand for machine-readable optical layers. White-space concentrates in authenticity markers for luxury goods where shelf-visible verification without reader infrastructure commands premium positioning. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated metallization specialists seeking certification-accured regional footprints. Long-term viability favors originators with captive cleanroom infrastructure and pharmaceutical serialization integration capabilities. Watch central bank digital currency pilot expansion as volume inflection signal for banknote substrate security demand.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 14298 Certification Acquisition | Qualifies suppliers for EU Falsified Medicines Directive pharmaceutical tenders. |
| Micro-Optics Portfolio Diversification | Extends holography capabilities into full-brand protection systems beyond optical devices. |
| Master Origination Talent Development | Addresses laser interference patterning specialist scarcity constraining capacity expansion. |
| Alternative Substrate Pre-Qualification | Satisfies REACH restrictions on heavy metal pigments in European pharmaceutical applications. |
| Serialized Aggregation Integration | Aligns optical authentication with FDA Drug Supply Chain Security Act traceability mandates. |
Study Parameters
Document review covered regulatory filings from FDA, EMA, and CDSCO, complemented by interviews with security printer operations directors, pharmaceutical packaging procurement managers, central bank technical committee members, and holography R&D specialists. Secondary validation drew from ISO 14298 certification registries, IHMA membership directories, customs trade data for metallized polyester films, and SEC disclosures from listed security printers. Bottom-up capacity assessments across master origination facilities were triangulated against top-down demand modeling from pharmaceutical serialization mandates and banknote substrate procurement.
Unit and value projections were generated through segment-level modeling across product type, application, technology, and end-use dimensions, with additional stratification by certification tier and geographic regulatory cluster. CAGRs were derived from regression analysis of historical pharmaceutical packaging line expansion rates and central bank substrate security procurement cycles. Forecast inputs incorporated REACH regulatory timeline assumptions and digital currency pilot trajectory scenarios.
Inputs from certification bodies and regulatory agencies were available through the study window; gaps in private contract pricing and master origination equipment capacity utilization introduce uncertainty bands around competitive share projections. Forecasts reflect documented assumptions regarding pharmaceutical serialization mandate enforcement consistency and metallized substrate supply stability. Central bank digital currency adoption rates, REACH reformulation cost pass-through elasticity, and laser interference patterning talent pipeline expansion warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Alarm Monitoring Software Market
Security and Surveillance
Global Wireless Doorbells Market
Security and Surveillance
Explosive Trace Detection Market
Security and Surveillance
Latin America Electronics Security Market
Security and Surveillance
Security Services Market
Security and Surveillance
Global Physical Security Software Market
Security and Surveillance
Global Wireless Monitoring and Surveillance Market
Security and Surveillance
Smart Home Security Market
Security and Surveillance
North America Security Screening Market
Security and Surveillance
India Perimeter Intrusion Detection and Prevention Market
Security and Surveillance
Perimeter Security Market
Security and Surveillance
Global Intrusion Detection System Market
Security and Surveillance
Russian Intelligent Eavesdropping Detection System Market
Security and Surveillance
Threat Detection Systems Market
Security and Surveillance
Vietnam Private Security Market
Security and Surveillance
Europe Anti-Piracy Protection Market