
 Middle East and Africa Cargo and Vehicle Screening Market | 2026-2036
Middle East and Africa Cargo and Vehicle Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Cargo and Vehicle Screening Market Insights
Emirati port operators is rebalancing capacity toward automated inspection lanes. Rapiscan Systems leverages its installed base across Gulf airports to sustain service revenue. Smiths Detection Group anchors European-origin supply into African customs modernization programs. Nuctech dominates Chinese-funded infrastructure corridors linking East African ports to inland logistics hubs.
Cargo and vehicle screening encompasses non-intrusive inspection technologies that detect contraband, explosives, and hazardous materials in commercial freight and passenger vehicles using X-ray transmission, computed tomography, or radiation portal monitors, typically operating at 1-9 MeV energy levels for dense cargo penetration. These systems serve customs enforcement, critical infrastructure protection, and trade compliance verification at transit chokepoints. X-ray technology leads installed volumes across seaports due to lower capital thresholds and proven throughput rates, while CT scanning captures premium-margin replacements at aviation checkpoints where three-dimensional imaging meets emerging hold-baggage standards. Government agencies represent the dominant end-user category, though logistics providers are expanding private screening investments ahead of supply chain security certification requirements.
Saudi Arabia's SFDA coordinates hazardous materials transport rules with customs screening protocols, while South Africa's national regulator enforces port security standards aligned with the International Ship and Port Facility Security Code. The UAE's MOHAP and federal customs authority jointly specify radiation detection thresholds for cross-border commercial traffic. Stakeholders must weigh technology refresh timing against evolving multi-energy imaging standards and financing structures for greenfield African port installations.
Market Dynamics
Automated inspection lanes at Gulf ports are compressing operator labor requirements while expanding throughput capacity, forcing incumbents to restructure service revenue models around predictive maintenance and software upgrades rather than hardware replacement cycles.
Growth Catalysts
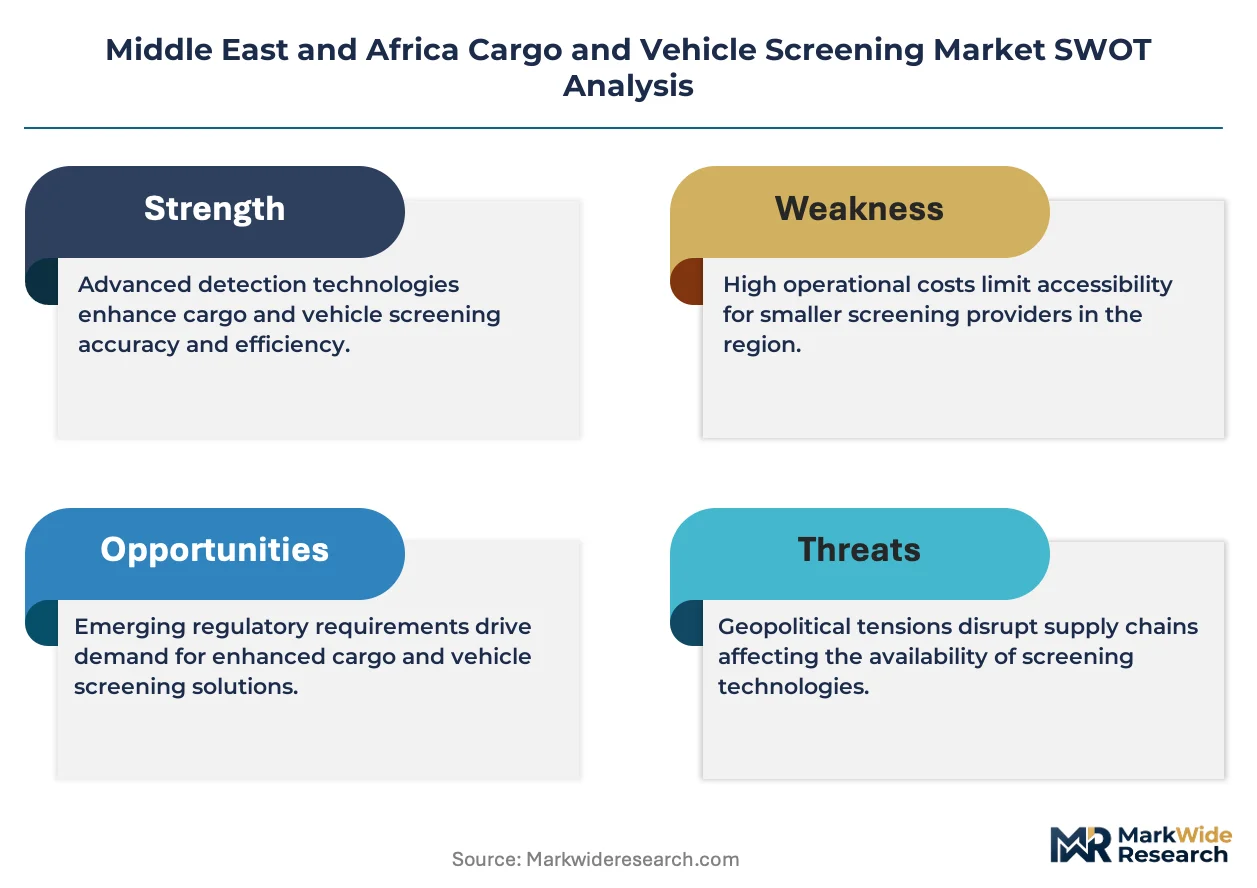
- SFDA hazardous materials coordination:Saudi Arabia's food and drug authority mandates unified screening protocols for chemical shipments, creating standardized procurement specifications across customs and transport agencies.
- East African corridor infrastructure:Chinese-funded rail and port linkages between Mombasa and Nairobi generate dedicated screening infrastructure requirements at inland container depots and border crossings.
- CT scanner adoption:Aviation security agencies across the Gulf Cooperation Council deploy computed tomography systems to meet emerging hold-baggage resolution standards, displacing legacy X-ray units at premium checkpoints.
Market Restraints
- High-energy X-ray tube supply concentration:Specialized vacuum tube manufacturing concentrates in European and North American suppliers, exposing African procurement timelines to extended lead times and currency volatility.
- Technical limitation in dense cargo penetration:Conventional 6 MeV systems struggle with fully loaded container verification, forcing expensive dual-energy upgrades or manual secondary inspection protocols.
- Regulatory friction from divergent customs codes:The UAE's federal customs authority maintains distinct technical specifications from Saudi Arabia's Zakat and Tax Authority, fragmenting vendor certification requirements across adjacent markets.
Strategic Opportunities
- Underpenetrated Nigerian port modernization:Lagos Port Complex and Tin Can Island terminal expansion plans lack committed screening infrastructure budgets, creating first-mover positioning for integrated system providers.
- Technology convergence of radiation portal and imaging systems:Combined gamma-neutron detection with automated X-ray analysis reduces lane footprint and staffing requirements at high-volume land borders.
- MOHAP radiation detection thresholds:The UAE's ministry of health and prevention mandates upgraded detection sensitivity for cross-border commercial traffic, accelerating replacement demand at existing installations.
Industry Challenges
- Certification timeline compression:South Africa's national customs control act implementation deadlines force rapid deployment of ISPS-aligned screening infrastructure before full vendor qualification cycles complete.
- Integration complexity with legacy customs IT:New screening systems must interface with decades-old manifest processing databases at Jebel Ali and Durban ports, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Cargo and Vehicle Screening Market |
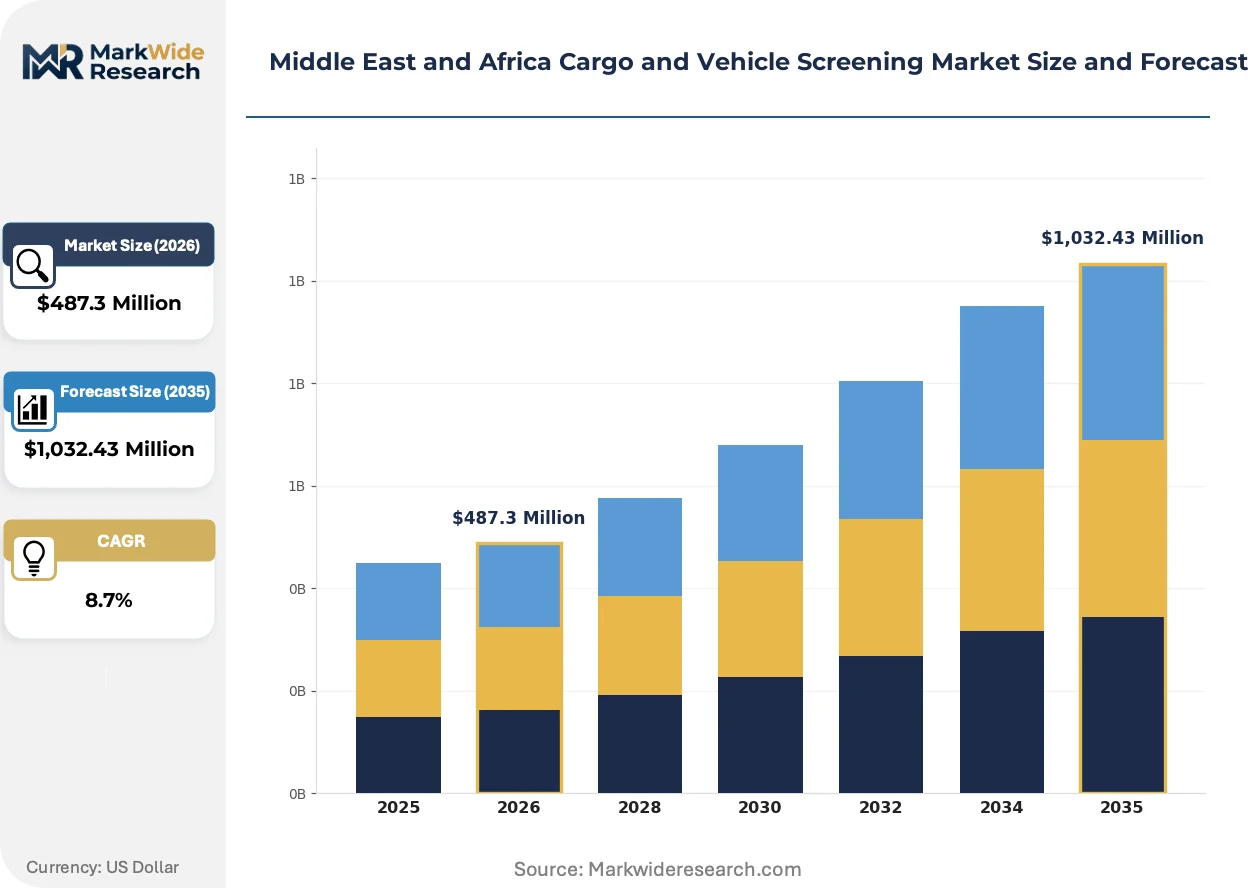
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: X-Ray, CT Scanning, Radiation Detection, Explosive Trace Detection Application: Airports, Seaports, Border Security, Customs End User: Government Agencies, Transport Companies, Security Firms, Logistics Providers Solution: Integrated Systems, Stand-Alone Systems, Software Solutions, Consultation Services |
| Companies Covered | Rapiscan Systems, Westminster Group, OSI Systems, ADANI, Leidos, Nuctech, LINEV Systems, L3Harris Technologies, Smiths Detection Group, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Cargo and Vehicle Screening Market Trends and Innovations
Multi-energy imaging architectures are displacing single-source systems across high-volume checkpoints, while software-defined detection algorithms reduce hardware refresh frequency. These shifts compress capital equipment cycles and expand recurring revenue attachment rates.
Computed tomography for air cargo is consolidating inspection workflows at Gulf aviation hubs. Emirates Group and Etihad Airways cargo terminals deploy 3D reconstruction systems to eliminate manual break-bulk procedures. This consolidation reduces physical inspection rates from 15% to under 5% while compressing clearance times for express freight.
South Africa's national customs control act enforces port security standards aligned with the International Ship and Port Facility Security Code. Terminal operators at Durban and Cape Town must upgrade perimeter and cargo screening infrastructure to maintain vessel call schedules. The regulation accelerates equipment refresh cycles for radiation portal monitors and vehicle inspection systems.
Logistics providers are unbundling after-sales service contracts from initial equipment procurement. DHL Global Forwarding and similar operators across the UAE and Kenya negotiate separate multi-year maintenance agreements with performance-based uptime guarantees. This shift transfers operational risk to vendors while locking in captive service revenue streams.
Middle East and Africa Cargo and Vehicle Screening Market Segmentation
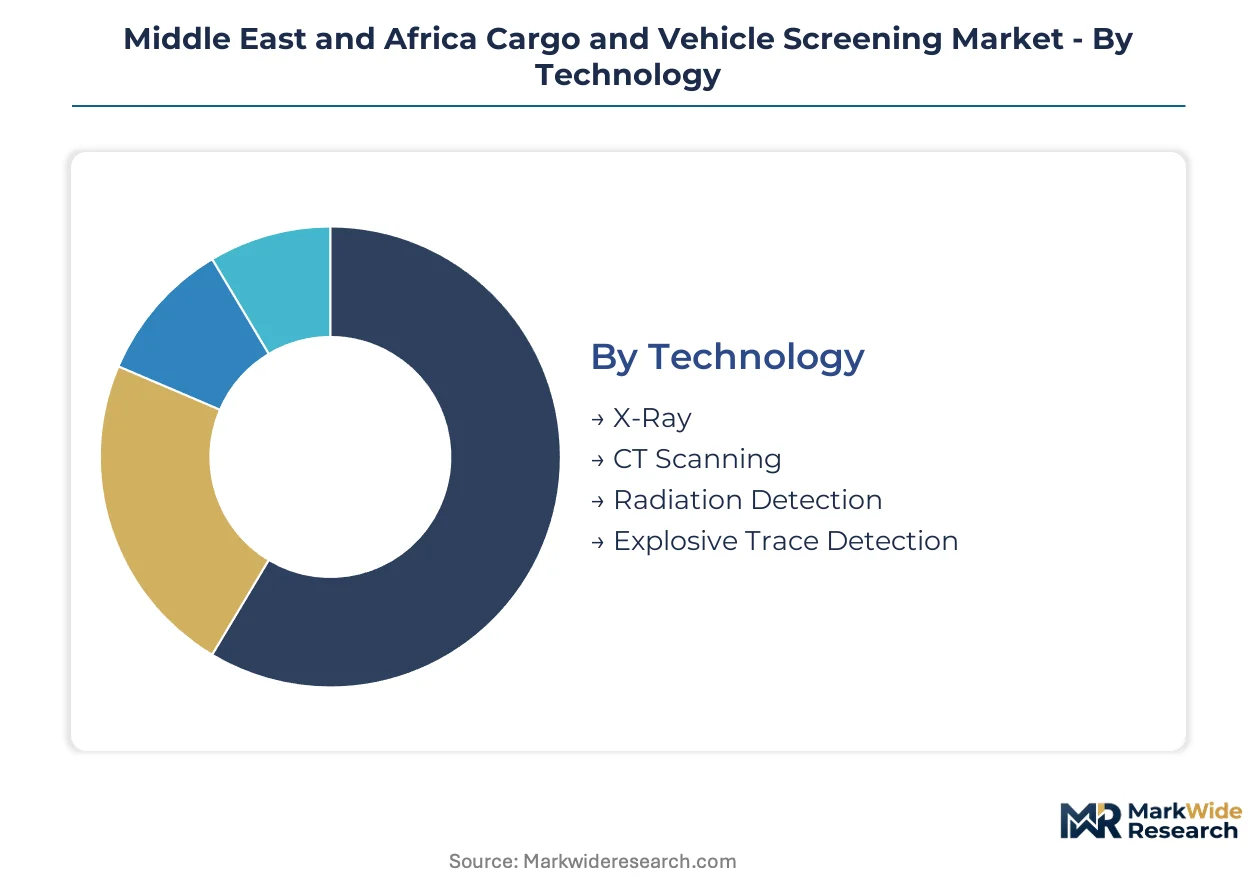
Segmentation in the Middle East and Africa cargo and vehicle screening market reveals distinct procurement patterns across technology maturity and infrastructure integration levels. Gulf Cooperation Council agencies favor bundled solutions with predictive maintenance, while African customs authorities prioritize standalone hardware with lower capital thresholds.
Technology:
X-ray and CT scanning systems operate as standalone inspection platforms, while radiation detection and explosive trace technologies embed into multi-sensor architectures at high-volume chokepoints.
- X-Ray:Linear accelerator-based systems generate 1-9 MeV energy for dense cargo penetration. Dubai's Jebel Ali Port deploys these for container verification, though dual-energy upgrades face procurement delays from European tube supply concentration.
- CT Scanning:Computed tomography reconstructs three-dimensional cargo images to eliminate manual break-bulk. Emirates Group cargo terminals at Al Maktoum International Airport displace legacy units to meet emerging hold-baggage resolution standards.
- Radiation Detection:Gamma-neutron portal monitors screen commercial traffic at land borders.
- Explosive Trace Detection:Ion mobility spectrometry devices supplement imaging at aviation checkpoints.
X-ray leads volumes today; CT scanning is gaining share fastest.
Application:
Seaports and airports concentrate capital expenditure, while border security and customs applications spread across smaller procurement packages with shorter replacement cycles.
- Airports:Hold-baggage and air cargo screening dominate technology refresh budgets. Gulf aviation hubs deploy 3D reconstruction systems that compress physical inspection rates from 15% to under 5% for express freight.
- Seaports:Container inspection systems anchor regional deployment volumes. South Africa's Durban and Cape Town terminal operators upgrade radiation portal monitors and vehicle inspection systems under national customs control act deadlines.
- Border Security:Land crossing infrastructure spans the East African corridor between Mombasa and Nairobi.
- Customs:Inland container depots require flexible screening configurations.
Seaports absorb the largest capital allocation; airports show the steepest expansion trajectory.
End User:
Government agencies dominate tender volumes, while logistics providers and security firms expand private screening investments ahead of supply chain certification mandates.
- Government Agencies:Federal customs authorities and port operators specify technical standards and operate procurement. The UAE's federal customs authority and MOHAP jointly set radiation detection thresholds for cross-border commercial traffic.
- Transport Companies:Rail and trucking operators face hazardous materials coordination rules from Saudi Arabia's SFDA.
- Security Firms:Private contractors maintain perimeter screening at critical infrastructure.
- Logistics Providers:DHL Global Forwarding and similar operators negotiate separate multi-year maintenance agreements with performance-based uptime guarantees.
Government agencies control procurement today; logistics providers are expanding most quickly.
Solution:
Integrated systems command premium pricing with software-defined detection algorithms, while standalone hardware and consultation services address budget-constrained African installations.
- Integrated Systems:Combined imaging and radiation detection reduces lane footprint and staffing requirements. Technology convergence at high-volume land borders compresses clearance times while expanding recurring revenue attachment rates.
- Stand-Alone Systems:Single-purpose X-ray or radiation units serve lower-throughput checkpoints. Nigerian port modernization at Lagos Port Complex and Tin Can Island terminal lacks committed screening infrastructure budgets, creating first-mover positioning.
- Software Solutions:Detection algorithm updates extend hardware refresh cycles.
- Consultation Services:Vendor expertise navigates certification timelines and legacy customs IT integration complexity.
Integrated systems capture premium margins; software solutions are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's customs modernization outpaces South Africa's port security upgrades in absolute spending, yet Nigerian terminal expansions present larger untapped procurement volumes for screening infrastructure.
United Arab Emirates
Dubai's Jebel Ali Port and Al Maktoum International Airport anchor regional deployment volumes for automated inspection lanes. MOHAP and the federal customs authority jointly specify radiation detection thresholds for cross-border commercial traffic. Abu Dhabi's Khalifa Port is expanding container screening capacity ahead of transshipment volume growth.
Saudi Arabia
SFDA coordinates hazardous materials transport rules with customs screening protocols, creating unified procurement specifications across agencies. The Zakat and Tax Authority maintains distinct technical specifications from neighboring customs regimes. Riyadh's King Khalid International Airport and Jeddah Islamic Port are refreshing legacy X-ray units under aviation security mandates.
South Africa
Durban and Cape Town terminal operators upgrade radiation portal monitors and vehicle inspection systems under national customs control act deadlines aligned with ISPS Code requirements. The national regulator enforces compressed certification timelines. The Port of Durban's container terminal is deploying dual-energy systems to address dense cargo penetration limits.
Nigeria
Lagos Port Complex and Tin Can Island terminal expansion plans lack committed screening infrastructure budgets, creating first-mover positioning for integrated system providers. The country's national customs authority is revising technical specifications for non-intrusive inspection equipment. Apapa and Lekki port zones concentrate demand for standalone hardware with lower capital thresholds.
Kenya
Chinese-funded rail and port linkages between Mombasa and Nairobi generate dedicated screening infrastructure requirements at inland container depots and border crossings. The Kenya Revenue Authority is standardizing customs codes with East African Community protocols. The Mombasa Port modernization program and Nairobi Inland Container Depot anchor equipment deployment volumes.
Middle East and Africa Cargo and Vehicle Screening Market Competitive Landscape
North American and European producers anchor one tier; Chinese specialists hold procurement advantages across African infrastructure corridors. The vendor base concentrates around three strategic archetypes: integrated solution providers bundling hardware with predictive maintenance contracts, regional specialists leveraging installed bases for service revenue, and state-linked fabricators capturing corridor-specific tenders. Competitive moves center on technology convergence partnerships and unbundled after-sales service contracts with performance-based uptime guarantees.
Among the named participants, Rapiscan Systems and Smiths Detection Group exemplify Western-origin suppliers with established aviation and seaport footprints, while Nuctech occupies a position as the dominant Chinese-funded infrastructure corridor provider. These three anchors illustrate how geographic origin and financing source shape procurement access across Gulf customs modernization and African greenfield port development.
| Leading Market Players |
|---|
| Rapiscan Systems |
| Westminster Group |
| OSI Systems |
| ADANI |
| Leidos |
| Nuctech |
| LINEV Systems |
| L3Harris Technologies |
| Smiths Detection Group |
| Others |
Pricing and Supply Chain Analysis
Specialized vacuum tube engineering talent clusters in Germany and the United States widen labor-cost differentials between European-origin systems and Chinese-funded alternatives, compressing pricing-tier spreads for high-energy X-ray components while inflating premium margins for predictive maintenance contracts.
Pricing Analysis
Capacity additions in Chinese manufacturing corridors are reshaping price floors for radiation detection hardware across African customs modernization programs. Three-tier pricing structure across premium, standard, and economy levels separates ISPS-certified integrated systems from standalone hardware and basic consultation packages. Price differentiation hinges on after-sales bundling and certification grade, with Gulf Cooperation Council agencies least sensitive due to bundled procurement mandates. Cost compression in entry-level X-ray units is intensifying because Nuctech's corridor-specific financing undercuts European-origin quotes.
Supply Chain Analysis
ISPS Code certification and MOHAP radiation detection qualification gates restrict vendor participation to pre-approved fabricators, elongating procurement timelines. Manufacturing concentrates in Germany, the United States, and China for high-energy X-ray tubes, linear accelerator assemblies, and gamma-neutron portal monitors. Component sourcing draws from specialized vacuum tube foundries, radiation sensor fabs, and precision mechanical sub-suppliers. Single-source vulnerability in European tube manufacturing exposes African installations to currency volatility and extended lead times. Distribution runs through government tender channels and state-linked infrastructure financiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa cargo and vehicle screening market compounds regulatory demand through successive customs code harmonization deadlines, with South Africa's national customs control act implementation creating immediate equipment refresh obligations.
For Market Incumbents: Lock in predictive maintenance revenue streams by unbundling service contracts from initial hardware procurement, as DHL Global Forwarding's performance-based uptime negotiations demonstrate. Secure backward integration into software-defined detection algorithms to extend hardware refresh cycles and displace substitute analytics providers. Counter Nuctech's corridor financing advantage by anchoring European-origin supply into Saudi SFDA-mandated unified screening protocols. For New Entrants and Emerging Players: Direct-to-government digital procurement portals offer the fastest route to qualification, bypassing incumbent distributor networks. Target Nigerian port modernization at Lagos Port Complex and Tin Can Island terminal, where committed screening infrastructure budgets remain unallocated. Position integrated systems with flexible financing against standalone hardware preferences at Apapa and Lekki port zones. For Investors and Strategic Acquirers: State-linked infrastructure developers are the most active acquirer in this space, consolidating technology convergence capabilities for Chinese-funded African corridors. Five-to-ten year viability rests on recurring revenue attachment rates from software upgrades rather than capital equipment cycles. Monitor MOHAP radiation detection threshold revisions as the inflection signal for replacement demand acceleration across UAE installations.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Convergence Partnership | Combined gamma-neutron detection with automated X-ray analysis reduces staffing at high-volume land borders. |
| Unbundled Service Contract Model | Performance-based uptime guarantees transfer operational risk from logistics providers to equipment vendors. |
| Corridor-Specific Financing Structure | Chinese-funded infrastructure packages lock in Nuctech supply across East African rail and port linkages. |
| Software-Defined Detection Investment | Algorithm updates extend hardware refresh cycles and expand recurring revenue attachment rates. |
| Dual-Energy System Upgrade | Addresses dense cargo penetration limits at Durban and Jebel Ali port container terminals. |
Research Methodology
Coverage spans Gulf Cooperation Council states, South Africa, Nigeria, and Kenya, with primary inputs from each customs authority and port operator category. The approach combines structured interviews with customs procurement directors, terminal operations managers, and hazardous materials transport regulators with secondary validation from ISPS Code implementation filings, national customs control act regulatory texts, and East African Community protocol harmonization documents. Bottom-up equipment deployment tallies triangulate against top-down infrastructure budget allocations.
Rate-of-change decomposition separates volume growth from unit value evolution across the projection horizon. Segmentation dimensions include technology type, application endpoint, end-user category, and solution architecture, with corridor-specific financing structure modeled as an additional procurement behavior dimension. CAGRs derive from equipment refresh cycle analysis and regulatory deadline clustering. Forecast inputs incorporate SFDA hazardous materials coordination timelines and MOHAP radiation detection threshold revision schedules.
The model assumes a particular technology adoption path; alternative pathways for multi-energy imaging architectures would alter the outlook. Forecasts reflect assumptions regarding customs code harmonization velocity and infrastructure financing availability. A model refresh is warranted upon material change in Chinese-funded corridor commitment levels or GCC aviation security mandate acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Explosive Detection Kit Market
Security and Surveillance
Global Security Assurance Market
Security and Surveillance
Speed Limit Radar Signs Market
Security and Surveillance
Security System Integrators Market
Security and Surveillance
Global Cargo Inspection Market
Security and Surveillance
Asia-Pacific Security Screening Market
Security and Surveillance
Consumer Security Market
Security and Surveillance
Air Cargo Security and Screening Systems Market
Security and Surveillance
Alarm Monitoring [Central Stations] Software Market
Security and Surveillance
Face Smart Lockers Market
Security and Surveillance
APAC Security Testing Market
Security and Surveillance
Middle East Manned Security Services Market
Security and Surveillance
Residential Security Market
Security and Surveillance
Crowdsourced Security Market
Security and Surveillance
Security Holograms Market
Security and Surveillance
Shock Sensor Market