
 North America Urban Security Screening Market | 2026-2036
North America Urban Security Screening Market Size, Share, and Industry Trends Forecast 2026-2036
North America Urban Security Screening Market Analytics
Municipal procurement channels is tilting toward multi-technology platform contracts that bundle hardware, software, and long-term service agreements. Smiths Detection leverages its established airport footprint to extend into urban transit verticals across Canadian provinces and U.S. states. Evolv Technologies differentiates through AI-enabled weapons detection systems that operate without requiring passengers to remove personal items. Rapiscan Systems anchors the high-throughput X-ray segment with systems deployed at major sports venues and federal courthouses.
Urban security screening encompasses the deployment of sensor networks, imaging systems, and analytical software designed to detect concealed threats within densely populated metropolitan environments. Millimeter-wave imaging sensors operate at frequencies between 70 GHz and 300 GHz, penetrating clothing to identify anomalies while emitting non-ionizing radiation levels below FCC exposure thresholds. AI Analytics represents the fastest-expanding technology segment as transit operators demand real-time threat classification with minimal false-positive rates. Stadium deployments constitute the most mature end-user category, whereas public transport installations in older infrastructure present the steepest integration challenges and corresponding margin pools for specialized service providers.
TSA, DHS, and Transport Canada collectively establish certification requirements that dictate product eligibility for federal funding streams and cross-border interoperability standards. FCC equipment authorization processes constrain radio-frequency sensor deployment timelines, while OSHA workplace safety rules influence maintenance staffing models for screening checkpoints. Stakeholders must monitor evolving AI governance frameworks at the state and provincial level, as algorithmic bias regulations will reshape vendor qualification criteria and system validation protocols.
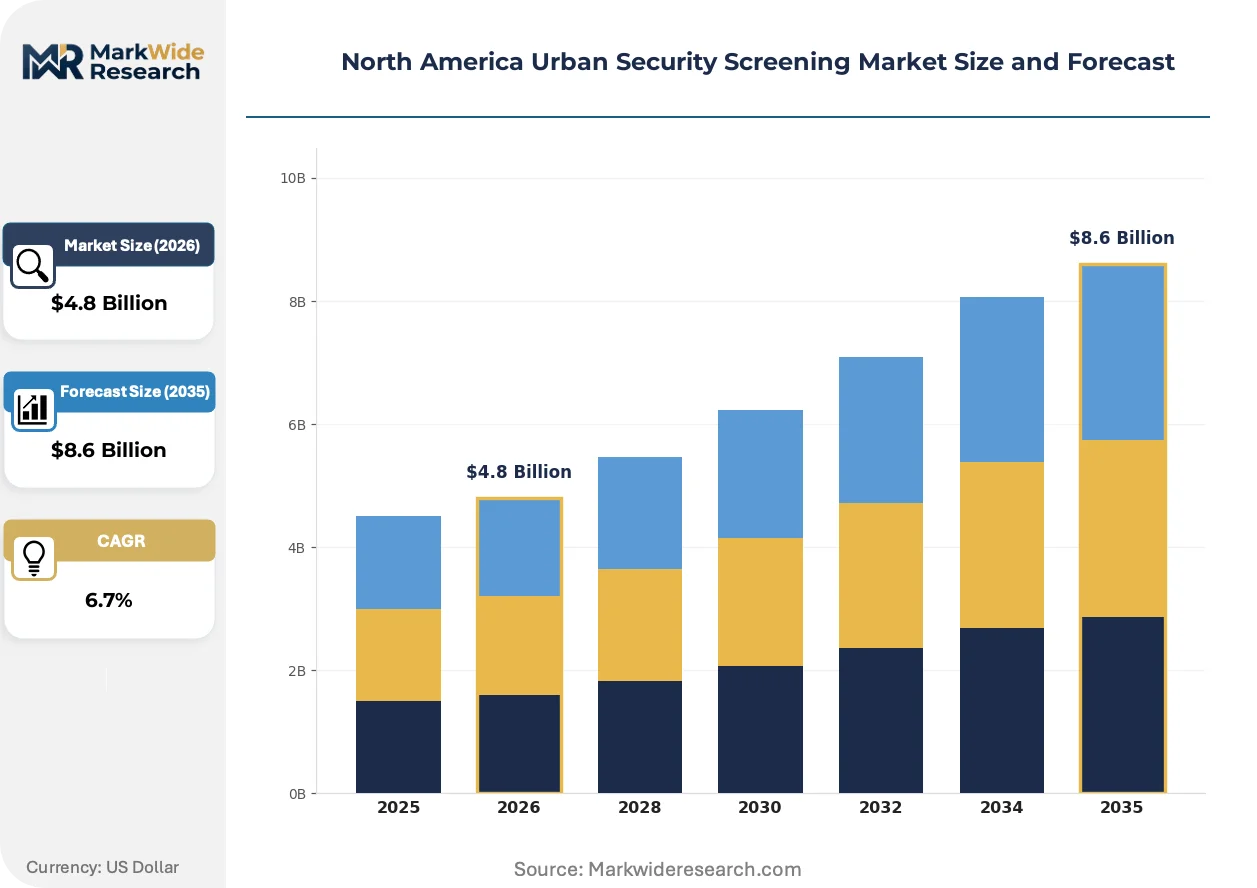
Market Dynamics
Transit agencies across the United States and Canada are consolidating vendor relationships around integrated screening platforms that combine hardware, software, and predictive maintenance under unified procurement frameworks. This structural shift compresses equipment refresh timelines while elevating service contract values.
Growth Catalysts
- TSA Screening Partnership Program:Federal cost-sharing mechanisms accelerate municipal adoption of certified screening systems at subway and commuter rail facilities across U.S. states.
- Millimeter-wave sensor maturation:Non-ionizing imaging technology operating between 70 GHz and 300 GHz enables high-throughput passenger screening without health exposure concerns.
- New York MTA deployment scale:The Metropolitan Transportation Authority's platform expansion creates reference architecture for other North American transit operators.
Market Restraints
- FCC equipment authorization timelines:Radio-frequency sensor deployments face 12-18 month certification queues that delay revenue recognition for hardware vendors.
- Legacy infrastructure integration costs:Pre-1970s subway stations in Boston, Philadelphia, and Chicago require structural modifications exceeding equipment purchase prices.
- Copper and rare earth input volatility:Millimeter-wave antenna arrays depend on gallium arsenide substrates subject to supply concentration from single-source refiners.
Strategic Opportunities
- Canadian provincial transit expansion:Toronto Transit Commission and Vancouver's TransLink are greenfield screening deployments without legacy system retrofit burdens.
- AI-enabled threat classification:Machine learning inference at the edge reduces false-positive rates below human operator baselines, opening stadium and entertainment venue segments.
- Outcome-based service contracting:Municipal buyers are migrating from capital purchase to uptime-guaranteed subscriptions that bundle hardware refresh cycles.
Industry Challenges
- Algorithmic bias validation:State-level AI governance frameworks in California, Illinois, and New York require documented demographic parity testing for facial recognition components.
- Cross-jurisdictional certification fragmentation:DHS, TSA, and Transport Canada maintain non-harmonized testing protocols that multiply compliance engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Urban Security Screening Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Crowd Management, Threat Detection, Access Control, Surveillance Technology: X-ray, Metal Detection, Imaging Sensors, AI Analytics End User: Public Transport, Airports, Government Facilities, Stadiums Service Type: Integration, Maintenance, Consulting, Training |
| Companies Covered | IDEMIA, Evolv Technologies, Rapiscan Systems, Thruvision Group, Liberty Defense Technologies, Smiths Detection, OSI Systems, Inc., Patriot One Technologies, Leidos Security Detection & Automation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Urban Security Screening Market Evolving Landscape
Sensor fusion architectures are displacing single-modality screening systems across North American transit and venue security deployments. Vendors are integrating passive millimeter-wave, active radar, and magnetic anomaly detection into unified threat detection platforms.
Passive millimeter-wave imaging arrays now operate at standoff distances exceeding fifteen feet, enabling screening without passenger throughput bottlenecks. Transit operators in Atlanta, Dallas, and Toronto are piloting these configurations at station mezzanines. The technology is virtualizing the physical checkpoint, allowing threat detection to occur before passengers reach fare gates.
DHS certification standards for urban mass transit are tightening electromagnetic compatibility requirements for co-located communications equipment. Equipment vendors must demonstrate non-interference with 5G small cell deployments and public safety radio systems. Canadian transit authorities are adopting these standards through bilateral interoperability agreements, creating unified North American testing protocols.
Municipal procurement teams are consolidating screening equipment purchases into multi-year platform agreements that embed software update subscriptions. This displaces traditional capital-bid procurement where hardware and service contracts were separately awarded. The shift is most visible in California and Texas, where state procurement frameworks now preference total-cost-of-ownership evaluation criteria over upfront capital minimization.
North America Urban Security Screening Market Segmentation
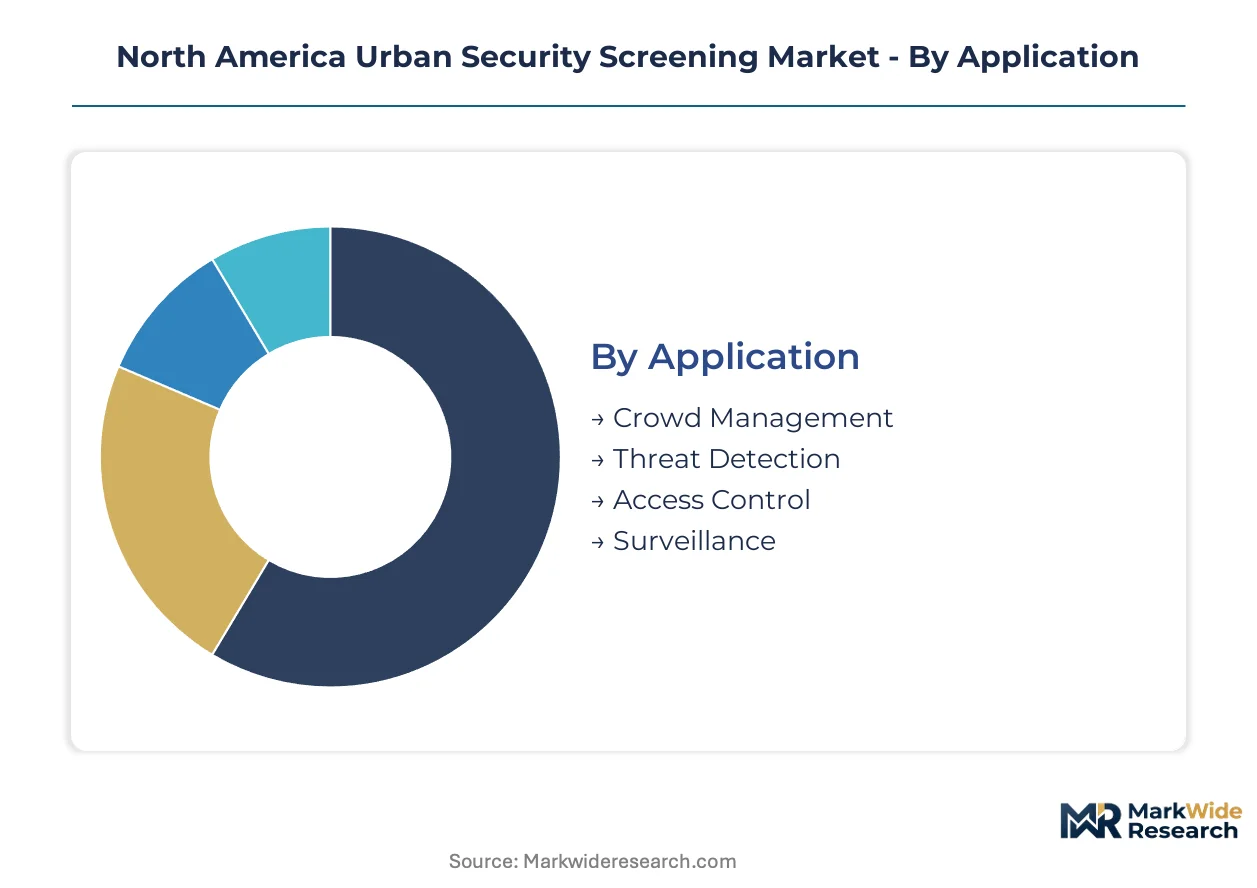
Urban security screening deployments vary sharply by threat environment, passenger throughput requirements, and infrastructure age. Segmentation reveals where procurement budgets concentrate and which technology combinations command premium pricing.
Application:
Mature crowd management systems dominate current installations while emerging AI-driven applications reshape competitive positioning.
- Threat Detection:Sensor fusion architectures combine millimeter-wave imaging with magnetic anomaly detection to identify concealed weapons and explosives. New York MTA and Toronto Transit Commission prioritize these systems for subway platform deployment due to high passenger density.
- Crowd Management:Video analytics platforms process real-time passenger flow data to predict bottlenecks before they form. Stadium operators in Atlanta, Dallas, and Los Angeles drive demand for integration with existing CCTV infrastructure.
- Access Control:Biometric credentialing systems gate entry to restricted zones at federal courthouses and government facilities.
- Surveillance:Passive monitoring networks support post-incident forensic analysis without active passenger screening.
Threat Detection handles the majority of throughput; AI Analytics is the fastest mover on share.
Technology:
Cost tiers separate legacy metal detection from premium imaging platforms with software subscriptions.
- AI Analytics:Machine learning inference engines classify threats at the edge, reducing false-positive rates below human operator baselines. Transit agencies in California and Texas mandate these capabilities for new procurements.
- Imaging Sensors:Millimeter-wave arrays operating between 70 GHz and 300 GHz penetrate clothing without ionizing radiation. FCC authorization timelines of 12-18 months constrain deployment velocity for vendors.
- X-ray:High-throughput baggage and parcel inspection systems anchor federal courthouse and sports venue security.
- Metal Detection:Walk-through and handheld units serve as baseline screening at cost-constrained municipal facilities.
Imaging Sensors commands the highest unit economics; AI Analytics is expanding most quickly as municipalities bundle software subscriptions.
End User:
Volume concentration varies by infrastructure age and federal funding eligibility.
- Public Transport:Subway and commuter rail operators across the United States and Canada represent the largest addressable market. TSA Screening Partnership Program cost-sharing accelerates procurement at facilities serving more than 10,000 daily passengers.
- Stadiums:Entertainment venues operate the most mature screening deployments with established refresh cycles. NFL and NBA facilities drive demand for high-throughput configurations that minimize entry delays.
- Government Facilities:Federal courthouses and administrative buildings require DHS-certified systems with documented electromagnetic compatibility.
- Airports:Terminal-adjacent transit connections and employee screening points extend vendor relationships from aviation into urban verticals.
Public Transport captures the steepest expansion trajectory; Stadiums maintains the most predictable replacement demand.
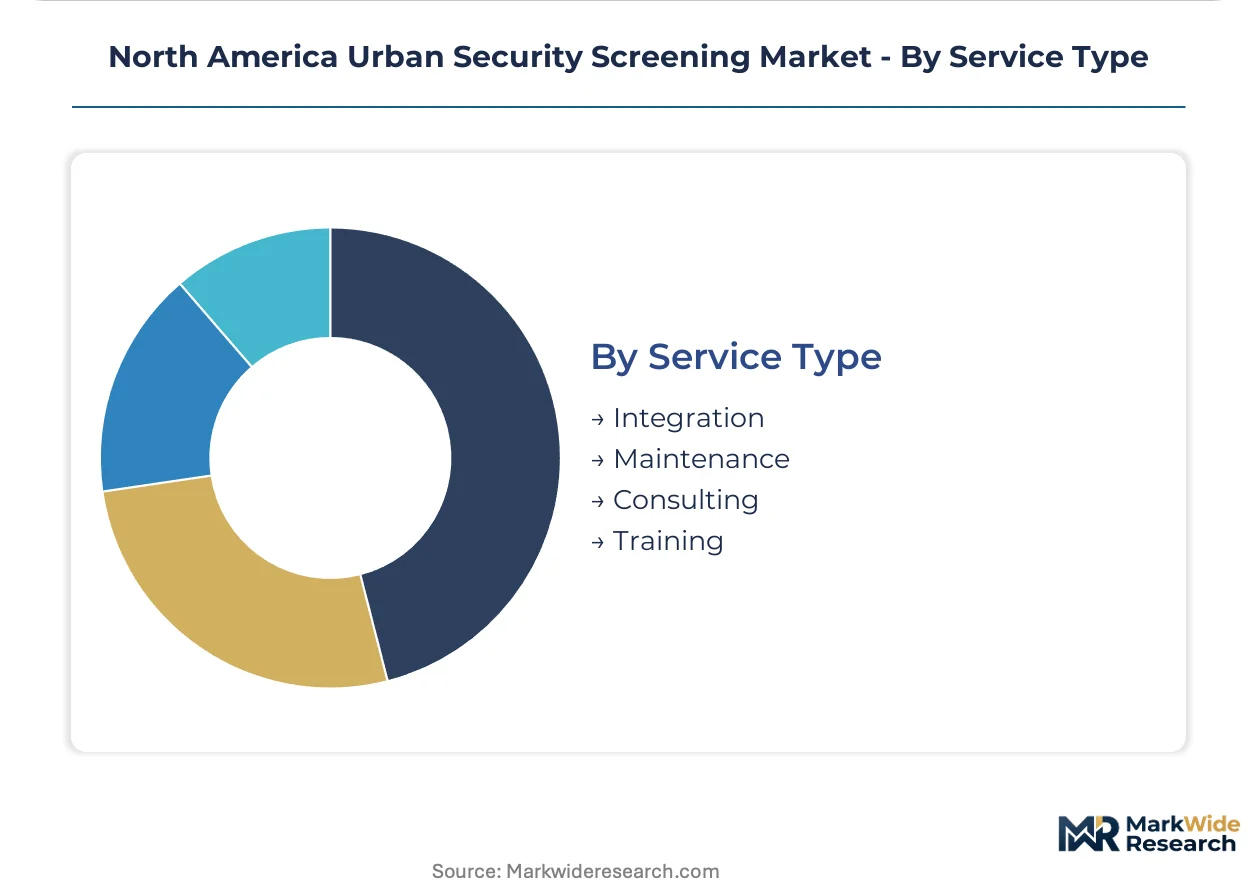
Service Type:
Customer type determines whether buyers favor capital purchase or outcome-based contracting.
- Integration:Structural modifications for pre-1970s subway stations in Boston, Philadelphia, and Chicago often exceed equipment costs. Specialized contractors capture margin pools from legacy infrastructure retrofit complexity.
- Maintenance:Uptime-guaranteed service contracts displace break-fix arrangements as municipalities migrate to total-cost-of-ownership evaluation frameworks.
- Consulting:Threat assessment and system design services support greenfield deployments at Canadian provincial transit authorities.
- Training:Operator certification programs ensure compliance with evolving DHS and Transport Canada standards.
Integration generates the largest project values; Maintenance subscriptions are climbing the fastest as procurement patterns shift toward platform contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal cost-sharing through TSA's Screening Partnership Program accelerates municipal procurement across the United States and Canada. Provincial transit authorities in Canada are adopting DHS electromagnetic compatibility standards through bilateral interoperability agreements. Mexico City Metro is evaluating screening architectures for its busiest transfer stations.
United States
The Metropolitan Transportation Authority operates the continent's largest urban security deployment across New York City subway and commuter rail platforms. TSA certification requirements dictate product eligibility for federal funding streams at facilities serving over 10,000 daily passengers. Transit operators in Atlanta, Dallas, and Boston are piloting standoff millimeter-wave configurations at station mezzanines.
Canada
Toronto Transit Commission and Vancouver's TransLink are executing greenfield screening deployments without legacy infrastructure retrofit burdens. Transport Canada maintains certification protocols that align with evolving DHS standards through bilateral agreements. Provincial procurement teams in Ontario and British Columbia preference total-cost-of-ownership evaluation criteria over upfront capital minimization.
Mexico
Mexico City Metro is assessing threat detection architectures for high-density transfer corridors serving millions of daily passengers. The country's national transit regulator is evaluating interoperability standards compatible with U.S. and Canadian certification frameworks. Security equipment distributors in the capital region are establishing service capabilities for predictive maintenance contracts.
North America Urban Security Screening Market Competitive Landscape
On the supply side, the industry is consolidating around integrated platform providers that bundle hardware, software, and long-term service agreements. Established airport security vendors leverage aviation certification relationships to extend into urban transit verticals. Three strategic archetypes dominate: legacy imaging system manufacturers, AI-native threat detection specialists, and diversified defense contractors with security divisions. Competitive intensity centers on multi-year municipal procurement wins and outcome-based service contracting models that displace traditional capital-bid arrangements.
Within the AI-native tier, Evolv Technologies exemplifies vendors differentiating through weapons detection systems that operate without requiring passengers to remove personal items. Among legacy imaging specialists, Smiths Detection and Rapiscan Systems occupy positions anchored by established airport footprints and DHS certification portfolios. These three companies represent the competitive fault lines between software-centric and hardware-centric approaches to urban security deployment.
| Leading Market Players |
|---|
| IDEMIA |
| Evolv Technologies |
| Rapiscan Systems |
| Thruvision Group |
| Liberty Defense Technologies |
| Smiths Detection |
| OSI Systems, Inc. |
| Patriot One Technologies |
| Leidos Security Detection & Automation |
| Others |
Value Network & Pricing Analysis
The I-95 corridor freight network linking Baltimore's electronics distribution hubs to New York MTA deployment sites shapes cost dynamics across the North America urban security screening market. Concentrated millimeter-wave sensor manufacturing in Massachusetts and Ontario creates regional pricing power, while cross-border logistics costs differentiate landed equipment prices between U.S. transit agencies and Canadian provincial buyers.
Pricing Analysis
Certification level (DHS/TSA/Transport Canada-grade) creates the primary spread between equipment tiers. Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with premium tiers bundling predictive maintenance subscriptions. Cost compression in standard-tier metal detection systems is intensifying because of Chinese component imports. Municipal transit agencies exhibit highest price sensitivity; federal courthouse security directors prioritize certification compliance over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for municipal procurement, with supply-chain finance facilities bridging vendor cash flow gaps. Gallium arsenide substrate production concentrates in the United States, Germany, and Japan. Millimeter-wave antenna arrays draw from rare earth processing facilities in China and Malaysia. Single-source vulnerability in gallium refining creates structural risk. Distribution runs through authorized security equipment dealers with DHS certification credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America urban security screening market represents early-cycle expansion, with TSA Screening Partnership Program cost-sharing driving penetration below 15% across eligible U.S. transit facilities.
For Market Incumbents: Harden certification portfolios against emerging AI-native entrants by accelerating Transport Canada reciprocity filings. Secure captive supply of gallium arsenide substrates through backward integration into semiconductor foundry partnerships. Channel control through exclusive dealer networks in California and Texas defends margin position against platform-agnostic competitors. For New Entrants and Emerging Players: Build out greenfield service capabilities targeting Toronto Transit Commission and Vancouver TransLink expansions. Canadian provincial transit authorities offer the most penetrable geography due to absence of legacy retrofit burdens. Go-to-market through outcome-based uptime subscriptions rather than capital-bid competition. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified defense contractors with underutilized urban security divisions. Five-to-ten year viability hinges on AI analytics software recurring revenue ratios exceeding hardware dependency. Watch DHS electromagnetic compatibility standard tightening as inflection indicator for vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Sensor fusion architectures combining millimeter-wave with magnetic anomaly detection address New York MTA throughput requirements. |
| Certification Investment | DHS electromagnetic compatibility testing accelerates federal funding eligibility for subway platform deployments. |
| Geographic Expansion | Toronto and Vancouver greenfield installations bypass legacy infrastructure retrofit costs plaguing Boston and Chicago. |
| Strategic Partnership | 5G small cell co-location agreements with transit authorities secure exclusive screening checkpoint placement rights. |
| Acquisition of Specialist Firm | AI analytics boutiques with edge inference capabilities fill capability gaps in legacy imaging system portfolios. |
Research Methodology
A spread of perspectives from transit agency procurement directors, DHS certification engineers, municipal budget officers, and security systems integrators converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through TSA procurement databases, Transport Canada equipment authorization records, FCC electromagnetic compatibility filings, and municipal bond disclosure documents. Bottom-up equipment shipment tracking and top-down transit agency capital budget analysis were triangulated against vendor revenue segment disclosures.
Demand-supply balance across the analysis window anchored the quantitative framework. Segmentation dimensions modeled include application type, technology tier, end-user category, and service contract structure. CAGRs were derived from equipment refresh cycle analysis and federal funding authorization trajectories. Millimeter-wave sensor maturation curves and AI false-positive rate improvement trajectories informed adoption elasticity assumptions.
Stress conditions across FCC authorization delays, gallium arsenide supply disruptions, and municipal budget freeze scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about TSA program continuity and bilateral U.S.-Canada certification harmonization. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
North America People Screening Market
Security and Surveillance
Electronic Alarms Market
Security and Surveillance
Narcotics Scanner Market
Security and Surveillance
Integrated Security Solutions Market
Security and Surveillance
Global Wireless Doorbells Market
Security and Surveillance
Europe Anti-Piracy Protection Market
Security and Surveillance
Explosive Trace Detection Market
Security and Surveillance
Russian Intelligent Eavesdropping Detection System Market
Security and Surveillance
Middle East and Africa Cargo Inspection Market
Security and Surveillance
Airport Baggage Screening Systems Market
Security and Surveillance
Europe Border Security Market
Security and Surveillance
Middle East Manned Security Services Market
Security and Surveillance
Prescriptive Security Market
Security and Surveillance
Signal Jammer Market
Security and Surveillance
Surveillance Radars Market
Security and Surveillance
Europe Security Testing Market