
 Smart Security Market | 2026-2036
Smart Security Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Security Market Analytics
UL 2900-1 cybersecurity certification for network-connectable products is bifurcating the competitive landscape into qualified and non-qualified suppliers. Honeywell International, Inc. leverages its building automation heritage to anchor enterprise-grade integrated security portfolios. Hangzhou Hikvision Digital Technology Co., Ltd. dominates camera hardware manufacturing scale while navigating geopolitical procurement restrictions in Western markets. Robert Bosch GmbH differentiates through German-engineered reliability standards and vertical integration into sensor fabrication.
Smart security encompasses electronically networked systems for intrusion detection, access management, and situational awareness, typically integrating IP cameras with edge-computing analytics processors operating at 30 frames per second minimum for real-time facial recognition. These systems serve commercial facilities, critical infrastructure, and residential properties by converting raw video feeds into actionable alert streams and automated lockdown triggers. Surveillance cameras occupy the largest product category by installed base, though smart locks are expanding fastest among residential retrofit buyers seeking smartphone-controlled entry. Cloud-based technology architectures now capture the highest-margin recurring revenue pools through subscription monitoring, while IoT-enabled platforms face margin pressure from interoperability standardization demands. The residential end-user segment shows the steepest adoption curve among single-family homeowners, whereas government buyers concentrate procurement around hardened, air-gapped systems with sovereign data requirements.
FCC equipment authorization rules in the United States govern radio-frequency emissions for wireless security devices, while the EU AI Act imposes conformity assessments on biometric identification systems deployed in public spaces. China's GB standards and MIIT network access licenses create a dual compliance burden for foreign manufacturers seeking domestic procurement contracts. Stakeholders must monitor diverging cybersecurity certification timelines across jurisdictions, as asynchronous regulatory rollout threatens product harmonization strategies and inventory allocation decisions.
Market Dynamics
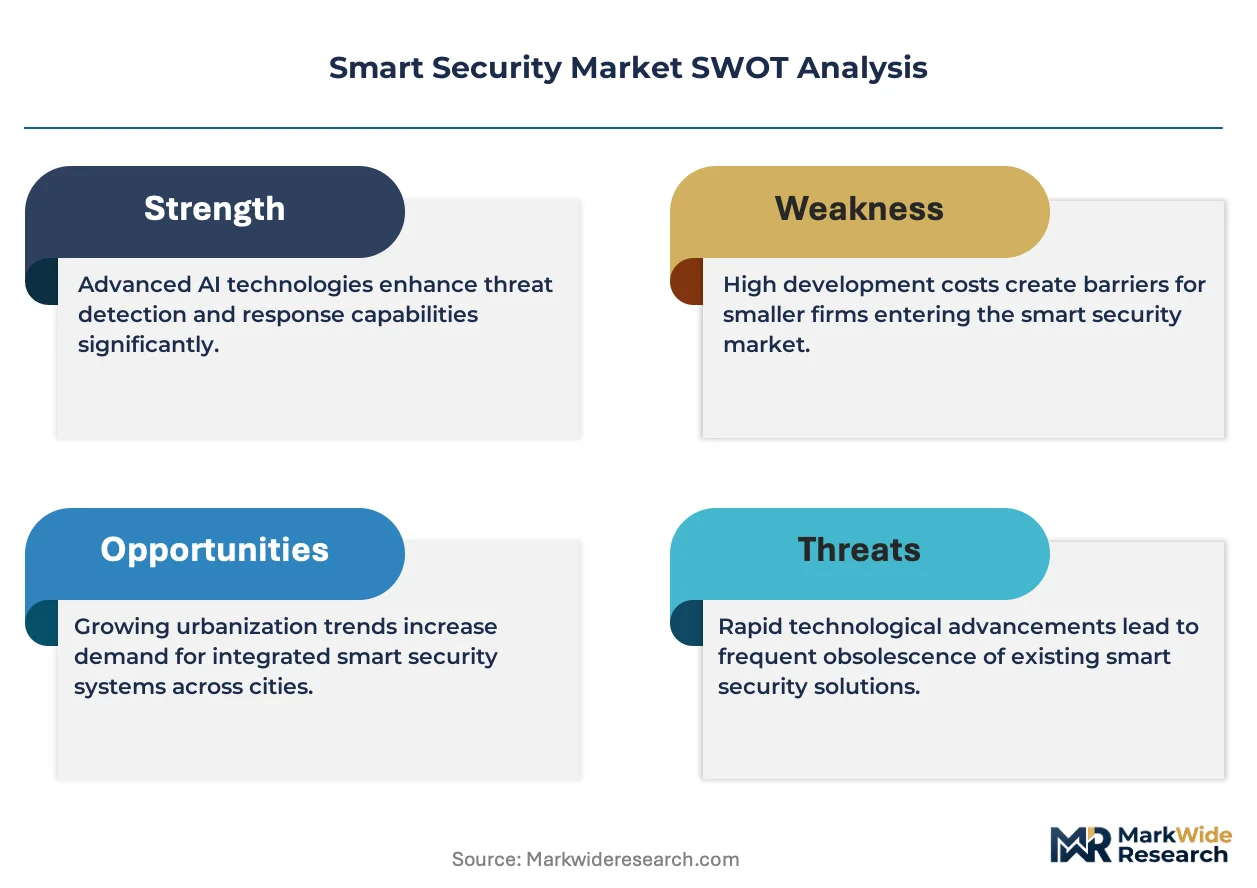
Cloud-native security architectures are compressing hardware refresh cycles while UL 2900-1 certification requirements fragment vendor qualification tiers across North American and European procurement channels.
Growth Catalysts
- EU AI Act conformity assessments:Biometric identification systems deployed in public spaces now require mandatory third-party auditing, creating certified product premiums for compliant manufacturers.
- Edge-computing analytics processors:Real-time facial recognition at 30 frames per second minimum is displacing centralized server architectures in stadiums, airports, and critical infrastructure facilities.
- China's MIIT network access licenses:Domestic procurement mandates for sovereign data handling are accelerating local production partnerships for foreign camera hardware suppliers.
Market Restraints
- CMOS sensor supply concentration:Taiwan and South Korean foundries control advanced image sensor fabrication, exposing camera manufacturers to geopolitical disruption risk.
- GDPR biometric data processing restrictions:EU member states impose divergent interpretations of lawful basis requirements, complicating cross-border deployment of facial recognition systems.
- LiDAR perimeter alternatives:Industrial facilities in mining and energy verticals are substituting video analytics with laser-based intrusion detection for extreme weather reliability.
Strategic Opportunities
- India's Smart Cities Mission:Municipal surveillance tenders specify interoperable IP camera networks with centralized command centers, opening volume deployment pathways for cloud-integrated platforms.
- Subscription monitoring services:Residential retrofit buyers are shifting from hardware-only purchases to recurring revenue models bundling professional monitoring with smartphone-controlled smart locks.
- 5G private network slicing:Manufacturing campuses in Germany are deploying dedicated wireless security networks with guaranteed latency for automated lockdown trigger systems.
Industry Challenges
- FCC equipment authorization timelines:Radio-frequency emissions testing for wireless security devices faces backlog delays, compressing product launch windows for battery-powered sensors.
- ONVIF Profile interoperability gaps:Camera-to-VMS integration requires custom middleware development, inflating deployment costs for multi-vendor enterprise installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Security Market |
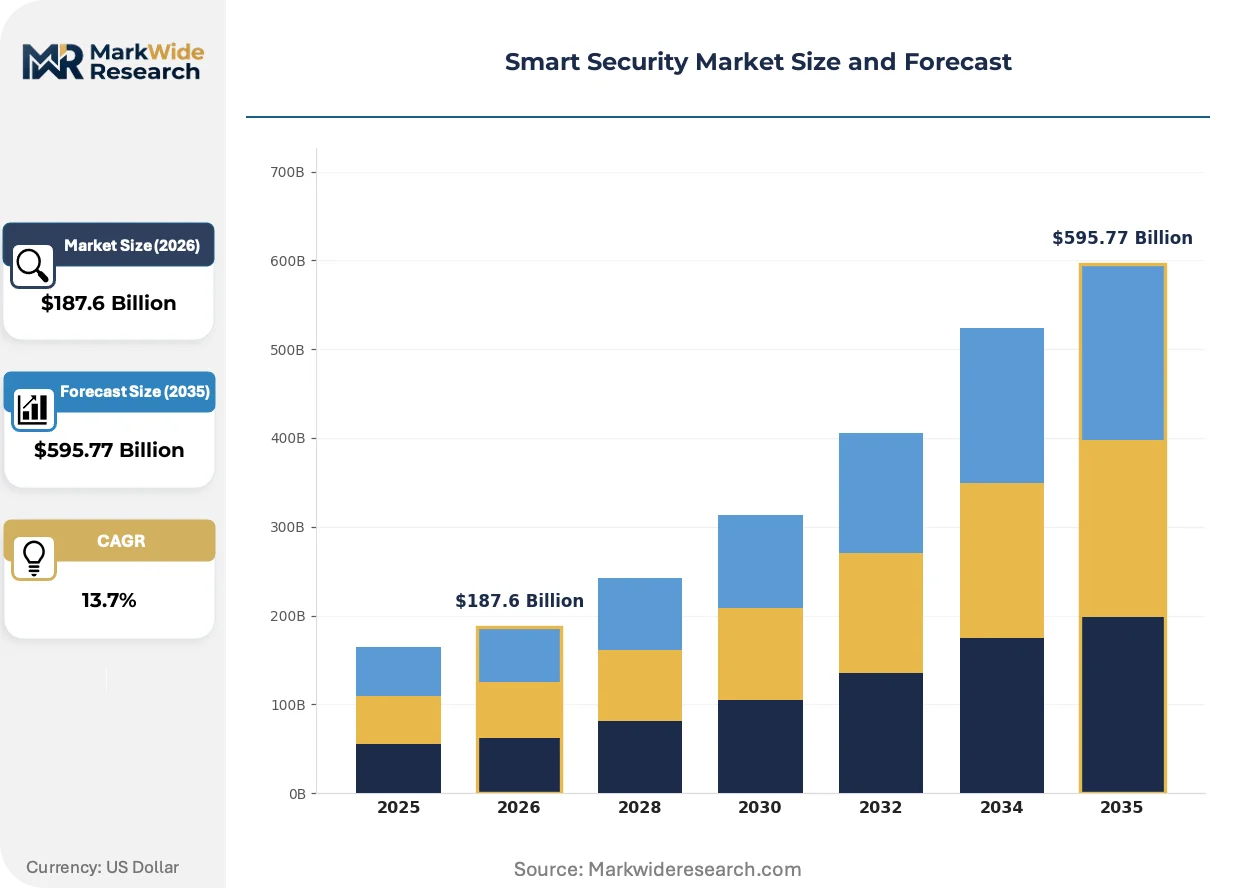
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $595.77 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surveillance Cameras, Alarm Systems, Access Control Systems, Smart Locks Technology: Wireless, Wired, Cloud-Based, IoT-Enabled End User: Residential, Commercial, Industrial, Government Installation Type: Professional, DIY, Managed Services, Hybrid |
| Companies Covered | Honeywell International, Inc., Hangzhou Hikvision Digital Technology Co., Ltd., ADT, Inc., Johnson Controls International PLC, Samsung Electronics Co., Ltd., Robert Bosch GmbH, Alarm.com Holdings, Inc., Amazon.com, Inc., Netgear, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Security Market Evolving Landscape
Edge AI inference engines are redistributing computational load from centralized servers to camera hardware, collapsing bandwidth requirements while enabling sub-100-millisecond alert generation for physical security applications.
Multispectral image sensors is miniaturizing thermal-visible fusion capabilities into standard dome camera form factors. Critical infrastructure operators in oil refineries and power substations are deploying these units for 24-hour perimeter monitoring without supplemental lighting infrastructure. The technology is compressing total cost of ownership for all-weather surveillance by eliminating separate thermal camera installations.
REACH restrictions on persistent organic pollutants are forcing solder material transitions in PCB assemblies for security devices sold across European Union member states. Manufacturers with German-engineered supply chains are accelerating tin-silver-copper alloy qualifications to maintain CE marking compliance. Video analytics hardware with legacy leaded components faces inventory obsolescence risk in continental procurement channels.
Facility managers are unbundling professional monitoring contracts from hardware procurement, selecting cloud-native platforms with open API architectures for integration with existing building management systems. This pattern is most visible in United States commercial real estate, where REITs standardize on vendor-agnostic video management software to avoid single-source lock-in across distributed property portfolios.
Smart Security Market Segmentation
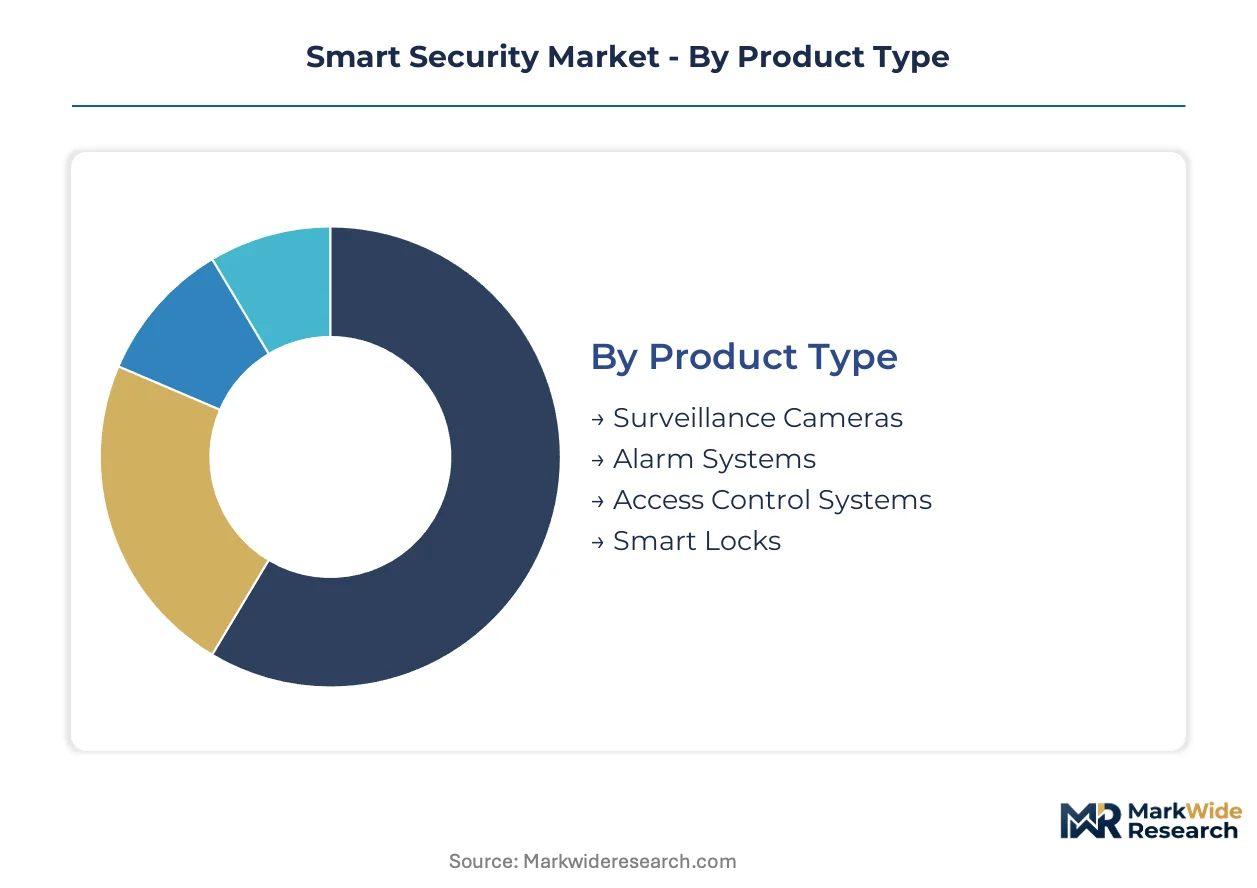
Segmentation in smart security reveals how margin pools concentrate around recurring revenue architectures and compliance-heavy procurement channels. Vendors must align product roadmaps with the diverging cost sensitivities of residential retrofit buyers versus sovereign data requirements in government verticals.
Product Type:
Margin pools concentrate in integrated systems that bundle hardware with multi-year monitoring subscriptions, while standalone device sales face commoditization pressure from Asian manufacturing scale.
- Surveillance Cameras:IP cameras with edge-computing analytics processors operating at 30 frames per second minimum for real-time facial recognition. Demand concentrates in United States commercial real estate and China city-scale smart infrastructure deployments, driven by FCC equipment authorization rules and MIIT network access license mandates respectively.
- Alarm Systems:Electronically networked intrusion detection systems converting sensor triggers into actionable alert streams. Residential retrofit buyers in Germany favor smartphone-integrated panels, constrained by GDPR biometric data processing restrictions on companion video verification features.
- Access Control Systems:Enterprise-grade credential management platforms with UL 2900-1 cybersecurity certification. Critical infrastructure operators in oil refineries and power substations mandate these for automated lockdown trigger capabilities.
- Smart Locks:Smartphone-controlled entry devices expanding fastest among single-family homeowners. The steepest adoption curve appears in United States residential retrofit channels seeking subscription monitoring bundles.
The dominant share belongs to Surveillance Cameras, while Smart Locks are closing the gap fastest.
Technology:
Cost tier stratification separates premium cloud-native architectures from hardware-centric legacy deployments, with interoperability standardization demands compressing margins in the middle.
- Wireless:Radio-frequency emission devices governed by FCC equipment authorization rules in the United States. Battery-powered sensor launches face backlog delays from testing queue congestion, compressing product windows for North American market entry.
- Wired:Ethernet-powered installations with guaranteed bandwidth for high-resolution video transmission. Industrial facilities in Germany's manufacturing campuses favor these for 5G private network slicing integration with automated lockdown systems.
- Cloud-Based:Native architectures capturing the highest-margin recurring revenue pools through subscription monitoring. United States REITs standardize on these platforms with open API architectures to avoid single-source lock-in across distributed property portfolios.
- IoT-Enabled:Interoperable platforms facing margin pressure from ONVIF Profile standardization gaps requiring custom middleware development. Multi-vendor enterprise installations in India's Smart Cities Mission absorb these inflated deployment costs for centralized command center integration.
Cloud-Based technology commands the premium tier, with IoT-Enabled platforms gaining share fastest as municipal interoperability mandates proliferate.
End User:
Application-driven purchasing patterns separate sovereign data requirements from cost-optimized consumer channels, with compliance burden intensity determining vendor qualification tiers.
- Residential:Single-family homeowners and multi-tenant property managers seeking smartphone-controlled entry and professional monitoring alternatives. United States buyers are unbundling hardware procurement from service contracts, selecting vendor-agnostic platforms.
- Commercial:REITs and facility managers deploying city-scale smart infrastructure with cybersecurity hardening mandates. China's commercial real estate operators accelerate adoption of cloud-connected surveillance and access platforms under domestic data localization rules.
- Industrial:Mining and energy verticals substituting video analytics with LiDAR alternatives for extreme weather reliability. These facilities prioritize 24-hour perimeter monitoring without supplemental lighting infrastructure through multispectral image sensors.
- Government:Procurement concentrated around hardened, air-gapped systems with sovereign data requirements. EU AI Act conformity assessments for biometric identification in public spaces create certified product premiums for compliant manufacturers serving this channel.
Commercial applications anchor volume deployment, while Government verticals deliver the steepest margin expansion for qualified suppliers.
Installation Type:
Customer type stratification reflects diverging technical sophistication and total cost of ownership calculations across do-it-yourself and enterprise-managed channels.
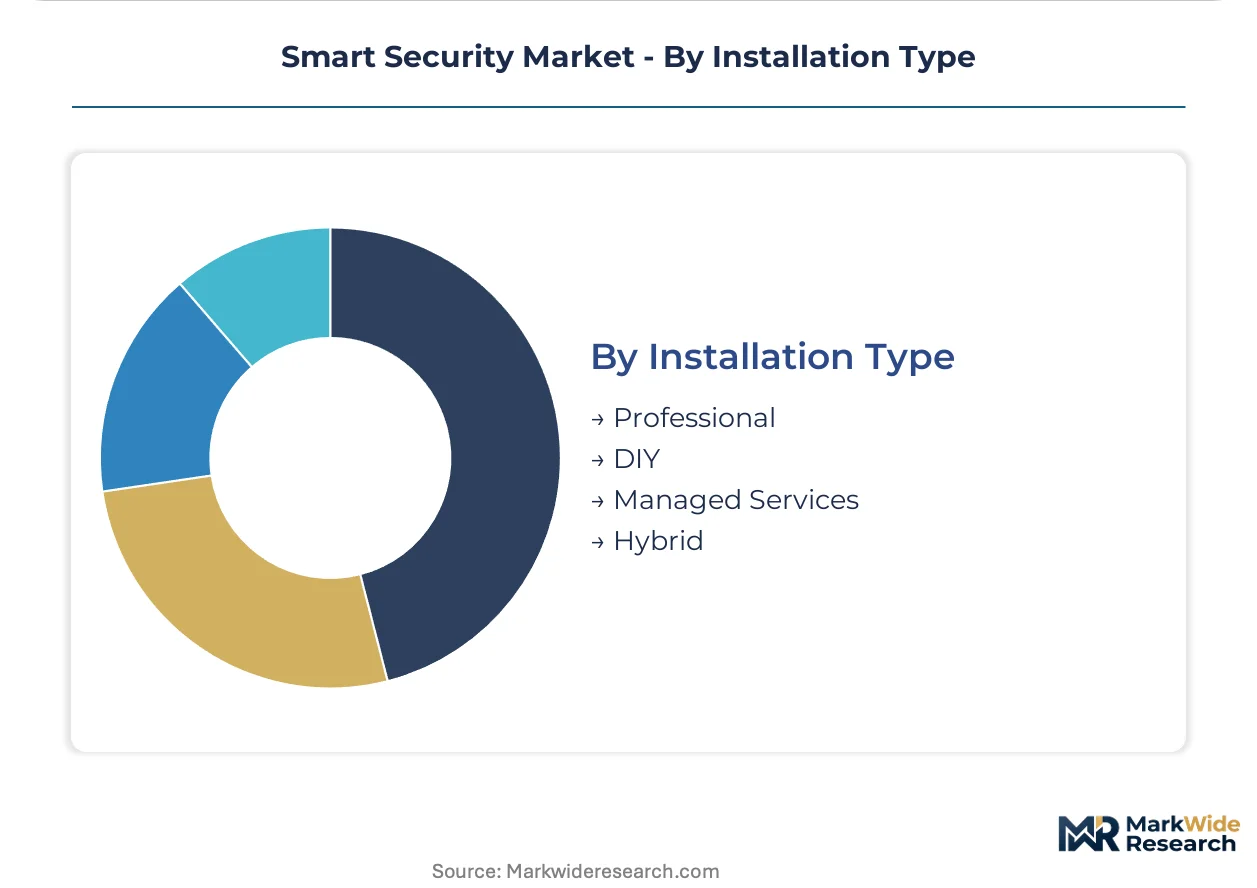
- Professional:Certified installer networks required for UL 2900-1 qualified systems in North American and European procurement channels. Fragmentation across vendor qualification tiers creates bifurcation between premium and standard service providers.
- DIY:Consumer self-installation expanding fastest among residential retrofit buyers seeking smartphone-controlled entry. These users accept limited integration depth in exchange for lower upfront capital outlay.
- Managed Services:Third-party monitoring and maintenance contracts bundling hardware with recurring revenue. Germany's manufacturing campuses deploy these for dedicated wireless security networks with guaranteed latency.
- Hybrid:Professional installation with consumer-managed software configuration, common in multi-tenant residential properties. India's municipal surveillance tenders specify these for interoperable IP camera networks with centralized oversight.
Professional installation retains the dominant share, though Managed Services are climbing the fastest as subscription models displace hardware-only purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer concentration clusters around sovereign procurement offices, commercial real estate investment trusts, and industrial facility operators with divergent compliance burdens. Government verticals in Germany and China mandate air-gapped architectures and domestic data localization respectively. Residential retrofit channels in the United States and India prioritize smartphone integration over hardened cybersecurity.
United States
Commercial real estate operators and critical infrastructure facilities drive demand for cloud-connected surveillance platforms. FCC equipment authorization rules govern radio-frequency emissions for wireless security devices, with testing backlogs compressing product launch windows. The New York Metro and Texas Triangle clusters concentrate REIT procurement activity around vendor-agnostic video management software.
Germany
Manufacturing campuses and municipal operators anchor demand for 5G private network slicing with guaranteed latency for automated lockdown systems. EU AI Act conformity assessments impose mandatory third-party auditing on biometric identification systems deployed in public spaces. The Bavaria and North Rhine-Westphalia industrial corridors lead deployment of dedicated wireless security networks.
China
City-scale smart infrastructure deployments and domestic procurement mandates accelerate adoption of sovereign data handling systems. MIIT network access licenses and GB standards create dual compliance burdens for foreign manufacturers seeking government contracts. The Yangtze River Delta and Pearl River Delta clusters concentrate local production partnerships for camera hardware suppliers.
India
Municipal surveillance tenders under the Smart Cities Mission specify interoperable IP camera networks with centralized command centers. BIS certification requirements and DGFT procurement guidelines shape product qualification pathways for foreign vendors. The Maharashtra and Karnataka urban corridors drive volume deployment of cloud-integrated security platforms.
United Kingdom
Critical infrastructure operators and commercial facility managers prioritize GDPR-compliant biometric data processing with divergent member state interpretations. The Information Commissioner's Office enforces lawful basis requirements for facial recognition systems in public spaces. The London-Southeast corridor concentrates enterprise-grade access control procurement around UL 2900-1 qualified systems.
Smart Security Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with building automation heritage and specialized camera hardware manufacturers with scale-driven cost positions. Market structure exhibits tiered qualification fragmentation, with UL 2900-1 cybersecurity certification bifurcating vendors into premium and standard service categories. Strategic archetypes include integrated building technology providers, pure-play surveillance hardware specialists, and cloud-native platform operators. Dominant competitive moves center on backward integration into sensor fabrication and geographic localization partnerships to satisfy sovereign data requirements.
Within the diversified conglomerate tier, Honeywell International, Inc. and Johnson Controls International PLC exemplify building automation heritage leveraged for enterprise-grade security portfolios. Among camera hardware specialists, Hangzhou Hikvision Digital Technology Co., Ltd. occupies a scale-driven position while navigating Western procurement restrictions. Robert Bosch GmbH represents German-engineered reliability standards with in-house production of sensor components. These three anchors illustrate how vendor qualification tiers fragment across North American and European procurement channels.
| Leading Market Players |
|---|
| Honeywell International, Inc. |
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| ADT, Inc. |
| Johnson Controls International PLC |
| Samsung Electronics Co., Ltd. |
| Robert Bosch GmbH |
| Alarm.com Holdings, Inc. |
| Amazon.com, Inc. |
| Netgear, Inc. |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory buffers for CMOS image sensors now separate qualified from distressed suppliers, compressing margin recovery timelines for camera manufacturers while amplifying pricing power for Taiwan and South Korean foundries with captive wafer supply.
Pricing Analysis
Cost-plus contracts with quarterly silicon wafer indexation dominate enterprise procurement, though residential channels favor subscription bundling. Price differentiation rests on UL 2900-1 certification tier and edge-computing performance bandwidth. Pricing pressure stems from ONVIF interoperability gaps inflating deployment costs for multi-vendor installations. Government buyers show lowest price sensitivity due to sovereign data mandates, while residential retrofit channels absorb steepest cost compression.
Supply Chain Analysis
Strategic stockpiling of advanced image sensors now supersedes just-in-time preferences among tier-one camera manufacturers. Supply concentrates in Taiwan, South Korea, and Japan for CMOS fabrication, with China dominating PCB assembly and enclosure manufacturing. Raw material dependencies span silicon wafers, rare-earth magnet components for pan-tilt motors, and tin-silver-copper solder alloys for EU REACH compliance. Single-source vulnerability in 7nm sensor foundries exposes inventory disruption risk. Distribution runs through certified installer networks in North America and direct OEM relationships in European procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart security is approaching a platform-economics inflection where open API architectures displace proprietary lock-in, rewarding vendors who embed with building management system ecosystems rather than standalone hardware dominance.
For Market Incumbents: Compound cloud-native recurring revenue through backward integration into edge AI processor design, defending against pure-play software entrants. Prioritize MIIT localization partnerships in China to preserve government contract eligibility. Accelerate UL 2900-1 qualification across full product lines before European procurement windows narrow.
For New Entrants and Emerging Players: Lead with vertical-specific analytics bundles for India's Smart Cities Mission tenders, where interoperability mandates create white-space for cloud-integrated platforms. Target Germany's manufacturing campus segment with 5G private network security slicing. Pursue channel partnerships with REIT property management software providers rather than direct hardware competition.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core security divisions with stranded certification investments. Long-term viability favors vendors with captive sensor supply and sovereign data localization capabilities. Watch for FCC equipment authorization backlog resolution as inflection signal for North American market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Processor Backward Integration | Captive supply of facial recognition chipsets reduces dependency on Taiwan foundry allocation queues. |
| MIIT Network Access Localization | Domestic production partnerships in China preserve eligibility for government procurement contracts under data sovereignty rules. |
| UL 2900-1 Certification Expansion | Full portfolio qualification opens premium procurement channels in United States critical infrastructure verticals. |
| Open API Platform Development | Vendor-agnostic integration with Honeywell and Johnson Controls building management systems displaces proprietary lock-in. |
| 5G Private Network Security Slicing | Dedicated wireless latency guarantees for automated lockdown systems penetrate Germany manufacturing campus demand. |
Research Methodology
The analysis maps surveillance camera hardware, access control platforms, alarm systems, and smart lock sub-sectors, each validated through facility managers, security system integrators, and municipal procurement officers. Primary interviews with REIT portfolio directors, critical infrastructure operators, and regulatory compliance consultants combined with secondary validation from FCC equipment authorization databases, EU AI Act conformity assessment registries, and MIIT network access license filings. Bottom-up unit economics triangulated against top-down construction spending and smart city infrastructure budgets.
Consistency checks validated volume and value outputs against hyperscaler security capex disclosures, commercial real estate technology spending surveys, and customs trade data for camera hardware shipments. Segmentation dimensions modeled include product type, technology architecture, end-user vertical, and installation channel across the projection horizon. CAGRs derived from regression analysis of historical adoption curves adjusted for regulatory compliance timeline acceleration and edge-computing cost decline trajectories.
The analysis sits within stated boundaries; outcomes outside sustained cloud infrastructure investment and stable geopolitical trade conditions would require recalibration. Forecasts reflect assumptions regarding interoperability standardization adoption rates and sovereign data localization enforcement intensity. Revision becomes warranted when FCC equipment authorization backlog duration or EU AI Act third-party auditor capacity crosses operational disruption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Global Security Advisory Services Market
Security and Surveillance
Baggage Scanner Market
Security and Surveillance
Global Alarm Monitoring Market
Security and Surveillance
Face Smart Lockers Market
Security and Surveillance
Intelligent Fencing Market
Security and Surveillance
Asia-Pacific Security Services Market
Security and Surveillance
India Perimeter Intrusion Detection and Prevention Market
Security and Surveillance
Middle East and Africa Baggage and Parcel Screening Market
Security and Surveillance
Explosive Detection Technology Market
Security and Surveillance
Security Inspection Market
Security and Surveillance
Global Container Security Market
Security and Surveillance
Global Acoustic Hailing Devices Market
Security and Surveillance
India Electronic Security Market
Security and Surveillance
Mass Transit Security Market
Security and Surveillance
Global Security and Vulnerability Management Market
Security and Surveillance
Europe Cargo and Vehicle Screening Market