
 North America People Screening Market | 2026-2036
North America People Screening Market Size, Share, and Industry Trends Forecast 2026-2036
North America People Screening Market Insights
Market Context
Canadian and U.S. security equipment manufacturing capacity is hardening around advanced imaging and AI-enabled threat detection platforms. Smiths Detection Group Ltd leverages its computed tomography baggage screening lineage to anchor major airport retrofit programs across the continent. Rapiscan Systems Limited sustains its position through deep channel relationships with federal transportation agencies and correctional institutions. Evolv Technologies differentiates via software-defined screening architectures that reduce physical pat-down rates at high-throughput venues.
Technical Definition and Segment Structure
People screening encompasses the integrated hardware and software systems designed to detect concealed objects, verify identity, and assess behavioral indicators in pedestrian flow environments, typically operating through electromagnetic, optical, or biometric sensing modalities with throughput rates exceeding 400 persons per hour at aviation checkpoints. Metal detectors and biometric systems capture the dominant share of current procurement value, though screening software is displacing hardware-centric budgets as airports and stadiums prioritize algorithmic threat classification over standalone sensor acquisition. Among end users, transportation authorities—particularly airport operators—represent the most concentrated margin pool, while healthcare facilities emerge as the fastest-growing adoption segment driven by workplace violence prevention mandates.
Regulatory Framework
The Transportation Security Administration, Health Insurance Portability and Accountability Act privacy constraints, and FDA radiation-emitting product standards collectively shape product certification pathways and deployment protocols across the United States. Canadian operators additionally navigate Transport Canada aviation security directives and Health Canada radiation safety benchmarks, creating a dual-compliance environment for cross-border vendors. Stakeholders must monitor evolving algorithmic accountability requirements from the U.S. Department of Homeland Security and corresponding Canadian federal procurement guidelines as AI-driven screening systems expand beyond pilot installations into operational scale.
Market Dynamics
The Transportation Security Administration's computed tomography retrofit mandate is compressing replacement cycles across aging U.S. airport infrastructure while Canadian operators parallel this shift under Transport Canada directives.
Growth Catalysts
- HIPAA-aligned biometric deployment:Healthcare facilities across the United States are integrating identity verification systems to satisfy workplace violence prevention mandates, creating new procurement verticals beyond aviation.
- Touchless screening protocols:Federal transportation agencies are specifying reduced-contact checkpoint architectures that accelerate hardware refresh timelines at congested corridor airports.
- Northeast corridor infrastructure aging:Federal security grants coincide with end-of-life replacement cycles at legacy facilities from Boston to Washington, concentrating near-term demand.
Market Restraints
- Semiconductor component volatility:AI-enabled threat detection platforms depend on specialized processing chips subject to supply concentration in East Asian foundries.
- FDA radiation certification timelines:New electromagnetic screening modalities face extended pre-market review pathways that delay revenue recognition for equipment vendors.
- Manual pat-down substitution:Secondary screening procedures retain operational necessity despite primary system automation, limiting full labor cost displacement.
Strategic Opportunities
- Canadian provincial healthcare expansion:Ontario and Quebec hospital networks are piloting behavioral indicator assessment systems for emergency department security.
- AI-driven software-defined architectures:Algorithmic threat classification capabilities are converging with existing sensor hardware to displace standalone equipment purchases.
- U.S. Department of Homeland Security algorithmic accountability frameworks:Emerging procurement guidelines favor vendors with documented bias-auditing capabilities, creating compliance-based differentiation.
Industry Challenges
- Machine learning model validation expertise:Vendors face acute shortages of personnel capable of training and certifying threat detection algorithms across diverse demographic datasets.
- Legacy metal detector integration:New computed tomography and biometric systems must interface with decades-old facility wiring and data infrastructure without operational downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America People Screening Market |
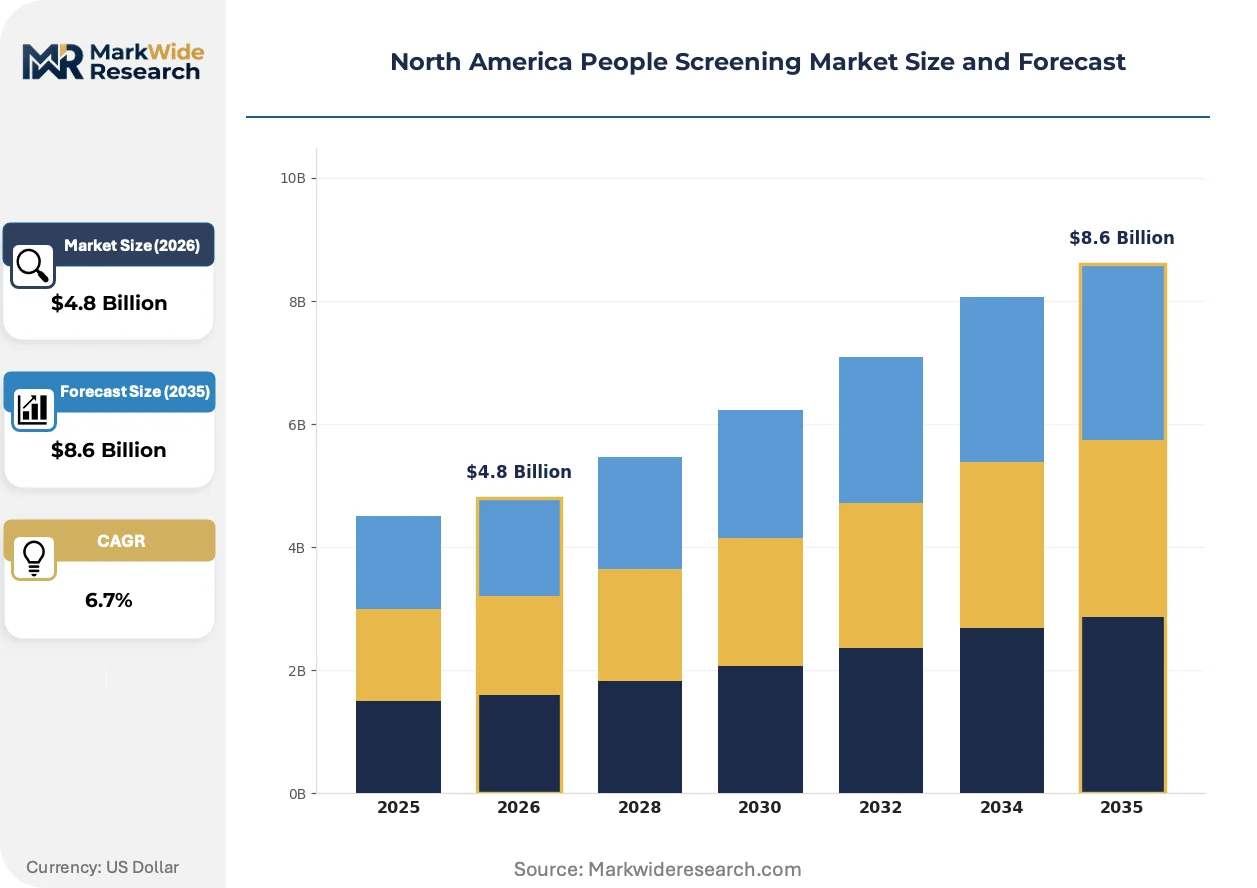
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Detectors, Biometric Systems, Surveillance Cameras, Screening Software End User: Government, Transportation, Healthcare, Education Technology: X-ray, Magnetometer, Infrared, Facial Recognition Application: Public Events, Airports, Hospitals, Prisons |
| Companies Covered | Smiths Detection Group Ltd, Rapiscan Systems Limited, Evolv Technologies, Thruvision Ltd, LINEV Systems, OSI Systems, Teledyne Flir LLC, Thermo Fisher Scientific Inc, Liberty Defense, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America People Screening Market Trends and Innovations
Checkpoint architectures are pivoting from hardware-centric acquisition models toward software-subscription frameworks, with threat detection algorithms receiving more frequent updates than the physical sensors they govern.
Millimeter-wave advanced imaging technology is converging with passive screening arrays to enable continuous monitoring without directed passenger positioning. Stadium operators and mass transit authorities in the United States are adopting these systems to maintain throughput during peak event flows. The structural consequence is compressing the addressable market for standalone walk-through metal detectors in high-volume venues.
The U.S. Department of Homeland Security is finalizing algorithmic accountability requirements for AI-driven screening systems that mandate documented bias testing and audit trails. Vendors must now maintain model versioning records and demographic performance benchmarks to qualify for federal procurement channels. Airport authorities in the Northeast corridor are delaying pilot-to-scale transitions until these frameworks stabilize.
Service unbundling is separating hardware ownership from algorithm licensing and maintenance obligations. Transportation authorities are negotiating multi-year software subscriptions while extending physical equipment depreciation schedules. This pattern is most visible at U.S. hub airports where capital budgets face competing priorities from terminal modernization programs.
North America People Screening Market Segmentation
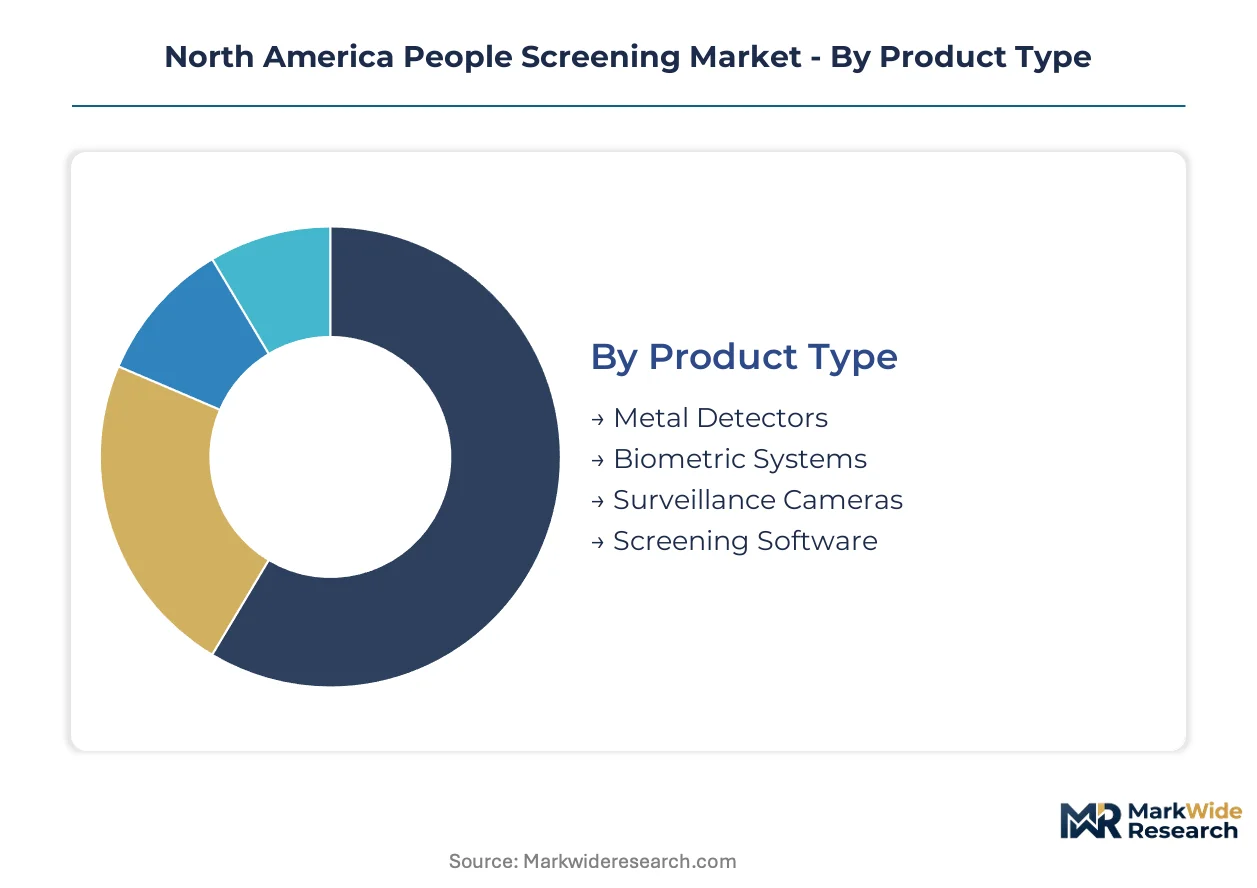
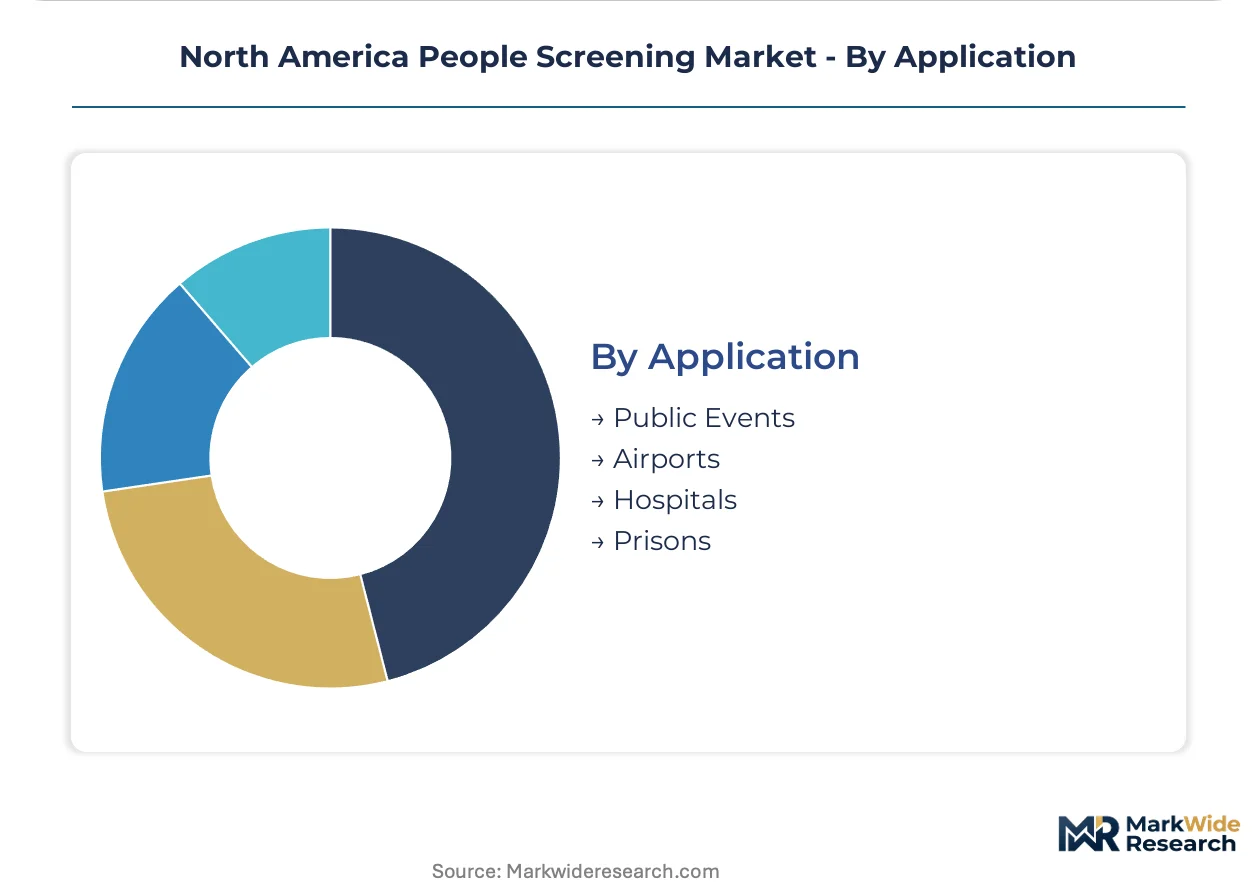
People screening procurement patterns diverge sharply across product architectures and deployment contexts. Transportation authorities prioritize throughput metrics while healthcare operators emphasize HIPAA-aligned identity verification. Understanding these segment-specific certification pathways and operational constraints enables targeted vendor positioning.
Product Type:
FDA radiation-emitting product standards govern electromagnetic screening hardware, while biometric systems face HIPAA privacy constraints and DHS algorithmic accountability requirements. Software-defined platforms navigate a lighter certification burden but carry evolving AI audit obligations.
- Metal Detectors:Walk-through and handheld units utilizing magnetometer coils to identify ferromagnetic objects. Demand concentrates at aging Northeast corridor airports where TSA grants fund replacement of legacy units installed during post-2001 infrastructure expansion.
- Biometric Systems:Identity verification platforms combining facial recognition, iris scanning, and fingerprint matching with liveness detection. Healthcare facilities across Ontario and Quebec are piloting behavioral indicator assessment integrations for emergency department security, creating provincial procurement verticals.
- Surveillance Cameras:Optical sensors with embedded analytics for crowd monitoring and anomaly detection.
- Screening Software:Algorithmic threat classification and passenger flow optimization platforms.
Leading the category by volume: Metal Detectors. Expanding most quickly: Screening Software.
End User:
Customer procurement authority determines contract structure and sales cycle length. Federal transportation agencies negotiate multi-year enterprise agreements while municipal education districts issue fragmented RFPs.
- Government:Federal, state, and municipal facilities including courthouses, embassies, and administrative buildings. U.S. Northeast corridor federal security grants are compressing replacement timelines at legacy installations from Boston to Washington.
- Transportation:Airport authorities, mass transit operators, and port facilities. TSA computed tomography retrofit mandates are reshaping procurement specifications toward touchless checkpoint architectures at congested hub airports.
- Healthcare:Hospital networks, outpatient clinics, and long-term care facilities. Workplace violence prevention mandates are driving identity verification deployments across U.S. hospital systems.
- Education:K-12 districts and university campuses. Campus security budgets favor metal detector deployments at entry points with limited algorithmic integration.
Dominant by contract value: Transportation. Gaining share fastest: Healthcare.
Technology:
Underlying sensing modalities dictate facility infrastructure requirements and operator training protocols. Electromagnetic systems demand shielded installation environments while optical platforms require controlled lighting conditions.
- X-ray:Ionizing radiation systems for baggage and parcel inspection. TSA mandates are accelerating computed tomography adoption at U.S. hub airports, displacing legacy 2D projection systems.
- Magnetometer:Passive magnetic field detection for metallic threat identification. Aging infrastructure across the Northeast corridor is driving replacement demand as end-of-life cycles coincide with federal grant availability.
- Infrared:Thermal imaging for fever detection and concealed object identification.
- Facial Recognition:Biometric matching against watchlists and credential databases. DHS algorithmic accountability frameworks are mandating documented bias testing for federal procurement eligibility.
Widest installed base: Magnetometer. Steepest expansion trajectory: Facial Recognition.
Application:
Deployment environment shapes throughput requirements and threat model specifications. Aviation checkpoints demand 400+ persons per hour while hospital emergency departments prioritize behavioral anomaly detection.
- Public Events:Stadiums, convention centers, and entertainment venues. Mass transit authorities in the United States are adopting millimeter-wave continuous monitoring to maintain throughput during peak event flows.
- Airports:Aviation security checkpoints and sterile area access control. TSA touchless screening protocols are accelerating hardware refresh timelines while compressing the addressable market for standalone walk-through metal detectors.
- Hospitals:Emergency department entry points and visitor screening checkpoints. Ontario and Quebec hospital networks are piloting behavioral indicator assessment systems, creating Canadian provincial demand concentration.
- Prisons:Correctional facility intake and visitor screening. Deep channel relationships with federal transportation agencies extend into correctional procurement through shared vendor ecosystems.
Highest throughput requirements: Airports. Fastest-growing deployment context: Hospitals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication clusters in the Pacific Northwest and Arizona supply specialized sensor components that anchor North American people screening manufacturing capacity.
United States
Federal security grants are compressing replacement timelines at aging Northeast corridor airports from Boston to Washington. TSA computed tomography retrofit mandates under Department of Homeland Security directives are reshaping procurement specifications toward touchless checkpoint architectures. Los Angeles International Airport and Chicago O'Hare anchor the largest hub retrofit programs, with millimeter-wave continuous monitoring pilot installations expanding across sterile area access points.
Canada
Transport Canada aviation security directives are paralleling U.S. computed tomography adoption curves at Toronto Pearson and Vancouver International. Health Canada radiation safety benchmarks create dual-compliance environments for cross-border vendors supplying both markets. Ontario and Quebec hospital networks are piloting behavioral indicator assessment systems for emergency department security, creating provincial procurement verticals outside aviation.
Mexico
Manufacturing maquiladoras in Baja California and Chihuahua are assembling magnetometer components for re-export to U.S. airport retrofit programs. Mexico's federal aviation security agency is modernizing Mexico City International and Cancun International with biometric passenger verification systems. Guadalajara's electronics manufacturing cluster is attracting foreign direct investment for screening sensor subassembly operations serving North American demand.
North America People Screening Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue software-defined architectures and AI-enabled threat detection platforms. The vendor base stratifies across three maturity levels: legacy equipment manufacturers with federal channel relationships, mid-tier specialists in biometric integration, and venture-backed challengers betting on algorithmic differentiation. Consolidation pressure concentrates among hardware-centric players as procurement shifts toward subscription-based software licensing. Dominant competitive moves include strategic partnerships with federal transportation agencies and backward integration into specialized semiconductor sourcing.
Within the legacy equipment tier, Smiths Detection Group Ltd and Rapiscan Systems Limited exemplify established market presence through deep federal channel relationships. Evolv Technologies occupies a distinct position representing the software-defined challenger archetype, with algorithmic threat classification capabilities converging with existing sensor hardware. These three anchors illustrate the competitive spectrum from hardware-centric incumbents to AI-native entrants reshaping procurement specifications.
| Leading Market Players |
|---|
| Smiths Detection Group Ltd |
| Rapiscan Systems Limited |
| Evolv Technologies |
| Thruvision Ltd |
| LINEV Systems |
| OSI Systems |
| Teledyne Flir LLC |
| Thermo Fisher Scientific Inc |
| Liberty Defense |
| Others |
Pricing and Supply Chain Analysis
FDA radiation certification timelines for computed tomography baggage systems gate both qualified supplier pools and premium-tier pricing access, compressing margins for vendors awaiting pre-market clearance while rewarding certified incumbents with sustained pricing power at U.S. hub airports.
Pricing Analysis
Extended warranty and algorithm-update bundling now separates subscription-based software tiers from capital-hardware transactions at major transportation authorities. Three-tier pricing structure across premium, standard, and economy levels tracks FDA certification status and TSA procurement list placement, with certified CT platforms commanding substantial premiums over legacy magnetometer replacements. Cost compression in standard-tier metal detector segments is intensifying because federal grant programs prioritize throughput metrics over brand loyalty. Municipal education districts exhibit the highest price sensitivity, while airport authorities with terminal modernization budgets demonstrate greater tolerance for premium software-defined architectures.
Supply Chain Analysis
Direct-to-federal-agency channels handle hyperscale procurement volumes from TSA and Transport Canada, while regional systems integrators manage downstream deployment at municipal healthcare and education facilities. Specialized semiconductor fabrication concentrates in Taiwan, South Korea, and the United States, with AI-enabled threat detection platforms drawing from advanced node GPU and FPGA supply. Critical dependencies include millimeter-wave sensor arrays, computed tomography detector modules, and biometric liveness detection chipsets. Single-source vulnerability in East Asian foundry capacity for radiation-hardened components threatens delivery timelines for next-generation checkpoint systems. Distribution runs through authorized federal channel partners with DHS procurement certifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around software-defined architectures, with algorithmic accountability mandates forcing hardware-centric vendors toward acquisition or obsolescence.
For Market Incumbents: Anticipate displacement from AI-native challengers by accelerating backward integration into semiconductor sourcing for specialized radiation-hardened components. Secure DHS algorithmic audit certifications ahead of finalized procurement guidelines to maintain federal channel access against Evolv Technologies and similar software-defined entrants. Priority lever: multi-year software subscription contracts that extend equipment depreciation schedules while capturing recurring revenue. For New Entrants and Emerging Players: Federal systems integrators with DHS procurement certifications represent the fastest path to pilot-to-scale transitions at Northeast corridor airports. Target Ontario and Quebec hospital networks piloting behavioral indicator assessment systems, where provincial procurement verticals remain underpenetrated by established aviation-focused vendors. Go-to-market angle: HIPAA-aligned identity verification bundles that satisfy workplace violence prevention mandates without requiring TSA certification timelines. For Investors and Strategic Acquirers: TSA delays in finalizing algorithmic accountability requirements is the leading indicator that consolidation windows will narrow once frameworks stabilize. Five-to-ten-year viability favors vendors with documented bias-auditing capabilities and federal channel relationships rather than pure-technology plays. Acquisition target archetype: mid-tier biometric specialists with Health Canada dual-compliance experience and existing Ontario healthcare pilot contracts. Signal to watch: Transport Canada directives paralleling U.S. CT retrofit mandates, which would validate cross-border scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Accountability Certification | DHS audit trail documentation secures federal procurement eligibility ahead of framework finalization. |
| Backward Integration into Semiconductors | Captive supply of radiation-hardened processing chips insulates against East Asian foundry concentration risk. |
| Healthcare Vertical Expansion | HIPAA-aligned biometric deployments in Ontario and Quebec diversify revenue beyond aviation cyclicality. |
| Software Subscription Unbundling | Multi-year algorithm licensing separates recurring revenue from capital equipment depreciation schedules. |
| Dual-Compliance Product Architecture | Simultaneous FDA and Health Canada certification accelerates cross-border deployment at Toronto and Vancouver hubs. |
Research Methodology
Multi-period observation of TSA procurement award patterns, Transport Canada directive timelines, and hospital network pilot announcements anchored the trend analysis, supplemented by interviews with airport procurement directors, healthcare security administrators, federal systems integrators, and semiconductor supply chain managers. Secondary validation drew from DHS algorithmic accountability framework drafts, FDA radiation-emitting product certification databases, Health Canada medical device licensing records, and congressional appropriations documentation for federal security grants. Bottom-up equipment shipment tracking and top-down federal budget allocation analysis provided cross-referenced triangulation.
Input-output matrices modeled deployment volumes across product architectures, end-user segments, technology modalities, and application environments throughout the forecast period. Segmentation dimensions included hardware versus software revenue mix, certification tier, and regional regulatory cluster. CAGRs were derived from replacement cycle compression analysis, grant funding trajectory assessment, and algorithmic capability diffusion curves. Industry-specific inputs encompassed TSA CT retrofit mandate implementation pace and provincial healthcare workplace violence prevention legislative adoption.
Caveats apply where FDA pre-market review delays, East Asian semiconductor export restrictions, or DHS algorithmic framework revisions could materially shift the outlook. Forecasts reflect assumptions regarding federal grant continuity and cross-border regulatory harmonization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Speed Limit Radar Signs Market
Security and Surveillance
Global Container Security Market
Security and Surveillance
Vietnam Private Security Market
Security and Surveillance
Global Firearm Sight Market
Security and Surveillance
Threat Detection Systems Market
Security and Surveillance
Signal Jammer Market
Security and Surveillance
Private Security Market
Security and Surveillance
Urban Security Screening Market
Security and Surveillance
Explosive Detection Technology Market
Security and Surveillance
Europe Anti-Piracy Protection Market
Security and Surveillance
X-Ray Security Screening System Market
Security and Surveillance
Home Security Market
Security and Surveillance
Seaport Security Management Market
Security and Surveillance
Middle East Manned Security Services Market
Security and Surveillance
Prison Management Systems Market
Security and Surveillance
Night Vision Scopes Market