
 Europe Cargo Inspection Market | 2026-2036
Europe Cargo Inspection Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cargo Inspection Market Foresight
European customs infrastructure is broadening its non-intrusive inspection footprint across major maritime gateways. SGS Group leverages its pan-European laboratory network to anchor quality assurance contracts with pharmaceutical distributors. Bureau Veritas SA sustains competitive positioning through specialized chemical analysis capabilities at Rotterdam and Hamburg terminals. Intertek Group plc differentiates via integrated audit and certification bundles targeting freight forwarders navigating EU customs compliance.
Cargo inspection encompasses the systematic verification of goods integrity, security status, and regulatory conformity through physical examination, sensor-based detection, and analytical testing, typically employing gamma-ray or neutron-based screening systems capable of penetrating sealed containers. The primary purpose centers on preventing contraband movement, ensuring supply chain safety, and validating trade documentation accuracy. Inspection services command the largest revenue share due to mandatory port-of-entry protocols, while chemical analysis technology is gaining traction as synthetic narcotics and hazardous materials diversify in molecular complexity. Customs authorities represent the most structurally entrenched end-user segment given sovereign enforcement mandates, though logistics providers are emerging as a faster-growing buyer category as liability frameworks tighten.
EMA guidelines on pharmaceutical cold-chain integrity, EU Green Deal customs protocols for carbon-intensive imports, and CE marking requirements for inspection equipment collectively elevate compliance-driven spending. REACH chemical registration obligations further expand testing service demand for cross-border hazardous cargo. Stakeholders must weigh capital allocation between automated screening upgrades and workforce retraining as regulatory thresholds for detection sensitivity tighten without corresponding tariff harmonization.
Market Dynamics
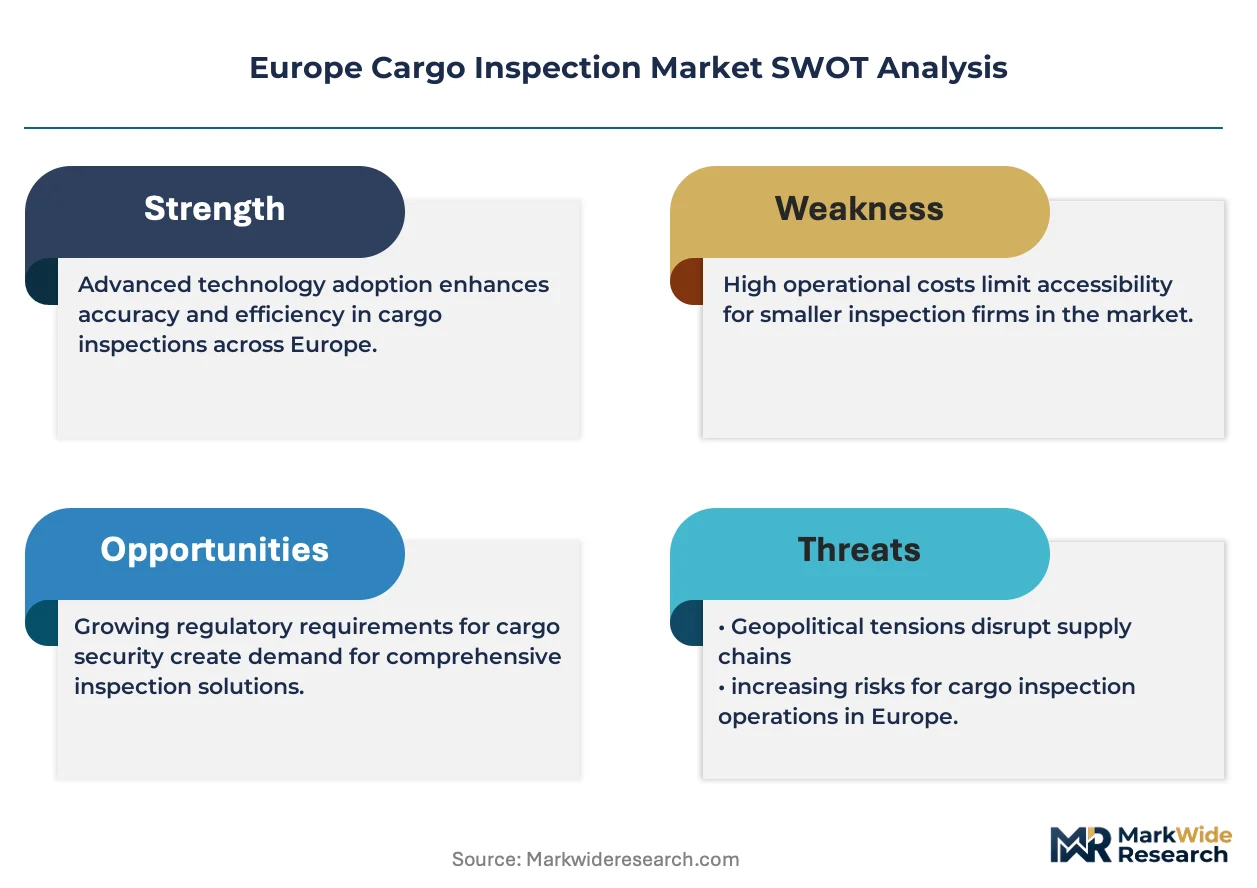
EU customs authorities are mandating higher detection sensitivity thresholds for synthetic narcotics and dual-use goods without harmonizing tariff structures, forcing inspection operators to absorb capital costs while margins compress.
Growth Catalysts
- EU Green Deal customs protocols:Carbon-intensive imports face expanded documentary and physical inspection requirements at Rotterdam and Hamburg, creating sustained service demand for emissions verification.
- Pharmaceutical distributors:EMA cold-chain integrity guidelines require temperature-validated inspection checkpoints across Rhine-Ruhr logistics corridors.
- Neutron-based screening:Port operators deploy advanced radiation detection to identify shielded contraband without container unloading.
Market Restraints
- Capital intensity:Automated gamma-ray scanner procurement cycles exceed customs authority budget approval timelines by 18-24 months.
- Technical limitation:Current sensor arrays cannot reliably distinguish complex synthetic opioid molecular structures from legitimate pharmaceutical precursors.
- Regulatory friction:CE marking certification delays for new inspection equipment block deployment across multiple member state jurisdictions simultaneously.
Strategic Opportunities
- Poland's Baltic corridor:Gdańsk and Szczecin terminals lack automated screening density relative to North Sea counterparts, presenting first-mover installation contracts.
- Drone-based container surveillance:Integration of aerial thermal imaging with ground-based sensor networks enables perimeter-to-dock inspection continuity.
- REACH chemical registration:Testing service providers capture recurring revenue from hazardous cargo cross-border documentation requirements.
Industry Challenges
- Workforce retraining:Automated screening deployment requires certified operators capable of interpreting neutron spectroscopy data, creating skills bottlenecks at Mediterranean ports.
- Legacy system integration:New detection hardware must interface with decade-old customs declaration databases without disrupting real-time clearance workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cargo Inspection Market |
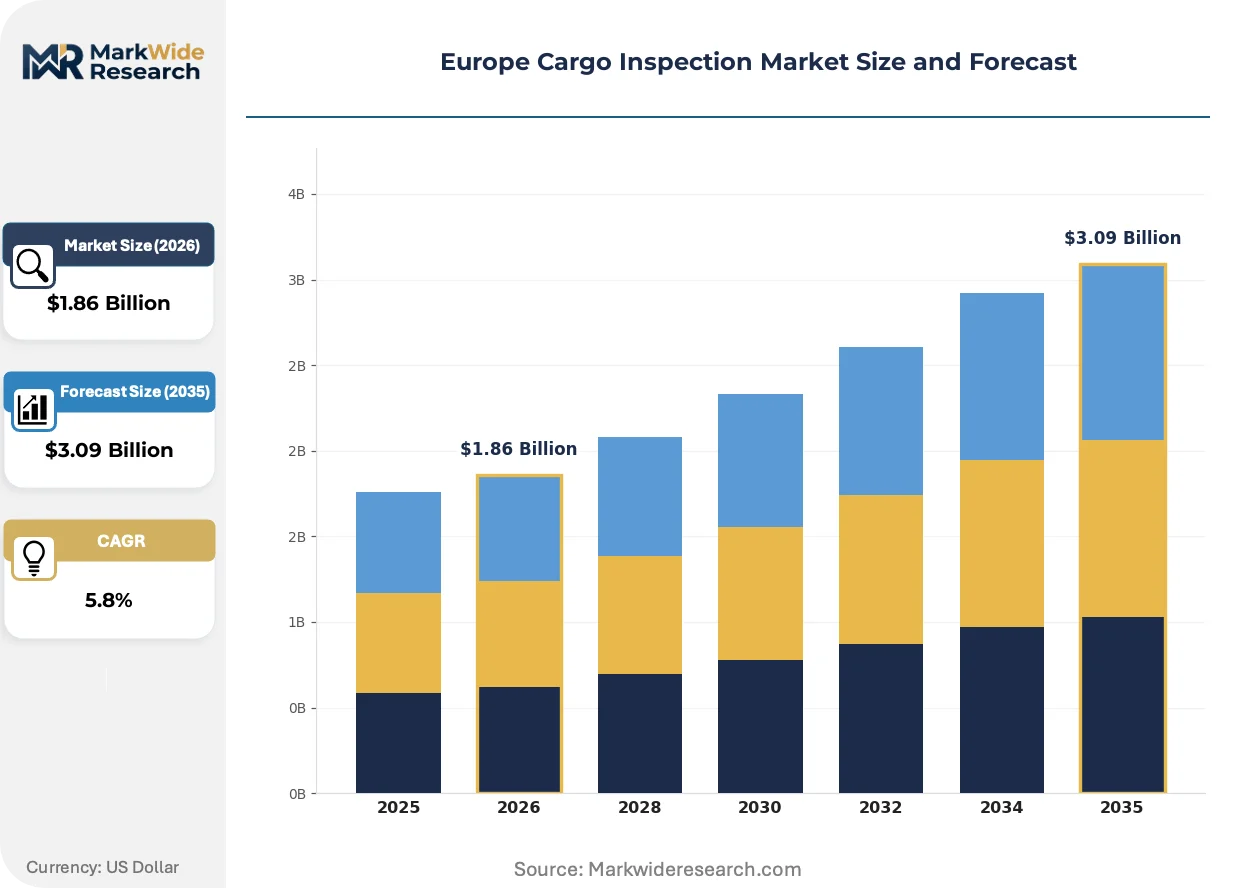
| Market Size in 2026 | $1.86 Billion |
| Market Size in 2035 | $3.09 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inspection Services, Testing Services, Certification Services, Audit Services Technology: X-Ray, Infrared, Chemical Analysis, Ultrasound End User: Shipping Companies, Freight Forwarders, Customs Authorities, Logistics Providers Application: Cargo Security, Quality Assurance, Regulatory Compliance, Risk Management |
| Companies Covered | SGS Group, Bureau Veritas SA, Intertek Group plc, Cotecna Inspection SA, TÜV SÜD, DEKRA SE, DNV GL, Eurofins Scientific, AmSpec Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cargo Inspection Market Shifts & Advancements
Inspection technology is converging around autonomous detection pipelines that reduce human intervention while regulatory pressure elevates documentation granularity for cross-border cargo movements.
Artificial intelligence-powered image recognition is absorbing pattern-matching workloads previously handled by trained customs officers. Belgian and Dutch terminals deploy machine learning models to flag anomalous container density profiles within seconds of scanning. The technology is absorbing mid-tier inspection labor demand while compressing clearance timelines at high-volume gateways.
REACH chemical registration obligations now mandate substance-level traceability for hazardous cargo entering EU customs territory. Industrial consequence includes expanded laboratory testing contracts for freight forwarders handling cross-border chemical shipments. Specialty chemical distributors face the steepest compliance cost escalation and are consolidating vendor relationships with pan-European testing networks.
Freight forwarders are unbundling inspection services from traditional logistics contracts and procuring directly from specialized providers. This disintermediation displaces port-authority bundled offerings in favor of certified third-party verification. German pharmaceutical logistics corridors exhibit the most pronounced buyer fragmentation as liability frameworks tighten for temperature-sensitive cargo.
Europe Cargo Inspection Market Segmentation
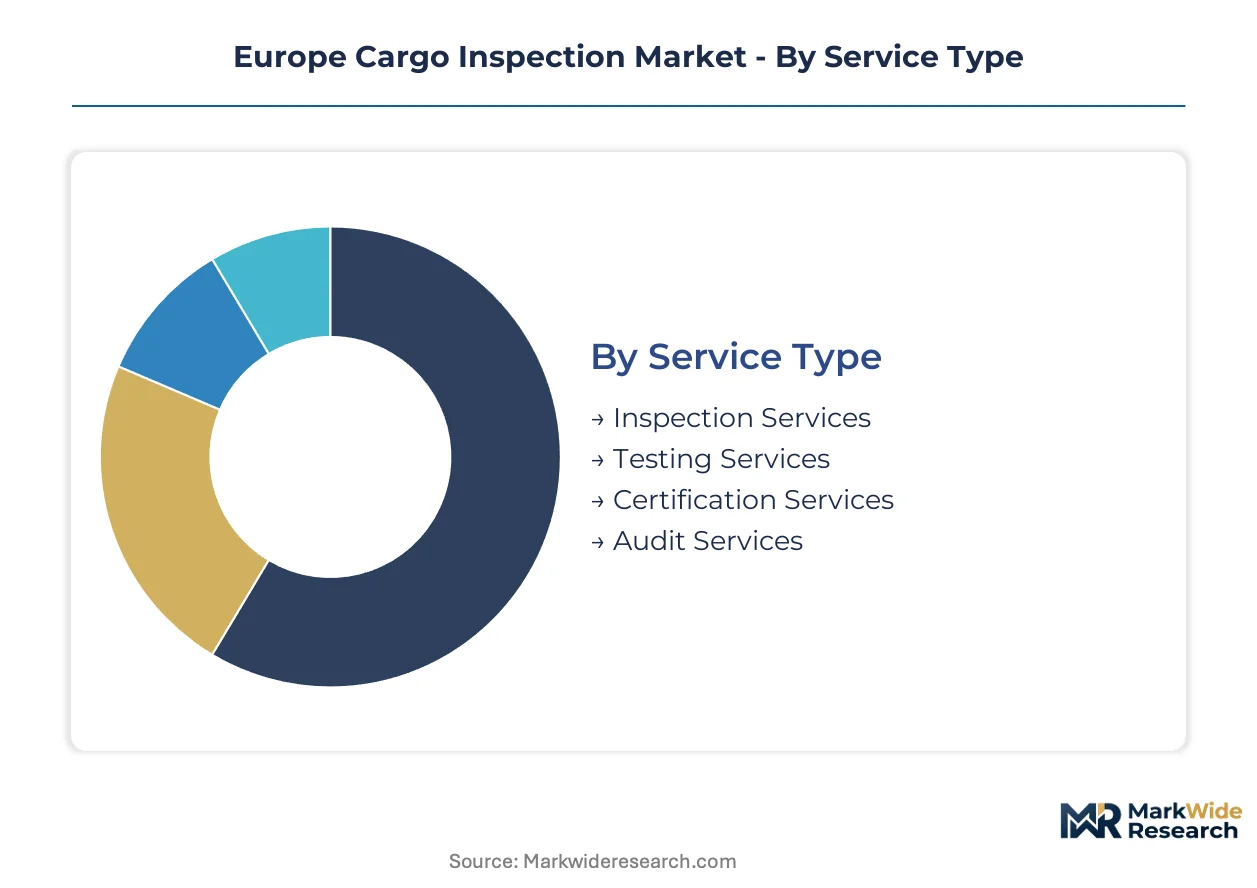
European cargo inspection procurement divides sharply between sovereign mandates and commercial liability frameworks. Buyers select service tiers and detection technologies based on cargo category risk profiles, regulatory exposure, and supply chain position rather than uniform standards.
Service Type:
Procurement patterns split between mandatory port-of-entry obligations and voluntary quality assurance investments.
- Inspection Services:Physical examination and sensor-based screening of sealed containers using gamma-ray or neutron detection systems. Rotterdam and Hamburg customs authorities mandate these protocols for 100% of high-risk cargo lanes, absorbing the largest share of sovereign enforcement budgets.
- Testing Services:Laboratory analysis of chemical composition, contamination levels, and material authenticity. REACH registration obligations drive recurring demand from Rhine-Ruhr chemical distributors seeking cross-border documentation compliance.
- Certification Services:Formal validation of conformity to CE marking, EU Green Deal emissions standards, and pharmaceutical GDP requirements.
- Audit Services:Systematic review of internal inspection protocols and documentation trails for freight forwarders managing temperature-sensitive pharmaceutical corridors.
Volume sits with Inspection Services; growth tilts toward Testing Services.
Technology:
Capital allocation follows detection sensitivity requirements rather than operational convenience.
- X-Ray:Gamma-ray and dual-energy scanning systems penetrating steel containers to reveal density anomalies. Belgian terminals deploy machine learning-enhanced X-Ray arrays to flag suspicious cargo profiles within seconds, compressing clearance timelines at high-volume gateways.
- Chemical Analysis:Spectroscopic and chromatographic techniques identifying molecular structures of narcotics, explosives, and hazardous materials. EMA cold-chain guidelines and REACH obligations concentrate demand among pharmaceutical logistics providers and specialty chemical distributors.
- Infrared:Thermal imaging for detecting temperature excursions in refrigerated containers and identifying concealed heat signatures.
- Ultrasound:Acoustic detection for structural integrity assessment of liquid bulk cargo and sealed pharmaceutical packaging.
Deployment concentrates on X-Ray infrastructure; Chemical Analysis claims the steepest expansion trajectory as synthetic opioid molecular complexity outpaces legacy detection.
End User:
Liability framework tightening determines whether buyers are sovereign or commercial entities.
- Customs Authorities:Sovereign enforcement agencies operating mandatory screening at EU external borders. Germany's Federal Customs Administration and Dutch Customs sustain the largest automated screening procurement budgets.
- Freight Forwarders:Logistics intermediaries unbundling inspection from traditional transport contracts to procure direct verification. German pharmaceutical corridors exhibit pronounced buyer fragmentation as temperature-sensitive cargo liability shifts downstream.
- Shipping Companies:Vessel operators conducting pre-loading inspections to avoid port detention and demurrage penalties.
- Logistics Providers:Warehousing and distribution operators integrating inspection checkpoints into value-added service portfolios.
Sovereign budgets anchor volume with Customs Authorities; Freight Forwarders are gaining share fastest as commercial liability frameworks displace bundled port offerings.
Application:
Regulatory pressure intensity shapes whether buyers prioritize security, quality, or documentation.
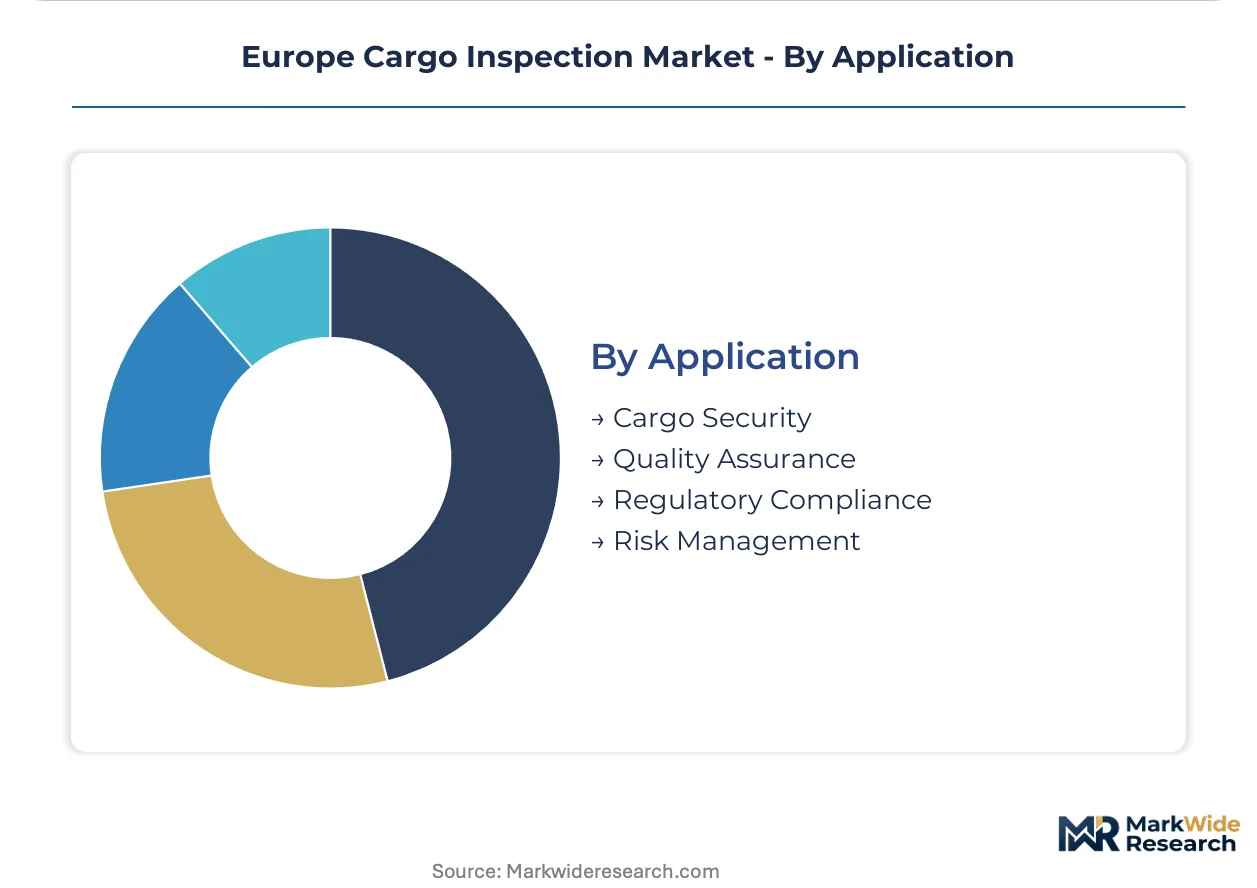
- Cargo Security:Contraband interdiction and threat detection at maritime gateways. EU customs protocols for dual-use goods and synthetic narcotics elevate sensitivity thresholds without harmonizing tariff structures, forcing operators to absorb capital costs.
- Regulatory Compliance:Verification of documentation accuracy and conformity to EU Green Deal carbon protocols, REACH registrations, and pharmaceutical GDP standards. Rotterdam terminals now require emissions verification documentation for carbon-intensive imports.
- Quality Assurance:Integrity validation for temperature-sensitive pharmaceuticals and perishable agricultural products.
- Risk Management:Insurance-driven inspection protocols and supply chain continuity planning for high-value manufacturing inputs.
Cargo Security commands the largest installed base; Regulatory Compliance climbs fastest as EU Green Deal and EMA guidelines expand documentary granularity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr corridor's chemical feedstock density anchors cargo inspection demand across northwestern Europe. Port infrastructure investments concentrate where industrial cargo volumes intersect with regulatory enforcement mandates.
Germany
Pharmaceutical cold-chain expansion and chemical distribution networks drive inspection service procurement. EMA guidelines on temperature-validated checkpoints mandate infrastructure upgrades across Rhine-Ruhr logistics corridors. Hamburg's container terminals deploy neutron-based screening arrays to handle elevated synthetic narcotics detection thresholds without unloading delays.
Netherlands
Rotterdam's status as Europe's largest maritime gateway generates sustained demand for emissions verification and hazardous cargo documentation. EU Green Deal customs protocols require expanded physical inspection for carbon-intensive imports entering Dutch terminals. The port authority's automated screening procurement absorbs significant sovereign enforcement capital.
Belgium
Antwerp's chemical processing cluster and pharmaceutical distribution hubs create dual demand streams for security screening and quality assurance. REACH registration obligations mandate substance-level traceability for hazardous cargo crossing Belgian customs territory. Machine learning-enhanced X-Ray arrays at Belgian terminals compress clearance timelines for high-volume container traffic.
France
Marseille-Fos port complex and Paris-region pharmaceutical logistics generate inspection demand across security and regulatory compliance applications. ANSM oversight of pharmaceutical distribution reinforces EMA cold-chain integrity requirements for temperature-sensitive cargo. Le Havre's container terminals face capacity constraints that accelerate automation procurement cycles.
Poland
Gdańsk and Szczecin terminals exhibit automated screening density gaps relative to North Sea counterparts. The Baltic corridor's expanding container volumes attract first-mover installation contracts for gamma-ray and neutron detection systems. Polish customs authorities absorb EU customs protocols for dual-use goods without matching North Sea infrastructure endowments.
Europe Cargo Inspection Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized chemical analysis and drone-integrated surveillance niches. The vendor base organizes around three functional layers: pan-European laboratory networks, port-terminal screening operators, and pharmaceutical-specialist certifiers. Consolidation pressure operates selectively—sovereign customs contracts favor scale while liability-driven commercial procurement fragments across specialized providers. Dominant competitive moves include geographic expansion into under-screened Baltic corridors and technology licensing for AI-powered image recognition systems.
Within the pan-European network tier, SGS Group and Bureau Veritas SA exemplify scale-driven positioning across laboratory and terminal infrastructure. Intertek Group plc occupies a differentiated niche through integrated audit and certification bundles targeting freight forwarder compliance needs. These three entities represent distinct archetypes: SGS Group anchors laboratory-network breadth, Bureau Veritas SA exemplifies chemical-analysis specialization at major maritime gateways, and Intertek Group plc sits within the liability-framework advisory segment.
| Leading Market Players |
|---|
| SGS Group |
| Bureau Veritas SA |
| Intertek Group plc |
| Cotecna Inspection SA |
| TÜV SÜD |
| DEKRA SE |
| DNV GL |
| Eurofins Scientific |
| AmSpec Group |
| Others |
Supply & Pricing Matrix
EMA cold-chain integrity mandates and EU Green Deal emissions verification protocols are forcing freight forwarders to unbundle inspection services from traditional logistics contracts, compelling specialized providers to absorb capital-intensive screening upgrades while pricing power fragments across certification tiers.
Pricing Analysis
Service-bundling differentiation separates comprehensive audit-certification packages from standalone screening transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales technical support depth. Cost compression in standard-tier gamma-ray scanning is intensifying because customs authorities extend procurement cycles without harmonizing tariff structures. Freight forwarders managing pharmaceutical corridors exhibit highest price sensitivity; sovereign customs authorities with mandated enforcement budgets show lowest.
Supply Chain Analysis
Neutron generator and gamma-ray detector manufacturing rests on German, Dutch, and Belgian precision engineering clusters. Specialized scintillation crystals, high-voltage power supplies, and machine learning-optimized sensor arrays feed from these concentrated production hubs. Single-source vulnerability in semiconductor components for spectroscopic analysis equipment creates procurement bottlenecks. Distribution runs through pan-European laboratory networks and port-terminal operator consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive neutron source production and in-house AI model training represents the dominant vertical-integration race, as inspection operators seek to escape component supply constraints and differentiate detection sensitivity.
For Market Incumbents: Deploy machine learning-enhanced image recognition libraries to defend against emerging AI-native screening specialists. Consolidate laboratory network density across Poland's Baltic corridor before first-mover installation windows close. Absorb REACH documentation specialists to capture recurring chemical testing revenue from Rhine-Ruhr distributors.
For New Entrants and Emerging Players: Launch via drone-integrated thermal surveillance partnerships with Mediterranean port authorities lacking perimeter-to-dock inspection continuity. Target Gdańsk and Szczecin terminal operators with gamma-ray scanner lease-to-own structures. Penetrate pharmaceutical logistics corridors through temperature-validated checkpoint certification.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized chemical analysis providers given REACH registration obligation expansion. Five-to-ten year viability favors pan-European laboratory networks with hazardous cargo documentation capabilities. Watch EU customs authority budget approval timelines as capital deployment inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Neutron Source Production | Reduces dependency on Belgian and German precision engineering suppliers for spectroscopic detection arrays. |
| AI-Powered Image Recognition Platform Launch | Belgian and Dutch terminals deploy machine learning models to compress container clearance timelines. |
| Polish Baltic Corridor Geographic Expansion | Gdańsk and Szczecin terminal automation gaps attract first-mover gamma-ray and neutron detection contracts. |
| REACH Documentation Specialist Acquisition | Captures recurring revenue from Rhine-Ruhr chemical distributors facing cross-border hazardous cargo obligations. |
| Drone-Thermal Surveillance Joint Venture | Mediterranean ports lacking perimeter-to-dock continuity seek aerial-ground sensor network integration. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs. Primary interviews with customs technology procurement officers, port terminal operations directors, pharmaceutical logistics compliance managers, and hazardous cargo testing laboratory heads combined with ECHA REACH registration databases, EU customs union enforcement reports, and port authority capital expenditure disclosures. Bottom-up service provider revenue aggregation and top-down sovereign enforcement budget analysis enabled triangulation.
Data-stream reconciliation across inspection service procurement volumes, technology deployment counts, and end-user expenditure patterns shaped the analytical framework. Segmentation dimensions modeled encompass service type, detection technology, end-user liability framework, and application regulatory intensity. CAGRs derived from weighted average of historical procurement trajectories and mandated protocol expansion schedules. Neutron-based screening penetration curves and pharmaceutical cold-chain checkpoint density served as industry-specific forecast inputs.
EU customs tariff harmonization delays, EMA guideline revision cycles, and CE marking certification backlogs are the dominant revision risks. Forecasts reflect documented assumptions regarding sovereign enforcement budget growth and commercial liability framework tightening. A small set of regulatory trigger events warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Physical Security
France Data Center Physical Security Market
Physical Security
Smart Police Helmet Market
Physical Security
Asia-Pacific Data Center Physical Security Market
Physical Security
Asia-Pacific (APAC) Physical Security Market
Physical Security
Tactical Lights Market
Physical Security
United States Data Center Physical Security Market
Physical Security
Europe Physical Security Market
Physical Security
Hong Kong Data Center Physical Security Market
Physical Security
Security Guard Market
Physical Security
South America Data Center Physical Security Market
Physical Security
Bespoke Safe Rooms and Panic Rooms Market
Physical Security
Active Geofencing Market
Physical Security
Body Armor Market
Physical Security
Airport Full Body Scanner Market
Physical Security
Global Data Center Physical Security Market
Physical Security
Physical Security Market