
 Seaweed Market | 2026-2036
Seaweed Market Size, Share, and Industry Trends Forecast 2026-2036
Seaweed Market Intelligence
The division between high-purity, application-specific extracts and bulk commodity seaweed for feed or fertilizer is restructuring the competitive landscape. Cargill leverages its extensive supply chain to compete in high-volume food and feed applications. In contrast, Acadian Seaplants Limited specializes in proprietary extraction technologies for high-value agricultural biostimulants. FMC Corporation focuses on carrageenan and alginate hydrocolloids for food and pharmaceutical end markets.
Seaweed encompasses numerous species of marine macroalgae, cultivated or wild-harvested for their rich polysaccharide content. Key components include alginates, carrageenans, and agar, which provide gelling, thickening, and stabilizing functions in industrial applications. The Red Seaweed product type, a source of carrageenan, continues to dominate the food and beverage application segment due to its functional properties. Brown Seaweed is gaining traction in agriculture as a primary input for biofertilizers, driven by sustainability initiatives.
Food safety frameworks, including those from the US FDA and the European Food Safety Authority (EFSA), set strict limits on heavy metals in seaweed for human consumption. Organic certifications and standards like the EU Green Deal influence the use of seaweed in biofertilizers and animal feed. Navigating the patchwork of international regulations for different end-uses remains a critical competency for market participants.
Market Dynamics
The fundamental market dynamic is the bifurcation between high-volume, low-margin bulk seaweed for agricultural and feed inputs, and low-volume, high-margin purified extracts for pharmaceutical and nutraceutical applications. This split dictates distinct supply chain, R&D, and regulatory strategies.
Growth Catalysts
- Sustainable Agriculture Policies:The EU Green Deal and similar global initiatives promote seaweed-based biostimulants and biofertilizers as a substitute for synthetic chemicals, directly expanding the agricultural end-use market.
- Plant-Based Food Innovation:Consumer demand for vegan and vegetarian food products fuels the use of seaweed-derived hydrocolloids like carrageenan and agar as gelling agents, thickeners, and stabilizers in dairy and meat alternatives.
- Advanced Extraction Technologies:The development of proprietary extraction and purification methods enables the isolation of high-purity polysaccharides, fucoidan, and phlorotannins, unlocking new applications in the pharmaceutical and cosmetics industries.
Market Restraints
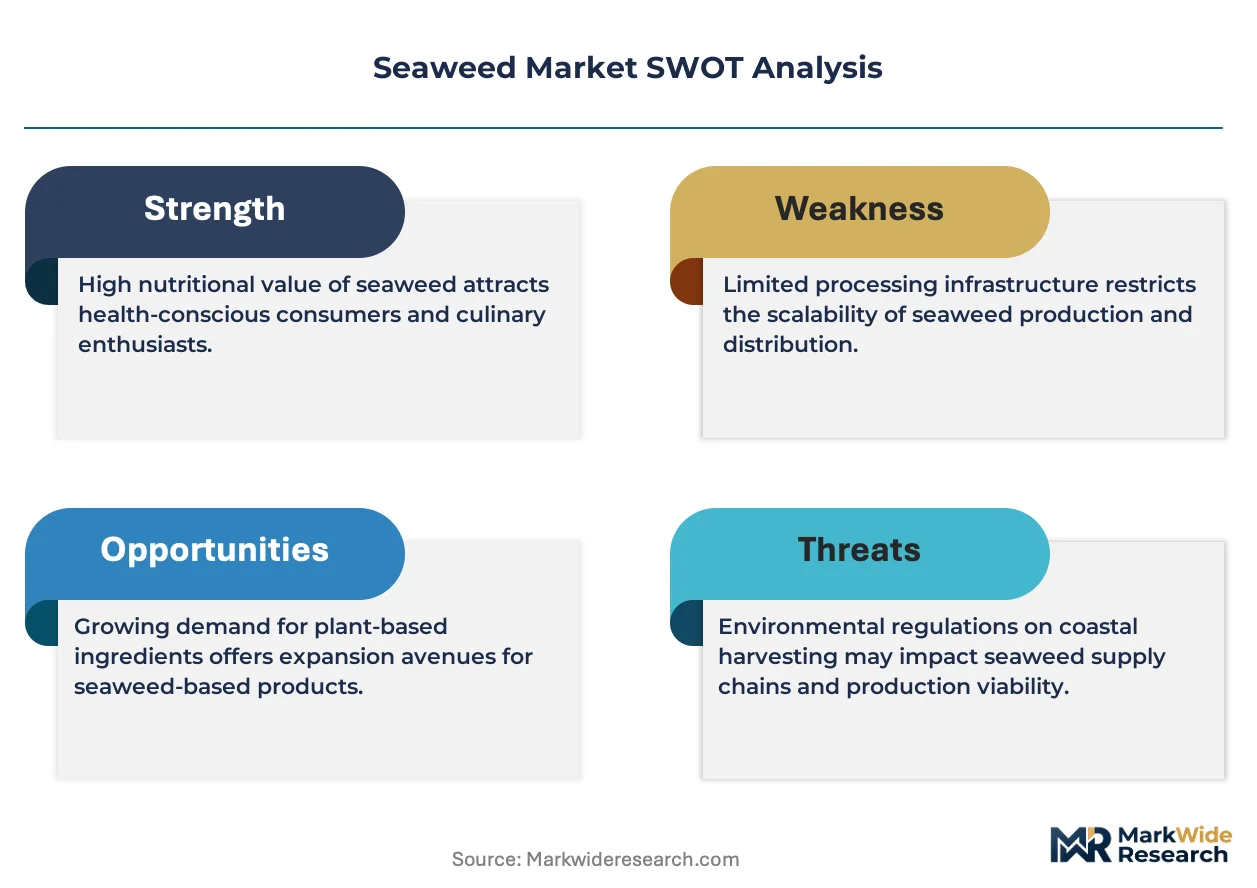
- Regulatory Fragmentation:Navigating disparate international standards for heavy metal content, such as those set by the US FDA and the European Food Safety Authority (EFSA), creates compliance burdens and trade friction.
- Supply Chain Volatility:Dependence on wild-harvesting for certain species introduces supply instability due to weather events, marine ecosystem health, and over-exploitation, particularly in key harvesting regions of Southeast Asia.
- High Processing Costs:Energy-intensive drying and extraction processes constitute a significant portion of the final product cost, limiting price competitiveness against synthetic alternatives in some industrial applications.
Strategic Opportunities
- Bioplastic Feedstock:Emerging research into using seaweed biomass to produce biodegradable plastics and packaging materials presents a significant, large-scale industrial application opportunity aligned with circular economy goals.
- New Cultivation Geographies:Expanding seaweed aquaculture to the coastlines of North America and Europe offers a path to diversify global supply away from its current concentration in Asia and meet growing regional demand.
- Carbon Sequestration Markets:The potential for large-scale seaweed farms to qualify for carbon credits under emerging blue carbon frameworks could create a new revenue stream and incentivize massive expansion of cultivation.
Industry Challenges
- Quality Standardization:The absence of globally accepted grading standards for raw seaweed based on species, origin, and biochemical profile complicates international trade and procurement for industrial processors.
- Logistical Infrastructure Gaps:Scaling the production of fresh and high-value seaweed products requires significant investment in cold chain logistics and specialized handling capabilities, which are currently underdeveloped.
- Specialized Talent Shortages:A scarcity of trained phycologists, marine biologists, and aquaculture technicians constrains the ability of companies to scale up advanced cultivation and processing operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seaweed Market |
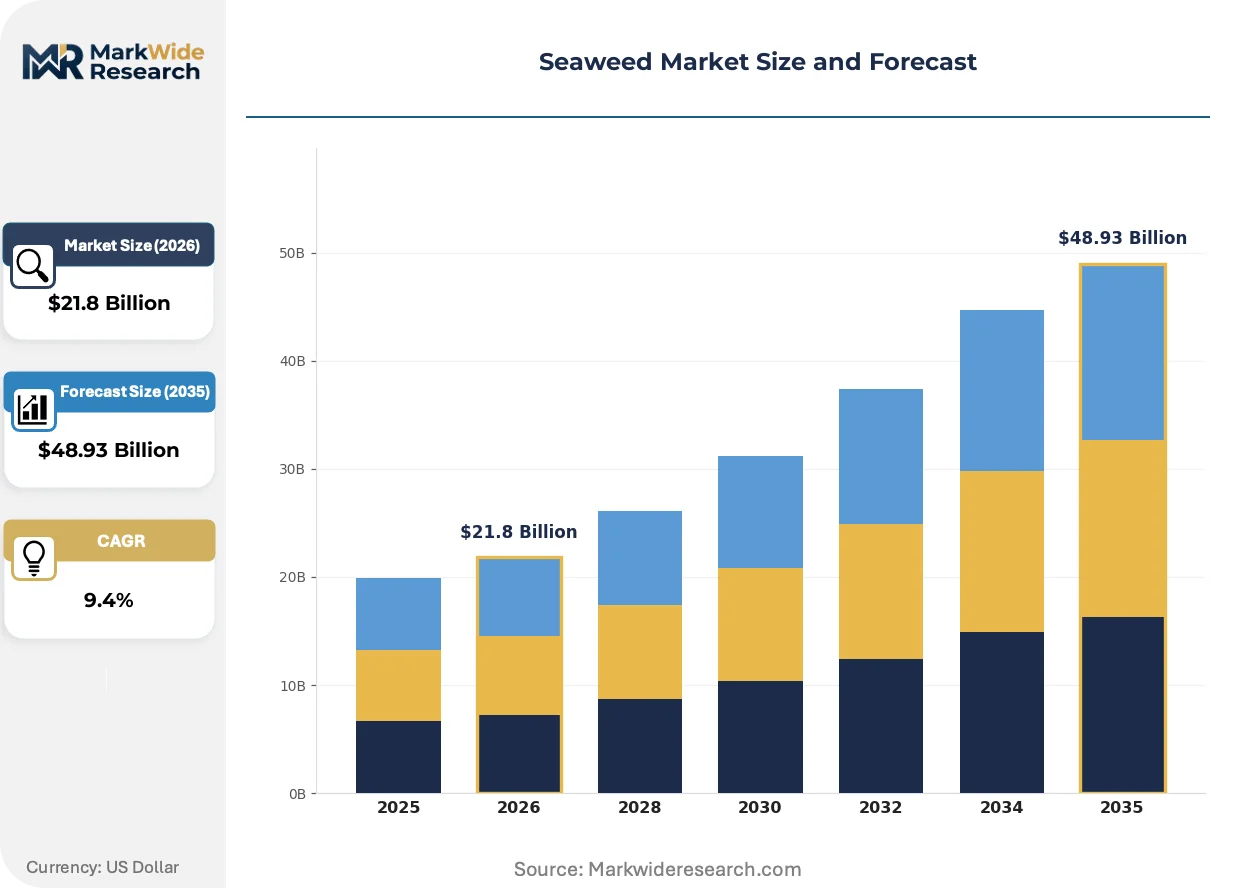
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $48.93 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red Seaweed, Brown Seaweed, Green Seaweed, Blue-Green Algae, Kelp Application: Food & Beverage, Pharmaceuticals, Cosmetics, Agriculture, Biofertilizers, Animal Feed Extraction Technique: Solvent Extraction, Supercritical Fluid Extraction, Enzymatic Extraction, Ultrasonic Extraction End User: Food Manufacturers, Pharmaceutical Companies, Personal Care Producers, Agrochemical Firms, Nutraceutical Brands |
| Companies Covered | Acadian Seaplants Limited, Qingdao Seawin Biotech Group, Cargill, Tate & Lyle, Algaia, Gelymar, CP Kelco, FMC Corporation, DuPont de Nemours, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seaweed Market Strategic Shifts & Innovations
Innovation in the seaweed market is driven by a push towards value-added products and process efficiency. Technological advancements in both cultivation and extraction are enabling the creation of specialized ingredients that cater to increasingly sophisticated end-use demands.
Precision fermentation is a key technological development for producing specific seaweed compounds without marine cultivation. Pharmaceutical and high-end nutraceutical manufacturers are adopting these lab-grown ingredients to ensure purity and supply consistency. This bio-manufacturing capability is converging with traditional aquaculture, offering producers a hybrid model to mitigate agricultural risks and stabilize input quality for sensitive applications.
South Korea's Ministry of Food and Drug Safety (MFDS) is implementing stricter evidence requirements for products making functional health claims. This regulatory shift compels producers of seaweed-based supplements to invest heavily in clinical research to validate the efficacy of their extracts, such as fucoidan. The functional foods segment is most affected, as it must transition from marketing general wellness benefits to promoting specific, scientifically substantiated health outcomes.
A notable behavioral change is the rising buyer preference for certified and traceable seaweed raw materials. Food, feed, and cosmetic manufacturers are increasingly demanding proof of sustainable harvesting or cultivation, such as through the ASC-MSC Seaweed Standard. This procurement trend is most advanced in European markets, where retailer and consumer pressure for transparent and ethical sourcing is reshaping supply contracts.
Seaweed Market Segmentation
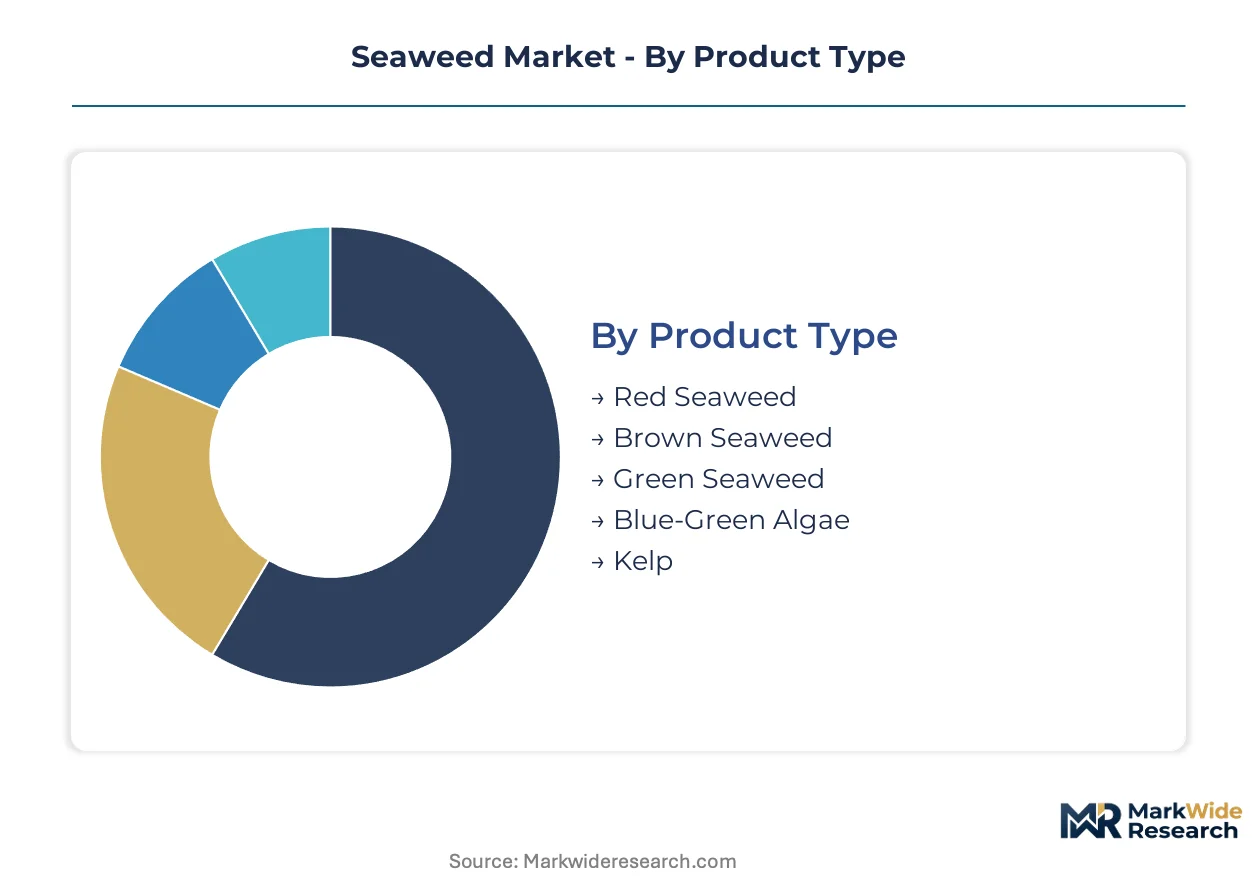
The Seaweed Market's segmentation reveals diverse value streams and operational models across its supply chain. Understanding these distinct categories provides clarity on where investment capital is directed and where differentiated product development occurs. Each segment addresses specific industrial needs, from bulk commodities to high-purity specialized ingredients.
Product Type:
The capital intensity of cultivation and processing infrastructure varies significantly across different seaweed product types.
- Red Seaweed:This macroalgae species is primarily cultivated for its carrageenan content, a hydrocolloid used for gelling and thickening. Demand concentrates in European and North American food and beverage sectors due to its functional properties in dairy alternatives and processed foods.
- Brown Seaweed:Comprising species like Ascophyllum nodosum and Laminaria, brown seaweed is rich in alginates and fucoidan. Agricultural demand in Europe and Brazil is rising for its use in biofertilizers, driven by sustainability mandates and organic farming trends.
- Green Seaweed:Species such as Ulva lactuca are recognized for their protein and mineral content, finding use in human nutrition and animal feed.
- Blue-Green Algae:Spirulina and Chlorella are microalgae cultivated for their high protein, vitamin, and antioxidant profiles, primarily targeting the nutraceutical market in Japan.
- Kelp:Large brown algae like Kombu and Wakame are consumed directly as food in East Asian cuisines and processed for alginate extraction.
Most installed capacity flows through Red Seaweed cultivation for its broad industrial applications. Expansion is steepest in Brown Seaweed due to its increasing role in sustainable agriculture.
Application:
The end applications for seaweed products delineate distinct market requirements and regulatory pathways.
- Food & Beverage:This segment utilizes seaweed extracts like carrageenan, agar, and alginates as gelling agents, thickeners, and stabilizers in numerous products. Consumer demand for plant-based alternatives in Germany and the UK drives its integration into dairy-free and meat-substitute formulations.
- Pharmaceuticals:High-purity fucoidan and alginates derived from seaweed are integral to drug delivery systems, wound care, and specialized medical nutrition. East Asian markets, particularly South Korea, exhibit strong demand for these compounds, driven by extensive clinical research and health claims.
- Cosmetics:Seaweed extracts provide moisturizing, anti-aging, and antioxidant properties for skincare and hair care products, appealing to natural ingredient trends.
- Agriculture:Whole seaweed biomass and crude extracts serve as soil conditioners and plant growth promoters, supporting organic farming practices.
- Biofertilizers:Concentrated seaweed extracts deliver essential micronutrients and biostimulants to crops, enhancing nutrient uptake and stress resistance in European farming.
- Animal Feed:Seaweed inclusion in animal diets improves gut health and nutrient absorption for livestock and aquaculture, reducing reliance on antibiotics.
High-volume commercialization characterizes the Food & Beverage application. High-value specialized products define the Pharmaceuticals segment.
Extraction Technique:
The choice of extraction technique directly influences the purity, yield, and ultimately the margin potential of seaweed-derived compounds.
- Supercritical Fluid Extraction:This advanced technique uses supercritical CO2 to isolate high-purity, heat-sensitive compounds without organic solvents. Pharmaceutical and nutraceutical manufacturers in Switzerland and Canada adopt this method for premium ingredient production, ensuring minimal degradation.
- Enzymatic Extraction:Utilizing specific enzymes, this method selectively cleaves polysaccharides, yielding highly functional and bioactive molecules with reduced chemical residue. Cosmetics and high-end food ingredient producers in France and the US value its gentle, targeted approach.
- Solvent Extraction:Traditional solvent-based methods use chemicals like ethanol or water to isolate desired compounds, often for bulk industrial applications.
- Ultrasonic Extraction:This method employs high-frequency sound waves to enhance cell disruption and compound release, improving extraction efficiency and speed for various applications.
Supercritical Fluid Extraction represents the most technologically sophisticated approach for high-value compounds. Solvent Extraction remains a foundational method for commodity-grade products.
End User:
Different end-user segments demand tailored product specifications, packaging, and regulatory compliance from seaweed suppliers.
- Pharmaceutical Companies:These users require ultra-high purity, stringent quality control, and extensive documentation for active pharmaceutical ingredients (APIs) and excipients. Global regulatory bodies like the US FDA and EMA mandate rigorous testing for heavy metals and microbial contamination.
- Food Manufacturers:Large-scale food processors integrate seaweed hydrocolloids and nutrients into a wide array of consumer products, from dairy to baked goods. They prioritize consistent supply, competitive pricing, and adherence to food safety standards like those from EFSA.
- Personal Care Producers:Cosmetic and personal care brands incorporate seaweed extracts for their beneficial skin and hair properties, emphasizing natural and sustainable sourcing.
- Agrochemical Firms:Companies in this sector purchase seaweed biomass or extracts for formulation into biostimulants and biofertilizers, targeting sustainable agriculture markets.
- Nutraceutical Brands:These brands develop dietary supplements and functional foods using concentrated seaweed compounds, requiring scientific validation for health claims in markets like South Korea.
Regulatory burden is highest for Pharmaceutical Companies due to strict quality and safety requirements. Volume procurement drives engagement with Food Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trained phycologists and marine biologists globally anchor advanced cultivation and processing operations for seaweed. This specialized talent pool is critical for scaling up sophisticated extraction technologies and meeting diverse end-user demands across various regions. Their expertise directly influences the localized development of value-added seaweed products.
South Korea
Demand for high-purity fucoidan and alginates drives pharmaceutical and nutraceutical applications in South Korea. The Ministry of Food and Drug Safety (MFDS) enforces stricter evidence requirements for functional health claims, compelling clinical research. Seoul's biotech cluster focuses on validating efficacy for advanced seaweed-based supplements.
Germany
European consumer demand for plant-based alternatives fuels the use of carrageenan and agar in Germany's food and beverage sector. The EU Green Deal encourages seaweed-derived biostimulants, aligning with sustainable agriculture goals. Munich's food innovation hubs integrate these hydrocolloids into dairy-free and meat-substitute formulations.
Japan
East Asian markets like Japan concentrate demand for high-purity extracts in pharmaceutical applications and nutraceuticals. The Ministry of Economy, Trade and Industry (METI) supports research into advanced processing techniques for kelp and blue-green algae. Tokyo's research institutions are developing specialized ingredients for health-conscious consumers.
United States
Expanding seaweed aquaculture and advanced extraction technologies underpin growth in the United States, particularly for cosmetics and pharmaceuticals. The US FDA sets strict limits on heavy metals for human consumption, ensuring product safety. The Pacific Northwest region explores new cultivation geographies to diversify global supply.
Brazil
Rising agricultural demand in Brazil for brown seaweed as a primary input for biofertilizers supports sustainability mandates. ANVISA regulates food and pharmaceutical ingredients, influencing product development for local markets. Coastal regions in the South are increasing cultivation efforts for these agricultural applications.
Seaweed Market Key Industry Players
Top-tier vendors anchor the high-volume, low-margin bulk seaweed market, while specialized players dominate the low-volume, high-margin purified extracts segment. This tiered structure creates distinct competitive positioning. Two strategic archetypes emerge: integrated commodity suppliers and technology-driven ingredient specialists. Dominant competitive moves include supply chain optimization for bulk products and proprietary extraction technology development for high-value applications.
Specialists in high-value agricultural biostimulants include Acadian Seaplants Limited, which emphasizes proprietary extraction technologies. Cargill occupies a position among integrated commodity suppliers, leveraging its extensive supply chain for high-volume food and feed applications. FMC Corporation anchors the hydrocolloids segment, focusing on carrageenan and alginate for food and pharmaceutical end markets. These companies exemplify the bifurcation between bulk and specialized product offerings.
| Leading Market Players |
|---|
| Acadian Seaplants Limited |
| Qingdao Seawin Biotech Group |
| Cargill |
| Tate & Lyle |
| Algaia |
| Gelymar |
| CP Kelco |
| FMC Corporation |
| DuPont de Nemours |
| Others |
Cost & Logistics Intelligence
Carrageenan spot prices, influenced by harvesting yields and processing costs, cascade through the seaweed supply chain, shaping the pricing tiers for both bulk commodities and refined extracts. This dynamic creates distinct market segments where supply concentration impacts pricing power for specific applications.
Pricing Analysis
The bundled-vs-unbundled service split drives price differentiation in the seaweed market. Contract-based long-term offtake agreements characterize bulk commodity sales, while value-based pricing applies to specialized, high-purity extracts. Price differentiation stems from the purity grade and specific certifications, such as ASC-MSC Seaweed Standard compliance. Pricing pressure stems from energy-intensive drying and extraction processes in bulk segments. Pharmaceutical companies exhibit the least price sensitivity for high-purity fucoidan, while food manufacturers remain highly sensitive to costs for commodity hydrocolloids.
Supply Chain Analysis
Heavy metal content and organic certifications gate access to premium supply chains. Geographic supply concentrates in Southeast Asia for wild-harvested species and across Asia for cultivated macroalgae. The supply chain draws from cultivated biomass and wild-harvested species, with processing often located near coastal regions. Supply instability due to weather events in key harvesting regions presents a structural risk. Distribution runs through integrated commodity suppliers like Cargill and specialized ingredient distributors, with direct sales to large food and pharmaceutical manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play, where lower cultivation costs in Southeast Asia contrast with stringent regulatory incentives for sustainable sourcing in European markets.
For Market Incumbents: Anchor existing market share by diversifying sourcing geographies beyond traditional Asian hubs, mitigating supply chain volatility from climate events. Invest in proprietary extraction technologies to enhance product purity and expand into high-value pharmaceutical applications. Control over cold chain logistics for fresh seaweed products reduces spoilage and maintains quality. The threat of synthetic alternatives in some industrial applications necessitates continuous R&D into cost-effective, high-performance seaweed compounds.
For New Entrants and Emerging Players: Specialized ingredient distributors represent a viable channel for market entry, particularly for novel biostimulants or nutraceuticals. Target the emerging bioplastic feedstock market, which remains underpenetrated and aligns with circular economy goals. Focus on developing certified and traceable raw materials for European markets, leveraging consumer demand for sustainable sourcing. A go-to-market angle emphasizing environmental benefits and functional efficacy can differentiate new offerings.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized technology firms possessing proprietary extraction methods for high-purity compounds. These companies offer access to high-margin pharmaceutical and cosmetic segments. Long-term viability hinges on the market's growth trajectory in sustainable agriculture inputs and specialized health ingredients. A signal to watch is the expansion of blue carbon frameworks, which could incentivize massive aquaculture expansion and create new revenue streams.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in New Geographies | Diversifies supply away from volatile regions and meets regional demand. |
| Proprietary Extraction Technology Development | Unlocks high-value applications in pharmaceuticals and cosmetics. |
| Green Manufacturing Process Adoption | Aligns with EU Green Deal and consumer sustainability demands. |
| Certification Program Investment | Builds trust and secures premium market access in European markets. |
| R&D into Bioplastic Feedstock | Positions companies for emerging circular economy opportunities. |
Research Approach
Coverage spans East Asia, Europe, North America, and South America, with primary inputs from each region. The analysis combines insights from in-depth interviews with aquaculture technicians, food scientists, regulatory affairs specialists, and agro-chemical formulators. Secondary validation draws from FAO fisheries statistics, EFSA reports, US FDA guidelines, and patent databases, triangulating data through bottom-up and top-down approaches.
Rate-of-change decomposition underpins the forecast framework, modeling market dynamics over the projection horizon. Segmentation dimensions include product type, application, extraction technique, end-user, and regional regulatory shifts. Compound annual growth rates were derived from historical trends and projected future demand drivers. Key forecast inputs include evolving sustainability mandates and advances in biostimulant formulation.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to unforeseen climate events affecting cultivation and rapid shifts in food safety regulations. A model refresh is warranted upon material change in major policy shifts regarding marine resource management.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Spain Alfalfa Hay Market
Agriculture and Agri Products
Colombia Floriculture Market
Agriculture and Agri Products
Asia Pacific Animal Feed Market
Agriculture and Agri Products
Compound Feed Market
Agriculture and Agri Products
Palm Kernel Expeller Market
Agriculture and Agri Products
Primary Feed Materials Market
Agriculture and Agri Products
South Africa Agriculture Market
Agriculture and Agri Products
Italy Animal Protein Market
Agriculture and Agri Products
Saudi Arabia Agriculture Market
Agriculture and Agri Products
Philippines Feed Industry Market
Agriculture and Agri Products
Europe Alfalfa Hay Market
Agriculture and Agri Products
Lucerne Market
Agriculture and Agri Products
Poultry and Eggs Market
Agriculture and Agri Products
Organic Soybean Market
Agriculture and Agri Products
Bee Pollen Market
Agriculture and Agri Products
Animal Feed and Pet Food Market