
 Primary Feed Materials Market | 2026-2036
Primary Feed Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Primary Feed Materials Market Analytics
Buyer concentration among integrated livestock processors is shifting toward vertically coordinated supply chains across Brazil, the United States, and Vietnam. Cargill Group leverages its origination networks across North American grain belts to secure consistent soybean meal flows for poultry integrators. Nutreco N.V. anchors its position through marine ingredient sourcing partnerships that serve European salmon farmers. Archer Daniels Midland Company competes on amino acid fortification technology for swine diet optimization.
Primary feed materials comprise unprocessed or minimally processed agricultural commodities—typically containing 8-14% crude protein for grains, 35-45% for oilseed meals—formulated into nutritionally complete diets through grinding, pelleting, and liquid additive infusion. Grains occupy the largest value share due to corn and wheat's energy density in ruminant and poultry rations, though margin compression persists from weather-driven price volatility. Oilseeds generate premium returns where solvent-extracted soybean meal commands higher protein content for monogastric species. Aquaculture represents the fastest-growing end user as extruded floating feeds replace farm-made mixtures in shrimp and salmon production.
The EU Green Deal and REACH chemical standards restrict pesticide residues in imported feed crops, while the USDA's Grain Inspection, Packers and Stockyards Administration enforces mycotoxin limits that shape export eligibility. China's SAMR implements GB standards for genetically modified feed labeling that complicate cross-border trade flows. Stakeholders must monitor regulatory divergence between major importing jurisdictions to avoid supply disqualification and secure long-term offtake agreements.
Market Dynamics
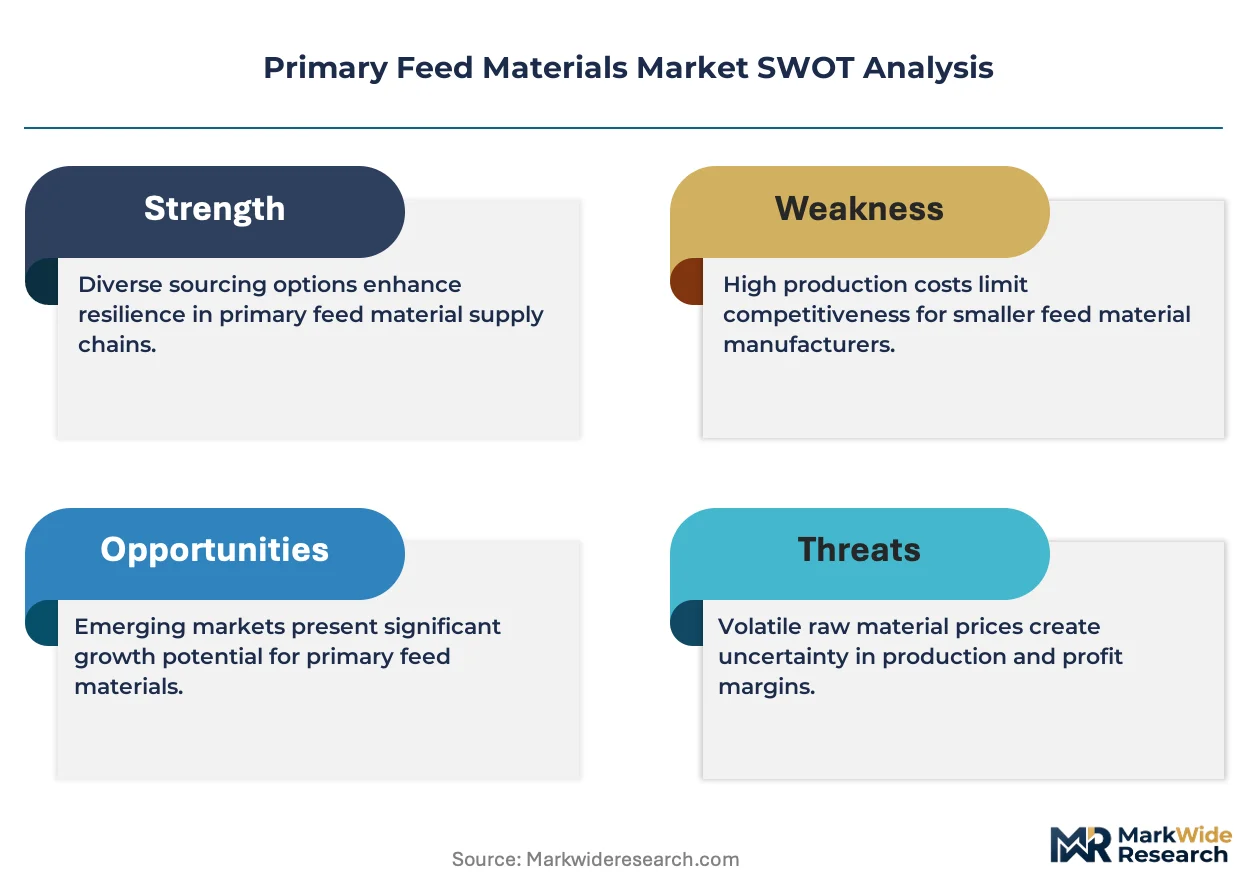
The EU Green Deal's Farm to Fork strategy is redirecting procurement toward certified deforestation-free supply chains, compressing margins for uncertified origins while rewarding traceability investments. This regulatory pressure intersects with aquaculture's rapid intensification across Southeast Asia, creating dual momentum for industrial feed adoption.
Growth Catalysts
- EU Deforestation Regulation:Mandatory due diligence for soy and palm imports is accelerating certified supply chain development, opening premium market access for compliant Brazilian and Argentinian exporters.
- Shrimp aquaculture intensification:Vietnam's Mekong Delta producers are replacing farm-made mixtures with extruded floating feeds, driving compound feed penetration in monogastric species.
- Solvent extraction advances:Higher protein recovery from soybean meal is improving feed conversion ratios for poultry integrators, reducing per-unit protein costs.
Market Restraints
- Weather-driven corn volatility:North American drought cycles and Brazilian rainfall variability create input cost instability that compresses blender margins.
- South American soy concentration:Origination dependence on Mato Grosso and Buenos Aires provinces exposes buyers to port congestion and currency fluctuation risks.
- Marine ingredient scarcity:Peruvian anchovy quota restrictions limit fishmeal availability, forcing salmon farmers toward costlier alternative protein sources.
Strategic Opportunities
- Indian aquaculture expansion:Andhra Pradesh's shrimp belt remains underpenetrated by industrial feed, offering first-mover advantages for extruded feed producers.
- Precision fermentation proteins:Microbial biomass from single-cell organisms is converging with traditional oilseed processing, enabling novel amino acid fortification pathways.
- EU Carbon Border Adjustment Mechanism:Upcoming embodied carbon tariffs on imported feed crops will reward low-carbon Brazilian soy producers with preferential market access.
Industry Challenges
- Traceability system integration:Blending legacy farm management software with blockchain-based origin verification requires substantial IT capex and technical expertise.
- Mycotoxin testing capacity:EU REACH pesticide residue standards and USDA mycotoxin limits demand expanded laboratory infrastructure that smaller mill operators struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Primary Feed Materials Market |
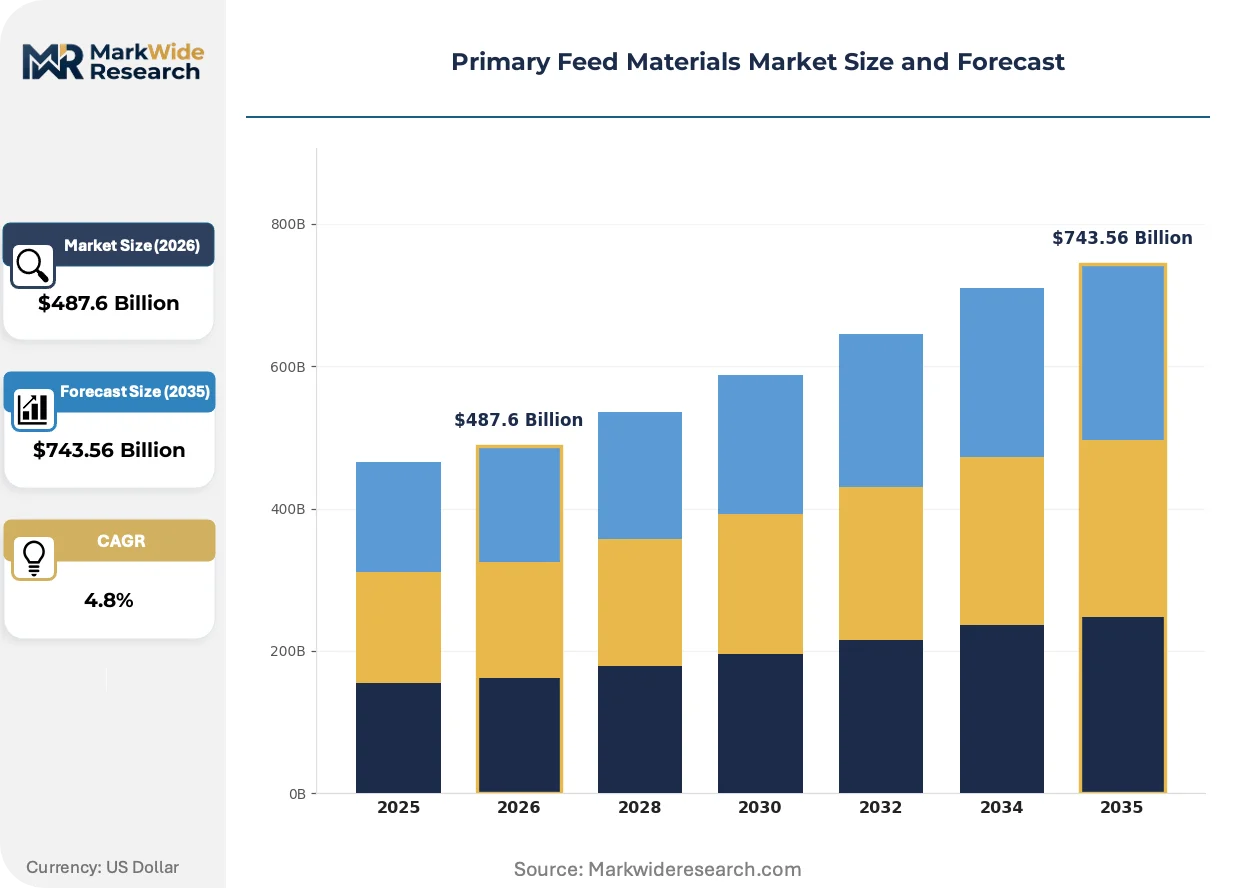
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $743.56 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grains, Oilseeds, Legumes, By-Products Form: Pellets, Mash, Liquid, Crumble End User: Poultry, Swine, Ruminants, Aquaculture Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | VH Group, Alltech Inc., Cargill Group, Nutreco N.V., Purina Animal Nutrition LLC, Archer Daniels Midland Company, BIOMIN Holding GmbH, Devenish Nutrition Limited, Josera GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Primary Feed Materials Market Evolving Landscape
Feed formulation is absorbing digital and biological innovations that compress development cycles and enable precise nutrient targeting. Three interconnected developments are restructuring how raw materials become finished rations.
Enzymatic pre-treatment of plant proteins is absorbing anti-nutritional factors that previously limited soybean meal inclusion rates in young animal diets. Poultry integrators in the United States are adopting phytase and protease cocktails at commercial scale, enabling higher fiber tolerance without growth penalty. This technology is absorbing the historical protein premium paid for fishmeal in starter feeds, redirecting formulation spend toward amino acid crystalline supplementation.
REACH chemical standards and EU Green Deal sustainability criteria are tightening pesticide residue thresholds for imported feed crops. This regulatory pressure is disqualifying conventional supply origins and redirecting procurement toward certified low-chemical operations with full traceability documentation. European compound feed manufacturers are responding by consolidating supplier bases and demanding third-party sustainability certification for all soy and palm derivatives.
Integrated livestock processors are consolidating procurement decisions into centralized nutrition teams that bypass traditional distributor networks. This channel compression is most visible in Brazil's poultry sector, where JBS and BRF operate captive feed mills with direct origination relationships. The shift is absorbing margin pools previously captured by regional feed distributors and forcing independent mills to specialize in species-specific formulations or exit.
Primary Feed Materials Market Segmentation
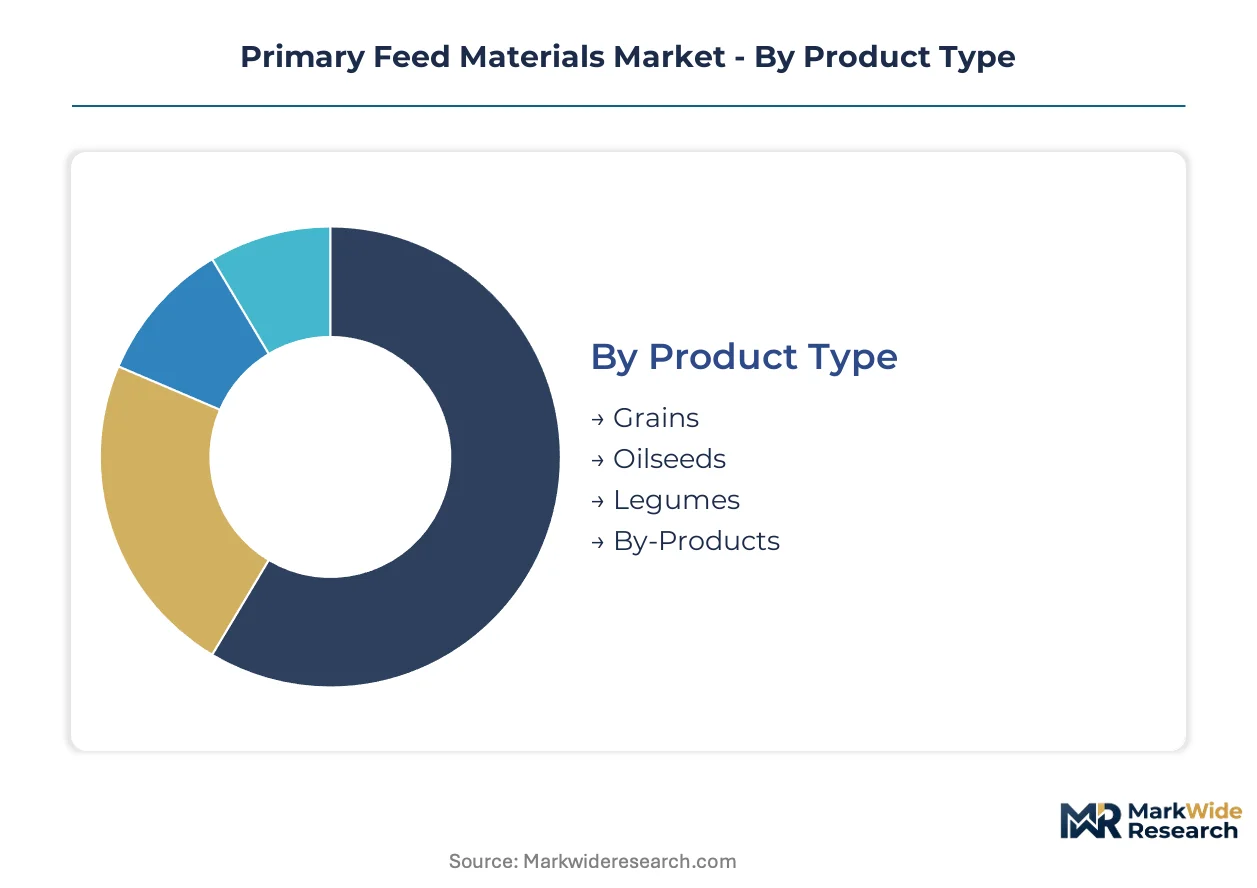
Primary feed materials segment across multiple dimensions that determine procurement economics and formulation flexibility. Supply concentration varies sharply by product type and geography, reshaping how compound feed manufacturers structure their raw material portfolios.
Product Type:
Supply concentration clusters around grain belts in the United States and oilseed crushing capacity in Brazil and Argentina, creating divergent margin structures across commodity categories.
- Grains:Corn and wheat deliver 8-14% crude protein with high metabolizable energy density for ruminant and poultry rations. Demand concentrates in Iowa and Illinois grain belts where processors secure forward contracts with ethanol co-product streams. Weather-driven price volatility compresses blender margins during drought cycles.
- Oilseeds:Solvent-extracted soybean meal achieves 35-45% protein content for monogastric species, commanding premium returns where amino acid profiles match poultry integrator specifications. Brazilian Mato Grosso crushers anchor global supply, exposing buyers to port congestion and currency fluctuation risks.
- Legumes:Field peas and lupins offer regional protein alternatives in European crop rotations under EU Green Deal sustainability criteria.
- By-Products:Distillers dried grains and wheat middlings recycle processing waste into cost-effective fiber sources for dairy operations.
Today's leader: Grains. Tomorrow's challenger: Oilseeds.
Form:
Processing intensity determines feed conversion efficiency and storage economics, with higher-value forms capturing margin from species-specific nutritional requirements.
- Pellets:Extruded and compressed feed reduces waste and improves digestibility through heat-treated starch gelatinization. Aquaculture operations across Vietnam's Mekong Delta scale industrial pellet use as intensive shrimp farming replaces traditional practices.
- Mash:Unprocessed ground mixtures retain lower capital requirements for small-scale poultry producers in developing markets.
- Liquid:Fat emulsions and molasses-based additives enable precise nutrient targeting in automated feeding systems.
- Crumble:Broken pellet fragments suit young animal starter diets where particle size affects intake volume.
Pellets dominate value capture. Crumble gains share fastest in starter feed applications.
End User:
Species-specific nutritional requirements drive formulation complexity and ingredient premiums, with aquaculture expanding most quickly as industrial feed penetration accelerates.
- Poultry:Broiler and layer operations consume the largest grain volumes, with integrators demanding precise amino acid fortification for feed conversion optimization.
- Swine:Grower-finisher diets require lysine-supplemented soybean meal to maximize lean tissue deposition.
- Ruminants:Beef and dairy cattle utilize fiber-rich forages and grain energy supplements, with EU methane reduction targets pressuring emission-intensive feed choices.
- Aquaculture:Extruded floating feeds for shrimp and salmon production represent the steepest expansion trajectory as Southeast Asian producers industrialize. Peruvian anchovy quota restrictions force alternative protein sourcing.
Poultry anchors volume. Aquaculture climbs the fastest on intensification trends.
Distribution Channel:
Channel structure reflects customer scale and technical service requirements, with procurement centralization compressing traditional distributor roles.
- Online:Digital platforms serve smallholder farmers with price transparency and input financing in fragmented markets.
- Retail:Farm supply stores stock packaged supplements for hobby and backyard producers.
- Wholesale:Regional distributors aggregate grain and meal volumes for independent mill operators lacking direct origination.
- Direct Sales:Integrated processors like JBS and BRF operate captive feed mills with direct Brazilian soybean contracts, bypassing third-party channels entirely.
Direct sales concentrate among large integrators. Online channels expand reach fastest into underpenetrated smallholder segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agronomists and feed formulation specialists cluster in the United States, Brazil, and Vietnam, anchoring regional expertise networks that shape procurement decisions and processing investments across major grain belts and aquaculture zones.
United States
Poultry integrators in Iowa and Illinois drive corn and soybean meal consumption through vertically coordinated supply chains. The USDA enforces mycotoxin limits through its Grain Inspection, Packers and Stockyards Administration, filtering export eligibility for feed crop shipments. Ethanol co-product streams in the Midwest supply distillers dried grains to dairy operations concentrated in Wisconsin and Minnesota.
Brazil
Integrated processors in São Paulo and Paraná states scale compound feed production for broiler and swine operations serving domestic and export markets. The country's national agricultural regulator, MAPA, oversees feed safety standards that align with EU deforestation compliance requirements. Mato Grosso crushers anchor global soybean meal supply, exposing buyers to port congestion at Santos and Paranaguá.
Vietnam
Shrimp and pangasius producers across the Mekong Delta industrialize feed use as intensive aquaculture replaces traditional farm-made mixtures. Vietnam's Ministry of Agriculture and Rural Development implements feed quality standards under Circular 21 that govern import licensing and domestic manufacturing. Can Tho and An Giang provinces concentrate extruded floating feed demand from expanding commercial pond operations.
China
Swine restocking after disease outbreaks drives soybean meal consumption through coastal crushing facilities. SAMR enforces GB standards for genetically modified feed labeling that complicate cross-border trade flows and shape procurement from North and South American origins. Shandong and Guangdong provinces host the largest compound feed manufacturing clusters serving integrated livestock operations.
Netherlands
Salmon farmers and specialty feed blenders in the Randstad region demand certified deforestation-free soy and marine ingredients. ECHA REACH chemical standards restrict pesticide residues in imported feed crops, redirecting procurement toward traceable supply chains with full sustainability documentation. Rotterdam's port infrastructure handles certified soy flows destined for European compound feed manufacturers.
Primary Feed Materials Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across origination, processing, and formulation layers. The market structure tilts toward consolidation among integrated agribusinesses with captive crushing and feed milling capacity. Three archetypes dominate: global traders with origination networks, regional compound feed specialists with species-specific expertise, and nutrition technology providers with additive and premix portfolios. Competitive intensity centers on backward integration into oilseed crushing and geographic expansion into underpenetrated aquaculture markets.
Within the diversified agribusiness tier, Cargill Group and Archer Daniels Midland Company exemplify global traders with origination-to-formulation reach. Nutreco N.V. occupies a position among nutrition-focused specialists emphasizing marine ingredient sourcing and aquaculture feed technology. These three companies anchor the competitive landscape through contrasting strategic postures: trading scale versus formulation precision versus species-specific vertical integration.
| Leading Market Players |
|---|
| VH Group |
| Alltech Inc. |
| Cargill Group |
| Nutreco N.V. |
| Purina Animal Nutrition LLC |
| Archer Daniels Midland Company |
| BIOMIN Holding GmbH |
| Devenish Nutrition Limited |
| Josera GmbH & Co. KG |
| Others |
Value Network & Pricing Analysis
Integrated livestock processors in Brazil, the United States, and Vietnam command substantial pricing leverage through captive feed milling and direct origination relationships, compressing margins for independent compound feed manufacturers dependent on spot market procurement.
Pricing Analysis
Commodity spot pricing dominates unprocessed grains and oilseed meals, while contract-based long-term offtake agreements govern premium-certified soy flows to EU compound feed manufacturers. Price differentiation stems from certification grade—EU deforestation-free compliance commands substantial premiums over conventional origins—and volume scale, where integrated poultry processors secure favorable terms through backward integration into crushing. Cost compression in standard-grade grains is intensifying because North American drought cycles and Brazilian rainfall variability destabilize input costs. Smallholder aquaculture operators in Vietnam's Mekong Delta exhibit the highest price sensitivity, whereas European salmon farmers demonstrate lowest sensitivity due to sustainability premium pass-through.
Supply Chain Analysis
Soybean meal supply rests on crushing capacity concentrated in Brazil's Mato Grosso province, Argentina's Buenos Aires region, and Iowa-Illinois processing clusters in the United States. Raw material dependencies include North American corn, South American soybeans, and Peruvian anchovy for fishmeal. Single-source vulnerability concentrates in Santos and Paranaguá port infrastructure, where congestion disrupts global meal flows. Distribution runs through vertically coordinated channels for integrated processors and regional wholesale aggregators serving independent mill operators lacking direct origination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through precision fermentation protein adoption, which displaces costlier marine ingredients and enables premium-tier formulation for aquaculture species.
For Market Incumbents: Anticipate regulatory divergence between EU deforestation compliance and USDA mycotoxin standards by consolidating supplier certification investments and expanding traceability infrastructure. Defend position by securing long-term offtake agreements with Mato Grosso crushers before EU Carbon Border Adjustment Mechanism implementation. Capacity addition in Vietnam's Mekong Delta anchors aquaculture feed growth against Peruvian anchovy quota volatility. For New Entrants and Emerging Players: Enter via Andhra Pradesh's underpenetrated shrimp belt, where industrial feed penetration lags Vietnam's industrialization trajectory. Target extruded floating feed production for monogastric species, leveraging lower land and labor costs versus Southeast Asian competitors. Partner with regional distributors possessing established smallholder relationships rather than building direct sales infrastructure. For Investors and Strategic Acquirers: Diversified agribusiness conglomerates with captive crushing and aquaculture feed technology represent the most active acquirer category in this space. Long-term viability centers on backward integration into precision fermentation protein production and geographic expansion into Indian aquaculture markets. Watch for EU Carbon Border Adjustment Mechanism implementation timing as inflection indicator for certified supply chain valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Cargill and ADM secure Mato Grosso capacity to bypass port congestion at Santos. |
| Precision Fermentation Protein Scale-Up | Nutreco partnerships with microbial biomass producers displace Peruvian fishmeal dependency. |
| EU Deforestation Certification Investment | European compound feed manufacturers consolidate supplier bases to meet Farm to Fork criteria. |
| Aquaculture Feed Geographic Expansion | Extruded floating feed producers target Andhra Pradesh's underpenetrated shrimp operations. |
| Blockchain Traceability System Deployment | JBS and BRF integrate origin verification to secure premium EU market access. |
Research Methodology
Multiple input streams—primary interviews with agronomists and feed formulation specialists, regulatory filings from USDA and EU ECHA, and customs trade data—were reconciled through bottom-up and top-down triangulation. Conversations covered compound feed procurement managers at integrated poultry processors, marine ingredient sourcing directors at aquaculture nutrition firms, and grain origination leads at major trading houses. Secondary validation drew from SEC 10-K filings, EU REACH chemical standards documentation, and Brazilian MAPA feed safety regulations.
Data-stream reconciliation anchored volume and value projections across the analysis window. Segmentation dimensions modeled included product type, processing form, end-use species, and distribution channel structure. CAGRs were derived from trend extrapolation of aquaculture intensification rates and EU regulatory compliance adoption curves. Industry-specific inputs incorporated Peruvian anchovy quota cycles, North American drought frequency patterns, and precision fermentation protein commercialization timelines.
Inputs from USDA Grain Inspection reports and EU ECHA pesticide residue databases were available through the study window; gaps in real-time blockchain traceability adoption metrics introduce uncertainty bands around certified supply chain penetration forecasts. Material deviation in EU Carbon Border Adjustment Mechanism implementation timing or Peruvian anchovy quota restrictions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Ghana Agriculture Market
Agriculture and Agri Products
Asia-Pacific Rapeseed Oil Market
Agriculture and Agri Products
North America Compound Feed Market
Agriculture and Agri Products
Agriculture in Egypt Market
Agriculture and Agri Products
Argentina Compound Feed Market
Agriculture and Agri Products
Bee Pollen Market
Agriculture and Agri Products
United Kingdom Poultry Meat Market
Agriculture and Agri Products
Rapeseed Oil Market
Agriculture and Agri Products
Australia Animal Protein Market
Agriculture and Agri Products
United Arab Emirates Poultry Meat Market
Agriculture and Agri Products
Italy Alfalfa Market
Agriculture and Agri Products
Kuwait Poultry Meat Market
Agriculture and Agri Products
Global Medicated Feed Market
Agriculture and Agri Products
Cage Free Eggs Market
Agriculture and Agri Products
Floriculture Market
Agriculture and Agri Products
North America Swine Feed Premix Market